
 Generic Oncology Drugs Market | 2026-2036
Generic Oncology Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Generic Oncology Drugs Market Intelligence
The consolidation of hospital group purchasing organizations and large retail pharmacy networks is restructuring procurement dynamics for generic oncology drugs. Sandoz Group AG leverages its extensive portfolio of biosimilars and small molecules to secure large-volume contracts. Teva Pharmaceutical Industries Ltd. competes through its broad manufacturing footprint and established supply chains in the United States and Europe. Fresenius Kabi AG specializes in injectable oncology products, aligning with acute care hospital formulary needs.
Generic oncology drugs are bioequivalent versions of brand-name cancer therapies whose patents have expired. These formulations must demonstrate the same active pharmaceutical ingredient (API), dosage form, and bio-availability as the originator product to gain approval. Chemotherapy agents form a mature, high-volume segment, while generic targeted therapies represent the fastest-growing category due to recent patent cliffs of major blockbusters. The shift towards oral therapies from intravenous delivery is altering administration patterns across hospitals and outpatient clinics.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) establish stringent bioequivalence and manufacturing standards. Approval pathways in China, managed by the NMPA, and India, overseen by the CDSCO, are critical for market access, influencing global production strategies. Manufacturers' success hinges on navigating these varied international regulatory requirements while managing complex API supply chains.
Market Dynamics
The primary structural force shaping the generic oncology drug market is the wave of patent expirations for blockbuster biologic therapies. This patent cliff creates an opening for lower-cost biosimilars, fundamentally altering procurement strategies for hospital systems and public health agencies worldwide.
Growth Catalysts
- Expanding Public Health Coverage:National health insurance schemes, such as Brazil's Sistema Único de Saúde (SUS), are expanding access to cancer care, creating large-volume, price-sensitive demand for generic chemotherapy and supportive care drugs.
- Streamlined Regulatory Pathways:Abbreviated approval frameworks, including the FDA's ANDA process and the EMA's biosimilar pathway, reduce the time and cost for manufacturers to bring bioequivalent products to market.
- Demand Consolidation:The growing influence of hospital Group Purchasing Organizations (GPOs) and large pharmacy benefit managers concentrates purchasing power, favoring generic manufacturers capable of fulfilling high-volume, multi-year contracts.
Market Restraints
- Originator Legal Strategies:Brand-name drug manufacturers utilize "patent thickets" and other litigation tactics to extend market exclusivity, creating legal uncertainty and significant financial risk for generic developers attempting to enter the market.
- Complex Manufacturing Requirements:The production of biosimilars involves highly complex and capital-intensive cell culture and purification processes, establishing a high barrier to entry for companies lacking specialized biomanufacturing expertise and facilities.
- Divergent International Standards:Variations in bioequivalence testing and data requirements between regulatory bodies like the NMPA in China and the FDA in the US can force manufacturers to run duplicative clinical studies.
Strategic Opportunities
- Emerging Market Penetration:Healthcare systems in Southeast Asian countries, including Indonesia and Vietnam, represent significant white space for generic oncology drugs as public and private insurance coverage for cancer treatment improves.
- Novel Drug Formulations:The development of oral solid dosage versions of existing intravenous oncology drugs presents a major opportunity to meet demand from outpatient clinics and support the shift toward home-based patient care.
- Next-Generation Biosimilars:An upcoming patent cliff for several classes of small molecule targeted therapies, such as kinase inhibitors, opens a high-value pipeline for generic manufacturers to pursue beyond traditional chemotherapies.
Industry Challenges
- API Supply Chain Concentration:Heavy reliance on a limited number of API suppliers, primarily located in China and India, exposes manufacturers to significant geopolitical risks, supply disruptions, and quality control vulnerabilities.
- Sterile Manufacturing Compliance:Adhering to the rigorous aseptic processing standards mandated by regulators like the EMA for sterile injectable drugs is a constant operational challenge, carrying the risk of costly product recalls and facility inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generic Oncology Drugs Market |
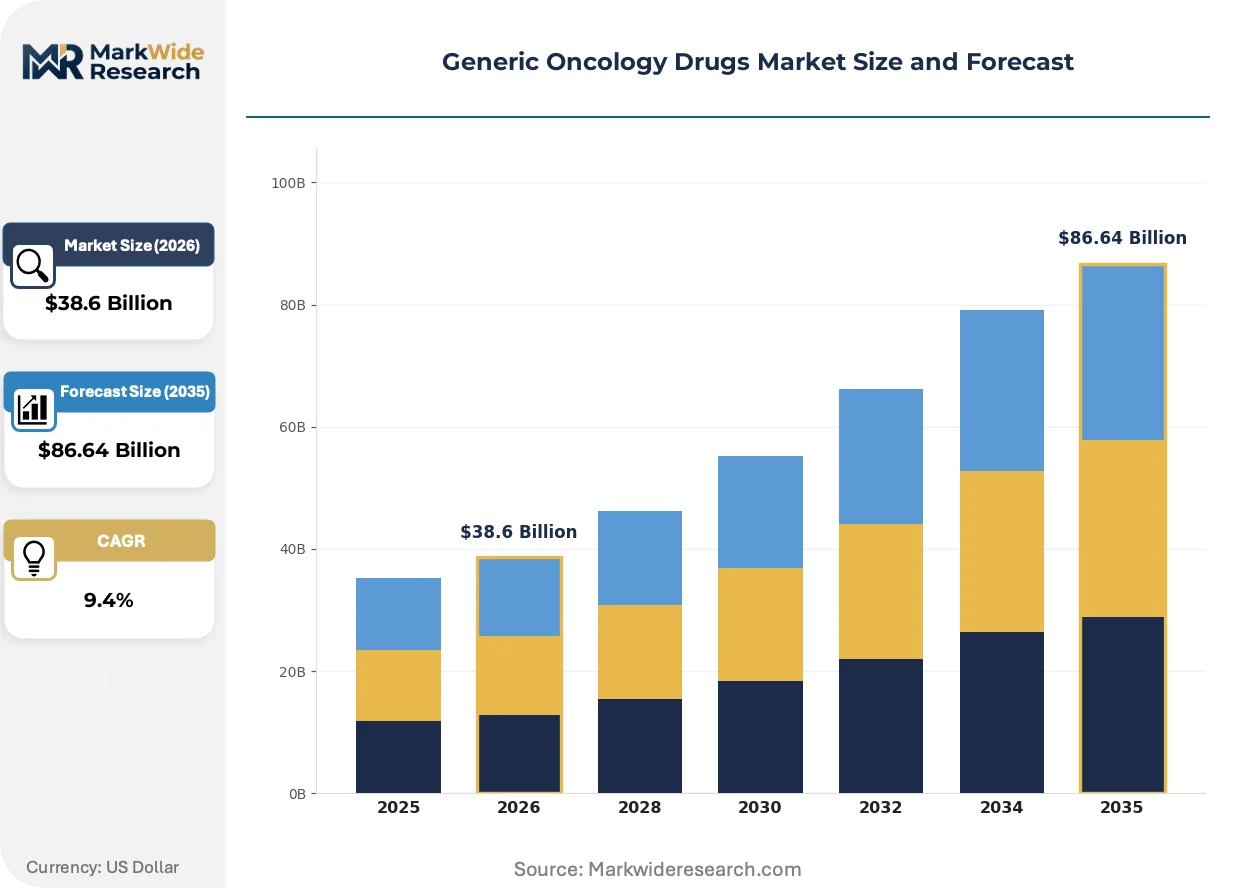
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy Agents, Targeted Therapies, Immunotherapies, Hormonal Therapies End User: Hospitals, Outpatient Clinics, Specialty Pharmacies, Research Institutions Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular Therapy Area: Breast Cancer, Lung Cancer, Colorectal Cancer, Leukemia |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Fresenius Kabi AG, Sandoz Group AG, Mylan N.V. (Viatris), Biocon, Apotex Inc., Zydus Cadila, Hikma Pharmaceuticals, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generic Oncology Drugs Market Strategic Shifts & Innovations
A fundamental transition is underway from high-volume, commoditized chemotherapies toward more complex and higher-value biosimilars. This evolution reshapes manufacturing requirements, elevates regulatory scrutiny, and demands more sophisticated commercial strategies from market participants.
Modular production technology is a key innovation for biosimilar manufacturing. These systems, which utilize single-use bioreactors and flexible facility designs, are being adopted by both established generic firms and specialized CDMOs. This technology is decentralizing production capabilities from monolithic plants to smaller, multi-product sites, enabling faster product changeovers and more resilient supply chains.
China's National Medical Products Administration (NMPA) has implemented policies that accelerate the review and approval of generic drugs, especially those on the national essential medicine list. This regulatory shift drastically reduces market entry timelines for both domestic and international manufacturers operating in the country. The injectable chemotherapy and first-generation targeted therapy segments are most affected, experiencing intensified competition and rapid price declines.
Value-based contracting models are gaining traction among large healthcare purchasers. This changes purchasing criteria from a simple per-unit price to a focus on total cost of care, patient outcomes, and supply chain reliability. This trend is most visible in the United States and the United Kingdom, where integrated delivery networks and national health systems prioritize budget predictability.
Generic Oncology Drugs Market Segmentation
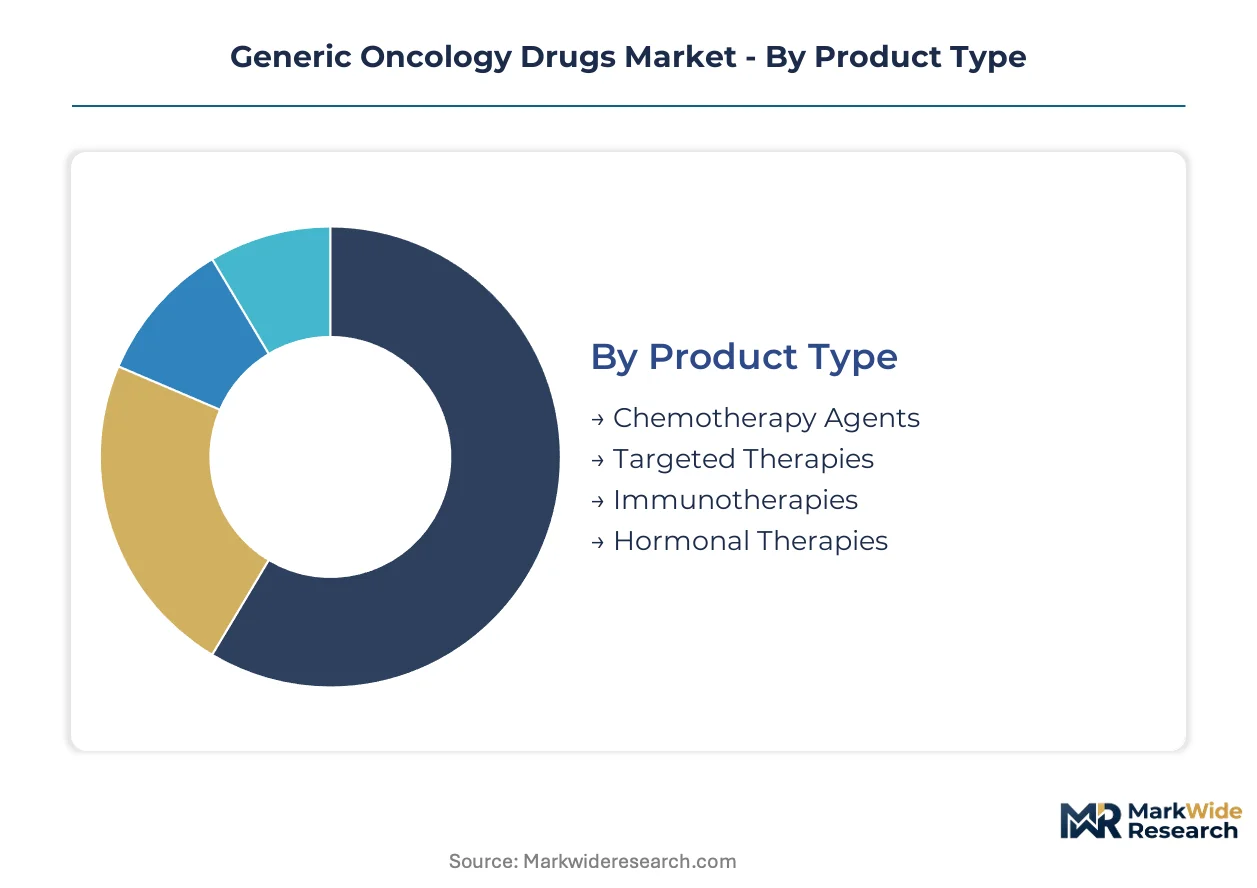
The Generic Oncology Drugs Market segmentation provides a granular view of product types, end-users, delivery modes, and therapy areas that collectively define market dynamics. Understanding these distinct segments helps manufacturers tailor product development and commercial strategies. This detailed analysis highlights areas of high demand and emerging growth opportunities within the global landscape.
Product Type:
The integration of generic oncology drugs into treatment protocols varies significantly by product type, reflecting their established use or novel applications within cancer care.
- Chemotherapy Agents:These are cytotoxic drugs designed to kill rapidly dividing cells, forming the backbone of many cancer treatment regimens. Demand concentrates in hospital systems and public health programs across countries like Brazil and India due to their broad applicability and cost-effectiveness.
- Targeted Therapies:These drugs specifically block cancer cell growth by interfering with specific molecular targets involved in tumor development. The demand for generic versions is expanding in developed markets like the United States and Europe, driven by recent patent expirations of blockbuster biologics.
- Immunotherapies:This segment includes generic versions of drugs that harness the body's immune system to fight cancer cells.
- Hormonal Therapies:These agents block or add hormones to slow or stop cancer growth, particularly in hormone-sensitive cancers.
Chemotherapy Agents leads volumes today; Targeted Therapies is gaining share fastest.
End User:
The purchasing power and treatment delivery models of different end-user segments significantly influence procurement patterns for generic oncology drugs.
- Hospitals:These institutions serve as primary points of care for complex cancer treatments, including chemotherapy and targeted therapy infusions. Hospital Group Purchasing Organizations (GPOs) consolidate purchasing power, favoring manufacturers capable of large-volume, consistent supply.
- Outpatient Clinics:These facilities provide chemotherapy and other cancer treatments in a non-hospital setting, emphasizing patient convenience and cost efficiency. The shift towards oral oncology therapies is increasing demand from these clinics, particularly in urban centers.
- Specialty Pharmacies:These pharmacies specialize in dispensing high-cost, complex medications, including many oral oncology drugs, providing patient support and adherence programs.
- Research Institutions:These entities utilize generic oncology drugs for clinical trials, drug development, and academic research purposes.
Hospitals command the largest procurement volumes; Outpatient Clinics are expanding their treatment capacity rapidly.
Delivery Mode:
Patient convenience and clinical efficacy drive preferences across various delivery modes for generic oncology drugs, influencing both hospital and home-based care.
- Intravenous:This mode involves administering drugs directly into a vein, typically in a hospital or clinic setting, allowing for rapid and precise dosing. Many traditional chemotherapy agents and biologics are administered intravenously, requiring professional oversight.
- Oral:Oral therapies are taken by mouth, offering significant convenience for patients and enabling home-based treatment, reducing hospital visits. The development of generic oral versions of previously intravenous drugs is a major growth area, particularly in regions with expanding home healthcare.
- Subcutaneous:This delivery method involves injecting drugs under the skin, offering a less invasive option than intravenous administration.
- Intramuscular:Intramuscular injections deliver medication deep into muscle tissue, suitable for certain drug formulations.
Intravenous delivery remains the most common; Oral delivery is seeing the steepest expansion trajectory.
Therapy Area:
The prevalence of specific cancer types and the maturity of their treatment protocols dictate the demand profile for generic oncology drugs across different therapy areas.
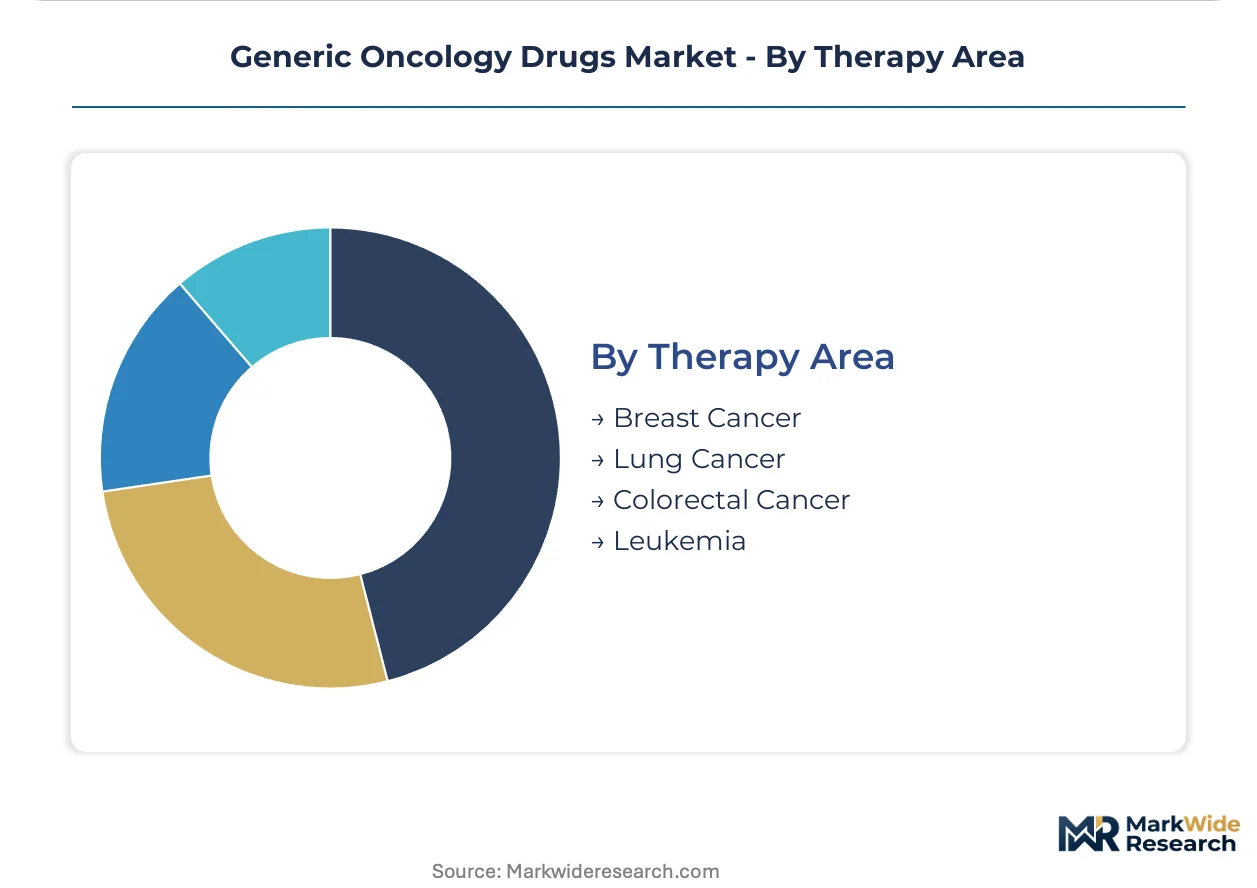
- Breast Cancer:This therapy area includes a broad range of generic chemotherapies, hormonal therapies, and targeted therapies used in various stages of breast cancer treatment. Public health initiatives and screening programs in countries like China are increasing the diagnosed patient pool.
- Lung Cancer:Generic drugs for lung cancer address both small cell and non-small cell types, encompassing chemotherapy and targeted therapies. The high incidence rates globally, particularly in Asia, drive substantial demand for cost-effective treatment options.
- Colorectal Cancer:This segment involves generic drugs for treating cancers of the colon and rectum, including various chemotherapy regimens.
- Leukemia:Generic treatments for leukemia target different forms of blood cancer, including both acute and chronic types.
Breast Cancer therapies represent a mature segment; Lung Cancer treatments are experiencing significant innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States market prioritizes value-based contracting for generic oncology drugs, China's NMPA policies focus on accelerating market access for essential medicines. This creates divergent strategic approaches for manufacturers seeking to capitalize on regional demand. Brazil's public health system drives large-volume, price-sensitive procurement, contrasting with Germany's emphasis on high-quality injectable formulations.
United States
Hospital Group Purchasing Organizations and large retail pharmacy networks drive demand for cost-effective generic oncology drugs. The FDA's abbreviated new drug application (ANDA) process facilitates market entry for bioequivalent products. Boston's biotech cluster attracts specialized manufacturing for complex biosimilars, fostering innovation in formulation and delivery.
China
Expanding public health insurance coverage and a national essential medicine list fuel significant demand for generic cancer therapies. The NMPA has implemented policies to accelerate the review and approval of these drugs, particularly for first-generation targeted therapies. The Yangtze River Delta region hosts numerous domestic manufacturers expanding production capacity for both APIs and finished formulations.
Brazil
Brazil's Sistema Único de Saúde (SUS) expands access to cancer care, creating large-volume, price-sensitive demand for generic chemotherapy and supportive care drugs. ANVISA, the national health surveillance agency, streamlines approval pathways for essential medicines to improve public access. São Paulo's pharmaceutical industry benefits from local manufacturing partnerships and distribution networks for oncology products.
India
A large patient pool and focus on cost-effectiveness drive substantial demand for generic oncology drugs, alongside its role as a major API supplier. The CDSCO oversees stringent bioequivalence and manufacturing standards for both domestic and export markets. Hyderabad and Ahmedabad serve as major hubs for generic API production and advanced formulation development, supporting global supply chains.
Germany
Established healthcare systems and a focus on quality drive consistent demand for generic oncology drugs, particularly for complex injectable formulations. The European Medicines Agency (EMA) biosimilar pathway facilitates market entry across the European Union. Frankfurt's pharmaceutical cluster supports advanced research and development, alongside specialized production facilities for high-value oncology products.
Generic Oncology Drugs Market Key Industry Players
United States and European producers anchor one tier of the generic oncology drugs market; Indian and Chinese specialists hold another. The market exhibits a tiered structure, with established multinational pharmaceutical firms and specialized biosimilar manufacturers. Large-volume contract specialists focus on securing high-volume, multi-year agreements with Group Purchasing Organizations. Companies prioritize expanding their manufacturing footprint and navigating varied international regulatory requirements.
Among the established global players, Teva Pharmaceutical Industries Ltd. exemplifies a firm leveraging a broad manufacturing footprint and established supply chains in key markets. Sandoz Group AG, a Switzerland-based company, represents a major player utilizing an extensive portfolio of biosimilars and small molecules for large-volume contracts. Germany's Fresenius Kabi AG occupies a position as a specialist in injectable oncology products, aligning with the acute care hospital formulary needs across various regions.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Fresenius Kabi AG |
| Sandoz Group AG |
| Mylan N.V. (Viatris) |
| Biocon |
| Apotex Inc. |
| Zydus Cadila |
| Hikma Pharmaceuticals |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Outsourced API production significantly influences the generic oncology drugs market, anchoring both supply position and the pricing power of finished product manufacturers. This model allows for specialized manufacturing but introduces dependencies.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for generic oncology drugs, intensifying competition. Value-based contracting models are gaining traction, shifting procurement criteria beyond simple per-unit price. Volume scale for large-volume contracts and specialized manufacturing expertise for complex biosimilars drive price differentiation. Pricing pressure stems from the influx of new generic entrants following patent expirations, making public health agencies and GPOs highly price-sensitive.
Supply Chain Analysis
China's NMPA policies prioritizing domestic essential medicines are reshaping sourcing strategies for generic oncology drugs, encouraging local production and reducing reliance on external suppliers. Geographic supply concentrates heavily on API manufacturers in India and China. Active pharmaceutical ingredients (APIs) and specialized excipients are critical dependencies, creating single-source vulnerability for key inputs. Distribution runs through hospital Group Purchasing Organizations and specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The generic oncology drugs market functions as a stable compounder, driven by expanding public health coverage worldwide. This fundamental force ensures consistent, long-term demand for cost-effective cancer treatments.
For Market Incumbents: Anticipate continued price erosion from an influx of new generic entrants and originator legal strategies. Incumbents should secure large-volume, multi-year contracts with hospital Group Purchasing Organizations to maintain market share. Investing in advanced biosimilar manufacturing facilities in Germany ensures adherence to stringent EMA standards and offers a competitive advantage. Focus on channel control through established supply chains and robust regulatory compliance.
For New Entrants and Emerging Players: Outpatient clinics represent an underserved buyer archetype with rapidly expanding treatment capacity for oral oncology therapies. New entrants should target emerging markets in Southeast Asia, where public and private insurance coverage is improving. Focus on developing novel oral drug formulations of existing intravenous oncology drugs to meet outpatient demand. Strategic partnerships with local distribution networks offer a critical go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for biosimilar manufacturers because of the high capital intensity and stringent regulatory hurdles in production. This market offers long-term viability, driven by continuous patent expirations and expanding public health coverage. Acquirers should target vertically integrated mid-cap specialists with robust API supply chains and specialized biomanufacturing expertise. The approval rate for next-generation biosimilars by regulatory bodies like the FDA and EMA serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Enables high-volume production of complex biosimilars to meet global demand. |
| Regulatory Approval Pathway | Accelerates market entry for generic oncology drugs through streamlined FDA and EMA processes. |
| Long-term Supply Agreement | Secures consistent demand from hospital Group Purchasing Organizations and public health systems. |
| Pipeline Diversification | Broadens product offerings beyond mature chemotherapies into next-generation targeted therapies. |
| Geographic Expansion | Penetrates underserved markets in Southeast Asia, capitalizing on improving healthcare access. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, integrating primary and secondary research. Primary interviews engaged pharmaceutical executives, regulatory affairs leads, hospital procurement managers, and specialty pharmacy directors. Secondary data sources included FDA filings, EMA submissions, NMPA policies, and company financial disclosures. This approach enabled robust bottom-up and top-down triangulation.
The forecast window was anchored to historical reference periods, establishing a baseline for projections. Volume and value outputs reflect a triangulated approach, modeling segmentation dimensions like product type, end-user, delivery mode, and therapy area. Compound annual growth rates were derived from multi-factor regression, incorporating patent expiration schedules and public health expenditure trends.
Underlying measurement precision varies by segment; chemotherapy agents and targeted therapies carry tighter precision than immunotherapies. Forecasts reflect assumptions, though geopolitical risks, regulatory shifts could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Global Immuno Oncology Assays Market
Biopharmaceuticals
Echinocandins Market
Biopharmaceuticals
Recombinant Therapeutic Antibodies and Proteins Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Terbinafine Tablet Market