
 Anti-Tumor Drugs Market | 2026-2036
Anti-Tumor Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Tumor Drugs Market Outlook
Good Manufacturing Practice certification for active pharmaceutical ingredients is bifurcating the competitive landscape into qualified and non-qualified suppliers. F. Hoffmann-La Roche Ltd leverages its vertically integrated biologics manufacturing network across Basel and Penzberg to sustain supply security for monoclonal antibody portfolios. Novartis AG anchors its position through radioligand therapy production capabilities at its Indianapolis and Ivrea facilities. Bristol-Myers Squibb Company differentiates via checkpoint inhibitor specialization, with nivolumab and ipilimumab manufacturing concentrated at its Devens and Syracuse sites.
Anti-tumor drugs comprise synthetic small molecules, recombinant proteins, monoclonal antibodies, antibody-drug conjugates, and cell-based therapies engineered to interrupt oncogenic signaling, induce apoptosis, or activate immune-mediated tumor cell destruction; these agents require sterile aseptic filling, cold-chain distribution at 2-8°C, and stability validation under ICH Q1A guidelines to preserve potency from manufacture through patient administration. Immunotherapy commands premium pricing and fastest volume expansion as PD-1/PD-L1 inhibitors displace chemotherapy in first-line non-small cell lung cancer and melanoma settings. Targeted therapy occupies mature but durable revenue pools in chronic myeloid leukemia and HER2-positive breast cancer, where generic erosion of small-molecule tyrosine kinase inhibitors is reshaping margin structures. Chemotherapy persists as a cost-competitive backbone in resource-constrained settings and combination regimens, particularly for triple-negative breast cancer and aggressive lymphomas.
FDA's Breakthrough Therapy designation and EMA's PRIME eligibility scheme compress development timelines, while WHO prequalification programs govern access to lower-cost biosimilars in low-income markets. China's NMPA reform of drug review procedures and inclusion of novel oncology agents in the National Reimbursement Drug List are accelerating domestic market formation. Stakeholders must monitor evolving HTA methodologies in Germany's G-BA and England's NICE, as incremental benefit thresholds increasingly determine market access and pricing latitude for novel mechanisms.
Market Dynamics
Checkpoint inhibitor therapy is compressing first-line treatment paradigms across solid tumor categories, forcing incumbents to defend chemotherapy and targeted therapy positions through combination trial designs and biosimilar cost positioning.
Growth Catalysts
- Accelerated Approval Pathways:FDA Breakthrough Therapy and EMA PRIME eligibility compress Phase II-to-approval timelines from six years to under four, enabling earlier commercialization for novel mechanisms.
- Radioligand Therapy Infrastructure:Academic medical centers in Germany and the United States are installing cyclotron and radiopharmacy capabilities to support lutetium-177 and actinium-225-based regimens.
- China's NRDL Expansion:NMPA reform and National Reimbursement Drug List inclusion of PD-1 inhibitors are unlocking volume access for domestic biotech innovators.
Market Restraints
- Cold-Chain Distribution Costs:Monoclonal antibodies and cell therapies require 2-8°C validated logistics with real-time temperature monitoring, inflating per-dose fulfillment costs by 15-25% versus small molecules.
- API Supply Concentration:High-potency cytotoxic active pharmaceutical ingredient manufacturing concentrates in Switzerland, India, and select US sites, creating single-source vulnerability for antibody-drug conjugate payloads.
- Reimbursement Compression:Germany's G-BA benefit assessment and England's NICE cost-effectiveness thresholds are tightening pricing latitude for therapies showing incremental rather than transformative survival gains.
Strategic Opportunities
- Sub-Saharan Africa Access Programs:WHO prequalification pathways for trastuzumab and rituximab biosimilars present volume expansion for manufacturers willing to accept tiered pricing structures.
- ADC-IO Combinations:Antibody-drug conjugate and checkpoint inhibitor pairing in HER2-low breast cancer and urothelial carcinoma represents a mechanistic white space with limited approved competitors.
- Japan's Sakigake Designation:PMDA's early approval framework for regenerative medicines and innovative oncology drugs offers priority review and extended market exclusivity for first-in-class entrants.
Industry Challenges
- Cell Therapy Manufacturing Scale-Up:Autologous CAR-T production requires patient-specific vector transduction and expansion, constraining batch throughput and creating multi-week vein-to-vein timelines.
- Companion Diagnostic Co-Development:CDx validation and FDA premarket approval synchronization with drug filing adds 12-18 months to development schedules and fragments diagnostic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Tumor Drugs Market |
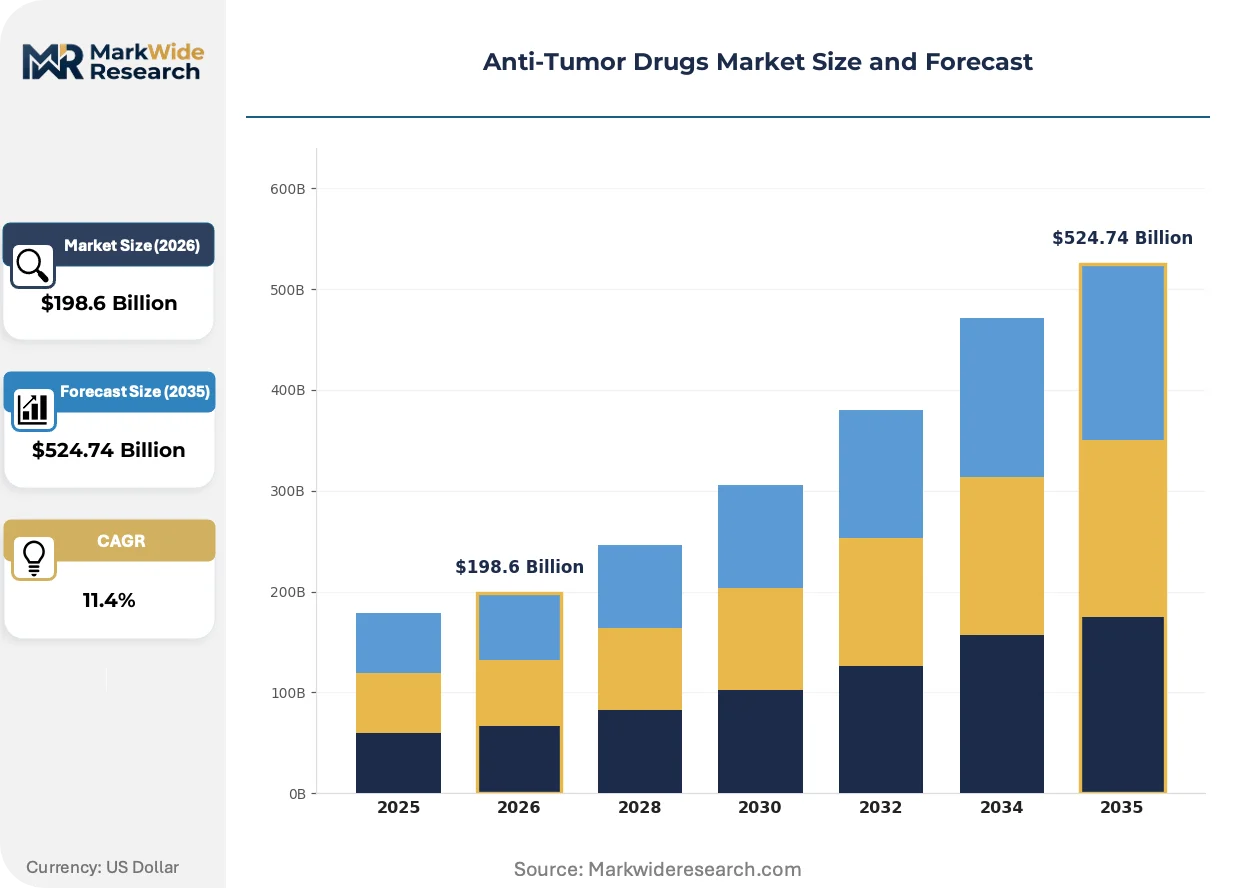
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $524.74 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular Cancer Type: Breast Cancer, Lung Cancer, Colorectal Cancer, Leukemia Patient Demographics: Pediatric, Adult, Geriatric, Pregnant Women |
| Companies Covered | F. Hoffmann-La Roche Ltd, Novartis AG, Bristol-Myers Squibb Company, Merck & Co., Inc., Pfizer Inc., AstraZeneca PLC, Johnson & Johnson, Amgen Inc., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Tumor Drugs Market Strategic Shifts
Biologic engineering and regulatory science are converging to enable precision dosing and site-of-care administration, reducing hospital dependency and reshaping competitive moats around manufacturing flexibility.
Bispecific T-cell engagers are miniaturizing therapeutic footprints by consolidating dual-antigen recognition into single constructs, eliminating the need for combination regimens. Community oncology practices in the United States are adopting these formats for outpatient administration, displacing infusion center requirements. This compression is enabling earlier-line positioning and expanding addressable prescriber bases beyond academic centers.
EMA's revised Clinical Trial Regulation harmonizes protocol submission and safety reporting across EU member states, reducing multinational trial activation timelines. Sponsors are consolidating European development strategies around centralized CTA procedures rather than country-by-country filings. Oncology trials with adaptive designs and expanded cohorts are capturing the greatest efficiency gains under this framework.
Hospital procurement consortia in Germany and France are unbundling drug acquisition from infusion services, forcing manufacturers to compete on transparent net pricing rather than bundled rebates. This disintermediation favors suppliers with direct-to-pharmacy distribution capabilities and real-world evidence contracts. The shift is most pronounced in immuno-oncology, where therapeutic alternatives create genuine substitution elasticity.
Anti-Tumor Drugs Market Segmentation
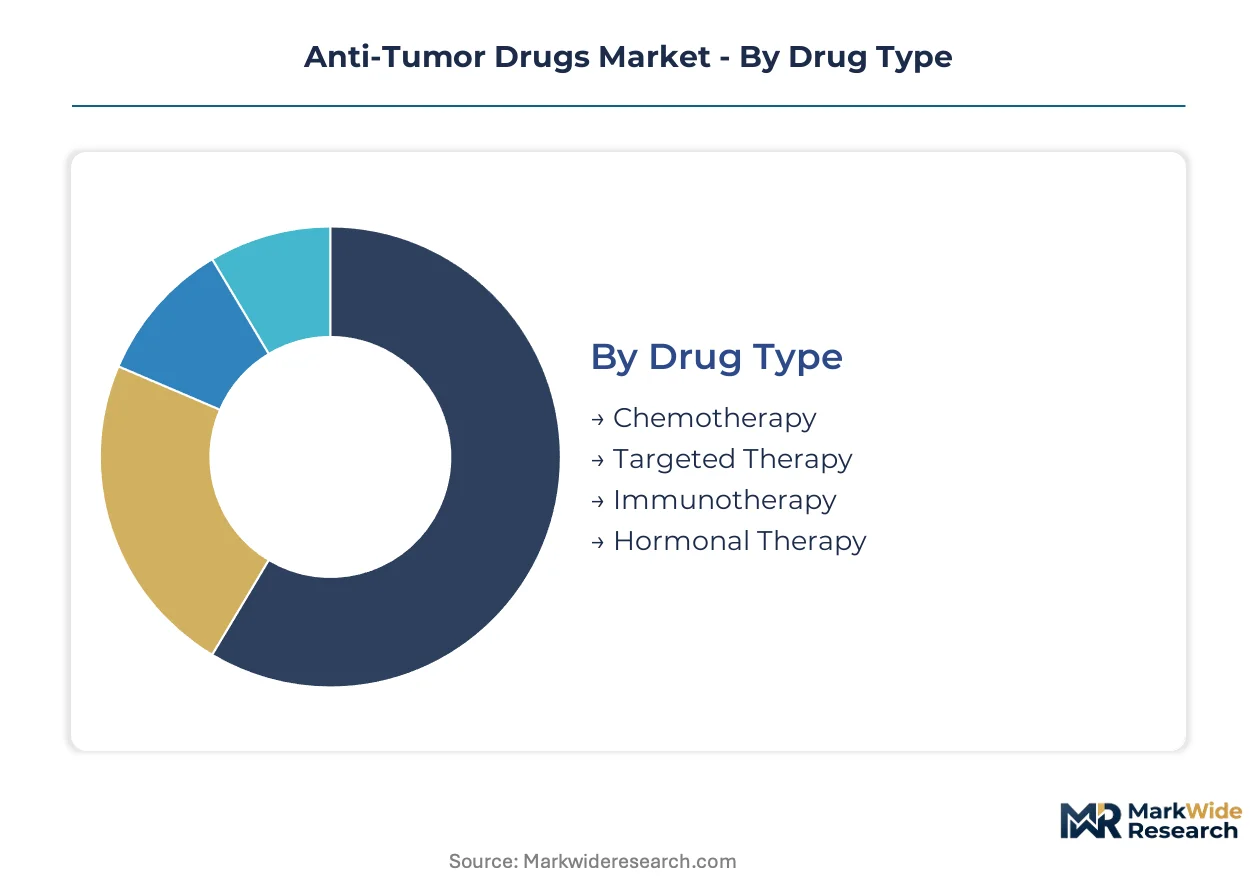
Segmentation in anti-tumor drugs reveals distinct manufacturing, distribution, and reimbursement requirements across therapeutic modalities. Drug type and administration route classifications directly determine cold-chain infrastructure investments and site-of-care economics.
Drug Type:
Domestic manufacturing concentrates immunotherapy and targeted therapy production in the United States, Switzerland, and China, while chemotherapy APIs flow predominantly from Indian and Chinese export hubs.
- Immunotherapy:Engineered monoclonal antibodies and checkpoint inhibitors that activate T-cell mediated tumor destruction. Demand clusters in academic medical centers across the United States and Germany where infusion infrastructure and reimbursement density align; cold-chain requirements at 2-8°C constrain distribution to qualified logistics networks.
- Targeted Therapy:Small-molecule tyrosine kinase inhibitors and hormone receptor modulators designed for specific oncogenic mutations. Prescription volume concentrates in outpatient oncology practices in Japan and England where oral bioavailability enables home administration; generic erosion in chronic myeloid leukemia and HER2-positive breast cancer is compressing margin structures.
- Chemotherapy:Cytotoxic alkylating agents, antimetabolites, and plant alkaloids that indiscriminately target rapidly dividing cells.
- Hormonal Therapy:Selective estrogen receptor modulators and aromatase inhibitors for hormone-sensitive malignancies.
Chemotherapy holds the largest share; momentum sits with immunotherapy.
Administration Route:
Route selection dictates site-of-care requirements, with intravenous formats demanding hospital infrastructure and oral formulations enabling community pharmacy dispensing.
- Intravenous:Direct vascular delivery of biologics and cytotoxic agents requiring sterile compounding and infusion center supervision. Utilization concentrates in tertiary hospitals across France and the United States where reimbursement bundles cover drug acquisition plus administration services; checkpoint inhibitors and antibody-drug conjugates drive volume expansion.
- Oral:Self-administered small molecules and targeted agents with defined bioavailability profiles. Adoption accelerates in Italy and Spain where pharmacy benefit structures favor home-based regimens; tyrosine kinase inhibitors for lung cancer and chronic lymphocytic leukemia anchor demand.
- Subcutaneous:Depot formulations and monoclonal antibody preparations for sustained release.
- Intramuscular:Hormonal depot injections and supportive care agents.
Intravenous administration dominates current revenue; oral formats are climbing the fastest.
Cancer Type:
Oncology drug development pipelines and regulatory approvals concentrate on indications with large addressable populations and defined molecular targets.
- Lung Cancer:Non-small cell and small cell carcinomas with high mutation burden and PD-L1 expression variability. Clinical trial infrastructure in the United States and China generates first-line immunotherapy approvals; screening program expansion in South Korea and Japan is enlarging early-stage detectable populations.
- Breast Cancer:Hormone receptor-positive, HER2-positive, and triple-negative subtypes with distinct therapeutic pathways. Treatment centers in Germany and England deploy CDK4/6 inhibitors and HER2-directed antibody-drug conjugates; biosimilar trastuzumab penetration is reshaping competitive dynamics.
- Colorectal Cancer:Adenocarcinomas of the colon and rectum with microsatellite instability stratification.
- Leukemia:Acute and chronic myeloid and lymphoid malignancies requiring intensive induction regimens.
Breast cancer commands the largest therapeutic investment; lung cancer is gaining share fastest.
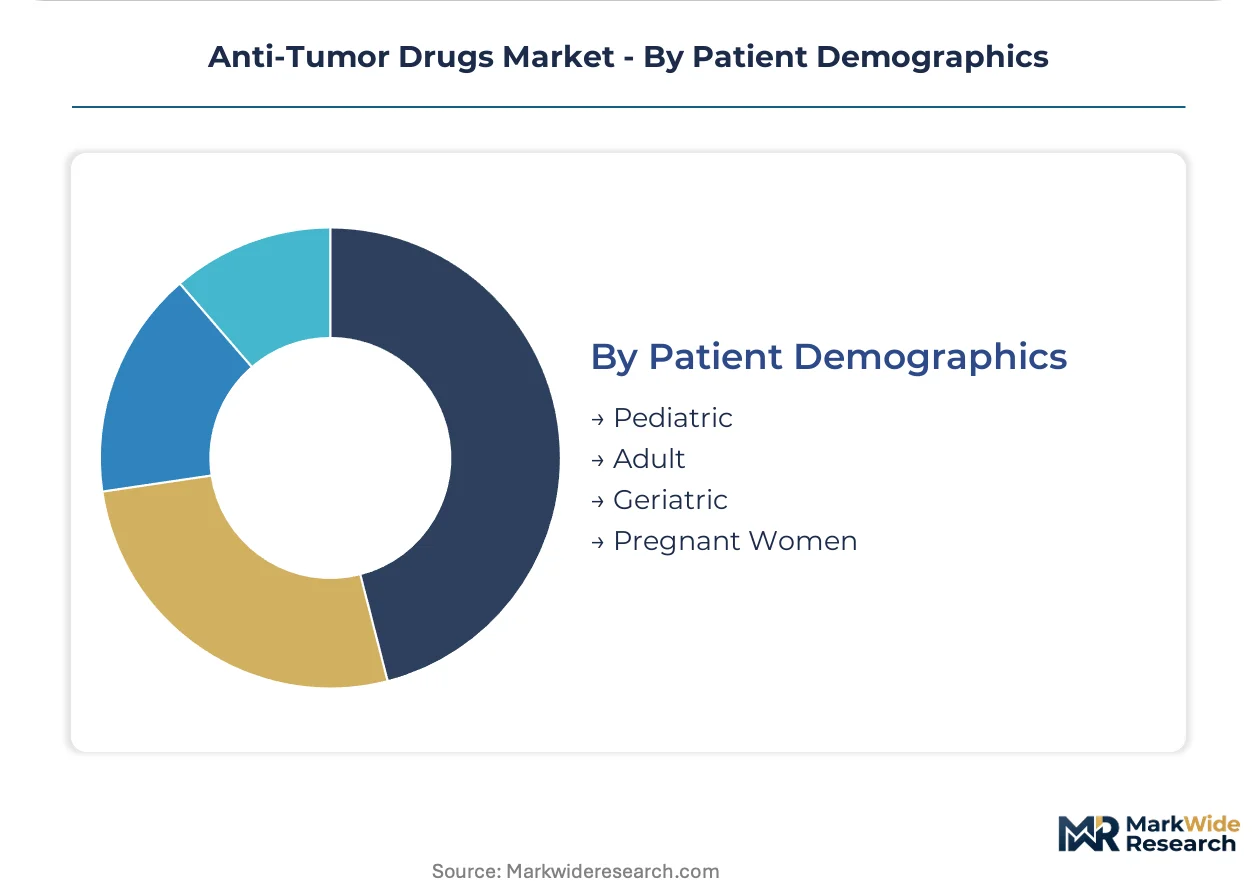
Patient Demographics:
Age-stratified dosing protocols and organ function adjustments create formulation and labeling complexity across pediatric, adult, and geriatric populations.
- Adult:Patients aged 18-64 with standard organ function and performance status. Volume concentrates in United States community oncology networks and Chinese tertiary hospitals where checkpoint inhibitors and targeted agents displace chemotherapy; clinical trial eligibility criteria historically center this demographic.
- Geriatric:Patients over 65 with comorbidity burden and polypharmacy considerations. Demand expands in Japan and Italy where aging demographics enlarge the addressable population; dose-modified regimens and supportive care integration dominate prescribing patterns.
- Pediatric:Infants, children, and adolescents with developmentally specific pharmacokinetics.
- Pregnant Women:Patients requiring teratogenic risk stratification and fetal-sparing protocols.
Adult patients represent the dominant segment; geriatric populations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain terminals anchor European distribution for temperature-sensitive biologics, while Shanghai Pudong International Airport's cargo hub underwrites Asia-Pacific oncology supply security. These infrastructure assets compress vein-to-vein timelines for cell therapies and monoclonal antibodies.
United States
Academic medical centers in Boston and Houston drive checkpoint inhibitor adoption through NCI-designated cancer center networks. FDA's Breakthrough Therapy designation compresses Phase II-to-approval timelines below four years for novel mechanisms. The Research Triangle Park cluster in North Carolina concentrates contract manufacturing for antibody-drug conjugate payloads.
Germany
Germany's G-BA benefit assessment determines pricing latitude for therapies entering the statutory health insurance system. EMA's centralized marketing authorization procedures enable simultaneous EU-wide access from Frankfurt-based regulatory submissions. The Rhine-Main biotech corridor hosts radioligand therapy production facilities serving lutetium-177 demand.
China
NMPA reform of drug review procedures accelerates domestic PD-1 inhibitor approvals for National Reimbursement Drug List inclusion. Shanghai's Zhangjiang Hi-Tech Park concentrates biologics manufacturing capacity for export-qualified monoclonal antibodies. Tiered pricing structures unlock volume access for biosimilar trastuzumab in provincial procurement tenders.
Switzerland
Swissmedic's accelerated access pathways align with EMA conditional marketing authorizations for priority oncology medicines. Basel's pharmaceutical cluster integrates active pharmaceutical ingredient synthesis with finished dose formulation for high-potency cytotoxics. The country's bilateral recognition agreements with FDA streamline multi-territory filing strategies.
Japan
PMDA's Sakigake designation offers priority review and extended market exclusivity for first-in-class oncology entrants. The Kansai region's Osaka pharmaceutical hub specializes in oral tyrosine kinase inhibitor formulation for Asia-Pacific export. Aging demographics enlarge the geriatric oncology addressable population beyond standard clinical trial eligibility criteria.
Anti-Tumor Drugs Market Competitive Environment
Listed leaders compete with private specialists across manufacturing scale and therapeutic modality concentration. The market structure consolidates around vertically integrated biologics manufacturers with captive fill-finish capacity and radiopharmaceutical specialists with cyclotron networks. Three archetypes dominate: checkpoint inhibitor specialists with academic center anchoring, antibody-drug conjugate developers with payload manufacturing control, and radioligand therapy platforms with site-of-care logistics. Competitive moves center on M&A for manufacturing capacity and strategic partnerships for companion diagnostic co-development.
Among Swiss-based pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd and Novartis AG occupy positions spanning immunotherapy and targeted therapy archetypes. Bristol-Myers Squibb Company exemplifies the checkpoint inhibitor specialization model with nivolumab and ipilimumab manufacturing concentration. These three entities represent distinct strategic postures within the competitive set: integrated biologics manufacturing, radioligand therapy infrastructure, and immuno-oncology portfolio depth.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Pfizer Inc. |
| AstraZeneca PLC |
| Johnson & Johnson |
| Amgen Inc. |
| Eli Lilly and Company |
| Others |
Value Chain & Pricing Dynamics
Cyclotron network density in Germany and the United States creates scale advantages that simultaneously concentrate radioligand therapy supply and establish price floors for lutetium-177-based regimens. Academic medical centers with captive radiopharmacy capabilities command procurement leverage over manufacturers lacking site-of-care integration, compressing margins for outsourced distribution models while rewarding vertically integrated producers.
Pricing Analysis
Certification level creates the primary spread across the anti-tumor drugs landscape, with FDA-breakthrough and EMA-PRIME designated therapies commanding substantial premiums over standard-of-care alternatives. GMP-active pharmaceutical ingredient qualification and cold-chain validation at 2-8°C differentiate pricing tiers, while Germany's G-BA benefit assessment and England's NICE cost-effectiveness thresholds intensify downward pressure on therapies showing incremental survival gains. Community oncology practices exhibit highest price sensitivity due to reimbursement bundle constraints, whereas academic medical centers with research funding demonstrate greater tolerance for premium mechanisms.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes directly impact monoclonal antibody inbound logistics costs, with Shanghai Pudong cargo hub congestion creating ripple effects through Swiss and German fill-finish networks. High-potency cytotoxic API manufacturing concentrates in Switzerland, India, and select United States sites, drawing from specialized fermentation feedstocks, single-use bioreactor components, and sterile filtration assemblies. Single-source vulnerability for antibody-drug conjugate payloads represents the dominant structural risk. Distribution runs through hospital procurement consortia in Germany and France, with direct-to-pharmacy channels gaining share as infusion service unbundling accelerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in companion diagnostic co-development and real-world evidence contracting are expanding faster than standalone drug revenue, creating recurring revenue streams that offset patent cliff exposure.
For Market Incumbents: Consolidate manufacturing capacity around captive fill-finish networks in Basel and Penzberg to defend against biosimilar erosion in HER2-positive and CD20-positive indications. Lock in cyclotron partnerships for radioligand therapy production before site-of-care infrastructure saturates in German academic centers. Prioritize vertical integration into high-potency cytotoxic API synthesis to reduce single-source dependency for ADC payloads. For New Entrants and Emerging Players: Differentiate on subcutaneous administration formats that displace infusion center requirements in community oncology practices across Italy and Spain. Target ADC-IO combination white spaces in HER2-low breast cancer and urothelial carcinoma where mechanistic competition remains sparse. Pursue WHO prequalification pathways for trastuzumab and rituximab biosimilars to unlock volume access in Sub-Saharan African markets through tiered pricing acceptance. For Investors and Strategic Acquirers: Radioligand therapy platform specialists with established cyclotron networks and lutetium-225 production capabilities represent the most defensible acquisition archetype given site-of-care infrastructure moats. Long-term viability hinges on manufacturing flexibility across biologic modalities rather than single-mechanism concentration. Monitor Japan's Sakigake designation awards as an inflection indicator for first-in-class oncology entrants securing priority review and extended exclusivity.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Adaptive trial designs with expanded cohorts accelerate FDA Breakthrough Therapy eligibility timelines. |
| Regulatory Approval Pathway | EMA centralized procedures enable simultaneous EU-wide market access from Frankfurt submissions. |
| Manufacturing Scale-Up | Cold-chain capacity expansion at Port of Rotterdam terminals secures biologics distribution integrity. |
| Pipeline Diversification | ADC-IO combinations in urothelial carcinoma address mechanistic white spaces with limited competition. |
| Licensing Agreement | Companion diagnostic co-development partnerships reduce fragmented CDx validation timelines. |
Study Parameters
The analysis maps immunotherapy, targeted therapy, chemotherapy, and radioligand therapy sub-sectors, each validated through formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary interviews with drug development executives and GPO contracts managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue reconciliation ensured triangulation consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by drug type, administration route, cancer indication, and patient demographic, with regional regulatory clusters as an additional dimension. CAGRs derived from patent expiry schedules, biosimilar entry curves, and reimbursement expansion trajectories. Forecast inputs incorporated NMPA reform velocity, NRDL inclusion probability, and G-BA benefit assessment tightening patterns.
Decision-makers should treat outputs as directional under assumptions of stable reimbursement density in United States and German markets; material deviation through NICE cost-effectiveness threshold shifts or China's provincial procurement tender volatility would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Global MRSA Drugs Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
North America Contraceptives Market