
 United States Cancer Biomarkers Market | 2026-2036
United States Cancer Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cancer Biomarkers Market Analytics
The gap between CLIA-certified laboratory-developed tests and FDA-cleared in vitro diagnostic kits is repositioning competitive boundaries in the United States cancer biomarkers landscape. Thermo Fisher Scientific leverages its end-to-end sequencing platform to anchor high-complexity oncology workflows in major health systems. Guardant Health dominates liquid biopsy commercialization through its Medicare-cleared comprehensive genomic profiling assay. Exact Sciences competes in colorectal cancer screening by extending its multi-cancer early detection pipeline beyond its established stool-based franchise.
Cancer biomarkers are measurable biological molecules—proteins, nucleic acids, metabolites, or cellular vesicles—whose presence, concentration, or molecular alteration indicates normal or pathological processes, with immunoassay detection thresholds typically reaching picogram-per-milliliter sensitivity for serum-based oncology panels. Their primary commercial purpose centers on enabling early cancer detection, guiding targeted therapy selection, and monitoring minimal residual disease recurrence in clinical practice. Protein biomarkers occupy the largest installed base due to decades of CLIA-validated workflow integration, while genetic biomarkers represent the fastest-expanding margin pool as next-generation sequencing costs decline and payer coverage broadens. Genomic sequencing technology leads R&D investment intensity, though PCR retains dominant share in community hospital laboratories where capital constraints limit platform diversification.
FDA, CMS, and CLIA collectively govern market access through premarket authorization pathways, national coverage determinations, and laboratory quality standards that dictate which biomarker tests reach reimbursable clinical use. The FDA's breakthrough devices program compresses review timelines for oncology diagnostics addressing life-threatening conditions, while CMS parallel coverage tracks create immediate commercial viability upon approval. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled biomarker interpretation and state-level laboratory licensing harmonization as determinants of competitive positioning.
Market Dynamics
FDA breakthrough device designations and CMS parallel coverage tracks are compressing commercialization timelines for oncology diagnostics, while academic medical centers in Boston and Houston expand liquid biopsy infrastructure. This regulatory-coverage convergence is redrawing competitive boundaries between CLIA-certified laboratories and FDA-cleared kit manufacturers.
Growth Catalysts
- Medicare coverage expansion:CMS national coverage determinations for companion diagnostics are unlocking immediate reimbursement for comprehensive genomic profiling assays in community oncology practices.
- Liquid biopsy platform maturation:Cell-free DNA isolation technologies are achieving picogram-per-milliliter sensitivity thresholds, enabling minimal residual disease monitoring in solid tumor workflows.
- Integrated health network consolidation:Northeast and California health systems are centralizing oncology reference testing into high-complexity molecular diagnostics hubs.
Market Restraints
- Next-generation sequencing reagent cost volatility:Proprietary library preparation chemistries and flow cell consumables concentrate pricing power with three dominant sequencing platform vendors.
- Laboratory-developed test regulatory uncertainty:FDA draft guidance on CLIA-validated assay oversight is creating compliance timeline ambiguity for academic medical center laboratories.
- Polymerase chain reaction platform lock-in:Capital-constrained community hospitals face switching costs that entrench lower-multiplex testing workflows despite clinical demand for broader profiling.
Strategic Opportunities
- Multi-cancer early detection pipeline expansion:Blood-based screening panels targeting multiple tumor types simultaneously are entering validation studies for asymptomatic population screening.
- Artificial intelligence-enabled biomarker interpretation:FDA guidance development on machine learning-assisted variant classification is creating first-mover positioning for algorithm-integrated assay developers.
- State-level laboratory licensing harmonization:Interstate compact frameworks are reducing operational friction for multi-site reference laboratory networks.
Industry Challenges
- Bioinformatics pipeline integration complexity:Variant annotation and clinical decision support software require specialized computational pathology expertise scarce in community hospital settings.
- Minimal residual disease assay standardization delays:Lack of harmonized analytical validation frameworks across liquid biopsy vendors is complicating clinical utility evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cancer Biomarkers Market |
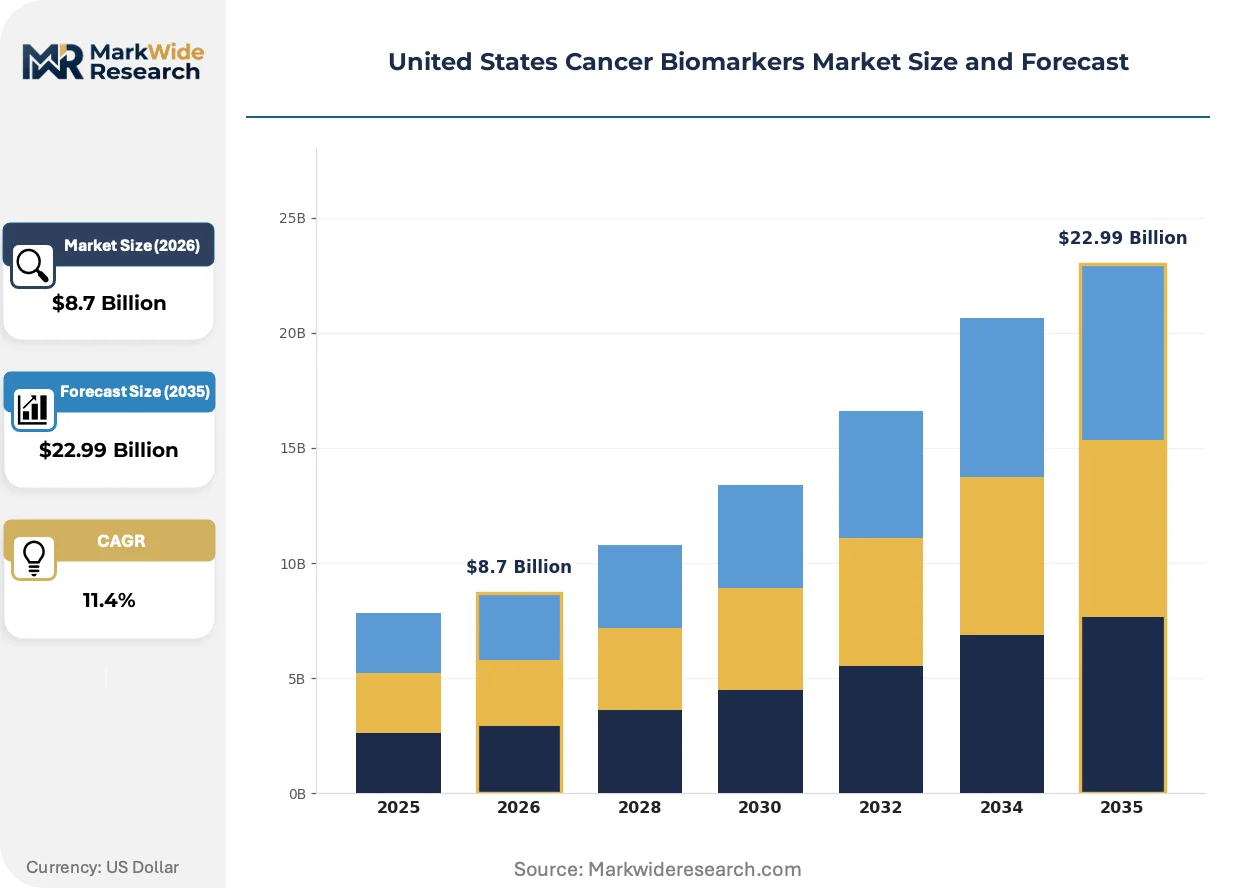
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Biomarkers, Genetic Biomarkers, Cell-Derived Exosomes, Metabolite Biomarkers Application: Diagnostics, Prognostics, Therapeutics, Monitoring End User: Hospitals, Laboratories, Clinics, Research Institutions Technology: Immunoassay, Genomic Sequencing, Mass Spectrometry, PCR |
| Companies Covered | Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, Guardant Health, Exact Sciences, Illumina Inc., Abbott Laboratories, QIAGEN N.V., bioMérieux, Bio-Rad Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cancer Biomarkers Market Evolving Landscape
Liquid biopsy automation and regulatory-coverage convergence are compressing the gap between biomarker discovery and clinical deployment. Three developments are reshaping how oncology diagnostics reach reimbursable use.
Automated cell-free DNA extraction platforms are automating pre-analytical workflow standardization across reference laboratories and academic medical centers. High-complexity molecular diagnostics laboratories in Boston and Houston are deploying these systems to reduce batch-to-batch variability in circulating tumor DNA recovery. This automation is compressing turnaround times for comprehensive genomic profiling from tissue and blood specimens alike.
FDA breakthrough devices program designation pathways are accelerating premarket authorization timelines for oncology diagnostics addressing life-threatening conditions with unmet clinical needs. The agency's parallel review structure with CMS creates immediate commercial viability upon approval, eliminating historical coverage lag. Companion diagnostic developers targeting lung and colorectal cancer indications are prioritizing this dual-track submission strategy.
Health system procurement of molecular diagnostics is consolidating into centralized laboratory service agreements with preferred vendor panels. Integrated delivery networks across the Northeast and California are unbundling test menus from equipment leases, shifting toward reagent rental and per-test pricing structures. This purchasing pattern shift favors platform-agnostic assay developers with flexible commercial models over capital-intensive instrument placements.
United States Cancer Biomarkers Market Segmentation
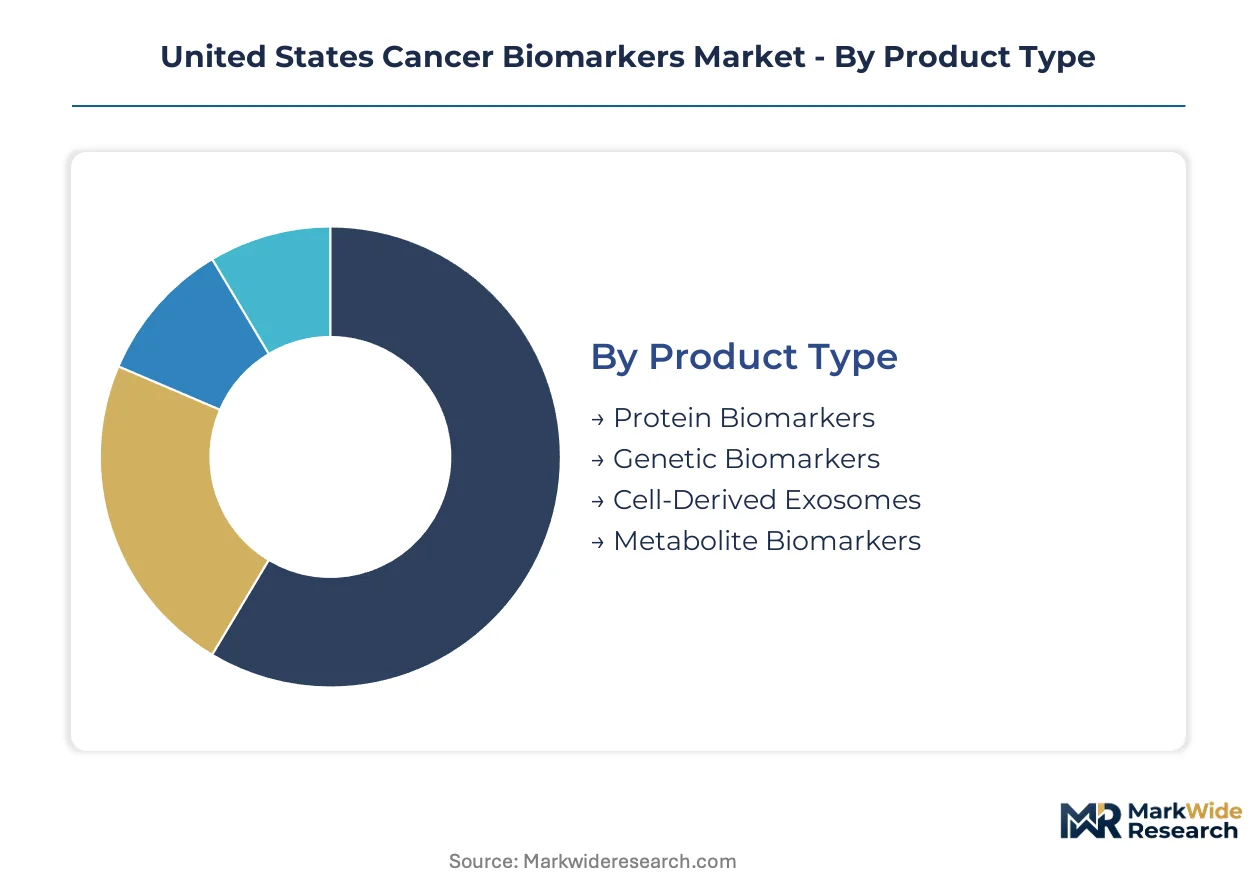
Biomarker platform selection in the United States hinges on installed base maturity, reimbursement pathways, and workflow integration requirements. Segmentation reveals where capital deployment concentrates and which technologies face displacement pressure from next-generation alternatives.
Product Type:
Upgrade cycles vary dramatically across biomarker classes, with protein assays facing replacement pressure from multiplex genomic platforms while metabolite detection emerges from research-only status.
- Protein Biomarkers:Serum-based oncology panels detect circulating proteins at picogram-per-milliliter thresholds using established immunoassay infrastructure. Demand concentrates in community hospital laboratories across the Midwest and Southeast where CLIA-validated workflow familiarity reduces retraining burdens.
- Genetic Biomarkers:Next-generation sequencing of circulating tumor DNA and tissue-derived nucleic acids enables comprehensive genomic profiling for therapy selection. Academic medical centers in Boston and Houston are expanding sequencing capacity to anchor precision oncology programs.
- Cell-Derived Exosomes:Extracellular vesicle isolation platforms capture tumor-derived RNA and protein cargo from blood specimens.
- Metabolite Biomarkers:Mass spectrometry-based metabolic profiling detects oncometabolite alterations for early detection research.
Protein biomarkers sit at the top of the volume ranking, with genetic biomarkers climbing the fastest.
Application:
Reimbursement intensity and evidence requirements shape how biomarker applications penetrate clinical versus research settings.
- Diagnostics:Early cancer detection and screening applications require FDA premarket authorization and CMS national coverage determination for commercial viability. Blood-based multi-cancer early detection panels are entering prospective validation studies for asymptomatic population screening.
- Therapeutics:Companion diagnostic assays guide targeted therapy selection in lung, colorectal, and breast cancer indications. FDA breakthrough device designation pathways compress review timelines for diagnostics addressing life-threatening conditions with unmet clinical needs.
- Prognostics:Risk stratification assays predict disease progression and survival outcomes.
- Monitoring:Minimal residual disease tracking through circulating tumor DNA surveillance.
Diagnostics commands the largest revenue pool, with therapeutics gaining share fastest on companion diagnostic expansion.
End User:
Capital constraints and test complexity dictate which end-user settings adopt high-multiplex versus low-multiplex biomarker platforms.
- Hospitals:Integrated delivery networks across the Northeast and California centralize oncology reference testing into high-complexity molecular diagnostics hubs. Health system procurement is consolidating into preferred vendor panels with reagent rental and per-test pricing structures.
- Laboratories:Reference laboratories and CLIA-certified facilities process comprehensive genomic profiling at scale. Liquid biopsy automation is compressing turnaround times for cell-free DNA extraction across Boston and Houston academic medical centers.
- Clinics:Community oncology practices rely on send-out arrangements for complex molecular testing.
- Research Institutions:Translational research programs drive biomarker discovery and analytical validation.
Hospitals anchor installed base volume, with laboratories expanding most quickly on reference testing consolidation.
Technology:
Platform switching costs and reagent pricing power concentrate vendor relationships across technology categories.
- Genomic Sequencing:Next-generation sequencing platforms achieve broad multiplexing for comprehensive genomic profiling from tissue and liquid biopsy specimens. Proprietary library preparation chemistries and flow cell consumables concentrate pricing power with three dominant sequencing platform vendors.
- PCR:Polymerase chain reaction retains dominant share in community hospital laboratories where capital constraints limit platform diversification. Lower-multiplex workflows face displacement pressure from sequencing despite entrenched operational familiarity.
- Immunoassay:Chemiluminescent and ELISA-based protein detection dominates serum biomarker testing.
- Mass Spectrometry:High-resolution metabolite and proteome profiling requires specialized technical expertise.
PCR holds the deepest installed base penetration, with genomic sequencing showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized molecular pathologists and genomic data scientists concentrate in the Northeast corridor and California, anchoring precision oncology infrastructure development across the United States.
Greater Boston
Academic medical centers at Massachusetts General Hospital and Dana-Farber Cancer Institute anchor liquid biopsy program expansion. FDA breakthrough device designations for local diagnostics developers accelerate premarket authorization timelines. The Longwood Medical Area anchors high-complexity molecular diagnostics hub formation with centralized sequencing capacity.
Texas Medical Center Houston
MD Anderson Cancer Center and Baylor College of Medicine drive comprehensive genomic profiling demand for clinical trial enrollment. CMS national coverage determinations for companion diagnostics unlock immediate reimbursement for local reference laboratories. The Texas Medical Center district concentrates cell-free DNA isolation automation deployment across multiple hospital systems.
California
Integrated health networks in the San Francisco Bay Area and Los Angeles consolidate oncology reference testing into centralized molecular diagnostics hubs. CLIA-certified laboratory-developed test oversight from FDA draft guidance creates compliance timeline planning for academic medical center laboratories. Stanford Medicine and UCSF anchor multi-cancer early detection validation studies for asymptomatic population screening.
Mid-Atlantic Corridor
Memorial Sloan Kettering Cancer Center and Johns Hopkins Medicine drive demand for minimal residual disease monitoring assays. State-level laboratory licensing harmonization across New York, New Jersey, and Pennsylvania reduces operational friction for multi-site reference laboratory networks. The Philadelphia-Camden metro anchors reagent rental and per-test pricing structure adoption among health system procurement teams.
Pacific Northwest
Fred Hutchinson Cancer Center and Providence St. Joseph Health anchor precision oncology program development. Proprietary library preparation chemistry pricing power from dominant sequencing platform vendors concentrates capital deployment decisions. Seattle's South Lake Union biotech cluster anchors artificial intelligence-enabled biomarker interpretation algorithm development.
United States Cancer Biomarkers Market Competitive Landscape
Capital-heavy instrument manufacturers compete with asset-light assay developers across the United States cancer biomarkers landscape. The vendor base stratifies between platform-agnostic reagent suppliers and integrated system providers. Three archetypes dominate: end-to-end sequencing platform anchors, liquid biopsy commercialization specialists, and stool-based screening franchise extenders. Competitive moves concentrate on Medicare coverage expansion for comprehensive genomic profiling and health system procurement consolidation into preferred vendor panels.
Among platform-anchored conglomerates, Thermo Fisher Scientific exemplifies the capital-intensive archetype through its end-to-end sequencing infrastructure. Guardant Health occupies a position within the liquid biopsy commercialization tier, while Exact Sciences represents the screening franchise extension model. These three entities anchor distinct competitive vectors without overlapping strategic positioning. Specialists in PCR-based community hospital workflows and immunoassay protein detection occupy adjacent but non-competing market positions.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| Guardant Health |
| Exact Sciences |
| Illumina Inc. |
| Abbott Laboratories |
| QIAGEN N.V. |
| bioMérieux |
| Bio-Rad Laboratories |
| Others |
Value Network & Pricing Analysis
EPA hazardous waste disposal mandates for laboratory reagents and flow cell consumables gate qualified supply access for comprehensive genomic profiling assays, concentrating premium-tier pricing power with vendors holding validated environmental compliance infrastructure. CLIA-certified laboratories lacking certified disposal partnerships face exclusion from high-complexity oncology workflows, compressing margins on standard-tier service offerings.
Pricing Analysis
Bundled instrument-lease-plus-reagent contracts dominate academic medical center procurement, while unbundled per-test pricing gains traction among integrated delivery networks in California and the Northeast. Price differentiation rests on FDA breakthrough device designation status and Medicare coverage determination timing, with cleared companion diagnostics commanding 40-60% premiums over laboratory-developed tests. Pricing pressure stems from proprietary sequencing platform vendor concentration in library preparation chemistries, squeezing margins for assay developers. Community hospital laboratories exhibit highest price sensitivity due to capital constraints, while reference laboratories absorb premium pricing for automated liquid biopsy platforms.
Supply Chain Analysis
Domestic-content mandates in federal biomedical research funding are reshaping sourcing patterns for cell-free DNA isolation platforms and flow cell consumables, favoring U.S.-based contract manufacturers. Supply concentrates in California for sequencing instrumentation, Massachusetts for reagent formulation, and South Korea for semiconductor components in detection hardware. Raw material dependencies include fluorinated polymers for microfluidic cartridges, rare earth elements for laser optics, and synthetic oligonucleotides for probe synthesis. Single-source vulnerability in proprietary sequencing chemistry supply creates concentration risk for multi-site laboratory networks. Distribution runs through specialized cold-chain logistics providers serving CLIA-certified facilities nationwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States cancer biomarkers market functions as a stable compounder anchored by Medicare reimbursement expansion for companion diagnostics, generating predictable revenue streams across economic cycles.
For Market Incumbents: To counter regulatory uncertainty from FDA draft guidance on laboratory-developed test oversight, anchor defensive positioning through backward integration into cell-free DNA extraction automation and CLIA-certified laboratory network acquisition. Prioritize Medicare coverage determination parallel-track submissions to compress commercialization timelines for comprehensive genomic profiling assays. Certification investment in EPA-compliant hazardous waste infrastructure protects premium-tier pricing access against emerging competitors. For New Entrants and Emerging Players: Reference laboratory partnerships offer the most penetrable channel for algorithm-integrated assay developers lacking direct health system procurement relationships. White-space targets concentrate in artificial intelligence-enabled variant interpretation software for community hospital laboratories lacking specialized computational pathology expertise. Multi-cancer early detection validation study enrollment provides the strongest go-to-market angle for blood-based screening panel commercialization. For Investors and Strategic Acquirers: Valuations sit cheapest among CLIA-certified regional laboratories with established liquid biopsy workflows but limited Medicare coverage determination track records. Long-term viability framing centers on platform-agnostic assay developers with flexible reagent rental commercial models displacing capital-intensive instrument placements. Watch FDA guidance finalization on artificial intelligence-enabled biomarker interpretation as the critical inflection signal for algorithm-integrated diagnostic valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Compresses premarket authorization timelines for oncology diagnostics addressing life-threatening conditions with unmet clinical needs. |
| CMS Parallel Coverage Track Submission | Eliminates historical reimbursement lag, creating immediate commercial viability upon FDA approval for companion diagnostics. |
| Liquid Biopsy Automation Deployment | Reduces batch-to-batch variability in circulating tumor DNA recovery across Boston and Houston academic medical centers. |
| Multi-Cancer Early Detection Validation Enrollment | Positions blood-based screening panels for asymptomatic population screening reimbursement expansion. |
| State Laboratory Licensing Harmonization Advocacy | Reduces operational friction for multi-site reference laboratory networks across interstate compact frameworks. |
Research Methodology
Direct dialogue with molecular pathologists, laboratory operations directors, health system procurement executives, and CMS coverage policy specialists grounded qualitative insights, cross-validated against FDA 510(k) and PMA filings, CMS national coverage determination databases, ClinicalTrials.gov biomarker study records, and hospital GPO contract repositories. Bottom-up and top-down triangulation reconciled assay volume estimates with Medicare claims data and sequencing platform vendor shipment disclosures.
Bottom-up modeling aggregated test volume projections by biomarker platform, application, and end-user setting, while top-down analysis calibrated aggregate market sizing against CMS reimbursement expenditure trends and sequencing reagent market disclosures. Segmentation dimensions included product type, application, technology, and end user, with geographic clustering by integrated health network concentration. CAGRs derived from Medicare coverage expansion trajectories and next-generation sequencing cost decline curves, incorporating liquid biopsy platform maturation and artificial intelligence-enabled interpretation adoption as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance finalization on laboratory-developed test oversight and state-level licensing harmonization implementation. Forecasts reflect assumptions regarding Medicare coverage determination continuity and sequencing platform vendor pricing discipline. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Personal Genome Testing Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
Short-Read Sequencing Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
Mitochondrial DNA Market
Genomics
Global Gene Amplification Technologies Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Next Generation Genomics Market
Genomics
China Genetic Testing Market
Genomics
Retail Genomics Market
Genomics
Genomics and Transcriptomics Market
Genomics
UAE Genetic Testing Market
Genomics
SNP Genotyping Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Point-Of-Care Genetic Testing Market