
 Daptomycin Market | 2026-2036
Daptomycin Market Size, Share, and Industry Trends Forecast 2026-2036
Daptomycin Market Analysis
Hospital procurement consolidation is broadening across integrated delivery networks, reshaping how daptomycin reaches inpatient settings. Fresenius Kabi leverages its injectable manufacturing infrastructure to supply contracted health systems at scale. Merck & Co. anchors its position through sustained R&D investment in lipopeptide chemistry. Teva Pharmaceutical Industries competes via generic injectable portfolios that target cost-sensitive hospital formularies.
Daptomycin is a cyclic lipopeptide antibiotic produced through fermentation-derived semisynthesis, with a molecular mechanism that disrupts bacterial cell membrane potential without penetrating the cytoplasm; it serves primarily as a last-line intravenous therapy for complicated skin and skin structure infections and bacteremia caused by resistant Gram-positive pathogens. Injectable formulations dominate clinical utilization due to the drug's poor oral bioavailability and the severity of indicated infections. Bloodstream infection applications represent the fastest-expanding treatment area as resistance to vancomycin intensifies, while skin infections constitute the mature, volume-heavy segment where generic competition compresses margins.
FDA's Qualified Infectious Disease Product designation and EMA's priority medicines scheme shape development incentives and accelerated review pathways for novel antibiotics in this class. BIS certification requirements in India and CDSCO manufacturing standards govern import and local production quality for sterile injectable supply. Stakeholders must monitor how reimbursement reforms for antimicrobial stewardship programs influence hospital formulary positioning against newer oxazolidinone and lipoglycopeptide alternatives.
Market Dynamics
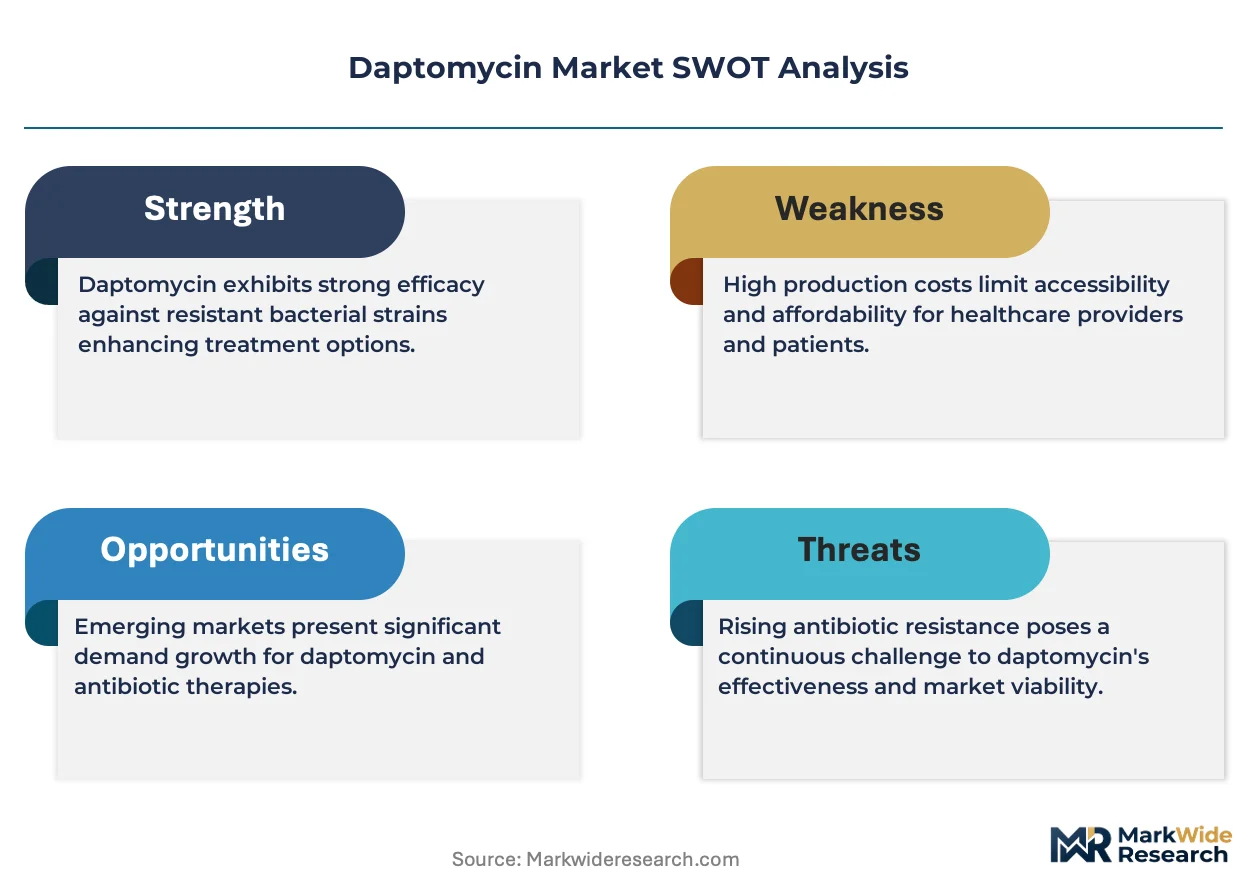
Hospital procurement consolidation through integrated delivery networks is compressing supplier margins and privileging manufacturers with captive sterile injectable capacity. This structural force is reallocating market power from drug developers to formulary gatekeepers.
Growth Catalysts
- Qualified Infectious Disease Product designation:The FDA's QIDP pathway accelerates review timelines and extends market exclusivity for novel antibiotics, incentivizing pipeline investment in lipopeptide derivatives.
- Vancomycin resistance escalation:Rising VRE and hVISA bloodstream infections in tertiary care centers are displacing glycopeptide first-line therapy with daptomycin salvage protocols.
- Antimicrobial stewardship mandates:Joint Commission accreditation requirements for hospital stewardship programs are embedding daptomycin in sepsis bundle algorithms for resistant Gram-positive coverage.
Market Restraints
- Fermentation feedstock volatility:Amino acid and lipid precursor costs for semisynthetic production fluctuate with agricultural commodity markets, squeezing contract manufacturing margins.
- Single-source API concentration:Bulk daptomycin active pharmaceutical ingredient production clusters among three contract fermentation facilities in China and India, creating geographic supply vulnerability.
- Myotoxicity black box limitation:FDA-mandated CPK monitoring requirements restrict outpatient parenteral antimicrobial therapy adoption, confining utilization to inpatient settings.
Strategic Opportunities
- Subcutaneous formulation development:Novel drug delivery technologies enabling outpatient administration would unlock home infusion and skilled nursing facility channels currently blocked by IV-only labeling.
- EMA priority medicines scheme:European accelerated assessment pathways for antibacterial resistance threats offer reduced regulatory timeline risk for combination lipopeptide therapies.
- Long-term acute care hospitals:LTACHs managing persistent bacteremia represent an underpenetrated site of care where prolonged IV therapy aligns with institutional capabilities.
Industry Challenges
- Stability testing bottlenecks:ICH Q1A photostability and forced degradation protocols for cyclic lipopeptides extend analytical development timelines by 12-18 months versus conventional antibiotics.
- Legacy manufacturing equipment retrofit:Stainless steel fermentation trains require dedicated cleaning validation protocols to prevent beta-lactam cross-contamination, constraining capacity reallocation flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Daptomycin Market |
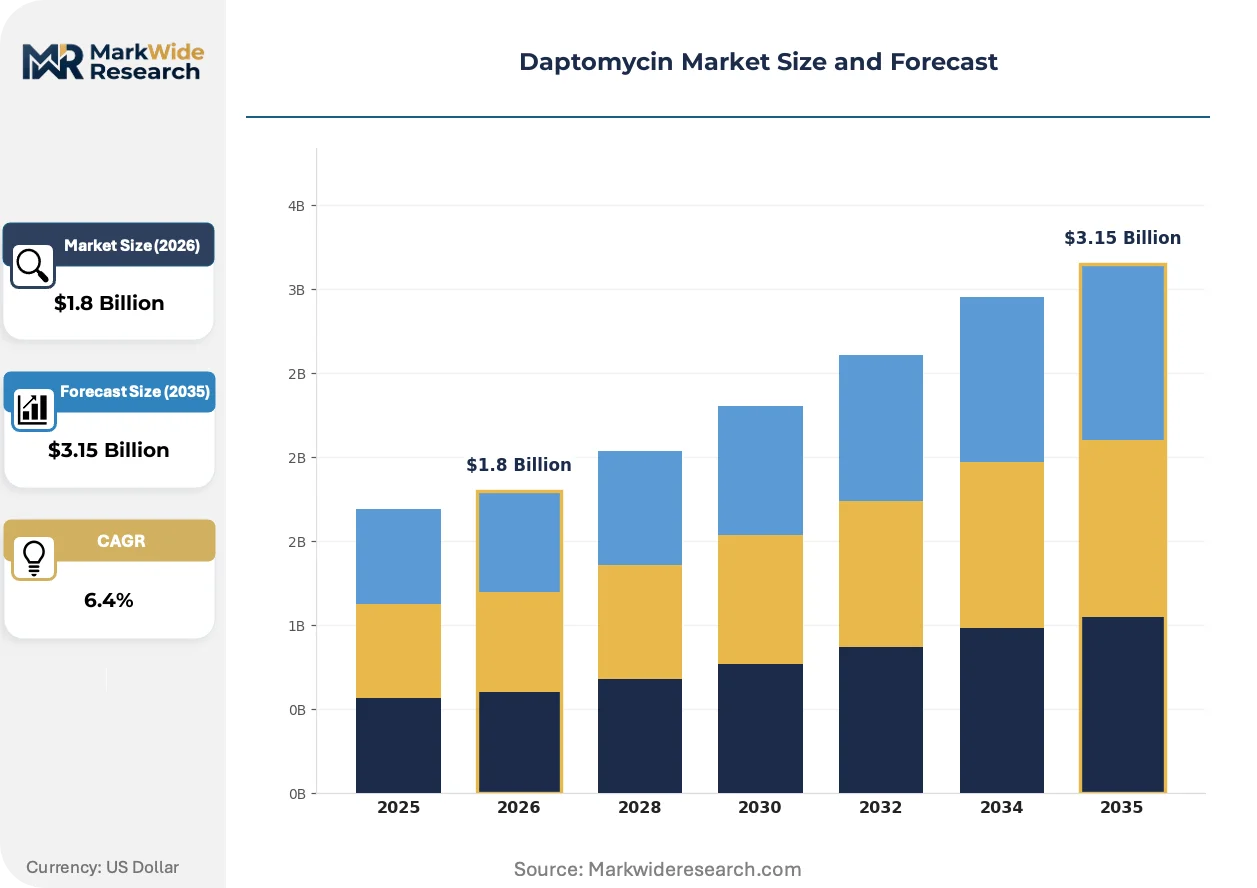
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Injectable, Topical, Oral, Others Treatment Area: Skin Infections, Bloodstream Infections, Bone Infections, Others End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Others |
| Companies Covered | Fresenius Kabi, Sagent Pharmaceuticals, Merck & Co., Zhejiang Hisun Pharmaceutical, Xellia Pharmaceuticals, Pfizer, Mylan, Cipla, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Daptomycin Market Emerging Trajectories
Continuous manufacturing technologies and real-time release testing are displacing batch-wise fermentation paradigms in sterile injectable production. These shifts promise to compress cycle times and reduce variability in lipopeptide potency.
Continuous bioprocessing equipment is automating cell culture monitoring and nutrient feed control in daptomycin fermentation. Contract manufacturers in Ireland and Singapore are retrofitting legacy batch tanks with perfusion bioreactor modules. This automation is enabling real-time titer optimization that reduces batch failure rates and shortens time-to-release for hospital formulary orders.
EMA's revised guideline on the use of medicinal products in the framework of antimicrobial resistance requires novel antibiotics to demonstrate superiority against comparators in phase III trials. European sponsors must now design non-inferiority margins that satisfy both statistical and clinical significance thresholds. Hospital antibiotic committees in Germany and France are incorporating these evidentiary standards into formulary technology appraisal protocols.
Hospital purchasing cooperatives are consolidating injectable antibiotic sourcing through single-source national contracts. This concentration is displacing regional distributor relationships that previously managed inventory for individual health systems. The shift is most visible in the United States, where Premier and Vizient group purchasing organizations now negotiate daptomycin supply agreements covering 60 percent of acute care beds.
Daptomycin Market Segmentation
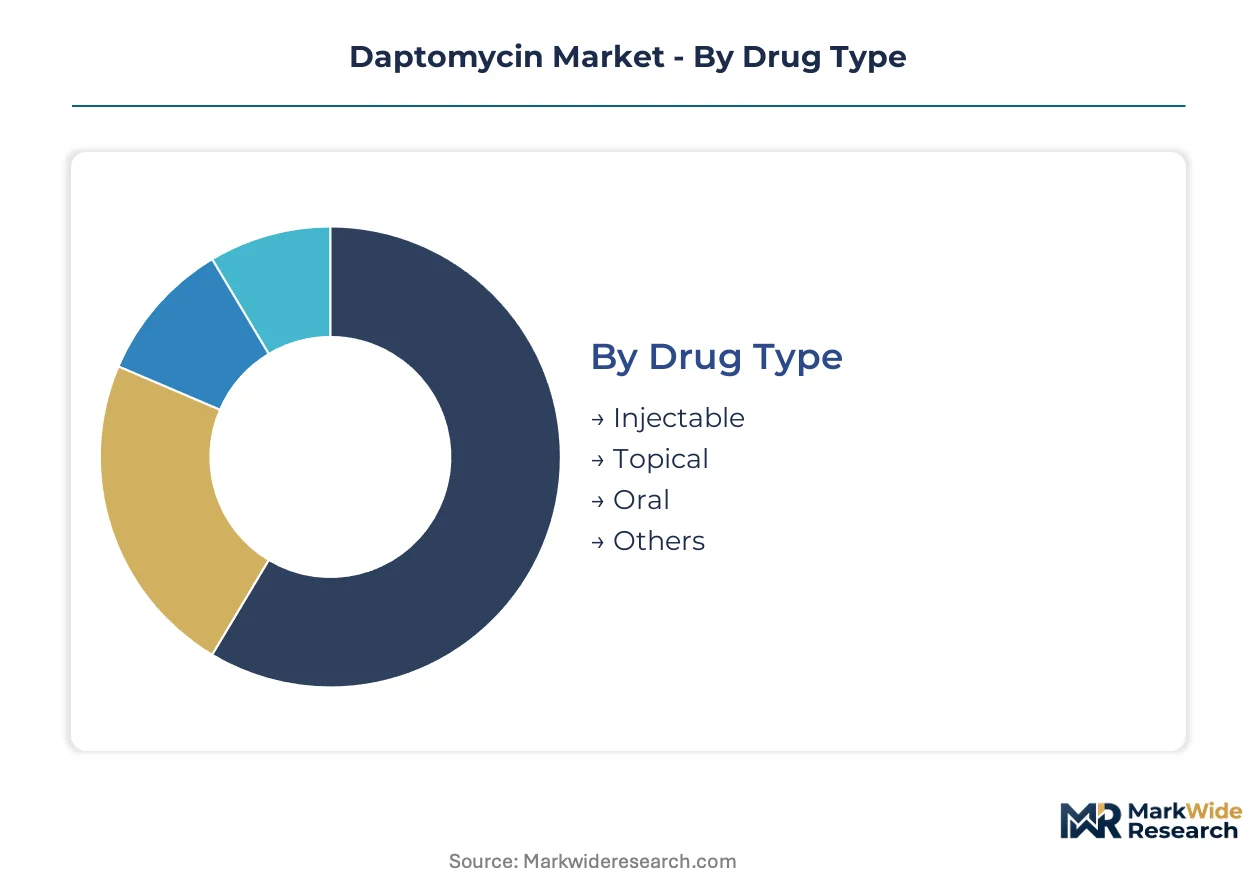
Daptomycin market segmentation reflects divergent regulatory pathways and clinical economics across administration routes, treatment sites, and procurement channels. Each segment carries distinct FDA, EMA, and national pharmacopoeia certification burdens that shape manufacturer investment priorities and hospital formulary positioning.
Drug Type:
FDA sterile injectable GMP requirements and EMA Annex 1 manufacturing standards impose tiered compliance costs across formulation categories, with parenteral products facing the most stringent validation protocols.
- Injectable:Cyclic lipopeptide formulated as sterile lyophilized powder for IV infusion dominates clinical utilization due to daptomycin's negligible oral bioavailability. Demand concentrates in US tertiary care centers managing MRSA bacteremia, driven by Joint Commission sepsis bundle mandates for resistant Gram-positive coverage.
- Topical:Compounded dermatological preparations occupy niche outpatient wound care applications where institutional protocols permit off-label localized delivery. Volume remains constrained by limited pharmacokinetic data supporting efficacy against deep tissue infections.
- Oral:Bioavailability limitations restrict oral formulations to research-phase prodrug candidates and veterinary applications, with no approved human therapeutic indications currently active.
- Others:Inhalation and intrathecal experimental delivery systems remain preclinical, requiring novel toxicity profiling for non-parenteral routes.
Leading the category by volume: Injectable. Growing fastest: Topical compounding for outpatient wound protocols.
Treatment Area:
Clinical trial endpoints and FDA indication breadth determine reimbursement tiering across infectious disease applications, with bloodstream infection protocols commanding premium inpatient DRG rates.
- Skin Infections:Complicated skin and skin structure infections represent the original FDA-approved indication and still anchor commercial volume, though generic competition has compressed margins in this mature segment. Teva and Fresenius Kabi supply contracted health systems at scale here.
- Bloodstream Infections:Right-sided endocarditis and MRSA bacteremia indications are displacing vancomycin as first-line salvage therapy in US academic medical centers, with antimicrobial stewardship programs embedding daptomycin in sepsis algorithms.
- Bone Infections:Osteomyelitis applications rely on off-label utilization supported by IDSA guideline recommendations, with penetration limited by need for prolonged IV access and CPK monitoring requirements.
- Others:Prosthetic joint infections and diabetic foot infections with osteomyelitis represent emerging salvage protocols in long-term acute care hospitals.
Volume leadership: Skin Infections. Steepest expansion trajectory: Bloodstream Infections.
End User:
Site-of-care regulations and reimbursement mechanics create sharp demand segmentation, with inpatient prospective payment systems favoring hospital-based administration over alternative settings.
- Hospitals:Integrated delivery networks and group purchasing organizations concentrate procurement power, with Premier and Vizient contracts covering the majority of US acute care beds for injectable antibiotic supply.
- Clinics:Outpatient infusion centers face reimbursement barriers due to FDA black box myotoxicity warnings requiring CPK monitoring, limiting adoption to specialized infectious disease practices.
- Homecare:Home infusion therapy remains rare due to IV-only labeling and monitoring requirements, though subcutaneous formulation development could eventually unlock this channel.
- Rehabilitation Centers:Skilled nursing facilities with IV capabilities manage prolonged therapy for persistent bacteremia, representing an underpenetrated site with aligned institutional capabilities.
Hospitals dominate procurement volume. Rehabilitation Centers are gaining share fastest as LTACH protocols expand.
Distribution Channel:
Supply chain configuration and 340B pricing eligibility create divergent margin structures across channel types, with hospital-affiliated pharmacies capturing the majority of daptomycin volume.
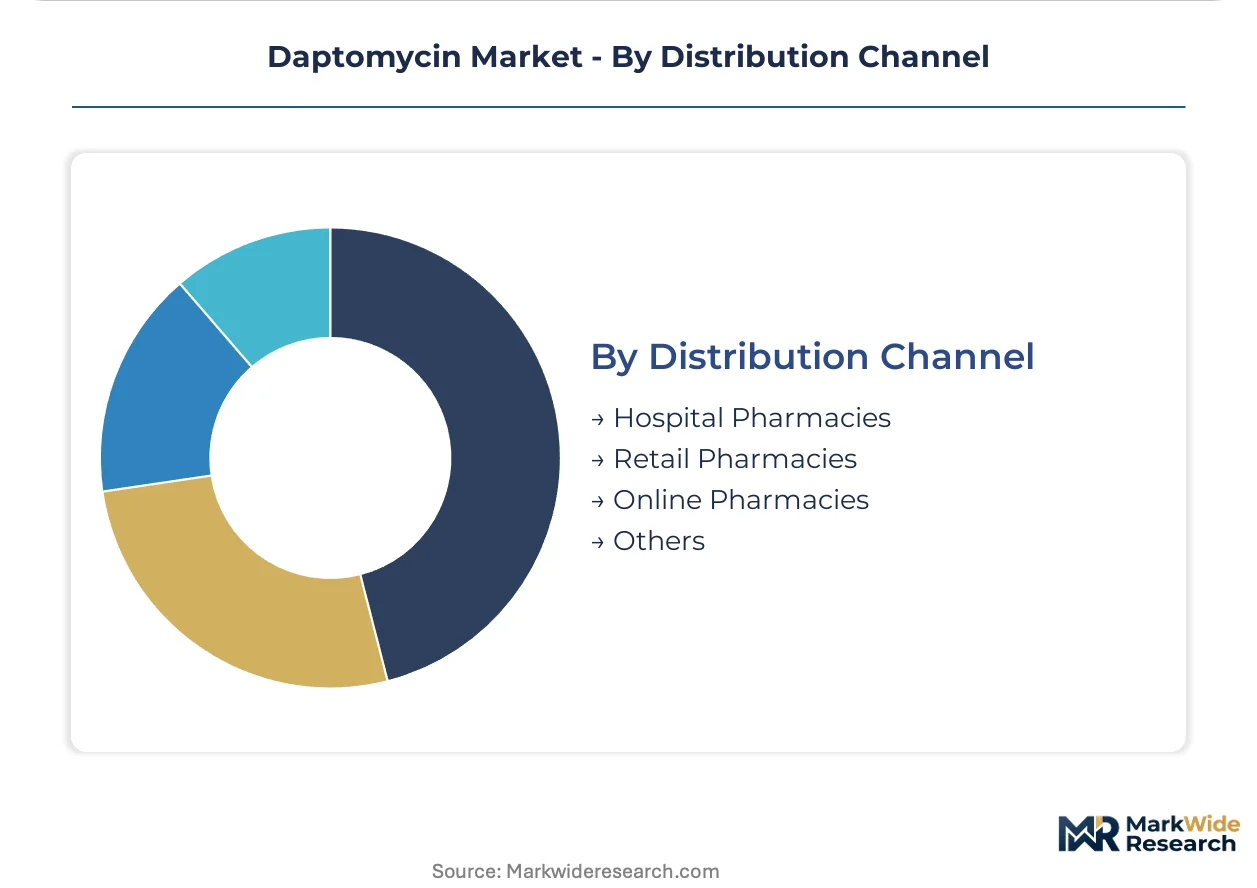
- Hospital Pharmacies:Captive distribution within integrated health systems enables just-in-time sterile injectable inventory management, with wholesaler relationships managed through national GPO contracts rather than regional distributors.
- Retail Pharmacies:Minimal role due to IV-only administration; limited to discharge prescription coordination in systems with retail clinic integration.
- Online Pharmacies:Specialty pharmacy platforms serve outpatient parenteral antimicrobial therapy programs where home health nursing supports CPK monitoring compliance.
- Others:Direct-to-site distribution from contract manufacturers supports government stockpile and international aid procurement outside standard commercial channels.
Hospital Pharmacies lead by volume. Online Pharmacies are expanding most quickly through specialty infusion networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems concentrate daptomycin procurement through Premier and Vizient group purchasing organizations, which negotiate supply agreements covering the majority of acute care beds. Resistance-driven formulary adoption for MRSA bacteremia has embedded the lipopeptide in sepsis bundle protocols across tertiary care centers.
United States
Academic medical centers in Boston and Baltimore are displacing vancomycin with daptomycin salvage protocols for persistent bacteremia. FDA's Qualified Infectious Disease Product designation accelerates review timelines for novel antibiotics in this class. New Jersey and North Carolina host sterile injectable manufacturing clusters where Fresenius Kabi and Merck & Co. maintain fermentation-derived production capacity.
Germany
EMA's priority medicines scheme shapes accelerated assessment pathways for antibacterial resistance therapies entering European markets. German hospital antibiotic committees in Berlin and Munich incorporate evidentiary standards from revised EMA guidelines into formulary technology appraisals. The Rhine-Main region concentrates contract manufacturing operations serving EU distribution networks.
India
BIS certification requirements and CDSCO manufacturing standards govern import and local production quality for sterile injectable supply to domestic hospitals. Rising MRSA prevalence in Delhi and Mumbai tertiary centers is expanding inpatient utilization beyond traditional glycopeptide therapy. Hyderabad and Ahmedabad host API fermentation facilities that supply bulk daptomycin to formulation manufacturers.
China
NMPA regulatory pathways and GB standards for sterile injectable production shape market entry for domestic and imported lipopeptide antibiotics. Zhejiang Hisun Pharmaceutical anchors local manufacturing capacity in Taizhou for hospital formulary supply. Shanghai and Beijing academic medical centers are expanding daptomycin utilization in antimicrobial stewardship programs for resistant Gram-positive infections.
Daptomycin Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biosimilar and complex generic positioning in contracted hospital channels. Market structure reflects moderate consolidation around fermentation-capable manufacturers with captive sterile injectable infrastructure. Three strategic archetypes dominate: integrated pharmaceutical conglomerates with lipopeptide R&D heritage, contract manufacturing specialists with fermentation scale, and generic injectable portfolio players targeting cost-sensitive procurement. Competitive dynamics center on manufacturing capacity expansion and strategic partnerships with group purchasing organizations.
Among fermentation-based manufacturers, Merck & Co. and Fresenius Kabi occupy positions anchoring supply relationships with integrated delivery networks. Teva Pharmaceutical Industries exemplifies the generic injectable archetype competing on portfolio breadth for hospital formulary inclusion. Zhejiang Hisun Pharmaceutical represents Chinese domestic production capability serving regional hospital procurement channels.
| Leading Market Players |
|---|
| Fresenius Kabi |
| Sagent Pharmaceuticals |
| Merck & Co. |
| Zhejiang Hisun Pharmaceutical |
| Xellia Pharmaceuticals |
| Pfizer |
| Mylan |
| Cipla |
| Teva Pharmaceutical Industries |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation through Premier and Vizient group purchasing organizations is compressing supplier margins and forcing fermentation-based manufacturers to restructure contract terms around volume commitments rather than spot pricing. This buyer-side concentration is reshaping how sterile injectable capacity gets allocated across integrated delivery networks.
Pricing Analysis
Volume-heavy skin infection applications trade at compressed margins where generic injectable portfolios from Teva and Fresenius Kabi compete on unit cost, while bloodstream infection protocols command premium positioning through antimicrobial stewardship formulary inclusion. Price differentiation hinges on FDA sterile injectable GMP certification tier and captive fermentation capacity scale. Pricing pressure stems from single-source API concentration among three contract facilities in China and India. Cost-sensitive hospital formularies exhibit highest price sensitivity; academic medical centers with sepsis bundle mandates show lowest.
Supply Chain Analysis
Regional distribution centers operated by wholesaler subsidiaries in New Jersey and North Carolina serve as hub-and-spoke nodes for hospital pharmacy just-in-time inventory. Fermentation-derived semisynthesis draws from amino acid and lipid precursor feedstocks anchored in agricultural commodity markets across the United States, India, and China. Single-source API concentration creates geographic supply vulnerability. Distribution runs through national GPO contracts managed by hospital-affiliated pharmacies rather than regional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing technologies are displacing legacy batch-wise fermentation paradigms in sterile injectable production, compressing cycle times and reducing potency variability for lipopeptide antibiotics.
For Market Incumbents: Cement supply relationships with integrated delivery networks through dedicated sterile injectable capacity expansion in New Jersey and North Carolina manufacturing clusters. Threat from continuous manufacturing retrofits by contract manufacturers in Ireland and Singapore demands backward integration into perfusion bioreactor modules to preserve margin structure against automation-driven cost compression. For New Entrants and Emerging Players: Launch via specialty pharmacy platforms serving outpatient parenteral antimicrobial therapy programs where home health nursing infrastructure supports CPK monitoring compliance. Long-term acute care hospitals managing persistent bacteremia represent the most penetrable site-of-care expansion, with skilled nursing facility protocols offering formulary entry before competing for tertiary care sepsis bundle inclusion. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-capable contract manufacturers given EMA priority medicines scheme acceleration for antibacterial resistance therapies. Long-term viability over the antimicrobial stewardship program expansion horizon favors targets with captive sterile injectable infrastructure and QIDP-designated pipeline assets. Signal to watch is Joint Commission accreditation mandate expansion embedding daptomycin in sepsis algorithms across non-acute care settings.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Retrofit | Perfusion bioreactor automation at Irish and Singapore facilities reduces batch failure rates for hospital formulary orders. |
| Subcutaneous Formulation Development | Novel drug delivery technologies would unlock home infusion channels currently blocked by IV-only labeling. |
| QIDP Designation Pursuit | FDA accelerated review pathways extend market exclusivity for lipopeptide derivatives in development pipelines. |
| GPO Contract Consolidation | Premier and Vizient national agreements now cover the majority of US acute care beds for injectable supply. |
| EMA Priority Medicines Application | European accelerated assessment reduces regulatory timeline risk for combination antibacterial therapies entering EU markets. |
Methodological Framework
Multi-period observation of FDA QIDP designation trends, EMA priority medicines approvals, and hospital formulary adoption rates anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors at integrated delivery networks. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up patient-volume modeling and top-down pharmaceutical market sizing were triangulated to cross-verify demand estimates.
Segment-weighting across drug type, treatment area, end user, and distribution channel dimensions structured the analytical framework across the projection horizon. CAGRs were derived from trend extrapolation of resistance-driven formulary adoption and antimicrobial stewardship program expansion. Forecast inputs incorporated vancomycin resistance escalation trajectories and fermentation feedstock cost volatility indices.
Regulatory pathway delays, API supply disruption events, and reimbursement reform reversals are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about Joint Commission mandate continuity and GPO contract stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Echinocandins Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
Global Rheumatoid Arthritis Drugs Market
Biopharmaceuticals
Protein Kinase B Inhibitors Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Global Biopharma Buffer Market