
 Klinefelter Syndrome Therapeutics Market | 2026-2036
Klinefelter Syndrome Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Klinefelter Syndrome Therapeutics Market Foresight
Specialty-grade testosterone formulations is unwinding the commodity-tier pricing that long dominated androgen replacement. Pfizer Inc. leverages its endocrinology manufacturing scale to supply consistent API volumes across North American and European markets. Novo Nordisk A/S anchors its position through deep specialization in hormone delivery systems, while Eli Lilly and Company differentiates via integrated clinical trial networks that accelerate patient recruitment for rare disease indications.
Klinefelter Syndrome therapeutics encompass pharmaceutical and surgical interventions targeting the 47,XXY chromosomal aneuploidy, with testosterone replacement typically administered via intramuscular injection of testosterone cypionate or enanthate esters at 50-200 mg every 2-4 weeks to restore physiological androgen levels and mitigate gynecomastia, osteoporosis, and metabolic syndrome risks. Hormone Replacement Therapy occupies the dominant margin pool due to chronic administration requirements and limited generic substitution, while Psychological Support represents the fastest-expanding segment as multidisciplinary care models integrate mental health screening for anxiety and depression comorbidities. Specialty Clinics concentrate the highest patient throughput, though Home Care administration routes are gaining traction as transdermal gel formulations improve caregiver confidence.
The US FDA's orphan drug program shapes development economics through tax credits and market exclusivity provisions, while the EMA's paediatric investigation plans mandate juvenile safety data that extend regulatory timelines for adolescent indications. Reimbursement coding under Medicare and commercial payors in the United States directly determines patient access to gonadotropin therapies and fertility preservation procedures. Stakeholders must monitor evolving payer evidence requirements for quality-of-life endpoints as value-based contracts displace traditional fee-for-service models in rare disease management.
Market Dynamics
Pediatric endocrinology clinics are expanding adoption of early-intervention protocols, creating a structural pull toward chronic disease management models that integrate testosterone replacement with fertility preservation counseling and metabolic monitoring.
Growth Catalysts
- US FDA Orphan Drug Designation:Tax credits and market exclusivity provisions compress development timelines for rare chromosomal disorder therapeutics, accelerating investigational new drug filings.
- Specialty Clinic Infrastructure:Concentrated patient throughput in multidisciplinary centers enables standardized screening protocols for anxiety and depression comorbidities alongside hormone management.
- Transdermal Gel Formulations:Improved bioavailability and caregiver confidence are displacing intramuscular injection as the default administration route in adolescent populations.
Market Restraints
- API Supply Concentration:Testosterone cypionate and enanthate active pharmaceutical ingredient production clusters in a limited number of contract manufacturing organizations, creating single-source vulnerability.
- EMA Paediatric Investigation Plans:Mandatory juvenile safety data requirements extend regulatory timelines for adolescent indications, delaying market entry for age-specific formulations.
- Fertility Preservation Cost Burden:Sperm cryopreservation and assisted reproductive technology procedures remain uncovered or poorly reimbursed across multiple national health systems, restricting access.
Strategic Opportunities
- Home Care Administration:Subcutaneous testosterone pellet implants and long-acting injectable formulations enable patient-managed therapy outside clinic settings, reducing specialty care dependency.
- Integrated Mental Health Screening:Digital phenotyping tools for cognitive and behavioral assessment create reimbursement pathways for neuropsychological intervention alongside endocrine treatment.
- Value-Based Contracts:Quality-of-life endpoint demonstration aligns with Medicare and commercial payer evidence requirements, opening risk-sharing arrangements for comprehensive care models.
Industry Challenges
- Rare Disease Trial Recruitment:Dispersed patient geography and diagnostic underrecognition compress enrollment velocity, requiring satellite site networks and telemedicine screening.
- Biomarker Standardization:Inconsistent testosterone assay methodologies across reference laboratories create data heterogeneity that complicates multi-site clinical evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Klinefelter Syndrome Therapeutics Market |
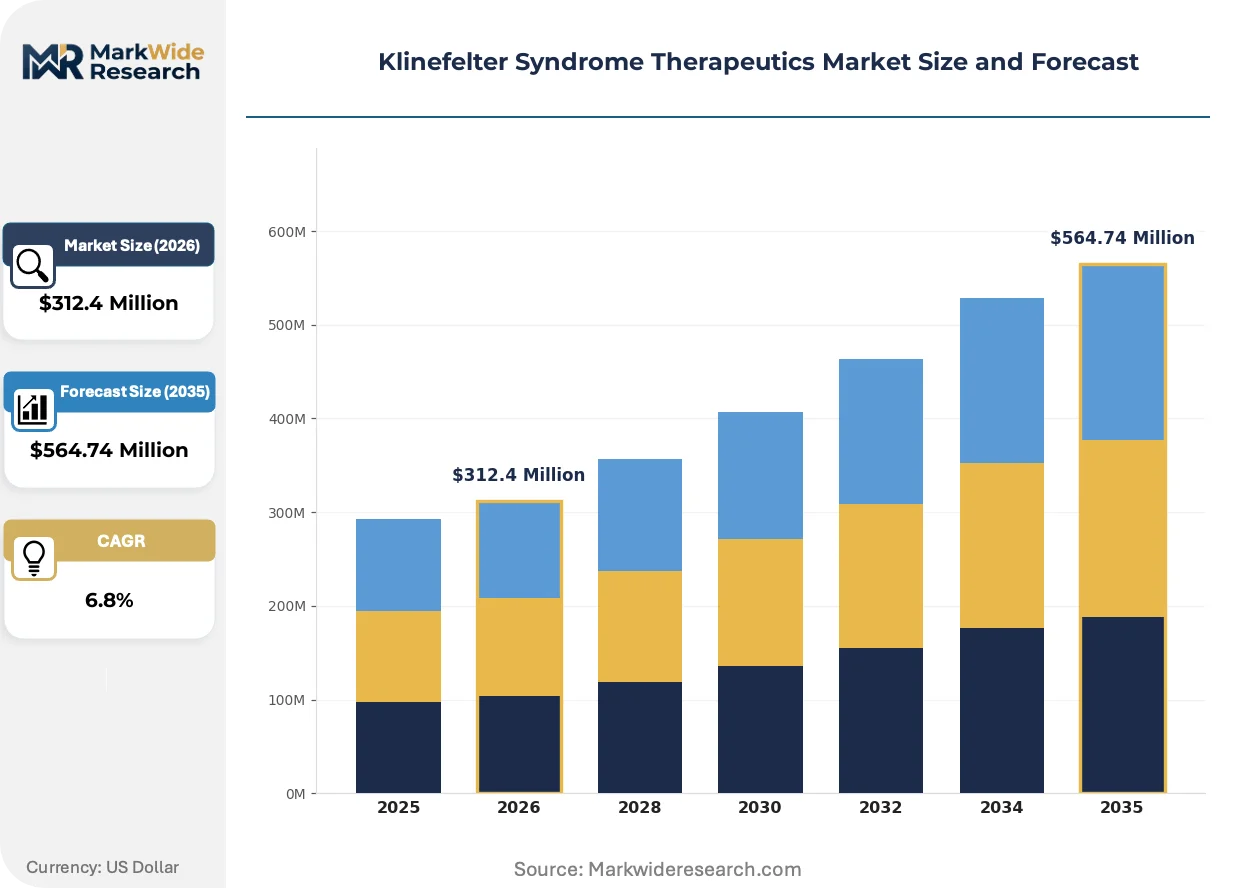
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Hormone Replacement Therapy, Testosterone Therapy, Surgical Interventions, Psychological Support Patient Age Group: Children, Adolescents, Adults, Seniors Care Setting: Primary Care, Specialty Clinics, Hospitals, Home Care Administration Route: Oral, Injection, Transdermal, Inhalation |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, Ferring Pharmaceuticals, Endo International plc, Teva Pharmaceutical Industries Ltd., AbbVie Inc., Bayer AG, Novo Nordisk A/S, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Klinefelter Syndrome Therapeutics Market Shifts & Advancements
Long-acting testosterone formulations and digital therapeutics are restructuring how chronic androgen replacement is delivered, monitored, and reimbursed across care settings.
Subcutaneous testosterone pellet implants are fragmenting the dominant intramuscular injection paradigm by offering three-to-six month dosing intervals that reduce clinic visit burden. Adolescent transition clinics and rural endocrinology practices are adopting pellet protocols at accelerating rates. This delivery modality is fragmenting patient flow away from hospital-based infusion centers toward ambulatory surgery and office-based procedure settings.
EMA's paediatric investigation plan mandates are compressing development timelines for adult-only indications while extending juvenile study requirements for adolescent labeling. Manufacturers are responding by sequencing submissions to prioritize adult approvals, then pursuing pediatric extensions through supplemental filings. European markets face delayed access to age-appropriate formulations as a consequence of this regulatory sequencing.
Caregiver-administered transdermal protocols are displacing clinic-dependent injection models as primary education and confidence-building programs expand. Home care channels are capturing administration volume previously concentrated in specialty endocrinology practices. The United States exhibits the most pronounced channel shift, driven by commercial payer preference for reduced facility fee exposure and patient convenience prioritization in rare disease management.
Klinefelter Syndrome Therapeutics Market Segmentation
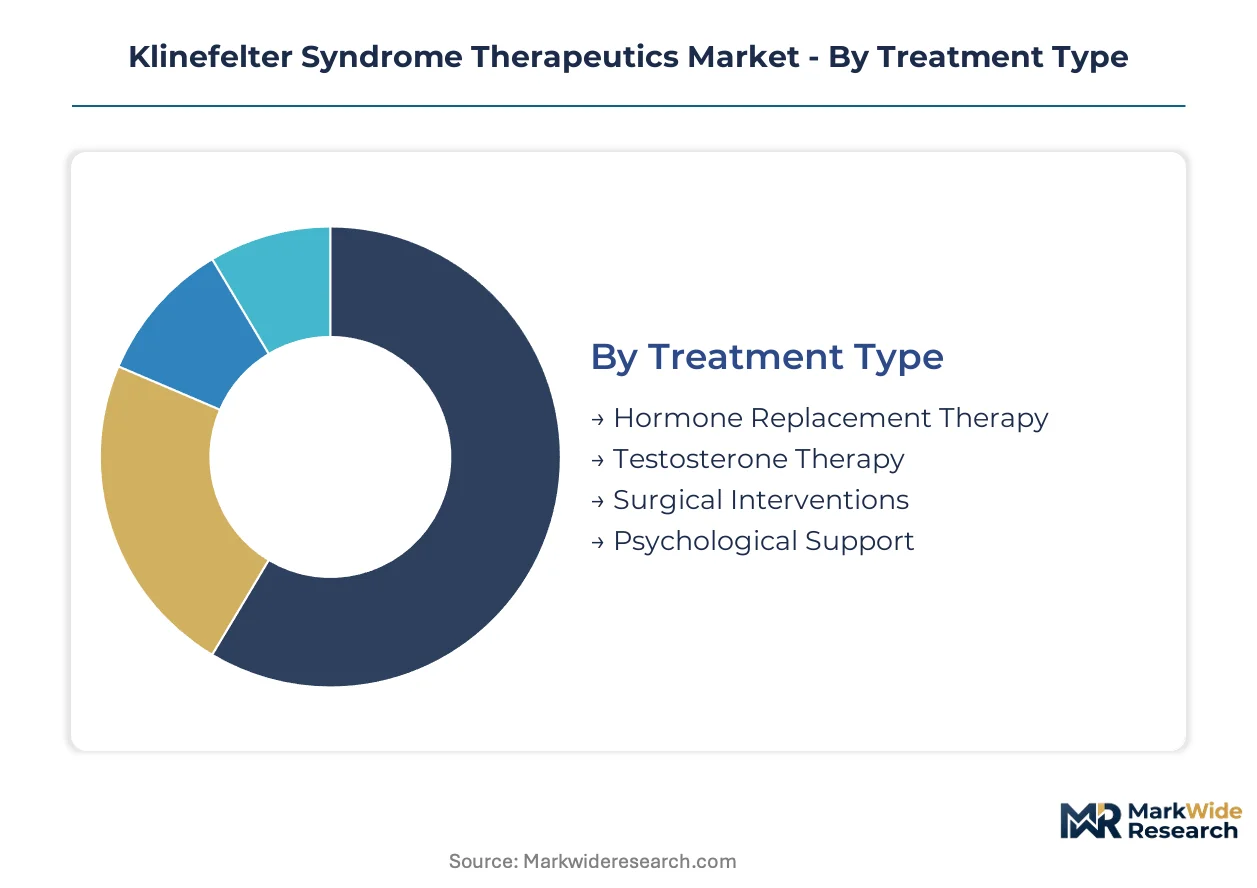
Klinefelter Syndrome therapeutics flow through distinct channel configurations that shape prescribing patterns and reimbursement capture. Each segmentation dimension reveals how patient age, care setting, and delivery modality intersect to determine market access and commercial prioritization.
Treatment Type:
Channel concentration varies sharply across therapeutic categories, with chronic administration models dominating volume and episodic interventions capturing premium pricing.
- Hormone Replacement Therapy:Chronic testosterone administration via cypionate or enanthate esters forms the backbone of clinical management. Specialty endocrinology clinics in the United States concentrate the highest patient throughput for initiation and monitoring protocols.
- Psychological Support:Integrated mental health screening for anxiety and depression comorbidities is expanding fastest within multidisciplinary care models. Demand concentrates in pediatric transition clinics where neuropsychological intervention accompanies endocrine treatment.
- Testosterone Therapy:Distinct from broader HRT, this segment encompasses targeted androgen restoration protocols with specific formulation optimization.
- Surgical Interventions:Gynecomastia correction and fertility preservation procedures occupy hospital-based settings with limited reimbursement coverage across multiple national health systems.
Hormone Replacement Therapy dominates installed base. Psychological Support is where expansion concentrates.
Patient Age Group:
Cost tier stratification across age bands determines therapy intensity and monitoring frequency, with adolescent protocols commanding premium resource allocation.
- Adolescents:Pubertal induction and fertility preservation counseling require intensive endocrinologist involvement and represent the highest per-patient expenditure tier. EMA paediatric investigation plan mandates extend regulatory timelines for age-specific formulations in European markets.
- Adults:Chronic maintenance protocols with established testosterone replacement regimens generate predictable recurring revenue. The United States exhibits the most pronounced demand concentration due to specialty care infrastructure density.
- Children:Early detection programs in pediatric endocrinology clinics are expanding, though treatment initiation remains conservative pending developmental staging.
- Seniors:Metabolic syndrome risk mitigation and bone density preservation drive continued therapy adherence in older populations with established diagnoses.
Adults anchor revenue volume. Adolescents represent the steepest expansion trajectory.
Care Setting:
Volume distribution is shifting as home-administered formulations reduce facility dependency and payer preference moves toward lower-cost settings.
- Specialty Clinics:Multidisciplinary centers concentrate diagnostic throughput and complex case management. These settings integrate endocrinology, genetics, and psychology services under unified protocols.
- Home Care:Transdermal gel and subcutaneous pellet formulations are displacing clinic-dependent injection models. Commercial payers in the United States drive this channel shift through reduced facility fee exposure.
- Hospitals:Surgical interventions and acute metabolic complications retain hospital-based concentration, though volume share is eroding.
- Primary Care:Stable maintenance patients with established regimens increasingly transfer to generalist oversight, extending specialist capacity for complex cases.
Specialty Clinics dominate installed base. Home Care is gaining share fastest.
Administration Route:
Supply concentration in API manufacturing shapes route availability, with testosterone ester production clustering in limited contract manufacturing organizations.
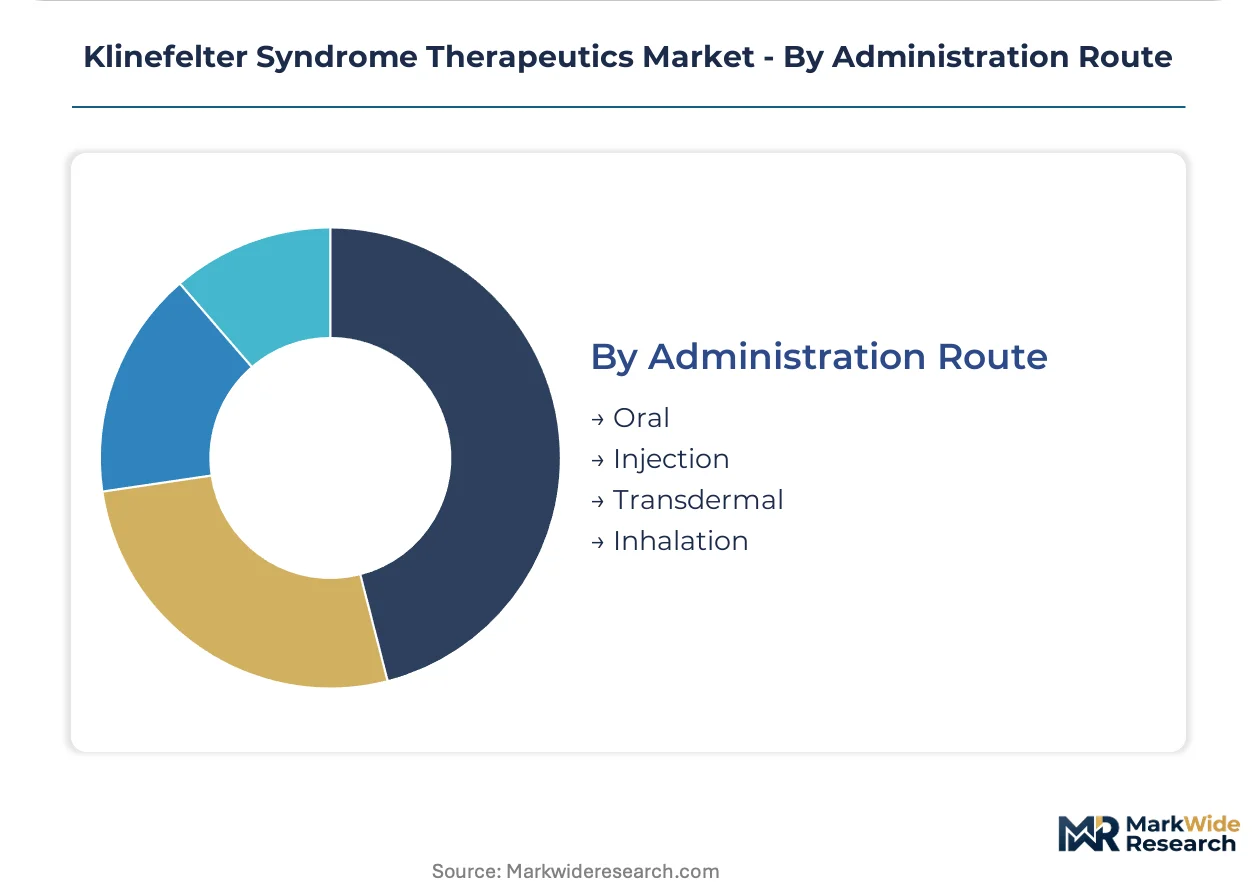
- Injection:Intramuscular testosterone cypionate or enanthate at 50-200 mg every 2-4 weeks remains the default protocol for cost-sensitive populations and large-volume institutional purchasers.
- Transdermal:Gel and patch formulations improve bioavailability consistency and enable caregiver-administered protocols. Rural endocrinology practices and adolescent transition clinics are adopting these modalities at accelerating rates.
- Oral:Limited bioavailability and hepatic metabolism concerns restrict oral testosterone to niche applications with specific compliance requirements.
- Inhalation:Nasal testosterone gel represents an emerging delivery modality with rapid absorption kinetics, though market penetration remains limited by reimbursement positioning.
Injection dominates installed base. Transdermal is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a structural surplus in Klinefelter Syndrome therapeutics, exporting specialty-grade testosterone formulations while importing limited volumes of API feedstocks from European contract manufacturers. Germany and Switzerland anchor European supply, with the UK and France representing concentrated demand centers shaped by distinct reimbursement architectures.
United States
Pediatric endocrinology clinics in Boston and New York Metro drive early-intervention protocol adoption, while Medicare reimbursement coding determines patient access to gonadotropin therapies. The FDA's orphan drug designation pathway accelerates development timelines through tax credits and market exclusivity provisions. Specialty care infrastructure concentrates in the Northeast Corridor and California, where multidisciplinary centers integrate hormone management with fertility preservation counseling.
Germany
EMA paediatric investigation plan mandates extend regulatory timelines for adolescent-specific formulations, compressing adult-only indication approvals first. Baden-Württemberg and Bavaria host concentrated endocrinology research clusters that shape European clinical practice guidelines. Domestic reimbursement frameworks under statutory health insurance provide predictable access to testosterone replacement therapies, though fertility preservation procedures remain variably covered.
United Kingdom
NHS England's specialized commissioning frameworks route complex Klinefelter cases through designated supra-regional centers in London and Manchester. The National Institute for Health and Care Excellence issues technology appraisals that directly determine formulary inclusion for novel hormone delivery systems. Scotland and Wales operate parallel assessment processes, creating fragmented access patterns across the devolved administrations.
Japan
PMDA consultation pathways for rare diseases compress review timelines for testosterone formulations with demonstrated pediatric safety profiles. The Kanto region, centered on Tokyo, concentrates both diagnostic capacity and specialist endocrinology practices. METI's healthcare industry promotion programs support domestic development of long-acting injectable formulations to reduce import dependency.
Switzerland
Swissmedic's streamlined orphan drug procedures attract European headquarters functions for specialty pharmaceutical developers targeting chromosomal disorders. The Basel-Zurich corridor hosts concentrated pharmaceutical manufacturing and clinical trial operations. Cantonal health insurance variations create pricing differentiation across the confederation, with Geneva and Zurich commanding premium reimbursement tiers.
Klinefelter Syndrome Therapeutics Market Competitive Landscape
Listed leaders compete with private specialists across hormone delivery system development, creating a tiered structure where scale-driven pharmaceutical conglomerates anchor volume supply while boutique endocrinology-focused developers capture premium positioning. The market organizes around three archetypes: diversified giants with endocrinology divisions, hormone-specialized mid-caps, and rare-disease-focused biotechs. Competitive dynamics center on M&A activity to acquire delivery technology platforms and strategic partnerships with fertility clinic networks to secure patient referral pathways.
Within the diversified pharmaceutical tier, Pfizer Inc. and Eli Lilly and Company exemplify scale-driven positions, with the former leveraging manufacturing infrastructure across North American markets and the latter anchoring integrated clinical trial networks for rare disease indications. Novo Nordisk A/S occupies a specialized position through deep concentration in hormone delivery systems. These three entities represent distinct strategic postures: volume consistency, trial acceleration, and delivery innovation respectively.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| Ferring Pharmaceuticals |
| Endo International plc |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Bayer AG |
| Novo Nordisk A/S |
| Novartis AG |
| Others |
Supply & Pricing Matrix
US FDA orphan drug designation gates both supply qualification and price differentiation simultaneously, compressing development timelines through tax credits while creating market exclusivity windows that sustain premium positioning for specialty-grade testosterone formulations against commodity-tier alternatives.
Pricing Analysis
Specialty endocrinology clinics anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on formulation bioavailability and caregiver training bundling, with transdermal gel protocols commanding premiums over intramuscular injection. Cost compression in the economy tier is intensifying because API supply concentration limits generic substitution. Medicare reimbursement frameworks exhibit highest price sensitivity, while private payers in the United States show greater tolerance for value-based premiums.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for testosterone cypionate and enanthate esters, while European contract manufacturers in Germany and Switzerland concentrate specialty formulation finishing. Raw material dependencies include steroid precursor feedstocks, sterile packaging components, and cold-chain logistics infrastructure. Single-source vulnerability clusters in limited contract manufacturing organizations serving North American markets. Distribution runs through specialty pharmacy channels and hospital-based outpatient infusion centers, with home care channels capturing accelerating volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-acting testosterone formulations and digital therapeutics present substitution threats that incumbent hormone replacement therapy suppliers must navigate through delivery innovation and integrated care model defense.
For Market Incumbents: Shield market position by deepening captive supply of API feedstocks through backward integration into steroid precursor manufacturing, reducing single-source exposure. Fortify reimbursement capture through value-based contract demonstration with Medicare and commercial payers, anchoring quality-of-life endpoints against emerging digital phenotyping competitors. For New Entrants and Emerging Players: Home care administration protocols represent a service-layer gap where incumbents under-serve rural endocrinology practices and adolescent transition clinics. Penetrate the subcutaneous pellet implant segment through caregiver confidence-building education programs and direct-to-patient training platforms, bypassing established specialty clinic gatekeepers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across long-acting injectable formulation development due to EMA paediatric investigation plan mandates and juvenile safety data requirements. Target acquisition candidates with approved adult indications and supplemental filing pathways for adolescent labeling. Watch FDA orphan drug exclusivity expiration schedules as inflection indicators for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Integrated trial networks in Boston and New York Metro accelerate rare disease patient recruitment velocity. |
| Regulatory Approval Pathway | FDA orphan drug designation compresses development timelines through tax credit and market exclusivity provisions. |
| Manufacturing Scale-Up | Endocrinology manufacturing infrastructure in North American markets supplies consistent API volumes across dosage forms. |
| Pipeline Diversification | Digital phenotyping tools for cognitive assessment create reimbursement pathways alongside hormone replacement. |
| Strategic Partnership | Fertility clinic network alliances secure patient referral pathways for sperm cryopreservation procedures. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Conversations with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists inform demand-side validation. Bottom-up patient population estimates and top-down therapeutic category spending triangulate market sizing across treatment type, patient age group, care setting, and administration route segments.
Segmentation dimensions modeled include treatment line, dosage form, administration route, patient population, and regional regulatory cluster across the projection horizon. CAGRs derive from historic growth rate analysis adjusted for orphan drug designation impacts and early-intervention protocol expansion. Forecast inputs incorporate pediatric endocrinology clinic capacity expansion and transdermal gel bioavailability improvement trajectories.
Material uncertainties — regulatory timeline compression for adult-only indications, fertility preservation reimbursement coverage expansion, and biomarker assay standardization — sit outside the modeled envelope. Forecasts reflect assumptions about continued Medicare coding stability and commercial payer value-based contract adoption. Recalibration cycles align with material shifts in FDA orphan drug policy and EMA paediatric investigation plan enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Genome Editing Market
Gene Editing & CRISPR
Knockout Mice Model Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
US Gene Editing Market
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
Genetic Engineering Market
Gene Editing & CRISPR
Germany Gene Editing Market
Gene Editing & CRISPR
Recombinant DNA Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
CRISPR Gene Editing Market
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
Base Editing Market