
 Peptide and Anticoagulant Drugs Market | 2026-2036
Peptide and Anticoagulant Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Peptide and Anticoagulant Drugs Market Intelligence
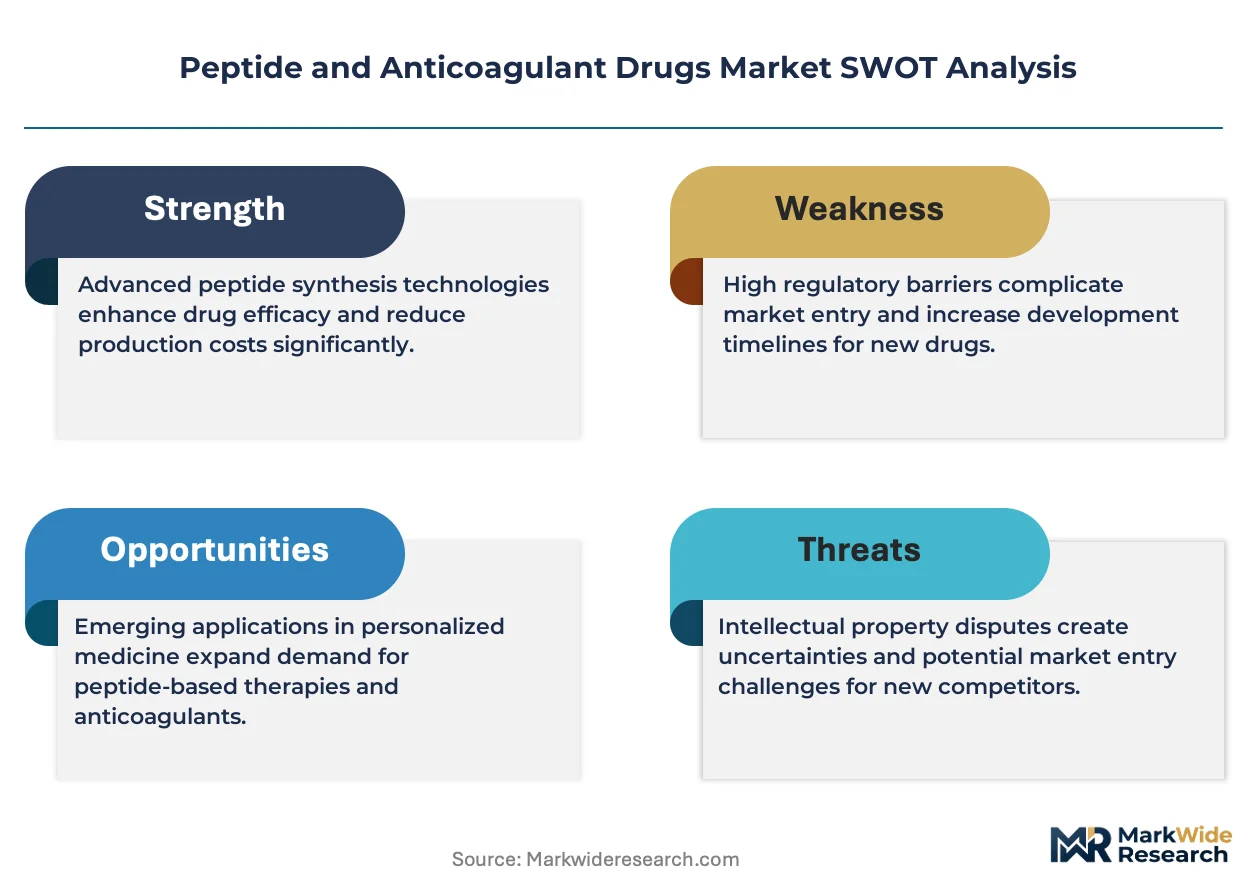
A long-standing reliance on traditional pharmacology expertise is unwinding as computational biology and peptide synthesis skills become critical for innovation. This shift challenges established R&D models for drug discovery and development. Pfizer leverages its extensive clinical trial infrastructure to accelerate new anticoagulant approvals. Meanwhile, Novartis differentiates through its focus on developing novel synthetic peptides for niche indications.
Peptide and anticoagulant drugs encompass two distinct but often related therapeutic classes. Peptides are short-chain amino acid polymers, while anticoagulants inhibit blood coagulation by targeting specific clotting factors like thrombin or Factor Xa. Their primary purpose is the prevention and treatment of thromboembolic conditions. The market for Factor Xa inhibitors continues to expand, driven by oral delivery modes that offer greater patient convenience than injectable heparins.
Regulatory oversight from bodies like the U.S. FDA, the European Medicines Agency (EMA), and China's NMPA governs market access. These agencies mandate rigorous clinical trials and define standards for drug safety and efficacy. The EMA's specific guidance on biosimilar peptides, for instance, creates pathways for generic competition. The critical decision for drug developers is how to balance investment between blockbuster indications and targeted therapies for rare diseases.
Market Dynamics
The central structural force is the pivot from empirical drug discovery to data-driven R&D models. This transition prioritizes computational biology and advanced peptide synthesis, challenging the long-standing dominance of traditional pharmacology expertise in creating new therapeutics.
Growth Catalysts
- Expanding Chinese Market:China's focus on expanding healthcare access for its aging population creates significant demand for cardiovascular therapies, including anticoagulants.
- Oral Delivery Modes:The development of oral Factor Xa inhibitors offers greater patient convenience compared to injectable heparins, driving adoption in outpatient settings.
- Biosimilar Pathways:The EMA's specific guidance on biosimilar peptides establishes a clear regulatory framework, encouraging generic competition and expanding market access.
Market Restraints
- High Synthesis Costs:The complex and costly nature of peptide synthesis and purification processes acts as a barrier to entry and limits affordability.
- Stringent Regulatory Hurdles:Rigorous clinical trial mandates from agencies like the U.S. FDA and EMA lead to long development timelines and high attrition rates.
- Patent Expiration:The loss of market exclusivity for several blockbuster anticoagulant drugs intensifies price pressure from generic and biosimilar competitors.
Strategic Opportunities
- Niche Indications:Development of novel synthetic peptides for rare diseases presents an opportunity to address unmet medical needs with less competition.
- Geographic Expansion:Underpenetrated markets in Southeast Asia and Latin America, where cardiovascular disease incidence is rising, offer new growth frontiers for established drugs.
- AI in Drug Discovery:Leveraging artificial intelligence and computational platforms can accelerate the identification and optimization of new peptide and anticoagulant drug candidates.
Industry Challenges
- Specialized Talent Scarcity:A shortage of professionals with combined expertise in peptide chemistry, computational biology, and regulatory affairs constrains R&D productivity.
- Manufacturing Complexity:Ensuring the stability and quality of sensitive peptide drug formulations during large-scale manufacturing and distribution remains a significant operational hurdle.
- Intellectual Property Navigation:Managing the dense and often overlapping patent landscape for peptide sequences and delivery technologies complicates commercialization strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptide and Anticoagulant Drugs Market |
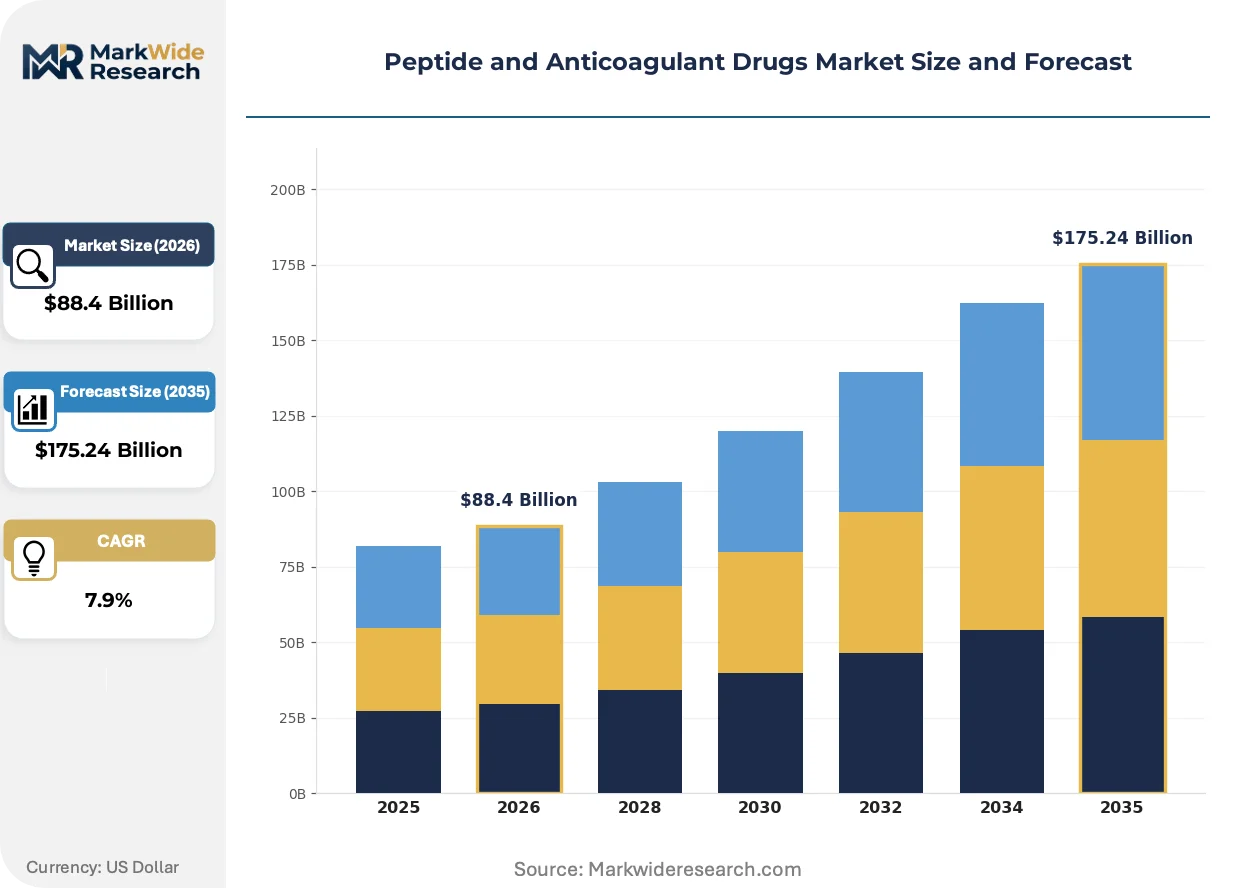
| Market Size in 2026 | $88.4 Billion |
| Market Size in 2035 | $175.24 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heparins, Direct Thrombin Inhibitors, Factor Xa Inhibitors, Synthetic Peptides, Low Molecular Weight Heparins Therapy Area: Venous Thromboembolism, Atrial Fibrillation, Myocardial Infarction, Stroke Prevention, Deep Vein Thrombosis End User: Cardiology Clinics, Specialized Pharmacies, Hematology Centers, Diagnostic Laboratories, Ambulatory Care Centers Delivery Mode: Injectable, Oral Tablets, Transdermal Patches, Intravenous Infusions, Subcutaneous Injections |
| Companies Covered | Bristol-Myers Squibb, Bayer, Boehringer Ingelheim, Merck & Co., Amgen, Pfizer, Novartis, AstraZeneca, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptide and Anticoagulant Drugs Market Strategic Shifts & Innovations
The convergence of biologic drug development with digital health tools is defining the market's trajectory. This integration enables more patient-centric delivery mechanisms and personalized therapeutic strategies, moving beyond one-size-fits-all treatment paradigms.
Oral delivery technologies, including permeation enhancers and encapsulation methods, enable the conversion of injectable drugs into pill form. Cardiology clinics and patients managing chronic conditions are adopting these formulations for superior convenience. This shift away from clinical administration for certain therapies is fragmenting the traditional hospital-centric delivery model into a more distributed system.
The EU's Medical Device Regulation (MDR) imposes stricter requirements on drug-device combination products like pre-filled anticoagulant pens. This regulation increases the clinical data and post-market surveillance burden for manufacturers. As a result, companies targeting the European market are redesigning devices and updating conformity assessments to maintain market access.
A demand-side shift toward personalized medicine influences anticoagulant prescribing. Generic prescriptions are being challenged by therapies selected based on patient-specific genetic markers or bleeding risk profiles. This trend is most visible in specialized cardiology centers in the United States and Germany, where diagnostic testing increasingly guides therapeutic choices.
Peptide and Anticoagulant Drugs Market Segmentation
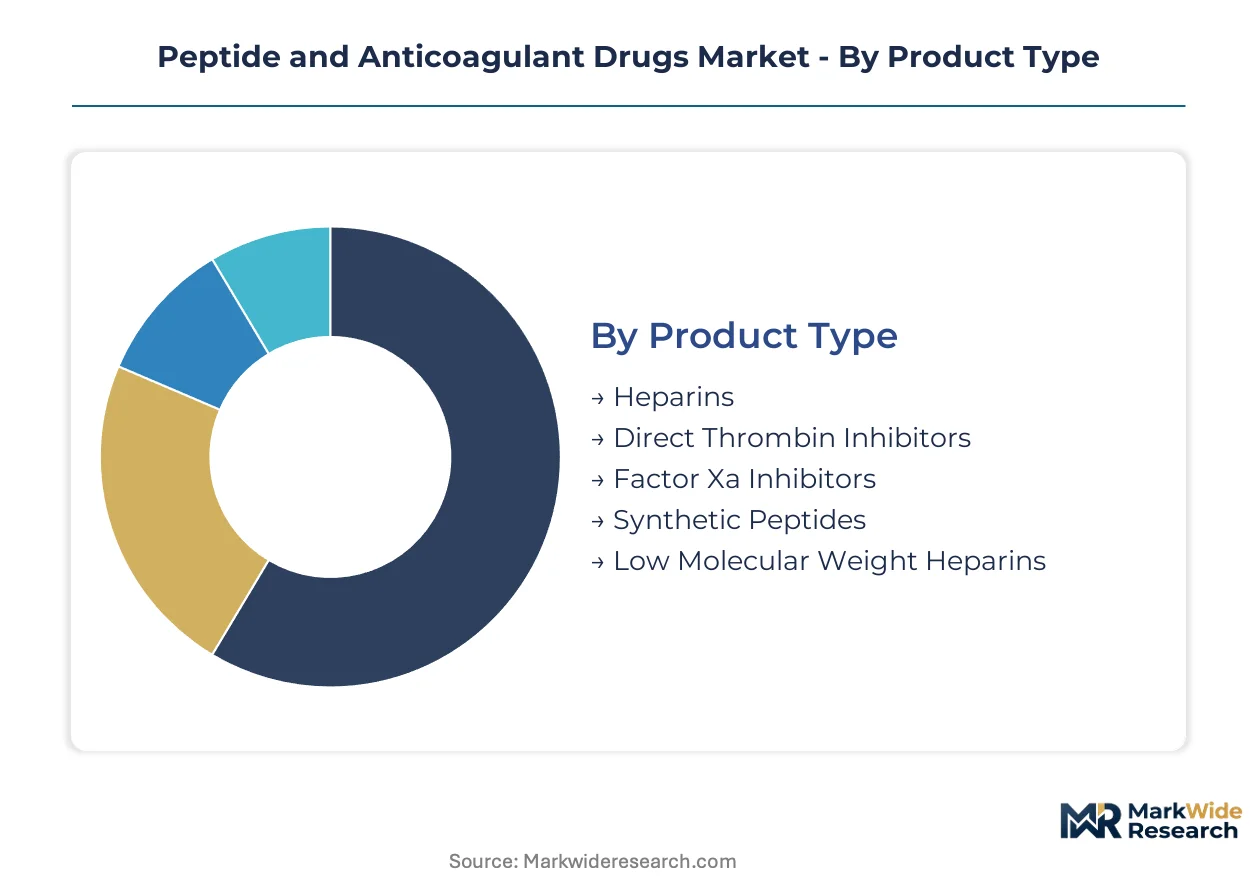
Market segmentation provides a critical framework for understanding the diverse dynamics and value propositions within the peptide and anticoagulant drugs sector. This breakdown illuminates specific areas of revenue concentration and highlights distinct growth opportunities across various product types, therapeutic applications, end-user groups, and delivery methods.
Product Type:
Margin pools within the product type category often concentrate around novel synthetic peptides and advanced Factor Xa inhibitors due to their therapeutic innovation and patient convenience.
- Heparins:These are naturally derived anticoagulant polysaccharides that enhance the activity of antithrombin, primarily used for preventing and treating thromboembolic disorders.
- Direct Thrombin Inhibitors:These agents directly block the enzymatic activity of thrombin, a crucial clotting factor, to prevent clot formation.
- Factor Xa Inhibitors:These drugs directly target Factor Xa, a key enzyme in the coagulation cascade, preventing thrombin generation. Demand concentrates in outpatient settings in Germany due to the convenience of oral administration for chronic conditions.
- Synthetic Peptides:These are engineered short-chain amino acid polymers designed for specific therapeutic targets, offering high specificity and reduced off-target effects. Demand is concentrating in specialized oncology centers in the United States for targeted therapies.
- Low Molecular Weight Heparins:These are fractionated heparins providing more predictable anticoagulant effects and a longer half-life than unfractionated heparin.
The dominant share belongs to Factor Xa Inhibitors, while Synthetic Peptides are closing the gap fastest.
Therapy Area:
Application-specific demand shapes the therapy area landscape, reflecting the prevalence of cardiovascular conditions globally.
- Venous Thromboembolism:This condition encompasses deep vein thrombosis and pulmonary embolism, requiring immediate and often extended anticoagulant treatment. Demand concentrates in hospital settings in the United States, driven by post-surgical prophylaxis protocols and emergency care.
- Atrial Fibrillation:This cardiac arrhythmia increases the risk of blood clot formation in the atria, necessitating long-term anticoagulant therapy. Demand concentrates in cardiology clinics in China due to the expanding elderly population and improved diagnostic capabilities.
- Myocardial Infarction:Anticoagulants are crucial for preventing re-thrombosis and managing acute coronary syndromes following a heart attack.
- Stroke Prevention:Preventing ischemic stroke, particularly in patients with atrial fibrillation, is a primary application for oral anticoagulants.
- Deep Vein Thrombosis:This involves clot formation in deep veins, often in the legs, requiring anticoagulant intervention to prevent pulmonary embolism.
Venous Thromboembolism applications remain substantial, but the Atrial Fibrillation segment is expanding most quickly.
End User:
Volume distribution across end-user segments reflects where diagnostic and treatment protocols for thromboembolic conditions are most established.
- Cardiology Clinics:These specialized medical facilities manage patients with various heart conditions, including those requiring chronic anticoagulant therapy. Demand concentrates in urban centers in Germany, driven by routine follow-ups for patients with atrial fibrillation and other cardiovascular diseases.
- Specialized Pharmacies:These pharmacies dispense complex or high-cost medications, including novel anticoagulants and peptide drugs, often with patient counseling. Demand concentrates in major metropolitan areas in Japan, supporting home-based care and patient adherence programs.
- Hematology Centers:These centers specialize in blood disorders, providing advanced diagnostics and treatment for complex coagulation issues.
- Diagnostic Laboratories:These facilities perform critical tests for coagulation parameters and drug monitoring, guiding anticoagulant therapy.
- Ambulatory Care Centers:These outpatient facilities provide same-day medical procedures and consultations, including initial anticoagulant prescriptions and monitoring.
Cardiology Clinics account for a significant portion of drug administration, with Specialized Pharmacies gaining share fastest through their dispensing services.
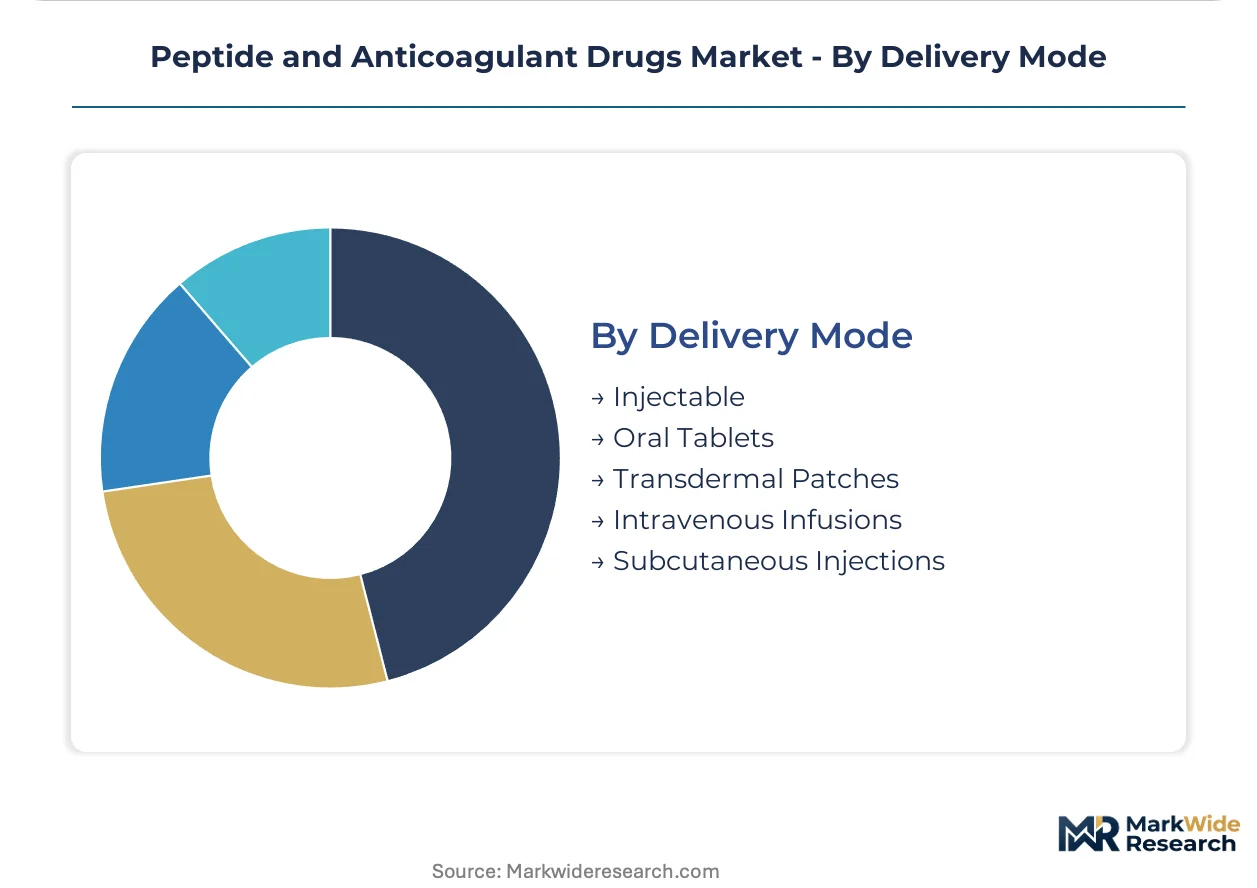
Delivery Mode:
Cost tiers within delivery modes are often influenced by manufacturing complexity and patient convenience, affecting overall market accessibility.
- Injectable:This traditional delivery method ensures rapid systemic absorption and precise dosing, often used for acute conditions or in hospital environments. Demand concentrates in emergency departments in France for immediate anticoagulant intervention in critical cases.
- Oral Tablets:These formulations offer significant patient convenience and adherence benefits, facilitating long-term management of chronic conditions outside hospital settings. Demand concentrates in the United States, driven by consumer preference for non-invasive drug administration.
- Transdermal Patches:These patches deliver medication through the skin, offering sustained release and avoiding first-pass metabolism.
- Intravenous Infusions:This method provides immediate and continuous drug delivery directly into the bloodstream, typically used in critical care settings.
- Subcutaneous Injections:These injections are administered under the skin, suitable for self-administration and certain long-acting formulations.
Injectable delivery modes maintain a foundational presence, but Oral Tablets are currently on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide and anticoagulant drug consumption varies significantly across key geographies. China's market expansion is driven by an aging population and increasing healthcare access for cardiovascular conditions. In contrast, the United States prioritizes patient convenience through oral delivery and targeted therapies.
United States
Demand for oral tablets offers patient convenience for chronic conditions. The U.S. FDA mandates rigorous clinical trials, influencing drug development timelines. Cardiology centers in major metropolitan areas like Boston and New York guide therapeutic choices based on patient-specific genetic markers.
China
China's expanding elderly population and improved diagnostic capabilities drive demand for atrial fibrillation treatments. The NMPA governs market access, ensuring drug safety and efficacy standards for new approvals. Cardiology clinics in urban centers such as Shanghai and Guangzhou see concentrated demand for long-term anticoagulant therapies.
Germany
Oral Factor Xa inhibitors are highly adopted in Germany for outpatient settings due to patient convenience. The EMA's Medical Device Regulation (MDR) imposes stricter requirements on drug-device combination products. Cardiology clinics in urban centers like Berlin and Munich manage patients with chronic cardiovascular diseases.
Japan
Specialized pharmacies in Japan support home-based care and patient adherence programs for complex anticoagulant regimens. The PMDA sets stringent standards for drug approval and post-market surveillance. Major metropolitan areas like Tokyo and Osaka concentrate demand for advanced dispensing services.
France
Injectable delivery modes maintain a foundational presence in France for immediate anticoagulant intervention. ANSM provides national regulatory oversight for pharmaceutical products and medical devices. Emergency departments in cities such as Paris and Marseille see high demand for acute thromboembolic treatment.
Peptide and Anticoagulant Drugs Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the market structure. This tiered landscape features firms leveraging extensive clinical trial infrastructure, alongside those specializing in novel synthetic peptides and computational biology. Key competitive moves include accelerating new drug approvals and differentiating through focus on niche indications. Portfolio diversification and strategic partnerships also shape the competitive environment, influencing market access and innovation.
Within the integrated leaders tier, Pfizer, a global pharmaceutical corporation, exemplifies leveraging extensive clinical trial infrastructure to accelerate new anticoagulant approvals. Novartis, a Swiss-based pharmaceutical firm, represents differentiation through its focus on developing novel synthetic peptides for niche indications, often for specialized patient populations. Bristol-Myers Squibb, another prominent global pharmaceutical company, occupies a significant position among the major players, anchoring scale-driven operations and broad market reach across therapeutic areas.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Bayer |
| Boehringer Ingelheim |
| Merck & Co. |
| Amgen |
| Pfizer |
| Novartis |
| AstraZeneca |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Long-term supply contracts for active pharmaceutical ingredients lock in both supply access and price visibility for peptide and anticoagulant drug manufacturers. This arrangement mitigates volatility in raw material costs, allowing for more predictable finished product pricing strategies.
Pricing Analysis
Value-based pricing dominates for novel synthetic peptides, reflecting their high specificity and reduced off-target effects. Price differentiation stems from regulatory approval status and formulation complexity. Pricing softness reflects generic competition, particularly for blockbuster anticoagulant drugs facing patent expiration. Outpatient settings exhibit higher price sensitivity compared to specialized oncology centers, which prioritize therapeutic efficacy.
Supply Chain Analysis
Inventory management for sensitive peptide drug formulations requires cold chain logistics and specialized storage, impacting lead times. Geographic supply concentration for key raw materials centers in China and India, while advanced peptide synthesis often occurs in European facilities. Single-source vulnerability for advanced intermediates represents a structural risk within the supply chain. Distribution runs through specialized pharmacies and hospital systems for final patient access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a fragmentation opportunity as personalized medicine creates distinct niches for targeted therapeutic strategies.
For Market Incumbents:Secure intellectual property for next-generation Factor Xa inhibitors to counter patent expiration. Accelerate biosimilar development for established peptide drugs, leveraging extensive clinical trial infrastructure. Invest in proprietary oral delivery technologies to enhance patient convenience and expand market reach. Regulatory expertise remains a critical lever against generic competition.
For New Entrants and Emerging Players:Anchor in rare disease indications by developing novel synthetic peptides for unmet medical needs. Target underpenetrated markets in Southeast Asia where cardiovascular disease incidence is rising. Niche synthetic peptides for orphan diseases represent the most penetrable segment. A direct-to-specialist sales force in specialized cardiology centers offers an effective go-to-market angle.
For Investors and Strategic Acquirers:Biotech firms specializing in AI-driven peptide discovery present attractive acquisition targets for sustained innovation over a five-to-ten year window. Focus on companies with strong pipelines in targeted therapies and proven regulatory pathways. Successful Phase 3 clinical trial readouts for novel peptide platforms serve as a key signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel peptide and anticoagulant drug candidates through rigorous efficacy and safety data. |
| Regulatory Approval Pathway | Secures market access and competitive advantage by navigating complex requirements from agencies like the U.S. FDA and EMA. |
| Manufacturing Scale-Up | Ensures consistent supply of sensitive peptide drug formulations to meet expanding global demand. |
| Pipeline Diversification | Mitigates R&D risks by exploring multiple therapeutic areas beyond traditional cardiovascular applications. |
| Strategic Partnership | Leverages complementary expertise in drug discovery, development, or distribution to expand market footprint. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation. Drug development executives, regulatory affairs leads, hospital procurement managers, and specialized pharmacy directors provided critical insights. Secondary data sources included FDA filings, EMA submissions, clinical trial registries, and pharmaceutical industry reports, facilitating bottom-up and top-down triangulation.
The forecasting framework established a comprehensive analytical approach across the analysis window. Segmentation dimensions modeled included product type, therapy area, end-user, delivery mode, and regional regulatory environment. Compound annual growth rates were derived through a weighted average of historical trends and projected market dynamics, incorporating forecast inputs like patent expiration schedules and new drug approval rates.
Decision-makers should treat outputs as directional under base assumptions regarding regulatory stability and clinical success; material deviation would warrant model refresh. Unforeseen regulatory changes or major clinical trial failures represent significant risk factors for market projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
H1N1 Vaccination Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Global Rotavirus Vaccine Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Rheumatology Therapeutics Market