
 Injectable Drugs Market | 2026-2036
Injectable Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Injectable Drugs Market Outlook
Modular packaging configurations combining prefilled syringes with auto-injector compatibility is broadening buyer choice across hospital and homecare settings. Pfizer leverages vertical integration from active pharmaceutical ingredient production to finished sterile dosage forms. Fresenius Kabi anchors European supply through specialized aseptic manufacturing infrastructure. Amgen differentiates via concentrated biologic formulations that reduce injection frequency for chronic therapy patients.
Injectable drugs comprise sterile liquid, powder, or suspension formulations administered parenterally through intravenous, subcutaneous, intramuscular, or intra-articular routes, requiring pyrogen-free manufacturing under ISO 5 cleanroom conditions and terminal sterilization or aseptic processing. Biologics command premium pricing due to cold-chain dependencies and complex protein stabilization requirements, while small molecules maintain volume leadership in emergency and acute care protocols. Subcutaneous delivery modes are expanding fastest as self-administration protocols shift site-of-care from hospitals to homecare settings, redistributing margin pools toward patient training services and compliance monitoring technologies.
FDA enforces Current Good Manufacturing Practice under 21 CFR Parts 210-211 with heightened scrutiny of particulate matter and endotoxin limits, while EMA's Annex 1 revision mandates continuous viable and non-viable particle monitoring throughout aseptic processing. The EU MDR imposes Unique Device Identification on combination products including prefilled syringes and needle safety systems, elevating compliance costs for market access. Stakeholders must monitor convergence between pharmaceutical quality standards and medical device regulations as combination product submissions become the dominant pathway for novel injectable therapies.
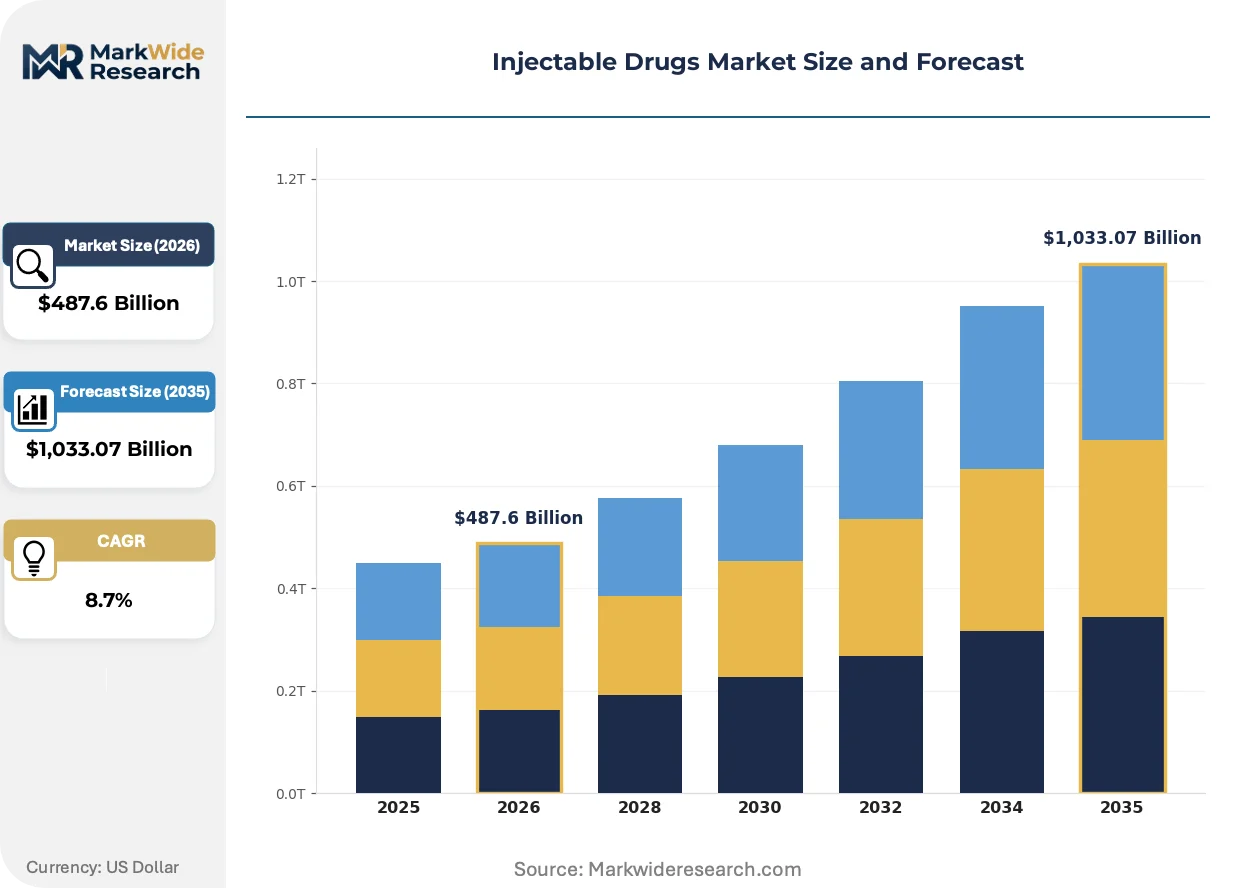
Market Dynamics
The Injectable Drugs Market is being fundamentally restructured by the migration of administration from hospital infusion centers to patient homes, which is redistributing manufacturing priorities toward prefilled delivery systems and cold-chain logistics networks.
Growth Catalysts
- FDA Biosimilar Approval Pathway:Accelerated entry of follow-on biologics is expanding therapeutic access while compressing originator pricing power across oncology and immunology segments.
- Subcutaneous Formulation Engineering:Concentrated protein stabilization technologies enable self-administration protocols that shift site-of-care and unlock homecare reimbursement codes.
- German Cold-Chain Infrastructure Investment:Specialized aseptic manufacturing clusters in Baden-Württemberg and Bavaria are anchoring European supply security for temperature-sensitive biologics.
Market Restraints
- Glass Primary Packaging Concentration:Borosilicate tubing supply concentrates among three European suppliers, creating single-source vulnerability for prefilled syringe manufacturers.
- EMA Annex 1 Compliance Costs:Continuous viable particle monitoring mandates throughout aseptic processing are elevating capital expenditure thresholds for facility upgrades.
- Biologic Cold-Chain Energy Intensity:Ultra-low temperature storage requirements for mRNA and cell therapies constrain distribution reach into emerging markets lacking reliable power infrastructure.
Strategic Opportunities
- Japan Homecare Expansion:METI reimbursement reforms for self-injection therapies are opening patient-administered channels for chronic disease management outside hospital settings.
- Combination Product Convergence:Integration of connected auto-injectors with digital adherence monitoring creates subscription revenue streams beyond drug substance sales.
- Indian Biosimilar Manufacturing:CDSCO streamlined approval pathways and PLI scheme incentives position domestic producers for export-oriented biologic production.
Industry Challenges
- Aseptic Processing Talent Scarcity:ISO 5 cleanroom operators with viable particle detection expertise command premium wages that compress manufacturing margins.
- EU MDR UDI Implementation:Unique Device Identification serialization requirements for prefilled syringes and needle safety systems are extending compliance timelines for combination product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injectable Drugs Market |
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,033.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Vaccines, Hormones Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Intra-articular End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Oncology, Diabetes, Cardiovascular, Autoimmune |
| Companies Covered | Johnson & Johnson Services, Pfizer, Merck & Co., Novartis AG, Baxter International, F. Hoffmann-La Roche Ltd., Amgen, GlaxoSmithKline, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injectable Drugs Market Strategic Shifts
Injectable drug delivery is converging with connected health infrastructure, creating pressure on manufacturers to integrate digital capabilities into physical delivery devices while maintaining sterility assurance.
Connected auto-injector platforms with embedded sensors and wireless transmission modules are electrifying the patient adherence monitoring landscape. Hospital systems in the United States are piloting these devices for post-discharge oncology patients to reduce emergency readmissions. The technology is electrifying competitive differentiation beyond molecule efficacy toward integrated care pathway economics.
EMA's revised Annex 1 on sterile medicinal products is tightening environmental monitoring requirements across European aseptic manufacturing facilities. Continuous viable particle detection systems are becoming mandatory rather than batch-sampled, forcing facility redesigns. Small-volume parenteral manufacturers in Italy and Spain are consolidating production lines to amortize compliance investments across higher throughput.
Homecare infusion services are unbundling from hospital pharmacy departments into specialized third-party providers with dedicated nursing networks. This channel fragmentation is compressing traditional hospital purchasing leverage and elevating direct-to-patient logistics capabilities. The shift is most visible in Germany and the Netherlands where homecare reimbursement frameworks have matured fastest.
Injectable Drugs Market Segmentation
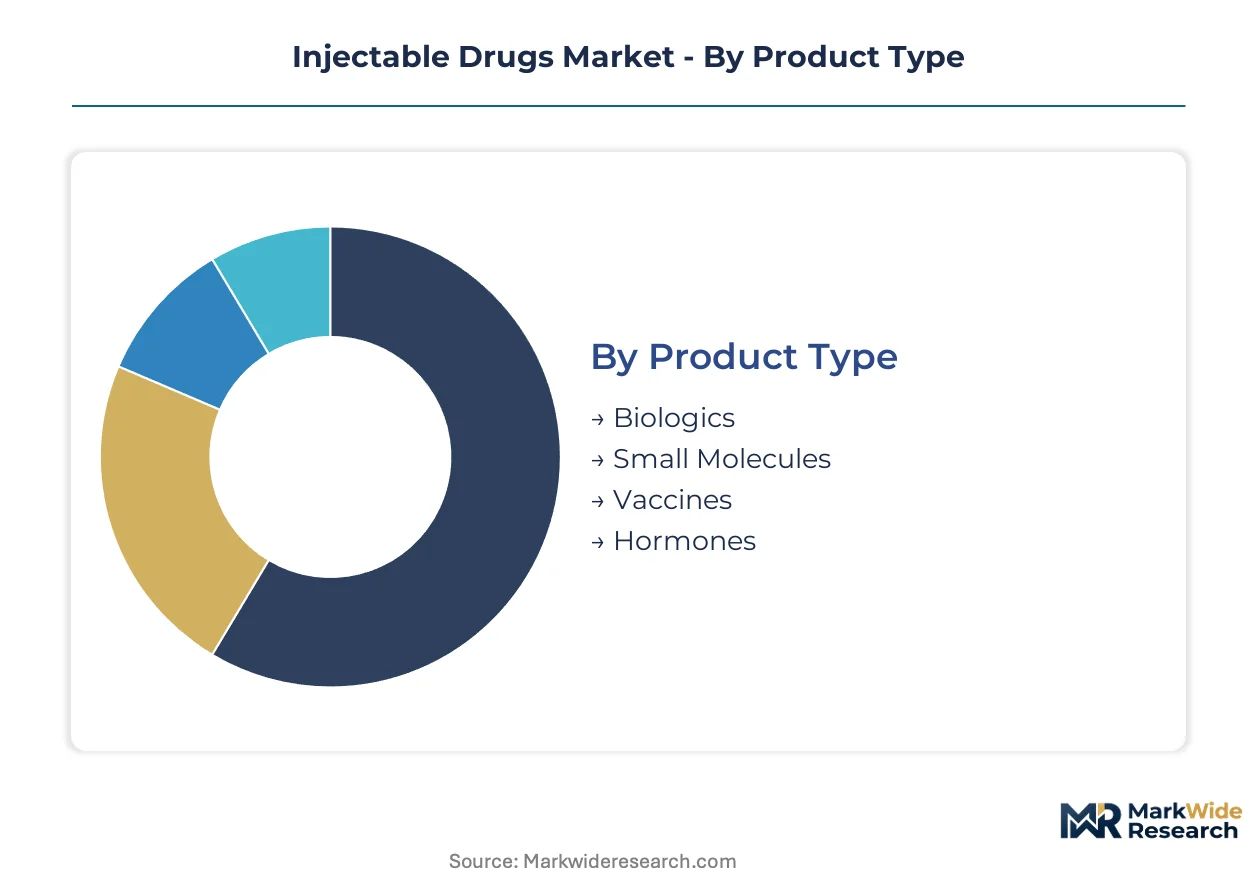
Injectable drug segmentation reveals how formulation complexity, administration setting, and therapeutic specialization fragment manufacturing priorities. Each category channels capital toward distinct capability requirements.
Product Type:
Standardization dominates small molecules while biologics demand bespoke manufacturing infrastructure and cold-chain validation protocols.
- Biologics:Complex protein formulations requiring aseptic processing under ISO 5 conditions and ultra-low temperature stabilization. Demand concentrates in United States hospital systems managing oncology and immunology protocols, constrained by EMA Annex 1 continuous monitoring mandates that elevate facility capital requirements.
- Small Molecules:Synthetic chemical compounds amenable to terminal sterilization and higher throughput manufacturing. Volume leadership sits with emergency and acute care applications in German hospital networks, where standardized procurement frameworks favor multi-source supply security.
- Vaccines:Antigen-based formulations spanning viral vector and mRNA platforms with distinct cold-chain profiles.
- Hormones:Peptide and steroid formulations for endocrine replacement and reproductive therapy protocols.
Leading the category by volume: Small Molecules. Expanding most quickly: Biologics.
Delivery Mode:
Route selection determines device complexity, patient training burden, and reimbursement coding structure across markets.
- Intravenous:Direct vascular administration requiring infusion pump compatibility and hospital pharmacy compounding. Demand concentrates in United States oncology centers, where site-of-care reimbursement differentials sustain hospital-based administration despite higher per-dose costs.
- Subcutaneous:Tissue-layer injection enabling self-administration via prefilled syringes and auto-injector systems. Japanese homecare expansion under METI reimbursement reforms is accelerating patient-administered adoption for chronic disease management.
- Intramuscular:Deep tissue delivery for depot formulations and vaccine administration.
- Intra-articular:Joint-space injection for localized anti-inflammatory therapy in orthopedic and rheumatology settings.
Volume leadership: Intravenous. Steepest expansion trajectory: Subcutaneous.
End User:
Channel structure fragments purchasing authority between consolidated hospital systems and dispersed homecare providers.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees governing formulary access. German university hospitals anchor European demand for high-complexity biologics, leveraging specialized aseptic compounding capabilities.
- Homecare:Third-party nursing services and direct-to-patient logistics for self-administered therapies. Netherlands reimbursement frameworks have matured fastest, unbundling infusion services from hospital pharmacy departments.
- Clinics:Outpatient specialty settings for routine administration and monitoring.
- Pharmacies:Retail and specialty dispensing channels for patient-collected injectables.
Greatest procurement leverage: Hospitals. Fastest channel growth: Homecare.
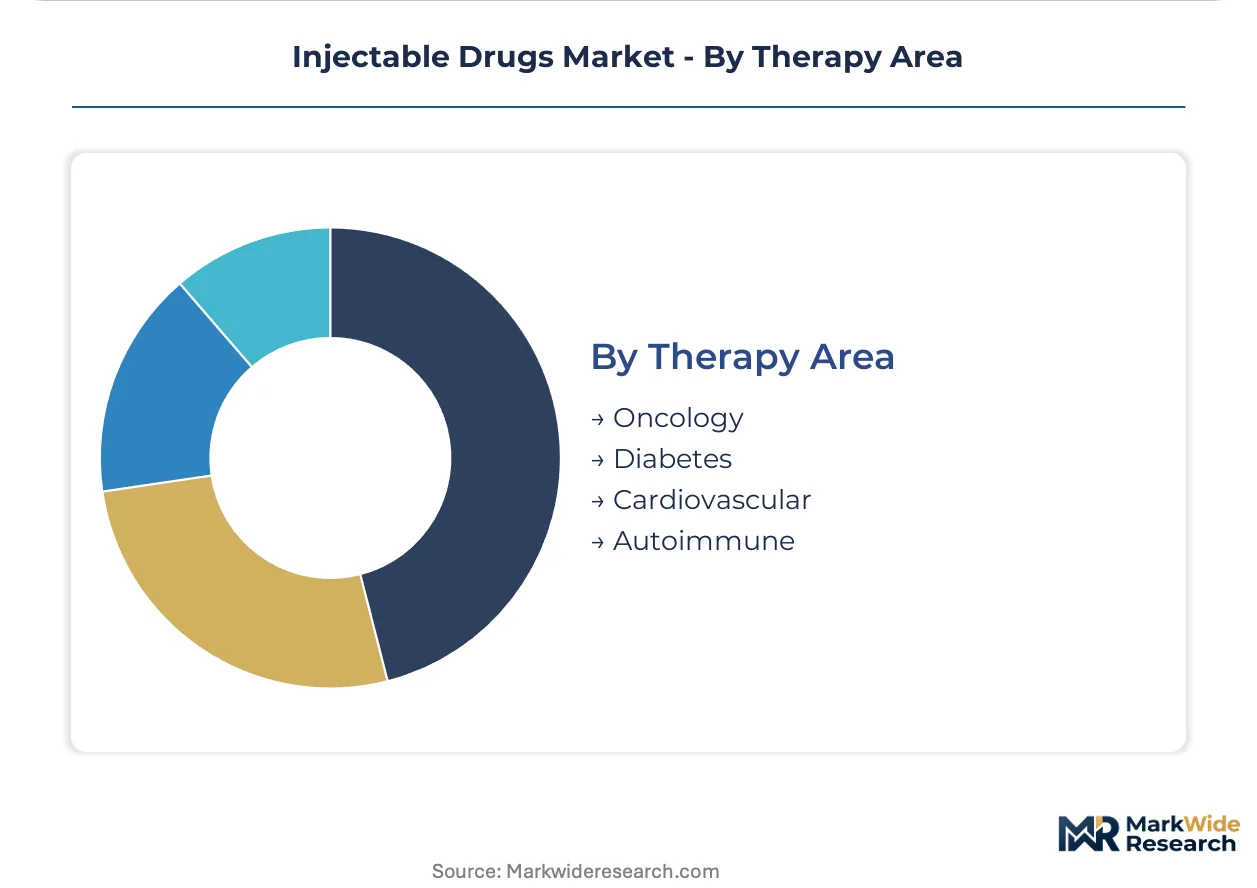
Therapy Area:
Therapeutic specialization dictates pricing power, clinical trial requirements, and competitive entry barriers.
- Oncology:Cytotoxic and immunologic agents for solid tumor and hematologic malignancy protocols. FDA biosimilar approval pathways are compressing originator pricing power while expanding therapeutic access in United States academic medical centers.
- Diabetes:Insulin analogs and GLP-1 receptor agonists for glycemic control. German sickness funds drive volume procurement through centralized tendering, favoring biosimilar insulin entry.
- Cardiovascular:Anticoagulant and antiplatelet injectables for acute coronary syndrome management.
- Autoimmune:Cytokine inhibitors and immunomodulators for rheumatoid arthritis, psoriasis, and inflammatory bowel disease.
Revenue concentration: Oncology. Gaining share fastest: Diabetes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical zones in Singapore and Ireland concentrate sterile manufacturing capacity through tax-advantaged structures. These jurisdictions attract multi-billion dollar aseptic facility investments. Cold-chain infrastructure buildout follows regulatory harmonization patterns across major demand centers.
United States
Oncology infusion centers and hospital outpatient departments drive biologic injectable consumption through site-of-service reimbursement differentials. FDA biosimilar approval pathways under the Biologics Price Competition and Innovation Act accelerate follow-on entry. The Research Triangle Park in North Carolina anchors sterile fill-finish capacity expansion for temperature-sensitive formulations.
Germany
University hospital networks and sickness fund tendering frameworks concentrate procurement leverage for high-complexity biologics. EMA Annex 1 revisions mandate continuous viable particle monitoring throughout aseptic processing. Manufacturing clusters in Baden-Württemberg and Bavaria specialize in cold-chain validated sterile dosage forms for European distribution.
Japan
Homecare reimbursement reforms under METI enable patient-administered subcutaneous therapies outside hospital settings. PMDA streamlined review pathways for combination products accelerate connected auto-injector market entry. The Kansai region around Osaka hosts specialized aseptic manufacturing infrastructure serving domestic and export markets.
India
CDSCO streamlined biosimilar approval pathways and PLI scheme incentives position domestic producers for export-oriented biologic manufacturing. The central government's pharmaceutical parks program targets sterile injectable capacity in Telangana and Gujarat. Hyderabad's Genome Valley cluster concentrates contract development and manufacturing organizations with US FDA-inspected facilities.
Switzerland
Specialized aseptic manufacturing expertise and bilateral regulatory recognition agreements sustain export competitiveness for high-value biologics. Swissmedic maintains stringent sterile product standards aligned with EU MDR requirements. The Basel region anchors European biologic drug substance and finished dosage form integration.
Injectable Drugs Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation complexity tiers. Market structure concentrates among vertically integrated pharmaceutical majors with captive active pharmaceutical ingredient supply and contract manufacturers with specialized aseptic capabilities. Three archetypes dominate: originator biologic developers with patent-protected portfolios, biosimilar specialists with cost-optimized manufacturing, and delivery-technology integrators combining drug substance with device platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure sterile manufacturing slots and cold-chain logistics networks.
Among diversified pharmaceutical majors, Pfizer and Novartis occupy positions spanning originator biologics and established small molecule injectables. Fresenius Kabi exemplifies the specialized sterile manufacturing archetype with European aseptic infrastructure focus. These entities represent contrasting strategic postures: broad therapeutic portfolio diversification versus concentrated delivery-system expertise.
| Leading Market Players |
|---|
| Johnson & Johnson Services |
| Pfizer |
| Merck & Co. |
| Novartis AG |
| Baxter International |
| F. Hoffmann-La Roche Ltd. |
| Amgen |
| GlaxoSmithKline |
| Fresenius Kabi |
| Others |
Value Chain & Pricing Dynamics
Backward integration from active pharmaceutical ingredient synthesis through finished sterile dosage form production anchors both supply security and pricing power for originator biologic developers. Pfizer's captive control over monoclonal antibody substance and fill-finish infrastructure insulates margin structures from borosilicate glass tubing volatility while enabling premium positioning for temperature-sensitive oncology formulations.
Pricing Analysis
Short lead-time premiums for cold-chain validated sterile products sustain margin pools for manufacturers with redundant aseptic capacity, while spot inventory discounts emerge for standard small molecules with terminal sterilization pathways. Three-tier pricing structure across premium biologics, standard generics, and economy multi-source injectables stratifies by EMA Annex 1 compliance certification and ISO 5 cleanroom validation tier. Pricing pressure stems from FDA biosimilar approval pathways compressing originator oncology pricing. German sickness funds exhibit highest price sensitivity through centralized tendering, while United States academic medical centers prioritize supply security over unit cost.
Supply Chain Analysis
EMA Annex 1 and FDA Current Good Manufacturing Practice certifications gate supplier qualification for aseptic processing components, concentrating approved vendors among German, Swiss, and United States sterile manufacturing equipment specialists. Borosilicate glass tubing for prefilled syringes draws from Schott AG in Germany and Corning in the United States, with silicone oil lubricants and elastomeric plunger stoppers sourced from specialized chemical suppliers. Single-source vulnerability concentrates in European glass primary packaging. Distribution runs through cold-chain validated logistics networks anchored by United States hospital distribution centers and European specialized pharma hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
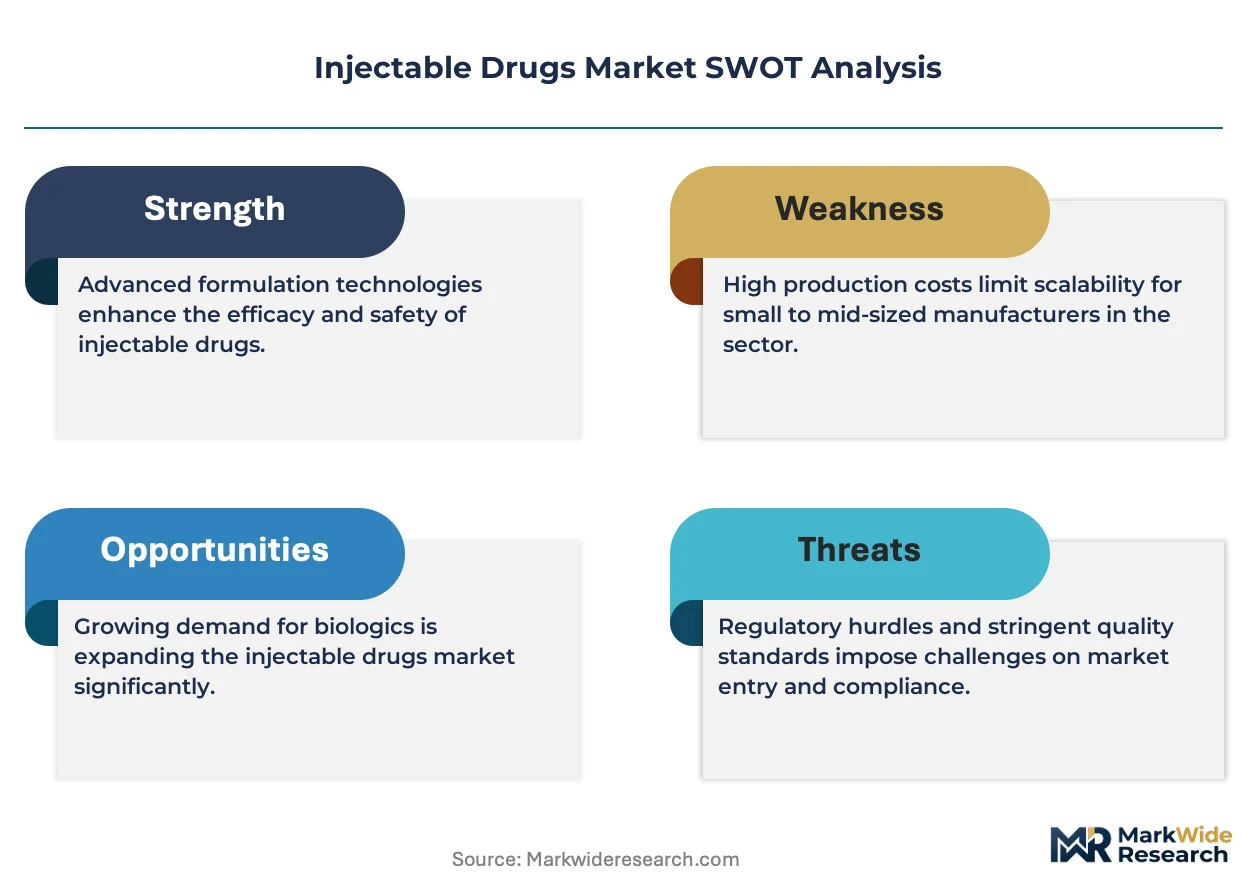
This market consolidates around manufacturers with integrated sterile infrastructure as EMA Annex 1 compliance costs and talent scarcity force sub-scale facility closures. Weaker players lacking captive aseptic capacity face margin compression from contract manufacturing slot scarcity.
For Market Incumbents: To counter biosimilar pricing erosion in oncology and immunology segments, secure redundant fill-finish capacity through strategic partnerships with CDMOs in Singapore and Ireland. Invest in continuous viable particle monitoring systems to preempt EMA enforcement actions on Annex 1 compliance gaps. Prioritize subcutaneous formulation engineering to capture homecare reimbursement codes shifting site-of-care economics.
For New Entrants and Emerging Players: Third-party homecare nursing networks offer the most penetrable channel for patient-administered subcutaneous therapies, bypassing consolidated hospital formulary gatekeeping. Target Japanese METI reimbursement reform corridors for connected auto-injector market entry. Pursue CDSCO streamlined biosimilar pathways in India for export-oriented manufacturing scale before competing in regulated Western markets.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized aseptic CDMOs with US FDA and EMA dual-inspected facilities, as pharmaceutical majors outsource sterile manufacturing to manage capital intensity. Long-term viability hinges on cold-chain logistics integration and digital adherence monitoring capabilities. Watch FDA biosimilar approval velocity as the inflection signal for originator portfolio repricing risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Manufacturing Scale-Up | EMA Annex 1 mandates continuous particle monitoring, elevating facility capital thresholds for market access. |
| Connected Auto-Injector Development | PMDA streamlined review pathways accelerate digital adherence monitoring integration into combination products. |
| Cold-Chain Logistics Partnership | Specialized temperature-controlled distribution networks unlock homecare reimbursement codes in Germany and Japan. |
| Biosimilar Portfolio Expansion | FDA approval pathways compress originator pricing while expanding therapeutic access across oncology segments. |
| Glass Primary Packaging Diversification | Schott AG supply concentration creates vulnerability for prefilled syringe manufacturers seeking dual-source security. |
Study Parameters
Document review covered FDA 483 inspection observations, EMA GMP non-compliance reports, and ClinicalTrials.gov protocol registries, complemented by interviews with sterile manufacturing executives, regulatory affairs directors, hospital pharmacy procurement managers, and payer access specialists. Secondary validation drew from formulary database audits, SEC 10-K pharmaceutical segment disclosures, and customs trade data on sterile injectable imports. Bottom-up capacity modeling triangulated against top-down therapeutic demand projections.
Market size and growth trajectory outputs synthesized patient population epidemiology, treatment protocol penetration rates, and pricing elasticity assumptions across the projection horizon. Segmentation modeling spanned molecule type, administration route, end-user channel, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves calibrated to historical approval velocity and reimbursement policy shifts, with specific inputs including FDA biosimilar approval timelines and METI homecare reform implementation pace.
Caveats apply where EMA Annex 1 enforcement intensity or FDA inspection backlog could materially shift the outlook for aseptic manufacturing capacity expansion. Forecasts reflect assumptions on cold-chain infrastructure buildout pace and biosimilar substitution rates in oncology. A model refresh is warranted upon material change in FDA biosimilar approval velocity or German sickness fund tendering framework reforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Hepatitis C Drug Market
Pharmacology
Global Artemisinin Combination Therapy Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
UK Pharmacovigilance Market
Pharmacology
Influenza Medication Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Global Geriatric Medicines Market
Pharmacology
Apixaban Market
Pharmacology
Global Olanzapine Market
Pharmacology
Ketoprofen API Market
Pharmacology
Drug Repurposing Market