
 H1N1 Vaccination Market | 2026-2036
H1N1 Vaccination Market Size, Share, and Industry Trends Forecast 2026-2036
H1N1 Vaccination Market Foresight
Aftermarket cold-chain logistics revenue is tilting toward specialized distributors with validated thermal packaging capabilities. Sanofi Pasteur leverages end-to-end refrigerated distribution networks spanning multiple continents. GlaxoSmithKline anchors its position through high-yield egg-based production infrastructure. Seqirus differentiates via cell-culture manufacturing platforms that reduce lead times during strain updates.
H1N1 vaccination refers to immunization against the influenza A virus subtype H1N1 using formulations containing inactivated, live attenuated, or recombinant hemagglutinin antigens typically administered at 15 micrograms per strain in seasonal trivalent or quadrivalent compositions, designed to elicit protective antibody responses against circulating pandemic and seasonal variants. The adjuvanted vaccine segment captures premium positioning where immunogenicity enhancement serves elderly and immunocompromised populations. Intranasal delivery modes occupy a structural niche in pediatric applications where needle-free administration improves compliance rates. Public health departments represent the dominant procurement channel through centralized national tendering systems.
The FDA oversees strain composition approvals through its Vaccines and Related Biological Products Advisory Committee, while WHO coordinates global surveillance via the Global Influenza Surveillance and Response System. EMA's Committee for Medicinal Products for Human Use harmonizes seasonal strain selections across European member states. Stakeholders must monitor antigenic drift patterns and regulatory acceleration mechanisms to align manufacturing capacity with potential pandemic declaration timelines.
Market Dynamics
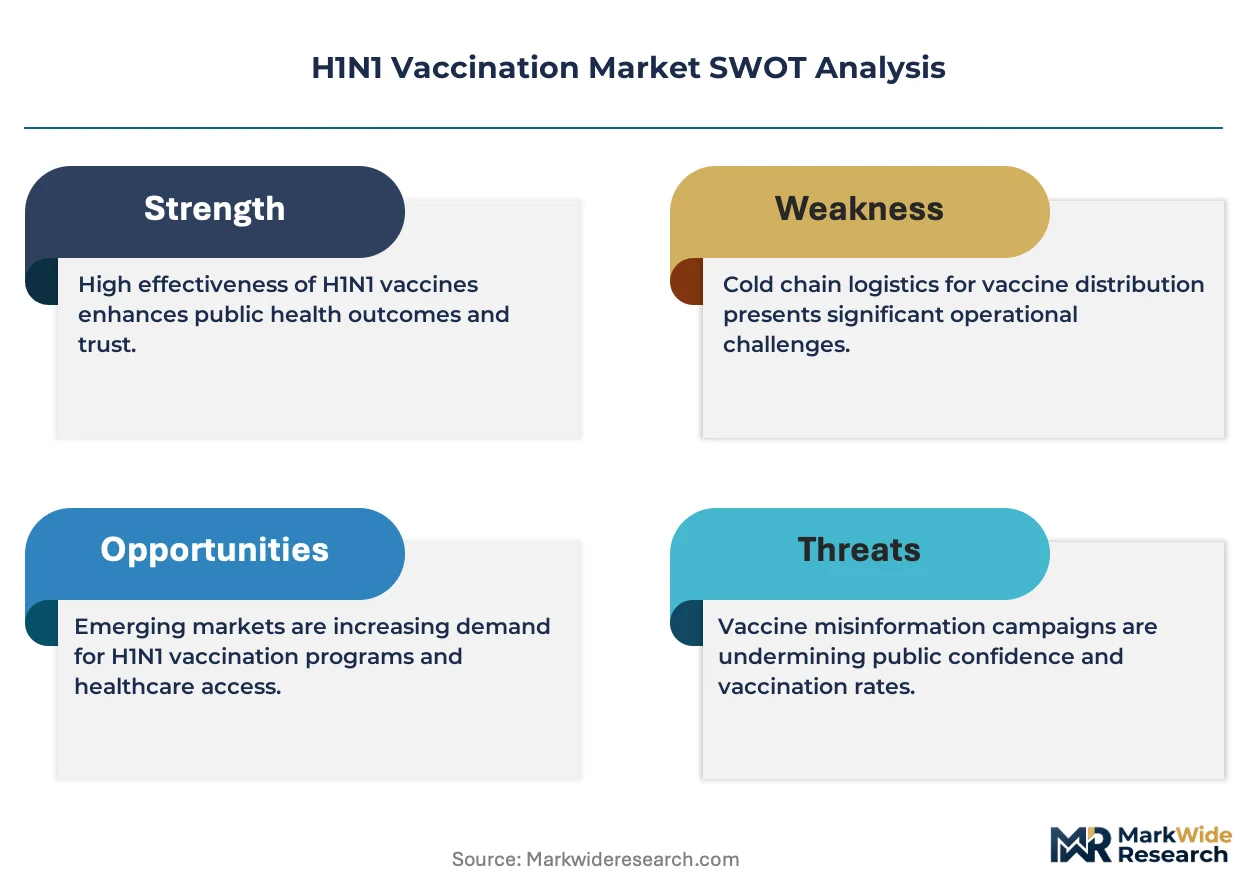
Adjuvanted formulation procurement by public health departments is compressing manufacturing lead times and reshaping competitive positioning around immunogenicity benchmarks rather than volume scale alone.
Growth Catalysts
- Strain-Change Acceleration Pathways:The FDA's streamlined approval mechanisms for pandemic strain updates reduce regulatory lag between surveillance detection and commercial release. Public health departments benefit from compressed deployment timelines during outbreak windows.
- Elderly Immunization Mandates:Seasonal program expansion in the United States broadens eligibility criteria to include younger adult cohorts. This demographic pull sustains baseline demand outside pandemic declaration periods.
- WHO Prequalification Standards:Harmonized manufacturing benchmarks enable multi-country tender participation by qualified suppliers. Emerging market access depends on this certification status for national procurement eligibility.
Market Restraints
- Egg-Based Input Dependency:High-yield embryonated egg supply concentrates in specialized agricultural regions. Avian influenza outbreaks in these zones threaten upstream antigen production continuity.
- Cold-Chain Infrastructure Gaps:Validated thermal packaging capacity remains concentrated among specialized distributors. Last-mile temperature excursions compromise dose integrity in resource-limited settings.
- Antigenic Drift Surveillance Burden:The Global Influenza Surveillance and Response System requires sustained coordination across 100+ national laboratories. Funding volatility strains real-time variant tracking precision.
Strategic Opportunities
- Cell-Culture Platform Adoption:Mammalian cell-based manufacturing reduces lead times from strain selection to commercial release. This technology convergence enables response acceleration during pandemic velocity.
- Pediatric Intranasal Formulations:Needle-free delivery modes address compliance barriers in school-based immunization programs. The United States and European member states represent underpenetrated channels for this administration route.
- Centralized National Tendering Systems:Multi-year procurement contracts with public health departments provide revenue visibility. Suppliers securing these agreements gain defensive positioning against spot-market competitors.
Industry Challenges
- Fill-Finish Capacity Bottlenecks:Aseptic manufacturing suites require capital-intensive qualification protocols. Facility expansion timelines extend 18-24 months, misaligning with pandemic surge requirements.
- Cross-Reactive Antibody Standardization:Immunogenicity assay harmonization across WHO, FDA, and EMA guidelines remains incomplete. Divergent correlates of protection complicate multi-regional trial design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | H1N1 Vaccination Market |
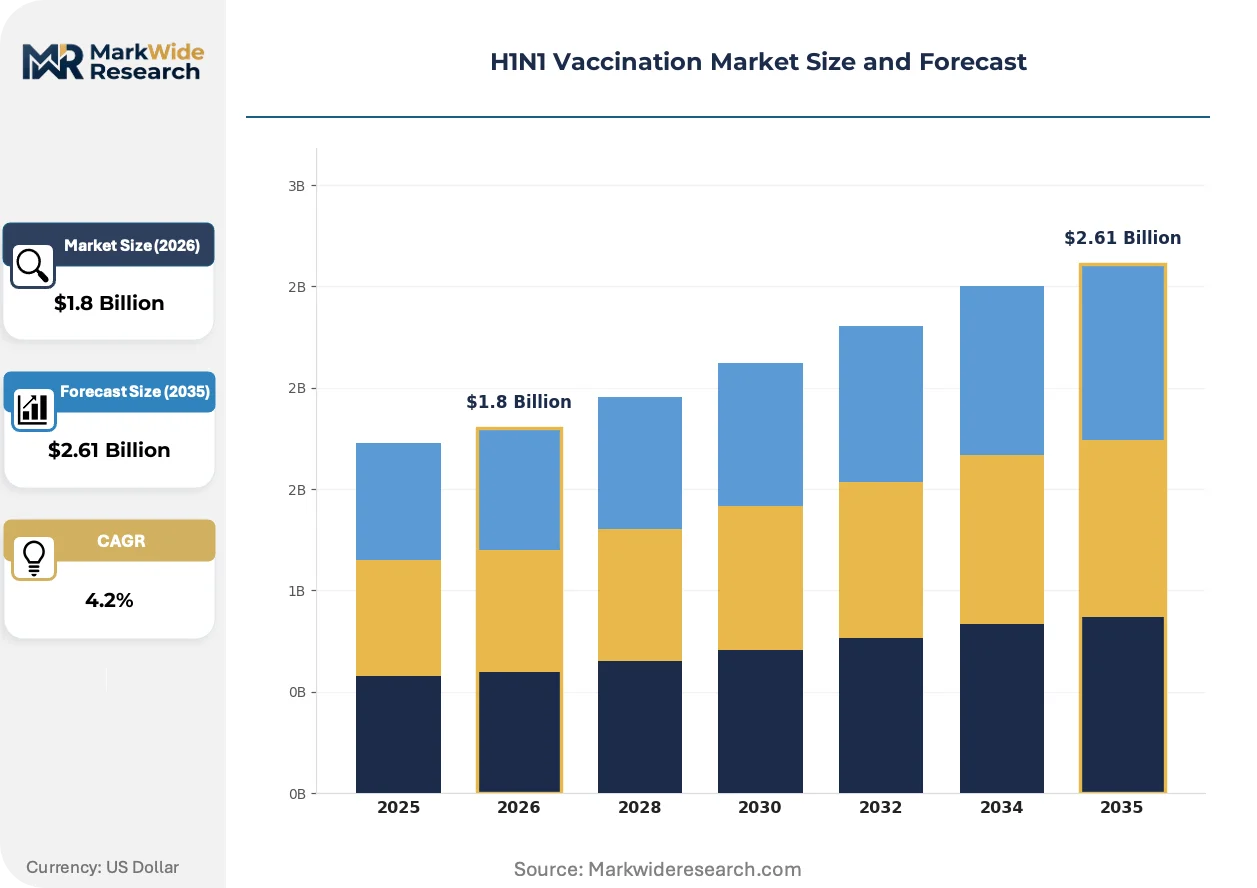
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccine, Live Attenuated Vaccine, Adjuvanted Vaccine, Cell-Based Vaccine Delivery Mode: Intramuscular Injection, Intranasal Spray, Subcutaneous Injection, Oral Administration End User: Hospitals, Clinics, Pharmacies, Public Health Departments Age Group: Children, Adolescents, Adults, Elderly |
| Companies Covered | Sanofi Pasteur, GlaxoSmithKline, Pfizer, AstraZeneca, Seqirus, Novartis, Serum Institute of India, Bharat Biotech, CSL Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
H1N1 Vaccination Market Shifts & Advancements
Manufacturing platforms are migrating from egg-based to cell-culture systems, while regulatory frameworks accelerate strain-update responsiveness. Distribution models simultaneously concentrate around specialized cold-chain operators capable of validated thermal performance.
Recombinant hemagglutinin antigen production is migrating from traditional embryonated egg incubation to insect cell-baculovirus expression systems. Protein Sciences Corporation pioneered this platform, and public health departments in the United States now specify cell-derived alternatives in tender documents. This migration from egg dependency is compressing the six-month strain-to-dose timeline toward four-month cycles, enabling closer alignment between vaccine composition and circulating variant match.
The FDA's Vaccines and Related Biological Products Advisory Committee has formalized accelerated strain-change review protocols following 2009 pandemic experience. Manufacturers submitting comparability protocols for updated hemagglutinin antigens receive expedited evaluation timelines versus original biologics license applications. Seasonal suppliers with established master cell banks and validated downstream processes capture disproportionate benefit from this regulatory architecture.
Public sector buyers are consolidating procurement through multi-year national tender awards rather than annual spot purchasing. The United States CDC and European Union joint procurement initiatives concentrate volume commitments among prequalified suppliers with demonstrated surge capacity. This behavioral shift rewards manufacturers with redundant production sites and penalizes single-facility operators unable to guarantee pandemic-scale supply commitments.
H1N1 Vaccination Market Segmentation
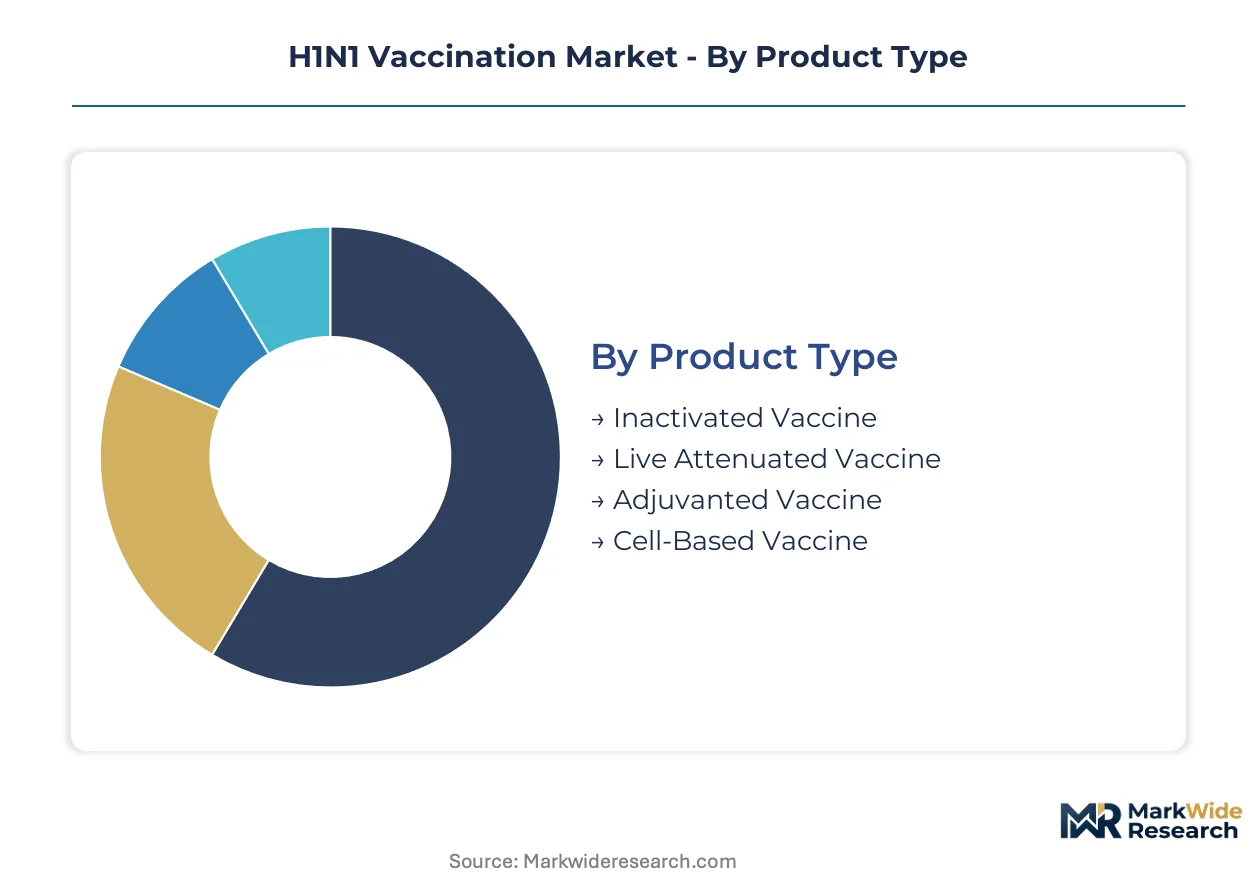
Product architecture in H1N1 vaccination spans four distinct immunological platforms, each commanding different manufacturing complexity and procurement economics. Delivery modality and end-user channel configurations further stratify competitive positioning across public and private procurement systems.
Product Type:
Cost tier differentiation separates commodity inactivated formulations from premium adjuvanted and cell-culture alternatives with compressed production timelines.
- Inactivated Vaccine:Split-virus or subunit formulations containing 15 micrograms hemagglutinin antigen per strain represent the volume baseline in seasonal programs. Procurement concentrates through CDC centralized tenders in the United States, where price sensitivity dominates multi-million dose awards.
- Adjuvanted Vaccine:Oil-in-water emulsion formulations with MF59 or AS03 enhance immunogenicity in elderly populations with attenuated immune responses. Demand is tilting toward public health departments in Europe and the United States as eligibility criteria broaden to immunocompromised cohorts.
- Live Attenuated Vaccine:Cold-adapted temperature-sensitive strains delivered intranasally target pediatric compliance advantages.
- Cell-Based Vaccine:Mammalian cell-culture production reduces egg supply dependency and accelerates strain-change responsiveness.
Inactivated vaccines hold installed capacity. Cell-based platforms are rotating up the share rankings.
Delivery Mode:
Application context determines route selection, with intramuscular administration dominating adult populations and alternative modes penetrating pediatric or needle-averse segments.
- Intramuscular Injection:Deltoid administration of inactivated formulations remains the clinical standard for adults and adolescents. Deployment concentrates in hospital outpatient departments and retail pharmacy chains across the United States, where throughput efficiency supports mass immunization campaigns.
- Intranasal Spray:Live attenuated cold-adapted strains deliver needle-free administration with improved pediatric acceptance. Demand is concentrating in school-based programs and European community health settings where compliance barriers suppress coverage rates.
- Subcutaneous Injection:Alternative route for specific adjuvanted formulations with modified immunogenicity profiles.
- Oral Administration:Experimental and limited commercial availability restricts current procurement relevance.
Intramuscular delivery holds installed capacity. Intranasal administration is rotating up the share rankings.
End User:
Customer type segmentation reflects procurement concentration patterns, with public sector buyers commanding volume leverage over fragmented private channels.
- Public Health Departments:National immunization programs and pandemic preparedness stockpiles represent the dominant procurement channel. Tender concentration in the United States, United Kingdom, and Germany rewards suppliers with WHO prequalification and demonstrated surge manufacturing capacity.
- Hospitals:Acute care facilities administer seasonal and post-exposure prophylaxis doses with immediate inventory requirements. Procurement runs through group purchasing organizations with consolidated contracting leverage.
- Clinics:Outpatient and community health centers serve underinsured populations with federal program reimbursement.
- Pharmacies:Retail chains capture convenience-driven seasonal demand with walk-in administration services.
Public health departments hold installed capacity. Pharmacy channels are rotating up the share rankings.
Age Group:
Maturity-based immunization policy drives demand allocation, with elderly mandates and pediatric expansion reshaping dose volume distribution.
- Elderly:Adults over 65 years receive priority allocation for adjuvanted high-dose formulations due to immunosenescence. United States Medicare reimbursement policies and European Union age-based recommendations concentrate procurement volume in this cohort.
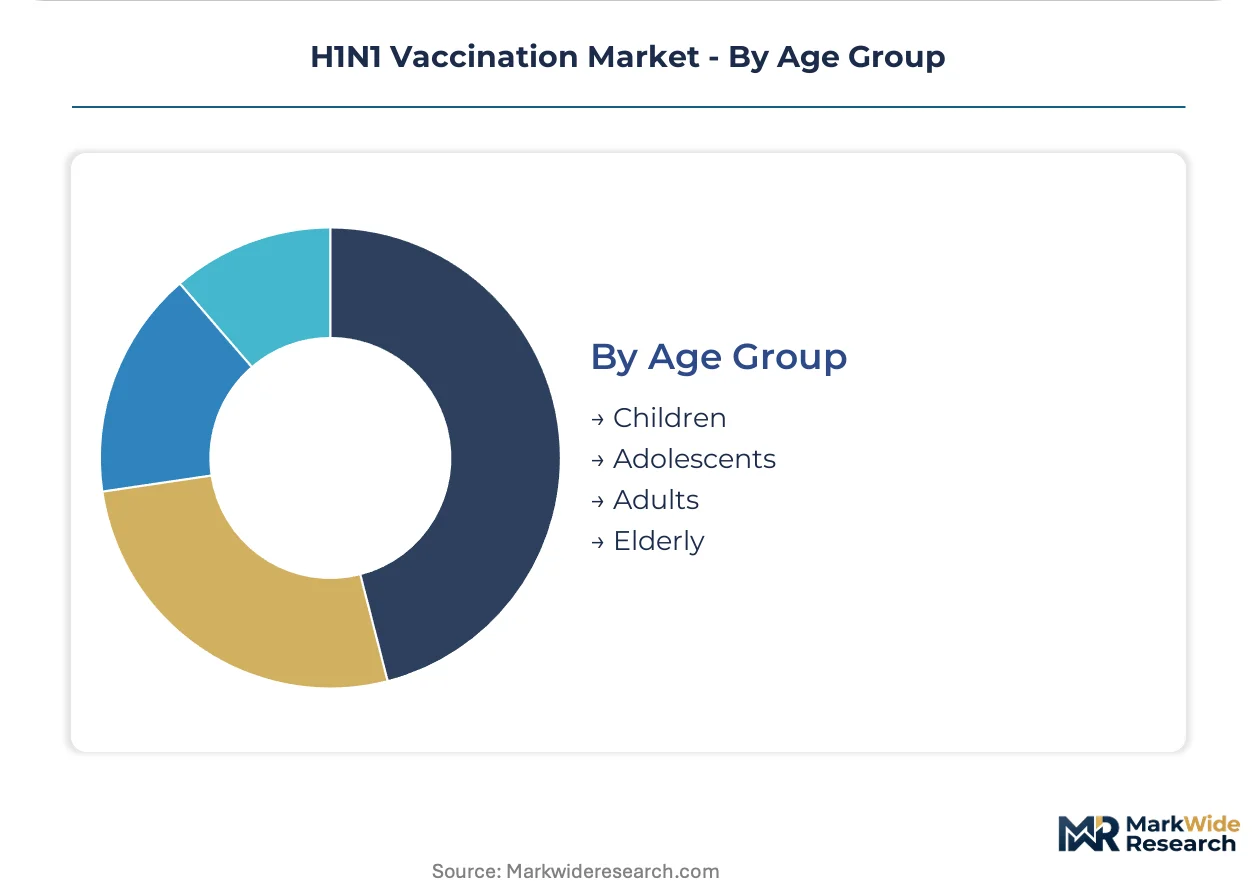
- Adults:Working-age populations 18-64 years represent the seasonal program expansion frontier as eligibility criteria broaden beyond traditional risk groups.
- Children:Pediatric formulations and school-based delivery programs target coverage gaps in routine immunization schedules.
- Adolescents:Transitional age group with mixed delivery through pediatric and adult care pathways.
Elderly immunization holds installed capacity. Adult expansion programs are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity through CDC centralized tenders, while Indian and Southeast Asian procurement systems exhibit acute sensitivity to per-dose costs in national immunization programs.
United States
Seasonal program expansion and pandemic stockpile mandates drive procurement volume through CDC centralized tenders. The FDA's Vaccines and Related Biological Products Advisory Committee streamlines strain-change approvals for rapid deployment. Manufacturing concentration clusters in North Carolina and Massachusetts, where fill-finish capacity supports surge requirements.
Germany
Elderly immunization mandates and adjuvanted formulation preference reshape tender specifications toward high-immunogenicity products. The EMA's Committee for Medicinal Products for Human Use harmonizes strain selections across member states. The Marburg region anchors production infrastructure for egg-based and cell-culture platforms serving European distribution networks.
India
Universal Immunization Program scale and WHO prequalification pursuit dominate procurement priorities for cost-optimized formulations. The CDSCO regulates manufacturing licenses and clinical trial approvals for domestic and export markets. Hyderabad and Pune concentrate bulk antigen production and formulation capabilities for emerging market supply.
United Kingdom
National tender consolidation and pandemic preparedness stockpiling sustain multi-year procurement commitments. The MHRA oversees seasonal strain updates and post-market surveillance requirements. Manufacturing activity concentrates in Liverpool and Oxfordshire, where fill-finish operations serve NHS distribution channels.
Japan
Pediatric intranasal formulation demand and elderly high-dose preferences segment procurement across delivery modes. The PMDA regulates seasonal composition changes through established master file procedures. Kanto region production sites supply domestic immunization programs and regional export markets.
H1N1 Vaccination Market Competitive Landscape
Capability concentration sits with cell-culture and recombinant platform specialists; scale advantage sits with egg-based incumbents with decades of installed capacity. The market structures around three tiers: multinational vaccine divisions with end-to-end cold-chain control, mid-scale regional suppliers with WHO prequalification status, and emerging platform technology firms. Dominant competitive moves include backward integration into antigen production and multi-year national tender capture.
Within the multinational tier, Sanofi Pasteur, GlaxoSmithKline, and Seqirus occupy positions defined by manufacturing platform differentiation. Sanofi Pasteur exemplifies egg-based scale advantages with continental distribution network control. GlaxoSmithKline represents adjuvanted formulation specialization serving elderly and immunocompromised segments. Seqirus anchors the cell-culture transition with mammalian platform capabilities that compress strain-to-dose timelines.
| Leading Market Players |
|---|
| Sanofi Pasteur |
| GlaxoSmithKline |
| Pfizer |
| AstraZeneca |
| Seqirus |
| Novartis |
| Serum Institute of India |
| Bharat Biotech |
| CSL Limited |
| Others |
Supply & Pricing Matrix
Hyderabad and Pune concentrate bulk antigen production and formulation capabilities for emerging market supply, with their capacity utilization rates directly shaping downstream pricing power for public health tenders in India, Southeast Asia, and Africa. CDC centralized tenders in the United States command premium positioning through volume commitments and surge requirements, while WHO prequalification status determines eligibility for multi-country procurement at standard-tier rates.
Pricing Analysis
Long-term offtake contracts with public health departments anchor pricing stability, with multi-year national tenders rewarding suppliers with demonstrated manufacturing scale and cold-chain validation. Three-tier pricing structure across premium adjuvanted formulations, standard inactivated doses, and economy egg-based alternatives reflects immunogenicity benchmarks and production complexity. Cost compression in economy tiers intensifies as Indian and Southeast Asian manufacturers expand WHO prequalified capacity. Public health departments in emerging markets exhibit acute price sensitivity, while United States CDC tenders demonstrate the lowest elasticity through mandated stockpile and seasonal program commitments.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from specialized distributors with validated thermal packaging capabilities are reshaping working capital structures for manufacturers without captive cold-chain networks. Antigen production concentrates in the United States, Germany, and India, with fill-finish operations clustering in North Carolina, Massachusetts, Marburg, Liverpool, and Hyderabad. Embryonated egg supply draws from specialized agricultural regions in the United States and Europe, while mammalian cell-culture media and recombinant protein expression systems rest on bioreactor equipment and serum suppliers. Single-source vulnerability in egg-based input channels threatens production continuity during avian influenza outbreaks. Distribution runs through public health department centralized tenders, hospital group purchasing organizations, and retail pharmacy chains with regional cold-chain partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-culture platform adoption represents a high-growth disruption, with FDA accelerated strain-change approval pathways compressing regulatory lag and enabling pandemic-responsive manufacturing timelines that reshape competitive economics.
For Market Incumbents: Harden surge manufacturing capacity through redundant production sites and validated master cell banks that guarantee pandemic-scale supply commitments under CDC tender specifications. Secure backward integration into bioreactor equipment and specialized cold-chain distribution to defend margin position against spot-market competitors during strain-update windows. Cell-culture platform specialists threaten egg-based volume advantages through compressed lead times. For New Entrants and Emerging Players: Build out pediatric intranasal formulation capabilities for school-based immunization programs in the United States and European member states, where needle-free delivery modes remain underpenetrated relative to intramuscular standards. Target pharmacy retail channels with convenience-driven seasonal demand and walk-in administration services. Pursue WHO prequalification status as the essential gateway to emerging market national tender participation. For Investors and Strategic Acquirers: Long-term, this sits as a pandemic-preparedness infrastructure play because regulatory acceleration mechanisms and public health stockpile mandates create defensive revenue visibility independent of seasonal variability. Acquisition targets should prioritize cell-culture platform specialists with validated downstream processes and established master cell banks. The signal to watch is FDA strain-change approval velocity and WHO prequalification queue depth as indicators of manufacturing responsiveness premium.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Culture Platform Scale-Up | Mammalian cell-based manufacturing reduces strain-to-dose timelines from six months toward four months. |
| Multi-Year National Tender Capture | CDC and European Union joint procurement initiatives concentrate volume among prequalified suppliers with surge capacity. |
| Adjuvanted Formulation Specialization | MF59 and AS03 oil-in-water emulsions command premium positioning for elderly and immunocompromised populations. |
| Cold-Chain Distribution Integration | End-to-end refrigerated network control defends dose integrity through last-mile validated thermal packaging. |
| Pediatric Intranasal Development | Live attenuated cold-adapted strains address compliance barriers in school-based immunization programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA strain-change approval filings, EMA Committee for Medicinal Products for Human Use decisions, WHO prequalification assessments, and CDC tender documentation to establish baseline market sizing. Primary interviews engaged vaccine development executives at multinational manufacturers, regulatory affairs leads navigating accelerated approval pathways, public health procurement managers overseeing national immunization programs, and cold-chain logistics specialists managing validated thermal distribution. Bottom-up dose volume estimates by product type, delivery mode, and end-user channel triangulate against top-down public health expenditure data and manufacturer revenue disclosures.
Forecast inputs include antigenic drift surveillance patterns from the Global Influenza Surveillance and Response System, regulatory acceleration mechanism adoption rates, cell-culture platform capacity expansion timelines, and public health department procurement behavior shifts across the analysis window. Segmentation modeling spans product type, delivery mode, end user, and age group dimensions with regional regulatory cluster differentiation. CAGRs derive from dose volume projections calibrated to immunization program expansion criteria and pandemic preparedness stockpile mandates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cell-culture platform specialists or recombinant antigen technology firms would shift outcomes beyond modeled parameters. Antigenic drift velocity exceeding surveillance system tracking precision, avian influenza disruptions to egg-based supply chains, or regulatory harmonization failures between FDA, EMA, and WHO guidelines would prompt revision. Macroeconomic constraints on public health budgets, emerging market procurement system reforms, or novel platform technology breakthroughs represent additional deviation scenarios requiring forecast update.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Global Onychomycosis Treatment Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
India Over-The-Counter Drugs (OTC) Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Mitotane Market