
 Asia-Pacific Fatty Bases for Suppositories Market | 2026-2036
Asia-Pacific Fatty Bases for Suppositories Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fatty Bases for Suppositories Market Analytics
Market Context
Modular formulation kits that pair fatty bases with active pharmaceutical ingredients are pivoting how regional buyers configure procurement contracts. Bliss GVS Pharma Ltd. leverages backward integration into cocoa butter refining to control input quality across its suppository lines. Sun Pharmaceutical Industries anchors its fatty base sourcing through captive hydrogenated oil processing in western India. Takeda Pharmaceutical competes on JIS-compliant excipient documentation that streamlines access to Japanese hospital formularies.
Technical Definition and Segment Structure
Asia-Pacific fatty bases for suppositories comprise lipid excipients—primarily cocoa butter, hydrogenated vegetable oils, and palm oil derivatives—formulated to melt at body temperature for rectal or vaginal drug delivery, with hydroxyl value and iodine specifications determining compatibility with active compounds. Cocoa butter maintains dominant share among product types due to its established pharmacopeial acceptance and broad compatibility, though hydrogenated oils represent the fastest-expanding category as Indian and Chinese manufacturers seek lower-cost alternatives with tighter melting point ranges. Hospital procurement channels capture the deepest margin pools because institutional buyers negotiate multi-year supply agreements with excipient qualification requirements that lock out unvalidated suppliers.
Regulatory Framework
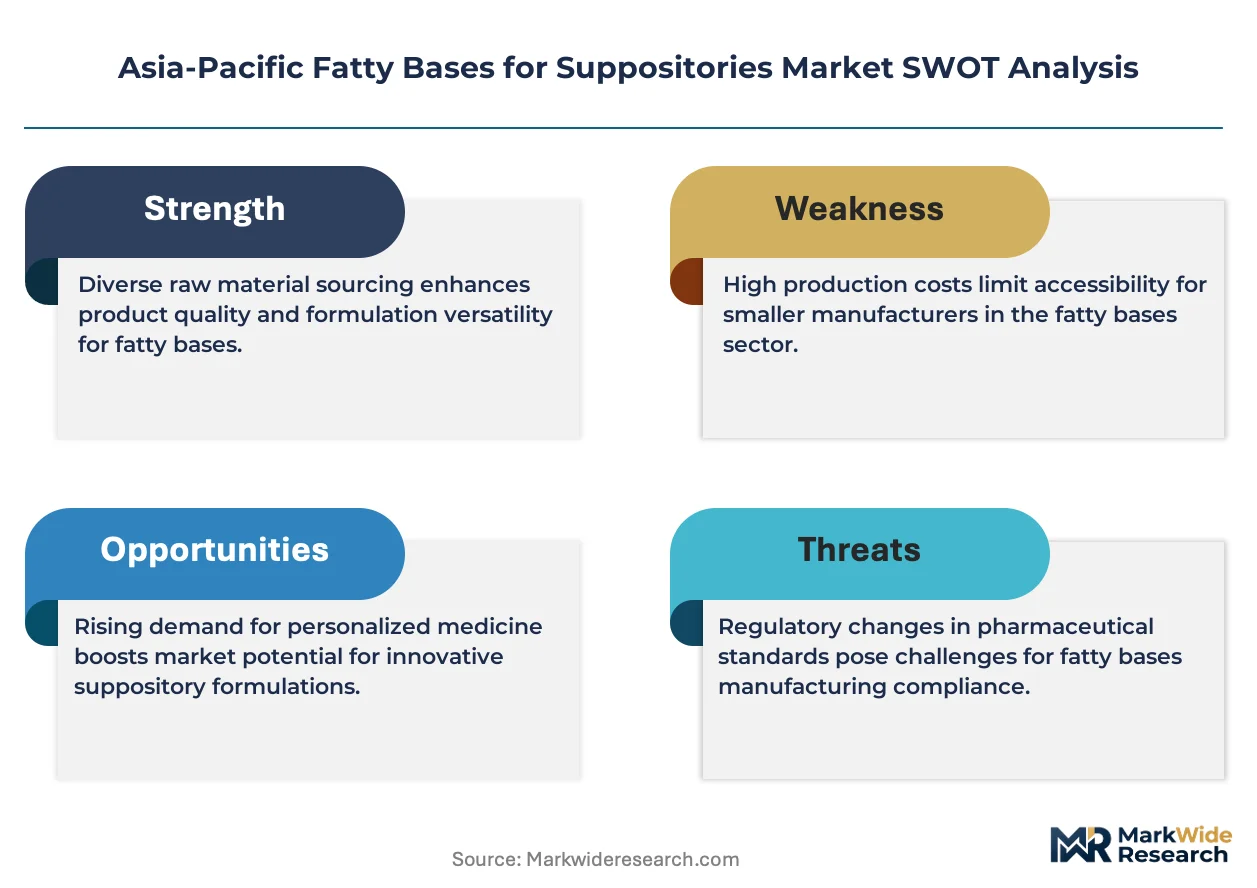
India's CDSCO mandates excipient drug master filing for all imported fatty bases, while China's NMPA enforces GB standard compliance for hydrogenated oils used in pharmaceutical applications, and Japan's PMDA requires foreign manufacturers to register as designated marketing authorization holders. These frameworks elevate compliance costs for new entrants but protect incumbent suppliers with established regulatory dossiers. Stakeholders must monitor evolving pharmacopeial harmonization between ICH member states, as divergence in heavy metal limits and peroxide value thresholds could force dual qualification strategies.
Market Dynamics
CDSCO and NMPA excipient purity mandates are compressing supplier qualification timelines while hydrogenated oil alternatives gain formulation share across Indian and Chinese contract manufacturing facilities.
Growth Catalysts
- India's PLI scheme for pharmaceuticals:Domestic suppository production incentives are accelerating fatty base qualification programs at Mumbai-Pune corridor facilities.
- Rectal drug delivery expansion:Pediatric and geriatric formulations are widening addressable indications beyond traditional analgesic applications.
- GB standard harmonization:China's NMPA alignment with ICH Q3D guidelines is reducing dual-testing burdens for hydrogenated oil imports.
Market Restraints
- Cocoa butter price volatility:West African supply disruptions transmit directly to Asia-Pacific formulation costs given limited regional cultivation.
- Supplier concentration in western India:Three refining clusters control over sixty percent of hydrogenated oil base capacity, creating single-source vulnerability.
- Melting point range limitations:Hydrogenated alternatives narrow thermal windows complicate active ingredient compatibility with heat-sensitive compounds.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing:Greenfield suppository facilities in Binh Duong province seek qualified fatty base suppliers outside established Indian channels.
- Modular excipient kits:Pre-blended base-active ingredient combinations are opening contract formulation partnerships with mid-tier domestic marketers.
- Japan PMDA foreign manufacturer registration:Early dossier submission creates preferred supplier status for hospital formulary access.
Industry Challenges
- Excipient master file compilation:CDSCO's drug master file requirements demand twelve-to-eighteen month preparation cycles for new market entrants.
- Peroxide value control:Oxidative stability testing infrastructure gaps at regional analytical laboratories extend release timelines.
- Cross-functional technical staffing:Formulation chemists with lipid excipient specialization command premium compensation in competitive labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fatty Bases for Suppositories Market |
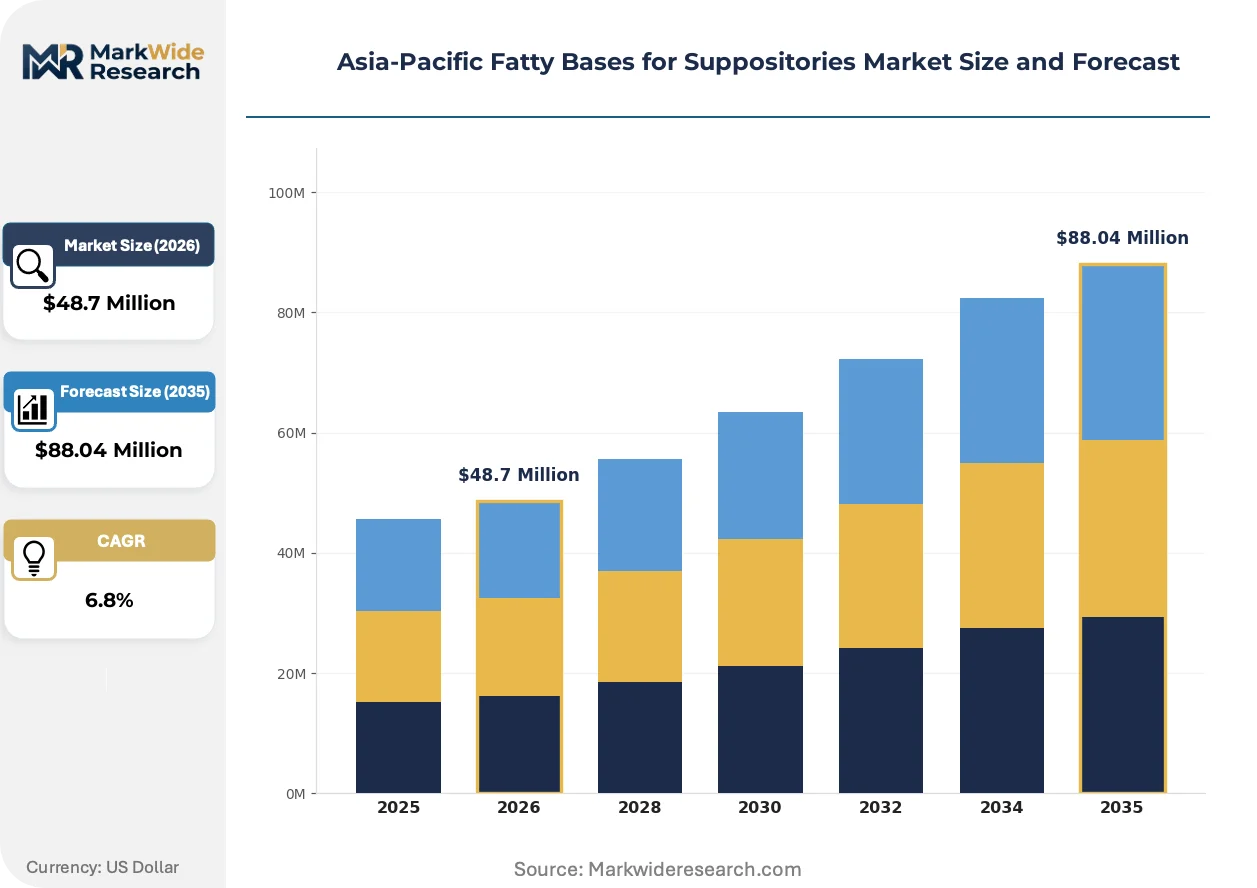
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Butter, Glycerin Oleate, Hydrogenated Oils, Palm Oil Form: Suppositories, Pessaries, Enemas, Inserts End User: Pharmacies, Hospitals, Clinics, Home Care Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Bliss GVS Pharma Ltd., Priyans Drugs, Sun Pharmaceutical Industries, Cipla, Takeda Pharmaceutical, Cadila Healthcare Limited, Glenmark Pharmaceuticals Limited, Intas Pharmaceuticals Limited, Aenova Holding GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fatty Bases for Suppositories Market Evolving Landscape
Formulation technology convergence with precision thermal profiling is compressing development cycles while regulatory documentation standardization reshapes competitive qualification barriers across the region.
Controlled-release suppository matrices incorporating hydrogenated palm oil fractions with defined polymorphic stability are rewriting rectal drug delivery pharmacokinetics. Regional contract manufacturers in Gujarat and Jiangsu province are adopting these bases for anti-emetic and anti-pyretic lines. The technology is rewriting competitive positioning by enabling bioequivalence claims that accelerate generic approvals.
Japan's PMDA foreign manufacturer registration system now requires on-site inspections for designated marketing authorization holders supplying hospital channels. This industrial consequence elevates compliance infrastructure investment for excipient refiners seeking Japanese market access. Hydrogenated oil suppliers with existing JIS documentation are responding by prioritizing PMDA dossier completion over secondary market expansion.
Hospital procurement consolidation through regional purchasing cooperatives is compressing supplier qualification cycles and unbundling technical service from base material pricing. Western India's institutional buyers now negotiate multi-year framework agreements with embedded excipient validation requirements. This pattern concentrates most visibly in Maharashtra's public health system tendering, where three purchasing blocks dominate suppository contract awards.
Asia-Pacific Fatty Bases for Suppositories Market Segmentation
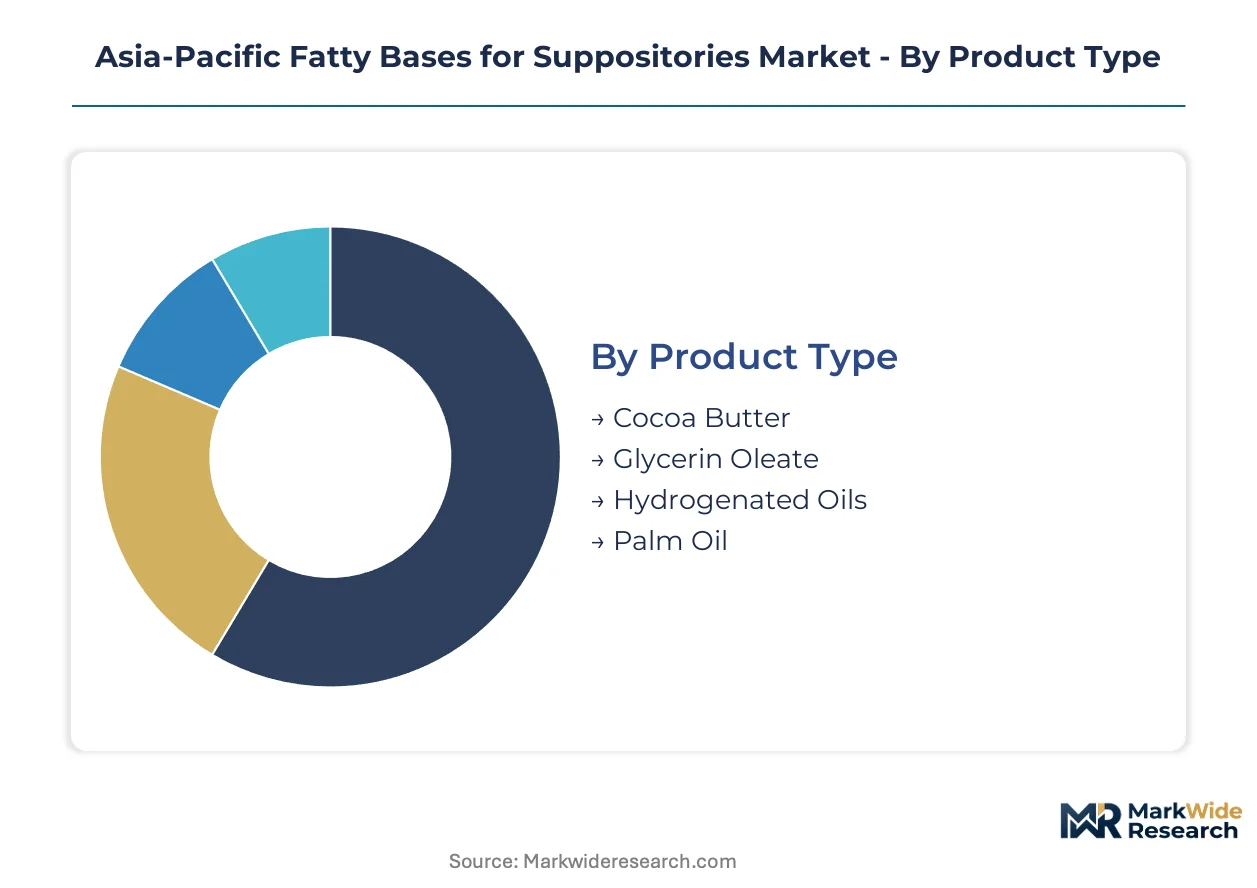
Fatty base selection dictates regulatory pathway complexity across Asia-Pacific suppository manufacturing. Each segment carries distinct pharmacopeial burdens that shape supplier qualification timelines and procurement contract structures.
Product Type:
CDSCO drug master filing requirements vary sharply by lipid chemistry, with natural triglycerides facing stricter heavy metal documentation than hydrogenated alternatives. NMPA GB standard compliance thresholds for peroxide values and iodine numbers create tiered validation costs across the four product categories.
- Cocoa Butter:Natural theobroma oil with defined polymorphic crystallization behavior requiring precise tempering protocols. Demand clusters in Maharashtra's Mumbai-Pune corridor where export-oriented contract manufacturers serve European pharmacopeial markets. CDSCO mandates excipient drug master filing for all imported lots, extending qualification cycles.
- Hydrogenated Oils:Catalytically hardened vegetable fats with tunable melting point ranges between 32-37°C. Chinese manufacturers in Jiangsu province favor these bases for cost-sensitive domestic anti-pyretic lines. NMPA enforces GB standard compliance with tightening peroxide value thresholds under ICH Q3D alignment.
- Glycerin Oleate:Mono- and di-ester blends with emulsifying properties for water-soluble active compatibility.
- Palm Oil:Fractionated palm stearin with high oxidative stability but variable supply chain sustainability credentials.
Leading the category by volume: Cocoa Butter. Growing fastest: Hydrogenated Oils.
Form:
Rectal and vaginal delivery geometries impose distinct mechanical specifications on base selection, with mold-release properties and structural integrity during storage driving formulation decisions across manufacturing scales.
- Suppositories:Torpedo-shaped rectal inserts requiring bases with sharp melting profiles near 37°C. Indian hospital procurement channels specify cocoa butter or hydrogenated oil bases with documented bioequivalence data for generic analgesic formulations. PMDA foreign manufacturer registration requirements elevate documentation burdens for Japanese institutional supply.
- Pessaries:Vaginal inserts demanding superior structural integrity at ambient temperatures. Manufacturing concentrates in Gujarat's pharmaceutical cluster where contract producers serve both domestic Ayurvedic markets and regulated export destinations.
- Enemas:Liquid rectal preparations with emulsion stability requirements.
- Inserts:Solid vaginal or urethral delivery systems with extended-release matrix compatibility.
Suppositories dominate institutional procurement volumes. Pessaries expand most quickly as women's health formulations gain regional regulatory attention.
End User:
Channel-specific purchasing power and technical validation requirements fragment demand patterns, with hospital systems extracting stringent excipient qualification commitments that smaller channels cannot enforce.
- Hospitals:Institutional buyers negotiating multi-year framework agreements with embedded supplier audit rights. Maharashtra's public health purchasing blocks and Japan's hospital formularies lock in validated excipient sources through designation requirements. CDSCO master file documentation and PMDA foreign manufacturer registration serve as non-negotiable entry credentials.
- Pharmacies:Retail dispensaries stocking over-the-counter analgesic and anti-emetic suppositories with less stringent provenance documentation.
- Clinics:Outpatient facilities purchasing smaller lot sizes with flexible base specifications.
- Home Care:Direct-to-patient channels for chronic disease management applications.
Hospitals command premium pricing through qualification-intensive supply contracts. Home Care channels expand most rapidly as geriatric self-administration protocols proliferate.
Distribution Channel:
Channel economics determine technical service bundling and inventory risk allocation, with direct sales relationships capturing formulation development partnerships that wholesale intermediaries cannot replicate.
- Direct Sales:Manufacturer-to-formulator relationships enabling collaborative melting point optimization and polymorphic stability testing. Western India's refining clusters leverage captive hydrogenated oil production to offer integrated technical support. These partnerships lock in multi-year supply commitments with price-volume escalation clauses.
- Wholesale:Bulk distributors serving mid-tier pharmaceutical manufacturers with standardized base specifications.
- Retail:Pharmacy-facing channels for finished suppository products rather than excipient materials.
- Online:Digital procurement platforms emerging for small-batch specialty base sourcing.
Direct Sales captures margin concentration through technical integration. Online channels gain share fastest as digital procurement penetrates mid-tier Vietnamese and Indonesian manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and China manufacture the majority of fatty base volumes consumed across Asia-Pacific, while Japan and Australia depend on imports for hospital-grade excipient supply. This production-consumption divide shapes regulatory diplomacy and cross-border qualification timelines.
India
Maharashtra's Mumbai-Pune corridor hosts the densest concentration of hydrogenated oil refining capacity serving domestic and export suppository manufacturers. CDSCO's excipient drug master filing mandate compresses supplier entry timelines to twelve-to-eighteen months. Gujarat's pharmaceutical cluster specializes in pessary contract production for Ayurvedic and regulated export markets.
China
Jiangsu province manufacturers favor hydrogenated vegetable oil bases for cost-sensitive domestic anti-pyretic formulations. NMPA's GB standard alignment with ICH Q3D guidelines reduces dual-testing burdens for qualified imports. The Yangtze River Delta region concentrates polymorphic stability research facilities serving controlled-release matrix development.
Japan
PMDA's foreign manufacturer registration system requires on-site inspections for excipient suppliers seeking hospital formulary access. Kanto region purchasing cooperatives negotiate multi-year framework agreements with embedded validation requirements. Domestic formulators prioritize JIS-compliant documentation for rectal drug delivery lines.
Vietnam
Binh Duong province greenfield pharmaceutical facilities seek qualified fatty base suppliers outside established Indian channels. The country's national pharmaceutical regulator tightens excipient import documentation for hospital procurement. Ho Chi Minh City-based contract manufacturers scale suppository output for ASEAN export markets.
Australia
TGA's pharmacopeial standards for lipid excipients demand peroxide value documentation that extends release timelines for Asian imports. Melbourne and Sydney hospital systems source through regional purchasing cooperatives with strict supplier audit protocols. Domestic formulation capacity remains limited, preserving import dependence for specialized bases.
Asia-Pacific Fatty Bases for Suppositories Market Competitive Landscape
The competitive structure tilts toward vertically integrated pharmaceutical conglomerates with captive excipient processing capabilities. Three refining clusters in western India control over sixty percent of hydrogenated oil base capacity, creating supply-side concentration. Strategic archetypes include backward-integrated domestic formulators, multinational excipient specialists with regulatory dossier depth, and regional contract manufacturers scaling modular formulation services. Dominant competitive moves encompass captive hydrogenated oil processing investments and PMDA foreign manufacturer registration pursuit for Japanese hospital access.
Within the integrated domestic formulator tier, Bliss GVS Pharma Ltd. and Sun Pharmaceutical Industries exemplify backward integration into base material control. Takeda Pharmaceutical occupies a position representing multinational regulatory documentation capabilities. These three anchors illustrate how geographic origin and corporate structure map to competitive positioning: Mumbai-based Bliss GVS Pharma Ltd. and Sun Pharmaceutical Industries leverage proximity to western India's refining infrastructure, while Takeda Pharmaceutical's Japanese registration status opens institutional channels requiring PMDA compliance.
| Leading Market Players |
|---|
| Bliss GVS Pharma Ltd. |
| Priyans Drugs |
| Sun Pharmaceutical Industries |
| Cipla |
| Takeda Pharmaceutical |
| Cadila Healthcare Limited |
| Glenmark Pharmaceuticals Limited |
| Intas Pharmaceuticals Limited |
| Aenova Holding GmbH |
| Others |
Value Network & Pricing Analysis
Formulation chemists with lipid excipient specialization cluster in western India's Mumbai-Pune corridor, and their premium compensation spreads widen the gap between hospital-grade certified bases and economy-tier alternatives. CDSCO's twelve-to-eighteen month drug master file cycles lock in qualified suppliers, compressing price competition at the top tier while hydrogenated oil alternatives absorb cost-sensitive volume.
Pricing Analysis
Margin tightening in economy-tier hydrogenated oils reflects Jiangsu province manufacturers racing to undercut cocoa butter on domestic anti-pyretic contracts. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-registered Japanese hospital supply from CDSCO-filed Indian institutional channels and unvalidated wholesale lots. Price differentiation rests on certification depth: JIS-compliant documentation commands 40-60% spreads over GB-standard alternatives. CDSCO and NMPA purity mandates are accelerating cost-down pressure as reformulation expenses pass through base pricing. Hospital procurement blocks in Maharashtra and Kanto show lowest price sensitivity due to multi-year framework lock-ins; mid-tier Vietnamese contract manufacturers exhibit highest elasticity, switching between Indian and Chinese supply monthly.
Supply Chain Analysis
Return flows of out-of-specification fatty bases for re-refining and peroxide value remediation concentrate in Gujarat's pharmaceutical cluster, where captive processing recovers pharmaceutical-grade material. Geographic supply concentration centers on India, China, and Malaysia: western India's three refining clusters control over sixty percent of hydrogenated oil capacity, Jiangsu province anchors Chinese hydrogenated vegetable oil output, and Malaysian palm oil fractionation feeds regional stearin supply. Raw material dependencies draw from West African cocoa butter, Indonesian and Malaysian crude palm oil, and Indian soybean oil for hydrogenation feedstock. Single-source vulnerability in western India's refining corridor threatens continuity for CDSCO-registered supply. Distribution runs through direct manufacturer-to-formulator relationships for hospital-grade material, with wholesale intermediaries handling economy-tier spot volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refining capacity with active CDSCO drug master files is the binding constraint propping pricing power for qualified suppliers. New hydrogenated oil investments face eighteen-month qualification timelines, preserving margin pools for incumbents with validated dossiers.
For Market Incumbents: Hedge against cocoa butter price volatility by securing multi-year offtake agreements with Malaysian palm oil fractionators and accelerating backward integration into hydrogenated oil processing. CDSCO's tightening heavy metal documentation for natural triglycerides threatens to disqualify unvalidated cocoa butter imports, making captive hydrogenated oil production the priority defensive lever. PMDA foreign manufacturer registration pursuit secures Japanese hospital formulary access against regional competitors. For New Entrants and Emerging Players: Precision thermal profiling technology for controlled-release matrix development offers entry into Vietnam's Binh Duong greenfield facilities, where qualified fatty base supply remains undersupplied relative to ASEAN export ambitions. Modular excipient kits pairing pre-blended bases with active ingredients penetrate fastest among mid-tier Indian domestic marketers lacking in-house formulation chemistry. Go-to-market positioning should anchor on collaborative melting point optimization services that incumbent wholesalers cannot replicate. For Investors and Strategic Acquirers: Re-rating potential sits with hydrogenated oil refiners holding dual CDSCO and NMPA dossiers given ICH Q3D harmonization accelerating cross-border qualification. Five-to-ten year viability favors upstream-integrated assets over pure-play distributors facing hospital procurement consolidation. Watch NMPA's peroxide value threshold tightening as the inflection signal: sub-scale refiners lacking oxidative stability testing infrastructure will face forced exit, concentrating share among compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Foreign Manufacturer Registration | Unlocks Japanese hospital formulary access for hydrogenated oil suppliers with JIS documentation. |
| Backward Integration into Hydrogenated Oil Processing | Captures margin pools and insulates against cocoa butter volatility in western India's refining corridor. |
| Modular Excipient Kit Development | Opens contract formulation partnerships with mid-tier Vietnamese and Indonesian domestic marketers. |
| Controlled-Release Matrix Qualification | Enables bioequivalence claims that accelerate generic approvals for anti-emetic and anti-pyretic lines. |
| Regional Purchasing Cooperative Alignment | Secures multi-year framework agreements with embedded supplier audit rights in Maharashtra's public health system. |
Research Methodology
CDSCO regulatory filings, NMPA GB standard documentation, and Indian pharmaceutical customs records formed the secondary backbone, cross-referenced against primary interviews with excipient qualification managers, hospital procurement directors, and contract manufacturing executives. Bottom-up triangulation aggregated hydrogenated oil refinery capacity across western India's three clusters, while top-down validation checked against API manufacturer excipient purchasing patterns. Primary fieldwork with Maharashtra's public health purchasing blocks and Kanto region hospital cooperatives grounded institutional channel dynamics.
Historical trendline analysis of fatty base import volumes and qualification timelines established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type chemistry, end-user channel structure, and regional regulatory cluster as primary dimensions. CAGRs derived from weighted average of capacity expansion announcements, hospital procurement tender awards, and excipient master file submission rates. Forecast inputs included CDSCO drug master file approval velocity and NMPA ICH Q3D alignment implementation pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained West African cocoa butter supply disruption or abrupt NMPA peroxide value threshold revision. Forecasts reflect assumptions on CDSCO inspectorate capacity and Malaysian palm oil fractionation expansion timelines. Practitioners should monitor CDSCO master file queue lengths and Vietnamese pharmaceutical FDI announcements for early signals of qualification bottleneck easing or demand surge.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Plasma-Derived Protein Therapies Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
South Africa Diabetes Drugs Market
Pharmaceuticals
Rosuvastatin Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
India Pharmaceutical Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
Global Vaccine Contract Manufacturing Market
Pharmaceuticals
Telmisartan Market