
 South Korea Diabetes Drugs Market | 2026-2036
South Korea Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Diabetes Drugs Market Analytics
Hospital-centric prescribing for advanced biologics is collapsing as home care and pharmacy channels capture a rising share of chronic diabetes management. Novo Nordisk A/S anchors its position through deep specialization in GLP-1 receptor agonist formulations. Hanmi Pharmaceutical competes via differentiated fixed-dose combination therapies targeting the domestic Type 2 population. Eli Lilly and Company extends its reach through sustained investment in automated delivery device ecosystems.
South Korea diabetes drugs comprise pharmaceutical agents engineered to regulate blood glucose through insulin modulation, incretin pathway activation, or renal glucose reabsorption inhibition, with formulations requiring precise bioavailability parameters and cold-chain stability. These therapeutics serve to prevent microvascular complications, reduce cardiovascular risk, and maintain glycemic control across progressive disease stages. GLP-1 agonists and SGLT2 inhibitors command expanding prescriber preference due to demonstrated cardioprotective outcomes beyond glucose lowering. Insulin retains structural volume leadership despite margin compression from biosimilar entry led by Samsung Bioepis. DPP-4 inhibitors occupy a mature position where generic substitution pressures reimbursement rates.
MFDS operates parallel review tracks for innovative diabetes therapies while enforcing bioequivalence standards on domestically manufactured generics. The national health insurance system administered by HIRA shapes demand through positive list negotiations that favor cost-effective oral agents in first-line protocols. MFDS Good Manufacturing Practice inspections and pharmacovigilance reporting requirements determine which foreign manufacturers maintain active market registrations. Stakeholders must monitor reimbursement threshold adjustments for combination therapies and the evolving biosimilar interchangeability stance.
Market Dynamics
MFDS accelerated approval pathways for novel biologics are compressing commercialization timelines while hospital procurement concentrates GLP-1 agonist volumes in Seoul's tertiary networks, creating a bifurcated market structure between institutional and retail channels.
Growth Catalysts
- MFDS Accelerated Review Pathways:Parallel track evaluations for innovative diabetes therapies reduce time-to-market for novel biologics, incentivizing domestic and foreign manufacturers to prioritize South Korean regulatory submissions.
- Metabolic Disease Protocol Expansion:Broader hospital adoption of cardioprotective prescribing guidelines for Type 2 diabetes elevates demand for GLP-1 receptor agonists and SGLT2 inhibitors beyond glucose control endpoints.
- Seoul Tertiary Network Concentration:Affiliated specialty clinics and university hospitals generate concentrated prescriber influence that rapidly disseminates protocol changes across the national healthcare system.
Market Restraints
- Cold-Chain Distribution Costs:Biologic formulations requiring precise temperature maintenance impose elevated logistics expenditures that compress margins for pharmacy channel expansion beyond hospital settings.
- HIRA Reimbursement Compression:National health insurance positive list negotiations favor cost-effective oral agents in first-line protocols, constraining premium pricing for advanced injectable therapies.
- Biosimilar Interchangeability Uncertainty:Evolving MFDS stance on automatic substitution for insulin biosimilars creates prescriber hesitation and formulary access friction for originator manufacturers.
Strategic Opportunities
- Home Care Channel Penetration:Automated delivery device ecosystems enable patient self-administration outside hospital settings, opening pharmacy and direct-to-patient distribution models previously dominated by institutional procurement.
- Fixed-Dose Combination Development:Domestic manufacturers can leverage differentiated dual-mechanism formulations targeting the South Korean Type 2 population's specific metabolic profiles and comorbidity patterns.
- Pharmacovigilance Data Monetization:MFDS mandatory adverse event reporting requirements generate real-world evidence repositories that manufacturers can deploy for label expansion and differentiated reimbursement negotiations.
Industry Challenges
- Bioequivalence Testing Capacity Bottlenecks:MFDS Good Manufacturing Practice inspection backlogs and limited certified analytical laboratory availability delay generic and biosimilar market entry timelines.
- Specialized Formulation Talent Scarcity:Protein stabilization and sustained-release engineering expertise concentrates among a small cohort of domestic biotech specialists, constraining pipeline expansion for mid-cap developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Diabetes Drugs Market |
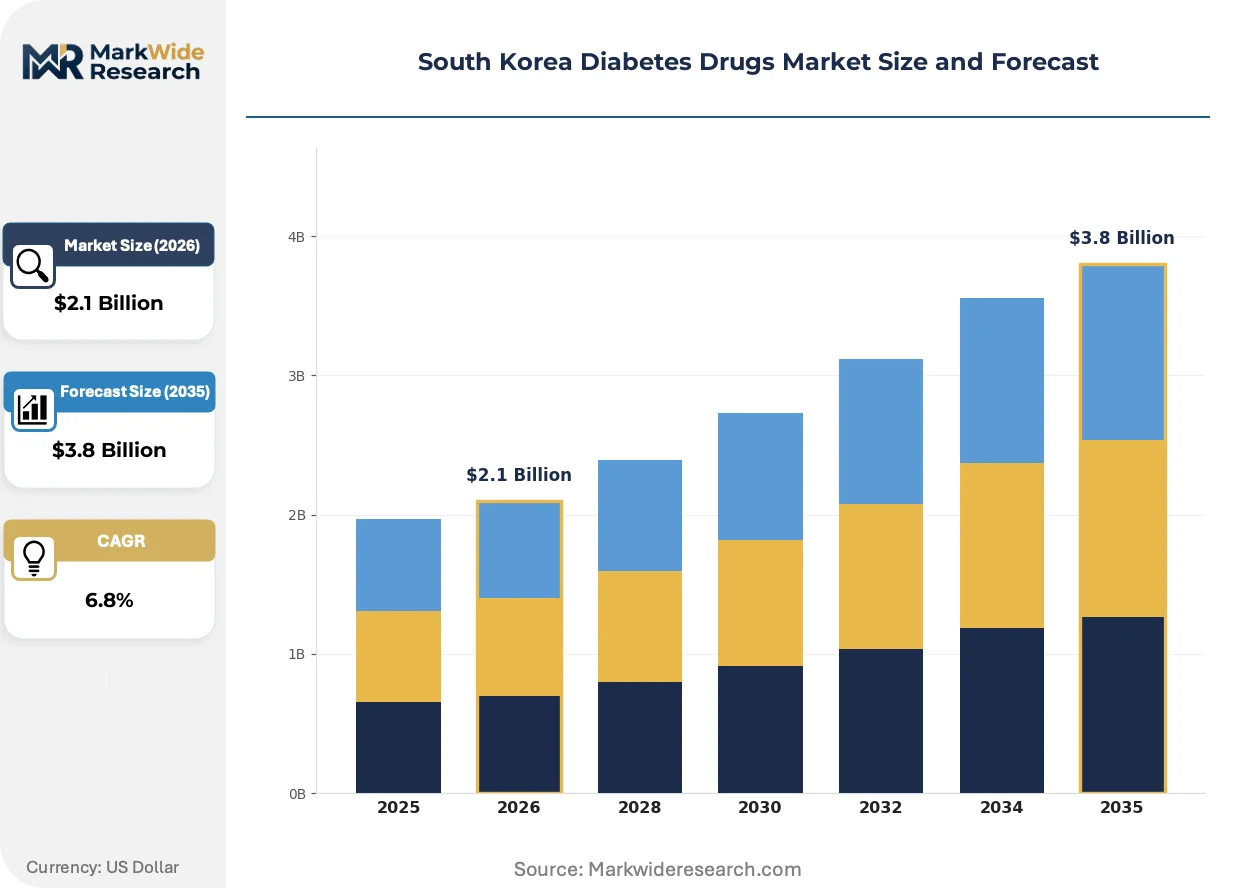
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes Delivery Mode: Subcutaneous Injection, Oral Tablets, Inhalation, Continuous Infusion End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Eli Lilly and Company, Novo Nordisk A/S, Sanofi, Merck & Co., Hanmi Pharmaceutical, AstraZeneca, Boehringer Ingelheim, Takeda, Samsung Bioepis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Diabetes Drugs Market Evolving Landscape
GLP-1 receptor agonist innovation is reconfiguring prescriber hierarchies in South Korea, with device-integrated delivery systems and real-world evidence generation emerging as the primary axes of competitive differentiation beyond molecular efficacy alone.
Smart pen injectors with dose-tracking connectivity are displacing conventional vial-and-syringe administration in South Korean hospital outpatient departments. Endocrinology clinics at Samsung Medical Center and Asan Medical Center have adopted Bluetooth-enabled devices that synchronize dosing data with electronic health records. This connectivity infrastructure is displacing manual glycemic diaries and enabling outcome-based reimbursement pilots with HIRA.
MFDS pharmacovigilance reporting requirements for novel biologics now mandate real-world safety data collection extending through post-market surveillance phases. This regulatory architecture elevates domestic clinical research organization capabilities and creates compliance barriers for foreign manufacturers lacking Korean-language adverse event processing infrastructure. Multinational sponsors are responding by establishing captive pharmacovigilance operations in Seoul rather than relying on regional hubs.
Hospital-centric chronic disease management is fragmenting as pharmacy-based diabetes counseling services expand under revised scope-of-practice regulations. Community pharmacists in Busan and Daegu metropolitan areas now administer injection training and glucose monitoring education previously restricted to hospital diabetes educators. This channel disintermediation is most visible in the Gyeongsang provinces where specialist physician density remains below Seoul levels.
South Korea Diabetes Drugs Market Segmentation
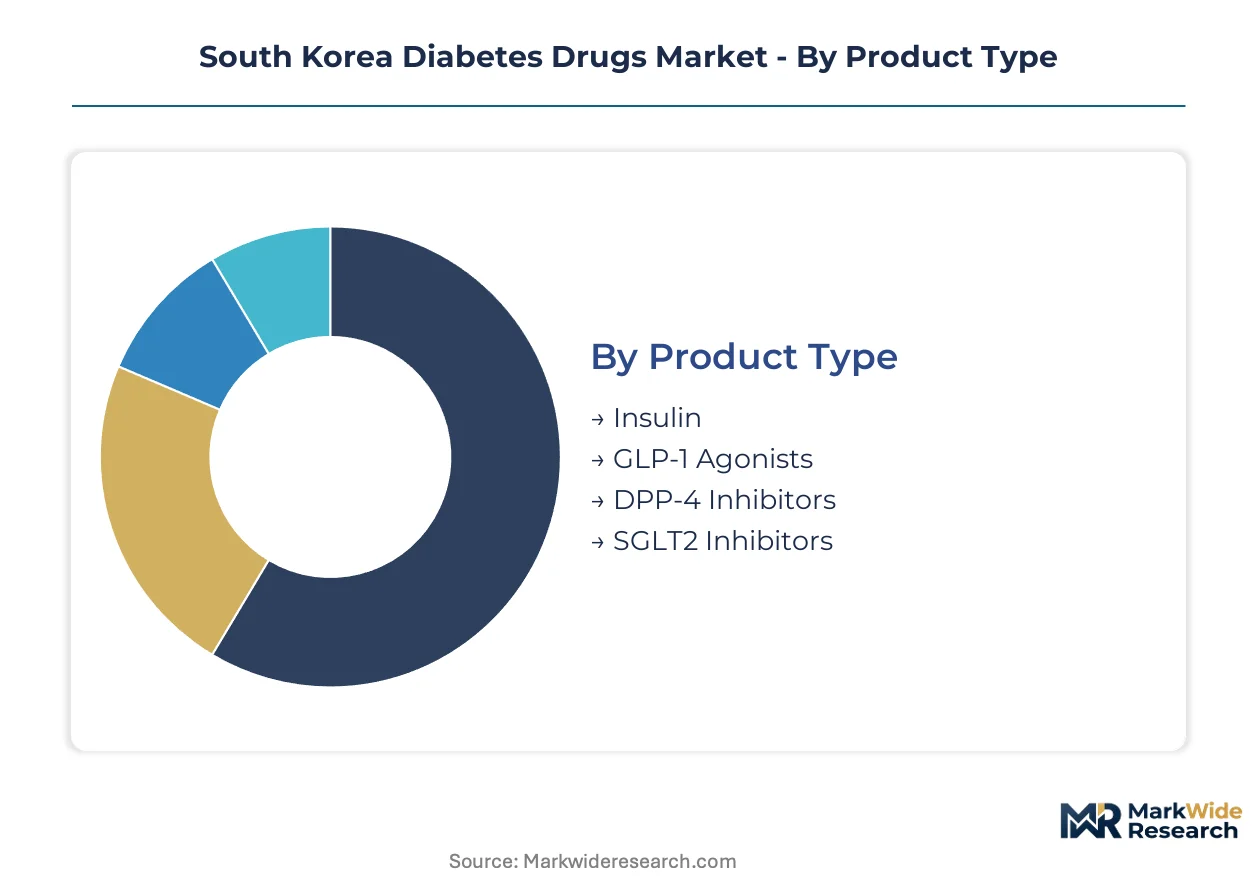
South Korea's diabetes drug segmentation reveals how MFDS reimbursement tiers and HIRA pricing protocols fragment commercial opportunity across molecular classes and care settings. Understanding margin concentration by product type and delivery channel determines effective market entry sequencing for domestic and multinational manufacturers.
Product Type:
GLP-1 agonists and SGLT2 inhibitors command premium reimbursement positioning due to demonstrated cardiovascular outcome benefits, while insulin faces biosimilar-driven margin compression and oral agents confront generic substitution pressures.
- Insulin:Biosynthetic and analog formulations requiring cold-chain stability serve as foundational therapy for Type 1 patients and advanced Type 2 cases. Seoul's tertiary hospital networks anchor procurement volumes, though Samsung Bioepis biosimilar entry is compressing originator pricing power through HIRA interchangeability pilots.
- GLP-1 Agonists:Peptide-based incretin mimetics with weekly or daily dosing profiles demonstrate superior HbA1c reduction and weight loss outcomes. Asan Medical Center and Samsung Medical Center endocrinology departments are expanding GLP-1 protocols beyond glycemic control to cardiovascular risk management, driving hospital formulary adoption.
- DPP-4 Inhibitors:Oral gliptins with favorable hypoglycemia profiles occupy mature market positioning where domestic generic manufacturers have eroded branded margins through MFDS bioequivalence certifications.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 blockers with renal protective indications are gaining HIRA positive list inclusion for diabetic nephropathy patients, expanding prescriber preference beyond endocrinology into nephrology departments.
Insulin holds installed capacity across South Korea's hospital networks. SGLT2 inhibitors are rotating up the share rankings through expanded cardioprotective labeling.
Therapy Area:
Type 2 diabetes generates overwhelming prescription volume due to South Korea's aging demographic and metabolic syndrome prevalence, while Type 1 and gestational segments offer concentrated but smaller addressable populations.
- Type 2 Diabetes:Progressive insulin resistance and beta-cell dysfunction affecting middle-aged and elderly populations drives pharmaceutical consumption across all drug classes. Gyeongsang province community health centers are expanding oral agent dispensing as first-line protocols per HIRA cost-effectiveness guidelines.
- Type 1 Diabetes:Autoimmune beta-cell destruction requiring exogenous insulin replacement represents a structurally smaller but therapy-intensive segment. Pediatric endocrinology units at Seoul National University Hospital maintain concentrated prescriber influence for novel rapid-acting analogs.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring short-term glycemic management with insulin or metformin. Obstetrics departments at Cheil Hospital and CHA Medical Center generate protocol-setting demand for pregnancy-safe formulations.
- Prediabetes:Impaired glucose tolerance not yet meeting diabetes diagnostic thresholds, addressed primarily through lifestyle intervention with limited pharmaceutical penetration pending progression.
Type 2 diabetes holds installed capacity across South Korea's reimbursement system. Prediabetes is climbing the fastest as screening protocols expand through national health checkup programs.
Delivery Mode:
Subcutaneous injection retains structural volume leadership for biologics, though oral tablet convenience drives prescriber preference where molecular characteristics permit, and device-integrated delivery systems are capturing premium positioning.
- Subcutaneous Injection:Parenteral administration of insulin and GLP-1 agonists via pen devices or syringes dominates biologic delivery. Bluetooth-enabled smart pens with dose-logging capabilities are displacing conventional devices at Asan Medical Center outpatient clinics.
- Oral Tablets:Small-molecule formulations including metformin, DPP-4 inhibitors, and SGLT2 blockers offer patient convenience and pharmacy channel accessibility. Busan metropolitan area community pharmacies have expanded oral agent counseling services under revised scope-of-practice regulations.
- Inhalation:Pulmonary insulin delivery systems with limited commercial presence face MFDS respiratory safety scrutiny and HIRA reimbursement exclusion, constraining adoption despite non-invasive administration benefits.
- Continuous Infusion:Insulin pump therapy with automated glucose-responsive dosing serves intensive management populations. Daegu tertiary centers are piloting closed-loop systems for pediatric Type 1 patients through regional insurance waivers.
Subcutaneous injection holds installed capacity across South Korea's diabetes care infrastructure. Continuous infusion is gaining share fastest through automated delivery ecosystem investments.
End User:
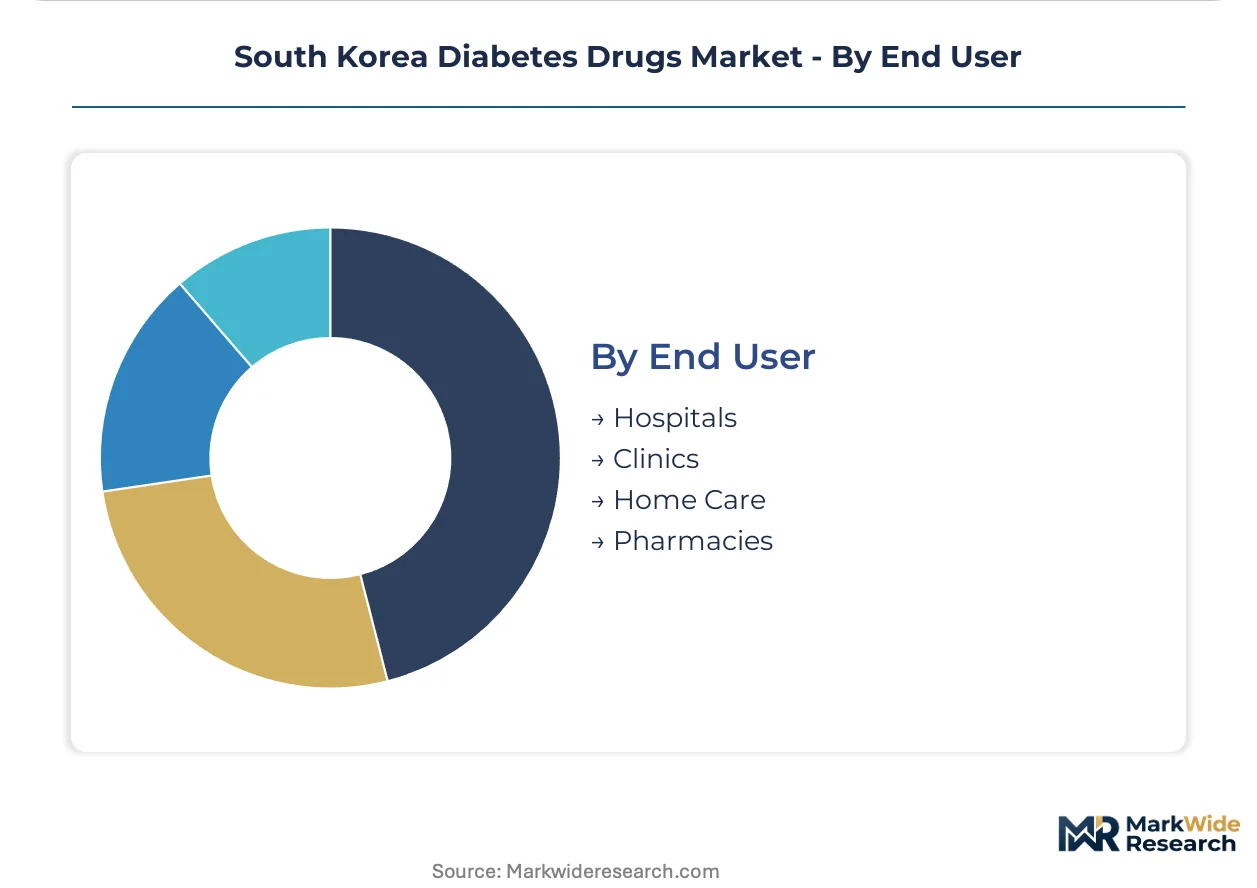
Hospital procurement concentrates advanced biologic volumes through Seoul's university-affiliated networks, while pharmacy and home care channels are capturing rising share of chronic oral therapy management.
- Hospitals:Tertiary and secondary acute care institutions with endocrinology departments generate concentrated demand for injectable biologics and inpatient glycemic control protocols. Samsung Medical Center, Asan Medical Center, and Seoul National University Hospital anchor national prescribing patterns.
- Clinics:Private specialty endocrinology practices and primary care settings manage stable Type 2 populations with oral agents and basal insulin. Gangnam district clinics demonstrate highest per-capita GLP-1 prescribing rates due to affluent patient demographics.
- Home Care:Patient self-administration with nursing support enables chronic disease management outside institutional settings. Home nursing agencies in Gyeonggi province are expanding injection training services for elderly patients with limited mobility.
- Pharmacies:Community retail dispensaries with expanded clinical service scopes now administer diabetes education and glucose monitoring training. Daegu and Busan pharmacy associations have led scope-of-practice expansion advocacy with regional health authorities.
Hospitals hold installed capacity across South Korea's biologic procurement system. Pharmacies are rotating up the share rankings through chronic disease management service expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul-Incheon port complex anchors South Korea's pharmaceutical import infrastructure, with cold-chain logistics corridors extending to Busan and Daegu enabling biologic distribution across the peninsula.
Seoul Capital Area
Asan Medical Center and Samsung Medical Center drive GLP-1 agonist procurement volumes through expanded metabolic disease protocols. MFDS headquarters in Cheongju coordinates accelerated approval pathways for novel biologics submitted by manufacturers targeting this cluster. Gangnam district specialty clinics concentrate affluent patient populations seeking advanced injectable therapies.
Busan-Ulsan
Community pharmacy networks in Busan metropolitan area have expanded diabetes counseling services under revised scope-of-practice regulations. HIRA regional offices administer positive list negotiations that favor cost-effective oral agents for stable Type 2 populations. Ulsan industrial biotech parks host analytical laboratories supporting bioequivalence testing for domestic generic manufacturers.
Daegu-Gyeongbuk
Tertiary centers in Daegu pilot closed-loop insulin pump systems for pediatric Type 1 patients through regional insurance waivers. MFDS Good Manufacturing Practice inspections determine which foreign manufacturers maintain active registrations for distribution into this corridor. Home nursing agencies expand injection training services for elderly patients with limited mobility across Gyeongbuk province.
Daejeon-Sejong
Sejong administrative city houses HIRA central operations shaping national reimbursement thresholds for combination therapies. Daejeon-based clinical research organizations process pharmacovigilance reports mandated for novel biologic post-market surveillance. Regional health authorities coordinate screening protocol expansion through national health checkup programs.
Gwangju-Honam
Specialist physician density remains below Seoul levels, accelerating pharmacy-based diabetes education adoption. Community health centers in Jeolla provinces expand oral agent dispensing as first-line protocols per HIRA cost-effectiveness guidelines. Regional pharmaceutical distributors maintain cold-chain warehousing for biologic formulations serving scattered rural populations.
South Korea Diabetes Drugs Market Competitive Landscape
Listed multinational leaders compete with private domestic specialists across device-integrated delivery ecosystems and fixed-dose combination formulations. The market structure concentrates volume among three strategic archetypes: global biologic innovators with deep GLP-1 specialization, domestic manufacturers leveraging combination chemistry expertise, and biosimilar specialists compressing insulin pricing through interchangeable alternatives. Competitive moves center on automated delivery device licensing and pharmacovigilance data partnerships with Seoul-based clinical research organizations.
Within the multinational innovator tier, Eli Lilly and Company and Novo Nordisk A/S occupy positions exemplifying deep GLP-1 receptor agonist specialization. Hanmi Pharmaceutical represents the domestic archetype, with differentiated fixed-dose combination therapies targeting South Korea's Type 2 population metabolic profiles. Samsung Bioepis anchors the biosimilar specialist category, with insulin interchangeability pilots through HIRA creating pricing pressure on originator manufacturers.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Novo Nordisk A/S |
| Sanofi |
| Merck & Co. |
| Hanmi Pharmaceutical |
| AstraZeneca |
| Boehringer Ingelheim |
| Takeda |
| Samsung Bioepis |
| Others |
Value Network & Pricing Analysis
Ninety-day cold-chain inventory buffers at Seoul-Incheon pharmaceutical hubs determine margin allocation between hospital procurement and pharmacy channel expansion, with biologic temperature sensitivity concentrating pricing power among distributors maintaining MFDS-certified logistics infrastructure.
Pricing Analysis
Volume-discount tiering separates originator biologics from biosimilar alternatives and domestic generics across HIRA reimbursement negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects cardiovascular outcome certification, MFDS bioequivalence status, and cold-chain service bundling. Cost compression in the biosimilar tier is intensifying because Samsung Bioepis insulin interchangeability pilots erode originator pricing power. Community pharmacies serving Gyeongsang province stable Type 2 populations exhibit highest price sensitivity, while Seoul tertiary hospital networks maintain lowest sensitivity due to protocol-driven prescribing.
Supply Chain Analysis
Incheon Port cold-chain chokepoints underwrite biologic distribution economics for GLP-1 agonists requiring precise temperature maintenance from manufacturer to patient. Active pharmaceutical ingredient production draws from China, India, and Switzerland, with peptide synthesis and bioreactor capacity concentrated among contract manufacturers in those geographies. Single-source vulnerability sits with specialized insulin analog fermentation facilities in Denmark and France. Distribution runs through Seoul's tertiary hospital networks for injectable biologics, while oral agents disperse via Busan and Daegu pharmacy wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's diabetes drugs market functions as a service-attach opportunity where automated delivery device ecosystems and pharmacovigilance data partnerships expand faster than molecular formulation sales alone.
For Market Incumbents: Secure captive pharmacovigilance operations in Seoul rather than regional hub dependency, as MFDS mandatory Korean-language adverse event processing creates compliance barriers for foreign manufacturers lacking local infrastructure. Anchor hospital formulary position through Bluetooth-enabled smart pen connectivity pilots at Asan Medical Center and Samsung Medical Center, defending against pharmacy channel disintermediation. For New Entrants and Emerging Players: Differentiate on fixed-dose combination chemistry targeting South Korean Type 2 metabolic profiles, exploiting Hanmi Pharmaceutical's demonstrated pathway for domestic regulatory prioritization. Penetrate Busan and Daegu pharmacy networks where scope-of-practice expansion has created diabetes counseling service attach points previously restricted to hospital educators. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management infrastructure play because HIRA outcome-based reimbursement pilots and MFDS real-world evidence mandates elevate data platform value above molecule exclusivity windows. Target clinical research organizations with established Seoul pharmacovigilance capabilities and hospital system data partnerships. Monitor MFDS biosimilar interchangeability rulings as the signal for insulin originator margin compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Delivery Device Ecosystem | Bluetooth-enabled smart pens with EHR synchronization displace conventional administration at Samsung Medical Center outpatient clinics. |
| Captive Pharmacovigilance Operation | Seoul-based adverse event processing infrastructure satisfies MFDS Korean-language reporting mandates for novel biologics. |
| Fixed-Dose Combination Development | Dual-mechanism formulations targeting domestic Type 2 metabolic profiles leverage Hanmi Pharmaceutical's regulatory prioritization pathway. |
| Pharmacy Channel Service Expansion | Busan and Daegu community pharmacies administer injection training previously restricted to hospital diabetes educators. |
| Hospital System Data Partnership | Real-world evidence repositories from Asan Medical Center connectivity pilots support HIRA reimbursement negotiations. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors provided ongoing calibration across primary interviews combined with secondary validation from MFDS filings, HIRA reimbursement databases, ClinicalTrials.gov entries, and hospital procurement records. Bottom-up patient population modeling and top-down pharmaceutical spending analysis triangulated market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include molecular class, therapy line, administration route, delivery device integration level, and regional regulatory cluster. CAGRs derived from patient population epidemiology, protocol adoption curves, and reimbursement access evolution. Forecast inputs incorporated HIRA positive list negotiation timelines and MFDS accelerated approval pathway utilization rates.
Material uncertainties — MFDS biosimilar interchangeability rulings, HIRA combination therapy reimbursement thresholds, cold-chain logistics cost trajectories — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as these regulatory and infrastructure conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Etomidate Market