
 Atrial Fibrillation Stroke Treatment Market | 2026-2036
Atrial Fibrillation Stroke Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Atrial Fibrillation Stroke Treatment Market Analytics
Bioresorbable polymer coatings are replacing permanent synthetic polymers in implantable left atrial appendage closure devices, and this material transition is restructuring device economics by reducing long-term implant complications and follow-up costs. Boston Scientific Corporation leverages its integrated electrophysiology portfolio to anchor catheter ablation device supply chains across North American hospital networks. Medtronic plc sustains R&D intensity in cryoballoon ablation platforms that compete on procedural efficiency versus radiofrequency alternatives. Johnson & Johnson differentiates through its biosense webster mapping systems that dominate 3D cardiac imaging workflows in high-volume ablation centers.
Atrial fibrillation stroke treatment encompasses pharmacological and interventional therapies designed to prevent thromboembolic events in patients with non-valvular atrial fibrillation, including vitamin K antagonists, direct oral anticoagulants targeting factor Xa or thrombin, and percutaneous or surgical left atrial appendage exclusion devices typically deployed via transseptal catheter access under fluoroscopic and echocardiographic guidance. Anticoagulants remain the largest product type segment due to established oral administration protocols and broad guideline endorsement, though implantable devices represent the fastest-growing category as eligible patient populations expand beyond warfarin-intolerant candidates. Transcatheter delivery mode adoption accelerates as ambulatory surgery centers build electrophysiology capacity, while hospital end users retain the dominant share of high-complexity surgical procedures.
FDA premarket approval requirements and EMA medical device regulation conformity assessments shape product development timelines and market access conditions for implantable devices across the United States and European Union. The Centers for Medicare & Medicaid Services national coverage determinations directly influence reimbursement-driven demand for catheter ablation and left atrial appendage closure procedures in American healthcare systems. Stakeholders must monitor evolving anticoagulation reversal agent availability and health technology assessment body valuations as these factors determine clinical substitution patterns between pharmaceutical and device-based stroke prevention strategies.
Market Dynamics
The transition from permanent polymer coatings to bioresorbable alternatives in left atrial appendage closure devices is compressing long-term complication rates and restructuring follow-up economics across implantable stroke prevention portfolios.
Growth Catalysts
- FDA Breakthrough Device Designations:Accelerated regulatory pathways for novel oral anticoagulants reduce time-to-market for factor Xa and direct thrombin inhibitors, compressing development cycles for pharmaceutical stroke prevention candidates.
- Ambulatory Surgery Center Expansion:Transcatheter delivery mode adoption accelerates as electrophysiology capacity builds in outpatient settings, extending procedural access beyond traditional hospital infrastructure.
- Germany's Aging Demographics:Established electrophysiology infrastructure in German hospital networks supports procedure volume expansion for catheter ablation and appendage closure interventions.
Market Restraints
- CMS National Coverage Determination Uncertainty:Reimbursement-driven demand for left atrial appendage closure procedures remains contingent on Medicare coverage decisions, creating access volatility for American healthcare systems.
- Anticoagulation Reversal Agent Availability:Limited commercial supply of specific reversal agents for direct oral anticoagulants constrains clinical confidence in pharmaceutical stroke prevention protocols.
- Transseptal Access Technical Complexity:Fluoroscopic and echocardiographic guidance requirements for device deployment restrict eligible operator pools and procedural scalability.
Strategic Opportunities
- Japan's Underpenetrated Device Segment:Aging population dynamics and expanding electrophysiology infrastructure create whitespace for transcatheter left atrial appendage closure adoption beyond warfarin-intolerant candidates.
- EMA Priority Medicine Status:Regulatory tailwinds for novel therapeutic candidates accelerate European market access timelines, creating competitive positioning advantages for early entrants.
- Integrated Mapping-Ablation Workflows:Convergence of 3D cardiac imaging systems with cryoballoon and radiofrequency platforms enables procedure time compression and throughput expansion in high-volume centers.
Industry Challenges
- Electrophysiology Specialist Training Bottlenecks:Procedural complexity for transseptal catheter access and device deployment outpaces fellowship program output, constraining operator supply expansion.
- Health Technology Assessment Timeline Compression:European reimbursement bodies demand extended real-world evidence for device-based stroke prevention, elongating commercialization pathways despite regulatory clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atrial Fibrillation Stroke Treatment Market |
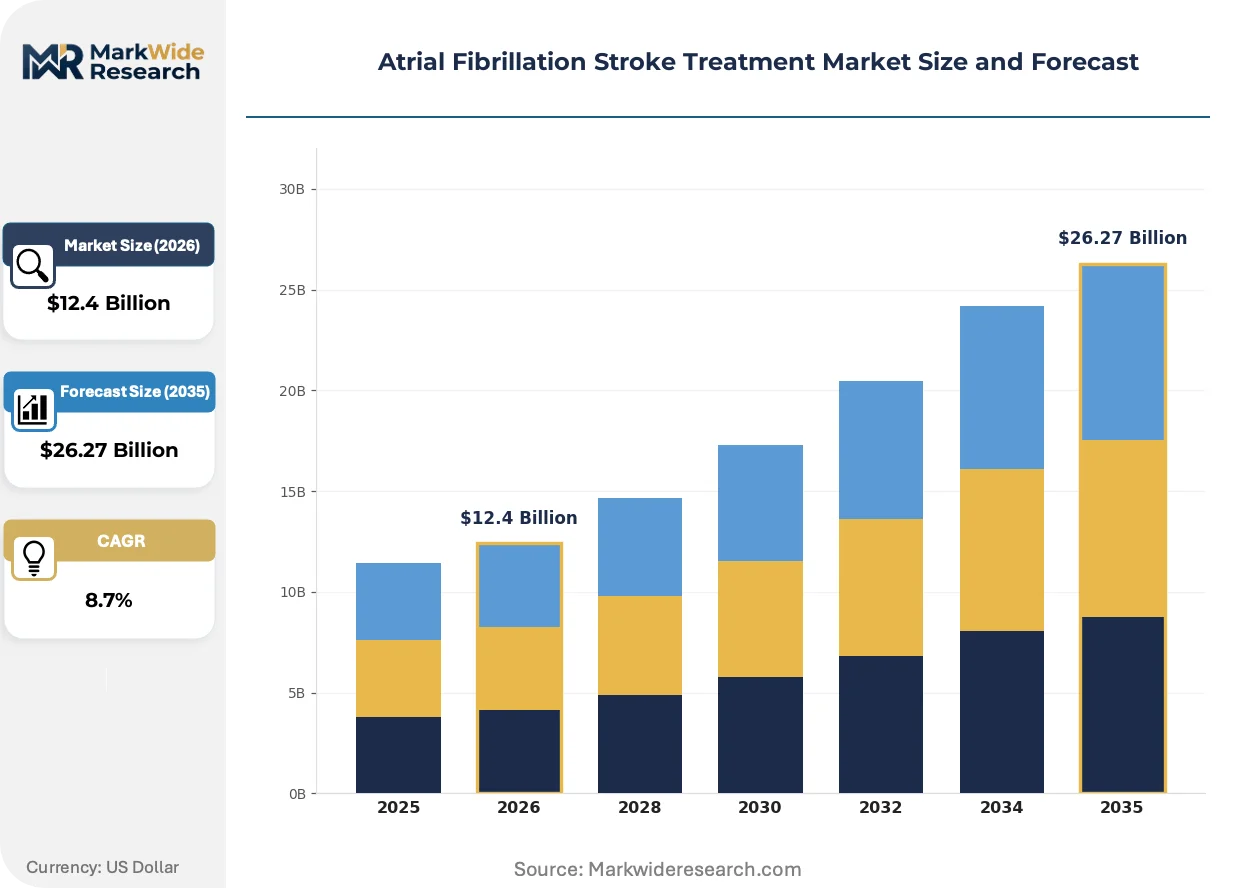
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Antiplatelet Agents, Catheter Ablation Devices, Implantable Devices Delivery Mode: Oral, Injectable, Transcatheter, Surgery End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Therapy Area: Cardiology, Neurology, Emergency Medicine, Critical Care |
| Companies Covered | Johnson & Johnson, Boston Scientific Corporation, Medtronic plc, Abbott Laboratories, AtriCure Inc., Boehringer Ingelheim GmbH, Bristol-Myers Squibb Company, Bayer AG, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atrial Fibrillation Stroke Treatment Market Evolving Landscape
Bioresorbable material science and automated procedural workflows are converging to reduce implant-related adverse events while compressing operator dependency in atrial fibrillation stroke prevention.
Bioresorbable polymer coatings in left atrial appendage closure devices degrade within 24-36 months post-implantation, eliminating permanent foreign body exposure. High-volume ablation centers in the United States are prioritizing these next-generation implants for warfarin-contraindicated patients. The technology is automating long-term risk stratification by removing chronic inflammation triggers and reducing surveillance imaging frequency.
EMA Medical Device Regulation conformity assessments now mandate extended clinical follow-up for implantable cardiac devices, reshaping post-market surveillance obligations. Manufacturers must maintain active registries spanning minimum five-year horizons to retain CE marking validity. Implantable device categories face the steepest compliance cost escalation, with smaller portfolio players consolidating regulatory functions to manage assessment timelines.
Japanese hospital procurement committees are unbundling device selection from catheter ablation procedure bundling, enabling standalone left atrial appendage closure purchasing decisions. Academic medical centers in Tokyo and Osaka lead this decoupling, negotiating direct manufacturer contracts for closure devices independent of mapping system vendors. This purchasing autonomy is most visible in metropolitan hospital networks with established electrophysiology fellowship programs.
Atrial Fibrillation Stroke Treatment Market Segmentation
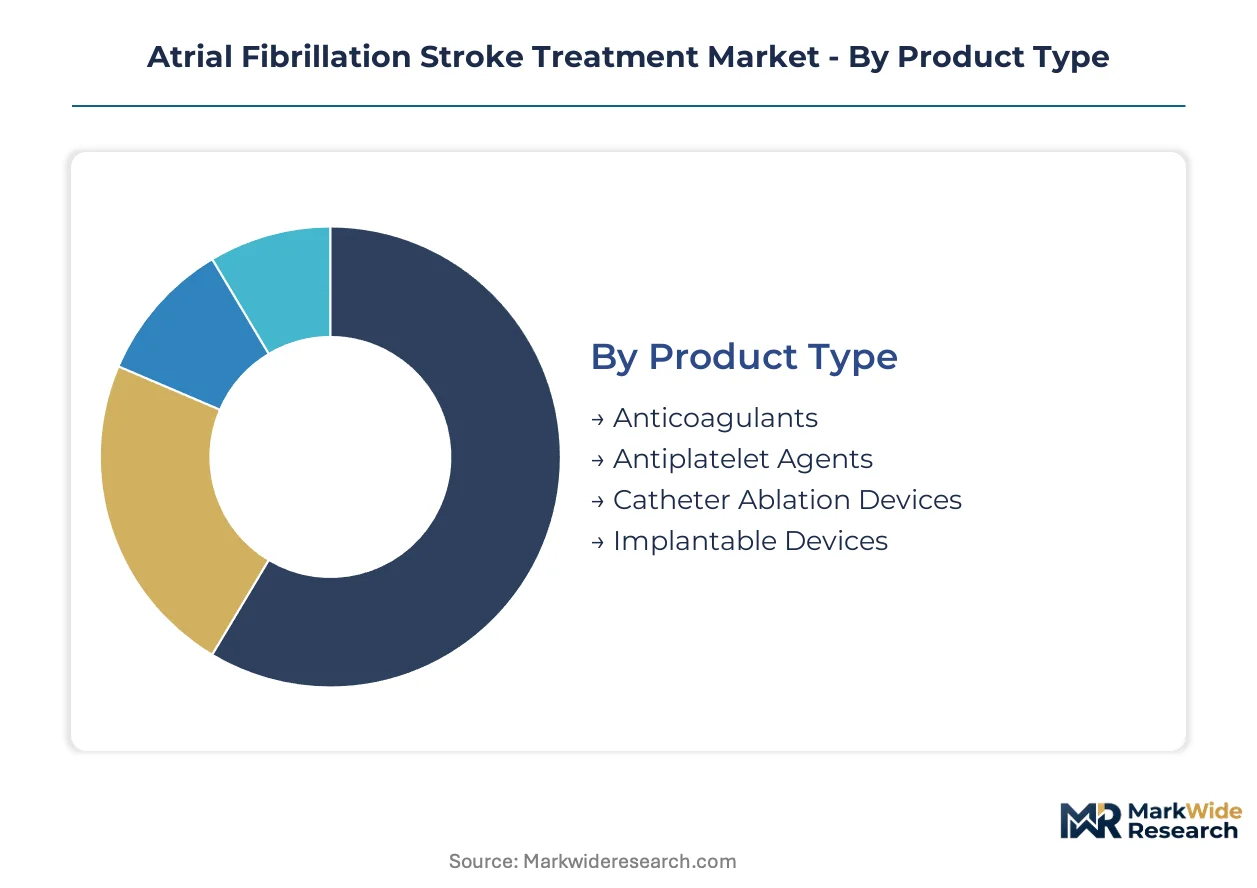
Stroke prevention in atrial fibrillation spans pharmaceutical maintenance and interventional resolution, with segmentation reflecting divergent clinical workflows, reimbursement structures, and operator skill requirements across care settings.
Product Type:
Standardization dominates anticoagulant formulations while implantable devices demand patient-specific anatomical customization and physician-tailored deployment protocols.
- Anticoagulants:Direct oral anticoagulants targeting factor Xa or thrombin have displaced vitamin K antagonists in guideline-preferred protocols. Demand concentrates in United States ambulatory settings where Medicare Part D coverage and established reversal agent availability support prescription volume.
- Implantable Devices:Left atrial appendage closure systems with bioresorbable polymer coatings reduce chronic foreign body exposure. German hospital networks drive European adoption, leveraging established electrophysiology infrastructure to expand beyond warfarin-intolerant candidates.
- Catheter Ablation Devices:Cryoballoon and radiofrequency platforms compete on procedural efficiency metrics.
- Antiplatelet Agents:Adjunctive therapy for combined cardiovascular risk profiles in select patient populations.
Leading the category by volume: Anticoagulants. Growing fastest: Implantable Devices.
Delivery Mode:
Cost tier stratification separates acute inpatient interventions from chronic outpatient management, with transcatheter procedures commanding premium reimbursement relative to pharmaceutical administration.
- Oral:Direct factor Xa inhibitors and direct thrombin inhibitors enable patient self-administration without INR monitoring requirements. United States pharmacy benefit managers drive formulary placement negotiations, concentrating demand in Medicare Advantage and commercial insurance networks.
- Transcatheter:Fluoroscopic and echocardiographic guidance enables percutaneous left atrial appendage closure without thoracotomy. Japanese metropolitan hospital networks in Tokyo and Osaka expand electrophysiology capacity to support outpatient procedure migration.
- Injectable:Bridging protocols and acute reversal scenarios requiring parenteral administration.
- Surgery:Thoracoscopic and open surgical appendage exclusion for anatomically complex cases.
Highest reimbursement tier: Transcatheter. Steepest volume decline: Surgery.
End User:
Application intensity varies by procedural complexity, with high-volume ablation centers demanding integrated device portfolios while community settings prioritize pharmaceutical protocols.
- Hospitals:Academic medical centers and high-volume community hospitals retain complex catheter ablation and surgical appendage closure procedures. CMS national coverage determinations directly influence procedure authorization thresholds in United States health systems.
- Clinics:Ambulatory surgery centers build electrophysiology capacity for transcatheter device deployment, extending procedural access beyond traditional inpatient infrastructure.
- Home Care:Oral anticoagulant administration with remote monitoring support for stable patients.
- Rehabilitation Centers:Post-interventional recovery and anticoagulation management in transitional care settings.
Dominant revenue concentration: Hospitals. Expanding most quickly: Clinics.
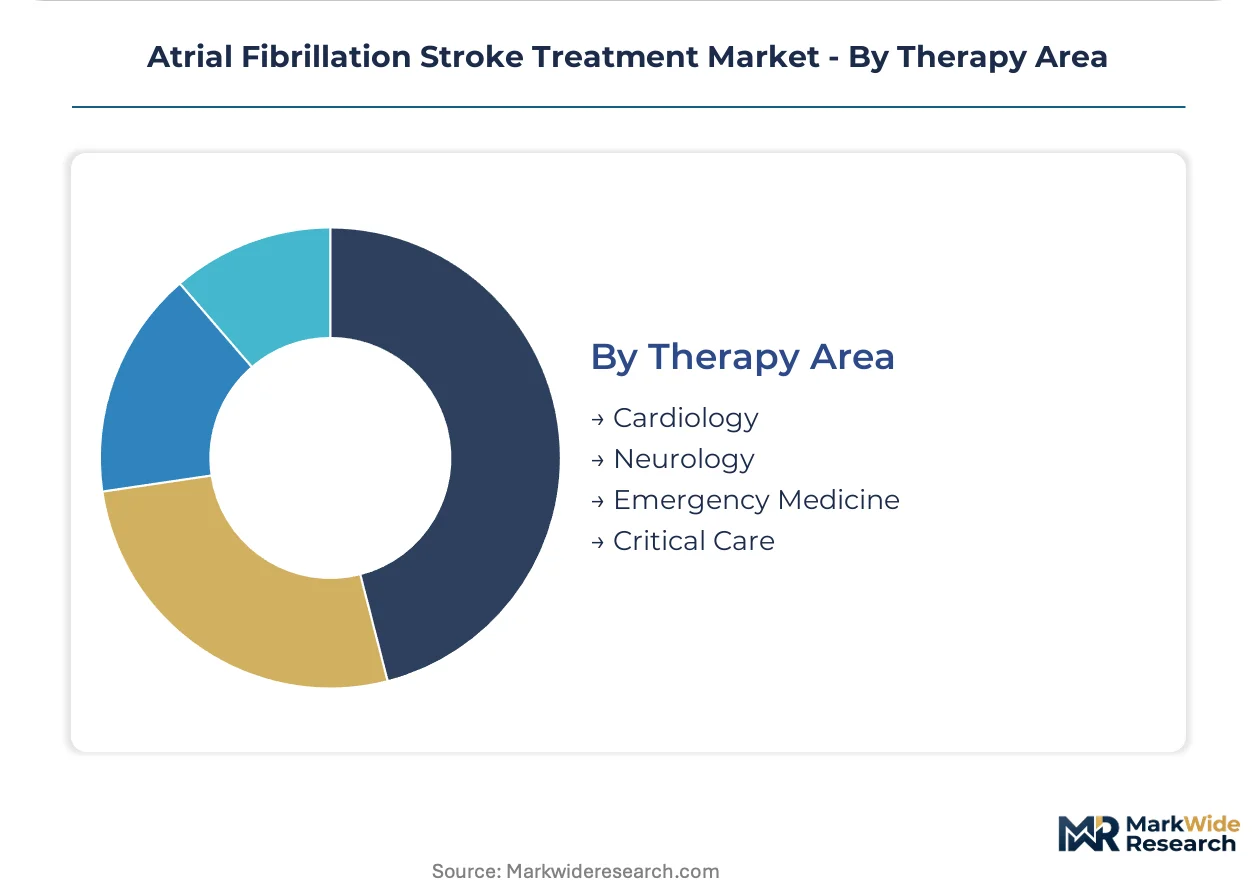
Therapy Area:
Customer type specialization reflects divergent training pathways, with electrophysiology-trained cardiologists driving device adoption while neurologists anchor thromboembolic event management protocols.
- Cardiology:Electrophysiology specialists perform catheter ablation and device implantation procedures. German hospital networks maintain fellowship training pipelines that constrain operator supply expansion relative to procedural demand growth.
- Neurology:Stroke specialists manage thromboembolic event prevention and coordinate anticoagulation protocols. Japanese academic medical centers integrate neurology consultation into atrial fibrillation clinic workflows.
- Emergency Medicine:Acute stroke evaluation and anticoagulation reversal decision-making in presenting patients.
- Critical Care:Hemodynamic management and bridging anticoagulation in unstable patients.
Primary procedure authority: Cardiology. Fastest protocol integration: Neurology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States, Germany, and Japan concentrate procedural demand for atrial fibrillation stroke treatments. Aging demographics and established electrophysiology infrastructure in these markets support catheter ablation volume expansion and transcatheter device adoption.
United States
Medicare Part D coverage and commercial insurance networks drive prescription volumes for direct oral anticoagulants. FDA breakthrough device designations compress regulatory timelines for novel therapeutic candidates. High-volume ablation centers in metropolitan hospital networks expand integrated mapping-ablation workflows.
Germany
Established electrophysiology fellowship programs and hospital infrastructure sustain procedure volume growth for catheter ablation and appendage closure interventions. EMA medical device regulation conformity assessments mandate extended clinical follow-up for implantable cardiac devices. Academic medical centers in Munich and Heidelberg lead adoption of bioresorbable polymer-coated closure devices.
Japan
Aging population dynamics and expanding electrophysiology infrastructure create whitespace for transcatheter left atrial appendage closure beyond warfarin-intolerant candidates. PMDA regulatory pathways prioritize novel therapeutic candidates with demonstrated safety profiles. Metropolitan hospital networks in Tokyo and Osaka unbundle device selection from catheter ablation procedure bundling.
United Kingdom
NHS England technology appraisal processes influence formulary placement for direct oral anticoagulants across integrated care systems. NICE health technology assessments demand real-world evidence for device-based stroke prevention strategies. London and Southeast England academic medical centers anchor clinical trial recruitment for novel anticoagulation reversal agents.
France
HAS (Haute Autorité de Santé) reimbursement decisions shape hospital procurement for implantable cardiac devices. ANSM pharmacovigilance requirements extend post-market surveillance obligations for anticoagulant therapies. Paris and Lyon metropolitan hospital networks concentrate electrophysiology specialist training and high-complexity procedural capacity.
Atrial Fibrillation Stroke Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as device manufacturers integrate pharmaceutical and interventional stroke prevention offerings. The market structures around three tiers: diversified medtech conglomerates with electrophysiology portfolios, pharmaceutical specialists with anticoagulant pipelines, and emerging device players focused on left atrial appendage closure innovation. Strategic archetypes include integrated platform providers, factor Xa inhibitor developers, and bioresorbable material science specialists. M&A activity and strategic partnerships represent the dominant competitive moves as players seek complementary capabilities across the therapy continuum.
Among diversified medtech conglomerates, Johnson & Johnson, Boston Scientific Corporation, and Medtronic plc exemplify the integrated platform archetype. Johnson & Johnson occupies a position spanning pharmaceutical anticoagulants and interventional device portfolios. Boston Scientific Corporation anchors electrophysiology supply chain relationships across North American hospital networks. Medtronic plc sits within the cryoballoon ablation platform segment, competing on procedural efficiency metrics. These three entities represent the consolidation endpoint toward which mid-cap specialists and regional players orient partnership strategies.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Boston Scientific Corporation |
| Medtronic plc |
| Abbott Laboratories |
| AtriCure Inc. |
| Boehringer Ingelheim GmbH |
| Bristol-Myers Squibb Company |
| Bayer AG |
| Sanofi |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up electrophysiology specialists anchor supply consolidation across North American hospital networks, compressing procurement leverage for standalone device manufacturers while sustaining premium pricing tiers for integrated mapping-ablation platforms. This ownership concentration feeds pricing discipline through exclusive long-term supply agreements that lock in formulary placement for catheter ablation and closure device portfolios.
Pricing Analysis
High-volume ablation centers command volume-based discounts that compress margins for cryoballoon and radiofrequency platforms, while community hospitals absorb premium pricing for bioresorbable polymer-coated closure devices due to limited procurement scale. Price differentiation separates FDA breakthrough-designated implants from standard CE-marked alternatives, with reimbursement tiering by CMS national coverage determinations amplifying buyer sensitivity in Medicare-dependent health systems. Pricing pressure stems from Japanese hospital procurement committees unbundling device selection from procedure bundling, forcing standalone negotiation for left atrial appendage closure systems. Academic medical centers exhibit lowest price sensitivity due to integrated electrophysiology fellowship training dependencies on specific vendor platforms.
Supply Chain Analysis
Device refurbishment and explant return flows from German hospital networks feed bioresorbable polymer coating research programs, with explanted closure devices providing degradation timeline validation data. Manufacturing concentrates in the United States, Ireland, and Costa Rica for sterile catheter production, while nitinol frame fabrication draws from titanium supply anchored in China and Russia. Supply chain risk centers on single-source dependency for specialized echocardiographic guidance transducers used in transseptal access procedures. Distribution runs through GPO-contracted medical-surgical distributors to hospital cath labs, with direct manufacturer contracting emerging in Japanese metropolitan networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
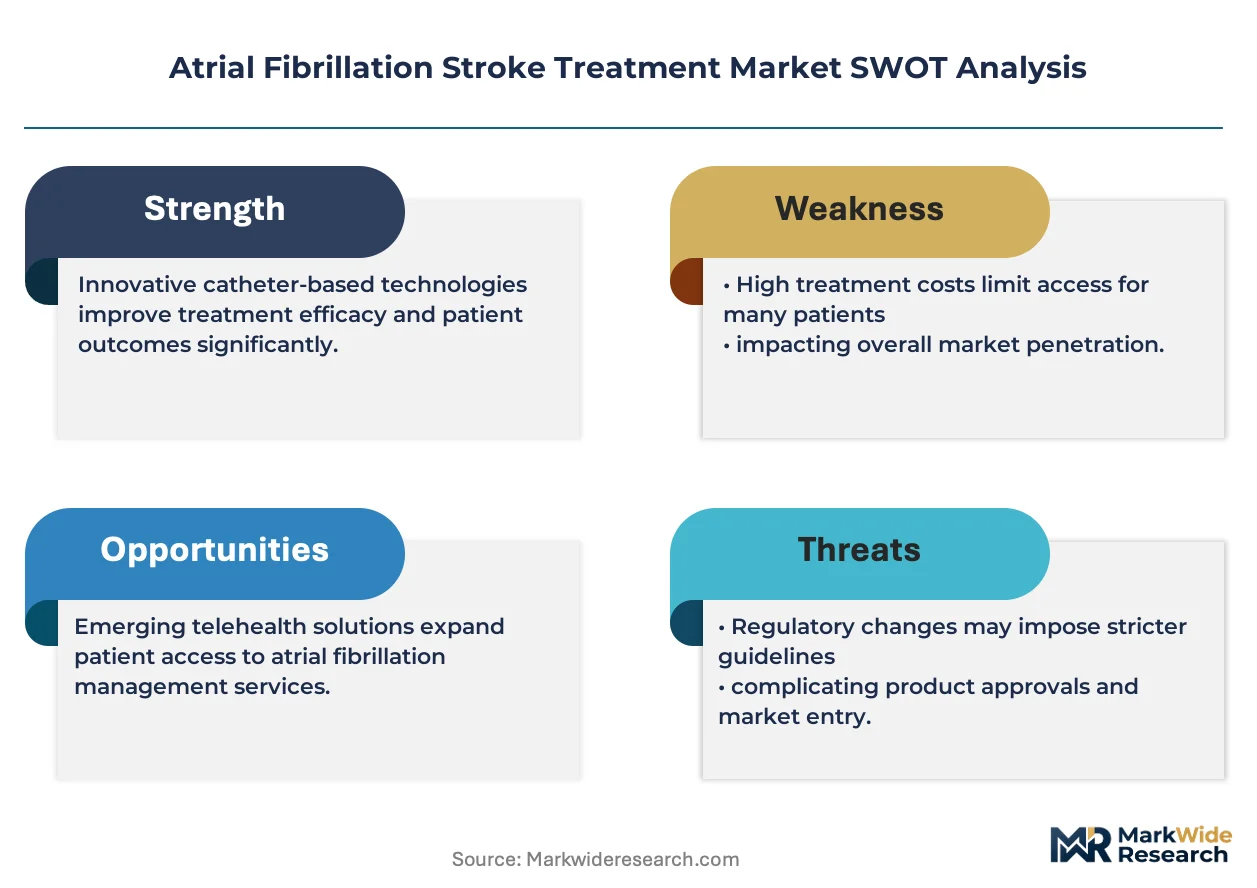
The atrial fibrillation stroke treatment market functions as a cost-of-compliance story where EMA Medical Device Regulation five-year post-market surveillance requirements erect barrier-to-entry moats that favor established players with active registry infrastructure.
For Market Incumbents: Cement exclusive supply agreements with high-volume ablation centers before Japanese procurement committees complete system-wide unbundling transitions. Expand backward integration into bioresorbable polymer resin production to capture coating technology margins threatened by materials science specialists. Prioritize FDA breakthrough device designation maintenance for next-generation closure systems to sustain reimbursement premium tiers against radiofrequency ablation substitutes. For New Entrants and Emerging Players: Telehealth-integrated remote patient monitoring platforms offer de novo entry vectors for oral anticoagulant adherence programs outside established hospital formulary control. Target Japan's underpenetrated device segment beyond warfarin-intolerant candidates, where electrophysiology infrastructure expansion outpaces incumbent sales force coverage. Pursue white-label manufacturing partnerships with Costa Rican catheter producers to bypass capital-intensive sterile production facility requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor bioresorbable materials science specialists with active FDA pre-submission feedback in hand, particularly those with German academic medical center clinical trial partnerships. Long-term viability hinges on integrated pharmaceutical-device portfolio positioning as substitution risk between anticoagulants and closure devices intensifies. Monitor CMS national coverage determination revision timelines as the critical inflection signal for left atrial appendage closure procedure volume trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated premarket approval timelines compress competitive entry windows for novel closure systems. |
| CE Marking Pathway under MDR | Extended clinical follow-up mandates reshape post-market surveillance economics for implantable portfolios. |
| Hospital System Partnership | Exclusive cath lab supply agreements lock in mapping-ablation workflow integration across metropolitan networks. |
| Software Companion Development | AI-enabled procedural guidance reduces operator training bottlenecks for transseptal access techniques. |
| Reimbursement Strategy | CMS national coverage determination alignment determines Medicare-driven demand authorization thresholds. |
Research Methodology
Independent corroboration across electrophysiology fellowship program directors, hospital purchasing committee chairs, and GPO contracts managers underwrites the qualitative findings on procurement pattern shifts. Primary interviews with biomedical engineers and cath lab operations heads combined with secondary validation against FDA premarket approval databases, EMA CE marking registries, and CMS Medicare claims data establish procedure volume baselines. Bottom-up triangulation across device implant registries and top-down reconciliation with pharmaceutical prescription audits anchor market sizing.
Rate-of-change decomposition across the projection horizon separates volume growth from pricing trajectory and mix shift effects. Segmentation dimensions span product type, delivery mode, end user, and therapy area, with regional regulatory cluster differentiation for FDA, EMA, and PMDA pathway timing. CAGRs derive from fitted growth curves calibrated to historical procedure expansion rates and electrophysiology specialist supply constraints. Forecast inputs incorporate anticoagulation reversal agent availability timelines and health technology assessment body valuation precedents.
The model holds under stable Medicare coverage determination and EMA MDR enforcement intensity; deviation in CMS national coverage revision schedules or polymer supply disruption would shift implantable device adoption curves. Forecasts reflect documented assumptions on operator training pipeline output and ambulatory surgery center electrophysiology capacity buildout. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Deep Vein Thrombosis Market
Cardiovascular
Cardiac Biomarkers Market
Cardiovascular
Global Statin Market
Cardiovascular
Heterozygous Familial Hypercholesterolemia (HEFH) Management Market
Cardiovascular
Vasculitis Market
Cardiovascular
Heart Block Therapeutics Market
Cardiovascular
Cardiovascular Clinical Trials Market
Cardiovascular
Coronary Artery Disease Therapeutics Market
Cardiovascular
Cardiac Troponin Market
Cardiovascular
Aortic Coarctation Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Myocardial Infarction Market
Cardiovascular
Myocardial Infarction Therapeutics Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Middle-East and Africa Ischemic Heart Disease Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market