
 Long-Acting Insulin Market | 2026-2036
Long-Acting Insulin Market Size, Share, and Industry Trends Forecast 2026-2036
Long-Acting Insulin Market Foresight
Hospital-centric procurement of long-acting insulin is collapsing as homecare and retail pharmacy channels capture patient volume. Novo Nordisk leverages its manufacturing scale to dominate degludec supply across European and Asian markets. Sanofi anchors glargine production through backward integration into recombinant DNA fermentation. Eli Lilly competes in the biosimilar glargine segment with specialized fill-finish capacity in regulated jurisdictions.
Long-acting insulin comprises synthetic basal analogs engineered for steady pharmacokinetic profiles over 18 to 42 hours, typically produced via recombinant DNA technology in E. coli or yeast expression systems to maintain peakless glucose control for diabetic patients. Glargine and degludec formulations occupy the largest margin pools due to patent-protected pricing and established clinician preference, while biosimilars represent the fastest-growing category as regulatory parity accelerates substitution in pen and vial delivery modes. The delivery mode dimension shows pumps gaining traction among intensive insulin users despite pens controlling volume, with inhalers remaining a niche segment limited by pulmonary absorption variability.
FDA biosimilar guidance and EMA scientific advice pathways shape product development timelines and interchangeability standards for insulin glargine and insulin detemir copies. The EU Green Deal and REACH chemical safety frameworks indirectly influence manufacturing site selection and solvent disposal protocols for biological production facilities. WHO prequalification requirements affect access programs in low-income markets where long-acting analogs remain underutilized relative to human insulin. Stakeholders must monitor biosimilar interchangeability rulings and reimbursement tier adjustments as these decisions will restructure prescribing patterns faster than clinical trial data alone.
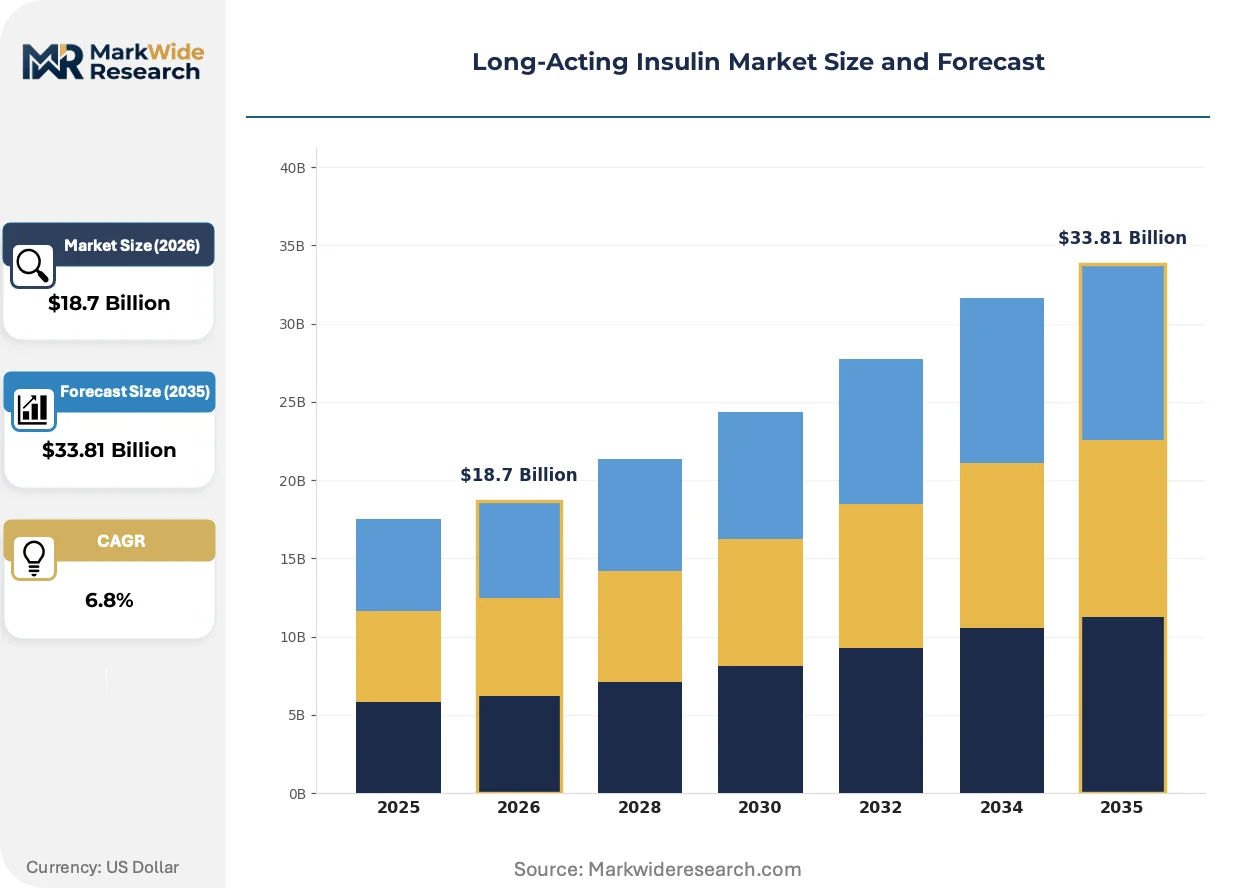
Market Dynamics
FDA and EMA biosimilar interchangeability rulings are restructuring prescribing patterns faster than clinical trial data alone, compressing brand insulin margins while expanding patient access to lower-cost basal analogs across retail pharmacy channels.
Growth Catalysts
- Homecare self-administration protocols:Type 2 diabetes patients in the United States and Germany are transitioning from clinic-based injections to pen-device home delivery, expanding addressable patient populations beyond traditional hospital capture.
- EMA biosimilar scientific advice pathways:Streamlined pre-submission consultations are accelerating development timelines for insulin glargine and detemir alternatives, reducing regulatory uncertainty for manufacturers targeting European markets.
- Reimbursement tier preference for analogs:China's national health insurance formulary revisions favor long-acting basal analogs over conventional NPH insulin, redirecting procurement volume toward synthetic formulations with steadier pharmacokinetic profiles.
Market Restraints
- Recombinant DNA fermentation capacity concentration:Backward-integrated production of active pharmaceutical ingredients concentrates among three major suppliers, creating single-source vulnerability for glargine and degludec supply chains.
- Cold chain distribution cost structure:Temperature-controlled logistics requirements for protein stability add 15-25% to landed costs in regions with limited refrigerated infrastructure, constraining analog penetration in low-income markets.
- WHO prequalification procedural delays:Extended review timelines for long-acting insulin analogs limit participation in global access programs, preserving human insulin dominance in publicly procured diabetes care.
Strategic Opportunities
- Pump-compatible formulation development:Concentrated U-300 and U-500 insulin variants for continuous subcutaneous infusion devices address unmet needs among insulin-resistant patients requiring higher basal delivery rates.
- REACH-compliant solvent recovery systems:EU Green Deal manufacturing incentives reward biological production facilities with closed-loop chemical processing, creating competitive differentiation for European-based fermentation sites.
- Retail pharmacy direct distribution:Bypassing hospital procurement committees through 90-day mail-order pharmacy channels captures chronic therapy refills with lower administrative burden and faster patient onboarding.
Industry Challenges
- Biosimilar immunogenicity assessment complexity:Demonstrating analytical similarity for insulin glargine copies requires extensive anti-drug antibody monitoring studies, extending development timelines and raising clinical trial costs.
- Legacy pen-device platform incompatibility:Different fill-finish specifications between originator and biosimilar delivery systems force patients to relearn injection techniques, generating prescriber hesitation and pharmacy substitution barriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long-Acting Insulin Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glargine, Detemir, Degludec, Biosimilars Delivery Mode: Pens, Vials, Pumps, Inhalers End User: Hospitals, Clinics, Homecare, Pharmacies Customer Type: Diabetics, Healthcare Professionals, Caregivers, Others |
| Companies Covered | Biocon, Wockhardt, Novo Nordisk, Gan & Lee Pharmaceuticals, Bioton, Eli Lilly, Julphar, Sedico, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long-Acting Insulin Market Shifts & Advancements
Delivery technology convergence and regulatory science advances are compressing the gap between originator and follow-on insulin performance, while patient behavior shifts favor convenience-optimized administration over clinical setting dependence.
Connected pen devices with dose-capture Bluetooth functionality are supplanting conventional mechanical injectors in intensive insulin user segments. Endocrinology practices in Germany and the United States are adopting these systems for remote adherence monitoring. The technology is enabling outcome-based reimbursement pilots that tie pharmacy benefit manager payments to glycemic control metrics rather than prescription volume alone.
REACH chemical safety frameworks are mandating solvent substitution in recombinant protein purification processes. Biological manufacturers operating European facilities must phase out acetonitrile-based chromatography in favor of aqueous buffer systems. Glargine production lines in Germany and France are retrofitting capture columns to maintain EMA compliance without batch yield degradation.
Patient switching behavior between basal analogs is accelerating as pharmacy benefit designs impose tiered co-pay structures favoring lowest-net-cost alternatives. Retail channels in the United States are capturing refill volume from specialty pharmacy networks through automated prior authorization platforms. This pattern concentrates in Medicare Part D populations where annual plan changes trigger therapeutic substitution reviews during open enrollment periods.
Long-Acting Insulin Market Segmentation
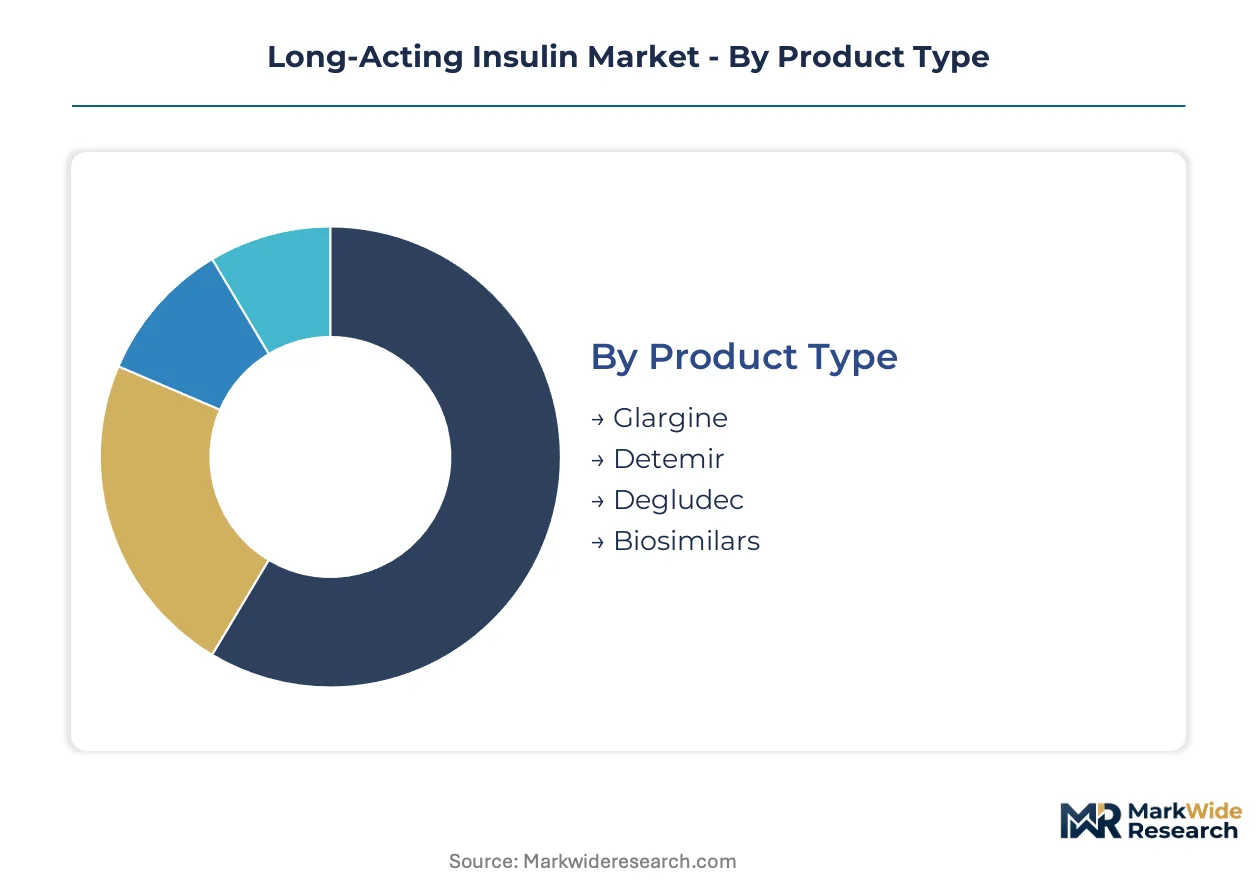
Long-acting insulin segmentation reveals how regulatory pathways, delivery technology, and patient setting interact to determine commercial outcomes. Each dimension carries distinct FDA and EMA compliance requirements that shape development investment and market access strategy.
Product Type:
FDA biosimilar interchangeability rulings and EMA scientific advice pathways create divergent approval timelines across molecular categories, directly affecting competitive positioning and pricing power.
- Glargine:Recombinant insulin analog with acidic pH formulation enabling 24-hour basal coverage through subcutaneous precipitation-dissolution kinetics. Demand concentrates in Medicare Part D populations in the United States where pharmacy benefit managers favor established clinician familiarity over switching incentives.
- Degludec:Multi-hexameric insulin degludec forms subcutaneous depots with ultra-long half-life exceeding 42 hours, permitting flexible dosing intervals. Germany's Diabetologen practices drive adoption among shift workers and elderly patients with irregular meal patterns, supported by BfArM reimbursement parity with glargine.
- Detemir:Acylated insulin with fatty acid side chain enabling albumin binding and prolonged absorption profile.
- Biosimilars:Follow-on biologics referencing glargine or detemir through analytical similarity and clinical immunogenicity programs.
Glargine handles the majority of throughput; biosimilars are expanding most quickly on share.
Delivery Mode:
Cost tier differentiation separates premium connected devices from commodity vial systems, with reimbursement bands determining patient out-of-pocket exposure across pharmacy channels.
- Pens:Disposable or reusable injection devices with dose-dialing mechanisms and concealed needles, dominating retail pharmacy dispensing. China's national health insurance reimburses pen devices at higher rates than vials in tier-one cities, accelerating substitution among newly diagnosed Type 2 patients.
- Vials:Multi-dose glass containers requiring syringe-based administration, retaining volume in institutional procurement and cash-pay segments.
- Pumps:Continuous subcutaneous infusion devices with programmable basal rates, capturing intensive insulin users.
- Inhalers:Pulmonary delivery systems for rapid-acting insulin, remaining experimental for basal analogs.
Pens control the largest prescription volume; pumps are climbing the fastest among intensive insulin users.
End User:
Patient setting migration from institutional to ambulatory channels is restructuring procurement authority and margin capture across the value chain.
- Homecare:Self-administration by patients or family members using pen devices or pumps, now the dominant volume channel. United States retail pharmacy 90-day mail-order programs capture chronic refill volume with lower administrative burden than hospital discharge prescriptions.
- Hospitals:Inpatient glycemic management protocols using sliding-scale or basal-bolus regimens, declining as a share of total volume.
- Clinics:Endocrinology and primary care practices providing injection training and dose titration.
- Pharmacies:Community and specialty pharmacy networks handling prescription fulfillment and prior authorization.
Homecare channels now process the majority of annual prescriptions; retail pharmacy direct distribution is gaining share fastest.
Customer Type:
Decision-making authority fragments across patients, prescribers, and caregivers, with each segment presenting distinct adherence monitoring and education requirements.
- Diabetics:Adult and pediatric patients with Type 1 or Type 2 diabetes requiring basal insulin supplementation. Germany's Disease Management Programs mandate structured education for new insulin starters, creating enrollment bottlenecks that delay therapy initiation.
- Healthcare Professionals:Endocrinologists, primary care physicians, and diabetes educators prescribing and monitoring therapy.
- Caregivers:Family members or home health aides administering insulin to pediatric or geriatric patients.
- Others:Research institutions, veterinary applications, and emergency preparedness stockpiles.
Diabetic patients represent the primary demand source; caregiver-administered therapy is expanding fastest among aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Danish and German insulin exports flow predominantly into United States and Chinese distribution channels, with cold-chain logistics networks radiating from Copenhagen and Frankfurt hubs to serve retail pharmacy and homecare delivery points.
United States
Medicare Part D enrollment expansion and pharmacy benefit manager tiered formularies drive basal analog substitution. FDA interchangeability rulings for biosimilar glargine accelerate retail channel penetration. Indianapolis and Research Triangle Park clusters host fill-finish operations for pen-device assembly.
Germany
Disease Management Programs mandate structured diabetes education, creating enrollment bottlenecks that delay insulin initiation. BfArM reimbursement parity between degludec and glargine supports flexible dosing adoption. Bavarian fermentation facilities retrofit solvent recovery systems to maintain EMA REACH compliance.
China
National health insurance formulary revisions favor long-acting basal analogs over NPH insulin in tier-one cities. NMPA accelerated review pathways for biosimilar insulins compress development timelines. Yangtze River Delta biomanufacturing parks expand recombinant protein capacity for domestic glargine supply.
India
CDSCO regulatory harmonization with ICH guidelines enables parallel filing for biosimilar insulin glargine. Government procurement programs for human insulin limit analog penetration in publicly funded care. Hyderabad and Bangalore clusters concentrate active pharmaceutical ingredient fermentation for export markets.
Japan
PMDA post-marketing surveillance requirements extend immunogenicity monitoring for biosimilar insulins beyond approval. Aging demographics expand caregiver-administered therapy demand. Kanto region distribution centers optimize cold-chain infrastructure for pen-device last-mile delivery.
Long-Acting Insulin Market Competitive Landscape
Player mix skews toward vertically integrated biopharmaceutical conglomerates with captive fermentation capacity and specialized biosimilar developers with contract manufacturing partnerships. Three archetypes dominate: originator patent-holders defending margin through delivery device innovation, biosimilar challengers exploiting regulatory parity, and emerging-market producers serving cost-sensitive procurement. Competitive moves concentrate on backward integration into recombinant DNA fermentation and pump-compatible formulation development.
Among Danish and French-origin integrated producers, Novo Nordisk and Sanofi anchor the originator tier with established clinician relationships and pen-device ecosystems. Eli Lilly occupies a hybrid position spanning both originator and biosimilar segments through specialized fill-finish capacity. Indian biosimilar specialists Biocon and Wockhardt exemplify the emerging-market challenger archetype, leveraging CDSCO regulatory alignment to supply cost-competitive glargine alternatives.
| Leading Market Players |
|---|
| Biocon |
| Wockhardt |
| Novo Nordisk |
| Gan & Lee Pharmaceuticals |
| Bioton |
| Eli Lilly |
| Julphar |
| Sedico |
| Sanofi |
| Others |
Supply & Pricing Matrix
FDA interchangeability rulings gate both supplier qualification and price differentiation in long-acting insulin markets, creating parallel certification tiers that separate originator manufacturers from biosimilar challengers while embedding cold-chain logistics costs into landed price structures across retail pharmacy channels.
Pricing Analysis
Originator glargine and degludec formulations command premium positioning against biosimilar alternatives and legacy NPH insulin, with price differentiation anchored in patent-protected delivery device ecosystems and clinician familiarity rather than clinical efficacy alone. Cost compression in the biosimilar tier is intensifying because EMA scientific advice pathways accelerate competitor entry, while Medicare Part D populations show highest price sensitivity due to tiered co-pay structures that favor lowest-net-cost alternatives.
Supply Chain Analysis
Just-in-time inventory strategies dominate insulin distribution to retail pharmacies, though strategic stockpiling persists among national health programs and emergency preparedness authorities facing cold-chain vulnerability. Active pharmaceutical ingredient production concentrates in Denmark, France, and Germany, with fill-finish operations drawing from recombinant DNA fermentation capacity anchored in Copenhagen and Frankfurt clusters. Single-source vulnerability for glargine and degludec APIs creates structural risk, while distribution runs through temperature-controlled logistics networks radiating from European hubs to United States and Chinese delivery points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive fermentation capacity and specialized fill-finish certification represent the scarce capabilities that determine competitive survival in long-acting insulin manufacturing, with backward integration into recombinant DNA production now table stakes for margin defense.
For Market Incumbents: Shield patent-protected positioning by accelerating pump-compatible U-300 and U-500 formulation development before biosimilar interchangeability rulings fully commoditize basal analog pricing. Deepen captive supply of active pharmaceutical ingredients through fermentation capacity expansion in REACH-compliant European sites, insulating against EMA solvent recovery mandates that threaten batch yields at non-integrated facilities. For New Entrants and Emerging Players: Anchor in China's tier-one cities where national health insurance formulary revisions favor long-acting basal analogs over NPH insulin, creating procurement volume redirection toward synthetic formulations. Exploit CDSCO regulatory harmonization to supply cost-competitive glargine alternatives into Indian export markets, leveraging Hyderabad and Bangalore fermentation clusters for active pharmaceutical ingredient production. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biosimilar insulin development programs as FDA immunogenicity assessment requirements extend clinical trial timelines and raise anti-drug antibody monitoring costs. Target acquisition profiles should emphasize contract manufacturing organizations with established EMA scientific advice relationships and existing fill-finish capacity in regulated jurisdictions. Revision becomes warranted when biosimilar interchangeability rulings trigger prescriber substitution rates that cross threshold levels for originator margin collapse.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Solvent Recovery | EMA manufacturing incentives reward closed-loop chemical processing at Bavarian fermentation facilities. |
| Pump-Compatible Formulation Development | U-300 and U-500 variants address unmet needs among insulin-resistant patients requiring higher basal delivery. |
| Retail Pharmacy Direct Distribution | Ninety-day mail-order channels capture chronic refill volume with lower administrative burden than hospital discharge. |
| Biosimilar Interchangeability Pathway | FDA rulings accelerate retail channel penetration while compressing brand insulin margins across pharmacy benefit tiers. |
| Connected Pen Device Integration | Bluetooth dose-capture functionality enables outcome-based reimbursement pilots tied to glycemic control metrics. |
Research Methodology
The analysis maps glargine, degludec, detemir, and biosimilar insulin sub-sectors, each validated through endocrinologists, pharmacy benefit managers, formulary directors, and cold-chain logistics operators, combining primary interviews with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare Part D claims data, with bottom-up prescription volume estimates triangulated against top-down manufacturer revenue benchmarks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical frameworks modeling product type, delivery mode, end-user setting, and customer decision-making authority dimensions. CAGRs were derived from patient population growth, analog substitution rates, and biosimilar penetration curves, incorporating insulin-resistant patient prevalence and pump adoption intensity as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable FDA interchangeability standards and REACH solvent regulation continuity; material deviation in biosimilar substitution velocity or EMA manufacturing compliance costs would warrant model refresh. Revision becomes warranted when cold-chain infrastructure investment in target markets crosses threshold levels that alter landed cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
Global Neuroprotective Agents Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Antihelminthics Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Global Nizatidine Market