
 Global Rotavirus Vaccine Market | 2026-2036
Global Rotavirus Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rotavirus Vaccine Market Foresight
The live-attenuated manufacturing capability gap between established and emerging suppliers is unwinding competitive stability in oral rotavirus vaccine supply. Merck & Co. Inc. anchors pentavalent production through its dedicated biologics network. GlaxoSmithKline plc leverages two decades of WHO prequalification experience to sustain tender access across African and Asian public health systems. Bharat Biotech International Limited specializes in heat-stable formulations that navigate cold-chain limitations in tropical distribution corridors.
Rotavirus vaccines are oral or injectable biologics containing live attenuated or inactivated rotavirus strains, formulated to induce intestinal mucosal immunity in infants under six months through serum IgA and neutralizing antibody responses. Pentavalent products command premium positioning in bundled immunization schedules, while monovalent alternatives occupy cost-sensitive procurement channels. Live attenuated formats dominate volume through established oral administration protocols, though inactivated candidates are gaining development traction for immunocompromised populations. Public health agencies represent the decisive end-user segment, controlling tender volumes and shaping manufacturer capacity planning through multi-year supply agreements.
WHO prequalification, FDA lot-release oversight, and EMA scientific opinion frameworks collectively determine market access for rotavirus vaccines in Gavi-eligible and middle-income countries. National regulatory authorities in India and China now align stringently with WHO norms, compressing approval timelines for domestic manufacturers seeking export eligibility. Stakeholders must monitor evolving WHO policy guidance on vaccine interchangeability and the potential entry of novel inactivated or subunit platforms that could fragment procurement preferences across immunization programs.
Market Dynamics
Gavi's multi-year supply agreements are compressing manufacturer margins while simultaneously locking in capacity commitments that deter new entrants from scaling live-attenuated production.
Growth Catalysts
- WHO Prequalification Pathway:The streamlined assessment framework accelerates market entry for heat-stable formulations targeting tropical distribution corridors in sub-Saharan Africa and South Asia.
- National Immunization Program Expansion:Low-income countries are integrating pentavalent rotavirus vaccines into bundled childhood schedules, creating procurement volume concentration through tender aggregation.
- Cold-Chain Infrastructure Investment:Development finance institutions are funding last-mile refrigeration networks that enable oral vaccine delivery to previously unreachable rural clinics.
Market Restraints
- Live-Attenuated Manufacturing Concentration:Production capability clusters among established biologics networks, creating supply vulnerability when single-source facilities face contamination events or regulatory holds.
- FDA Lot-Release Backlogs:Extended analytical review timelines for imported bulk materials delay shipment release to Gavi-eligible countries, compressing effective shelf life in tropical storage conditions.
- Inactivated Alternative Development Costs:Novel subunit platforms require substantially higher capital intensity per dose, pricing them out of public procurement channels where cost-per-dose thresholds are rigid.
Strategic Opportunities
- Immunocompromised Infant Segments:Inactivated rotavirus candidates address the unmet need of HIV-exposed infants excluded from live-attenuated protocols in South African and Kenyan treatment programs.
- Indian Domestic Manufacturer Export Eligibility:CDSCO alignment with WHO norms enables Bharat Biotech and emerging suppliers to compete in WHO prequalification tenders previously dominated by Western incumbents.
- Microarray Patch Delivery:Dissolvable microneedle formulations eliminate cold-chain dependence entirely, opening procurement channels for Ministries of Health in Pacific Island nations and conflict-affected territories.
Industry Challenges
- Fill-Finish Capacity Bottlenecks:Oral rotavirus vaccines require dedicated aseptic lines incompatible with standard injectable biologics equipment, forcing manufacturers to construct greenfield facilities or retrofit at substantial capital cost.
- Interchangeability Evidence Requirements:WHO policy guidance on sequential use of monovalent and pentavalent products demands costly head-to-head immunogenicity trials that strain mid-tier development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rotavirus Vaccine Market |
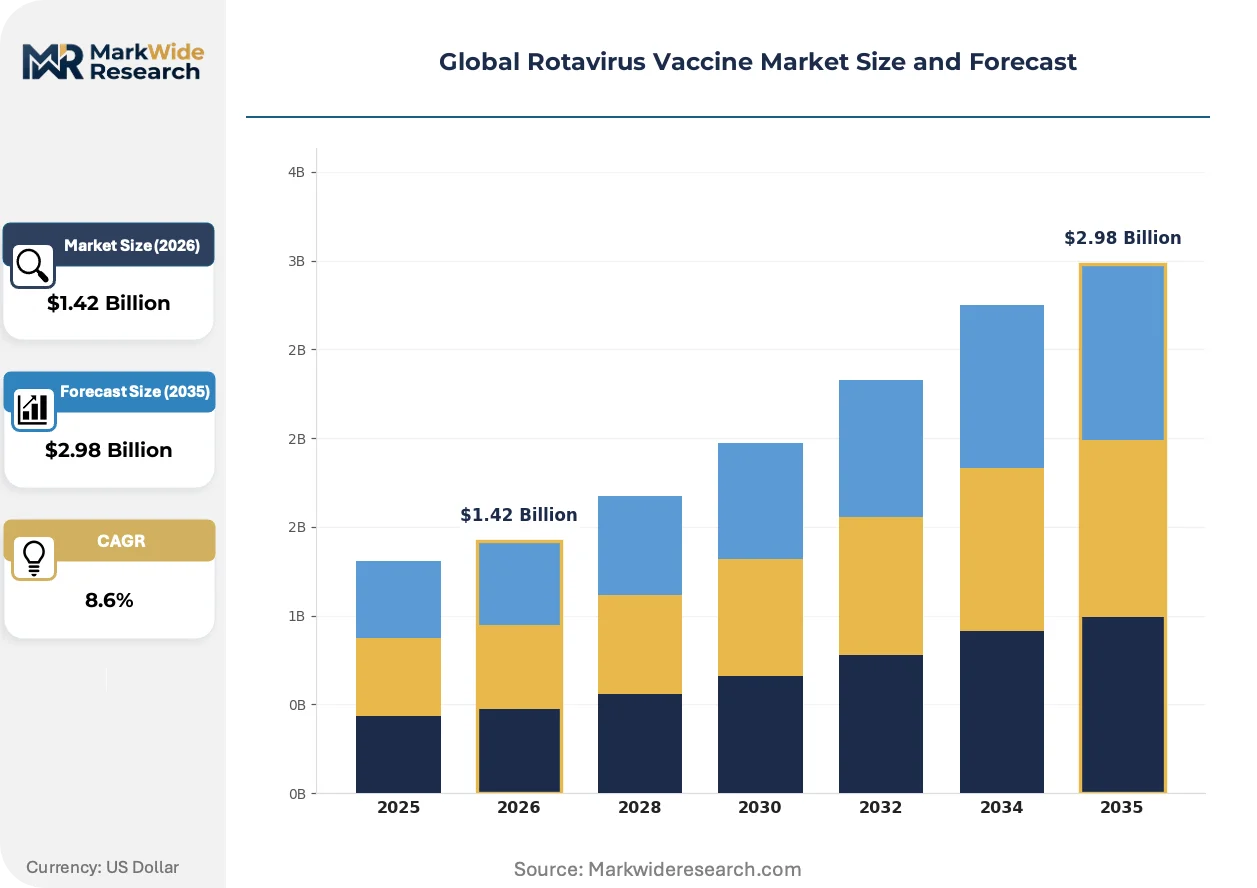
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monovalent, Pentavalent, Live Attenuated, Inactivated Application: Infant Immunization, Pediatric Clinics, Travel Medicine, Community Health Programs End User: Public Health Agencies, Specialty Clinics, Immunization Centers, Non-Governmental Organizations Distribution Channel: Hospitals, Retail Pharmacies, Online Pharmacies, Wholesale Distributors |
| Companies Covered | Serum Institute of India Private Limited, Sinovac Biotech Ltd., Merck & Co. Inc., China National Biotec Group Corporation, Biological E. Limited, GlaxoSmithKline plc, Bharat Biotech International Limited, Lanzhou Institute of Biological Products Co. Ltd., Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rotavirus Vaccine Market Shifts & Advancements
Bioprocess intensification and novel delivery platforms are fragmenting the long-stable oral live-attenuated paradigm, creating parallel development tracks for immunocompromised populations and tropical distribution constraints.
Single-use bioreactor systems are decomposing the traditional stainless-steel manufacturing footprint required for rotavirus vaccine bulk production. Emerging suppliers in India and Southeast Asia are adopting disposable technologies to bypass the capital barriers that protected incumbent manufacturers. This shift is decomposing the historical moat of dedicated facility investments, enabling faster scale-up but introducing new supply chain dependencies on single-use bag and filter suppliers.
EMA scientific opinion frameworks are expanding to encompass novel inactivated rotavirus platforms, creating a regulatory pathway parallel to WHO prequalification. European reference laboratories are establishing immunogenicity benchmarks that influence African and Asian national regulatory authorities. Pediatric hospitals in Germany and France are piloting these candidates for immunocompromised infant cohorts excluded from live-attenuated protocols.
Tender consolidation among Gavi-eligible countries is compressing supplier diversity as Ministries of Health pool procurement through the UNICEF Supply Division. National immunization programs in Nigeria, Pakistan, and the Democratic Republic of Congo are migrating from bilateral manufacturer contracts to multilateral aggregated purchasing. This concentration is visible most acutely in sub-Saharan Africa, where three countries now account for the majority of pentavalent volume allocated through Gavi co-financing mechanisms.
Global Rotavirus Vaccine Market Segmentation
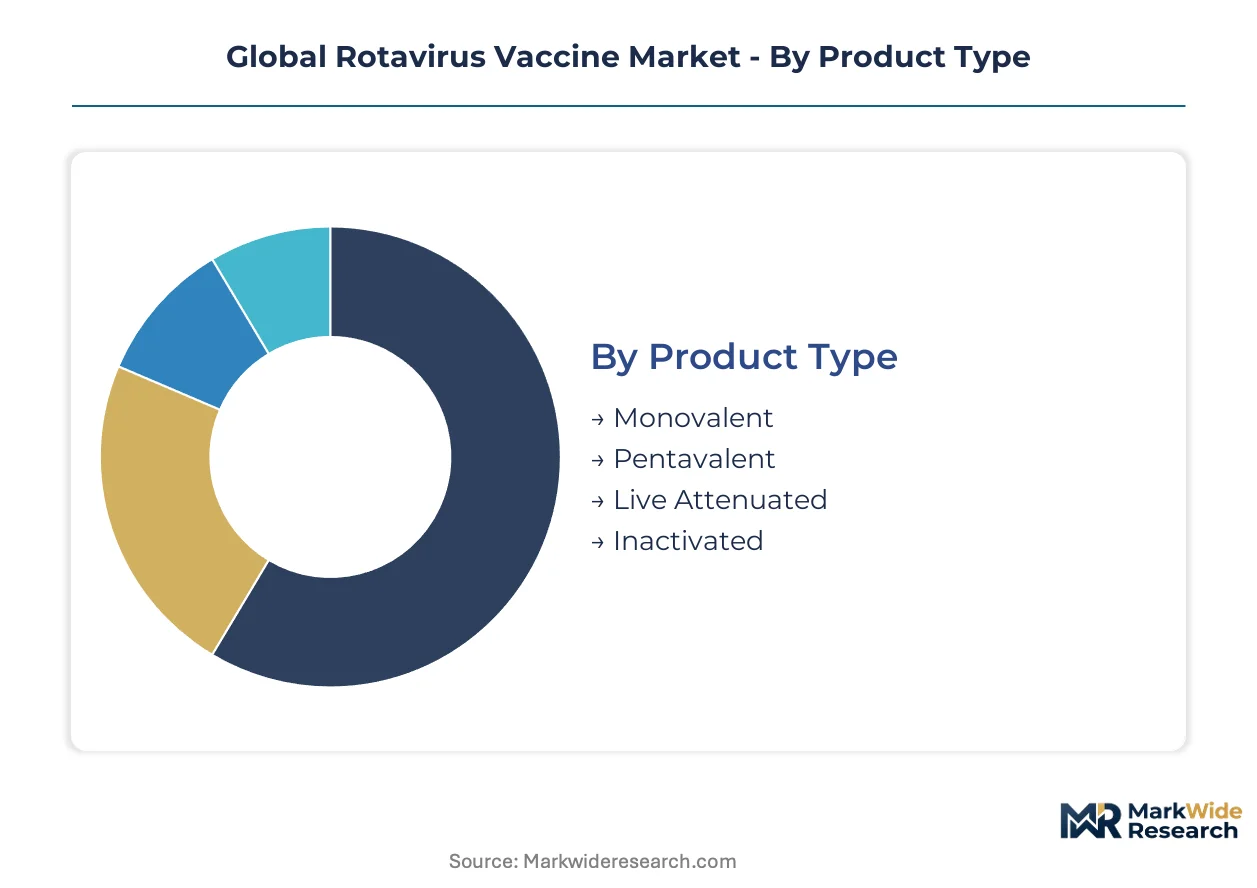
Rotavirus vaccine procurement channels fragment across technical specifications, delivery settings, and financing mechanisms. Each segmentation dimension carries distinct regulatory requirements and cold-chain obligations that determine manufacturer access and margin structure.
Product Type:
WHO prequalification pathways diverge sharply between live-attenuated and inactivated formats, with EMA scientific opinion frameworks now enabling parallel regulatory tracks for novel platforms.
- Pentavalent:These five-strain oral formulations induce broad serotype coverage through G1, G2, G3, G4, and P1A[8] components. Nigerian and Pakistani national immunization programs concentrate demand through Gavi co-financing tenders that lock in multi-year supply commitments. FDA lot-release backlogs for imported bulk materials compress effective shelf life in tropical storage corridors.
- Live Attenuated:Oral administration protocols dominate volume through established intestinal mucosal immunity induction. Sub-Saharan African Ministries of Health prioritize these formulations for routine infant schedules despite cold-chain dependencies that limit last-mile reach in rural Ethiopia and northern Kenya.
- Monovalent:Single-strain G1P[8] products occupy cost-sensitive procurement channels with simplified manufacturing footprints.
- Inactivated:Subunit and whole-virion candidates target HIV-exposed infant cohorts excluded from live-virus protocols in South African treatment programs.
Pentavalent products handle the majority of throughput; inactivated formats are expanding most quickly on share as immunocompromised indications open.
Application:
Delivery setting determines cold-chain intensity, with community outreach requiring heat-stable formulations that withstand ambient temperature excursions.
- Infant Immunization:Routine administration at 6 and 10 weeks aligns with WHO Expanded Program on Immunization schedules. Indian and Bangladeshi public health systems drive volume through birth-dose integration with pentavalent DTP-HepB-Hib combinations.
- Community Health Programs:Door-to-door campaigns in rural DRC and Chad deploy cold-box transport to overcome clinic infrastructure gaps. Gavi-funded outreach initiatives aggregate demand across dispersed populations previously unreachable through facility-based delivery.
- Pediatric Clinics:Urban hospital-based administration captures insured populations in middle-income settings.
- Travel Medicine:Pre-departure prophylaxis for infants visiting endemic regions occupies a narrow premium niche.
Infant immunization carries the volume concentration; community health programs are gaining share fastest as last-mile infrastructure expands.
End User:
Procurement authority determines pricing tier, with public tenders aggregating volume through UNICEF Supply Division mechanisms that compress supplier margins.
- Public Health Agencies:National immunization programs in Nigeria, Pakistan, and Indonesia control tender volumes through multi-year supply agreements. CDSCO-aligned manufacturers in India now compete for WHO prequalification slots previously reserved for Western incumbents.
- Non-Governmental Organizations:MSF and Gavi-eligible country partners fill coverage gaps in conflict-affected territories through emergency procurement channels. These actors prioritize heat-stable formulations that navigate broken cold chains in South Sudan and Yemen.
- Specialty Clinics:Private pediatric networks in urban India and Brazil serve insured populations outside public procurement.
- Immunization Centers:Government-run facilities process routine birth-dose administration in high-burden settings.
Public health agencies dominate throughput; non-governmental organizations are climbing fastest on share through emergency access mechanisms.
Distribution Channel:
Channel selection reflects financing source, with Gavi-eligible countries routing volume through centralized wholesale networks that aggregate demand across dispersed facilities.
- Wholesale Distributors:UNICEF Supply Division and national medical stores in Ghana and Kenya aggregate procurement across sub-national depots. These intermediaries manage cold-chain handoffs from manufacturer to district-level storage.
- Hospitals:Tertiary pediatric centers in South Africa and Thailand administer doses to insured populations through in-house pharmacy networks. Teaching hospitals in Cape Town and Bangkok pilot novel inactivated candidates for immunocompromised cohorts.
- Retail Pharmacies:Private purchase channels serve middle-income parents outside public immunization schedules in urban India and Mexico.
- Online Pharmacies:Direct-to-consumer platforms occupy a nascent niche for travel medicine indications.
Wholesale distributors manage the majority of throughput; hospital direct procurement is gaining share fastest as specialty indications fragment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany and Switzerland contrasts sharply with procurement compression across Gavi-eligible African markets, creating divergent margin structures for identical pentavalent formulations. Manufacturers navigate this asymmetry through tiered supply agreements that segment commercial and public channels.
Nigeria
National immunization programs drive pentavalent volume through Gavi co-financing mechanisms that aggregate demand across 36 states. NAFDAC alignment with WHO prequalification norms accelerates regulatory approval for heat-stable formulations. Lagos and Abuja medical stores anchor cold-chain distribution networks reaching northern Borno and Kano states.
India
Domestic manufacturers exploit CDSCO-WHO regulatory convergence to compete in export tenders previously reserved for Western suppliers. The PLI scheme for biotechnology incentivizes capacity expansion in bulk antigen production. Hyderabad and Pune clusters host fill-finish operations serving UNICEF Supply Division procurement.
United States
FDA lot-release oversight creates analytical bottlenecks that delay shipment release to developing countries, compressing effective shelf life. The Biomedical Advanced Research and Development Authority maintains stockpiles for domestic pediatric schedules. Maryland and Massachusetts biologics facilities anchor pentavalent production networks.
Brazil
ANVISA regulatory stringency shapes manufacturer access to Latin American tender markets beyond domestic procurement. The national immunization program integrates rotavirus doses into municipal health networks across São Paulo and Minas Gerais states. Butantan Institute partnerships enable technology transfer for regional supply security.
South Africa
HIV-exposed infant cohorts generate demand for inactivated candidates excluded from live-attenuated protocols in Gauteng and Western Cape treatment programs. SAHPRA scientific opinion frameworks influence regulatory acceptance across SADC member states. Cape Town teaching hospitals pilot novel subunit platforms for immunocompromised pediatric populations.
Global Rotavirus Vaccine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with established biologics networks defending pentavalent production against emerging suppliers adopting single-use manufacturing platforms. The market structure concentrates around three strategic tiers: Western multinationals with decades of WHO prequalification experience, Indian domestic manufacturers leveraging regulatory alignment for export eligibility, and Chinese state-backed entities serving captive regional demand. Competitive moves center on fill-finish capacity expansion and strategic technology licensing to bypass greenfield facility constraints.
Among Western-based biologics specialists, Merck & Co. Inc. and GlaxoSmithKline plc occupy positions exemplifying the prequalified incumbent archetype, while Serum Institute of India Private Limited represents the emerging supplier vector capitalizing on CDSCO-WHO regulatory convergence. These three entities anchor contrasting competitive strategies: dedicated facility networks versus disposable technology adoption versus vertically integrated antigen production.
| Leading Market Players |
|---|
| Serum Institute of India Private Limited |
| Sinovac Biotech Ltd. |
| Merck & Co. Inc. |
| China National Biotec Group Corporation |
| Biological E. Limited |
| GlaxoSmithKline plc |
| Bharat Biotech International Limited |
| Lanzhou Institute of Biological Products Co. Ltd. |
| Sanofi S.A. |
| Others |
Supply & Pricing Matrix
Multi-year offtake agreements with Gavi and UNICEF lock in supply access for pentavalent rotavirus vaccines while compressing manufacturer margins through volume commitments that span cold-chain delivery obligations across sub-Saharan Africa and South Asia.
Pricing Analysis
The customization-premium spread between WHO-prequalified formulations and non-prequalified alternatives widens as CDSCO-aligned Indian manufacturers enter tender markets. Three-tier pricing structure across premium, standard, and economy levels reflects cold-chain reliability grades and serotype coverage breadth. Cost compression in standard-tier supply is intensifying because Gavi's aggregated procurement pools negotiating leverage across Nigerian and Pakistani national programs. Public health agencies exhibit highest price sensitivity, while specialty clinics serving insured populations in urban India and Brazil show lowest.
Supply Chain Analysis
Inbound logistics costs through Durban and Mombasa port congestion elevate landed costs for bulk materials awaiting FDA lot-release, with container availability constraints on Asia-Africa trade lanes extending shipment timelines. Manufacturing concentrates in India, the United States, and Belgium for bulk antigen production, with fill-finish operations clustered in Hyderabad, Pune, and Massachusetts facilities. Production draws from porcine trypsin, cell culture media, and single-use bioreactor bags as critical inputs. Single-source vulnerability in dedicated aseptic lines for oral vaccine formats creates supply risk when contamination events trigger regulatory holds. Distribution runs through UNICEF Supply Division and national medical stores in Ghana and Kenya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic-era immunization backlogs, with cyclical momentum sustained by Gavi's replenished funding cycles and pent-up demand for routine infant schedules in low-income countries.
For Market Incumbents: Fortify fill-finish capacity through retrofit of existing biologics lines rather than greenfield construction, which faces extended capital recovery timelines under Gavi's compressed pricing. Lock in multi-year bulk supply agreements with Indian antigen producers to defend against emerging suppliers adopting single-use platforms. Prioritize WHO prequalification maintenance for heat-stable formulations as CDSCO-aligned competitors challenge tender access. For New Entrants and Emerging Players: Anchor in community health program channels where cold-box transport requirements favor heat-stable formulations that bypass incumbent cold-chain infrastructure advantages. Target South Sudan, Yemen, and Pacific Island territories where broken supply chains and conflict conditions exclude standard-tender suppliers. Pursue emergency procurement accreditation with MSF and Gavi's outbreak response mechanisms as the fastest route to volume. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with WHO-prequalified pentavalent portfolios locked into Gavi multi-year agreements. Five-to-ten year viability favors entities with backward integration into bulk antigen production rather than pure fill-finish operators exposed to margin compression. Watch for FDA lot-release backlog resolution as the inflection signal for effective shelf life extension and tropical distribution competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Accelerates tender access for heat-stable formulations targeting Nigerian and Pakistani procurement. |
| Fill-Finish Capacity Expansion | Addresses bottlenecks in oral vaccine aseptic lines incompatible with standard injectable equipment. |
| Single-Use Bioreactor Adoption | Enables Indian and Southeast Asian suppliers to bypass capital barriers protecting Western incumbents. |
| Inactivated Platform Development | Opens HIV-exposed infant segments excluded from live-attenuated protocols in South African programs. |
| Microarray Patch Delivery | Eliminates cold-chain dependence for Pacific Island and conflict-territory Ministries of Health. |
Research Methodology
Desk research of WHO prequalification listings, FDA lot-release records, and Gavi procurement disclosures preceded structured interviews with vaccine development executives, regulatory affairs leads at CDSCO and SAHPRA, UNICEF Supply Division procurement managers, and national immunization program coordinators in Nigeria and Pakistan. Primary fieldwork combined with secondary validation against clinical trial registries and tender documentation enabled bottom-up and top-down triangulation of manufacturer capacity and demand forecasts.
Variance decomposition across product type, application setting, end-user procurement authority, and distribution channel shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume modeling that incorporated Gavi co-financing trajectories, national immunization program expansion timelines, and cold-chain infrastructure investment flows. Forecast inputs included WHO policy guidance on vaccine interchangeability and EMA scientific opinion pathway adoption rates for novel inactivated platforms.
Underlying assumptions cover sustained Gavi funding commitment, CDSCO-WHO regulatory convergence continuity, and absence of major live-attenuated manufacturing contamination events, with deviation risk concentrated in FDA lot-release backlog persistence and novel subunit platform entry timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Global Topical Analgesic Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Global Janus Kinase Inhibitor (JAK) Market
Pharmaceuticals
Iceland Pharmaceutical Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Mtor Inhibitors Market
Pharmaceuticals
Second Generation Cephalosporins Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
North America Anticoccidial Drugs Market