
 Carbapenem Antibiotics Market | 2026-2036
Carbapenem Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Carbapenem Antibiotics Market Insights
Hospital formulary stewardship revenue is rewriting competitive dynamics for carbapenem suppliers. Pfizer Inc. leverages its institutional distribution networks to secure long-term supply contracts with major health systems. Merck & Co., Inc. anchors its position through sustained investment in resistance surveillance partnerships that guide formulary decisions. Aurobindo Pharma Ltd. competes on cost-engineered injectable volumes, particularly in emerging hospital markets where procurement is shifting toward tender-based sourcing.
Carbapenem antibiotics comprise a class of beta-lactam antimicrobials characterized by a fused bicyclic core with a carbon atom replacing sulfur at position 1, conferring stability against most serine beta-lactamases and extended-spectrum beta-lactamases; they are manufactured through semi-synthetic fermentation-derived pathways and serve as last-reserve therapies for severe nosocomial infections caused by resistant Enterobacteriaceae, Pseudomonas aeruginosa, and Acinetobacter species. Meropenem dominates product type revenue due to its established CNS penetration and broader formulary inclusion, while Ertapenem differentiates through once-daily outpatient dosing that captures shifting site-of-care economics toward outpatient centers. Injectable delivery mode sustains the largest margin pool given the severity of indications requiring inpatient administration, though intravenous formulations face growing biosimilar pressure across European tenders.
FDA antimicrobial development guidelines, EMA's Qualified Infectious Disease Product incentives, and WHO Essential Medicines List placement collectively shape carbapenem access, pricing, and clinical trial investment thresholds across major markets. The FDA's streamlined pathways for antibacterial therapies accelerate development timelines for novel agents, while WHO listing mandates national procurement prioritization in low- and middle-income health systems. Stakeholders must monitor resistance surveillance data from CDC and ECDC networks to anticipate formulary shifts before patent cliffs and generic entry reshape segment economics.
Market Dynamics
Hospital formulary stewardship programs are concentrating purchasing power into fewer institutional buyers, forcing carbapenem suppliers to restructure commercial operations around long-term supply contracts and resistance surveillance partnerships rather than traditional physician detailing.
Growth Catalysts
- Multidrug-resistant gram-negative surveillance networks:CDC and ECDC monitoring programs are expanding hospital testing protocols, creating mandatory demand for last-reserve antibiotics in documented resistance cases.
- Qualified Infectious Disease Product incentives:EMA's designation streamlines development pathways for novel carbapenems, reducing clinical trial investment thresholds for sponsors targeting resistant pathogens.
- India's hospital-acquired infection control mandates:National accreditation standards for tertiary care facilities are institutionalizing carbapenem availability in surgical and ICU protocols.
Market Restraints
- Fermentation-derived intermediate concentration:Active pharmaceutical ingredient production clusters in select Asian manufacturing zones, creating single-source vulnerability for semi-synthetic carbapenem synthesis.
- Antimicrobial susceptibility testing complexity:FDA's updated breakpoint requirements for beta-lactams extend validation timelines for diagnostic manufacturers, delaying formulary adoption of newer agents.
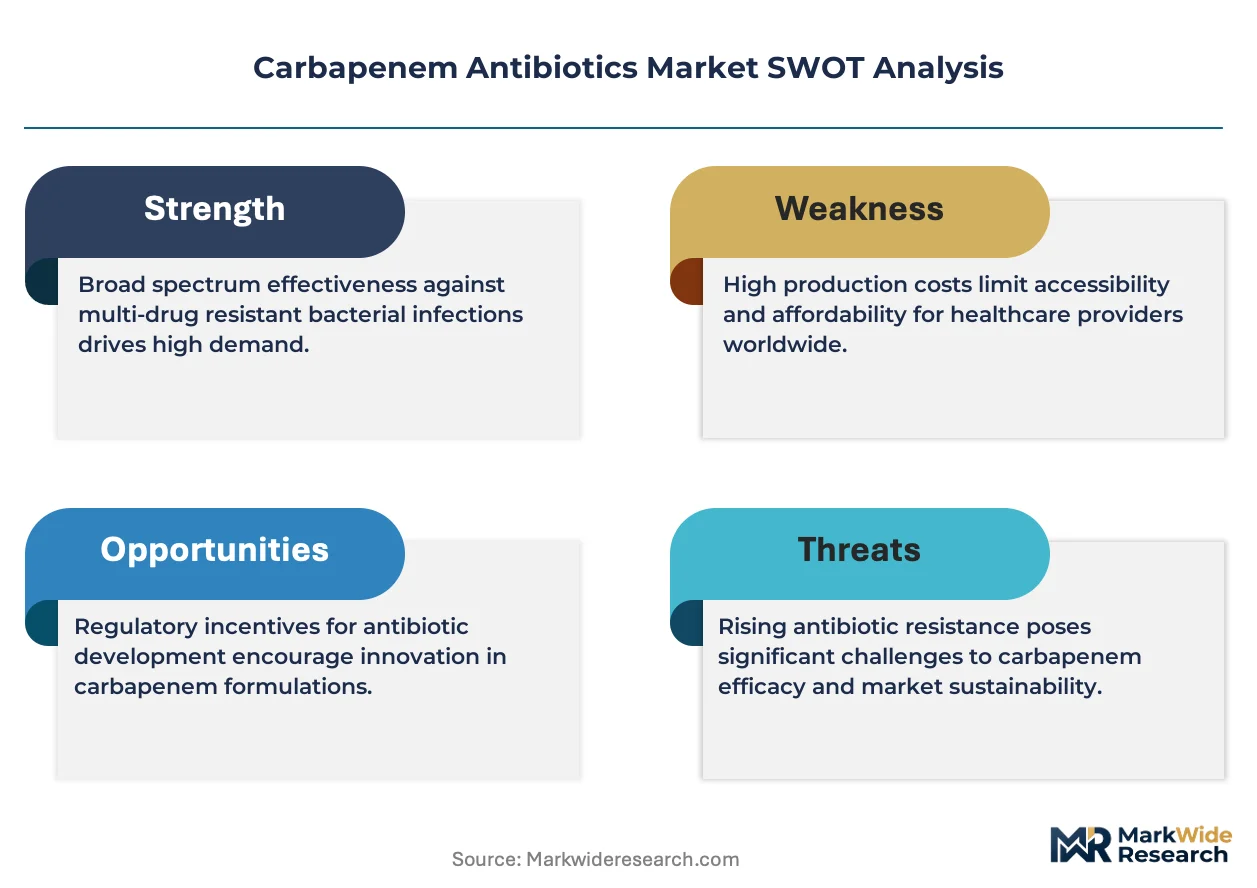
- Carbapenem-resistant Enterobacteriaceae (CRE) emergence:Resistance evolution in Klebsiella pneumoniae and Escherichia coli strains threatens clinical utility, compressing effective product lifecycles.
Strategic Opportunities
- Germany's DRG reimbursement evolution:Hospital payment reforms incorporating infection-related complication penalties are incentivizing prophylactic carbapenem use in high-risk surgical populations.
- Outpatient parenteral antimicrobial therapy (OPAT) expansion:Once-daily ertapenem formulations are capturing site-of-care migration from inpatient to infusion center settings.
- WHO Essential Medicines List procurement mandates:National health systems in low- and middle-income countries must prioritize listed antibiotics, creating tender opportunities for quality-assured generic injectables.
Industry Challenges
- Stability validation expertise shortage:Carbapenem susceptibility to hydrolysis demands specialized analytical chemistry capabilities that contract laboratories struggle to staff.
- Bioburden control capex requirements:Sterile injectable manufacturing upgrades to meet EMA's revised good manufacturing practice Annex 1 standards require substantial facility investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbapenem Antibiotics Market |
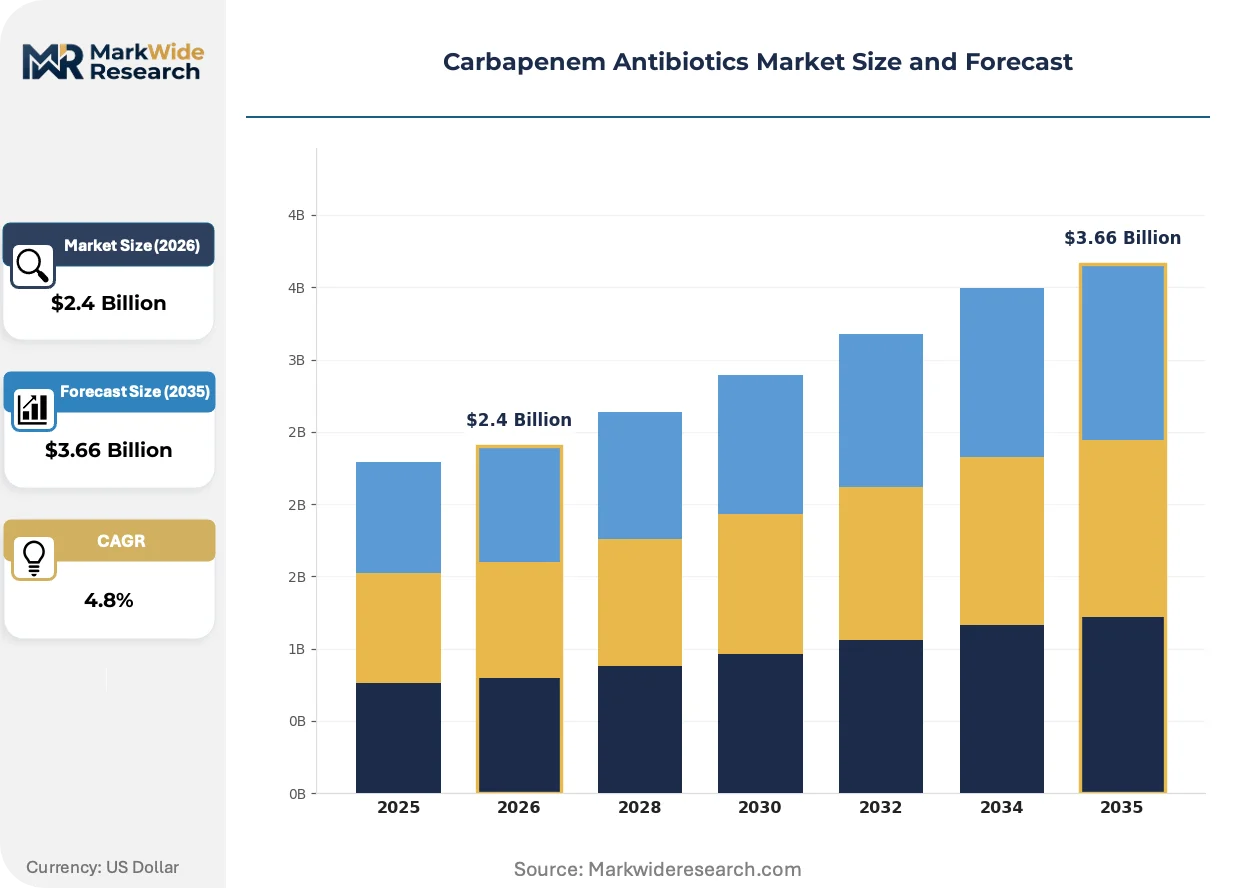
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imipenem, Meropenem, Ertapenem, Doripenem Delivery Mode: Injectable, Oral, Intravenous, Intramuscular End User: Hospitals, Clinics, Long-Term Care Facilities, Outpatient Centers Therapy Area: Infectious Diseases, Urinary Tract Infections, Pneumonia, Sepsis |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Aurobindo Pharma Ltd., Sumitomo Pharma, Fresenius Kabi, Sandoz International, Daewoong Pharmaceutical Co., Ltd., Gland Pharma Limited, ACS Dobfar S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbapenem Antibiotics Market Trends and Innovations
Carbapenem development and commercialization are being restructured by three intersecting forces: manufacturing technology compression, regulatory pathway redesign, and institutional purchasing consolidation.
Continuous manufacturing platforms for beta-lactam synthesis are collapsing batch-to-batch variability in fermentation-derived intermediates. Pfizer and Merck are piloting integrated flow chemistry systems at select production sites, reducing solvent waste and shortening cycle times from weeks to days. This compression is enabling just-in-time inventory models that reduce working capital requirements for hospital supply contracts.
FDA's streamlined antibacterial development pathways under the Limited Population Pathway for Antibacterial and Antifungal Drugs (LPAD) framework are accelerating approval timelines for carbapenems targeting resistant pathogens. The industrial consequence is earlier revenue recognition for sponsors willing to accept smaller initial indications. EMA's parallel adaptive licensing pilots are creating competitive pressure for US sponsors to pursue simultaneous European submissions.
Hospital procurement consortia are consolidating antibiotic purchasing across multi-state health systems in the United States, displacing individual hospital formulary autonomy. These centralized buying entities are demanding resistance surveillance data and total cost-of-infection metrics as contract prerequisites. The shift is most visible in California and Texas, where integrated delivery networks now control carbapenem allocation for dozens of affiliated facilities.
Carbapenem Antibiotics Market Segmentation
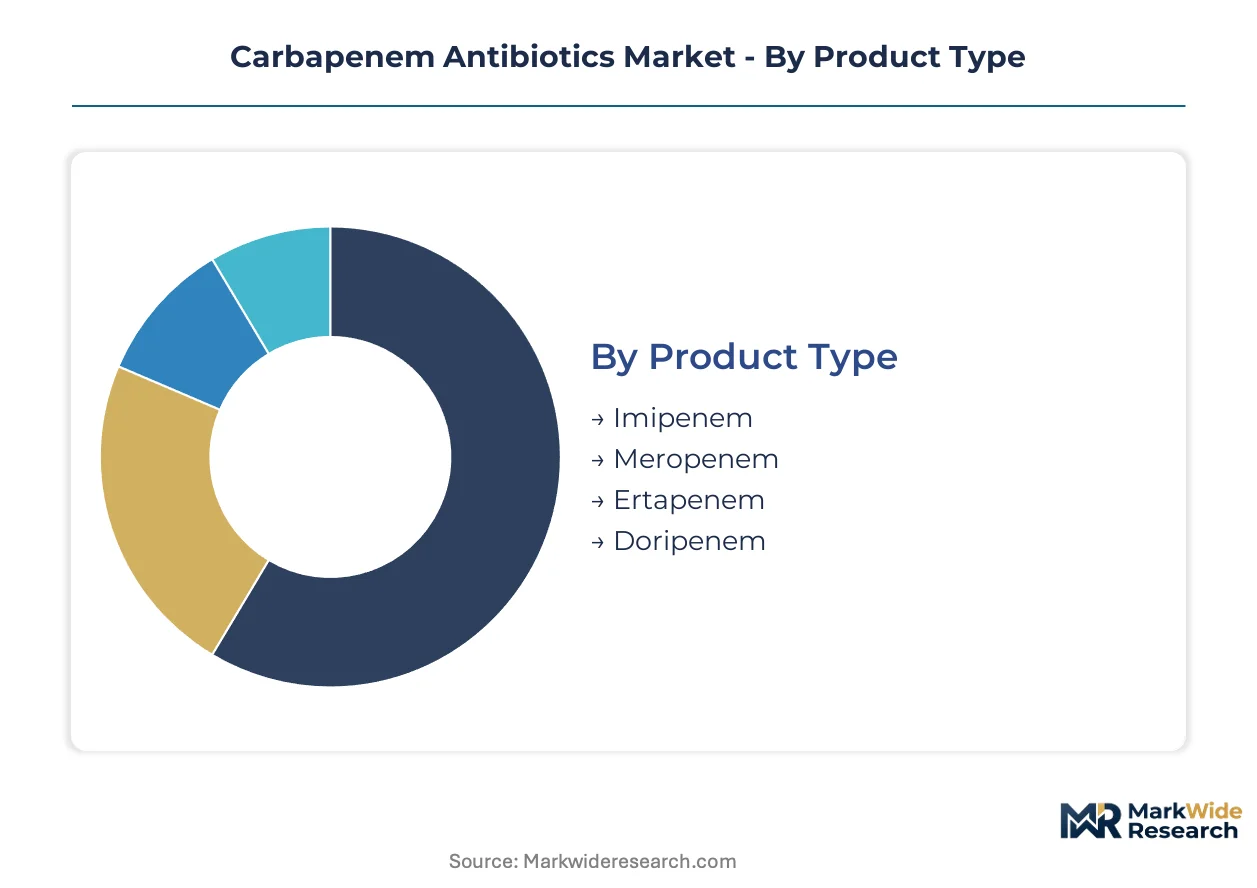
Carbapenem commercialization requires precise segment targeting because hospital formulary committees evaluate agents across multiple clinical and operational dimensions simultaneously. Product selection, delivery logistics, and site-of-care economics interact to determine contract viability and margin capture.
Product Type:
After-sales service intensity varies sharply across carbapenem generations, with newer agents demanding resistance surveillance partnerships and older molecules requiring only standard distribution support.
- Imipenem:The first-approved carbapenem combines a beta-lactam core with cilastatin to inhibit renal dehydropeptidase degradation. Demand concentrates in India and Southeast Asia where cost-sensitive hospital tenders favor established generic injectables.
- Meropenem:A pyrrolidine-substituted carbapenem with superior CNS penetration distinguishes itself in meningitis protocols and neurosurgical prophylaxis. United States academic medical centers drive volume through resistance-guided formulary inclusion.
- Ertapenem:Once-daily dosing with a 1-beta-methyl substituent conferring metabolic stability enables outpatient parenteral therapy expansion. Germany and the United Kingdom lead adoption as infusion center networks mature.
- Doripenem:The most recently approved agent offers comparable Pseudomonas coverage with reduced seizure liability versus imipenem. Japan's PMDA accelerated review pathway supported initial Asian market entry.
Meropenem holds the largest share; momentum sits with Ertapenem.
Delivery Mode:
Manufacturing complexity and cold-chain requirements stratify margin structures across administration routes, with sterile injectable production demanding substantially higher capital commitment.
- Injectable:Lyophilized powder vials requiring reconstitution dominate hospital procurement due to extended shelf stability and flexible dosing. EMA's Annex 1 GMP revisions are compressing supplier margins through facility upgrade mandates.
- Oral:No clinically relevant oral carbapenem formulations exist due to beta-lactam instability in gastric acid and poor intestinal permeability. This segment remains commercially dormant.
- Intravenous:Ready-to-use infusion bags capture premium pricing in United States integrated delivery networks where nursing labor costs dominate total therapy economics.
- Intramuscular:Limited clinical utility for carbapenems given the volume requirements and pain profile; occasional use in resource-limited settings without IV infrastructure.
Intravenous formulations command the highest unit economics; ready-to-use presentations are climbing the fastest.
End User:
Procurement sophistication and formulary autonomy determine contract structures, with consolidated health systems extracting steeper price concessions than independent facilities.
- Hospitals:Tertiary care institutions with active antimicrobial stewardship programs generate the majority of carbapenem consumption through ICU and oncology protocols. India's National Accreditation Board mandates carbapenem availability for surgical site infection prevention.
- Clinics:Outpatient infusion centers in Texas and California are expanding ertapenem volumes as site-of-care migration accelerates.
- Long-Term Care Facilities:Skilled nursing facilities face regulatory pressure to limit broad-spectrum use; carbapenem access typically requires infectious disease consultation.
- Outpatient Centers:Ambulatory surgery and oncology infusion sites represent the fastest-expanding addressable market for once-daily agents with simplified monitoring requirements.
Hospitals retain dominant volume; outpatient centers are gaining share fastest.
Therapy Area:
Resistance surveillance data and mortality risk stratification guide formulary placement across infectious disease indications, with sepsis protocols commanding the most aggressive empirical coverage.
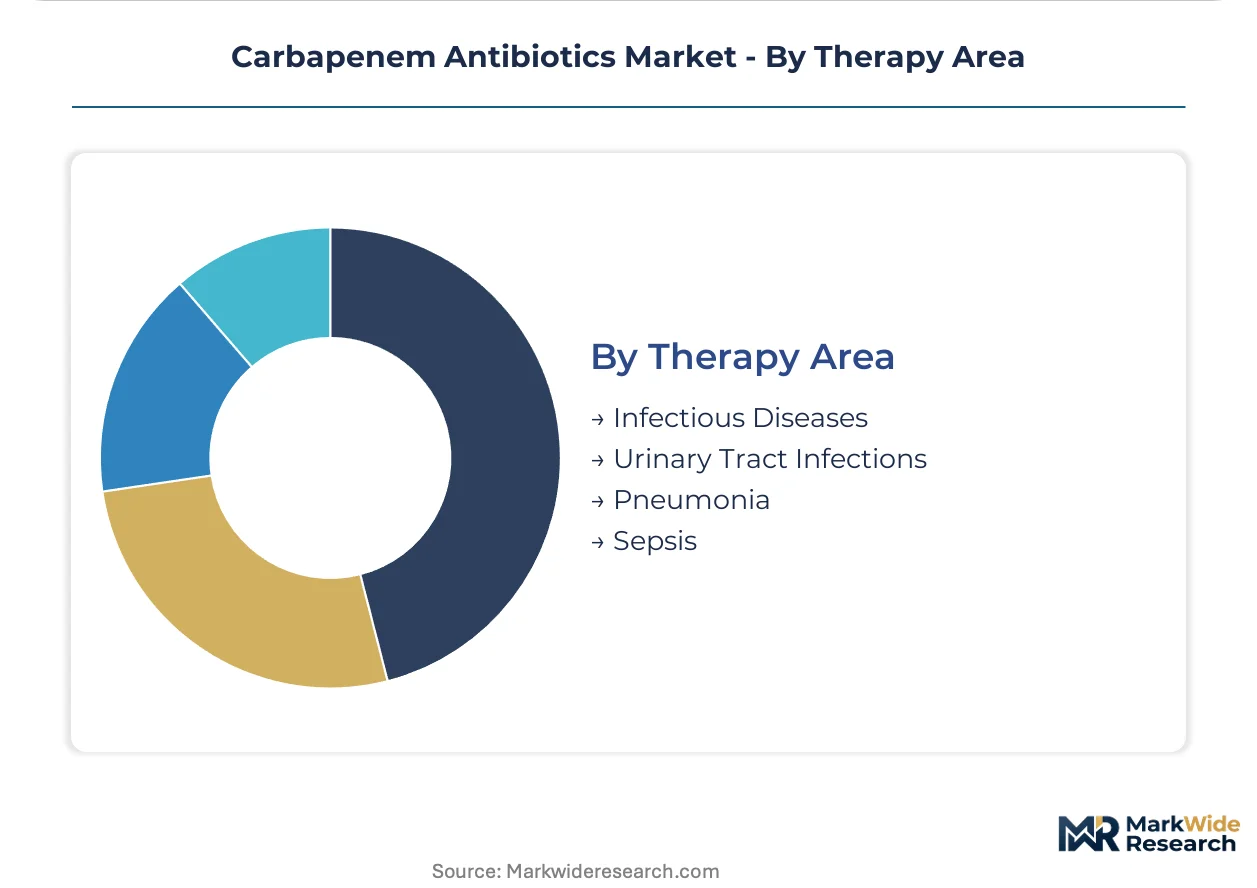
- Infectious Diseases:Broad-spectrum empirical therapy for undifferentiated febrile illness in neutropenic patients sustains baseline demand across all carbapenem agents. CDC resistance tracking networks inform hospital-specific formulary restrictions.
- Urinary Tract Infections:Complicated pyelonephritis and catheter-associated infections with extended-spectrum beta-lactamase producers drive ertapenem selection due to renal excretion and once-daily convenience.
- Pneumonia:Hospital-acquired and ventilator-associated pneumonia protocols favor meropenem for antipseudomonal coverage in cystic fibrosis and bronchiectasis populations.
- Sepsis:Surviving Sepsis Campaign guidelines recommend carbapenems for septic shock with suspected gram-negative resistance, creating time-critical demand concentrated in emergency departments.
Infectious diseases captures the largest indication footprint; sepsis protocols are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis for carbapenems clusters in select Asian manufacturing zones, creating geographic vulnerability that shapes procurement security planning across hospital systems worldwide.
United States
Academic medical centers in Massachusetts and California drive meropenem consumption through resistance-guided formulary protocols. FDA's streamlined antibacterial development pathways accelerate sponsor timelines for novel agents targeting resistant pathogens. Pfizer maintains institutional distribution networks that secure multi-year supply contracts with integrated delivery networks across the Midwest and Southeast.
Germany
Hospital payment reforms incorporating infection-related complication penalties incentivize prophylactic carbapenem deployment in Bavarian and North Rhine-Westphalian surgical populations. EMA's Qualified Infectious Disease Product designation reduces clinical trial investment thresholds for sponsors. Merck anchors its European position through sustained resistance surveillance partnerships that guide formulary committee decisions in Berlin and Hamburg health systems.
India
National accreditation standards for tertiary care facilities in Maharashtra and Karnataka institutionalize carbapenem availability in surgical and ICU protocols. CDSCO's tightened antimicrobial susceptibility testing requirements extend validation timelines for diagnostic manufacturers. Aurobindo Pharma competes on cost-engineered injectable volumes as procurement shifts toward tender-based sourcing in Delhi-NCR and Tamil Nadu hospital networks.
Japan
PMDA's accelerated review pathway supported initial doripenem market entry for antipseudomonal coverage in Tokyo and Osaka medical centers. METI's pharmaceutical manufacturing standards enforce bioburden control requirements that compress margins for sterile injectable producers. Sumitomo Pharma occupies a position within the domestic resistance surveillance ecosystem that informs hospital formulary placement.
United Kingdom
Infusion center networks in Greater London and the Midlands expand ertapenem volumes as site-of-care migration accelerates toward outpatient settings. EMA's updated clinical trial guidance for antibiotics tightens approval pathways for sponsors seeking European market access. Fresenius Kabi and Sandoz International sit within the generic injectable tier supplying National Health Service procurement frameworks.
Carbapenem Antibiotics Market Competitive Landscape
Research-intensive multinationals and cost-engineered generic specialists split the market across distinct value capture tiers. Hospital formulary stewardship programs concentrate purchasing power into fewer institutional buyers, forcing suppliers to restructure commercial operations around long-term supply contracts and resistance surveillance partnerships. Three archetypes dominate: integrated pharmaceutical conglomerates with institutional distribution networks, fermentation-capable API manufacturers with backward integration into sterile injectable production, and tender-focused generic houses competing on volume scale. Competitive moves center on manufacturing technology licensing and geographic expansion through resistance surveillance partnerships.
Within the research-intensive tier, Pfizer Inc. and Merck & Co., Inc. exemplify the integrated pharmaceutical conglomerate archetype through their institutional distribution networks and sustained investment in resistance surveillance infrastructure. Aurobindo Pharma Ltd. represents the cost-engineered generic specialist archetype, competing on volume scale in emerging hospital markets where procurement is shifting toward tender-based sourcing. These three companies anchor the competitive structure across distinct geographic and pricing tiers without overlapping strategic positioning.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Aurobindo Pharma Ltd. |
| Sumitomo Pharma |
| Fresenius Kabi |
| Sandoz International |
| Daewoong Pharmaceutical Co., Ltd. |
| Gland Pharma Limited |
| ACS Dobfar S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Fermentation-derived intermediate concentration in select Asian manufacturing zones creates single-source vulnerability that simultaneously compresses economy-tier margins through supply insecurity and sustains premium-tier pricing power through scarcity premiums. This structural dependency forces hospital procurement consortia to accept long-term contract premiums for qualified suppliers while tender-based sourcing in emerging markets extracts cost concessions from volume-dependent generic houses.
Pricing Analysis
EMA's Annex 1 GMP revisions dictate the pricing tier structure across carbapenem injectables. Three-tier pricing separates originator brands with resistance surveillance partnerships from standard-tier qualified generics with CDSCO certification from economy-tier tender-sourced volumes lacking comprehensive stability validation. Price differentiation stems from bioburden control compliance grade and after-sales service intensity. Cost compression in the economy tier is intensifying because EMA facility upgrade mandates eliminate marginal producers. Tender-based hospital procurement in India exhibits highest price sensitivity; United States integrated delivery networks prioritize total cost-of-infection metrics over unit price.
Supply Chain Analysis
Extended payment terms from hospital procurement consortia force API manufacturers to utilize supply-chain finance facilities, concentrating working capital risk with fermentation-capable suppliers. Active pharmaceutical ingredient synthesis clusters in India, China, and South Korea, drawing from fermentation-derived beta-lactam cores and specialized solvent systems. Single-source vulnerability for semi-synthetic carbapenem intermediates rests on geographic concentration of bioreactor capacity. Distribution runs through institutional distribution networks for research-intensive multinationals and tender-based government procurement frameworks for generic specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbapenem antibiotics represent a defensive-moat market where regulatory entrenchment through antimicrobial susceptibility testing validation and sterile injectable GMP certification creates substantial switching costs for hospital formulary committees.
For Market Incumbents: Entrench formulary position by deepening resistance surveillance partnerships with CDC and ECDC networks that guide empirical therapy protocols. Secure backward integration into fermentation-derived intermediate production to eliminate single-source API vulnerability. Expand capacity addition in India to capture tender-based procurement growth as CDSCO tightens antimicrobial susceptibility testing requirements.
For New Entrants and Emerging Players: Outpatient parenteral antimicrobial therapy infusion centers in Germany and the United Kingdom represent the most penetrable entry point for once-daily ertapenem formulations. Quality-assured generic injectables for WHO Essential Medicines List procurement in low- and middle-income health systems offer tender-based volume scale. Pursue go-to-market angles through resistance surveillance data partnerships that differentiate from commodity generic positioning.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation-capable API manufacturers with sterile injectable GMP compliance. Long-term viability over a multi-year window hinges on regulatory entrenchment through EMA Annex 1 certification and FDA streamlined antibacterial pathway navigation. Monitor resistance surveillance data from CDC and ECDC networks as the inflection indicator for formulary shift timing before patent cliffs reshape segment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Resistance Surveillance Partnership | CDC and ECDC data access guides hospital formulary placement decisions before generic entry. |
| Continuous Manufacturing Scale-Up | Pfizer and Merck pilot flow chemistry systems that reduce solvent waste and shorten cycle times. |
| EMA Annex 1 GMP Certification | Facility upgrade mandates eliminate marginal producers and consolidate supply among qualified manufacturers. |
| Outpatient Parenteral Therapy Expansion | Ertapenem once-daily dosing captures site-of-care migration from inpatient to infusion center settings. |
| WHO Essential Medicines List Procurement | National health systems in low- and middle-income countries must prioritize listed antibiotics in tenders. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through primary interviews with hospital formulary directors, antimicrobial stewardship program leads, sterile injectable manufacturing executives, and regulatory affairs specialists at CDSCO, FDA, and EMA. Secondary validation drew from FDA antibacterial therapy filings, EMA Qualified Infectious Disease Product designations, ClinicalTrials.gov carbapenem protocol registries, and hospital procurement database extracts. Bottom-up volume triangulation across product type, delivery mode, and end-user segments was cross-checked against top-down market sizing from API production capacity assessments.
Calibration against historical formulary adoption curves and resistance surveillance data trends shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included carbapenem generation, administration route, therapy area indication, hospital accreditation tier, and regional regulatory cluster. CAGRs were derived from epidemiological projections of multidrug-resistant gram-negative infection incidence and hospital payment reform elasticity estimates. Forecast inputs incorporated CDC resistance tracking network expansion rates and EMA clinical trial guidance revision impacts on sponsor investment thresholds.
Macroeconomic conditions sit as an overlay; deviation in hospital reimbursement rates, antimicrobial susceptibility testing equipment capex cycles, or fermentation input commodity prices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and resistance evolution patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Asia-Pacific Cancer Vaccines Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Oral Anti-Diabetic Drugs Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Global Anti-Neoplastic Agents Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Calcium Channel Blocker Market