
 Global Glaucoma Therapeutics Market | 2026-2036
Global Glaucoma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glaucoma Therapeutics Market Foresight
Ophthalmic clinical trial specialist staffing is collapsing across Western Europe and Japan, forcing sponsors to consolidate Phase III sites in fewer countries. Novartis AG leverages its integrated eye-care infrastructure to sustain investigator relationships in high-enrollment geographies. AbbVie Inc. anchors its glaucoma franchise through Allergan-legacy channel control in Latin American markets. Santen Pharmaceutical Co., Ltd. dominates Japanese regulatory navigation with localized manufacturing and PMDA-aligned quality systems.
Glaucoma therapeutics comprise pharmaceutical agents and drug-device combinations that modulate aqueous humor dynamics through trabecular meshwork enhancement, uveoscleral outflow promotion, or ciliary body secretion suppression, with intraocular pressure reduction serving as the validated surrogate endpoint for neuroretinal preservation. Prostaglandin analogues occupy the largest revenue pool due to once-daily dosing adherence advantages and extensive generic erosion at the base of the market. Sustained-release implants represent the fastest-growing delivery mode as physicians shift toward bimatoprost and travoprost depot formulations that eliminate topical administration burden. Combination drugs compete against sequential monotherapy through fixed-dose latanoprost-timolol and brimonidine-timolol offerings that reduce preservative exposure and copay complexity.
FDA ophthalmic drug guidance, EMA MDR requirements for implantable devices, and PMDA sakigake designation pathways collectively determine market access timelines and clinical evidence standards for new entrants. REACH chemical safety obligations and RoHS substance restrictions shape excipient selection and manufacturing location decisions for European-bound products. Stakeholders must monitor sustained-release implant durability data against competing minimally invasive glaucoma surgery adoption curves to calibrate pipeline prioritization and partnership strategies.
Market Dynamics
Sustained-release implant technology is compressing the traditional topical drop paradigm, forcing incumbents to restructure R&D portfolios around depot formulation durability and surgical placement workflows.
Growth Catalysts
- FDA Accelerated Approval Pathways:Ophthalmic device sponsors exploit breakthrough and priority review designations to compress Phase III timelines for sustained-release implants.
- Trabecular Meshwork Enhancement:Micro-invasive stent technologies expand the addressable patient pool beyond pharmaceutical responders into early surgical intervention.
- Germany:Statutory health insurance reimbursement reforms for implantable ocular devices accelerate physician adoption in outpatient clinic settings.
Market Restraints
- Preservative-Free Formulation Costs:Benzalkonium chloride elimination requires specialized packaging and shorter shelf lives, elevating manufacturing overhead.
- Western Europe Investigator Scarcity:Collapsing ophthalmic clinical trial specialist staffing forces sponsors to consolidate Phase III sites, lengthening enrollment timelines.
- Generic Erosion at Market Base:Prostaglandin analogue commoditization compresses pricing power for first-line topical therapies across mature markets.
Strategic Opportunities
- Japan PMDA Sakigake Designation:First-in-Japan approval incentives reward localized manufacturing investment with expedited regulatory review.
- Combination Drug Fixed-Dose Formulations:Latanoprost-timolol and brimonidine-timolol offerings reduce copay complexity and preservative exposure.
- Latin American Channel Control:Direct distribution infrastructure in Brazil and Mexico bypasses fragmented wholesale networks for sustained-release implants.
Industry Challenges
- Ocular Surgical Training Bottlenecks:Canaloplasty and micro-stent placement require specialized skills that residency programs are not scaling to match implant launch timelines.
- REACH Excipient Compliance:Chemical safety documentation obligations for European-bound products force reformulation of established preservative systems.
- Implant Durability Data Generation:Extended follow-up requirements for sustained-release depot formulations strain post-market surveillance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glaucoma Therapeutics Market |
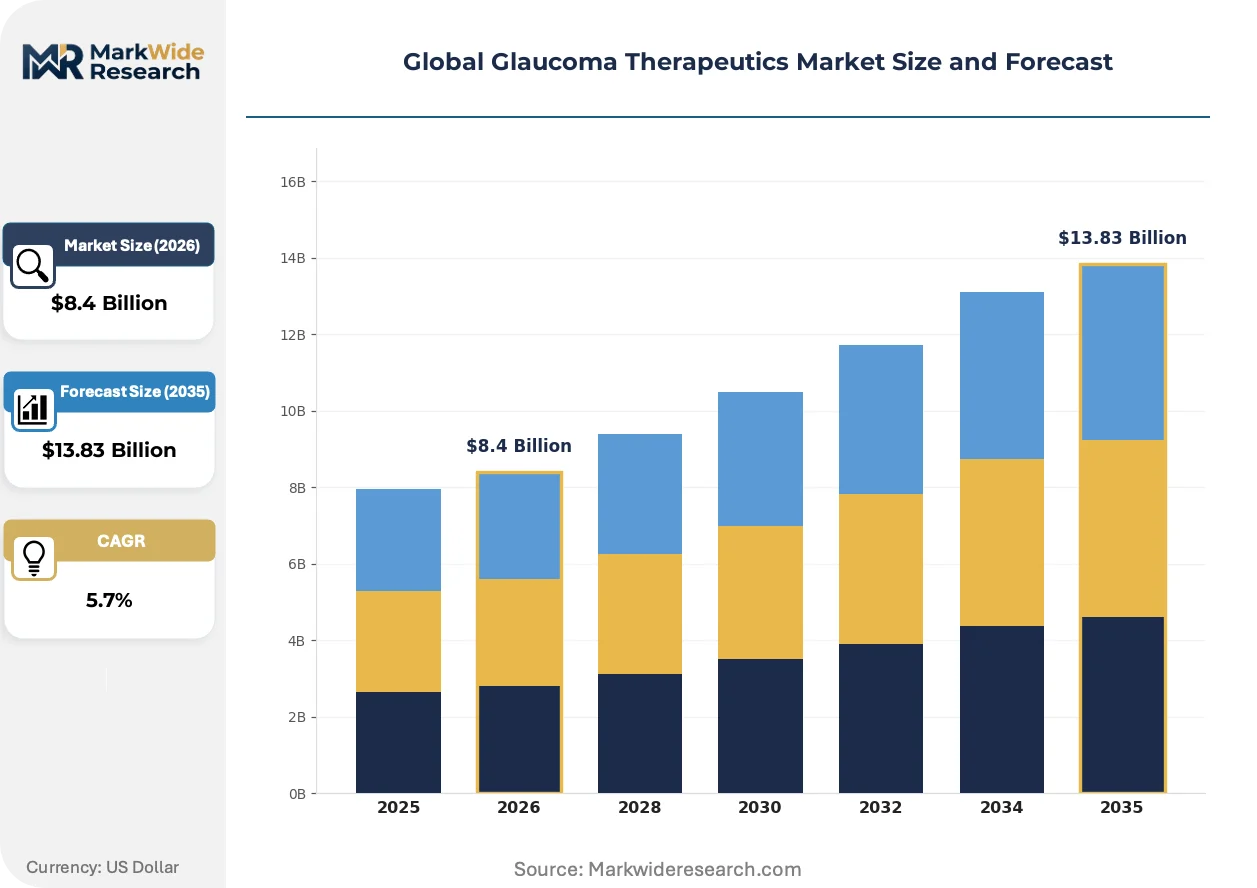
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prostaglandin Analogues, Beta Blockers, Alpha Agonists, Carbonic Anhydrase Inhibitors, Combination Drugs Therapy Area: Open-Angle Glaucoma, Angle-Closure Glaucoma, Normal-Tension Glaucoma, Congenital Glaucoma End User: Ophthalmology Clinics, Eye Hospitals, Ambulatory Surgical Centers, Research Institutes Delivery Mode: Topical Solutions, Oral Medications, Injectable Formulations, Sustained-Release Implants |
| Companies Covered | Novartis AG, AbbVie Inc., Merck & Co., Inc., Pfizer Inc., Santen Pharmaceutical Co., Ltd., Alcon Inc., Bausch + Lomb Corporation, Aerie Pharmaceuticals Inc., Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glaucoma Therapeutics Market Shifts & Advancements
Biodegradable polymer matrices and precision injection systems are redefining the competitive frontier, separating device-capable manufacturers from pure pharmaceutical players.
Bimatoprost and travoprost sustained-release implants are displacing daily topical administration in ophthalmology clinics across the United States and Germany. Physicians in high-volume screening centers are prioritizing depot formulations that eliminate adherence failure risks. The shift is compressing market share for conventional prostaglandin analogue drops in first-line therapy positioning.
EMA MDR requirements for implantable devices impose clinical evidence standards that extend pre-market approval timelines for new ocular device entrants. Manufacturers must demonstrate biocompatibility and long-term safety data that exceed prior medical device directives. Japanese and US sponsors with existing quality management systems are adapting faster than mid-tier European competitors.
Service unbundling is fragmenting the traditional pharmaceutical-rep relationship in ophthalmology practices. Clinics in Japan and Germany are contracting directly with implant manufacturers for surgical training and inventory management. The disintermediation is most visible in urban screening centers where physician networks consolidate procurement decisions.
Global Glaucoma Therapeutics Market Segmentation
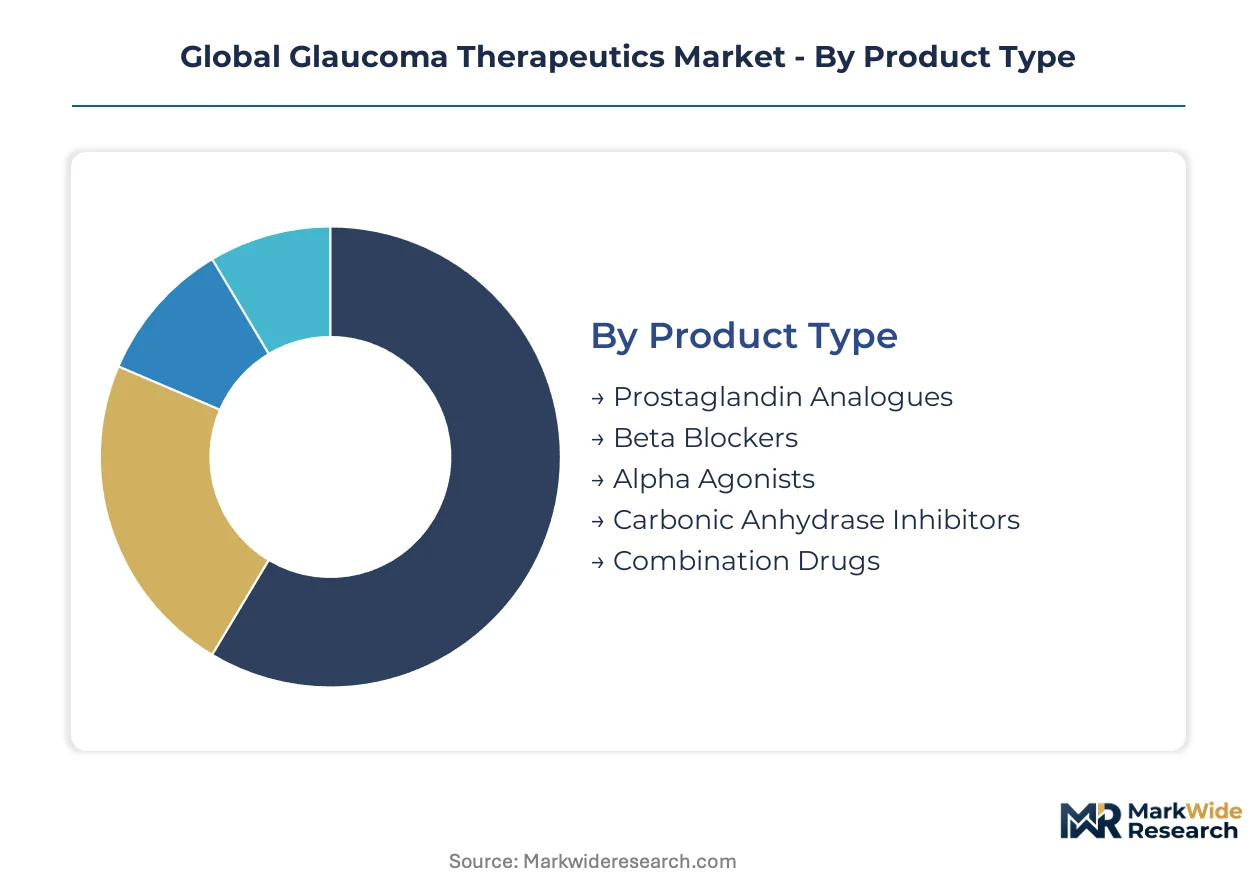
Glaucoma therapeutics segmentation reveals divergent margin structures across delivery technologies and therapy positioning. Pharmaceutical incumbents and device manufacturers calibrate portfolio allocation based on reimbursement tiering and surgical workflow integration.
Product Type:
Margin pools concentrate in combination formulations and prostaglandin analogues, where dosing adherence advantages sustain pricing power against generic erosion.
- Prostaglandin Analogues:Once-daily latanoprost, bimatoprost, and travoprost formulations modulate uveoscleral outflow through FP receptor agonism. Demand clusters in United States and Germany where aging populations drive screening volumes and first-line therapy positioning.
- Combination Drugs:Fixed-dose latanoprost-timolol and brimonidine-timolol offerings reduce preservative exposure and copay complexity for polypharmacy patients. Ophthalmology clinics in Japan are expanding adoption as PMDA reimbursement pathways favor simplified regimens.
- Beta Blockers:Timolol and carteolol solutions suppress aqueous humor production through ciliary body beta-adrenergic blockade.
- Alpha Agonists:Brimonidine formulations provide dual-mechanism pressure reduction via aqueous suppression and uveoscleral enhancement.
- Carbonic Anhydrase Inhibitors:Dorzolamide and brinzolamide target enzyme-mediated bicarbonate transport in ciliary epithelium.
Prostaglandin Analogues hold installed capacity. Combination Drugs is rotating up the share rankings.
Therapy Area:
Volume distribution skews heavily toward open-angle presentations, where chronic management protocols create recurring revenue streams.
- Open-Angle Glaucoma:Trabecular meshwork dysfunction drives elevated intraocular pressure in the predominant adult-onset form. Sustained-release implants are displacing daily drops in United States ophthalmology clinics seeking adherence failure mitigation.
- Angle-Closure Glaucoma:Pupil-block mechanisms require rapid pressure reduction through laser iridotomy or surgical intervention. Eye hospitals in Japan concentrate specialized surgical capacity for acute presentations.
- Normal-Tension Glaucoma:Optic neuropathy progression occurs despite statistically normal pressure ranges.
- Congenital Glaucoma:Trabeculodysgenesis presents in infancy with elevated pressure and corneal enlargement.
Open-Angle Glaucoma dominates prescription volumes. Angle-Closure Glaucoma commands premium surgical pricing.
End User:
Procurement authority is consolidating in high-volume ophthalmology clinics that integrate screening, diagnosis, and surgical intervention.
- Ophthalmology Clinics:Outpatient settings combine diagnostic imaging, medical management, and micro-invasive surgical procedures. Germany's statutory health insurance reforms accelerate implant adoption in these consolidated settings.
- Eye Hospitals:Tertiary centers manage complex cases requiring trabeculectomy or glaucoma drainage device implantation.
- Ambulatory Surgical Centers:Standalone facilities specialize in cataract-glaucoma combination procedures.
- Research Institutes:Academic medical centers generate durability data for sustained-release formulations.
Ophthalmology Clinics capture the steepest expansion trajectory. Eye Hospitals retain complex case referral networks.
Delivery Mode:
Technology transitions are compressing the traditional topical paradigm as surgical placement workflows mature.
- Sustained-Release Implants:Biodegradable polymer matrices enable bimatoprost and travoprost depot delivery over 4-6 month intervals. Physicians in United States and Germany prioritize these formulations to eliminate patient adherence failure.
- Topical Solutions:Eye drops remain the volume base despite preservative toxicity concerns and dosing burden.
- Oral Medications:Systemic carbonic anhydrase inhibitors serve acute pressure reduction or surgical bridging scenarios.
- Injectable Formulations:Intracameral agents provide perioperative pressure control.
Topical Solutions retain volume leadership. Sustained-Release Implants are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor the United States as the dominant geography, with reimbursement reforms in Germany and regulatory navigation capabilities in Japan creating concentrated demand clusters across three distinct regulatory jurisdictions.
United States
Aging demographics and elevated screening volumes drive prostaglandin analogue consumption in ophthalmology clinics. FDA breakthrough device designation compresses Phase III timelines for sustained-release implant sponsors. High-volume screening centers in California and New York prioritize bimatoprost depot formulations to eliminate patient adherence failures.
Germany
Statutory health insurance reimbursement reforms accelerate outpatient clinic adoption of implantable ocular devices. EMA MDR requirements for biocompatibility documentation extend pre-market approval timelines for new device entrants. The Rhine-Ruhr metropolitan cluster concentrates specialized ophthalmic surgical training capacity for micro-invasive stent placement.
Japan
PMDA sakigake designation rewards localized manufacturing investment with expedited regulatory review for first-in-Japan approvals. Aging population dynamics mirror US screening volume patterns, concentrating demand in urban ophthalmology networks. The Kanto region around Tokyo anchors Santen Pharmaceutical's quality systems and PMDA-aligned manufacturing infrastructure.
United Kingdom
NHS England commissioning frameworks for ophthalmology services reshape procurement authority toward consolidated clinic networks. MHRA post-Brexit regulatory autonomy creates divergence from EMA MDR implementation timelines. London and the Southeast concentrate private ophthalmology capacity for sustained-release implant surgical training.
Brazil
Direct distribution infrastructure bypasses fragmented wholesale networks for sustained-release implant penetration in Latin America's largest market. ANVISA regulatory pathways for implantable devices require localized clinical evidence generation. São Paulo anchors AbbVie's Allergan-legacy channel control and specialist ophthalmology referral networks.
Global Glaucoma Therapeutics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum commanding eye-care infrastructure and regulatory navigation capabilities that mid-tier competitors cannot replicate. The market structure reflects pharmaceutical-device convergence, where depot formulation expertise separates scalable players from pure topical manufacturers. Three archetypes dominate: integrated eye-care conglomerates with surgical workflow control, prostaglandin analogue specialists defending against generic erosion, and sustained-release implant pure-plays betting on adherence failure mitigation. Competitive moves concentrate on Phase III site consolidation to offset Western Europe investigator scarcity, and localized manufacturing investment to capture PMDA sakigake incentives.
Within the integrated conglomerate tier, Novartis AG and AbbVie Inc. exemplify divergent geographic anchoring strategies. Novartis leverages Swiss-based infrastructure to sustain investigator relationships across high-enrollment geographies in the United States and Germany. AbbVie occupies a position shaped by Allergan-legacy channel dominance in Latin American markets, particularly Brazil and Mexico. Santen Pharmaceutical Co., Ltd. represents the localized regulatory navigation archetype, with its Japanese corporate structure aligning manufacturing and PMDA quality systems.
| Leading Market Players |
|---|
| Novartis AG |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Santen Pharmaceutical Co., Ltd. |
| Alcon Inc. |
| Bausch + Lomb Corporation |
| Aerie Pharmaceuticals Inc. |
| Teva Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between sustained-release implant manufacturers and ophthalmology clinic networks lock in supply access and price visibility across the United States and Germany, insulating procurement decisions from spot-market volatility in active pharmaceutical ingredient markets.
Pricing Analysis
Project-based pricing for surgical implant procedures dominates reimbursement frameworks, with cost differentiation driven by FDA breakthrough device designation status and preservative-free formulation certification tiers. Pricing pressure stems from prostaglandin analogue commoditization at the market base, compressing margins for conventional topical therapies. Academic medical centers exhibit highest price sensitivity due to formulary budget constraints, while private ophthalmology networks in urban screening centers demonstrate lowest sensitivity when adherence failure mitigation justifies premium positioning.
Supply Chain Analysis
Biodegradable polymer matrix production concentrates in the United States, Germany, and Japan, where specialized excipient manufacturing infrastructure supports depot formulation scale-up. Supply chains draw from pharmaceutical-grade polymer feedstocks, precision injection molding equipment, and sterilization validation services. Single-source vulnerability in polymer precursor supply creates exposure to REACH chemical safety documentation delays. Distribution runs through direct manufacturer-to-clinic contracts that bypass fragmented wholesale networks in consolidated procurement settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as aging demographics across developed economies drive screening volume expansion and surgical intervention demand.
For Market Incumbents: Consolidate Phase III site networks to offset Western Europe investigator scarcity, and deepen backward integration into biodegradable polymer manufacturing to secure excipient supply against REACH compliance delays. Prioritize FDA breakthrough device designation pursuit for next-generation depot formulations to sustain pricing power against generic topical erosion. For New Entrants and Emerging Players: Anchor in Latin American direct distribution infrastructure where Allergan-legacy channel control has created whitespace for implant manufacturers with localized surgical training capabilities. Target Brazil's urban ophthalmology networks through ANVISA-aligned regulatory submissions and São Paulo-based specialist referral relationships. For Investors and Strategic Acquirers: Capital is best deployed toward sustained-release implant pure-plays with demonstrated durability data and PMDA sakigake designation eligibility; long-term viability hinges on surgical workflow integration rather than pharmaceutical manufacturing scale. Monitor minimally invasive glaucoma surgery adoption curves as the critical inflection signal for depot formulation demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses Phase III timelines for bimatoprost depot formulations in high-enrollment geographies. |
| PMDA Sakigake Pathway Navigation | Expedites regulatory review for first-in-Japan sustained-release implants with localized manufacturing. |
| Biodegradable Polymer Backward Integration | Secures excipient supply against REACH documentation delays and polymer precursor volatility. |
| Ophthalmology Clinic Direct Contracting | Bypasses fragmented wholesale networks and captures procurement authority in consolidated settings. |
| Surgical Training Infrastructure Buildout | Addresses canaloplasty and micro-stent placement bottlenecks that constrain implant launch timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across ophthalmology clinics, eye hospitals, and implant manufacturing facilities; clinical trial investigators, regulatory affairs specialists, formulary directors, and surgical training coordinators provided primary perspective. Secondary validation drew from FDA 510(k) filings, EMA MDR submissions, PMDA approval databases, and statutory health insurance reimbursement records. Bottom-up prescription volume modeling and top-down revenue triangulation anchored forecast integrity.
Across the analysis window, projections segmented by delivery mode, therapy area, and end-user setting incorporated patient adherence failure rates, surgical workflow adoption curves, and regional regulatory cluster dynamics. CAGRs derived from logarithmic trend fitting across historical revenue trajectories and forward-looking reimbursement reform schedules. Forecast inputs included prostaglandin analogue generic erosion timelines and sustained-release implant durability data maturation.
Decision-makers should treat outputs as directional under base assumptions of stable FDA accelerated approval pathway utilization and sustained German statutory health insurance reimbursement reform; material deviation in PMDA sakigake designation criteria or EMA MDR biocompatibility documentation requirements would warrant model refresh. Practitioners should keep alternative scenarios live as minimally invasive glaucoma surgery technology adoption and preservative-free formulation cost structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Eisenmenger Complex Management Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (APH) Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market