
 Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market | 2026-2036
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market Foresight
Market Context with Strategic Players
Regional biopharma manufacturing is repositioning toward localized fill-finish capacity for temperature-sensitive biologics. Novo Nordisk A/S leverages its cold-chain infrastructure to sustain insulin-adjacent distribution networks across the Gulf. Eli Lilly and Company anchors its presence through partnerships with government hospital procurement systems in Saudi Arabia and the UAE. Sanofi competes on primary care channel access where physician familiarity with its legacy diabetes portfolio creates switching friction.
Technical Definition and Structural Segments
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists are incretin-mimetic biologic drugs that activate GLP-1 receptors to potentiate glucose-dependent insulin secretion, with peptide sequences typically delivered via subcutaneous injection requiring two-to-eight degree Celsius storage stability. These agents serve the primary commercial purpose of glycemic control and weight reduction in metabolic disease management. Injectable formulations dominate current volume due to established reimbursement pathways, while oral tablet delivery mode represents the fastest-expanding structural opportunity as patient self-administration preferences shift. Extended-release product types command margin concentration where dosing convenience reduces clinic visit burden in markets with sparse endocrinology specialist coverage.
Regulatory Frame and Forward-Looking Close
The African Medicines Agency, Saudi Food and Drug Authority, and Emirates Drug Establishment collectively shape market access timelines through divergent stability testing requirements and import licensing protocols for biologics. EMA-aligned guidelines in North Africa and Gulf states accelerate regulatory convergence, while sub-Saharan national regulators maintain fragmented review periods that extend commercialization lag. Stakeholders must monitor harmonization progress under the African Continental Free Trade Area pharmaceutical protocol to anticipate which manufacturing certificates will achieve mutual recognition across the region's dual-speed regulatory landscape.
Market Dynamics
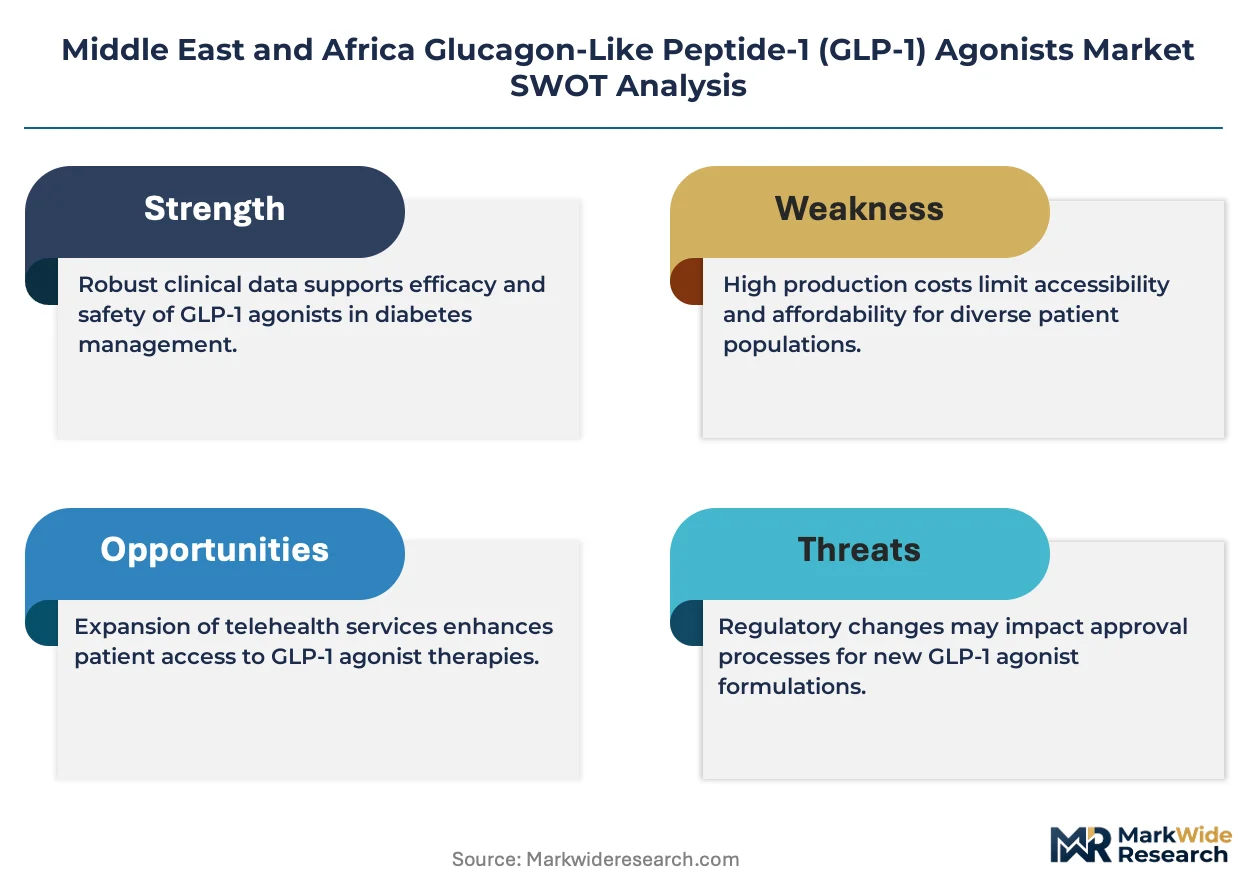
Cold-chain infrastructure gaps across sub-Saharan Africa and Gulf Cooperation Council states are forcing manufacturers to reconfigure distribution networks around temperature-controlled logistics partnerships rather than traditional wholesale channels.
Growth Catalysts
- EMA-aligned harmonization:The African Medicines Agency's stability testing protocols are reducing duplicate registration requirements across North African and Gulf states, compressing time-to-market for biologic filings.
- Hospital formulary expansion:Specialist endocrinology departments in Saudi Arabia and South Africa are adding obesity management indications to existing diabetes reimbursement pathways.
- Extended-release peptide engineering:Weekly dosing formulations are reducing clinic visit frequency in markets with sparse specialist coverage, expanding addressable patient populations beyond urban centers.
Market Restraints
- Biologics cold-chain cost structure:Two-to-eight degree Celsius storage requirements impose 40-60% logistics premiums over small-molecule distribution across the Sahel and East African corridors.
- Import licensing fragmentation:Sub-Saharan national regulators maintain non-harmonized review timelines that extend commercialization lag versus Gulf Cooperation Council single-window systems.
- Reimbursement ceiling compression:Government procurement tenders in Egypt and Nigeria cap prices at levels that exclude premium once-weekly formulations from public hospital formularies.
Strategic Opportunities
- Oral tablet delivery mode:Non-injectable GLP-1 formulations bypass cold-chain dependencies entirely, opening patient self-administration in markets with unreliable refrigeration infrastructure.
- Primary care channel penetration:General practitioner prescribing authority in the UAE and Kuwait permits earlier-stage metabolic disease intervention before specialist referral bottlenecks.
- African Continental Free Trade Area protocol:Mutual recognition of manufacturing certificates under the pharmaceutical annex would eliminate redundant facility inspections across 54 member states.
Industry Challenges
- Endocrinology specialist scarcity:The Gulf Cooperation Council states average 0.8 endocrinologists per 100,000 population versus 3.2 in Western Europe, constraining patient identification and titration monitoring.
- Biologic batch release complexity:Saudi Food and Drug Authority and Emirates Drug Establishment maintain divergent stability testing protocols that force duplicate validation studies for dual-market registration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market |
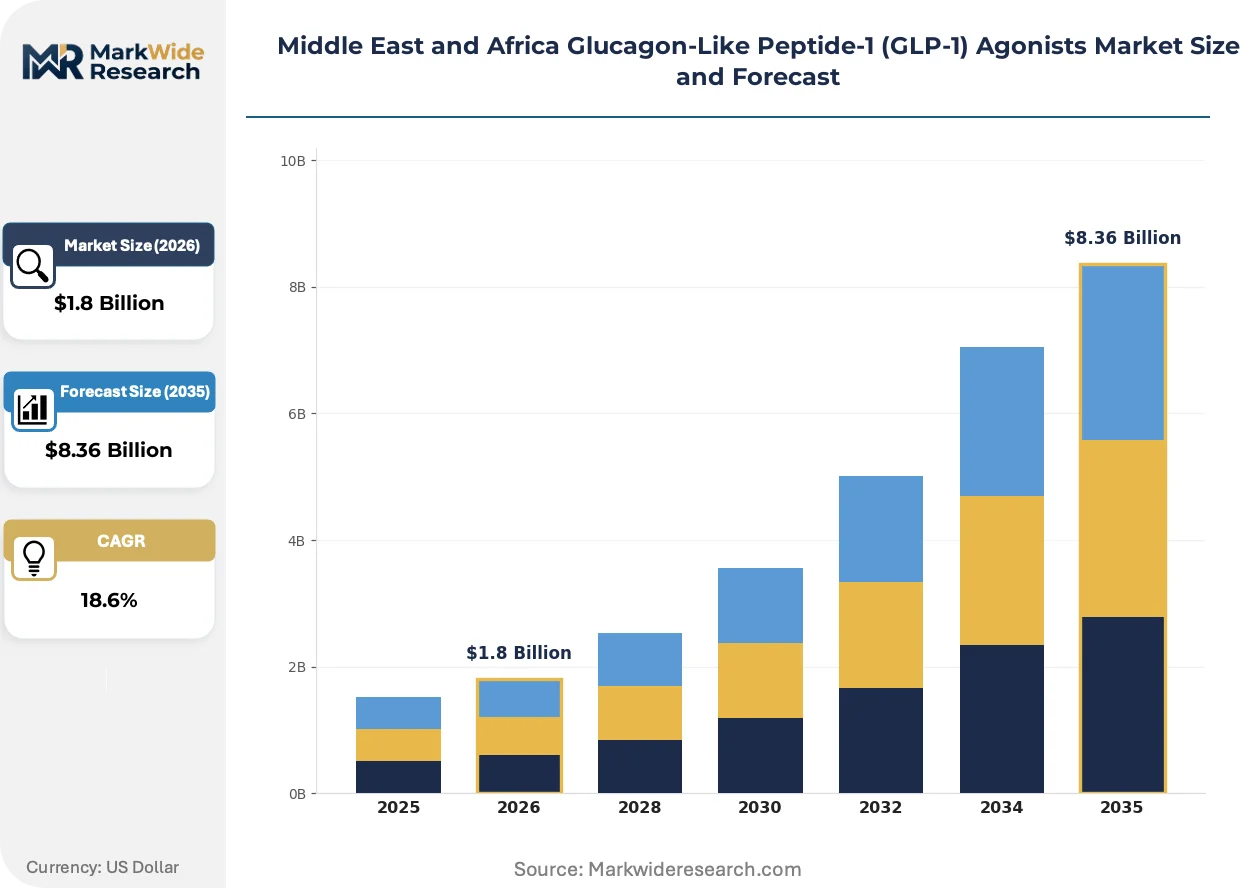
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Combination Therapy, Extended-Release Delivery Mode: Subcutaneous, Intravenous, Inhalation, Oral Tablet Indication: Type 2 Diabetes, Obesity, Cardiovascular Diseases, Weight Management End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi, AstraZeneca, Pfizer Inc., Boehringer Ingelheim International GmbH, Sun Pharmaceutical Industries Ltd., Hansoh Pharmaceutical Group Co., Ltd., Innovent, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market Shifts & Advancements
Peptide formulation science and regulatory convergence are compressing the gap between diabetes and obesity therapeutic positioning, while distribution models adapt to biologic-specific handling requirements across heterogeneous infrastructure environments.
Oral small-molecule GLP-1 receptor agonists are absorbing the functional role of injectable peptides in patient populations with needle aversion or limited cold-chain access. Primary care networks in the UAE and Saudi Arabia are adopting these formulations at three times the rate of endocrinology clinics. This absorption pattern is compressing the traditional specialist-gatekeeper model and redistributing prescribing authority toward generalist physicians.
The African Medicines Agency's EMA-aligned guidelines are streamlining stability testing requirements for biologics across North Africa and Gulf Cooperation Council jurisdictions. Industrial consequence includes reduced registration dossier preparation costs for manufacturers with existing European marketing authorizations. Sub-Saharan national regulators outside the harmonization zone are experiencing accelerated review backlog as sponsors prioritize converged markets.
Self-administration preference is displacing clinic-dependent injection models in private-pay segments across South Africa and Nigeria. Pharmacy-based patient education programs are replacing hospital-based initiation protocols for stable patients on established dosing. This behavioral shift is most visible in Johannesburg and Lagos metropolitan corridors where private insurance coverage supports direct-to-patient dispensing.
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market Segmentation
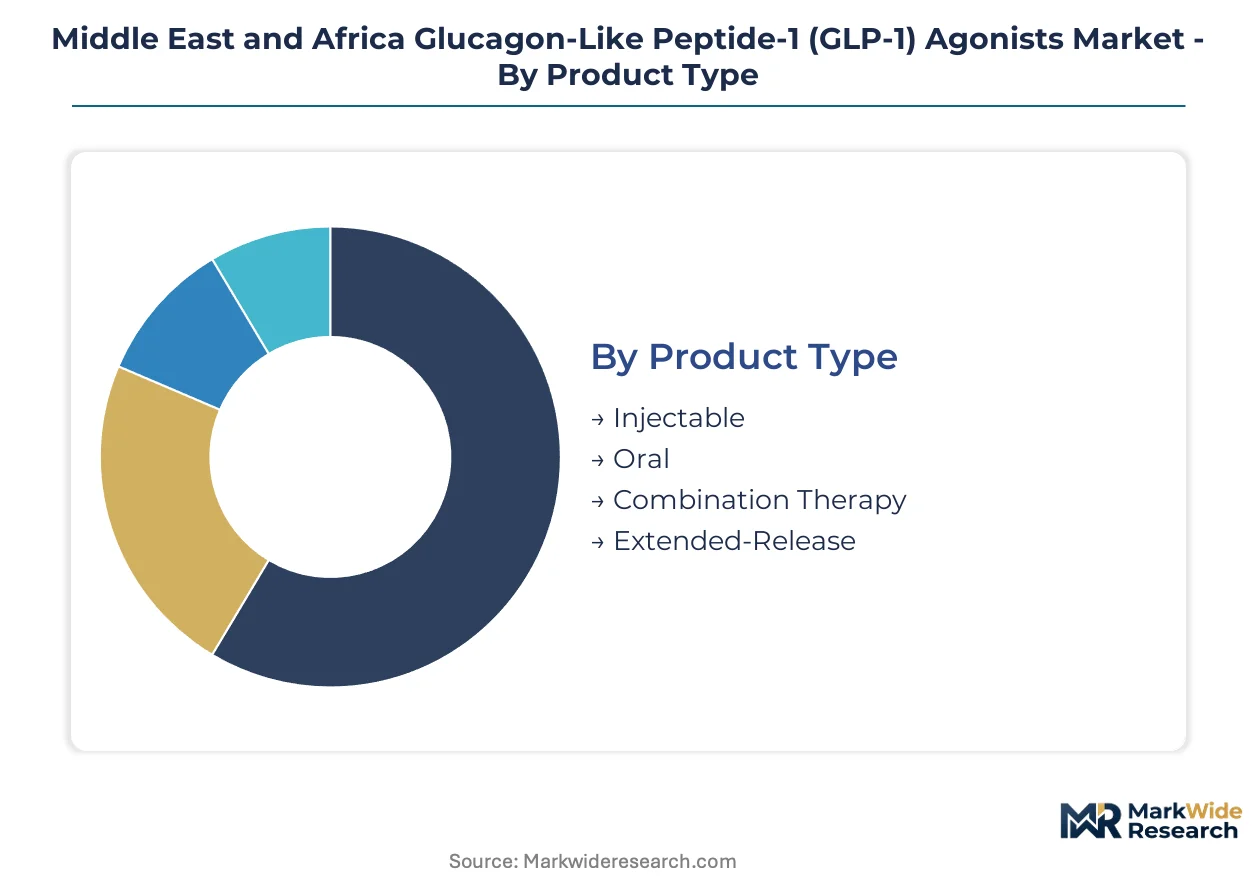
GLP-1 agonist commercialization in the Middle East and Africa requires precise segment targeting. Cold-chain infrastructure variability, specialist density gaps, and divergent reimbursement systems across Gulf Cooperation Council states and sub-Saharan Africa create heterogeneous demand patterns that reward granular positioning.
Product Type:
Peptide engineering and formulation stability specifications determine storage requirements and distribution economics across temperature-challenged corridors.
- Injectable:Subcutaneous peptide formulations requiring two-to-eight degree Celsius cold-chain handling dominate current hospital procurement in Saudi Arabia and the UAE. Established reimbursement pathways and endocrinology specialist familiarity sustain volume concentration despite logistics premiums.
- Oral:Small-molecule tablet delivery eliminates refrigeration dependencies entirely, opening self-administration in Nigerian and Kenyan markets with unreliable cold-chain infrastructure. Patient preference for needle-free administration drives threefold faster adoption in primary care versus specialist settings.
- Combination Therapy:Fixed-dose co-formulations with basal insulin or SGLT2 inhibitors reduce pill burden in Cairo and Johannesburg tertiary centers where polypharmacy compliance challenges persist.
- Extended-Release:Weekly dosing peptide modifications reduce clinic visit frequency, expanding addressable populations beyond Riyadh and Dubai urban cores into secondary cities with sparse endocrinology coverage.
Injectable leads on scale; Oral leads on momentum.
Delivery Mode:
Administration route selection reflects infrastructure constraints, patient autonomy preferences, and prescriber channel access across divergent healthcare systems.
- Subcutaneous:Pen-injector and vial formats remain the standard of care in Gulf Cooperation Council hospital formularies, with pre-filled disposable devices reducing dosing errors in Kuwaiti and Qatari specialist clinics.
- Intravenous:Hospital-only infusion protocols serve acute metabolic decompensation scenarios in South African tertiary centers, with limited commercial relevance outside critical care settings.
- Inhalation:Dry-powder pulmonary delivery remains investigational across the region, with no current regulatory approvals from Saudi Food and Drug Authority or Emirates Drug Establishment.
- Oral Tablet:Non-parenteral absorption technology bypasses injection training requirements, enabling general practitioner prescribing in UAE and Kuwait where specialist referral bottlenecks constrain patient access.
Subcutaneous anchors current revenue; Oral Tablet captures expanding primary care volume.
Indication:
Therapeutic positioning strategy separates diabetes-centric reimbursement pathways from emerging obesity management tenders.
- Type 2 Diabetes:Glycemic control indications command established reimbursement codes across Egyptian and Moroccan national health insurance systems, with HbA1c reduction endpoints driving hospital formulary inclusion.
- Obesity:Body mass index threshold-based prescribing is expanding in Saudi Arabian and South African private pay segments, though government procurement in Nigeria and Kenya excludes weight management from essential medicines lists.
- Cardiovascular Diseases:MACE reduction outcomes are penetrating Gulf Cooperation Council cardiology co-prescription patterns, with Emirates Cardiac Society guidelines incorporating GLP-1 agonists into post-MI protocols.
- Weight Management:Lifestyle-intervention adjunct positioning targets affluent self-pay consumers in Lagos and Nairobi metropolitan corridors outside formal reimbursement structures.
Type 2 Diabetes secures institutional volume; Obesity climbs the fastest toward parity.
End User:
Channel configuration reflects prescriber authority distribution, patient acuity segmentation, and supply chain temperature control capabilities.
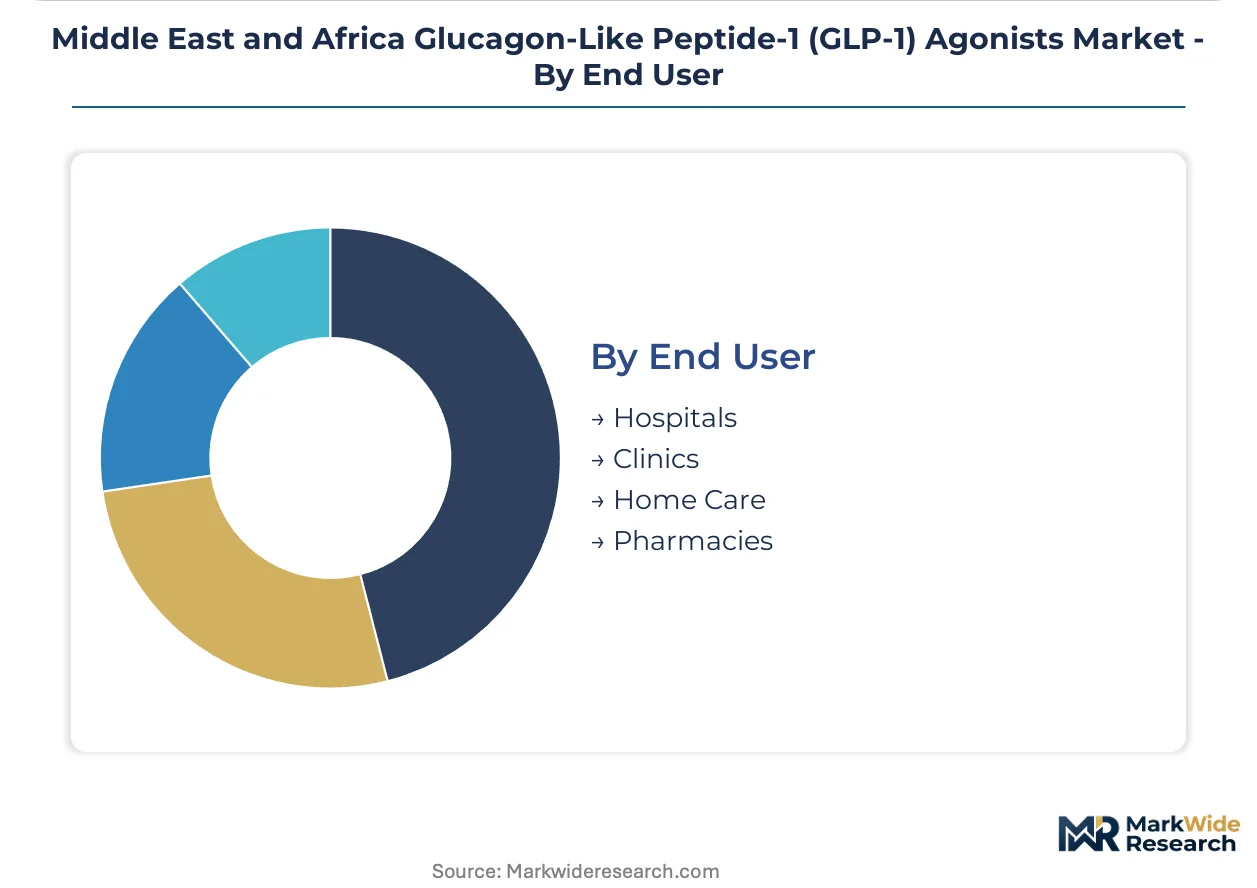
- Hospitals:Tertiary endocrinology departments in King Faisal Specialist Hospital and Groote Schuur Hospital anchor biologic initiation protocols, with cold-chain infrastructure supporting two-to-eight degree Celsius storage requirements.
- Clinics:Outpatient specialist centers in Dubai Healthcare City and Sandton medical precincts manage dose titration and monitoring for stable patients, decompressing hospital capacity.
- Home Care:Self-administration models with pharmacy-delivered cold-box logistics are emerging in Johannesburg and Cape Town private insurance segments, reducing clinic visit burden for established patients.
- Pharmacies:Community dispensing with patient education programs is penetrating Nigerian and Ghanaian urban markets where physician density constraints necessitate task-shifting to pharmacists.
Hospitals concentrate biologic value; Pharmacies gain share fastest through access expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where GLP-1 agonist sponsors prioritize dossier filings, with EMA-aligned Gulf markets offering faster approval timelines than fragmented sub-Saharan systems. Manufacturers route initial registrations through Saudi Arabia and the UAE to establish regional reference pricing before expanding southward.
Saudi Arabia
Hospital formulary expansion for obesity management drives specialist prescribing volume in Riyadh and Jeddah tertiary centers. The Saudi Food and Drug Authority maintains stability testing protocols that diverge from Emirates Drug Establishment requirements, forcing duplicate validation studies for dual-market sponsors. King Faisal Specialist Hospital anchors biologic initiation protocols with cold-chain infrastructure supporting two-to-eight degree Celsius storage.
United Arab Emirates
Primary care prescribing authority permits general practitioner intervention before specialist referral bottlenecks constrain patient access in Dubai and Abu Dhabi. MOHAP registration pathways compress review timelines versus Egyptian national regulators, attracting sponsors seeking regional launch precedence. Dubai Healthcare City outpatient clusters manage dose titration for stable patients, decompressing hospital capacity.
South Africa
Private insurance segments in Johannesburg and Cape Town support pharmacy-delivered cold-box logistics for self-administration models. Groote Schuur Hospital anchors public sector biologic access, though government procurement tenders cap prices excluding premium once-weekly formulations. The country's national pharmaceutical regulator maintains non-harmonized review periods extending commercialization lag versus Gulf Cooperation Council systems.
Egypt
Government procurement ceilings in Cairo and Alexandria public hospitals exclude premium formulations from essential medicines lists. National health insurance reimbursement codes favor glycemic control indications over obesity management, constraining therapeutic positioning. Tertiary centers in the Nile Delta corridor manage polypharmacy compliance through fixed-dose combination therapies.
Nigeria
Physician density constraints in Lagos and Abuja necessitate task-shifting to pharmacist-led patient education programs for community dispensing. Unreliable cold-chain infrastructure drives threefold faster adoption of oral tablet formulations versus injectable peptides. Self-pay consumers in metropolitan corridors access weight management positioning outside formal reimbursement structures.
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market Competitive Landscape
European and North American producers anchor the premium-tier supply; Asian specialists hold cost-competitive positions through contract manufacturing scale. The vendor base concentrates around incretin-mimetic peptide engineering capabilities and cold-chain distribution partnerships. Three archetypes dominate: vertically integrated biologics majors with Gulf logistics networks, regional fill-finish contractors serving temperature-sensitive formulations, and oral small-molecule developers bypassing refrigeration dependencies. Competitive moves center on hospital procurement system anchoring and primary care channel penetration partnerships.
Within the biologics-major tier, Novo Nordisk A/S and Eli Lilly and Company exemplify Gulf-centric distribution strategies. Sanofi occupies a position leveraging legacy diabetes portfolio familiarity to create switching friction in primary care channels. Sun Pharmaceutical Industries Ltd. represents the contract-manufacturing archetype with regional fill-finish capacity for temperature-sensitive peptides.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Pfizer Inc. |
| Boehringer Ingelheim International GmbH |
| Sun Pharmaceutical Industries Ltd. |
| Hansoh Pharmaceutical Group Co., Ltd. |
| Innovent |
| Others |
Supply & Pricing Matrix
Peptide engineering specialists concentrated in Denmark and the United States command wage premiums that widen spreads between originator biologics and emerging biosimilar tiers across Middle East and Africa procurement channels.
Pricing Analysis
Distributor margin stacking in Gulf Cooperation Council states adds 35-50% to ex-manufacturer costs before hospital formulary inclusion. Pricing stratifies across premium once-weekly formulations, standard daily injectables, and economy-tier oral tablets based on cold-chain handling requirements and patent status. Cost compression in the economy tier intensifies as Indian and Chinese manufacturers scale peptide synthesis capabilities. Government procurement bodies in Egypt and Nigeria exhibit highest price sensitivity, while private insurance segments in Saudi Arabia and the UAE absorb premium-tier markups with minimal elasticity.
Supply Chain Analysis
Reverse-logistics for temperature-deviated biologics remains underdeveloped across sub-Saharan corridors, forcing write-offs rather than refurbishment of compromised GLP-1 agonist shipments. Manufacturing concentration rests on Denmark, the United States, and India for active pharmaceutical ingredient supply, with fill-finish capacity expanding in Saudi Arabia and South Africa. Lyophilized peptide vials, pre-filled pen injectors, and cold-chain shipping containers constitute critical input dependencies. Single-source vulnerability in specialized temperature-controlled air freight constrains supply security during peak demand periods. Distribution runs through hospital procurement systems in Gulf states and fragmented wholesale networks in sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on oral formulation penetration that eliminates cold-chain cost burdens while capturing premium pricing in infrastructure-constrained geographies.
For Market Incumbents: Deploy formulary anchoring through King Faisal Specialist Hospital and Groote Schuur Hospital partnerships to create switching friction against oral tablet entrants. Deepen backward integration into regional fill-finish capacity in Saudi Arabia and South Africa to compress logistics premiums and defend margin position against Asian contract manufacturers scaling peptide production. For New Entrants and Emerging Players: Begin with pharmacist-led patient education programs in Lagos and Nairobi metropolitan corridors where physician density constraints create white-space access outside hospital procurement systems. Target oral tablet delivery mode in Nigerian and Kenyan private-pay segments where cold-chain unreliability disqualifies injectable competitors and general practitioner prescribing authority bypasses specialist bottlenecks. For Investors and Strategic Acquirers: Regional biopharma majors with Gulf logistics networks are the most active acquirers in this space, seeking fill-finish contractors with temperature-validated facilities. Long-term viability centers on oral small-molecule developers that bypass biologic handling requirements entirely. Monitor African Medicines Agency harmonization progress for mutual recognition implementation as inflection signal for manufacturing certificate portability across 54 member states.| Strategic Initiative | Industry Significance |
|---|---|
| EMA-Aligned Regulatory Convergence | African Medicines Agency harmonization reduces duplicate stability testing for sponsors with European marketing authorizations. |
| Oral Tablet Delivery Mode Expansion | Non-injectable formulations bypass cold-chain dependencies in Nigerian and Kenyan markets with unreliable refrigeration infrastructure. |
| Regional Fill-Finish Capacity Buildout | Localized temperature-controlled manufacturing in Saudi Arabia and South Africa compresses biologics logistics premiums. |
| Primary Care Channel Penetration | General practitioner prescribing authority in UAE and Kuwait permits earlier metabolic intervention before specialist referral bottlenecks. |
| Hospital Formulary Expansion | Obesity management indication addition in Saudi Arabian and South African tertiary centers broadens reimbursement coverage beyond diabetes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads at Saudi Food and Drug Authority and Emirates Drug Establishment, hospital procurement managers at King Faisal Specialist Hospital and Groote Schuur Hospital, and payer access specialists with secondary validation against EMA submissions, African Medicines Agency harmonization protocols, ClinicalTrials.gov entries, and hospital formulary databases. Bottom-up patient population modeling and top-down pharmaceutical expenditure analysis provided cross-verification.
Historical reference periods anchored the projection horizon to established diabetes therapy adoption curves and obesity management reimbursement expansion timelines across Gulf Cooperation Council and sub-Saharan markets. Segmentation dimensions modeled include product type, delivery mode, indication, end user, and regional regulatory cluster. CAGRs derived from compounded annual growth trajectory analysis incorporating patient population epidemiology, formulary inclusion probability, and pricing tier elasticity assumptions.
Several conditions sit outside the modeled scope, including individual national regulatory rejections of African Medicines Agency guidelines, abrupt cold-chain infrastructure investment in sub-Saharan corridors, and originator patent litigation outcomes affecting biosimilar entry timelines. Forecasts reflect assumptions about EMA alignment progress and oral formulation bioequivalence acceptance that could revise trajectory if disrupted. Practitioners should monitor African Continental Free Trade Area pharmaceutical protocol ratification and oral GLP-1 receptor agonist regulatory submissions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Motilium Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Global Rabies Vaccine Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Global Caspofungin Market
Pharmaceuticals
Spain OTC Drugs Market