
 Global Peptide Cancer Vaccine Market | 2026-2036
Global Peptide Cancer Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Peptide Cancer Vaccine Market Foresight
Project finance tied to milestone-based clinical partnerships is rewriting competitive access in peptide cancer vaccines. SELLAS Life Sciences leverages its asset-light development model to share Phase III risk with institutional backers. Immatics anchors European manufacturing scale through dedicated biologics facilities in Germany. IO Biotech competes via differentiated T-cell priming platforms that reduce cost-of-goods versus full protein alternatives.
Peptide cancer vaccines comprise synthetic amino acid sequences designed to elicit tumor-specific T-cell responses against oncogenic or neoantigen targets, typically formulated with adjuvants or delivered via dendritic cell loading to achieve cellular immunity. Their primary purpose is therapeutic immunization against established malignancies, particularly in settings where tumor mutational burden generates identifiable peptide epitopes. Synthetic peptides lead product type demand due to manufacturing reproducibility and regulatory familiarity, while personalized medicine applications capture fastest-growing interest as neoantigen sequencing costs decline. Combination vaccines command premium positioning where checkpoint inhibitor pairing demonstrates synergistic survival benefit in melanoma and non-small cell lung cancer indications.
The FDA accelerates demand through its Breakthrough Therapy designation and rolling review provisions that compress regulatory timelines for peptide vaccines demonstrating early efficacy signals. EMA's PRIME scheme and Japan's PMDA Sakigake designation create parallel fast-track pathways that shape multi-regional development strategies for sponsors targeting simultaneous US-Europe-Asia approvals. China's NMPA reform of biologics review standards further conditions market access for imported peptide therapies. Stakeholders must monitor how evolving reimbursement frameworks for personalized oncology products in Germany, Japan, and the United States determine which delivery modes and end-user channels achieve sustainable commercial traction.
Market Dynamics
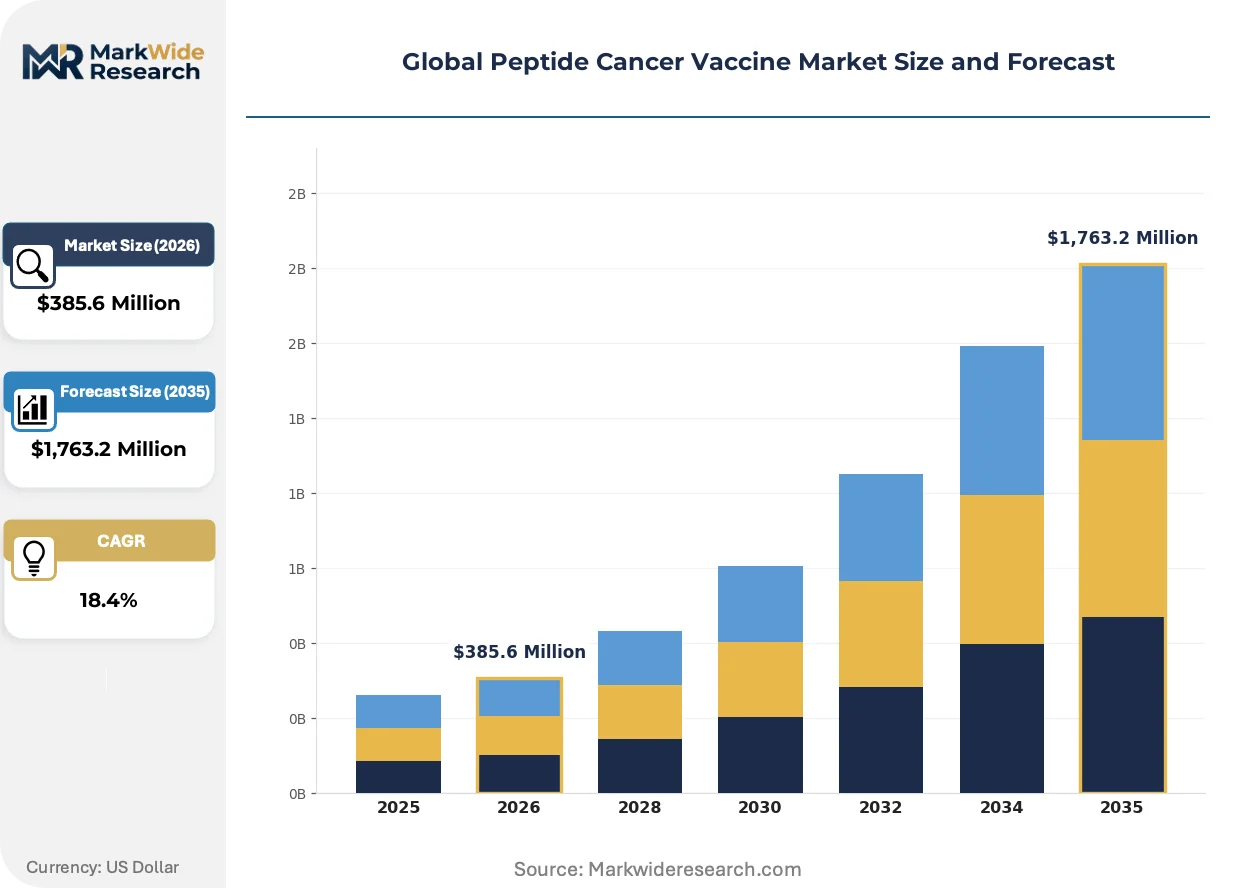
The convergence of FDA's Breakthrough Therapy designation with collapsing neoantigen sequencing costs is compressing development timelines from discovery to Phase II entry, while manufacturing partnerships in Germany and Japan are redrawing competitive access through dedicated biologics capacity.
Growth Catalysts
- Accelerated Approval Frameworks:The FDA's rolling review provisions compress regulatory timelines for peptide vaccines demonstrating early efficacy signals in melanoma and non-small cell lung cancer.
- Neoantigen Prediction Algorithms:Machine learning platforms for tumor-specific epitope identification are reducing personalized vaccine design cycles from months to weeks.
- China:NMPA reform of biologics review standards is conditioning market access for imported peptide therapies and stimulating domestic manufacturing investment.
Market Restraints
- Cost Structure:GMP-grade peptide synthesis and individualized quality control impose cost premiums that limit addressable patient populations outside reimbursed indications.
- Supply Concentration:Contract manufacturing for personalized vaccines concentrates among European CDMOs with dedicated biologics facilities, creating bottleneck risk.
- Technical Limitation:Cold-chain requirements for dendritic cell loading formulations restrict distribution to tertiary oncology centers with specialized infrastructure.
Strategic Opportunities
- Combination Regimens:Checkpoint inhibitor pairing in melanoma demonstrates synergistic survival benefit, opening premium positioning for combination vaccine platforms.
- Japan:PMDA Sakigake designation creates parallel fast-track pathways that enable simultaneous US-Asia development strategies for sponsors.
- Community Oncology Networks:Hub-and-spoke distribution models are emerging to extend peptide vaccine access beyond academic medical centers.
Industry Challenges
- Bioinformatics Talent Scarcity:Neoantigen prediction and patient-specific sequence optimization require computational immunology expertise that outpaces current training pipelines.
- Reimbursement Uncertainty:Germany's G-BA and US CMS are developing frameworks for personalized oncology products that remain unsettled, delaying commercial planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Peptide Cancer Vaccine Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,763.2 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Combination Vaccines, Adjuvanted Vaccines, Synthetic Peptides Application: Immunotherapy, Prophylactic Use, Therapeutic Use, Personalized Medicine Delivery Mode: Intravenous, Subcutaneous, Intra-tumoral, Oral End User: Hospitals, Research Institutions, Oncology Clinics, Contract Research Organizations |
| Companies Covered | SELLAS Life Sciences, ISA Pharmaceuticals, BrightPath Biotherapeutics, Scancell Holdings, Imugene, Shionogi, Evaxion, IO Biotech, Immatics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Peptide Cancer Vaccine Market Shifts & Advancements
Peptide cancer vaccine development is pivoting from standardized off-the-shelf products toward fully individualized manufacturing workflows, with technology platforms and regulatory frameworks racing to match this operational transformation.
Next-generation mass spectrometry-based immunopeptidome profiling is collapsing the timeline for patient-specific neoantigen identification from tumor biopsy to vaccine design. Academic medical centers in Boston and Heidelberg are adopting these platforms for prospective clinical trials. The compression of epitope discovery is enabling real-time manufacturing starts that align with checkpoint inhibitor treatment windows.
EMA's PRIME scheme is streamrolling scientific advice and accelerated assessment pathways for advanced therapy medicinal products, including personalized peptide vaccines. Sponsors are restructuring development programs to secure PRIME eligibility prior to Phase I initiation. This regulatory tailwind is concentrating European clinical trial investment in Germany and the Netherlands where centralized manufacturing infrastructure already exists.
Hospital procurement committees are fragmenting purchasing authority between pharmacy and oncology service lines, creating dual-gatekeeper dynamics for peptide vaccine adoption. Specialty distributors are responding with integrated logistics services that bundle cold-chain handling with patient scheduling coordination. This channel evolution is most pronounced in US integrated delivery networks and Chinese tier-1 hospital consortia where volume commitments unlock preferential supply terms.
Global Peptide Cancer Vaccine Market Segmentation
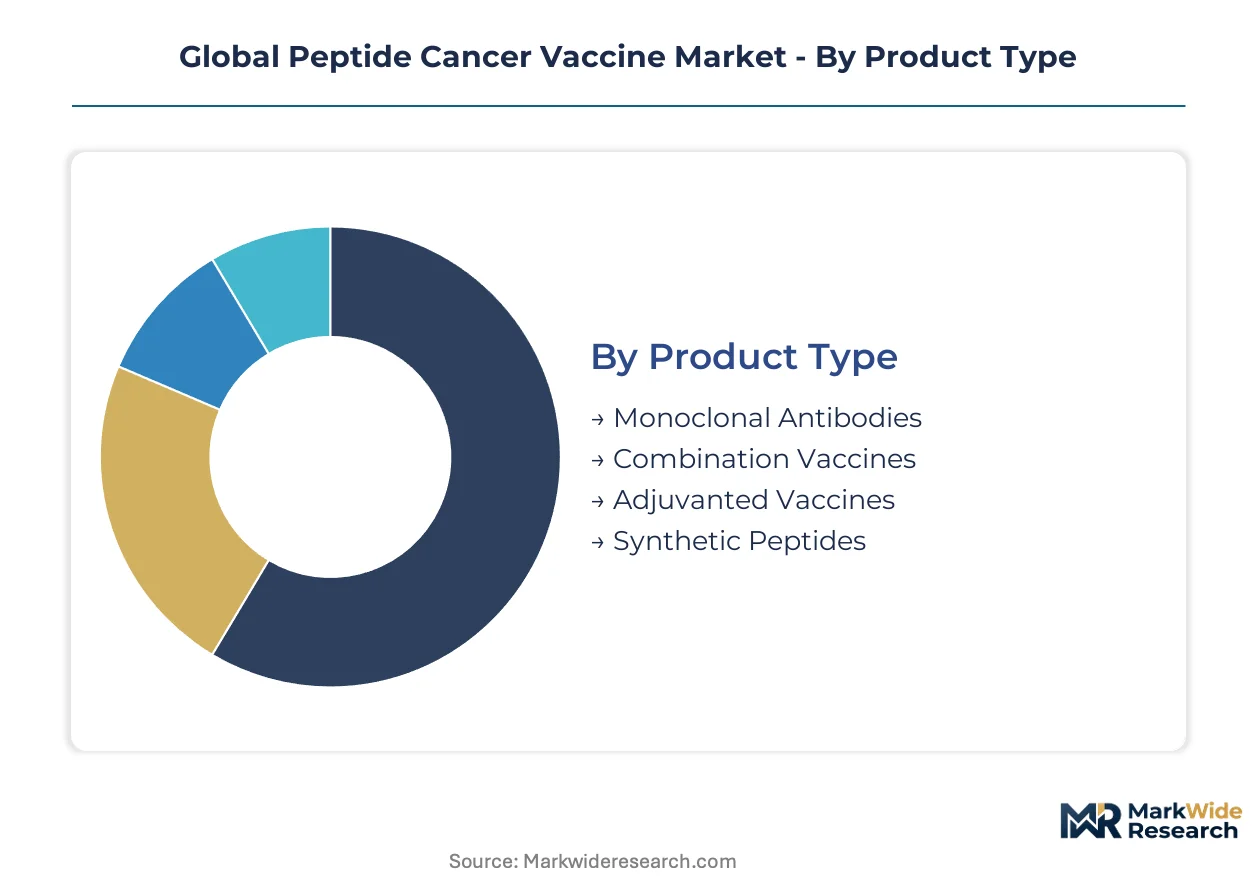
Peptide cancer vaccine manufacturers structure portfolios across four intersecting dimensions: molecular design, clinical intent, administration route, and care setting. Each dimension carries distinct regulatory, reimbursement, and manufacturing implications that determine commercial viability.
Product Type:
Cost tier differentiation separates standardized manufacturing from individualized production workflows.
- Synthetic Peptides:Chemically defined amino acid chains manufactured through solid-phase synthesis enable batch-to-batch reproducibility. Demand concentrates in United States oncology networks where FDA regulatory familiarity accelerates IND timelines. GMP-grade synthesis platforms at European CDMOs supply global Phase III programs.
- Combination Vaccines:Peptide antigens co-formulated with checkpoint inhibitors or immune adjuvants create synergistic T-cell priming. German university hospitals and Chinese tier-1 cancer centers are piloting melanoma and non-small cell lung cancer protocols. Manufacturing complexity limits sourcing to dedicated biologics facilities.
- Monoclonal Antibodies:Engineered immunoglobulins targeting tumor-associated antigens with peptide epitope specificity.
- Adjuvanted Vaccines:Peptide antigens formulated with aluminum salts, MPL, or oil-in-water emulsions to enhance dendritic cell uptake.
Synthetic peptides command the established base. The steepest expansion runs through combination vaccines.
Application:
Clinical intent determines patient selection criteria, biomarker requirements, and reimbursement pathways.
- Therapeutic Use:Active immunization against established malignancies drives the majority of clinical development. Japanese PMDA Sakigake designation and FDA Breakthrough Therapy pathways compress approval timelines for late-stage melanoma and glioblastoma indications. Heidelberg and Boston academic centers lead patient enrollment.
- Personalized Medicine:Patient-specific neoantigen vaccines designed from individual tumor sequencing. NGS cost collapse and machine learning epitope prediction are enabling real-time manufacturing in Netherlands and Singapore facilities. Reimbursement frameworks in Germany and the United States remain unsettled.
- Immunotherapy:Broad category encompassing immune modulation through peptide-based approaches.
- Prophylactic Use:Prevention of cancer onset in high-risk genetic carriers or virally induced malignancies.
Therapeutic use anchors current revenue. Personalized medicine is gaining share fastest as sequencing economics improve.
Delivery Mode:
Administration route shapes cold-chain infrastructure, site-of-care requirements, and patient compliance.
- Subcutaneous:Depot-formulated peptides injected into adipose tissue enable slow antigen release and simplified logistics. Community oncology networks in the United States and hub-and-spoke models in China extend access beyond academic centers. Self-administration potential reduces infusion center burden.
- Intra-tumoral:Direct injection into lesion sites maximizes local antigen presentation and abscopal effect activation. German interventional radiology units and Japanese specialized cancer centers are developing ultrasound-guided delivery protocols. Technical complexity restricts use to tertiary settings.
- Intravenous:Systemic circulation of peptide-loaded dendritic cells or liposomal formulations.
- Oral:Gastrointestinal delivery platforms overcoming epithelial barrier and enzymatic degradation.
Subcutaneous delivery holds the volume base. Intra-tumoral injection climbs fastest as interventional techniques mature.
End User:
Customer type dictates procurement authority, purchasing volume, and technical support requirements.
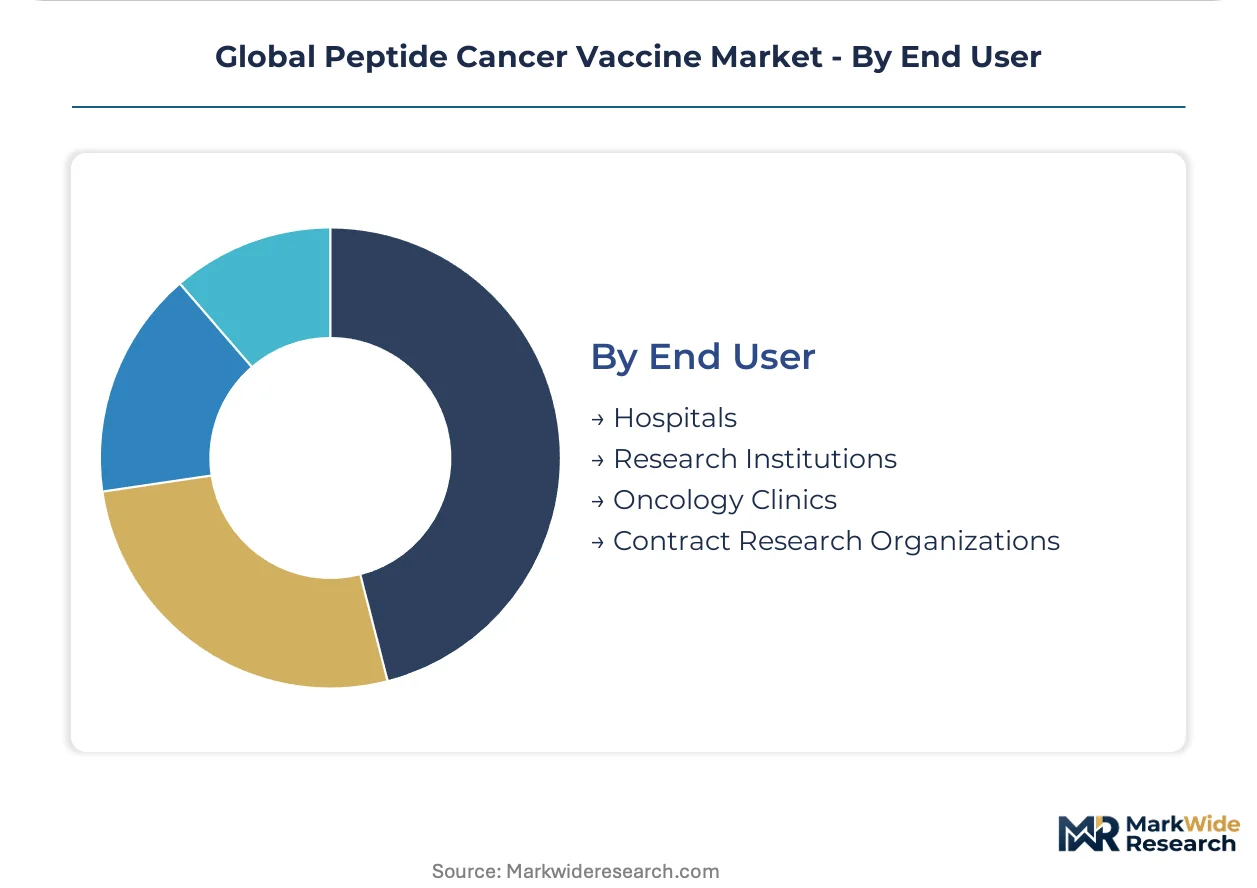
- Oncology Clinics:Specialized cancer treatment units within hospital systems or standalone facilities. United States integrated delivery networks and Chinese provincial cancer hospitals are building dedicated peptide vaccine pharmacy capabilities. Dual gatekeeper dynamics between pharmacy and oncology service lines complicate purchasing.
- Hospitals:General acute care institutions with oncology departments.
- Research Institutions:Academic medical centers and university hospitals conducting investigator-initiated trials.
- Contract Research Organizations:Clinical trial service providers managing peptide vaccine study execution.
Oncology clinics command the established base. Hospital networks are expanding fastest as centralized pharmacy models scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Breakthrough Therapy designation and Japan's PMDA Sakigake program are accelerating clinical trial starts across three continents. Manufacturing partnerships in Germany and China are redrawing competitive access through dedicated biologics capacity.
United States
Integrated delivery networks in Boston and Houston are building dedicated peptide vaccine pharmacy capabilities. FDA rolling review provisions compress regulatory timelines for melanoma and non-small cell lung cancer indications. Memorial Sloan Kettering and MD Anderson anchor patient enrollment for neoantigen vaccine trials.
Germany
Heidelberg University Hospital and Berlin Charité are pioneering mass spectrometry-based immunopeptidome profiling for real-time vaccine design. EMA PRIME scheme streamlines scientific advice for advanced therapy medicinal products. Bavarian biologics facilities supply European Phase III programs with GMP-grade peptide synthesis.
China
NMPA reform of biologics review standards is conditioning market access for imported peptide therapies. Tier-1 hospital consortia in Shanghai and Guangzhou are expanding centralized pharmacy models. Domestic manufacturing investment is accelerating in Suzhou and Hangzhou biotech clusters.
Japan
PMDA Sakigake designation enables simultaneous US-Asia development strategies for sponsors. Osaka and Tokyo specialized cancer centers are developing ultrasound-guided intra-tumoral delivery protocols. Regulatory tailwinds are concentrating clinical trial investment in Kansai and Kanto regions.
Netherlands
Amsterdam and Rotterdam facilities are enabling real-time manufacturing for personalized neoantigen vaccines. EMA centralized procedures leverage Dutch regulatory expertise for multi-national trial coordination. Leiden biotech corridor anchors European supply chain for patient-specific sequence optimization.
Global Peptide Cancer Vaccine Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: asset-light developers sharing Phase III risk with institutional backers, integrated manufacturers with captive biologics facilities, and platform specialists differentiating through T-cell priming technologies. Competitive moves concentrate on milestone-based clinical partnerships and dedicated manufacturing scale.
Within the asset-light development tier, SELLAS Life Sciences and IO Biotech represent partnership-dependent models that externalize capital intensity. Immatics anchors the integrated manufacturing vector through European biologics facilities. Evaxion occupies a position among algorithm-driven specialists leveraging machine learning for epitope prediction.
| Leading Market Players |
|---|
| SELLAS Life Sciences |
| ISA Pharmaceuticals |
| BrightPath Biotherapeutics |
| Scancell Holdings |
| Imugene |
| Shionogi |
| Evaxion |
| IO Biotech |
| Immatics |
| Others |
Supply & Pricing Matrix
Bavarian biologics clusters in southern Germany anchor GMP-grade peptide synthesis capacity, translating manufacturing scarcity into premium pricing power for personalized cancer immunotherapies across European and Asian markets.
Pricing Analysis
Certification level (FDA-grade versus EMA-grade versus domestic standard) creates the primary spread across peptide vaccine tiers. Contract manufacturers command premium positioning where captive biologics facilities hold ISO 13485 and FDA establishment registration. Cost compression in standard synthetic peptide tiers is intensifying because Chinese CDMOs are expanding GMP capacity in Suzhou and Hangzhou. Hospital procurement committees in integrated US delivery networks exhibit highest price sensitivity, while Japanese specialized cancer centers prioritize supply security over unit cost.
Supply Chain Analysis
Amino acid feedstocks and specialized solid-phase synthesis resins draw from chemical manufacturing bases in Germany, China, and Switzerland. Fmoc-protected amino acids, Wang resins, and HPLC purification media constitute critical input dependencies. Single-source vulnerability concentrates in European CDMOs holding dedicated biologics facilities for individualized vaccine production. Distribution runs through specialty pharmaceutical distributors bundling cold-chain logistics with patient scheduling coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peptide cancer vaccine market is recovering from a cyclical trough as FDA Breakthrough Therapy designations and collapsing neoantigen sequencing costs reactivate clinical investment cycles.
For Market Incumbents: Build regulatory data moats through parallel FDA-EMA-PMDA submission strategies that exhaust emerging entrants' capital reserves. Immatics and SELLAS Life Sciences demonstrate how captive European manufacturing capacity and milestone-based institutional partnerships neutralize biosimilar threats. Priority levers include Heidelberg and Netherlands facility expansion plus PRIME scheme pre-positioning before Phase I initiation.
For New Entrants and Emerging Players: Establish a beachhead in Chinese tier-1 hospital consortia where NMPA reform is conditioning market access for imported peptide therapies. White-space targets include community oncology networks in the United States adopting hub-and-spoke distribution models and ultrasound-guided intra-tumoral delivery protocols in Japanese specialized cancer centers. Go-to-market angle: algorithm-driven epitope prediction platforms that compress vaccine design cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because personalized medicine economics are converging with checkpoint inhibitor combination regimens. Target asset-light developers with Phase II melanoma or non-small cell lung cancer data sharing risk with institutional backers. Signal to watch: reimbursement framework settlements by Germany's G-BA and US CMS for individualized oncology products.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA Breakthrough Therapy designation compresses regulatory timelines for melanoma indications. |
| Manufacturing Scale-Up | Dedicated biologics facilities in Germany and Netherlands enable real-time personalized vaccine production. |
| Regulatory Approval Pathway | EMA PRIME scheme streamlines scientific advice for advanced therapy medicinal products. |
| Licensing Agreement | Milestone-based partnerships with institutional backers share Phase III risk for asset-light developers. |
| Pipeline Diversification | Neoantigen prediction algorithms enable expansion from melanoma into glioblastoma indications. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions for this analysis. Primary interviews across German oncology networks, Japanese specialized cancer centers, and Chinese tier-1 hospital consortia were validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down market sizing triangulated volume and value estimates across the projection horizon.
Demand-supply balance dynamics shaped the analytical framework throughout the forecast period. Segmentation dimensions included product type (synthetic peptides versus combination vaccines), application (therapeutic use versus personalized medicine), delivery mode (subcutaneous versus intra-tumoral), and end user (oncology clinics versus hospital networks). CAGRs were derived from patent expiration timelines, regulatory approval velocity, and manufacturing capacity expansion announcements across Bavarian and Dutch biologics clusters.
Stress conditions across neoantigen sequencing cost trajectories, reimbursement framework settlements, and CDMO capacity utilization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding checkpoint inhibitor combination efficacy and personalized vaccine manufacturing scale-up. Cross-checking against external benchmarks including EMA PRIME eligibility trends and PMDA Sakigake designation velocity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
United States Pharmaceutical Logistics Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Global Erythropoietin Stimulating Agents Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market