
 Rheumatology Therapeutics Market | 2026-2036
Rheumatology Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Rheumatology Therapeutics Market Intelligence
Specialty clinics is reorganizing the patient flow for rheumatology therapeutics, capturing complex infusion cases that hospitals once monopolized. AbbVie Inc. anchors its position through in-house production of Humira-originator supply chains and captive biologic manufacturing capacity. Pfizer Inc. leverages its Janus kinase inhibitor portfolio to compete in oral alternatives against injectable biologics. Eli Lilly and Co differentiates through IL-17 and IL-23 pathway specialization in psoriatic arthritis overlap indications.
Rheumatology therapeutics comprise pharmacologic agents targeting autoimmune and inflammatory joint diseases, including monoclonal antibodies, synthetic small molecules, and corticosteroid formulations designed to modulate cytokine signaling or suppress synovial inflammation. These agents functionally aim to achieve disease remission, prevent radiographic joint damage, and preserve functional mobility in progressive conditions such as rheumatoid arthritis and ankylosing spondylitis. Biologics occupies the dominant margin pool due to manufacturing complexity and patent-protected pricing, while Janus kinase inhibitors represent the fastest-expanding delivery mode segment as oral administration reduces site-of-care dependency. DMARDs sustains substantial volume across early-line protocols in rheumatoid arthritis, though pricing pressure intensifies as conventional synthetic options face biosimilar erosion.
FDA, EMA, and WHO collectively govern rheumatology therapeutic standards through biosimilar interchangeability rules, Good Manufacturing Practice inspections, and prequalification pathways that determine market access timelines. These frameworks directly shape clinical trial design requirements, post-marketing surveillance obligations, and reimbursement negotiations across jurisdictions. Stakeholders must monitor evolving FDA interchangeability designations and EMA extrapolation policies to anticipate prescribing authority shifts and pharmacy-level substitution risks.
Market Dynamics
The rheumatology therapeutics sector is pivoting around biosimilar substitution authority as FDA interchangeability designations and EMA extrapolation policies reconfigure prescribing hierarchies across institutional and retail pharmacy channels.
Growth Catalysts
- FDA Interchangeability Pathway:The designation framework permits pharmacy-level substitution without prescriber consultation, accelerating biosimilar uptake in self-administered TNF inhibitor categories.
- Specialty Clinic Expansion:Site-of-care migration from hospital outpatient departments to independent infusion centers reduces overhead reimbursement differentials and improves patient throughput.
- Janus Kinase Inhibitor Formulation:Oral small-molecule delivery eliminates cold-chain logistics and expands prescriber flexibility in early-line rheumatoid arthritis protocols.
Market Restraints
- Biologic Manufacturing Concentration:Mammalian cell culture capacity clusters in Switzerland, Ireland, and Singapore, creating single-source vulnerability for monoclonal antibody supply.
- EMA Extrapolation Friction:Indication expansion without dedicated clinical trials generates payer skepticism and prior authorization delays in psoriatic arthritis and axial spondyloarthritis.
- Originator Defense Tactics:Patent thicket strategies around formulation devices and subcutaneous delivery mechanisms prolong exclusivity periods beyond composition-of-matter expiration.
Strategic Opportunities
- Japan's Biosimilar Uptake Gap:PMDA's streamlined approval pathway for reference biologics with established EMA or FDA precedent offers first-mover positioning in a historically originator-loyal market.
- IL-17/IL-23 Pathway Convergence:Mechanism-of-action overlap between psoriasis and psoriatic arthritis creates indication-stacking potential with shared clinical trial infrastructure.
- Home Administration Transition:Prefilled syringe and auto-injector formats enable rheumatology practices to shift infusion-dependent patients to self-injection, reducing site-of-care bottlenecks.
Industry Challenges
- Immunogenicity Surveillance Complexity:Neutralizing antibody testing requirements for biosimilars demand specialized laboratory partnerships that many regional health systems lack.
- Reimbursement Code Fragmentation:J-code granularity for originator versus biosimilar products creates claims processing delays and patient cost-share confusion at pharmacy benefit managers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rheumatology Therapeutics Market |
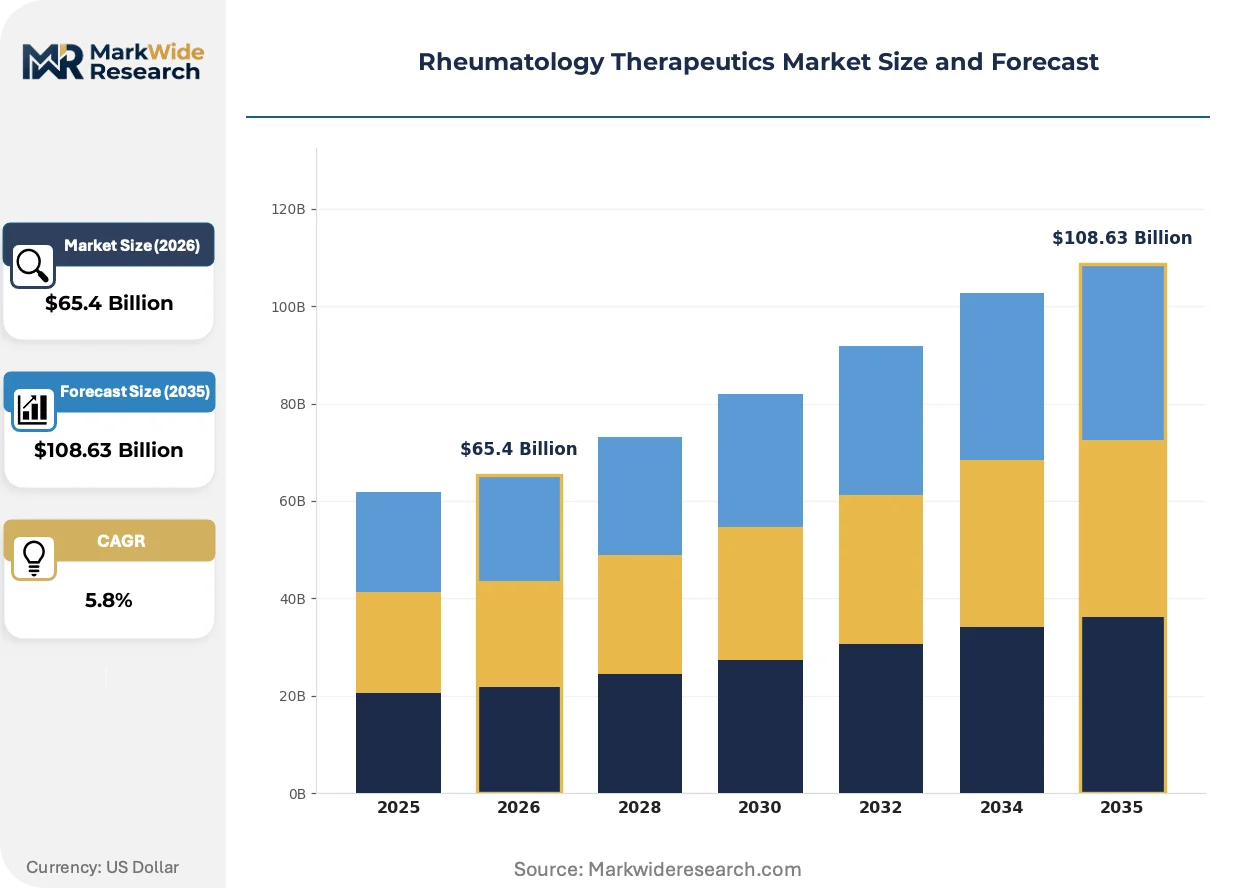
| Market Size in 2026 | $65.4 Billion |
| Market Size in 2035 | $108.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, DMARDs, NSAIDs, Corticosteroids, Janus Kinase Inhibitors Indication: Rheumatoid Arthritis, Osteoarthritis, Ankylosing Spondylitis, Lupus Erythematosus, Psoriatic Arthritis End User: Hospitals, Specialty Clinics, Ambulatory Care Centers, Rheumatology Practices, Research Institutes Delivery Mode: Oral Administration, Subcutaneous Injection, Intravenous Infusion, Topical Application, Intra-articular Injection |
| Companies Covered | Bristol-Myers Squibb Company, Novartis AG, AbbVie Inc., UCB S.A., F. Hoffmann-La Roche Ltd, Pfizer Inc., Johnson & Johnson, Eli Lilly and Co, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rheumatology Therapeutics Market Strategic Shifts & Innovations
Therapeutic modality diversification and administration site decentralization are compressing traditional biologic dominance while oral alternatives capture protocol positioning.
Biosimilar development is supplanting originator biologic prescribing in TNF inhibitor categories as rheumatology practices prioritize cost containment. Hospital systems and integrated delivery networks now mandate step-therapy protocols that position FDA-interchangeable biosimilars as preferred agents. This substitution dynamic compresses margin pools for reference products while expanding pharmacy benefit manager formulary control.
EMA's evolving extrapolation policy is reshaping clinical trial investment patterns for mechanism-of-action expansions. The guidance permits efficacy inference across related inflammatory indications without dedicated patient enrollment, reducing development timelines for IL-6 and IL-17 pathway agents. German and French health technology assessment bodies are responding with indication-specific pricing adjustments that de-link reimbursement from originator reference points.
Patient-administered delivery formats are disrupting infusion-center dependency in maintenance-phase rheumatoid arthritis. Rheumatology practices in the United States and Germany are converting stable patients from intravenous tocilizumab or infliximab to subcutaneous equivalents, reallocating nursing capacity to new patient onboarding. This channel shift accelerates as auto-injector training protocols standardize across specialty pharmacy networks.
Rheumatology Therapeutics Market Segmentation
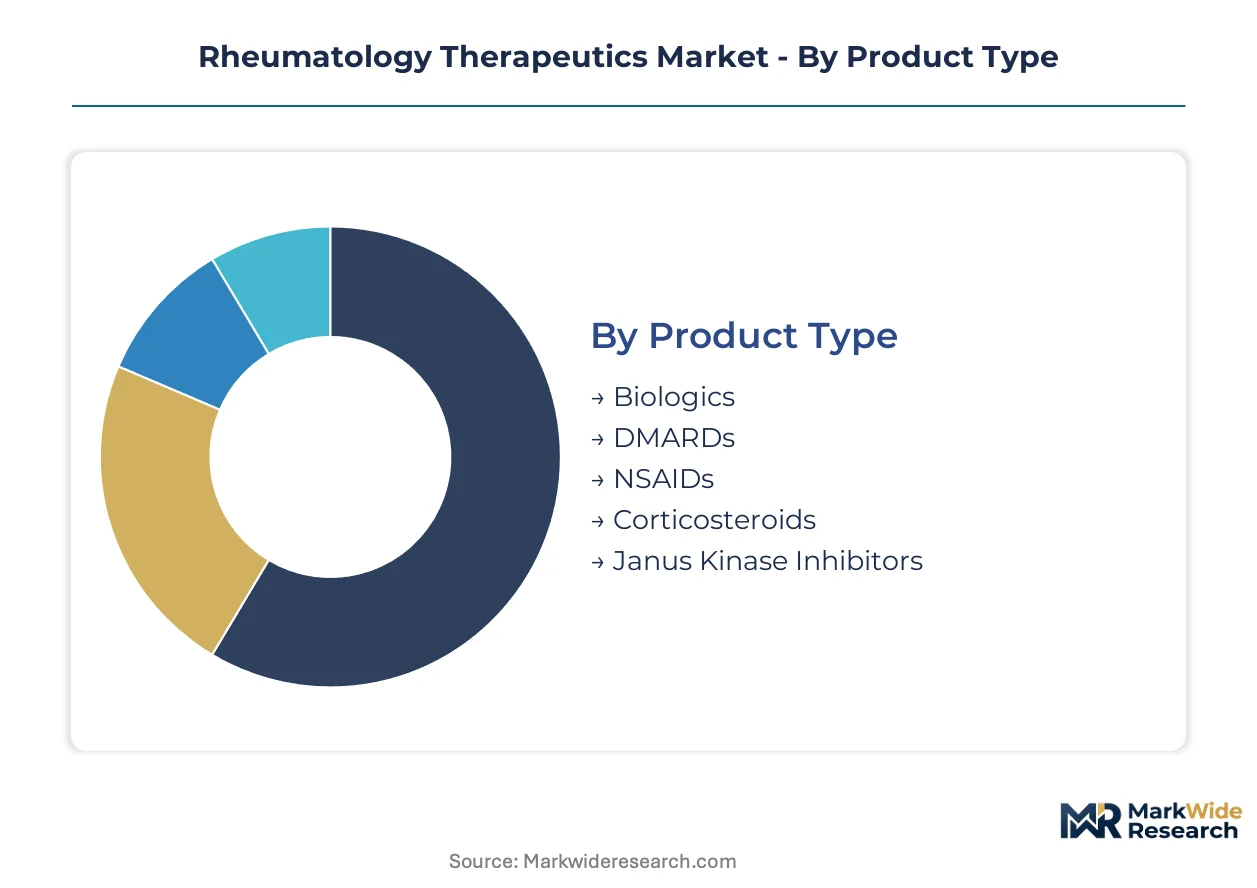
Therapeutic modality and site-of-care fragmentation in rheumatology creates distinct margin pools and regulatory exposure profiles. Segment-level dynamics determine whether manufacturers compete on manufacturing scale, clinical trial infrastructure, or pharmacy benefit manager contracting leverage.
Product Type:
Domestic formulation capabilities cluster around small-molecule production, while biologic manufacturing remains concentrated in Switzerland, Ireland, and Singapore for export markets.
- Biologics:Monoclonal antibodies and fusion proteins manufactured through mammalian cell culture command premium pricing due to cold-chain requirements and biosimilar lag. Demand concentrates in the United States and Germany where reimbursement frameworks for TNF inhibitors and IL-6 pathway drugs remain most established.
- Janus Kinase Inhibitors:Oral small-molecule therapeutics targeting intracellular signaling pathways eliminate infusion-center dependency. Prescribing flexibility in early-line rheumatoid arthritis protocols drives uptake in Japan and the United States as rheumatologists prioritize patient convenience.
- DMARDs:Conventional synthetic disease-modifying antirheumatic drugs sustain volume across early-line protocols.
- NSAIDs:Non-steroidal anti-inflammatory drugs address symptomatic management in osteoarthritis populations.
- Corticosteroids:Glucocorticoid formulations provide bridging therapy during biologic onset periods.
Biologics commands the established base. The steepest expansion runs through Janus Kinase Inhibitors.
Indication:
Clinical trial investment patterns diverge sharply between indications with established biomarker endpoints versus those requiring radiographic progression outcomes.
- Rheumatoid Arthritis:The most intensively studied autoimmune indication with validated ACR20/50/70 response criteria and established treat-to-target protocols. Patient recruitment infrastructure in the United States and Germany supports accelerated enrollment for novel mechanism trials.
- Psoriatic Arthritis:Mechanism-of-action overlap with psoriasis creates indication-stacking potential and shared clinical trial infrastructure. Dermatology-rheumatology crossover prescribing in the United States expands addressable prescriber base beyond traditional rheumatology practices.
- Osteoarthritis:Structural disease with limited biologic penetration due to lack of disease-modifying efficacy data.
- Ankylosing Spondylitis:Axial spondyloarthritis spectrum disorder with MRI-based outcome requirements.
- Lupus Erythematosus:Heterogeneous disease manifestation complicating endpoint selection and regulatory pathways.
Rheumatoid Arthritis anchors current revenue concentration. Psoriatic Arthritis is climbing the fastest as indication expansion strategies multiply.
End User:
Site-of-care economics and reimbursement differentials are reallocating patient volume across institutional settings.
- Specialty Clinics:Independent infusion centers capture complex biologic administration cases migrating from hospital outpatient departments. Reduced overhead reimbursement differentials and improved patient throughput attract rheumatology practices in the United States and Germany.
- Hospitals:Academic medical centers retain clinical trial participation and refractory case management. EMA's evolving extrapolation policy generates payer skepticism and prior authorization delays that hospital systems navigate through dedicated prior authorization staff.
- Rheumatology Practices:Private practice settings convert stable patients to self-injection formats.
- Ambulatory Care Centers:Federally qualified health centers and community-based facilities.
- Research Institutes:Contract research organizations and academic trial sites.
Hospitals retain the protocol-setting position. Specialty Clinics is gaining share fastest as site-of-care policies shift.
Delivery Mode:
Supply chain configuration and patient self-efficacy requirements segment manufacturing investment and training infrastructure.
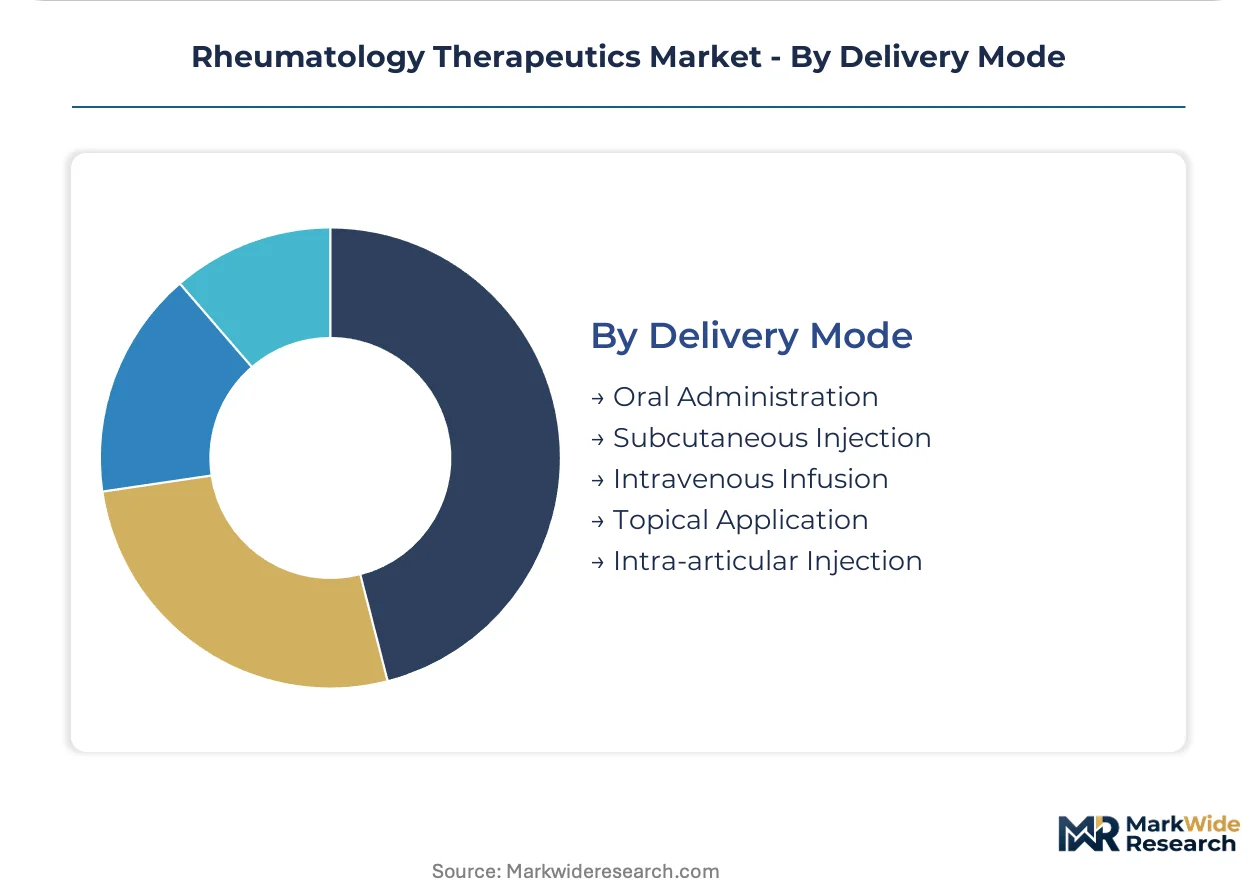
- Subcutaneous Injection:Prefilled syringe and auto-injector formats enable home administration transition for maintenance-phase patients. Rheumatology practices in the United States and Germany convert stable patients from intravenous equivalents, reallocating nursing capacity to new patient onboarding.
- Intravenous Infusion:Hospital and specialty clinic-dependent administration for loading doses and non-responders requiring dose escalation. Manufacturing concentration in Switzerland and Ireland creates single-source vulnerability for monoclonal antibody supply.
- Oral Administration:Small-molecule tablets eliminating cold-chain logistics.
- Topical Application:Localized delivery for limited joint involvement.
- Intra-articular Injection:Direct joint space administration for monoarticular flares.
Intravenous Infusion maintains the revenue base. Subcutaneous Injection is expanding most quickly as auto-injector training protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure anchors European biologic distribution, while Singapore's Changi cargo hub mediates Asia-Pacific supply. Germany's Rhine corridor rail network connects Swiss manufacturing to continental infusion centers.
United States
Medicare Part B reimbursement differentials and commercial payer step-therapy protocols concentrate demand for TNF inhibitors and IL-6 pathway drugs. FDA interchangeability designations permit pharmacy-level biosimilar substitution without prescriber consultation. The Boston-Cambridge corridor hosts rheumatology clinical trial infrastructure and biologic manufacturing partnerships.
Germany
Hospital outpatient departments and independent infusion centers compete for biologic administration volume under unified reimbursement frameworks. EMA extrapolation policies shape health technology assessment outcomes for indication expansion without dedicated trials. The Rhine-Main region clusters specialty pharmacy distribution and rheumatology practice networks.
Japan
PMDA's streamlined approval pathway for reference biologics with established FDA or EMA precedent accelerates biosimilar market entry. Aging demographics and rheumatoid arthritis prevalence sustain demand for Janus kinase inhibitor convenience. The Kanto region concentrates rheumatology specialist practices and hospital-based infusion capacity.
Switzerland
Mammalian cell culture manufacturing clusters around Basel and Geneva supply monoclonal antibodies to European and Asian markets. Swissmedic's alignment with EMA standards expedites cross-border regulatory recognition. The country's biologic production concentration creates single-source vulnerability for global supply chains.
Singapore
Changi Airport's temperature-controlled cargo infrastructure positions the city-state as Asia-Pacific distribution hub for cold-chain biologics. Regulatory harmonization with FDA and EMA standards attracts regional clinical trial investment. Biologic manufacturing capacity serves Japanese and Australian reimbursement markets.
Rheumatology Therapeutics Market Key Industry Players
Concentration sits with large-cap pharmaceutical incumbents holding patent-protected biologic portfolios and captive manufacturing infrastructure. Three to five originator manufacturers command margin pools in TNF inhibitor and IL pathway categories, while mid-scale biosimilar specialists erode pricing through FDA-interchangeable designations. Strategic archetypes include originator defenders leveraging formulation device patents, biosimilar pure-plays exploiting extrapolation pathways, and diversified pharmaceutical conglomerates balancing biologic and small-molecule exposure. Competitive moves center on indication-stacking across autoimmune overlap diseases and site-of-care contracting to capture infusion-center volume.
Among diversified pharmaceutical conglomerates, AbbVie Inc., Pfizer Inc., and Eli Lilly and Co exemplify distinct strategic positioning within the sector. AbbVie Inc. occupies a position anchored in originator biologic manufacturing scale and supply chain control. Pfizer Inc. represents the oral small-molecule alternative archetype through its Janus kinase inhibitor portfolio. Eli Lilly and Co sits within the IL pathway specialization tier targeting psoriatic arthritis overlap indications.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Novartis AG |
| AbbVie Inc. |
| UCB S.A. |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Johnson & Johnson |
| Eli Lilly and Co |
| Amgen Inc. |
| Others |
Cost & Logistics Intelligence
Mammalian cell culture capacity utilization rates above 85% in Swiss and Irish facilities create natural price floors for monoclonal antibody therapeutics, concentrating manufacturing leverage among originator biologic producers while compressing margin pools for biosimilar entrants competing on pharmacy benefit manager formularies.
Pricing Analysis
Three-tier pricing structure across originator biologics, FDA-interchangeable biosimilars, and conventional synthetic DMARDs segments rheumatology therapeutics by patent status and manufacturing complexity. Price differentiation rests on cold-chain logistics requirements and indication-specific reimbursement codes, with originator TNF inhibitors commanding premium positioning against interchangeable alternatives. Cost compression in the biosimilar tier is intensifying because Medicare Part B reimbursement differentials narrow with each new interchangeability designation. Hospital systems exhibit highest price sensitivity due to 340B drug pricing program exposure, while specialty clinics prioritize throughput economics over per-unit acquisition costs.
Supply Chain Analysis
Just-in-time inventory strategies dominate biologic distribution to minimize cold-chain degradation risk, though EMA's evolving extrapolation policy has prompted strategic stockpiling of reference biologics ahead of indication expansion decisions. Geographic supply concentration clusters in Switzerland, Ireland, and Singapore for mammalian cell culture production, with prefilled syringe and auto-injector device manufacturing anchored in Germany and the United States. Raw material dependencies include cell culture media, single-use bioreactor components, and pharmaceutical-grade glass for syringe barrels. Single-source vulnerability for monoclonal antibody supply creates exposure to Swissmedic inspection delays or Changi Airport temperature-controlled cargo disruptions. Distribution runs through specialty pharmacy networks and hospital outpatient departments with divergent reimbursement economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rheumatology therapeutics function as a service-attach opportunity where patient training programs, injection administration support, and prior authorization management services expand faster than biologic hardware margins, creating recurring revenue layers that offset originator price erosion.
For Market Incumbents: Secure captive biologic manufacturing capacity in Basel or Singapore to defend against biosimilar volume capture, while investing in subcutaneous auto-injector device patents that extend exclusivity beyond composition-of-matter expiration. FDA interchangeability designations represent the primary threat to originator pricing power; channel control through specialty pharmacy partnerships offers defensive leverage against pharmacy benefit manager formulary exclusion. For New Entrants and Emerging Players: Lead with IL-17 and IL-23 pathway specialization in psoriatic arthritis overlap indications where dermatology-rheumatology crossover prescribing expands addressable prescriber bases beyond traditional rheumatology practices. Japan's biosimilar uptake gap offers the most penetrable geography given PMDA's streamlined approval pathway for reference biologics with established FDA or EMA precedent. A go-to-market angle centered on home administration transition and auto-injector training protocols differentiates against infusion-center-dependent incumbents. For Investors and Strategic Acquirers: Biosimilar pure-plays with FDA-interchangeable designations and extrapolation pathway expertise command premium positioning as pharmacy substitution authority expands. Long-term viability over the analysis window hinges on manufacturing scale economics and payer contracting leverage rather than pipeline novelty. The signal to watch is EMA indication expansion decisions without dedicated clinical trials, which accelerate biosimilar addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive mammalian cell culture capacity in Switzerland or Ireland insulates against single-source supply disruptions. |
| Regulatory Approval Pathway | FDA interchangeability designation permits pharmacy-level substitution without prescriber consultation, accelerating volume capture. |
| Licensing Agreement | EMA extrapolation rights for IL-6 and IL-17 pathway agents reduce clinical trial investment requirements. |
| Pipeline Diversification | IL-23 pathway expansion into psoriatic arthritis leverages shared dermatology-rheumatology prescriber infrastructure. |
| Clinical Trial Advancement | ACR20/50/70 endpoint validation in rheumatoid arthritis supports accelerated enrollment for novel mechanism trials. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at pharmacy benefit managers, and hospital procurement managers. Secondary validation drew from FDA biosimilar approval filings, EMA extrapolation policy documents, ClinicalTrials.gov enrollment data, and Medicare Part B reimbursement code databases. Bottom-up patient volume estimates by indication and top-down manufacturer revenue triangulation were cross-referenced to resolve segmentation discrepancies.
Across the analysis window, the forecasting framework modeled therapeutic modality splits, site-of-care migration patterns, and regional regulatory cluster adoption curves. CAGRs were derived from log-linear trend fitting across annualized volume and value estimates, with segmentation dimensions including treatment line positioning, administration route, and patient population severity. Forecast inputs incorporated PMDA approval pathway timelines and specialty clinic expansion rates.
The analysis sits within stated boundaries; outcomes outside stable FDA interchangeability policy and EMA extrapolation precedent would require recalibration. Forecasts reflect documented assumptions around biosimilar substitution velocity and site-of-care reimbursement differentials. Revision becomes warranted when immunogenicity surveillance requirements or J-code granularity reforms cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Alirocumab Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Synthetic Drugs Market
Pharmaceuticals
Global Primary Biliary Cirrhosis Drug Market
Pharmaceuticals
Ion Channel Modulators Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Multiple System Atrophy (MSA) Therapeutics Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
New Zealand Diabetes Drugs Market