
 Leflunomide Market | 2026-2036
Leflunomide Market Size, Share, and Industry Trends Forecast 2026-2036
Leflunomide Market Insights
Single-source API procurement for leflunomide is consolidating toward vertically integrated manufacturers with captive pyrimidine synthesis capability. Sanofi leverages its established teriflunomide-leflunomide manufacturing complex to sustain cost advantages in active metabolite production. Teva Pharmaceutical Industries Ltd anchors North American generic supply through FDA-approved abbreviated new drug applications. Dr. Reddy's Laboratories Ltd competes on volume scale from its Indian formulation facilities.
Leflunomide is an isoxazole derivative immunomodulatory agent that inhibits dihydroorotate dehydrogenase, disrupting pyrimidine synthesis in proliferating lymphocytes with a loading dose of 100 mg daily followed by 20 mg maintenance. The compound serves primarily as a disease-modifying antirheumatic drug for rheumatoid arthritis management. Tablets dominate commercial volume due to established oral bioavailability and decades of clinical validation, while extended-release formulations represent the fastest-growing product type as patents expire and formulation differentiation intensifies. Rheumatoid arthritis commands the largest therapy area share, though inflammatory bowel disease applications are expanding off-label under specialist protocols.
FDA bioequivalence requirements under 21 CFR 320 govern generic leflunomide entry, while EMA guidelines through the Committee for Medicinal Products for Human Use shape European market access standards. India's CDSCO enforces bulk drug and formulation manufacturing inspections that determine export eligibility for API suppliers. Stakeholders must monitor evolving pharmacovigilance obligations for teratogenicity risk management as regulatory scrutiny of immunosuppressant safety intensifies across jurisdictions.
Market Dynamics
FDA bioequivalence enforcement for generic immunosuppressants is restructuring competitive entry pathways, while Medicare reimbursement policies in the United States concentrate demand around oral disease-modifying antirheumatic drugs. API procurement consolidation toward vertically integrated pyrimidine synthesis specialists further tightens supply-side control.
Growth Catalysts
- Rheumatoid arthritis hospital protocols:Treatment standardization in tertiary care settings anchors volume demand for leflunomide as first-line DMARD therapy.
- Medicare Part D reimbursement:Favorable coverage for oral DMARDs under United States federal insurance programs sustains patient access and prescription volumes.
- Teriflunomide-leflunomide manufacturing synergies:Captive pyrimidine synthesis capabilities reduce active metabolite production costs for integrated manufacturers.
Market Restraints
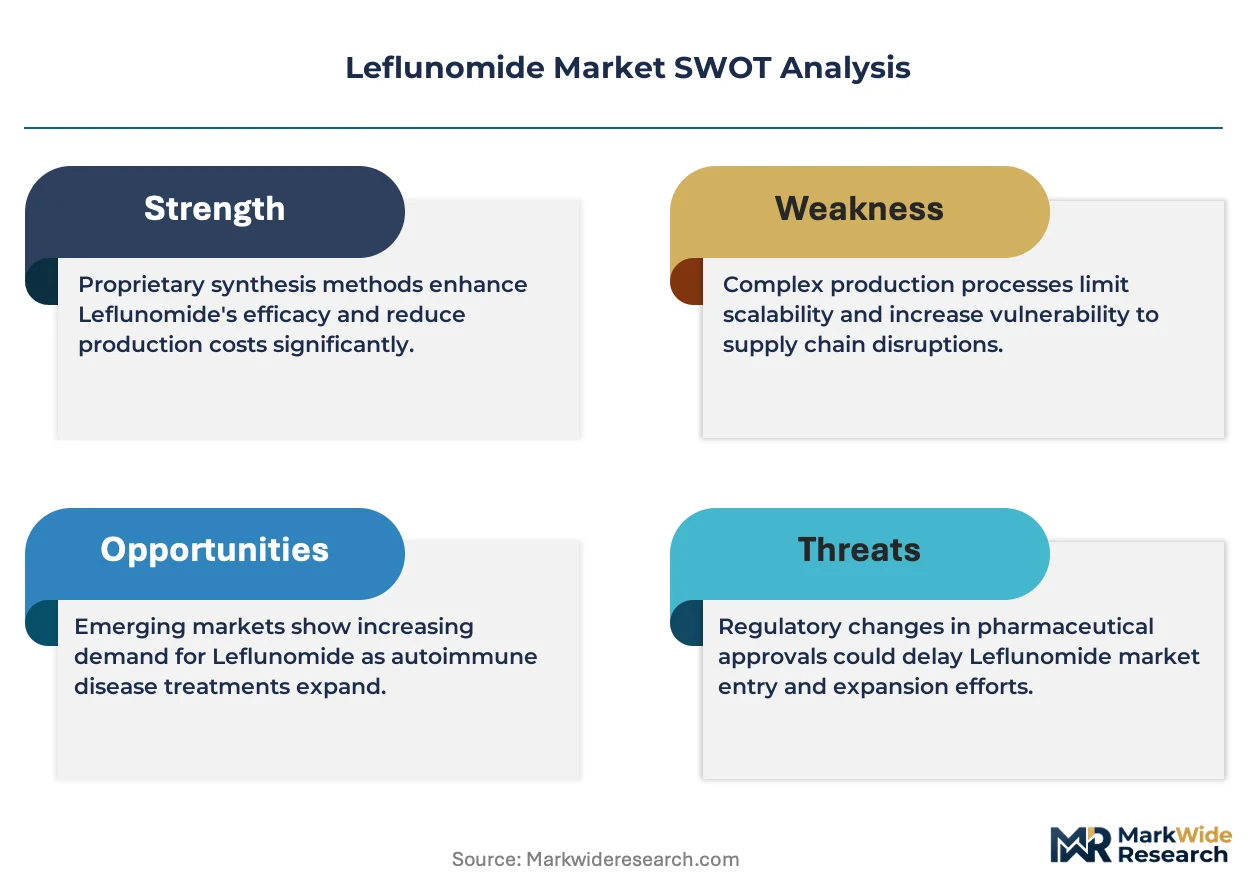
- Teratogenicity regulatory burden:FDA Risk Evaluation and Mitigation Strategies impose distribution and prescriber certification requirements that limit pharmacy channel flexibility.
- Single-source API concentration:Dependence on Indian bulk drug manufacturers for pyrimidine intermediates exposes formulations to CDSCO inspection delays and export permit volatility.
- Generic price compression:Abbreviated new drug application approvals under 21 CFR 314 erode branded margins without corresponding volume expansion.
Strategic Opportunities
- Extended-release formulation differentiation:Patent-expired markets enable 24-hour dosing products to capture patient compliance premiums in rheumatoid arthritis maintenance therapy.
- Inflammatory bowel disease off-label expansion:Specialist gastroenterology protocols in academic medical centers are piloting leflunomide as steroid-sparing therapy.
- Indian CDSCO export certification:Bulk drug and formulation inspections qualifying domestic manufacturers for regulated market supply create API sourcing alternatives to Chinese intermediates.
Industry Challenges
- Pharmacovigilance workforce scarcity:Immunosuppressant safety monitoring requires specialized teratogenicity risk management expertise that outpaces regulatory affairs hiring.
- Bioequivalence study complexity:21 CFR 320 requirements for active metabolite measurement extend generic development timelines and raise clinical trial costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leflunomide Market |
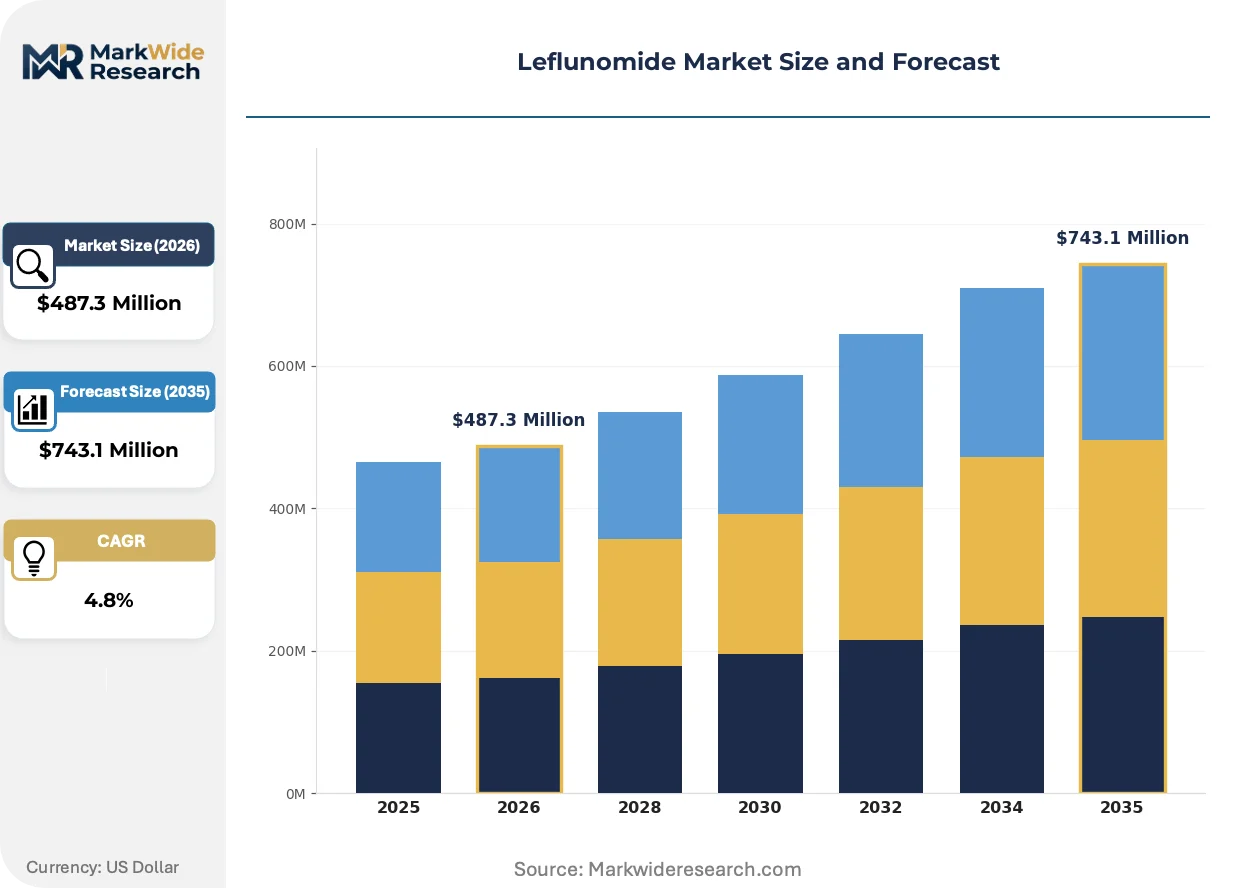
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable, Extended Release, Combo Therapy Therapy Area: Rheumatoid Arthritis, Psoriasis, Multiple Sclerosis, Inflammatory Bowel Disease Delivery Mode: Oral, Subcutaneous, Intravenous, Transdermal End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers |
| Companies Covered | Sanofi, Teva Pharmaceutical Industries Ltd, Sun Pharmaceutical Industries Ltd, Lupin Pharmaceuticals, Inc., AbbVie Inc., Pfizer Inc., Dr. Reddy's Laboratories Ltd., Aurobindo Pharma Limited, Sandoz International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leflunomide Market Trends and Innovations
Formulation science and regulatory science are converging to reshape how leflunomide reaches patients, with extended-release technologies and bioequivalence methodologies commanding disproportionate R&D investment.
Extended-release tablet platforms are overtaking immediate-release formats in new product development pipelines. These formulations maintain therapeutic plasma levels of teriflunomide with once-daily dosing, improving adherence among rheumatoid arthritis patients on maintenance therapy. Hospital formularies in the United States are adding these products to preferred drug lists, compressing the commercial viability of standard tablets.
EMA Committee for Medicinal Products for Human Use guidelines on immunosuppressant generic substitution are tightening bioequivalence demonstration standards. The industrial consequence is elevated clinical pharmacology study costs and extended regulatory review timelines for abbreviated new drug applications. European national health technology assessment bodies are responding by requiring additional real-world evidence for formulary inclusion of generic leflunomide.
Specialty pharmacy distribution is consolidating patient access for teratogenic drugs under Risk Evaluation and Mitigation Strategy protocols. Mail-order channels with certified pharmacist counseling are displacing retail pharmacy dispensing for leflunomide prescriptions in the United States. This channel shift concentrates volume with pharmacy benefit managers operating closed networks, reducing price transparency for end patients.
Leflunomide Market Segmentation
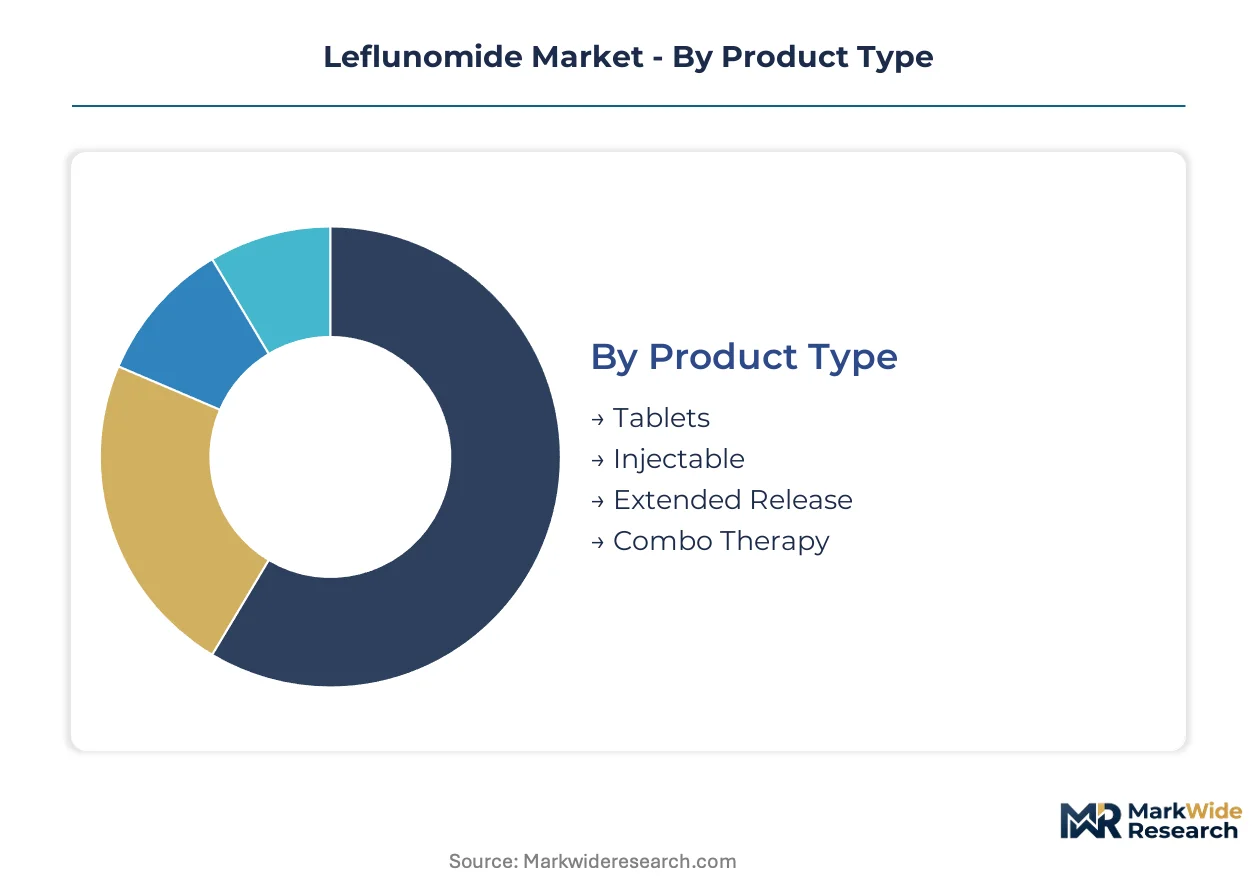
Segmentation in the leflunomide market reveals how formulation technology, therapy protocols, and reimbursement structures concentrate value across distinct patient access pathways. Understanding these divisions exposes where manufacturing scale, regulatory certification, and clinical evidence requirements create sustainable competitive positions.
Product Type:
Supply concentration in active metabolite production favors manufacturers with captive pyrimidine synthesis, tilting competitive advantage toward integrated players who control teriflunomide-leflunomide manufacturing complexes.
- Tablets:Immediate-release oral formulations containing 10 mg or 20 mg leflunomide with established bioavailability profiles and decades of clinical validation. Hospital formularies in the United States anchor volume demand through standardized rheumatoid arthritis protocols, though generic price compression under Medicare Part D reimbursement erodes margin expansion.
- Extended Release:Matrix-controlled or osmotic pump technologies maintaining therapeutic teriflunomide plasma levels over 24 hours with once-daily dosing. Patient compliance premiums in maintenance therapy are climbing the fastest as hospital formularies add these products to preferred drug lists and displace standard tablet volumes.
- Injectable:Sterile parenteral formulations for patients with severe gastrointestinal intolerance or rapid disease progression requiring precise dose titration.
- Combo Therapy:Fixed-dose combinations with methotrexate or other DMARDs for refractory rheumatoid arthritis cases requiring multimodal immunosuppression.
Today's leader: Tablets. Tomorrow's challenger: Extended Release.
Therapy Area:
Cost tier stratification separates hospital-administered protocols from outpatient maintenance regimens, with reimbursement intensity determining where formulation innovation earns returns.
- Rheumatoid Arthritis:Autoimmune joint destruction managed through dihydroorotate dehydrogenase inhibition with loading dose protocols. Tertiary care centers in the United States concentrate demand through standardized first-line DMARD therapy pathways.
- Inflammatory Bowel Disease:Off-label ulcerative colitis and Crohn's disease applications expanding under specialist gastroenterology protocols in academic medical centers as steroid-sparing alternatives.
- Psoriasis:Plaque psoriasis management leveraging leflunomide's antiproliferative effects on keratinocyte hyperplasia in dermatology clinic settings.
- Multiple Sclerosis:Limited use in progressive forms where teriflunomide's lymphocyte suppression overlaps with approved indications for the active metabolite.
Rheumatoid Arthritis commands current volume. Inflammatory Bowel Disease presents the steepest expansion trajectory for off-label protocol development.
Delivery Mode:
Application requirements from end users reshape manufacturing investment, with oral formats dominating scale economics and parenteral routes demanding specialized aseptic capacity.
- Oral:Gastrointestinal absorption with established food-effect profiles and decades of patient self-administration experience. Home care settings in the United States drive prescription volumes through Medicare Part D pharmacy benefit structures.
- Subcutaneous:Prefilled syringe or autoinjector delivery for patients requiring rapid immunosuppression onset or with tablet intolerance.
- Intravenous:Hospital-infused formulations for acute disease flares or perioperative immunosuppression management in surgical settings.
- Transdermal:Patch-based delivery systems in early development for patients with hepatic metabolism concerns or dosing flexibility requirements.
Oral delivery sustains volume leadership. Subcutaneous formats are gaining share fastest through specialty pharmacy channel expansion.
End User:
Customer type segmentation maps directly to reimbursement complexity, with institutional purchasers negotiating formulary placement against retail pharmacy distribution economics.
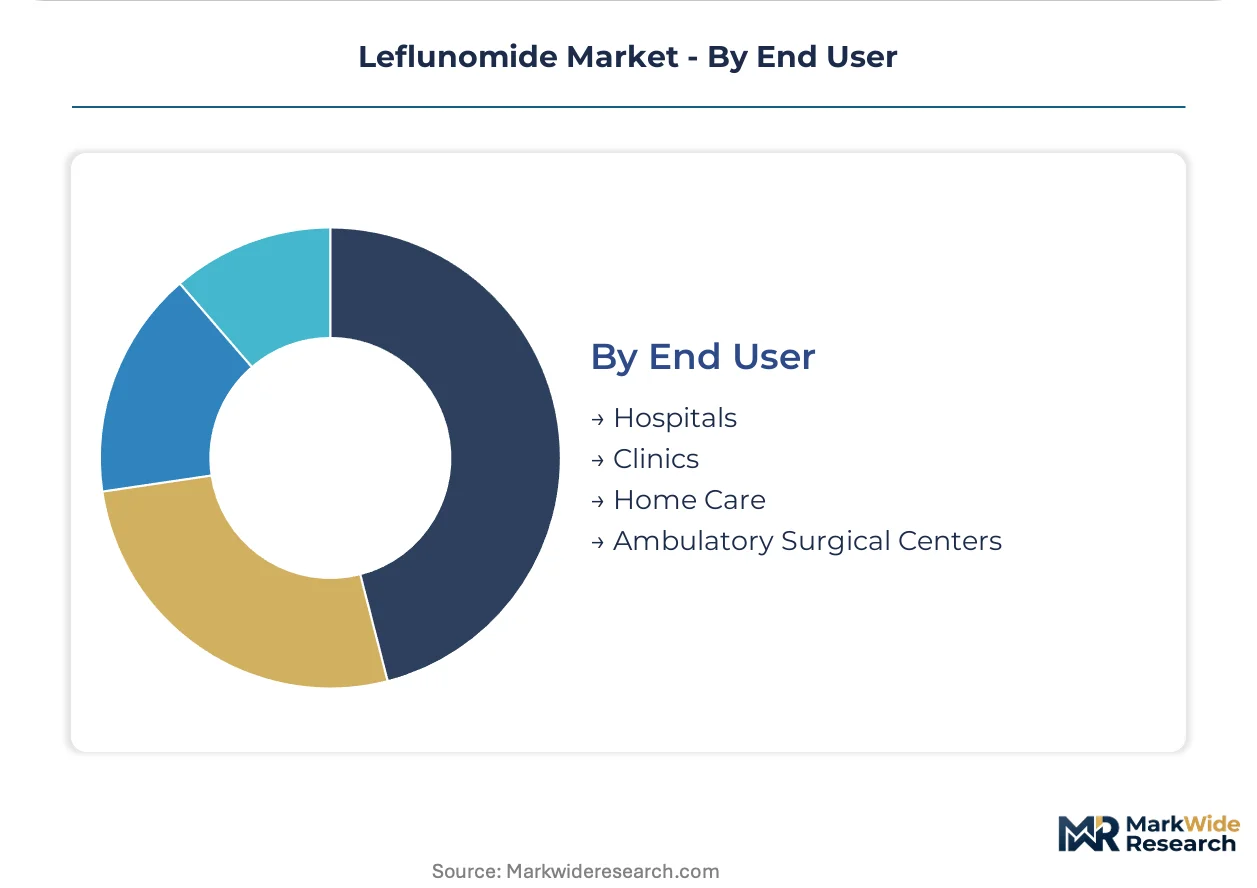
- Hospitals:Inpatient and outpatient infusion centers with pharmacy and therapeutics committees controlling DMARD protocol standardization. Medicare reimbursement policies favoring oral disease-modifying antirheumatic drugs concentrate prescription volumes in United States health systems with integrated specialty pharmacy operations.
- Home Care:Mail-order and specialty pharmacy channels with certified pharmacist counseling under FDA Risk Evaluation and Mitigation Strategy protocols for teratogenic drugs.
- Clinics:Rheumatology and gastroenterology private practices with direct purchasing relationships for oral maintenance therapy.
- Ambulatory Surgical Centers:Limited perioperative immunosuppression management for joint replacement patients with active rheumatoid arthritis.
Hospitals anchor current demand concentration. Home Care channels are expanding most quickly through Risk Evaluation and Mitigation Strategy consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian bulk drug manufacturers anchor API supply networks for leflunomide, with Hyderabad and Ahmedabad clusters dominating pyrimidine intermediate production. Regulatory certification patterns and reimbursement structures vary sharply across major pharmaceutical markets.
United States
Medicare Part D reimbursement policies concentrate prescription volumes for oral DMARDs in integrated health systems. FDA Risk Evaluation and Mitigation Strategies impose specialty pharmacy distribution requirements for teratogenic drugs. Boston and Philadelphia hospital networks standardize leflunomide protocols in rheumatoid arthritis care pathways.
Germany
EMA Committee for Medicinal Products for Human Use guidelines shape bioequivalence standards for generic immunosuppressant substitution. Germany's statutory health insurance funds negotiate reference pricing for leflunomide under AMNOG benefit assessment procedures. The Rhine-Main pharmaceutical cluster near Frankfurt sustains formulation manufacturing for European distribution.
India
CDSCO bulk drug inspections determine export eligibility for API suppliers serving regulated markets. India's PLI scheme for pharmaceuticals incentivizes domestic production of critical immunosuppressant intermediates. Hyderabad's active pharmaceutical ingredient corridor supplies pyrimidine synthesis capabilities to global formulation manufacturers.
Japan
PMDA pharmacovigilance requirements enforce strict teratogenicity risk management for immunosuppressant prescribing. Japan's National Health Insurance price listing process determines reimbursement levels for leflunomide tablets. The Kansai region's Osaka pharmaceutical hub maintains quality certification for export-oriented API production.
United Kingdom
NICE technology appraisals guide National Health Service commissioning decisions for rheumatoid arthritis biologics and small-molecule DMARDs. The MHRA post-Brexit regulatory framework maintains alignment with EMA standards for generic drug approvals. London's academic medical centers pilot extended-release leflunomide formulations in specialist rheumatology protocols.
Leflunomide Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and regulatory certification dimensions. The leflunomide market structures around three tiers: originators with teriflunomide-leflunomide manufacturing complexes, North American generic specialists with FDA-approved abbreviated new drug applications, and Indian volume manufacturers with CDSCO-certified export facilities. Competitive moves center on backward integration into pyrimidine synthesis and extended-release formulation differentiation as patents expire.
Within the originator tier, Sanofi occupies a position exemplifying captive metabolite production advantages. Among North American generic specialists, Teva Pharmaceutical Industries Ltd anchors supply relationships through established regulatory filings. At the Indian manufacturing end, Dr. Reddy's Laboratories Ltd represents volume-scale API and formulation capabilities serving export markets. These three archetypes illustrate how competitive positioning depends on control over active metabolite supply chains versus regulatory access versus cost-efficient scale.
| Leading Market Players |
|---|
| Sanofi |
| Teva Pharmaceutical Industries Ltd |
| Sun Pharmaceutical Industries Ltd |
| Lupin Pharmaceuticals, Inc. |
| AbbVie Inc. |
| Pfizer Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Aurobindo Pharma Limited |
| Sandoz International GmbH |
| Others |
Pricing and Supply Chain Analysis
Pharmacovigilance specialists concentrated in Hyderabad and Ahmedabad create labor-cost differentials that widen pricing-tier spreads between REMS-certified specialty formulations and standard generic tablets. CDSCO inspection backlogs in these clusters delay export permit timelines, forcing buyers to absorb premium pricing for certified supply or accept longer lead times for economy-tier alternatives.
Pricing Analysis
Input-cost pass-through from pyrimidine intermediate volatility governs leflunomide pricing dynamics across manufacturer tiers. Three-tier pricing structure across REMS-certified specialty, FDA-approved standard, and economy export-grade levels separates hospital formulary placements from retail pharmacy substitution. Cost compression in the standard tablet segment is intensifying because abbreviated new drug application approvals under 21 CFR 314 multiply generic competitors without expanding volume. Hospital procurement committees demonstrate lowest price sensitivity due to protocol standardization requirements, while independent retail pharmacies face highest sensitivity under Medicare Part D reimbursement pressure.
Supply Chain Analysis
Warehouse-distribution layers for leflunomide operate through regional distribution centers in Mumbai and Newark, with hub-and-spoke patterns radiating to hospital systems and specialty pharmacy networks. API production concentrates in India, China, and the United States, with pyrimidine synthesis capabilities anchoring in Hyderabad's bulk drug corridor. Raw material dependencies include isoxazole precursors, dihydroorotate dehydrogenase inhibitors, and teriflunomide active metabolite intermediates. Single-source vulnerability in Indian CDSCO-certified facilities exposes formulation manufacturers to inspection-triggered supply interruptions. Distribution runs through closed-network pharmacy benefit managers with REMS-certified counseling capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where CDSCO export certification delays in India create pricing premiums for United States buyers with limited alternative sourcing.
For Market Incumbents: Deepen backward integration into captive pyrimidine synthesis to offset API procurement volatility from Indian bulk drug manufacturers. Secure REMS distribution channel control against specialty pharmacy consolidation that threatens price transparency. Add formulation capacity in United States territories to bypass CDSCO inspection bottlenecks affecting export eligibility. For New Entrants and Emerging Players: Begin with extended-release formulation development targeting hospital formulary preferred-drug-list placement as patents expire. Inflammatory bowel disease off-label protocols in academic medical centers represent the most penetrable therapy expansion. Pursue FDA abbreviated new drug application submission with bioequivalence studies measuring active metabolite levels under 21 CFR 320. For Investors and Strategic Acquirers: North American generic specialists with established FDA filings are the most active acquirer in this space, consolidating abbreviated new drug application portfolios to capture Medicare Part D volume. Long-term viability hinges on teriflunomide-leflunomide manufacturing complex control across the 5-10 year window. Target acquisition archetype: Indian CDSCO-certified API manufacturers with captive pyrimidine synthesis. Monitor EMA Committee for Medicinal Products for Human Use bioequivalence guideline tightening as inflection signal for European generic substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Distribution Network Expansion | Specialty pharmacy certification under FDA Risk Evaluation and Mitigation Strategies secures teratogenic drug dispensing exclusivity. |
| Extended-Release Formulation Development | Matrix-controlled technologies capture patient compliance premiums as hospital formularies displace immediate-release tablets. |
| CDSCO Export Certification Investment | Hyderabad and Ahmedabad facility inspections qualify Indian manufacturers for regulated market API supply alternatives. |
| Teriflunomide Manufacturing Complex Integration | Captive active metabolite production reduces dependency on single-source pyrimidine intermediate suppliers. |
| Inflammatory Bowel Disease Clinical Protocol Pilot | Academic medical center specialist protocols expand leflunomide applications beyond rheumatoid arthritis anchor indication. |
Research Methodology
Multiple input streams — regulatory filing databases, hospital formulary records, and bulk drug export permit registries — were reconciled against primary interviews with regulatory affairs directors, hospital pharmacy and therapeutics committee members, CDSCO inspection coordinators, and specialty pharmacy operations managers. Secondary validation drew from FDA Orange Book listings, EMA assessment reports, ClinicalTrials.gov protocol registries, and Indian pharmaceutical export statistics. Bottom-up prescription volume modeling and top-down API production capacity estimates were triangulated to anchor market sizing.
Data-stream reconciliation across the projection horizon employed segmentation dimensions spanning formulation type, therapy area protocol, delivery mode, and end-user channel with regional regulatory cluster overlays. CAGRs were derived from fitted growth curves applied to standardized prescription volumes and average selling price trajectories. Forecast inputs incorporated Medicare Part D reimbursement policy stability assumptions and CDSCO inspection clearance rate patterns.
Several conditions sit outside the modeled scope, including unannounced FDA bioequivalence guideline revisions, sudden CDSCO enforcement actions, and teratogenicity risk management protocol changes. Forecasts reflect documented assumptions about regulatory pathway stability and inspection timeline norms. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Carbapenem Market
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Anti Obesity Prescription Drugs Market
Pharmaceuticals
China Opioids Market