
 Antiplatelet Market | 2026-2036
Antiplatelet Market Size, Share, and Industry Trends Forecast 2026-2036
Antiplatelet Market Analysis
CE marking under the EU Medical Device Regulation is redrawing competitive access for combination antiplatelet devices in Europe. AstraZeneca leverages its ticagrelor franchise to sustain leadership in oral P2Y12 inhibition. Bayer AG anchors the aspirin segment through decades of cardiovascular risk-reduction positioning. Daiichi Sankyo Company competes in the prasugrel category with differentiated bleeding-risk profiles.
Antiplatelet agents are pharmaceutical compounds that inhibit platelet aggregation through cyclooxygenase inhibition, P2Y12 receptor antagonism, or glycoprotein IIb/IIIa blockade, typically formulated as immediate-release tablets, film-coated oral dosages, or intravenous solutions for acute coronary syndrome intervention. The oral delivery mode dominates prescription volumes due to patient compliance advantages and outpatient manageability, while the injectable segment captures premium pricing in periprocedural settings. Cardiovascular diseases command the largest application share, with stroke prevention representing the fastest-growing indication as transient ischemic attack protocols expand.
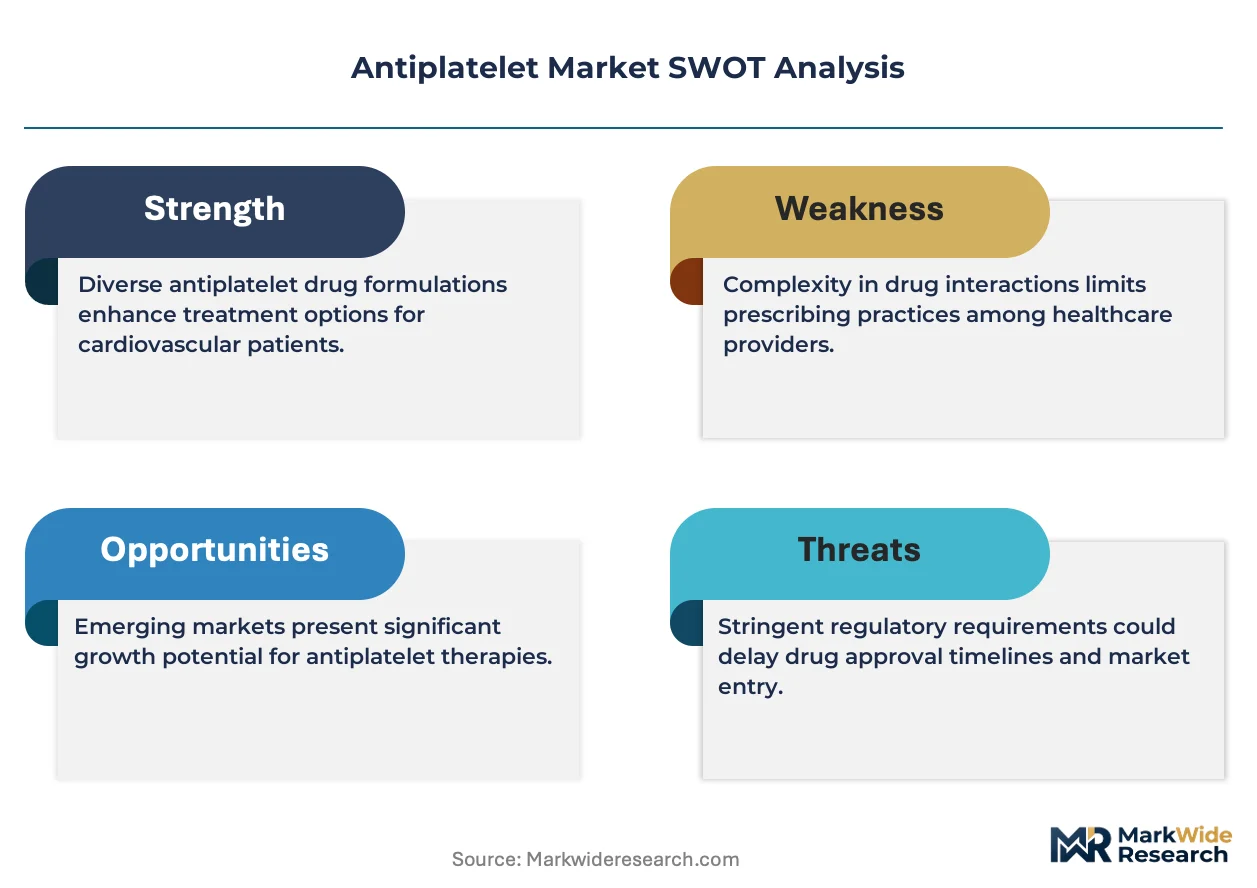
FDA pharmacovigilance mandates and EMA risk-management plans shape clinical trial design and post-approval labeling for antiplatelet developers. The EU AI Act and FDA's emerging guidance on machine-learning diagnostic companions are beginning to influence how antiplatelet therapy selection integrates with algorithmic risk scoring. Stakeholders must monitor how pharmacogenomic testing reimbursement policies in the United States and Germany reshape prescribing patterns for clopidogrel responders versus non-responders.
Market Dynamics
Pharmacogenomic stratification is fragmenting the oral P2Y12 inhibitor landscape as clopidogrel response variability forces payers to reimburse CYP2C19 testing before first-line therapy selection.
Growth Catalysts
- Aging cardiovascular patient pools:Japan, Germany, and the United States maintain expanding populations requiring chronic dual antiplatelet therapy post-percutaneous coronary intervention.
- FDA Risk Evaluation and Mitigation Strategies:Mandatory bleeding-risk disclosure protocols elevate physician confidence in newer agents with differentiated safety profiles.
- Point-of-care platelet function testing:Rapid turnaround assays in catheterization laboratories enable individualized loading-dose protocols during acute coronary syndrome events.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for thienopyridines clusters in specific Asian manufacturing zones, creating single-source vulnerability.
- Generic aspirin commoditization:Unbranded acetylsalicylic acid erodes pricing power across primary and secondary prevention segments in retail pharmacy channels.
- EMA pharmacovigilance burden:Periodic safety update report requirements extend post-approval compliance costs for oral P2Y12 inhibitors beyond original development timelines.
Strategic Opportunities
- Stroke prevention protocols:Transient ischemic attack management guidelines in Germany and Japan are expanding prescription eligibility beyond coronary indications.
- EU Medical Device Regulation convergence:Combination drug-device products with integrated antiplatelet delivery systems qualify for expedited review pathways.
- Algorithmic risk scoring integration:Machine-learning companion diagnostics paired with antiplatelet selection are gaining preliminary reimbursement traction in United States integrated delivery networks.
Industry Challenges
- Specialized hematology expertise gaps:Interpretation of platelet function assay results requires trained personnel that community hospitals struggle to retain.
- Legacy electronic health record interoperability:Antiplatelet therapy decision-support modules fail to integrate with established cardiology information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiplatelet Market |
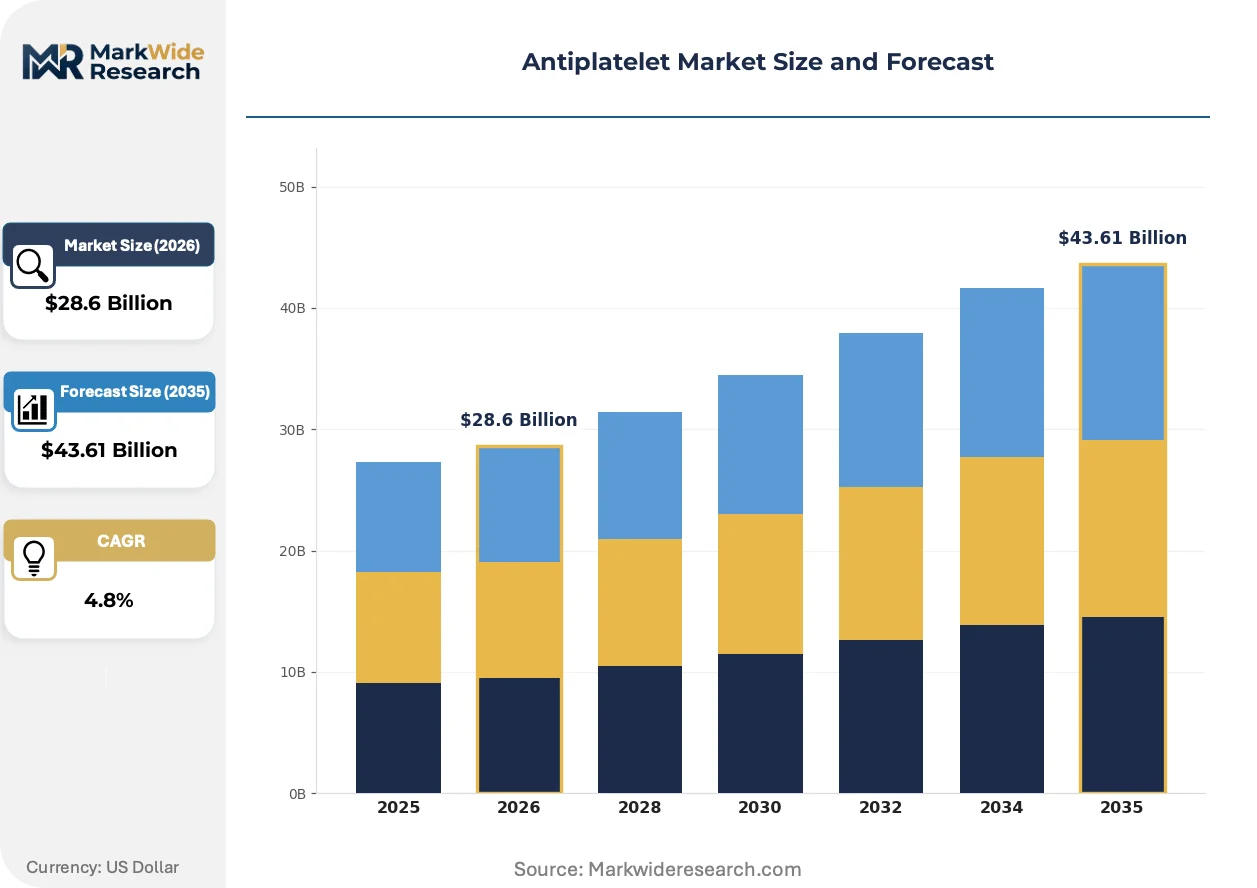
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspirin, Clopidogrel, Ticagrelor, Prasugrel End User: Hospitals, Clinics, Homecare Settings, Urgent Care Centers Delivery Mode: Oral, Injectable, Transdermal, Intravenous Application: Cardiovascular Diseases, Stroke Prevention, Peripheral Artery Disease, Others |
| Companies Covered | AstraZeneca, Bayer AG, Sanofi, Pfizer Inc., Eli Lilly and Company, Daiichi Sankyo Company, Boehringer Ingelheim, Bristol-Myers Squibb Company, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiplatelet Market Emerging Trajectories
Antiplatelet therapy development is pivoting toward precision-medicine frameworks that match agent selection to individual thrombotic risk profiles rather than protocol-driven uniform prescribing.
Implantable drug-eluting stent technology is miniaturizing strut thickness while maintaining polymer integrity for controlled antiproliferative and antiplatelet agent release. Interventional cardiologists in tertiary centers are adopting ultra-thin cobalt-chromium platforms at accelerated replacement cycles. This miniaturization is compressing the addressable market for systemic glycoprotein IIb/IIIa inhibitors during percutaneous coronary intervention.
EMA's Medical Device Regulation recertification deadlines are forcing combination product manufacturers to resubmit clinical evidence for antiplatelet-eluting coronary stents previously approved under the Active Implantable Medical Devices Directive. Industrial consequence includes extended regulatory timelines and redundant trial costs for legacy product portfolios. The stent segment is responding by consolidating submission strategies across European notified bodies.
Hospital procurement committees are consolidating antiplatelet formulary decisions through centralized pharmacy and therapeutics oversight rather than individual physician preference. This concentration is displacing traditional pharmaceutical representative access to prescribers. The shift is most visible in United States academic medical centers where integrated delivery network contracts override individual hospital purchasing autonomy.
Antiplatelet Market Segmentation
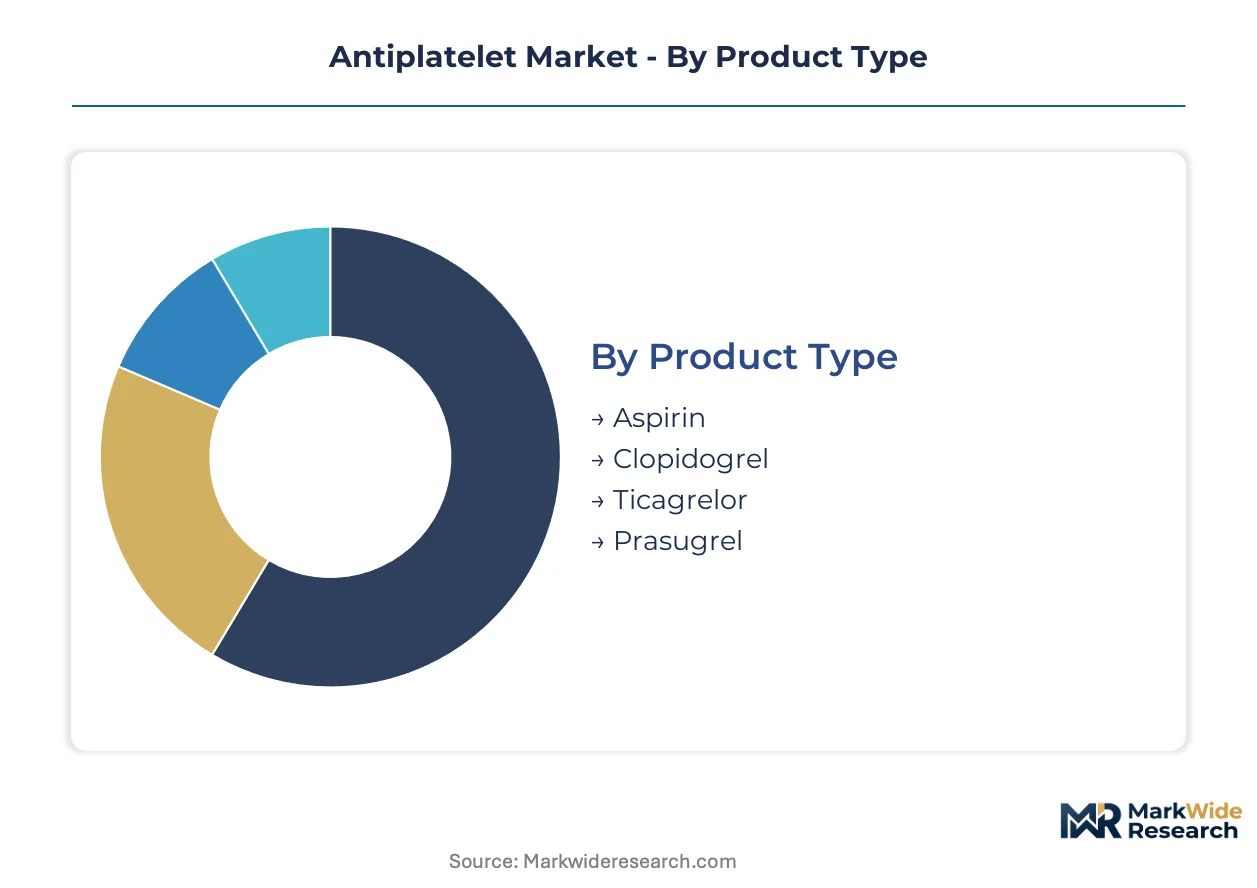
Antiplatelet segmentation reveals divergent margin structures across therapeutic classes and care settings. Product type stratification separates commoditized legacy agents from premium oral P2Y12 inhibitors commanding differentiated pricing power.
Product Type:
Margin concentration pools in oral P2Y12 receptor antagonists with patent-protected positioning, while aspirin anchors volume at compressed price points.
- Aspirin:Acetylsalicylic acid formulations dominate prescription volumes through decades of cardiovascular risk-reduction positioning. Primary care networks in the United States and Germany drive bulk procurement for secondary prevention protocols, though generic commoditization erodes branded pricing power across retail pharmacy channels.
- Clopidogrel:Thienopyridine prodrug requiring CYP2C19 hepatic activation exhibits significant pharmacogenomic response variability. Payers in Germany and the United States increasingly mandate CYP2C19 loss-of-function screening before first-line therapy selection, fragmenting demand toward alternatives in poor metabolizer populations.
- Ticagrelor:Reversible P2Y12 antagonist with faster onset and offset kinetics commands premium formulary placement in acute coronary syndrome protocols across tertiary centers.
- Prasugrel:Third-generation thienopyridine with enhanced platelet inhibition carries bleeding-risk black box warnings that restrict eligibility in elderly and low-weight patient cohorts.
Aspirin holds installed capacity across chronic prevention segments. Ticagrelor is rotating up the share rankings in interventional cardiology formularies.
End User:
Procurement authority is consolidating through centralized pharmacy and therapeutics committees rather than individual physician discretion.
- Hospitals:Tertiary cardiac centers and academic medical institutions anchor antiplatelet consumption through percutaneous coronary intervention volumes and dual antiplatelet therapy protocols. Integrated delivery network contracts in the United States override individual hospital purchasing autonomy, compressing pharmaceutical representative access to prescribers.
- Clinics:Outpatient cardiology practices manage chronic antiplatelet regimens post-discharge, with prescription volumes tied to coronary artery disease monitoring protocols. Germany's office-based cardiologist sector sustains steady demand for oral P2Y12 inhibitor maintenance dosing.
- Homecare Settings:Post-acute and long-term care facilities administer chronic antiplatelet therapy for stroke prevention in elderly populations with limited mobility.
- Urgent Care Centers:Retail-based acute facilities initiate loading-dose protocols for suspected acute coronary syndrome before transfer to catheterization laboratories.
Hospitals retain dominant procurement volume. Urgent care centers are climbing the fastest as point-of-care diagnostic capabilities expand.
Delivery Mode:
Patient compliance economics favor oral administration, while periprocedural settings sustain premium injectable pricing.
- Oral:Immediate-release and film-coated tablet formulations dominate outpatient prescription volumes through dosing convenience and pharmacy distribution reach. The segment captures chronic maintenance therapy across cardiovascular and cerebrovascular indications.
- Injectable:Subcutaneous and intramuscular glycoprotein IIb/IIIa inhibitors command premium pricing in catheterization laboratories during high-risk percutaneous coronary intervention. Ultra-thin drug-eluting stent miniaturization is compressing systemic inhibitor addressable markets.
- Transdermal:Patch-based delivery systems remain experimental for antiplatelet agents, with limited clinical validation for platelet inhibition consistency.
- Intravenous:Critical care and emergency department settings deploy IV loading for acute coronary syndrome with hemodynamic instability precluding oral absorption.
Oral formulations hold installed capacity across chronic indications. Injectable delivery is gaining share fastest in hybrid operating room expansions.
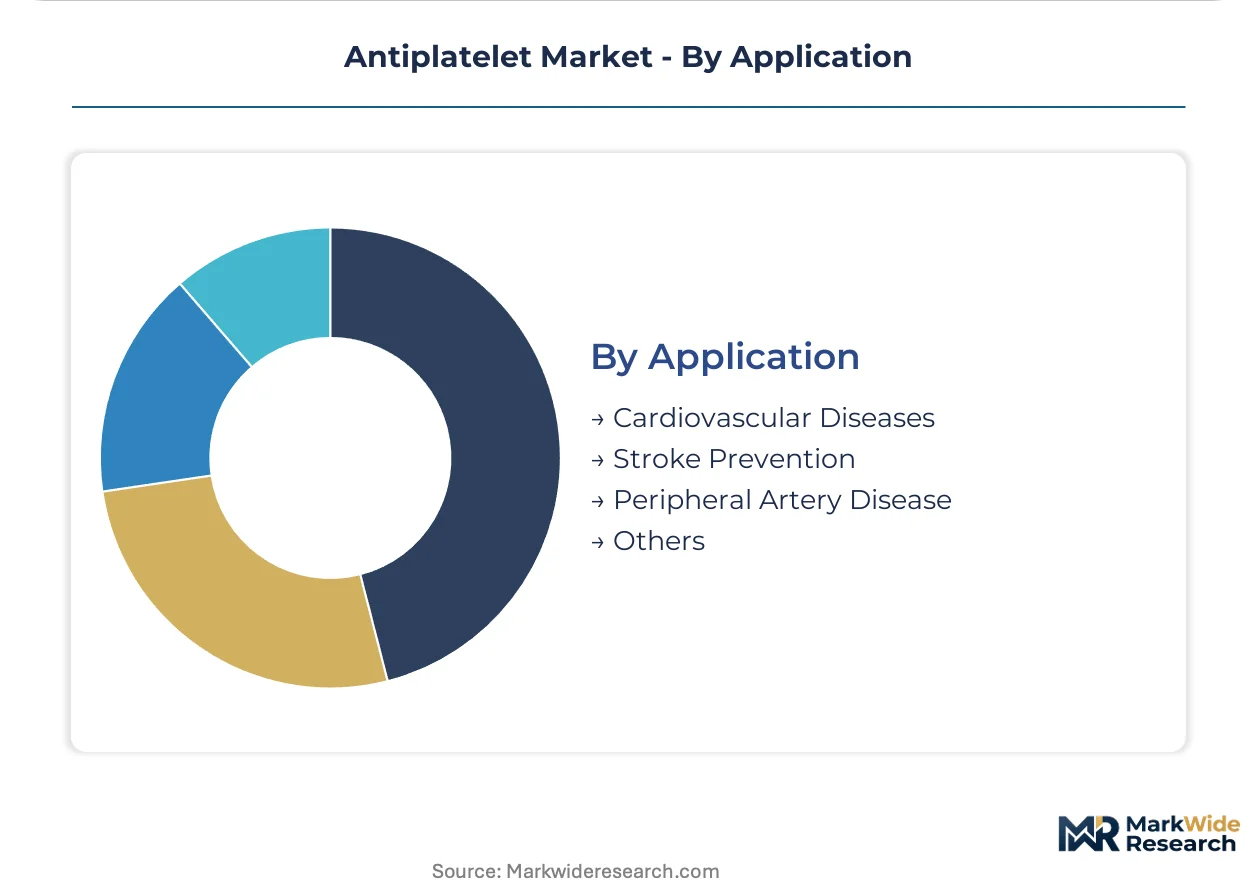
Application:
Indication expansion beyond coronary territories is reshaping prescriber targeting and clinical trial investment.
- Cardiovascular Diseases:Acute coronary syndrome, post-myocardial infarction, and post-percutaneous coronary intervention dual antiplatelet therapy constitute the foundational revenue base. Japan's aging demographics and established cardiology infrastructure sustain prescription volumes for chronic secondary prevention.
- Stroke Prevention:Transient ischemic attack management protocols in Germany and Japan are expanding eligibility criteria beyond traditional coronary indications. The application shows steepest expansion trajectory as cerebrovascular risk stratification integrates into primary care workflows.
- Peripheral Artery Disease:Lower extremity revascularization and critical limb ischemia protocols drive antiplatelet monotherapy or combination regimens in vascular surgery practices.
- Others:Antiphospholipid syndrome, prosthetic heart valve adjunct therapy, and investigational oncology applications represent niche utilization.
Cardiovascular diseases retain dominant indication share. Stroke prevention is rotating up the share rankings as TIA protocols expand reimbursement eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Risk Evaluation and Mitigation Strategies and EMA pharmacovigilance mandates are tightening post-market surveillance obligations across major prescribing jurisdictions. Germany's CYP2C19 testing reimbursement policies and Japan's aging cardiovascular patient pools sustain prescription volumes for oral P2Y12 inhibitors.
United States
Integrated delivery network contracts consolidate antiplatelet formulary decisions through centralized pharmacy and therapeutics committees. FDA pharmacovigilance requirements mandate periodic safety update reports for oral P2Y12 inhibitors. Academic medical centers in Boston and New York Metro override individual hospital purchasing autonomy, compressing pharmaceutical representative access.
Germany
Office-based cardiologists sustain steady demand for oral P2Y12 inhibitor maintenance dosing through coronary artery disease monitoring protocols. EMA risk-management plans shape clinical trial design and post-approval labeling for antiplatelet developers. The Bavaria and North Rhine-Westphalia regions anchor cerebrovascular risk stratification integration into primary care workflows.
Japan
Expanding populations require chronic dual antiplatelet therapy post-percutaneous coronary intervention. PMDA guidelines influence acute coronary syndrome loading-dose protocols in catheterization laboratories. The Kanto region surrounding Tokyo maintains established cardiology infrastructure sustaining prescription volumes for chronic secondary prevention.
United Kingdom
NHS England's centralized procurement frameworks negotiate antiplatelet therapy access agreements with manufacturers. MHRA post-Brexit regulatory autonomy maintains alignment with EMA pharmacovigilance standards. The London/Southeast corridor concentrates tertiary cardiac centers performing high-volume percutaneous coronary intervention.
China
NMPA accelerated review pathways expedite approval for novel oral P2Y12 inhibitors with differentiated bleeding-risk profiles. Domestic API manufacturing capacity for thienopyridines clusters in specific coastal zones. The Yangtze River Delta region houses contract development and manufacturing organizations serving multinational pharmaceutical supply chains.
Antiplatelet Market Vendor Landscape
Listed leaders compete with private specialists across patent-protected oral P2Y12 inhibitors and commoditized aspirin segments. The market structure concentrates margin capture in reversible P2Y12 antagonists with faster onset kinetics, while generic acetylsalicylic acid erodes pricing power. Three archetypes dominate: multinational pharmaceutical conglomerates with cardiovascular franchises, regional generic manufacturers, and specialty API suppliers. Competitive moves center on pharmacogenomic testing integration and combination drug-device product development.
Within the multinational pharmaceutical tier, AstraZeneca and Bayer AG exemplify divergent strategic positioning. AstraZeneca anchors the reversible P2Y12 antagonist segment through ticagrelor-based acute coronary syndrome protocols. Bayer AG occupies a position in the aspirin segment built on decades of cardiovascular risk-reduction positioning. Daiichi Sankyo Company represents the third-generation thienopyridine specialists competing on differentiated bleeding-risk profiles.
| Leading Market Players |
|---|
| AstraZeneca |
| Bayer AG |
| Sanofi |
| Pfizer Inc. |
| Eli Lilly and Company |
| Daiichi Sankyo Company |
| Boehringer Ingelheim |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Installed manufacturing capacity for thienopyridine APIs in coastal Chinese zones and select Indian pharmaceutical corridors shapes both supply concentration and price floors across oral P2Y12 inhibitor categories. Scale economies at these production nodes compress unit costs for generic clopidogrel while patent-protected ticagrelor and prasugrel formulations sustain premium positioning through regulatory exclusivity and differentiated bleeding-risk profiles.
Pricing Analysis
Certification level creates the primary spread between FDA-validated active pharmaceutical ingredients and regional-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels separates originator P2Y12 inhibitors from authorized generics and unbranded aspirin. Cost compression in the aspirin segment is intensifying because retail pharmacy chains consolidate procurement through central buying cooperatives. Hospital formulary committees show least price sensitivity for acute coronary syndrome loading-dose protocols, while primary care networks drive hardest bargains on chronic maintenance regimens.
Supply Chain Analysis
China and India anchor active pharmaceutical ingredient production for thienopyridine chemistry, with secondary formulation capacity concentrated in Germany and Japan. Manufacturing rests on salicylic acid derivatives, pyridine-based intermediates, and specialized polymer coatings for film-coated tablets. Single-source vulnerability persists where CYP2C19 testing reagents and platelet function assay consumables draw from limited qualified suppliers. Distribution runs through hospital-centric procurement networks in the United States and Germany, with retail pharmacy channels capturing outpatient maintenance volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FDA Risk Evaluation and Mitigation Strategies and EMA pharmacovigilance mandates creates substantial switching costs for prescribers and procurement committees.
For Market Incumbents: Compound regulatory data assets through expanded post-market surveillance studies that reinforce differentiated bleeding-risk positioning against generic alternatives. Deepen backward integration into CYP2C19 testing companion diagnostics to capture pharmacogenomic stratification value before payers fully mandate third-party screening protocols. Prioritize capacity addition in Japanese and German manufacturing corridors to secure regional supply continuity against API import disruption. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks offer the most penetrable regulatory pathway for novel P2Y12 inhibitors with reversible kinetics or reduced drug-drug interaction profiles. White-space concentration sits in stroke prevention protocols for transient ischemic attack populations currently underserved by coronary-centric marketing organizations. Target urgent care center formularies through point-of-care platelet function testing bundling that bypasses entrenched hospital pharmacy committee gatekeeping. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty API suppliers with long-term offtake agreements to branded formulation manufacturers. Five-to-ten year viability favors assets with captive thienopyridine chemistry expertise and validated regulatory dossiers across FDA, EMA, and PMDA jurisdictions. Acquisition priority targets vertically integrated manufacturers controlling both API synthesis and finished-dose production. Monitor pharmacogenomic testing reimbursement policy shifts in United States Medicare and German statutory health insurance as the critical inflection signal for clopidogrel demand fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Testing Integration | CYP2C19 screening reimbursement locks in P2Y12 inhibitor selection protocols before first-line therapy. |
| Combination Drug-Device Development | EU MDR expedited review pathways accelerate market access for antiplatelet-eluting coronary stent systems. |
| Point-of-Care Diagnostic Partnership | Catheterization laboratory platelet function assays enable individualized loading-dose protocols during acute events. |
| API Manufacturing Scale-Up | Domestic thienopyridine production in India and China reduces single-source vulnerability for global supply chains. |
| Reimbursement Strategy Investment | United States integrated delivery network contracts override individual hospital purchasing autonomy for formulary placement. |
Methodological Framework
Initial hypotheses were tested against primary input from regulatory affairs directors, hospital pharmacy and therapeutics committee chairs, cardiology department heads, and payer access specialists, then refined through secondary validation against FDA filings, EMA periodic safety update reports, ClinicalTrials.gov registries, and hospital procurement database extracts. Bottom-up prescription volume modeling across oral and injectable delivery modes was triangulated with top-down pharmaceutical revenue estimates to converge on market sizing.
Variance decomposition across therapeutic class, delivery mode, application indication, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate aggregation weighted by baseline revenue contribution. Forecast inputs incorporated pharmacogenomic testing penetration curves, dual antiplatelet therapy protocol adherence rates, and drug-eluting stent procedure volumes by tertiary center cluster.
Decision-makers should treat outputs as directional under assumptions of stable FDA and EMA regulatory enforcement, sustained CYP2C19 testing reimbursement, and uninterrupted API supply from qualified Asian manufacturing zones; material deviation in any driver would warrant model refresh. Recalibration cycles align with material shifts in pharmacogenomic policy, stent technology miniaturization adoption, and antiplatelet-eluting device regulatory pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Oligonucleotide Therapeutics Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Tenecteplase Drugs Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
North America Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Drug Allergy Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Atopic Dermatitis Drugs Market