
 Dual Antiplatelet Therapy Market | 2026-2036
Dual Antiplatelet Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Antiplatelet Therapy Market Analytics
Outcome-based contracting for antiplatelet adherence monitoring is recalibrating what hospitals and health systems purchase, shifting value capture from pill volume to patient management services. AstraZeneca leverages its ticagrelor franchise to anchor market presence across acute coronary syndrome protocols. Sanofi sustains competitive relevance through deep cardiovascular expertise and established clinician relationships. Bristol-Myers Squibb Company differentiates via its clopidogrel heritage and integrated cardiovascular portfolio breadth.
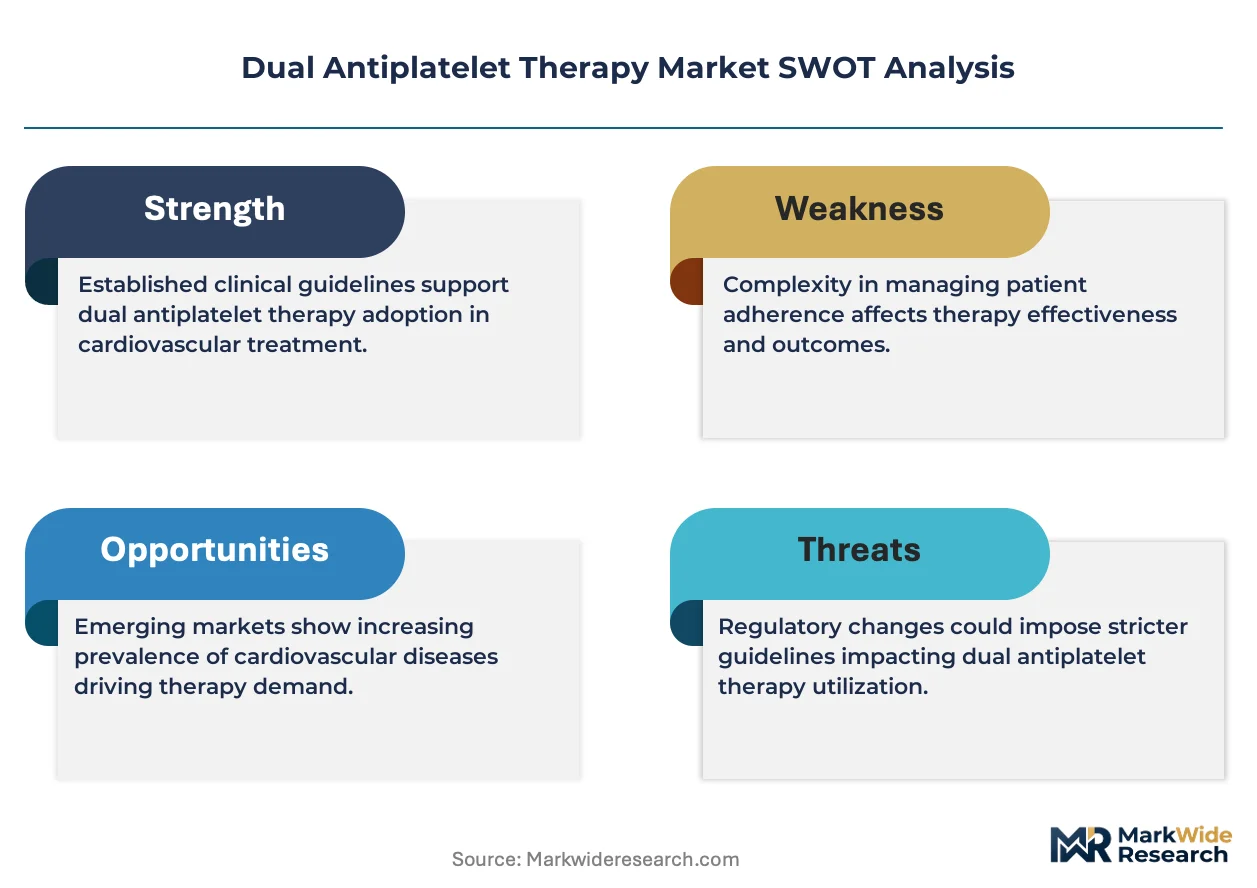
Dual antiplatelet therapy denotes the concurrent administration of two pharmacologically distinct platelet aggregation inhibitors—typically a cyclooxygenase-1 blocker such as aspirin combined with a P2Y12 receptor antagonist like clopidogrel, prasugrel, or ticagrelor—to prevent thrombotic events following coronary stenting or acute coronary syndrome. The regimen requires precise timing protocols, with loading doses administered pre-intervention and maintenance phases extending twelve months or longer per lesion complexity and bleeding risk stratification. Ticagrelor and prasugrel command expanding share in acute coronary syndrome indications where superior platelet inhibition offsets higher bleeding event rates, while clopidogrel retains dominant volume in stable coronary artery disease and cost-sensitive markets. Hospital procurement of oral formulations concentrates margin pools at the manufacturer level, whereas cardiology clinics increasingly drive transdermal and extended-release delivery innovation.
The FDA, EMA, and PMDA enforce divergent post-market surveillance requirements for bleeding complications, compelling manufacturers to maintain discrete safety databases and label variations across jurisdictions. ISO 14155 and ICH-GCP standards govern clinical trial conduct for new combination regimens, raising protocol costs and extending development timelines. Stakeholders must monitor evolving antithrombotic guideline revisions from cardiology societies and corresponding payer coverage determinations that will reshape prescribing algorithms irrespective of compound patent status.
Market Dynamics
Outcome-based contracting for antiplatelet adherence monitoring is recalibrating what hospitals and health systems purchase, shifting value capture from pill volume to patient management services.
Growth Catalysts
- Updated cardiology society guidelines:Revised protocols for post-stent maintenance expand combination regimen eligibility across acute coronary syndrome populations. Cardiology clinics in the United States accelerate adoption of extended-duration dual therapy.
- Coronary intervention volume expansion:Percutaneous coronary intervention procedures in Germany and Japan sustain maintenance-phase patient pools requiring twelve-month or longer antiplatelet coverage.
- Transdermal delivery innovation:Extended-release and patch-based formulations reduce gastrointestinal bleeding events compared with oral loading doses, attracting prescriber interest in bleeding-risk-stratified protocols.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for P2Y12 antagonists clusters in Chinese and Indian manufacturing zones, exposing formulators to geopolitical logistics disruptions.
- Bleeding risk liability:FDA and EMA safety labeling requirements mandate discrete adverse event databases per jurisdiction, raising post-market surveillance compliance costs.
- Generic clopidogrel substitution:Off-patent status of cyclooxygenase-aspirin combinations compresses reimbursement rates for branded combination therapies in cost-sensitive markets.
Strategic Opportunities
- Rural clinic penetration:Underpenetrated cardiology access in India's tier-2 and tier-3 cities creates whitespace for simplified loading-dose protocols delivered through regional hospital networks.
- Integrated adherence platforms:Digital therapeutic bundling with antiplatelet prescriptions captures value from medication persistence monitoring, reimbursable under United States Medicare Advantage supplemental benefit structures.
- Biosimilar convergence:P2Y12 receptor antagonist biosimilars combined with novel anticoagulant co-formulations address polypharmacy burden in elderly acute coronary syndrome populations.
Industry Challenges
- Hematology specialist scarcity:Bleeding event management requires interventional cardiologist-coagulation specialist coordination, creating care pathway bottlenecks in community hospital settings.
- ISO 14155 protocol costs:Clinical trial conduct standards for new combination regimens extend development timelines and raise site qualification expenditures across multinational studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Antiplatelet Therapy Market |
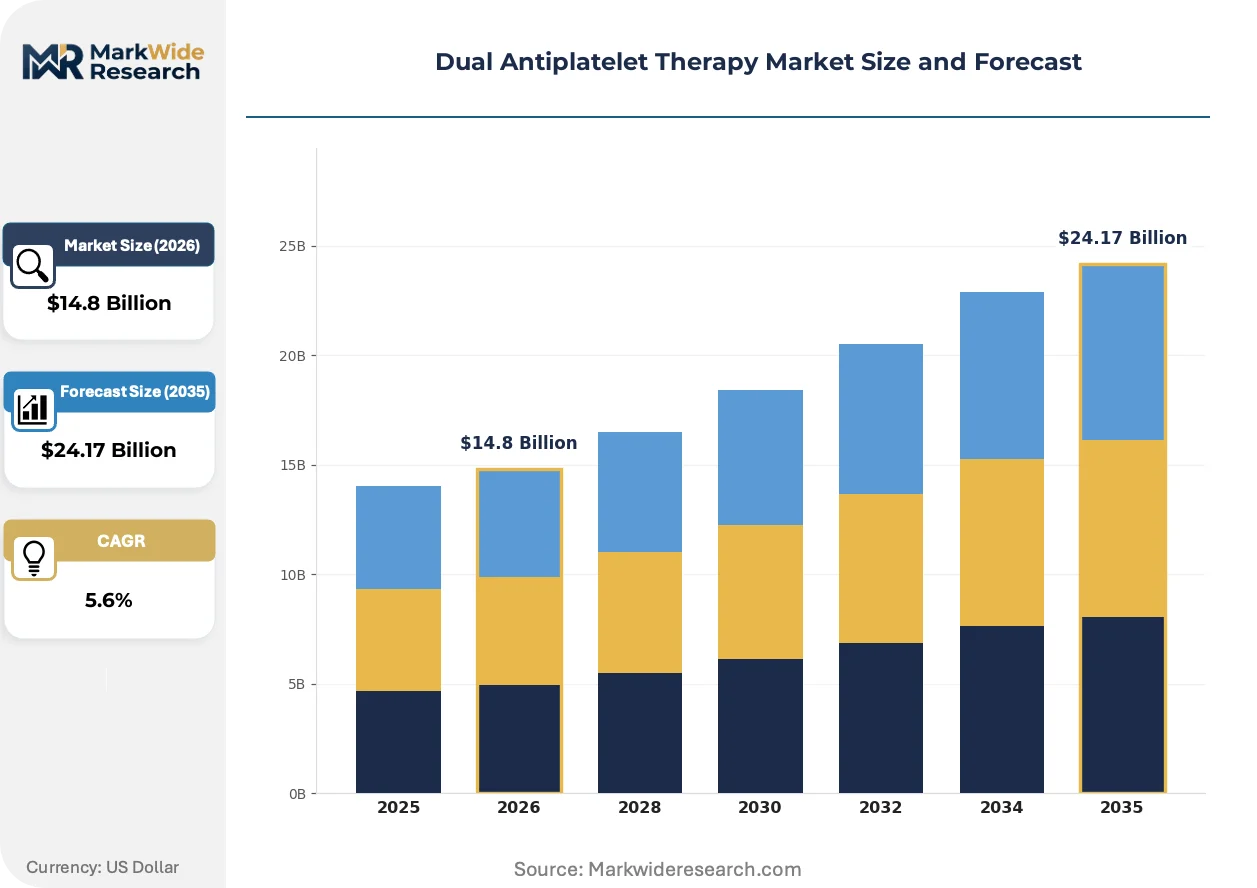
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aspirin, Clopidogrel, Prasugrel, Ticagrelor Indication: Coronary Artery Disease, Acute Coronary Syndrome, Peripheral Arterial Disease, Ischemic Stroke End User: Hospitals, Cardiology Clinics, Outpatient Centers, Homecare Delivery Mode: Oral, Injectable, Transdermal, Inhalable |
| Companies Covered | AstraZeneca, Sanofi, Bristol-Myers Squibb Company, Bayer AG, Eli Lilly and Company, Daiichi Sankyo Company, Otsuka Pharmaceutical, Novartis AG, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Antiplatelet Therapy Market Evolving Landscape
Antiplatelet therapy delivery is fragmenting across administration routes and monitoring modalities, compressing traditional oral-dominant margin pools while opening service-based revenue streams.
Transdermal antiplatelet patches incorporating iontophoretic enhancement are modularizing how loading doses reach systemic circulation. Cardiology clinics in South Korea and Australia pilot these devices for pre-intervention platelet inhibition. The technology is modularizing hospital pharmacy workflows by decoupling dose timing from oral administration windows.
EMA's tightened post-authorization safety study requirements for bleeding complications now mandate prospective registry enrollment across all new P2Y12 entrants. This policy compresses launch-to-real-world-evidence timelines for manufacturers. European hospital formularies respond by delaying uptake until twelve-month safety datasets mature.
Hospital procurement committees now unbundle antiplatelet purchasing from cardiovascular device contracts, reversing decade-old bundled pricing conventions. Group purchasing organizations in the United States negotiate standalone pharmaceutical contracts with adherence-monitoring service riders. This behavior shift concentrates price leverage with integrated delivery networks possessing internal pharmacy benefit management capabilities.
Dual Antiplatelet Therapy Market Segmentation
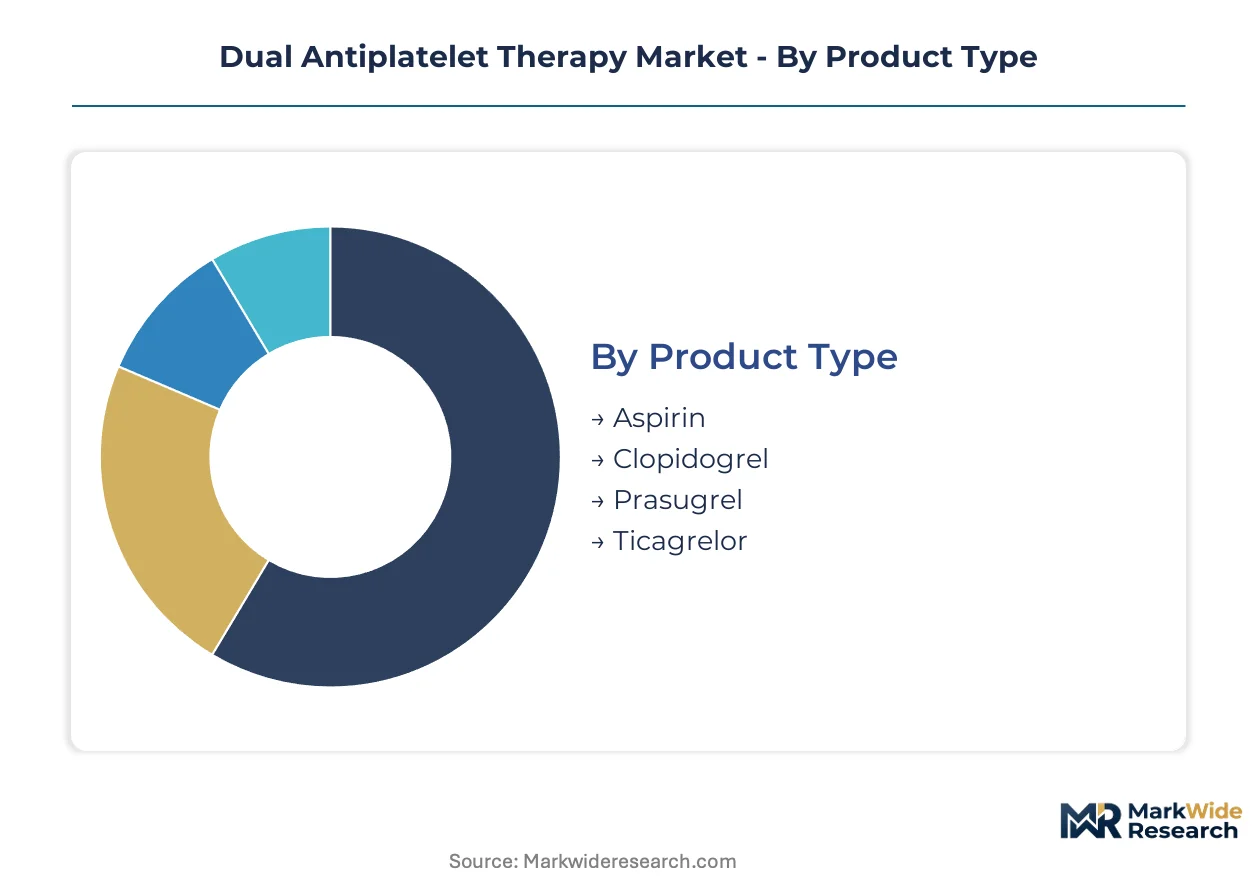
Antiplatelet purchasing decisions diverge sharply across clinical settings and patient risk profiles. Manufacturers must align formulation development, dosing protocols, and service bundling to the distinct procurement logic governing each segment boundary.
Product Type:
Hospital formularies weight bleeding risk stratification against acquisition cost when selecting P2Y12 agents for combination protocols.
- Aspirin:Cyclooxygenase-1 inhibitor serving as the foundational antiplatelet backbone across all dual therapy regimens. Demand concentrates in perioperative protocols at United States academic medical centers where generic sourcing minimizes pharmacy expenditure.
- Clopidogrel:Thienopyridine prodrug requiring CYP2C19 hepatic activation with variable antiplatelet response. Volume leadership persists in stable coronary artery disease maintenance at German statutory health system hospitals prioritizing cost containment over pharmacodynamic precision.
- Prasugrel:Irreversible P2Y12 antagonist with faster onset and more consistent platelet inhibition than clopidogrel. Prescribing concentrates in acute coronary syndrome populations at Japanese interventional cardiology centers managing high thrombotic risk post-PCI.
- Ticagrelor:Reversible cyclopentyl-triazolopyrimidine with direct hepatic metabolism bypassing CYP2C19 polymorphism constraints. Adoption accelerates in United States hospital systems participating in outcome-based contracts linking reimbursement to reduced recurrent myocardial infarction rates.
Clopidogrel leads on scale; ticagrelor leads on momentum.
Indication:
Guideline revision cycles reshape eligibility criteria and duration protocols for each therapeutic application.
- Coronary Artery Disease:Chronic atherosclerotic narrowing requiring indefinite single antiplatelet therapy with selective dual therapy escalation post-revascularization. Stable disease populations at United States cardiology clinics drive maintenance-phase volume for cost-optimized regimens.
- Acute Coronary Syndrome:Unstable angina, non-ST-elevation myocardial infarction, and ST-elevation myocardial infarction demanding intensive platelet inhibition. German coronary intervention centers sustain twelve-month dual therapy protocols for post-stent thrombosis prevention.
- Peripheral Arterial Disease:Atherosclerotic lower extremity ischemia with elevated cardiovascular event risk. Prescriber interest concentrates at United States vascular surgery practices integrating antiplatelet therapy with endovascular limb salvage procedures.
- Ischemic Stroke:Cerebrovascular thromboembolism requiring antiplatelet secondary prevention with narrower therapeutic windows than coronary indications. Japanese neurology departments pilot shorter-duration dual therapy protocols balancing recurrent stroke against intracranial hemorrhage risk.
Acute coronary syndrome commands the steepest expansion trajectory; coronary artery disease anchors installed base economics.
End User:
Site-of-care migration and reimbursement bundling determine whether pharmaceutical margin pools concentrate at institutional or distributed delivery points.
- Hospitals:Inpatient and procedural settings commanding loading-dose administration and acute event management. United States integrated delivery networks negotiate pharmaceutical contracts with adherence-monitoring service riders.
- Cardiology Clinics:Outpatient specialty practices managing maintenance-phase therapy and long-term risk stratification. South Korean and Australian clinics pilot transdermal delivery devices for pre-intervention platelet inhibition.
- Outpatient Centers:Ambulatory surgical facilities performing diagnostic catheterization and elective PCI. German outpatient cardiology centers sustain maintenance-phase patient pools through statutory insurance reimbursement frameworks.
- Homecare:Patient-directed administration supported by remote monitoring and digital therapeutic platforms. United States Medicare Advantage supplemental benefit structures reimburse medication persistence monitoring services.
Hospitals capture the largest prescription volume; homecare is gaining share fastest.
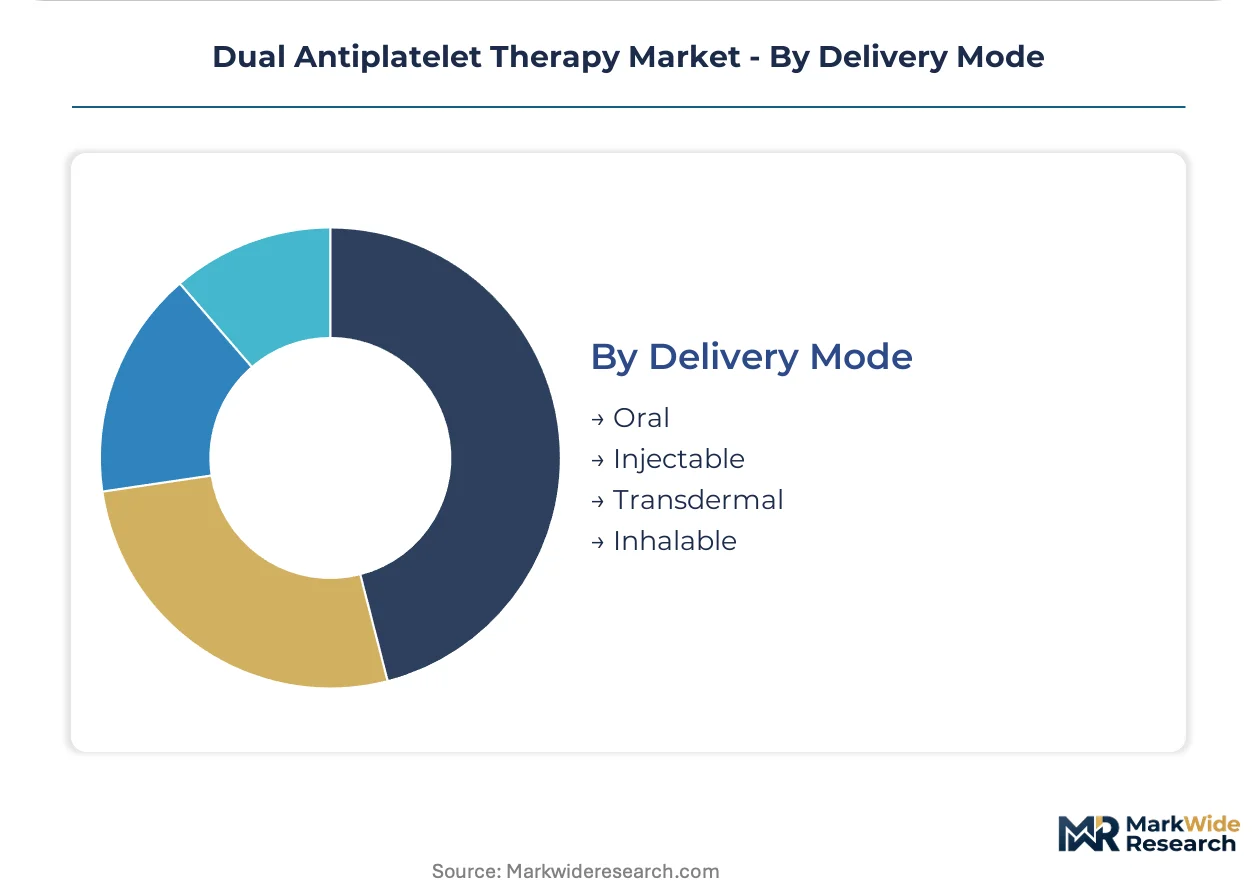
Delivery Mode:
Route of administration selection reflects bleeding risk tolerance, patient compliance capacity, and care setting workflow constraints.
- Oral:Tablet and capsule formulations dominating maintenance-phase therapy with established bioavailability profiles. Hospital pharmacy procurement committees unbundle oral antiplatelet purchasing from cardiovascular device contracts.
- Injectable:Intravenous and subcutaneous loading doses for acute coronary syndrome intervention settings. United States emergency departments prioritize injectable agents for rapid platelet inhibition in ST-elevation myocardial infarction.
- Transdermal:Patch-based and iontophoretic systems enabling non-gastrointestinal drug delivery. EMA post-authorization safety study requirements for bleeding complications compress launch-to-real-world-evidence timelines for transdermal entrants.
- Inhalable:Pulmonary delivery platforms in early development for rapid systemic absorption without intravenous access. Regulatory pathways remain undefined across FDA and EMA jurisdictions.
Oral formulations lead on scale; transdermal systems lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between FDA and EMA post-market surveillance requirements is pushing API sourcing toward jurisdictions with harmonized compliance frameworks. Manufacturers now route active pharmaceutical ingredient production through zones where dual-jurisdiction dossier preparation costs less.
United States
Coronary intervention volumes at Cleveland Clinic and Mayo Clinic networks sustain the world's largest post-stent maintenance patient pool. FDA tightened safety labeling requirements for bleeding risk profiles in 2024, compelling discrete adverse event databases. Texas Medical Center anchors prescriber training for extended-duration dual therapy protocols.
Germany
Statutory health system hospitals prioritize cost containment in stable coronary artery disease maintenance, preserving clopidogrel volume leadership. EMA post-authorization safety study mandates compress launch-to-real-world-evidence timelines for new P2Y12 entrants. Heidelberg and Munich interventional cardiology centers sustain twelve-month dual therapy protocols for post-PCI thrombosis prevention.
Japan
PMDA enforces distinct bleeding complication surveillance requirements separate from FDA and EMA frameworks, raising post-market compliance expenditures. Tokyo and Osaka interventional cardiology centers manage high thrombotic risk populations with prasugrel-dominant prescribing. Japanese neurology departments pilot shorter-duration dual therapy for ischemic stroke secondary prevention.
India
CDSCO accelerated approval pathways for fixed-dose combination antiplatelet therapies expanded access in tier-2 and tier-3 cities. Maharashtra and Gujarat cardiology networks drive rural clinic penetration for simplified loading-dose protocols. Mumbai and Ahmedabad hospital procurement committees negotiate standalone pharmaceutical contracts unbundled from cardiovascular device pricing.
South Korea
MFDS transdermal delivery device approvals enabled Seoul and Busan cardiology clinics to pilot iontophoretic patch systems for pre-intervention platelet inhibition. National health insurance reimbursement frameworks cover extended-release formulations reducing gastrointestinal bleeding events. Pangyo biocluster manufacturers develop modular hospital pharmacy workflow solutions decoupling dose timing from oral administration windows.
Dual Antiplatelet Therapy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with originators capturing margin in acute coronary syndrome indications while generic formulators dominate stable disease maintenance. The market structures around three tiers: large-cap pharmaceutical conglomerates with cardiovascular portfolio breadth, mid-sized regional players with deep clinician relationships, and emerging biosimilar developers targeting polypharmacy burden in elderly populations. Competitive moves concentrate on outcome-based contracting for adherence monitoring services and geographic expansion into underpenetrated rural clinic networks.
Among large-cap originators, AstraZeneca anchors market presence through its ticagrelor franchise across acute coronary syndrome protocols. Sanofi sustains competitive relevance via established cardiovascular expertise and clinician network depth. Bristol-Myers Squibb Company occupies a heritage position rooted in clopidogrel development history and integrated portfolio breadth. These three exemplify divergent strategic archetypes: AstraZeneca represents outcome-based contract leadership, Sanofi embodies regional relationship density, and Bristol-Myers Squibb illustrates legacy compound monetization.
| Leading Market Players |
|---|
| AstraZeneca |
| Sanofi |
| Bristol-Myers Squibb Company |
| Bayer AG |
| Eli Lilly and Company |
| Daiichi Sankyo Company |
| Otsuka Pharmaceutical |
| Novartis AG |
| Pfizer Inc. |
| Others |
Value Network & Pricing Analysis
Hospital procurement committee unbundling of antiplatelet purchasing from cardiovascular device contracts is forcing API suppliers to reconfigure volume commitments and pricing terms, compressing margin pools for formulators while opening service-based revenue attachments for integrated delivery networks with pharmacy benefit management capabilities.
Pricing Analysis
Distributor margin capture concentrates at the group purchasing organization level in United States integrated delivery networks, with three-tier pricing structure across premium, standard, and economy levels stratifying by bleeding risk profile and pharmacodynamic precision. Price differentiation hinges on FDA tier certification for enhanced safety labeling and volume scale through twelve-month maintenance protocols. Pricing pressure stems from generic clopidogrel substitution in German statutory health system hospitals. Cost-sensitive stable coronary artery disease populations exhibit highest price sensitivity; acute coronary syndrome intervention centers show lowest.
Supply Chain Analysis
Freight cost volatility from Chinese and Indian manufacturing zones to European and North American formulators is amplifying working capital requirements for P2Y12 antagonist API stockpiling. Active pharmaceutical ingredient production clusters in China, India, and selected European zones. Formulation draws from thienopyridine intermediates, cyclopentyl-triazolopyrimidine precursors, and cyclooxygenase-1 inhibitor raw materials. Single-source vulnerability concentrates in CYP2C19 metabolite supply for clopidogrel activation. Distribution runs through hospital pharmacy committees and cardiology clinic direct purchasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA's 2024 tightened safety labeling requirements for bleeding risk profiles are accelerating demand for discrete adverse event database capabilities and reshaping prescriber behavior across acute coronary syndrome protocols.
For Market Incumbents: Hedge against biosimilar convergence in P2Y12 receptor antagonists by deepening vertical integration into adherence-monitoring platform development and securing outcome-based contracts with United States Medicare Advantage plans. Defend margin position through captive supply of ticagrelor API and certification investment for EMA post-authorization safety study compliance. For New Entrants and Emerging Players: The mid-tier price-point gap between premium ticagrelor and economy clopidogrel creates whitespace for prasugrel biosimilars combined with novel anticoagulant co-formulations targeting elderly polypharmacy burden. India's tier-2 and tier-3 cities represent the most penetrable geography. A simplified loading-dose protocol delivered through regional hospital networks offers the clearest go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with digital therapeutic platforms bundling antiplatelet adherence monitoring, reimbursable under United States supplemental benefit structures with recurring revenue visibility across the analysis window. Acquisition targets should display integrated pharmacy benefit management capabilities and existing hospital system partnerships. The signal to watch is EMA post-authorization safety study completion rates for transdermal delivery entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Contracting | Links pharmaceutical reimbursement to reduced recurrent myocardial infarction rates in United States hospital systems. |
| Transdermal Delivery Device Development | Reduces gastrointestinal bleeding events compared with oral loading doses in South Korean and Australian pilot programs. |
| API Supply Geographic Diversification | Mitigates geopolitical logistics disruptions from concentrated Chinese and Indian manufacturing zones. |
| Digital Therapeutic Platform Integration | Captures value from medication persistence monitoring under Medicare Advantage supplemental benefits. |
| Rural Clinic Network Penetration | Expands access through simplified loading-dose protocols in India's underpenetrated tier-2 and tier-3 cities. |
Research Methodology
Multiple input streams — primary interviews with formulary directors, regulatory affairs leads, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, and ClinicalTrials.gov records; and hospital procurement database analysis — were reconciled through bottom-up prescription volume modeling and top-down market sizing triangulation.
Historical prescription trends were cross-referenced against panel input from interventional cardiologists and payer access specialists across the analysis window. Segmentation dimensions modeled include P2Y12 agent type, indication severity, delivery mode, and regional regulatory cluster. CAGRs were derived from procedure volume trajectories and guideline revision cycles. Forecast inputs incorporated percutaneous coronary intervention expansion rates and transdermal device approval timelines.
Caveats apply where FDA safety labeling revisions, EMA post-authorization study mandates, or API supply disruptions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Powder-Filled Hard Gelatin Capsules Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
US Hormone Replacement Therapy Market
Pharmaceuticals
Asia Pacific Drug Development Market