
 North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market | 2026-2036
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market Analytics
Market Dynamics
Multi-source API procurement is consolidating toward vertically integrated manufacturers with captive fermentation capacity. Eli Lilly and Company anchors cardiovascular outcome research through dedicated heart failure programs. AstraZeneca leverages extensive real-world evidence networks to sustain payer negotiations across commercial and Medicare Part D plans. Boehringer Ingelheim differentiates through co-formulation expertise with DPP-4 inhibitors.
Product Landscape
Sodium-dependent glucose co-transporter 2 inhibitors are selective renal proximal tubule transporter blockers that reduce glucose reabsorption threshold from approximately 180 mg/dL to 80-120 mg/dL, inducing glucosuric glucose elimination for glycemic control and hemodynamic unloading. Tablet formulations dominate commercial dispensing due to manufacturing scale and stability profiles, while extended-release capsules capture growing prescriber interest for dosing convenience in polypharmacy patients. Diabetes management remains the largest therapy area by volume, though chronic kidney disease applications are expanding fastest following label updates.
Regulatory Environment
FDA cardiovascular outcome trial requirements and CMS national coverage determinations shape market access timelines and prescribing thresholds for SGLT2 therapies. Health Canada and PMRA labeling harmonization influences cross-border formulary alignment between the United States and Canadian provinces. Stakeholders must monitor FDA advisory committee deliberations on heart failure indications and state-level Medicaid preferred drug list placement decisions.
Market Dynamics
FDA label expansions for heart failure indications are restructuring prescriber behavior across hospital outpatient departments and endocrinology clinics, concentrating volume in cardiovascular outcome trial-validated therapies while CMS reimbursement adjustments accelerate channel consolidation toward specialty pharmacy networks.
Growth Catalysts
- CMS National Coverage Determinations:Medicare reimbursement alignment with cardiovascular outcome trial data is expanding hospital outpatient prescribing for heart failure with reduced ejection fraction across United States health systems.
- Real-World Evidence Networks:Extensive payer negotiation datasets from integrated delivery networks are accelerating commercial and Medicare Part D formulary placement for chronic kidney disease indications.
- Captive Fermentation Capacity:Vertically integrated API manufacturers with in-house production of biosynthetic intermediates are securing supply chain priority for high-volume tablet formulations.
Market Restraints
- Genitourinary Infection Risk Profile:Safety labeling requirements for Fournier's gangrene and urinary tract infections create prescribing hesitation among primary care physicians in United States Medicaid programs.
- Active Pharmaceutical Ingredient Concentration:Fermentation-based SGLT2 inhibitor production concentrates among three major supply geographies, exposing formulations to single-source disruption risk.
- DPP-4 Inhibitor Substitution:Established gliptin therapies with comparable HbA1c efficacy and superior infection safety profiles retain preferred status in several state Medicaid preferred drug lists.
Strategic Opportunities
- Canadian Provincial Formularies:Health Canada and PMRA labeling harmonization with FDA heart failure indications is opening reimbursement pathways in Ontario and British Columbia hospital systems.
- Extended-Release Formulation Development:Once-daily capsule technologies targeting polypharmacy patients in United States Medicare Part D plans are capturing prescriber switching interest from immediate-release tablets.
- Cardiorenal Integrated Care Models:United States accountable care organization risk-sharing arrangements are creating bundled reimbursement incentives for combined diabetes and chronic kidney disease therapy selection.
Industry Challenges
- Specialty Pharmacy Integration:Hub service requirements for patient enrollment and adherence monitoring impose operational complexity on United States hospital outpatient dispensing workflows.
- State Medicaid PDL Variability:Inconsistent preferred drug list placement across fifty state programs fragments commercial access strategy and requires jurisdiction-specific prior authorization infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market |
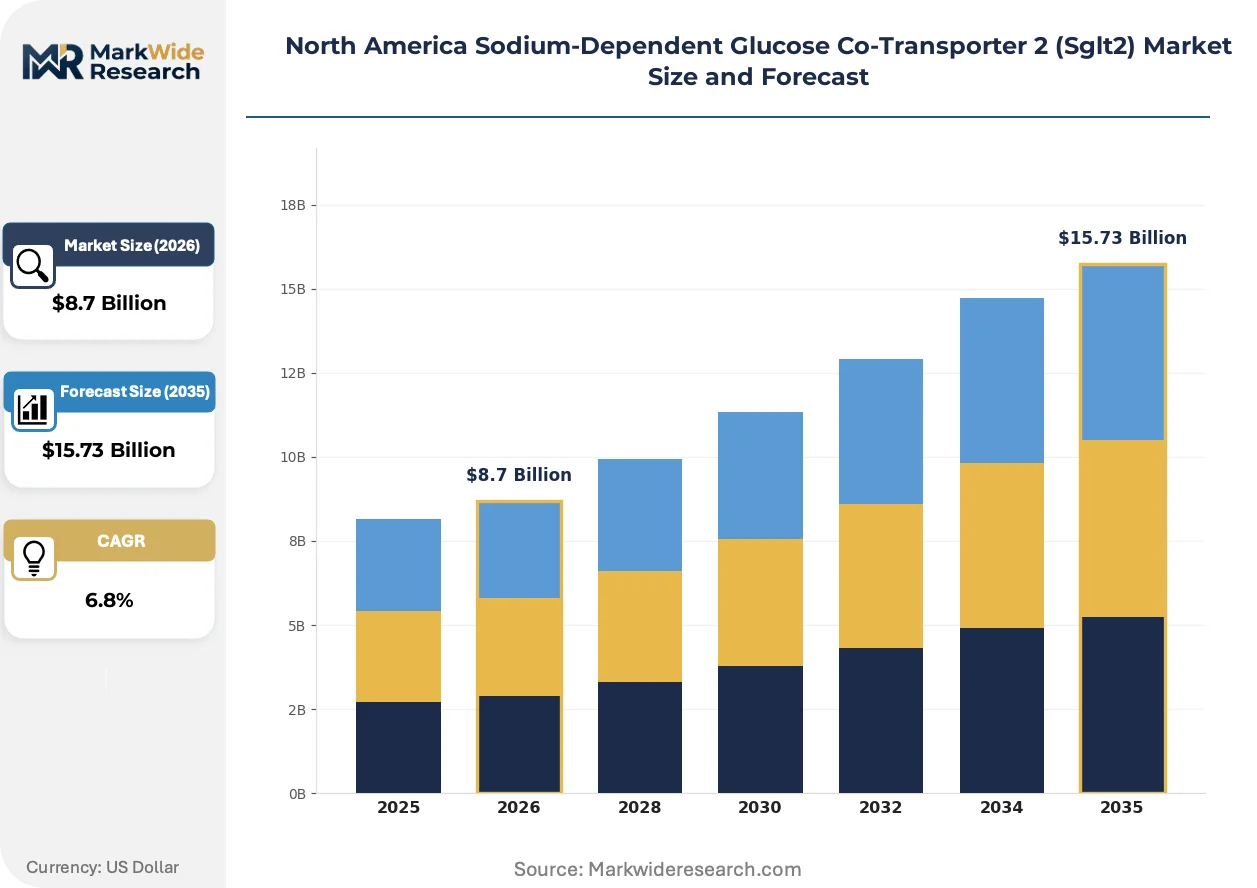
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable, Oral Solution, Extended-Release Capsules End User: Hospitals, Outpatient Clinics, Home Care Settings, Specialty Pharmacies Therapy Area: Diabetes Management, Chronic Kidney Disease, Cardiovascular Disorders, Obesity Management Delivery Mode: Subcutaneous, Intravenous, Oral, Transdermal |
| Companies Covered | Janssen, Eli Lilly and Company, AstraZeneca, Boehringer Ingelheim, Astellas Pharma, Merck & Co., Inc., TheracosBio, Lexicon Pharmaceuticals, Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market Evolving Landscape
Cardiovascular outcome trial requirements are fundamentally restructuring how SGLT2 inhibitors achieve market access, with evidence generation investments now determining competitive position before formulary negotiations begin.
Extended-release capsule formulations are overtaking immediate-release tablets in prescriber preference for United States Medicare Part D patients managing multiple chronic conditions. Polypharmacy burden reduction drives switching behavior among endocrinology clinics. This formulation shift is compressing manufacturing scale advantages historically held by high-volume tablet producers.
FDA advisory committee deliberations on supplemental heart failure indications are establishing new evidentiary thresholds for cardiovascular outcome claims. Manufacturers must now demonstrate mortality benefit in dedicated trials before label expansion approval. United States hospital outpatient departments are responding by concentrating prescribing in therapies with completed dedicated heart failure programs.
Specialty pharmacy channel consolidation is displacing traditional retail dispensing for United States SGLT2 inhibitor volumes. Integrated hub services managing prior authorization and adherence monitoring are becoming the standard access pathway. This channel shift is most visible in Medicare Part D and commercial plans with cardiovascular risk management programs.
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market Segmentation
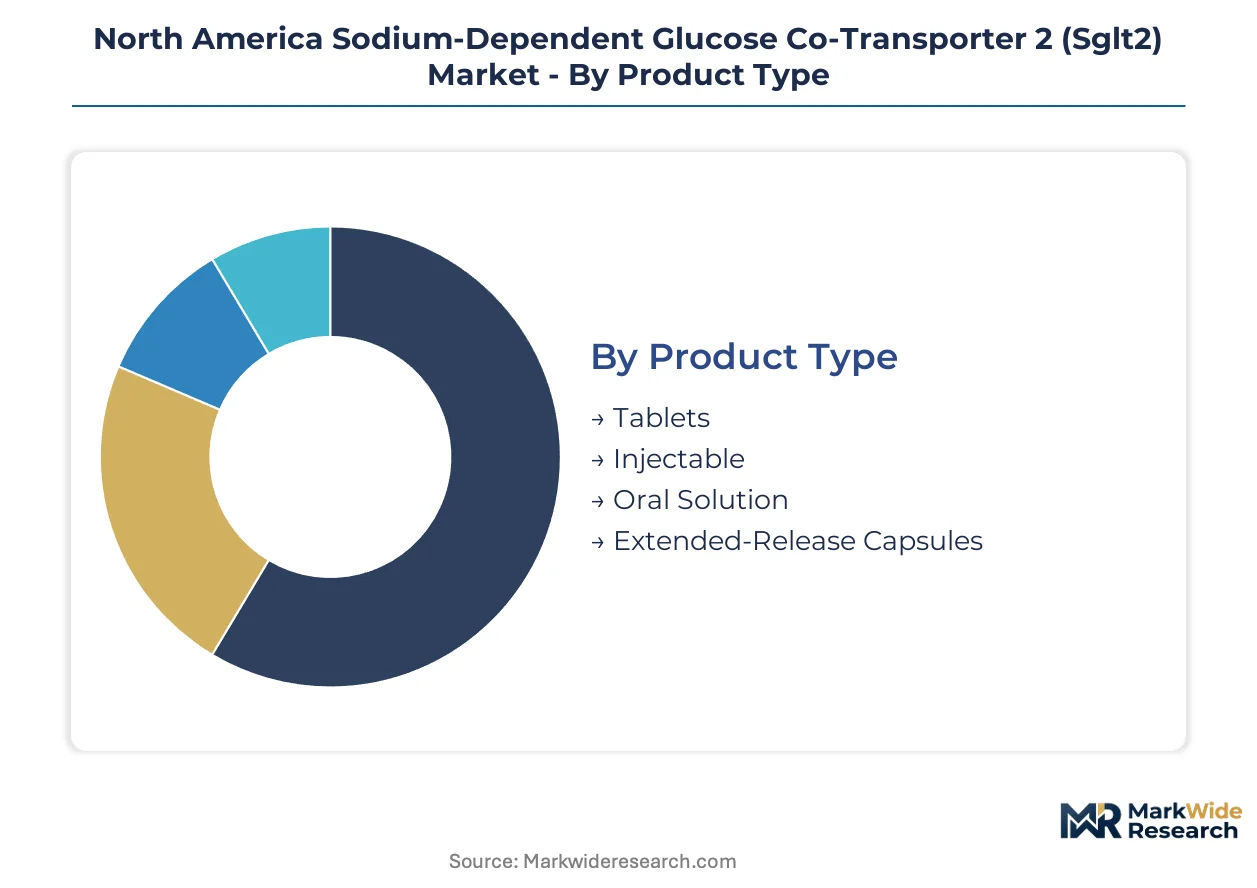
SGLT2 inhibitor market segmentation reveals how formulation choices, care settings, and therapeutic applications create distinct competitive arenas. Supply chain configuration and prescriber workflow requirements determine which segments capture volume concentration.
Product Type:
Manufacturing scale and captive fermentation capacity concentrate competitive advantage across formulation technologies.
- Tablets:Immediate-release compressed formulations dominate commercial dispensing through established high-volume production lines and proven stability profiles. United States hospital outpatient departments and Medicare Part D plans concentrate demand here due to manufacturing reliability and cost efficiency.
- Extended-Release Capsules:Matrix-based or osmotic pump technologies enable once-daily dosing for polypharmacy patients. United States endocrinology clinics are driving switching interest from immediate-release alternatives as adherence monitoring programs expand.
- Injectable:Subcutaneous formulations target hospitalized patients with acute glycemic management needs.
- Oral Solution:Liquid formulations address swallowing difficulties in elderly populations.
Today's leader: Tablets. Tomorrow's challenger: Extended-Release Capsules.
End User:
Reimbursement channel structure and patient risk stratification determine where volume concentrates across care settings.
- Specialty Pharmacies:Integrated hub services manage prior authorization, patient enrollment, and adherence monitoring for cardiovascular outcome trial-validated therapies. United States Medicare Part D and commercial risk-bearing plans are consolidating dispensing through these networks.
- Hospitals:Inpatient and emergency department initiation protocols for heart failure with reduced ejection fraction drive acute care prescribing. CMS national coverage determinations and FDA label expansions are expanding cardiovascular indication use in United States health systems.
- Outpatient Clinics:Endocrinology and cardiology practices manage chronic therapy maintenance.
- Home Care Settings:Long-term care facilities and visiting nurse programs support elderly patient adherence.
Volume gravity centers on Specialty Pharmacies. Expansion opportunity sits with Hospitals.
Therapy Area:
Clinical evidence generation and regulatory label scope determine prescriber access and payer reimbursement tiering.
- Diabetes Management:Glycemic control through glucosuric glucose elimination remains the foundational indication with established HbA1c efficacy endpoints. United States endocrinology clinics anchor volume concentration here, though growth rates are moderating as cardiovascular applications expand.
- Chronic Kidney Disease:Renoprotective benefits from hemodynamic unloading and reduced intraglomerular pressure are gaining fastest formulary traction. United States accountable care organization risk-sharing arrangements are creating bundled reimbursement incentives for combined diabetes and CKD therapy selection.
- Cardiovascular Disorders:Heart failure with reduced ejection fraction indications are restructuring hospital outpatient prescribing.
- Obesity Management:Adjunctive weight loss applications remain exploratory with limited payer coverage.
Established base: Diabetes Management. Steepest expansion trajectory: Chronic Kidney Disease.
Delivery Mode:
Pharmacokinetic requirements and patient self-administration capabilities shape formulation development priorities.
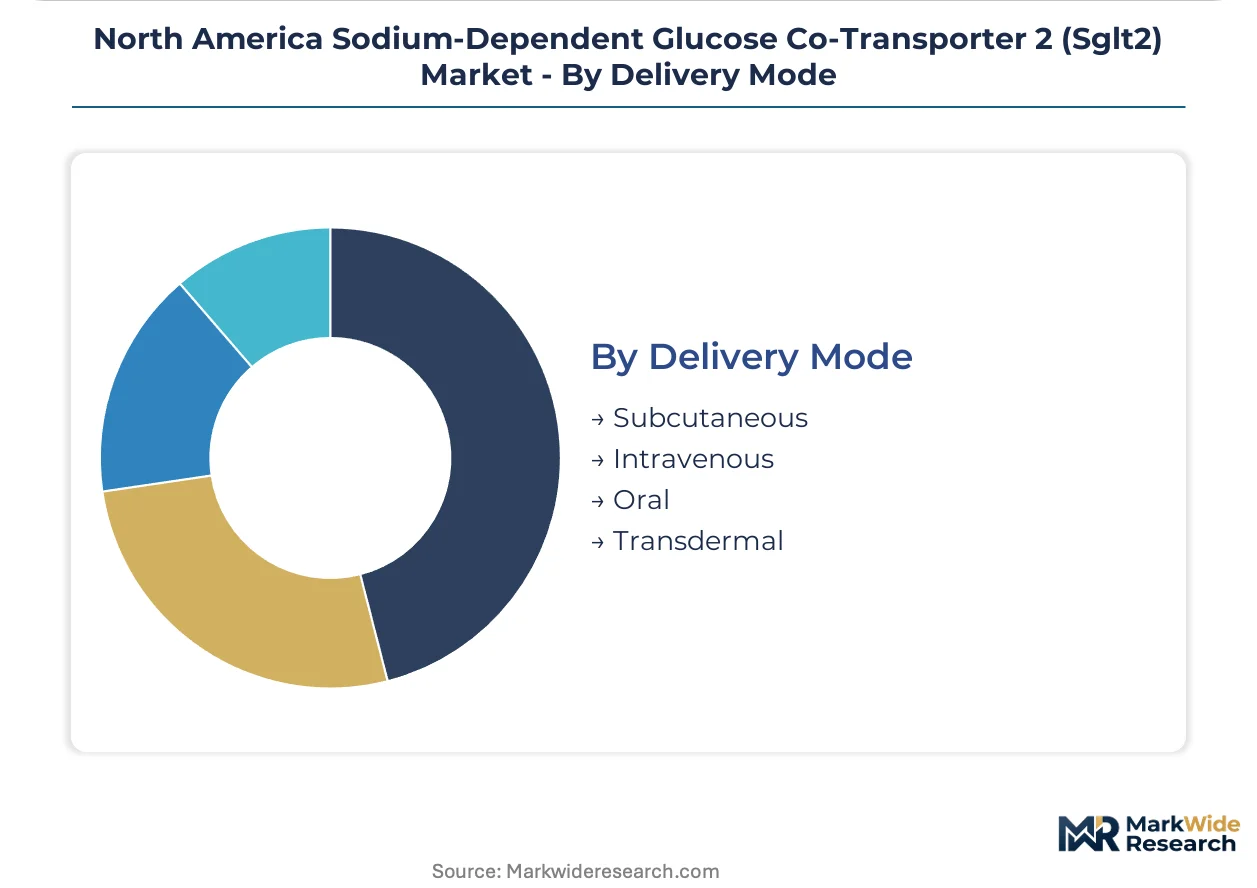
- Oral:First-pass hepatic metabolism and renal proximal tubule targeting enable convenient self-administration. United States Medicare Part D plans and commercial formularies concentrate coverage on oral formulations due to dispensing efficiency and patient preference data.
- Subcutaneous:Parenteral delivery supports acute inpatient glycemic control and patients with gastrointestinal absorption limitations.
- Intravenous:Hospital-restricted administration for perioperative or critical care settings.
- Transdermal:Patch-based delivery remains experimental with no approved SGLT2 inhibitor formulations.
Current standard: Oral. Clinical niche: Subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor captive fermentation capacity in jurisdictions with harmonized FDA-Health Canada labeling pathways, concentrating API production in established North American manufacturing corridors while Mexican maquiladora zones attract secondary packaging operations seeking tariff-advantaged access to United States Medicare reimbursement channels.
United States
Hospital outpatient departments and endocrinology clinics drive volume concentration through cardiovascular outcome trial-validated prescribing for heart failure with reduced ejection fraction. FDA label expansions and CMS national coverage determinations structure reimbursement access across commercial and Medicare Part D plans. The Boston-Cambridge pharmaceutical corridor anchors cardiovascular research programs, while New Jersey-Pennsylvania manufacturing clusters supply high-volume tablet formulations to specialty pharmacy networks.
Canada
Ontario and British Columbia hospital systems are expanding formulary placement following Health Canada and PMRA labeling harmonization with FDA heart failure indications. Provincial reimbursement pathways for chronic kidney disease applications are accelerating faster than diabetes management volume growth. The Toronto-Waterloo biotech corridor supports real-world evidence generation partnerships with United States integrated delivery networks, while Montreal-based fermentation facilities supply biosynthetic intermediates to North American API manufacturers.
Mexico
Maquiladora zones along the northern border states concentrate secondary packaging and finished dose formulation for United States export, leveraging USMCA tariff advantages and proximity to Texas distribution hubs. Mexican regulatory alignment with FDA bioequivalence standards enables abbreviated new drug pathway access for generic SGLT2 inhibitors. The Mexico City metropolitan area hosts clinical trial sites for cardiovascular outcome studies targeting Hispanic patient populations, while Guadalajara pharmaceutical parks expand cold-chain logistics capacity for biologic co-formulation development.
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue differentiated formulation technologies and cardiorenal integrated care partnerships. The North American SGLT2 inhibitor market structures around three operational archetypes: vertically integrated pharmaceutical conglomerates with captive API fermentation, mid-cap specialty firms focused on extended-release delivery systems, and cardiovascular outcome research specialists leveraging integrated evidence networks. Dominant competitive moves include strategic co-formulation alliances with DPP-4 inhibitor platforms and backward integration into biosynthetic intermediate production to secure supply chain priority.
Among research-intensive pharmaceutical conglomerates, Eli Lilly and Company and AstraZeneca exemplify the cardiovascular outcome-driven archetype, occupying positions sustained by dedicated heart failure program investments and extensive real-world evidence networks. Boehringer Ingelheim represents the co-formulation specialist tier, with organizational capabilities anchored in DPP-4 inhibitor combination expertise. These three entities collectively illustrate how evidence generation scale and payer negotiation infrastructure determine competitive positioning in United States Medicare and commercial formulary access.
| Leading Market Players |
|---|
| Janssen |
| Eli Lilly and Company |
| AstraZeneca |
| Boehringer Ingelheim |
| Astellas Pharma |
| Merck & Co., Inc. |
| TheracosBio |
| Lexicon Pharmaceuticals, Inc. |
| Bristol-Myers Squibb Company |
| Others |
Value Network & Pricing Analysis
Captive fermentation capacity among vertically integrated API manufacturers anchors supply security and pricing power across North American SGLT2 inhibitor procurement. This integration choice insulates high-volume tablet producers from biosynthetic intermediate volatility while concentrating margin capture upstream.
Pricing Analysis
Distributor margin compression in specialty pharmacy networks is restructuring net realized prices across the channel stack. Three-tier pricing structure across cardiovascular outcome-validated, chronic kidney disease-labeled, and diabetes-only therapies separates Medicare Part D reimbursement tiers. Cost compression in immediate-release tablets is intensifying because extended-release capsule switching erodes scale advantages. State Medicaid programs exhibit highest price sensitivity; hospital outpatient departments anchored to CMS national coverage determinations show lowest.
Supply Chain Analysis
USMCA domestic-content provisions for pharmaceutical finished dose formulation are reshaping sourcing toward North American packaging corridors. API production draws from United States, Puerto Rico, and Ireland fermentation facilities; biosynthetic intermediates feed from Chinese and Indian chemical synthesis hubs. Single-source vulnerability concentrates in high-purity SGLT2 inhibitor active pharmaceutical ingredient streams. Distribution runs through specialty pharmacy hub services managing prior authorization and patient enrollment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America SGLT2 inhibitor market compounds steadily as cardiovascular outcome trial requirements create durable evidence barriers protecting validated therapies. FDA label expansion momentum for heart failure and chronic kidney disease indications sustains prescriber concentration in trial-validated options.
For Market Incumbents: Deploy real-world evidence network expansion to defend Medicare Part D formulary position against DPP-4 inhibitor substitution pressure. Deepen backward integration into biosynthetic intermediate production to secure captive supply priority as API concentration risk intensifies. Anchor hospital outpatient prescribing through dedicated heart failure program investments that satisfy FDA advisory committee mortality benefit thresholds. For New Entrants and Emerging Players: Capture extended-release capsule white space in United States Medicare Part D polypharmacy segments where adherence monitoring programs drive switching interest. Target Canadian provincial formularies in Ontario and British Columbia where Health Canada labeling harmonization opens reimbursement pathways ahead of United States saturation. Pursue cardiorenal integrated care model partnerships with United States accountable care organizations as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where cardiovascular outcome research scale determines formulary access viability before revenue generation begins. Five-to-ten year viability favors mid-cap specialists with extended-release delivery technology and integrated evidence generation infrastructure. Acquisition target archetype: firms with Health Canada-approved heart failure indications and underpenetrated United States cardiovascular sales infrastructure. Watch FDA advisory committee scheduling for supplemental heart failure indications as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Advancement | Dedicated heart failure mortality trials satisfy FDA advisory committee thresholds for label expansion. |
| Extended-Release Formulation Development | Once-daily capsule technologies capture prescriber switching interest from immediate-release tablets in Medicare Part D. |
| Real-World Evidence Network Expansion | Integrated delivery network datasets accelerate commercial and Medicare Part D formulary negotiations. |
| Backward Integration into Biosynthetic Intermediates | In-house production of fermentation feedstocks secures supply chain priority for high-volume tablet formulations. |
| Canadian Provincial Formulary Partnership | Health Canada and PMRA labeling harmonization opens reimbursement pathways in Ontario and British Columbia hospital systems. |
Research Methodology
Direct dialogue with formulary directors, hospital procurement managers, payer access specialists, and regulatory affairs leads grounded qualitative assessment in prescriber workflow and reimbursement channel dynamics. Secondary validation drew from FDA advisory committee transcripts, CMS national coverage determination databases, ClinicalTrials.gov cardiovascular outcome trial registries, and Health Canada PMRA labeling harmonization records. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated segment-level estimates.
Segmentation outputs across product type, end user, therapy area, and delivery mode informed volume allocation across the projection horizon. CAGRs derived from prescription trend analysis, label expansion timelines, and reimbursement pathway adoption curves. Forecast inputs incorporated FDA advisory committee scheduling, CMS national coverage determination updates, and provincial formulary placement velocity in Canadian markets.
FDA advisory committee reversals, CMS reimbursement tier reclassifications, and biosynthetic intermediate supply disruptions are the dominant revision risks to modeled projections. Forecasts reflect documented assumptions regarding label expansion sequencing and formulary placement timing. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Respiratory Drug Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Global Atrial Fibrillation Drugs Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
Pregnenolone Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Alprazolam Powder Market