
 Angiogenesis Inhibitors and Stimulators Market | 2026-2036
Angiogenesis Inhibitors and Stimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Angiogenesis Inhibitors and Stimulators Market Outlook
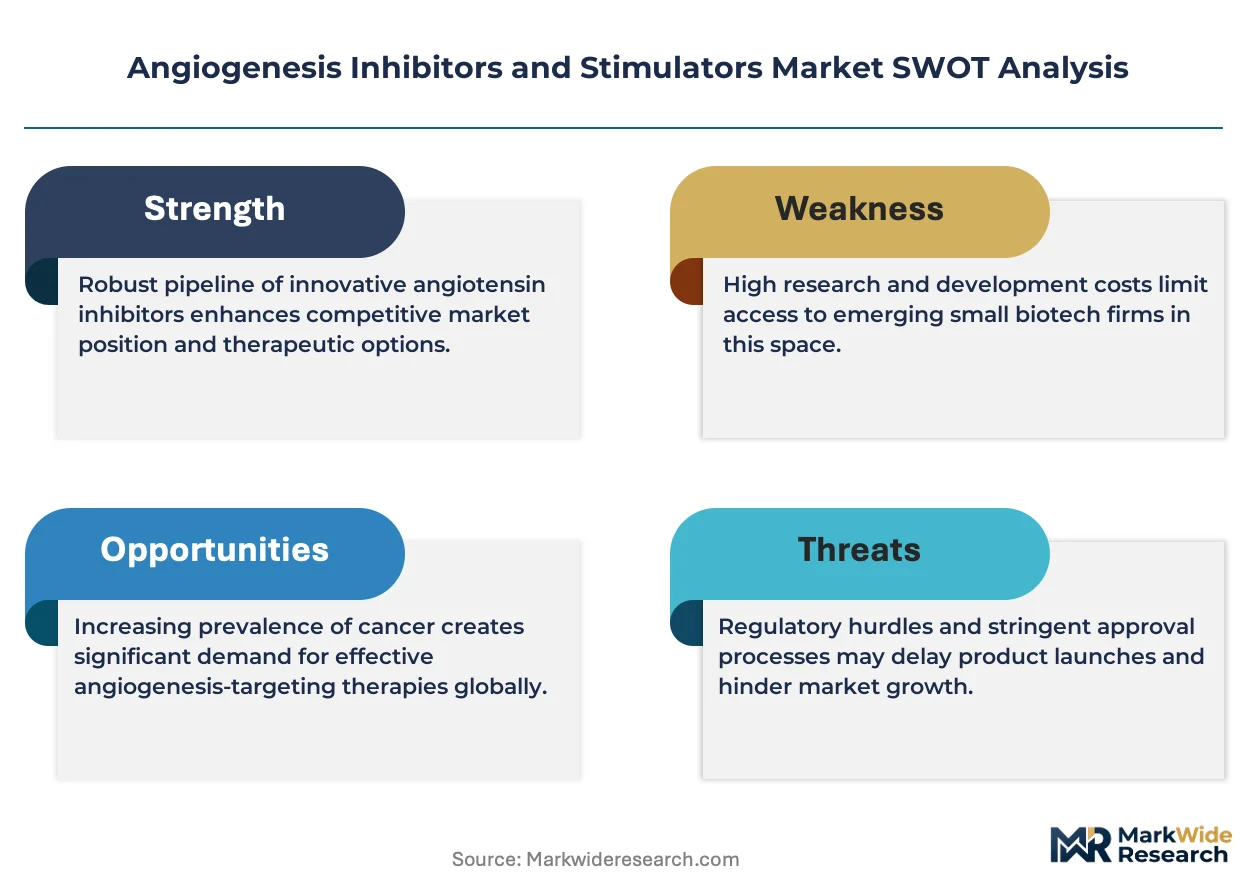
Bi-specific antibody engineering is tilting development pipelines away from single-target VEGF blockade toward dual-mechanism constructs. Roche leverages its ophthalmology franchise to sustain leadership in intravitreal anti-angiogenic delivery. Regeneron Pharmaceuticals anchors its position through proprietary trap-fusion platforms that extend half-life profiles. Novartis competes via integrated radioligand and angiogenesis portfolios that cross-sell into oncology centers.
Angiogenesis inhibitors and stimulators comprise bioactive molecules that modulate vascular endothelial growth factor signaling, platelet-derived growth factor pathways, or fibroblast growth factor cascades to either suppress pathological neovascularization or promote therapeutic revascularization in ischemic tissue. Monoclonal antibodies dominate current revenue pools due to validated manufacturing scale and established infusion infrastructure, while gene therapies represent the fastest-expanding category as adeno-associated viral vectors advance through late-stage trials for inherited retinal disorders. Small molecules concentrate margin capture in oral oncology regimens where patient compliance advantages offset pricing pressure from biosimilar monoclonal antibodies.
The FDA, EMA, and WHO set divergent evidentiary bars for anti-angiogenic approvals, with the FDA's breakthrough therapy designation compressing Phase II-to-approval intervals while EMA's adaptive pathway mandates broader real-world evidence commitments. These regulatory asymmetries force portfolio planners to sequence geographic filings strategically rather than pursue parallel submissions. Stakeholders must monitor how CMS national coverage determinations for combination anti-angiogenic protocols reshape hospital formulary access and prescribing thresholds.
Market Dynamics
Bi-specific antibody engineering is compressing development timelines for next-generation VEGF modulators while FDA breakthrough therapy designations accelerate regulatory pathways. This dual pressure is restructuring competitive positioning around platform durability rather than single-target potency.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy designation compresses Phase II-to-approval intervals for novel anti-angiogenic constructs. Tertiary hospital oncology departments respond by expanding VEGF-targeted protocol adoption.
- Gene Therapy Vectors:Adeno-associated viral delivery systems advance through late-stage trials for inherited retinal disorders, opening new therapeutic categories beyond oncology.
- Medicare Reimbursement Anchoring:United States federal coverage for anti-angiogenic infusions stabilizes commercial volume and reduces payer uncertainty for hospital formulary committees.
Market Restraints
- Manufacturing Scale Concentration:Monoclonal antibody production capacity clusters among contract manufacturers in Switzerland and Ireland, creating supply vulnerability for pipeline candidates.
- Biosimilar Pricing Compression:EMA reference pricing frameworks for off-patent bevacizumab erode margin capture for originator molecules across European oncology markets.
- Real-World Evidence Mandates:EMA adaptive pathway requirements demand broader post-market surveillance commitments, extending total cost-to-market for developers.
Strategic Opportunities
- Ophthalmology Route Expansion:Intravitreal delivery protocols for diabetic macular edema and wet age-related macular degeneration represent underpenetrated indications with durable reimbursement.
- Radioligand Convergence:Integration of angiogenesis inhibitors with radioligand therapeutics enables cross-selling into nuclear medicine departments at integrated oncology centers.
- Oral Small Molecule Capture:Patient compliance advantages in chronic administration settings create pricing power for kinase inhibitors against infusion-dependent biologics.
Industry Challenges
- Bioprocess Talent Scarcity:Cell culture scale-up expertise for trap-fusion platforms concentrates among a limited pool of specialists, constraining manufacturing expansion.
- CMS Coverage Determination Lag:National coverage determinations for combination anti-angiogenic protocols create formulary access uncertainty during launch windows.
- Cross-Portfolio Standardization:Divergent FDA, EMA, and WHO evidentiary bars force sequential rather than parallel geographic filings, complicating launch coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angiogenesis Inhibitors and Stimulators Market |
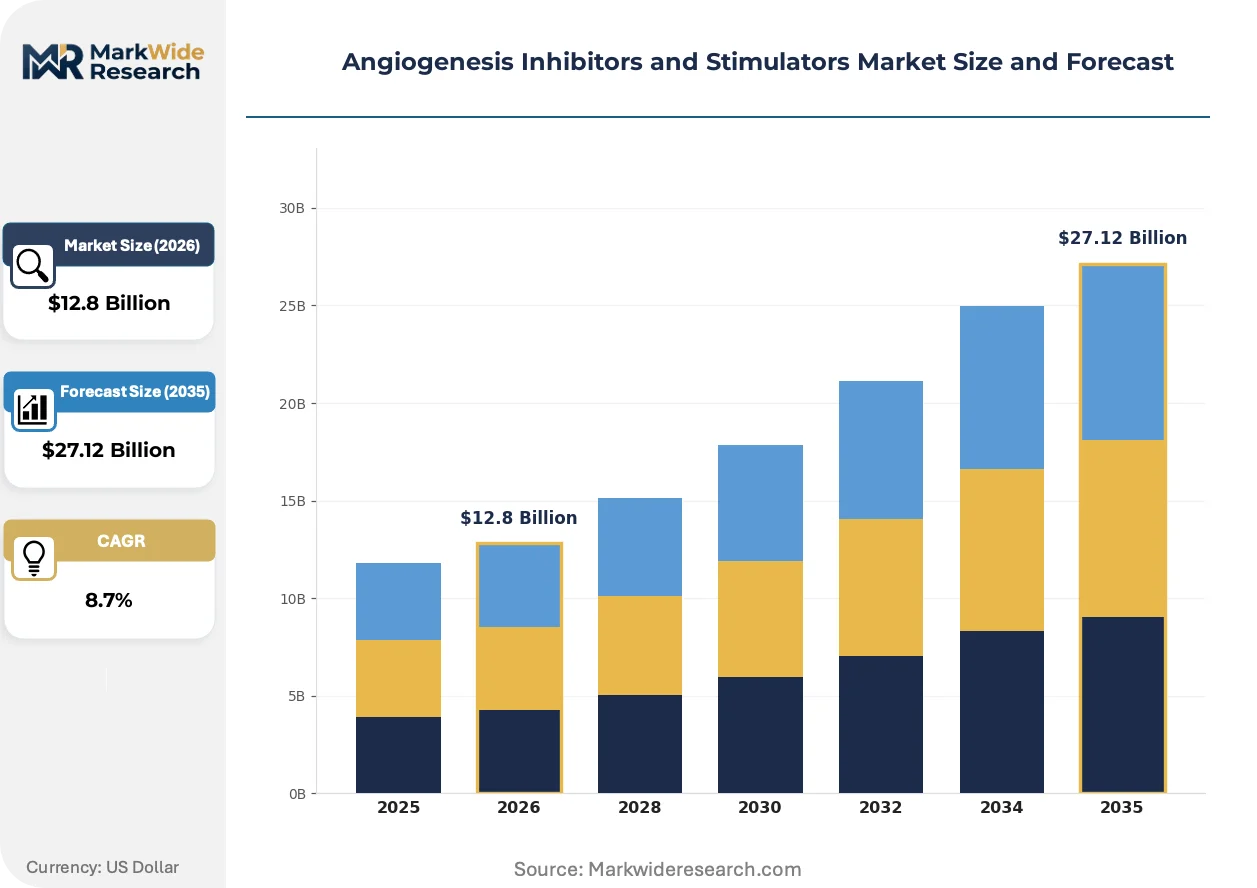
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Monoclonal Antibodies, Peptides, Gene Therapies Therapy Area: Cancer, Ophthalmology, Cardiovascular Diseases, Inflammatory Disorders Delivery Mechanism: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Research Institutions, Homecare |
| Companies Covered | Roche, Novartis, Regeneron Pharmaceuticals, Pfizer, Bristol Myers Squibb, AstraZeneca, Amgen, Bayer, Samsung Bioepis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angiogenesis Inhibitors and Stimulators Market Strategic Shifts
Computational protein design is reshaping therapeutic construct development while regulatory science evolves to accommodate novel modalities. These forces are compressing traditional discovery-to-clinic timelines.
Artificial intelligence-driven molecular simulation is digitizing antibody engineering workflows for dual-target VEGF constructs. Contract research organizations serving mid-cap biotech developers deploy these platforms to reduce lead optimization cycles. The structural consequence is digitizing candidate selection processes that previously required extensive wet-laboratory screening.
EMA's adaptive pathway framework mandates iterative evidence generation through controlled access programs rather than traditional Phase III completion. This regulatory architecture shifts commercial risk toward post-approval confirmatory trials. Oncology developers targeting European market entry must now build real-world evidence infrastructure concurrent with launch rather than as a retrospective exercise.
Hospital procurement committees increasingly unbundle anti-angiogenic infusions from bundled oncology episode payments, creating direct pharmaceutical budget accountability. This pattern concentrates negotiating leverage among integrated delivery networks in the United States. The shift is most visible in Medicare Advantage-contracted systems where pharmacy benefit managers assert formulary control over physician-administered drugs.
Angiogenesis Inhibitors and Stimulators Market Segmentation
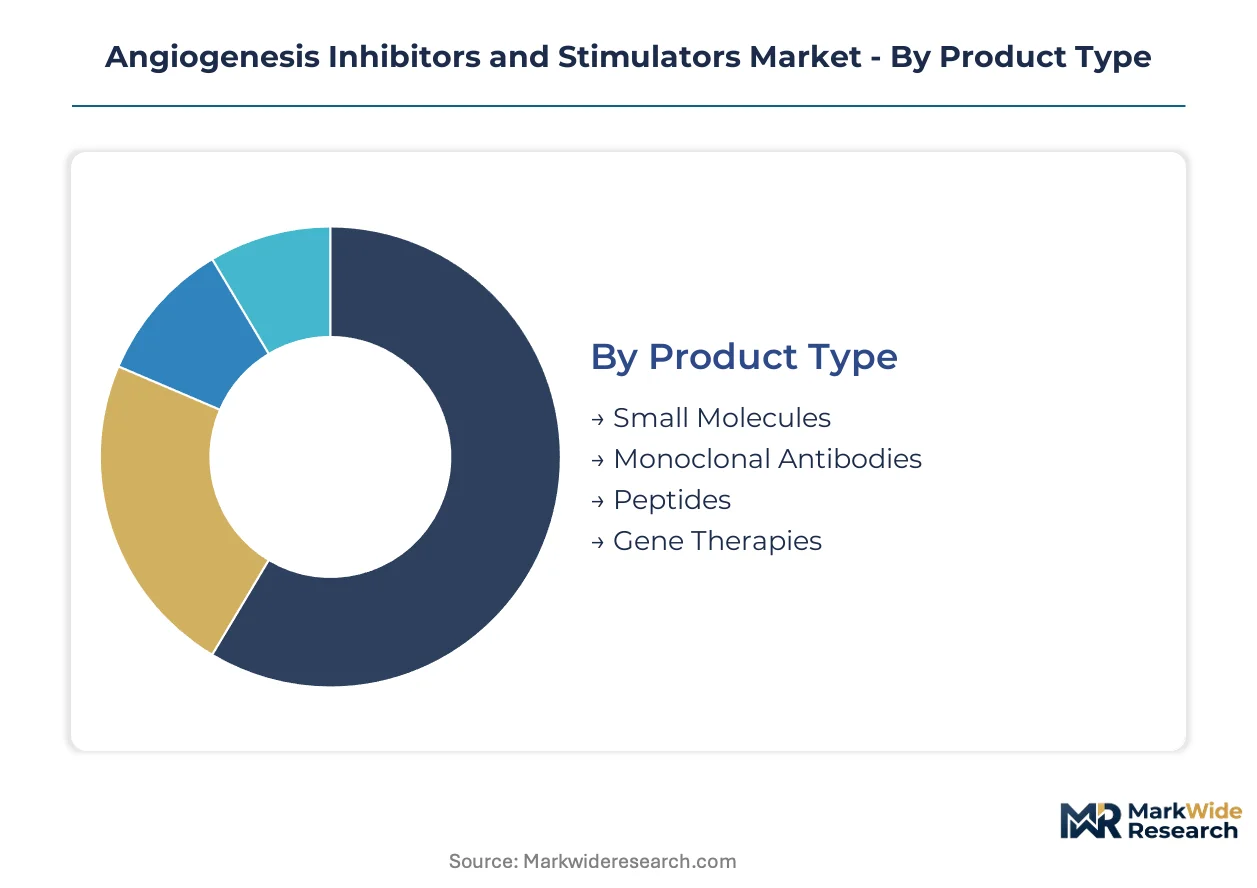
Angiogenesis modulators serve divergent clinical endpoints across oncology, ophthalmology, and regenerative medicine, demanding precise segmentation to align manufacturing scale with therapeutic requirements. Product type and delivery mechanism selections directly determine regulatory pathway complexity and reimbursement coding.
Product Type:
Mature modalities anchor current revenue while emerging platforms reshape pipeline composition and capital allocation priorities.
- Monoclonal Antibodies:These therapeutics bind VEGF-A with high specificity, leveraging established CHO cell production infrastructure at contract manufacturers in Switzerland and Ireland. Tertiary hospital oncology departments in the United States drive demand through Medicare-reimbursed infusion protocols for metastatic colorectal and lung cancers.
- Gene Therapies:Adeno-associated viral vectors deliver sustained VEGF expression for inherited retinal disorders, advancing through late-stage trials under FDA breakthrough therapy designations. Manufacturing bottlenecks at specialized viral vector facilities constrain supply expansion despite accelerating clinical enrollment.
- Small Molecules:Oral kinase inhibitors targeting VEGFR, PDGFR, and FGFR pathways enable chronic outpatient administration with compliance advantages over infusion-dependent biologics.
- Peptides:Short synthetic sequences modulate angiogenic signaling with reduced immunogenicity profiles, finding niche applications in topical wound healing formulations.
Monoclonal antibodies handle the majority of throughput; gene therapies are expanding most quickly on share.
Therapy Area:
Oncology concentration reflects validated VEGF blockade mechanisms, while ophthalmology applications exploit localized delivery routes with durable reimbursement structures.
- Cancer:Solid tumor indications dominate prescription volume, with anti-angiogenic combinations standard in first-line metastatic settings across colorectal, lung, and renal cell carcinomas.
- Ophthalmology:Intravitreal injections for wet age-related macular degeneration and diabetic macular edema command premium pricing through Medicare Part B, with Roche and Regeneron anchoring market leadership through sustained-release formulations.
- Cardiovascular Diseases:Therapeutic angiogenesis for refractory angina and peripheral artery disease remains clinically contested, with gene therapy trials targeting ischemic limb salvage showing mixed efficacy endpoints.
- Inflammatory Disorders:Psoriasis and rheumatoid arthritis applications exploit pathological neovascularization suppression, though these indications trail oncology and ophthalmology in regulatory priority.
Cancer commands the dominant revenue share; ophthalmology delivers the steepest margin expansion trajectory.
Delivery Mechanism:
Route selection determines site-of-care economics, with hospital-based administration capturing the highest reimbursement codes and patient compliance varying inversely with invasiveness.
- Intravenous:Infusion protocols for bevacizumab and biosimilar equivalents anchor hospital outpatient department revenue, requiring cold-chain logistics and pharmacy compounding infrastructure.
- Oral:Tyrosine kinase inhibitors enable home administration with superior adherence metrics, though hepatotoxicity monitoring requirements maintain specialist involvement.
- Subcutaneous:Aflibercept and ranibizumab biosimilars in development target reduced injection frequency versus intravitreal delivery, with patient preference driving formulary positioning.
- Topical:Peptide-based wound healing formulations address diabetic foot ulcers through direct application, bypassing systemic exposure concerns.
Intravenous delivery retains the largest patient volume; oral administration is climbing the fastest on convenience-driven substitution.
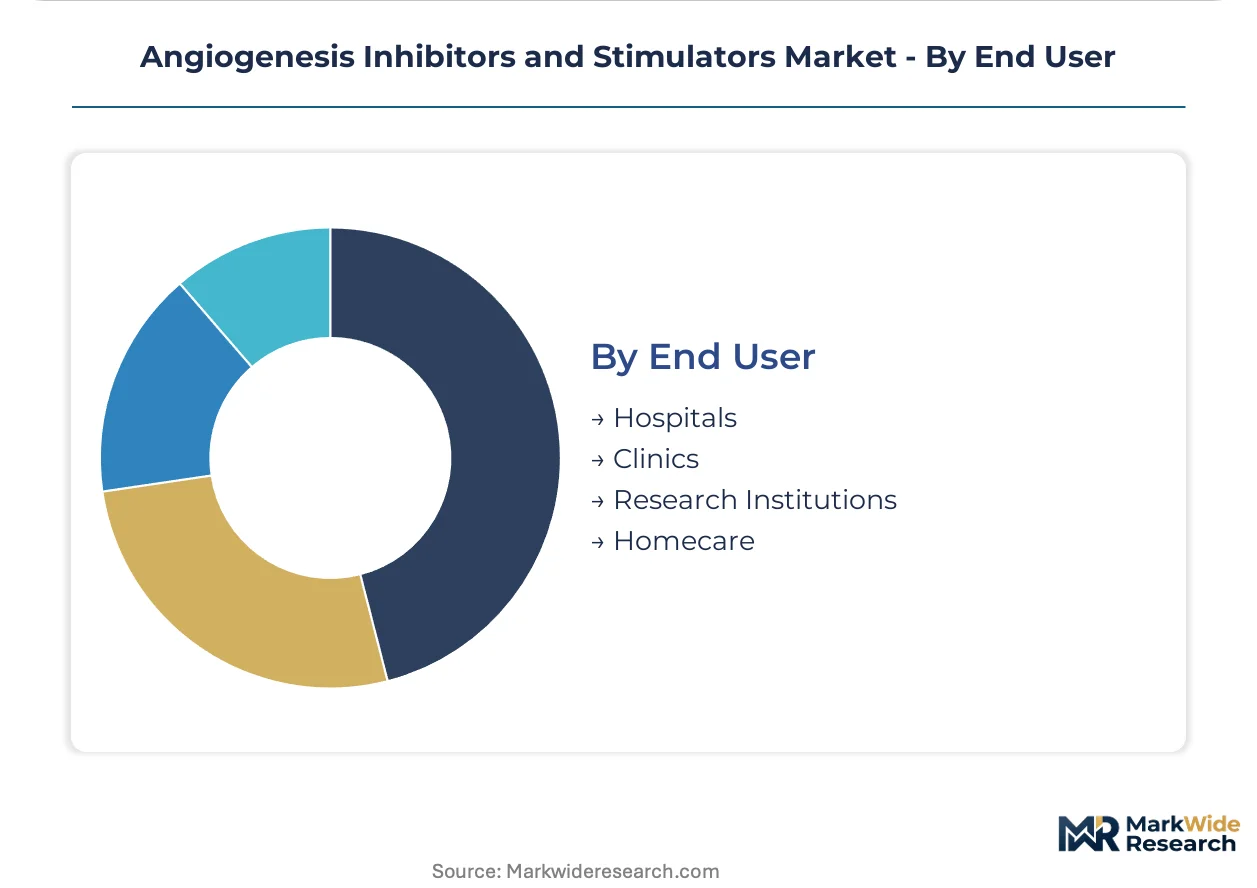
End User:
Institutional purchasing power concentrates negotiating leverage, while homecare expansion responds to payer pressure on site-of-care costs and patient preference for treatment accessibility.
- Hospitals:Integrated delivery networks in the United States leverage 340B pricing and bundled episode payments to capture margin on physician-administered anti-angiogenics, with oncology departments driving protocol adoption.
- Clinics:Ophthalmology specialty practices perform intravitreal injections with dedicated procedure suites, capturing professional fees alongside drug reimbursement.
- Research Institutions:Academic medical centers conduct gene therapy trials under FDA and EMA adaptive pathways, requiring real-world evidence infrastructure for post-approval confirmatory studies.
- Homecare:Oral small molecule dispensing through specialty pharmacies expands as payers redirect infusion-dependent patients toward self-administered alternatives.
Hospitals manage the dominant prescription volume; homecare channels are gaining share fastest on payer site-of-care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States purchase the majority of anti-angiogenic infusions, while hospital procurement committees in Germany and Japan concentrate negotiating leverage for biologics. Medicare reimbursement codes anchor commercial volume in North America, whereas EMA adaptive pathways reshape European launch sequencing.
United States
Tertiary hospital oncology departments drive bevacizumab protocol adoption through Medicare Part B reimbursement. FDA breakthrough therapy designations compress Phase II-to-approval intervals for novel VEGF constructs. The Greater Boston biotech corridor hosts gene therapy vector manufacturing for inherited retinal disorder trials.
Germany
University hospital networks in Baden-Württemberg and Bavaria standardize anti-angiogenic combination regimens for metastatic colorectal cancer. EMA reference pricing frameworks for biosimilar bevacizumab erode originator margins across statutory health insurance funds. The Rhine-Main biotechnology cluster concentrates monoclonal antibody contract manufacturing capacity.
Switzerland
Roche's Basel headquarters anchors ophthalmology franchise leadership in intravitreal anti-angiogenic delivery. Swissmedic maintains aligned evidentiary standards with EMA for adaptive pathway approvals. The greater Zurich area hosts specialized viral vector production facilities for gene therapy candidates.
Japan
PMDA sakigake designation accelerates regulatory review for bi-specific antibody constructs targeting VEGF signaling. Tokyo metropolitan oncology centers adopt combination protocols for gastric and lung cancer indications. The Kansai region's pharmaceutical manufacturing base supplies domestic infusion demand.
India
CDSCO accelerated approval pathways enable domestic biosimilar bevacizumab entry for oncology departments in Maharashtra and Karnataka. Government medical college hospitals in Delhi-NCR expand VEGF-targeted protocol access under Ayushman Bharat coverage. Hyderabad's vaccine and biologics cluster hosts contract development for ophthalmology biosimilars.
Angiogenesis Inhibitors and Stimulators Market Competitive Environment
Channel-controlling players compete with product-specialist players across infusion-dependent oncology and self-administered oral segments. The vendor base stratifies into three tiers: integrated pharmaceutical conglomerates with radioligand convergence capabilities, ophthalmology-focused biologics developers with sustained-release platforms, and biosimilar manufacturers exploiting EMA reference pricing frameworks. Dominant competitive moves include strategic partnerships for gene therapy vector access and portfolio diversification into radioligand-angiogenesis combinations.
Within the integrated conglomerate tier, Roche and Novartis occupy positions spanning oncology and ophthalmology delivery routes. Regeneron Pharmaceuticals exemplifies the platform-specialist archetype through trap-fusion engineering. These three entities anchor competitive dynamics around manufacturing scale, regulatory navigation, and hospital formulary access rather than single-target potency differentiation.
| Leading Market Players |
|---|
| Roche |
| Novartis |
| Regeneron Pharmaceuticals |
| Pfizer |
| Bristol Myers Squibb |
| AstraZeneca |
| Amgen |
| Bayer |
| Samsung Bioepis |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Swiss and Irish contract manufacturing for monoclonal antibody production compresses pricing tier spreads while amplifying supply vulnerability for pipeline candidates. EMA reference pricing frameworks for biosimilar bevacizumab simultaneously erode originator margins and reshape procurement toward cost-plus contract structures indexed to statutory health insurance benchmarks.
Pricing Analysis
Cost-plus contracts with Swiss and Irish manufacturers index pricing to CHO cell culture input costs and capacity utilization rates. Three-tier pricing structure across originator biologics, approved biosimilars, and emerging biobetters differentiates on FDA breakthrough therapy status and Medicare reimbursement coding. Pricing pressure stems from EMA reference pricing mandates that force parallel trade arbitrage across European markets. Hospital procurement committees exhibit highest price sensitivity through 340B program leverage, while ophthalmology specialty practices retain lowest sensitivity due to professional fee capture on intravitreal procedures.
Supply Chain Analysis
Upstream CHO cell culture media and protein A resin feedstock concentrate manufacturing input costs among suppliers in Switzerland, Ireland, and the United States. Viral vector production for gene therapy candidates draws from specialized facilities in Basel and Zurich, creating single-source vulnerability for AAV-based retinal programs. Tariff exposure on Chinese-sourced raw materials intensifies cost volatility for peptide synthesis reagents. Distribution runs through cold-chain logistics networks anchored by hospital outpatient departments and specialty pharmacy channels, with integrated delivery networks consolidating purchasing leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The angiogenesis modulator sector enters a cyclical recovery phase as FDA breakthrough therapy designations compress development timelines and reopen capital deployment into VEGF-targeted platforms. Medicare reimbursement stability for anti-angiogenic infusions provides demand anchoring through the recovery window.
For Market Incumbents: Entrench formulary control through trap-fusion platform extensions that extend half-life profiles beyond biosimilar reach. Secure captive supply of viral vector manufacturing capacity in the greater Zurich area to preempt gene therapy pipeline constraints. Defensive patent thickets around intravitreal delivery protocols protect ophthalmology margin pools from ranibizumab biosimilar erosion.
For New Entrants and Emerging Players: Establish a beachhead in oral small molecule kinase inhibitors targeting chronic outpatient administration where patient compliance advantages offset biologic pricing power. Target diabetic macular edema as the most penetrable ophthalmology indication with durable Medicare Part B reimbursement and underdeveloped biosimilar competition. Pursue licensing arrangements with academic medical centers for AAV vector technology access rather than greenfield manufacturing investment.
For Investors and Strategic Acquirers: FDA's accelerated approval pathway expansion reshapes the acquisition landscape toward platforms with confirmatory trial infrastructure already deployed. Five-to-ten year viability favors developers with integrated radioligand-angiogenesis portfolios that cross-sell into nuclear medicine departments. Watch EMA adaptive pathway enrollment velocity as the signal for European commercial execution capability.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Breakthrough therapy designation compresses Phase II-to-approval intervals for novel VEGF constructs. |
| Manufacturing Scale-Up | CHO cell culture expansion in Swiss and Irish facilities secures supply for biosimilar launch windows. |
| Regulatory Approval Pathway | EMA adaptive pathway mandates real-world evidence infrastructure concurrent with European launch. |
| Pipeline Diversification | Radioligand-angiogenesis combinations enable cross-selling into nuclear medicine at oncology centers. |
| Strategic Partnership | Gene therapy vector licensing with academic medical centers bypasses capital-intensive manufacturing buildout. |
Study Parameters
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling triangulated with top-down market size estimates from formulary database analysis.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, therapy area, delivery mechanism, and end user. CAGRs derived from patient population epidemiology, protocol adoption curves, and pricing trajectory assumptions. Forecast inputs incorporated Medicare coverage determination timelines and EMA adaptive pathway enrollment patterns specific to anti-angiogenic modalities.
Sensitivities concentrate around CMS national coverage determination delays for combination protocols and EMA real-world evidence mandate compliance costs. Cross-checking against hospital procurement database benchmarks and GPO contract pricing is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Mexico Diabetes Drugs Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Global Anti Epileptic Drugs for Pediatrics Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Global Controlled Release Drug Delivery Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Methylphenidate Hydrochloride Market