
 Pelvic Inflammatory Disease (PID) Treatment Market | 2026-2036
Pelvic Inflammatory Disease (PID) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pelvic Inflammatory Disease (PID) Treatment Market Intelligence
Hospital outpatient departments are recalibrating their role in PID care, shifting inpatient hysterectomy-dependent models toward ambulatory antibiotic infusion protocols. Pfizer Inc. leverages its cephalosporin manufacturing scale to dominate hospital formulary contracts across North America. Bayer AG anchors its position through sustained R&D investment in dual-action antimicrobial combinations. Merck & Co., Inc. competes on geographic reach, controlling distribution networks that extend into emerging markets with limited local manufacturing capacity.
Pelvic Inflammatory Disease treatment encompasses pharmacological and surgical interventions targeting upper genital tract infections, with antibiotic regimens typically combining a third-generation cephalosporin with doxycycline and metronidazole to cover polymicrobial etiologies including Neisseria gonorrhoeae, Chlamydia trachomatis, and anaerobic organisms. The primary purpose is to eradicate infection, prevent tubal scarring, and preserve fertility outcomes. Antibiotics command the largest revenue pool within product type segmentation due to their position as first-line therapy, while intravenous delivery modes capture premium pricing in acute PID cases requiring hospitalization. Gynecology clinics represent the fastest-growing end user channel as point-of-care nucleic acid amplification testing enables same-visit diagnosis and treatment initiation.
The US FDA and the EMA jointly shape antimicrobial development pathways through qualified infectious disease product designations and centralized pediatric investigation plan requirements, accelerating novel antibiotic approvals while constraining label expansion for legacy agents. India's CDSCO enforces mandatory adverse event reporting for Schedule H antibiotics, tightening dispensing controls through the Drugs and Cosmetics Act. Stakeholders must monitor evolving breakpoints from CLSI and EUCAST susceptibility committees, as resistance threshold revisions directly invalidate existing regimen efficacy claims and trigger formulary displacement cycles.
Market Dynamics
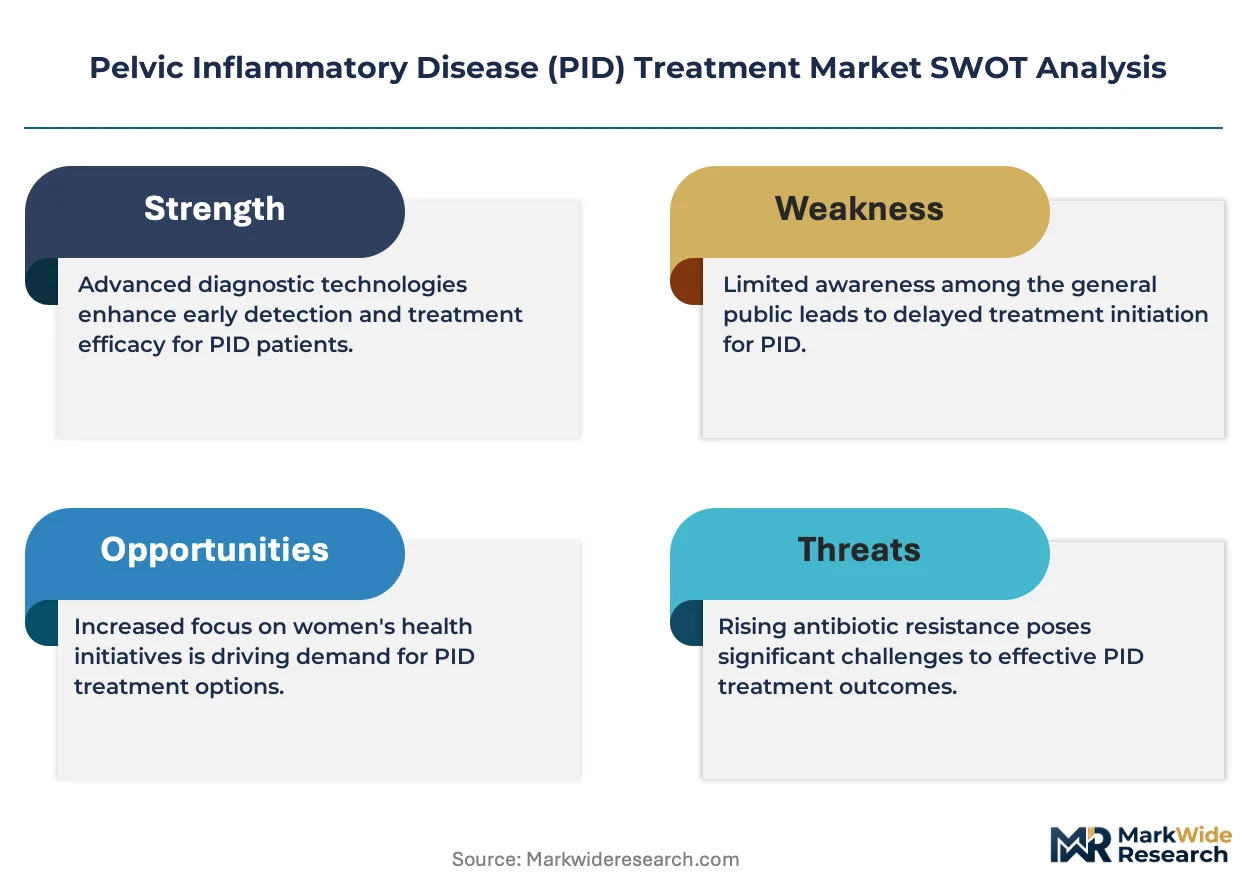
Hospital outpatient departments are displacing inpatient admission protocols for acute PID cases, driven by same-day antibiotic infusion capabilities and pressure from payers to reduce length-of-stay metrics. This structural shift compresses revenue per patient while expanding total addressable procedure volume.
Growth Catalysts
- India's National Reproductive Health Program:Government-funded screening initiatives in Maharashtra and Tamil Nadu are broadening diagnostic access for asymptomatic chlamydial infections, expanding the treated patient pool.
- Point-of-care NAAT platforms:Cepheid and Abbott molecular diagnostics enable same-visit diagnosis and treatment initiation in gynecology clinics, reducing loss-to-follow-up rates.
- CLSI breakpoint revisions:Updated susceptibility thresholds for cephalosporins against Neisseria gonorrhoeae are forcing formulary updates that favor combination regimens with retained efficacy.
Market Restraints
- API concentration in China:Active pharmaceutical ingredient manufacturing for doxycycline and metronidazole concentrates in Zhejiang and Jiangsu provinces, exposing supply chains to export restriction risk.
- Generic price erosion:Patent expirations for branded cephalosporins have collapsed unit pricing in hospital tenders, compressing manufacturer margins below sustainable R&D recovery thresholds.
- Anaerobic coverage limitations:Rising metronidazole resistance in Prevotella species strains threatens the efficacy of standard triple-therapy protocols, requiring costly regimen modifications.
Strategic Opportunities
- Sub-Saharan Africa diagnostic gap:Underpenetrated syndromic management protocols in Nigeria and Kenya present white space for integrated STI-PID testing platforms.
- EMA's Qualified Infectious Disease Product designation:Expedited review pathways for novel antibiotic combinations incentivize development of resistance-evading regimens.
- Telemedicine follow-up channels:Post-treatment adherence monitoring via remote consultation platforms reduces reinfection rates and captures recurring prescription volume.
Industry Challenges
- Microbiology laboratory capacity:Specimen processing bottlenecks in community hospitals delay culture-directed therapy adjustments, extending empiric treatment duration.
- Antimicrobial stewardship compliance:Mandatory pre-authorization requirements for broad-spectrum agents under US hospital stewardship programs add administrative friction to acute case management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelvic Inflammatory Disease (PID) Treatment Market |
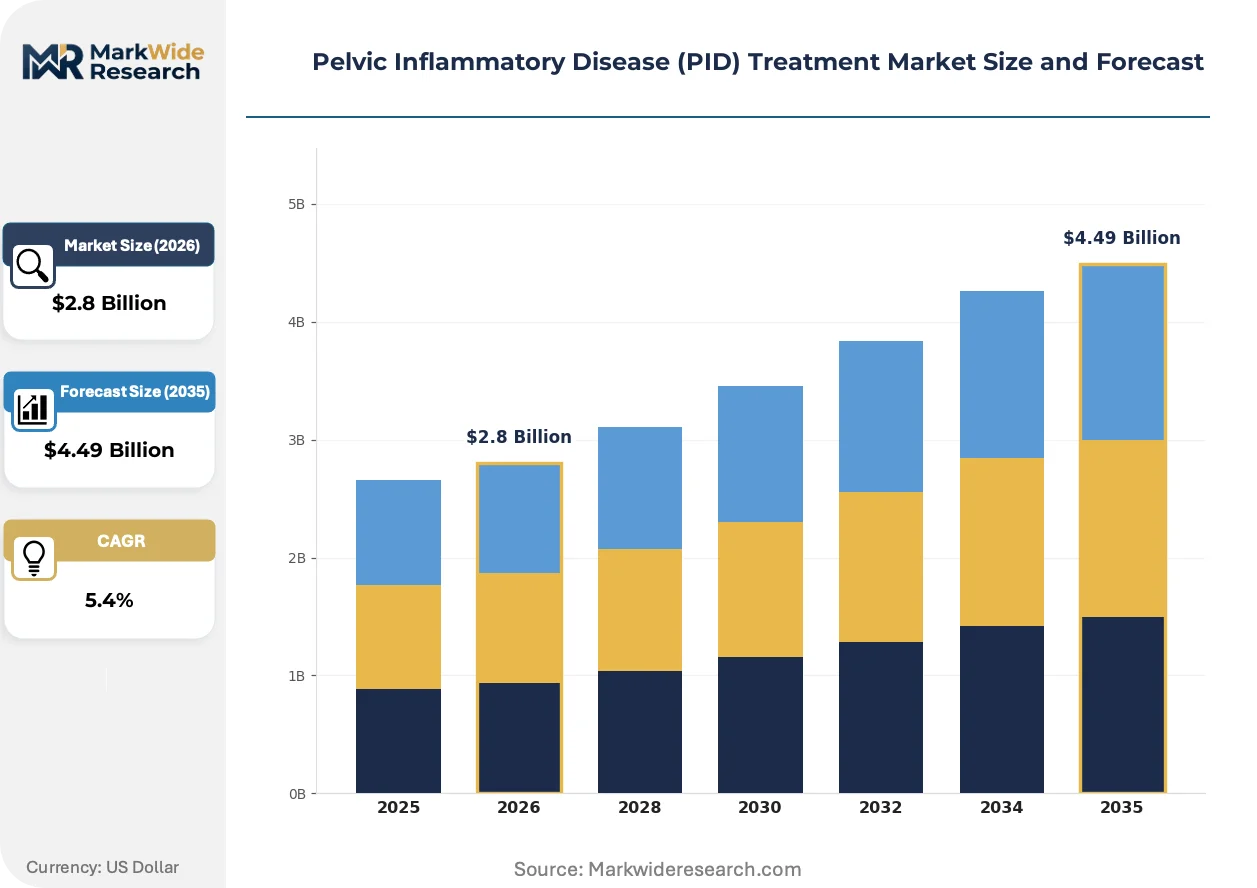
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antimicrobials, Anti-inflammatory Agents, Hormonal Therapy, Probiotics Therapy Area: Acute PID, Chronic PID, Tubo-ovarian Abscess, Endometritis, Salpingitis End User: Gynecology Clinics, Specialty Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories Delivery Mode: Oral, Intravenous, Intramuscular, Topical, Vaginal |
| Companies Covered | Pfizer Inc., Bayer AG, Johnson & Johnson, Merck & Co., Inc., GlaxoSmithKline plc, Sanofi, F. Hoffmann-La Roche Ltd, AbbVie Inc., Bristol-Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelvic Inflammatory Disease (PID) Treatment Market Strategic Shifts & Innovations
Antimicrobial resistance surveillance is reshaping prescribing patterns faster than product development cycles can respond, compressing the commercial lifespan of existing combination regimens. This pressure is accelerating investment in rapid diagnostics and resistance-guided therapy selection tools.
Multiplex PCR panels for simultaneous detection of Neisseria gonorrhoeae, Chlamydia trachomatis, and Mycoplasma genitalium are electrifying diagnostic workflows in hospital emergency departments and urgent care settings. Large health systems in Texas and Florida are deploying these platforms to reduce empiric overtreatment. The technology is electrifying a shift from syndromic management to pathogen-directed therapy, narrowing antibiotic exposure and preserving future regimen utility.
The FDA's updated antimicrobial susceptibility testing standards for Neisseria gonorrhoeae, implemented through CLSI M100 breakpoint revisions, are invalidating historical cephalosporin MIC interpretive criteria. Hospital pharmacy and therapeutics committees must now reconcile legacy susceptibility data with revised thresholds, triggering formulary displacement cycles for combination therapies. Manufacturers with robust post-market surveillance data are securing preferred status in revised hospital guidelines.
Patient preference for discreet, non-facility-based care is fragmenting the traditional gynecology clinic channel. Retail health clinics and direct-to-consumer telemedicine platforms are capturing low-acuity PID consultations previously routed to hospital-based specialists. This behavioral shift is most visible in urban US markets where appointment access constraints and stigma concerns drive channel switching toward CVS MinuteClinic and similar walk-in formats.
Pelvic Inflammatory Disease (PID) Treatment Market Segmentation
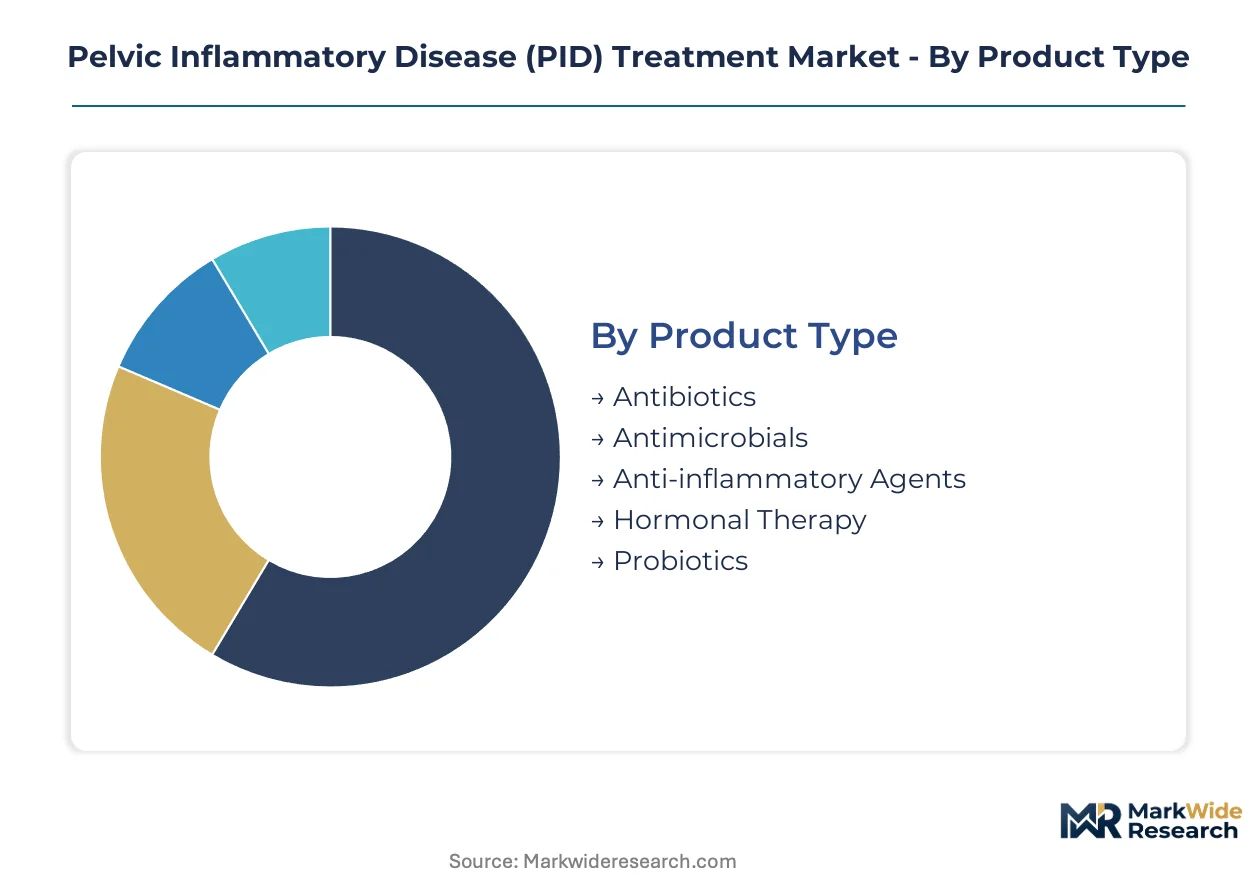
Segmentation in the PID treatment market reveals distinct capital requirements across product categories and delivery infrastructure. Hospital formulary committees and procurement officers use these divisions to allocate antimicrobial budgets and negotiate tiered pricing contracts.
Product Type:
Antibiotics demand the heaviest upfront manufacturing investment due to fermentation capacity, sterile fill-finish lines, and regulatory validation requirements for cephalosporin production.
- Antibiotics:Combination regimens pairing third-generation cephalosporins with doxycycline and metronidazole dominate hospital procurement tenders. Demand concentrates in North American health systems where FDA breakpoint revisions force formulary updates toward retained-efficacy combinations.
- Antimicrobials:Novel dual-action compounds targeting polymicrobial etiologies require extensive clinical trial investment. Indian government reproductive health programs are expanding access to subsidized antimicrobial diagnostics and therapy in Maharashtra and Tamil Nadu.
- Anti-inflammatory Agents:Adjunctive corticosteroid and NSAID formulations reduce tubal inflammation sequelae.
- Hormonal Therapy:Estrogen-progestin combinations modulate endometrial receptivity during recovery.
- Probiotics:Lactobacillus-dominant vaginal microbiome restoration products emerge as post-antibiotic adjuncts.
Antibiotics absorb the bulk of installed capacity; probiotics are expanding most quickly.
Therapy Area:
Acute PID cases generate the highest procedure volume and drive emergency department antibiotic utilization patterns across health systems.
- Acute PID:Sudden-onset upper genital tract infection requiring immediate empiric therapy. Hospital outpatient departments in Texas and Florida deploy multiplex PCR panels to reduce overtreatment.
- Chronic PID:Recurrent or persistent infection with tubal scarring sequelae. Gynecology clinics capture follow-up volume through point-of-care NAAT platforms enabling same-visit management.
- Tubo-ovarian Abscess:Complicated infection requiring image-guided drainage or surgical intervention.
- Endometritis:Postpartum or post-procedural uterine lining inflammation.
- Salpingitis:Isolated fallopian tube infection with direct fertility implications.
Acute PID commands the largest patient volume; chronic PID shows the steepest expansion trajectory as screening programs identify previously untreated cases.
End User:
Facility-based reimbursement models and capital equipment requirements create divergent investment thresholds across care settings.
- Gynecology Clinics:Point-of-care molecular diagnostics enable same-visit diagnosis and treatment initiation. Cepheid and Abbott platforms reduce loss-to-follow-up in urban US markets where CVS MinuteClinic and similar formats capture discreet care demand.
- Specialty Hospitals:Academic medical centers manage severe cases requiring surgical intervention. These institutions anchor training programs for residents in advanced laparoscopic techniques.
- Ambulatory Surgical Centers:Same-day hysteroscopy and drainage procedures.
- Diagnostic Laboratories:Centralized microbiology and susceptibility testing services.
Specialty hospitals retain the most complex case volume; gynecology clinics are gaining share fastest through diagnostic-therapy integration.
Delivery Mode:
Route selection balances bioavailability requirements against patient compliance and healthcare worker training costs.
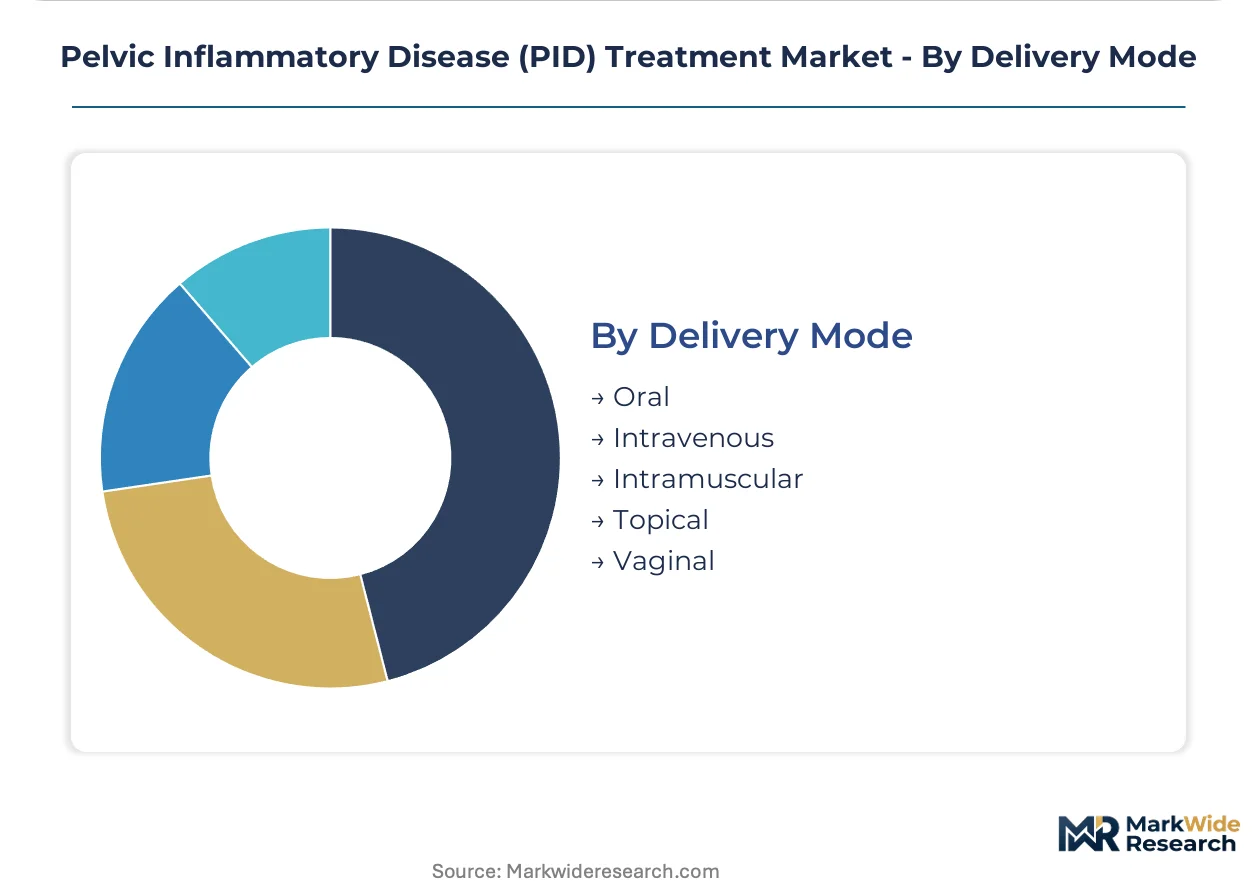
- Intravenous:Hospital-administered infusion for severe or complicated cases requiring inpatient observation. Acute PID protocols in US hospital outpatient departments shift toward same-day IV antibiotic administration.
- Oral:Outpatient step-down therapy and uncomplicated case management. Indian CDSCO Schedule H dispensing controls tighten through mandatory adverse event reporting.
- Intramuscular:Single-dose ceftriaxone administration in emergency departments.
- Topical:Limited utility for superficial adjunctive therapy.
- Vaginal:Local probiotic and antimicrobial gel formulations.
Intravenous delivery captures premium pricing in acute settings; oral formulations dominate total prescription volume through outpatient conversion protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones in Hyderabad and Visakhapatnam concentrate active pharmaceutical ingredient manufacturing for doxycycline and metronidazole, attracting contract manufacturing investment from multinational antibiotic suppliers seeking export capacity.
United States
Hospital outpatient departments in Texas and Florida deploy multiplex PCR diagnostic platforms to enable same-day antibiotic infusion protocols. FDA breakpoint revisions for Neisseria gonorrhoeae susceptibility testing force formulary updates toward retained-efficacy cephalosporin combinations. The Research Triangle Park corridor in North Carolina anchors clinical trial infrastructure for novel antimicrobial development.
India
Maharashtra and Tamil Nadu state governments expand subsidized chlamydial screening through the National Reproductive Health Program, broadening the treated patient pool for asymptomatic infections. CDSCO Schedule H dispensing controls tighten through mandatory adverse event reporting requirements for broad-spectrum antibiotics. The Hyderabad-Visakhapatnam pharmaceutical cluster supplies fermentation-based API for global metronidazole and doxycycline markets.
Germany
EMA Qualified Infectious Disease Product designations accelerate novel antibiotic combination approvals for polymicrobial PID coverage. Hospital pharmacy and therapeutics committees in Bavaria and North Rhine-Westphalia reconcile legacy susceptibility data with revised EUCAST breakpoints. The Frankfurt-Rhine-Main biopharma corridor hosts centralized pediatric investigation plan coordination for antimicrobial development.
China
Zhejiang and Jiangsu provinces concentrate fermentation capacity for generic cephalosporin and nitroimidazole active pharmaceutical ingredients. NMPA enforcement of updated pharmacovigilance standards tightens post-market surveillance for hospital-administered antibiotics. The Yangtze River Delta chemical cluster faces export restriction exposure as geopolitical risk concentrates in API supply chains.
Brazil
ANVISA streamlines antimicrobial registration pathways for combination therapies targeting polymicrobial gynecological infections. Public hospital procurement in São Paulo and Minas Gerais shifts toward syndromic management protocols with integrated STI-PID diagnostic platforms. The São Paulo metropolitan corridor concentrates private gynecology clinic networks adopting point-of-care molecular testing.
Pelvic Inflammatory Disease (PID) Treatment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with hospital formulary contracts concentrating around cephalosporin suppliers possessing fermentation scale and generic API producers competing on unit cost in outpatient channels. The competitive structure tiered across three archetypes: multinational pharmaceutical corporations with integrated manufacturing, regional generic specialists with API backward integration, and biotechnology developers pursuing resistance-evading novel mechanisms. Capacity expansion in Indian special economic zones and strategic partnerships for diagnostic-therapy integration represent the dominant competitive moves reshaping positioning.
Among multinational pharmaceutical corporations, Pfizer Inc., Bayer AG, and Merck & Co., Inc. occupy anchor positions within the hospital formulary tier. Pfizer exemplifies the fermentation-scale archetype through cephalosporin manufacturing infrastructure. Bayer represents sustained R&D investment positioning in dual-action antimicrobial combinations. Merck sits within the geographic reach archetype, with distribution networks extending into emerging markets with limited local manufacturing capacity.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| Johnson & Johnson |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Sanofi |
| F. Hoffmann-La Roche Ltd |
| AbbVie Inc. |
| Bristol-Myers Squibb Company |
| Others |
Cost & Logistics Intelligence
Fermentation-grade doxycycline API spot prices in the Yangtze River Delta chemical cluster cascade through cephalosporin combination therapy pricing tiers, compressing margins for hospital formulary contracts while rewarding manufacturers with captive fermentation capacity.
Pricing Analysis
Short lead-time premiums for sterile fill-finished cephalosporin vials command 15-25% markups over standard 90-day delivery contracts in North American hospital procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by GMP certification tier and post-market surveillance data completeness. Pricing pressure stems from generic metronidazole price erosion in Indian government tenders, where CDSCO Schedule H dispensing controls intensify cost scrutiny. Hospital pharmacy and therapeutics committees exhibit highest price sensitivity, while specialty gynecology clinics prioritize diagnostic-therapy bundling over unit cost.
Supply Chain Analysis
Third-generation cephalosporin API supply rests on fermentation capacity concentrated in Zhejiang and Jiangsu provinces, with secondary sourcing from Indian pharmaceutical special economic zones in Hyderabad and Visakhapatnam. Key inputs include corn-derived dextrose for fermentation media, specialized stainless steel bioreactor vessels, and sterile fill-finish isolator technology. Single-source vulnerability concentrates in nitroimidazole precursor chemicals from the Yangtze River Delta, exposing formulators to export restriction risk. Distribution runs through hospital group purchasing organizations and government procurement agencies, with direct manufacturer-to-clinic channels expanding for point-of-care diagnostic-therapy bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PID treatment supply chains are consolidating around backward integration into fermentation capacity, with players racing to secure captive API production before CDSCO and FDA tightening of pharmacovigilance standards raises compliance barriers.
For Market Incumbents: Lock in hospital formulary contracts through post-market surveillance data packages that validate retained efficacy against revised CLSI breakpoints. Secure fermentation capacity expansion in Indian pharmaceutical special economic zones to offset Zhejiang-Jiangsu supply concentration risk. Prioritize diagnostic-therapy integration partnerships with Cepheid and Abbott platform deployers to capture gynecology clinic channel growth. For New Entrants and Emerging Players: Telemedicine platforms represent the most penetrable channel for post-treatment adherence monitoring and recurring prescription capture in urban US markets. Target sub-Saharan Africa syndromic management protocols in Nigeria and Kenya with integrated STI-PID testing platforms that bypass microbiology laboratory capacity constraints. Pursue EMA Qualified Infectious Disease Product designation pathways to accelerate novel antibiotic combination approvals. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional generic specialists with API backward integration in Maharashtra and Tamil Nadu, where National Reproductive Health Program expansion is broadening the treated patient pool. Long-term viability hinges on resistance-evading regimen development and diagnostic-therapy bundling capabilities. Watch for CLSI and EUCAST breakpoint revision announcements as inflection indicators triggering formulary displacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Cephalosporin fermentation capacity expansion in Indian SEZs reduces Zhejiang-Jiangsu supply concentration exposure. |
| Regulatory Approval Pathway | EMA Qualified Infectious Disease Product designation accelerates novel antibiotic combination market entry timelines. |
| Strategic Partnership | Diagnostic-therapy integration with Cepheid and Abbott NAAT platform deployers captures gynecology clinic channel growth. |
| Backward Integration | Captive metronidazole and doxycycline API production insulates margins from generic price erosion in government tenders. |
| Geographic Expansion | Sub-Saharan Africa syndromic management protocols in Nigeria and Kenya present white space for integrated STI-PID platforms. |
Research Approach
Multi-period observation of FDA breakpoint revision timelines, CDSCO Schedule H enforcement patterns, and EMA pediatric investigation plan completion rates anchored the trend analysis, supplemented by interviews with hospital formulary directors, antimicrobial stewardship officers, gynecology clinic operators, and API procurement managers at multinational pharmaceutical manufacturers. Secondary validation drew from FDA antimicrobial susceptibility testing guideline updates, EUCAST breakpoint revision documentation, Indian government reproductive health program expenditure reports, and CLSI M100 standard publications. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation reconciled market size estimates.
Input-output matrices mapped antibiotic regimen demand against fermentation capacity utilization, API trade flow data, and hospital procurement contract structures across the analysis window. Segmentation dimensions encompassed product type, therapy area severity, end-user facility tier, and delivery mode, with regional regulatory clusters capturing FDA, EMA, CDSCO, and NMPA jurisdiction effects. CAGRs derived from epidemiological trend extrapolation, antimicrobial resistance surveillance data, and healthcare infrastructure investment trajectories. Forecast inputs included chlamydial screening program expansion rates and point-of-care diagnostic adoption curves.
Caveats apply where CLSI or EUCAST susceptibility threshold revisions, API export restrictions from Zhejiang-Jiangsu provinces, or antimicrobial stewardship program tightening could materially shift the outlook. A small set of triggers—breakpoint revision announcements, CDSCO adverse event reporting enforcement intensity, and telemedicine reimbursement policy changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Brucellosis Market