
 APAC Infectious Disease Diagnosis & Treatment Market | 2026-2036
APAC Infectious Disease Diagnosis & Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Infectious Disease Diagnosis & Treatment Market Insights
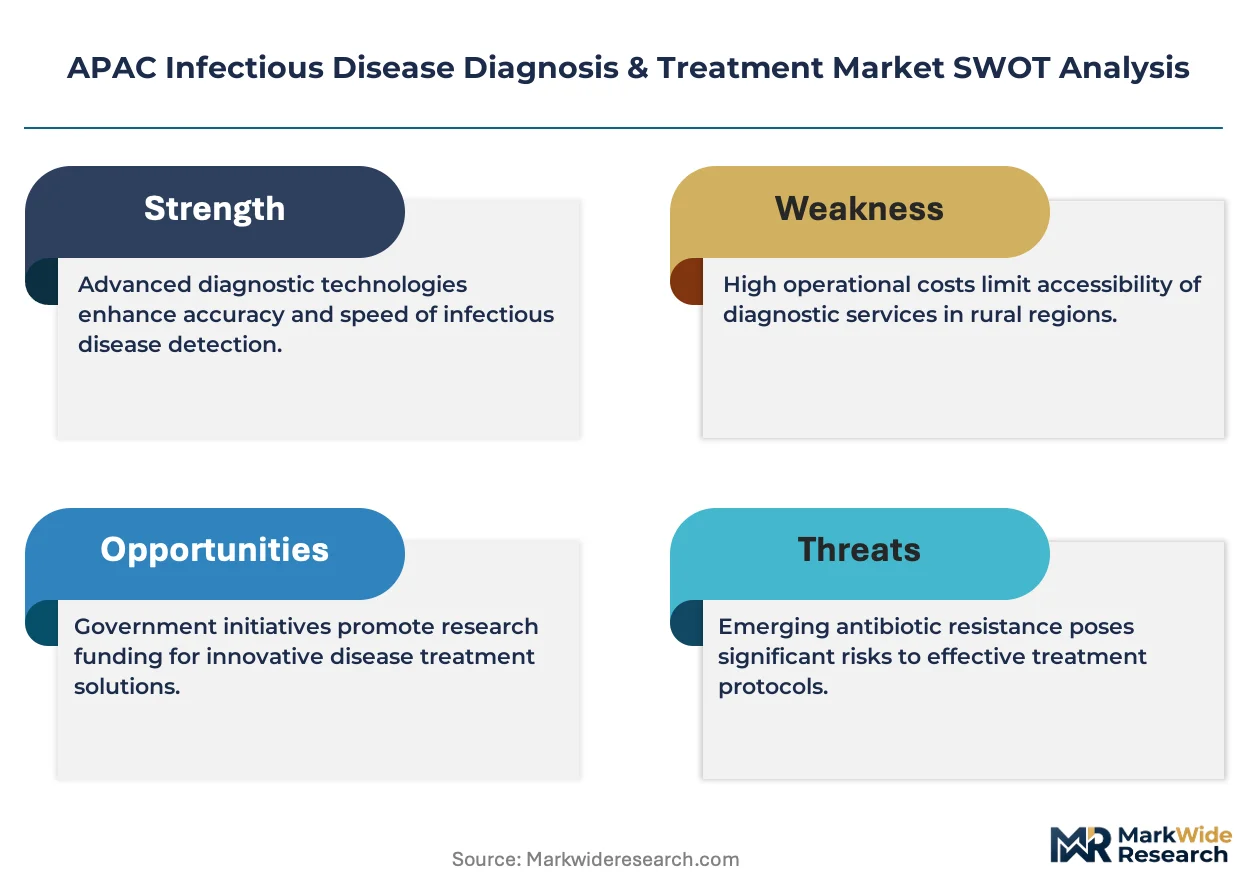
A shortage of trained molecular biologists and infectious disease specialists is redrawing competitive boundaries across the APAC region. Abbott Laboratories leverages its point-of-care manufacturing footprint to sustain supply continuity in fragmented distribution environments. F. Hoffmann-La Roche Ltd anchors high-throughput diagnostic workflows in premium hospital networks through integrated platform ecosystems. Danaher Corp competes on workflow automation density, differentiating its portfolio across clinical laboratory consolidation trends.
Infectious disease diagnosis and treatment encompasses the detection, identification, and therapeutic management of pathogenic microorganisms through in vitro diagnostic platforms, prophylactic immunization, and antimicrobial or antiviral pharmaceutical intervention, typically operating at sensitivity thresholds of 10-100 copies per milliliter for nucleic acid amplification methods. Molecular diagnostics platforms command premium positioning due to multiplex pathogen detection capabilities and laboratory information system integration requirements. Point-of-care testing occupies the fastest-expanding margin pool as decentralized healthcare infrastructure penetrates rural and peri-urban catchments. Drug therapies retain volume dominance across tuberculosis and HIV application segments where long-course regimens sustain recurring pharmaceutical demand.
India's CDSCO and the EU-MDR-aligned regulatory transitions in Australia through TGA are tightening premarket validation requirements for novel diagnostic assays, extending product development timelines and elevating capital barriers for market entry. China's NMPA accelerated review pathways for endemic disease priorities are redirecting multinational R&D investment toward localized clinical trial infrastructure. Stakeholders must monitor convergence between national essential medicine list revisions and procurement tender specifications to anticipate volume allocation shifts across public health programs.
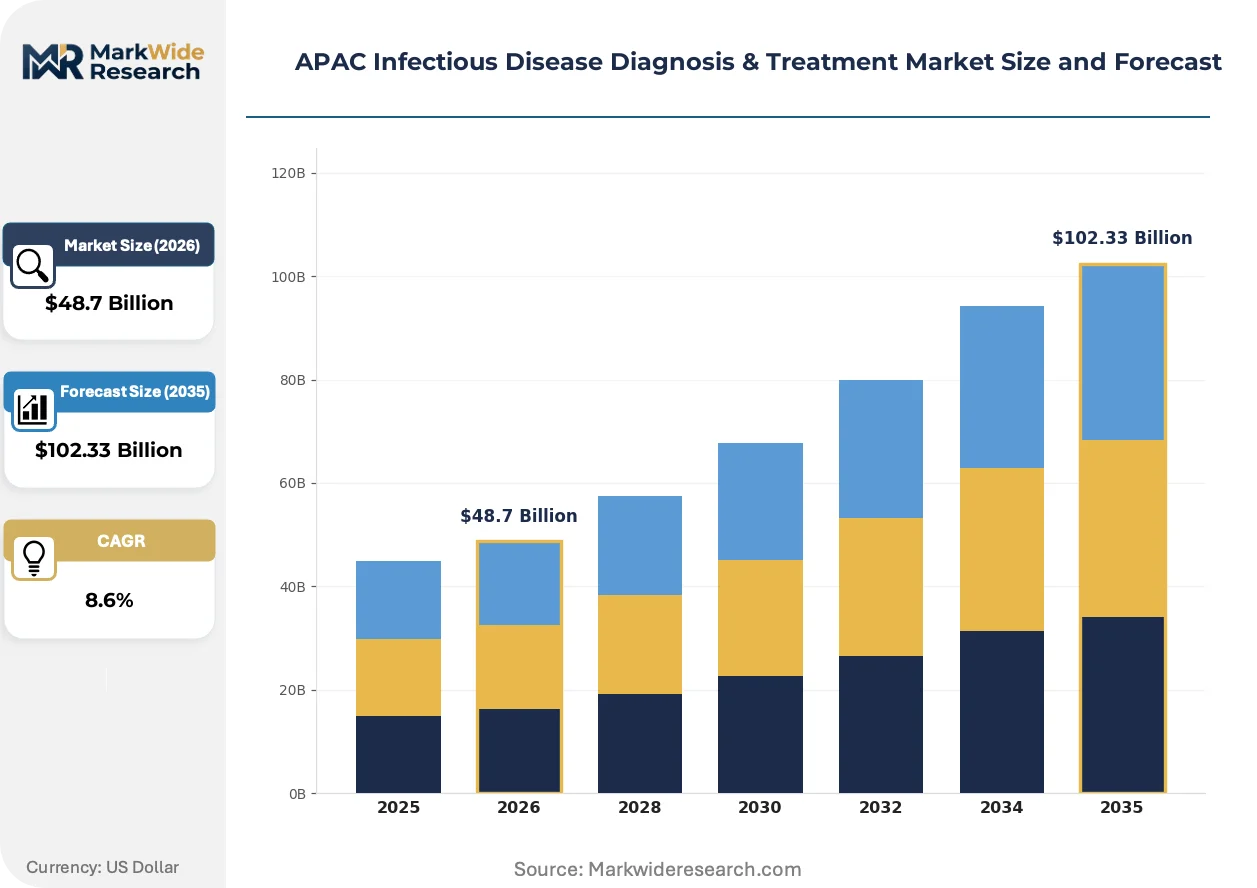
Market Dynamics
Automated molecular diagnostic platforms are compressing turnaround times for pathogen identification across Southeast Asian hospital networks, forcing capital reallocation from centralized laboratory infrastructure toward distributed point-of-care architectures.
Growth Catalysts
- India's PLI scheme:Domestic API and vaccine production incentives are redirecting pharmaceutical manufacturing investment toward captive supply chains, reducing import dependency for critical infectious disease therapeutics.
- CDSCO regulatory harmonization:Streamlined premarket validation pathways for endemic disease diagnostics are accelerating product registration timelines for manufacturers targeting tuberculosis and dengue assay segments.
- Tier-2 and tier-3 diagnostic infrastructure:India's secondary cities are closing laboratory capacity gaps through public-private partnership models, expanding addressable patient populations for molecular testing services.
Market Restraints
- Trained molecular biologist scarcity:Southeast Asian diagnostic laboratories face persistent workforce shortages, constraining throughput capacity for nucleic acid amplification platforms.
- Reagent supply concentration:Polymerase and probe chemistries for multiplex assays depend on concentrated North American and European supplier bases, exposing procurement to currency and logistics volatility.
- EU-MDR alignment costs:Australia's TGA transition toward European medical device regulation standards is extending clinical validation timelines and elevating documentation burdens for novel assay developers.
Strategic Opportunities
- Vietnam's central highlands:Underpenetrated rural catchments present first-mover advantages for portable point-of-care testing networks targeting malaria and respiratory pathogen screening.
- CRISPR-based diagnostic convergence:Gene-editing tool adaptation for field-deployable pathogen detection is opening white-space competition against incumbent PCR platform architectures.
- Telemedicine integration:Remote consultation platforms are creating new distribution channels for home-based infectious disease sampling kits, bypassing traditional hospital laboratory gatekeepers.
Industry Challenges
- Multiplex assay certification complexity:Validating simultaneous pathogen detection panels for NMPA and CDSCO submission requires parallel clinical trial infrastructure, duplicating development expenditure.
- Legacy LIS integration friction:Hospital information system heterogeneity across Indonesian and Philippine healthcare networks complicates automated result reporting for automated molecular platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Infectious Disease Diagnosis & Treatment Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Kits, Vaccines, Drug Therapies, Biologicals End User: Hospitals, Clinics, Laboratories, Home Care Technology: Molecular Diagnostics, Immunoassays, Point-of-Care Testing, Imaging Application: HIV, Tuberculosis, Malaria, Hepatitis |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Danaher Corp, Bio-Rad Laboratories Inc, Merck & Co., Pfizer Inc., Thermo Fisher Scientific Inc, Aurobindo Pharma, Dr. Reddy's Laboratories, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Infectious Disease Diagnosis & Treatment Market Trends and Innovations
Digital pathology integration and artificial intelligence-assisted pattern recognition are reshaping diagnostic workflow economics, compressing specialist interpretation bottlenecks while elevating assay sensitivity thresholds.
CRISPR-Cas12 and Cas13 diagnostic platforms are decomposing the cost and complexity barriers that have confined high-specificity nucleic acid testing to centralized reference laboratories. Community health centers in Thailand and Vietnam are piloting these systems for same-day tuberculosis confirmation. The technology is decomposing the traditional hub-and-spoke sample transport model that has delayed treatment initiation in rural catchments.
China's NMPA accelerated review pathways for endemic disease priorities are compressing regulatory timelines for domestic manufacturers targeting dengue fever and influenza assay segments. Multinational developers are redirecting clinical trial investment toward localized study infrastructure to access these expedited channels. Vietnamese and Indonesian regulators are observing this framework for potential adaptation, creating competitive pressure on traditional FDA-first registration strategies.
Public hospital procurement consolidation across India's state-level health missions is fragmenting vendor access, replacing multiple district-level tenders with centralized framework agreements. Diagnostic platform suppliers must now navigate single-entry-point negotiations with state purchasing authorities rather than cultivating individual institutional relationships. Karnataka and Tamil Nadu are furthest along this transition, with Maharashtra and Gujarat following comparable consolidation trajectories.
APAC Infectious Disease Diagnosis & Treatment Market Segmentation
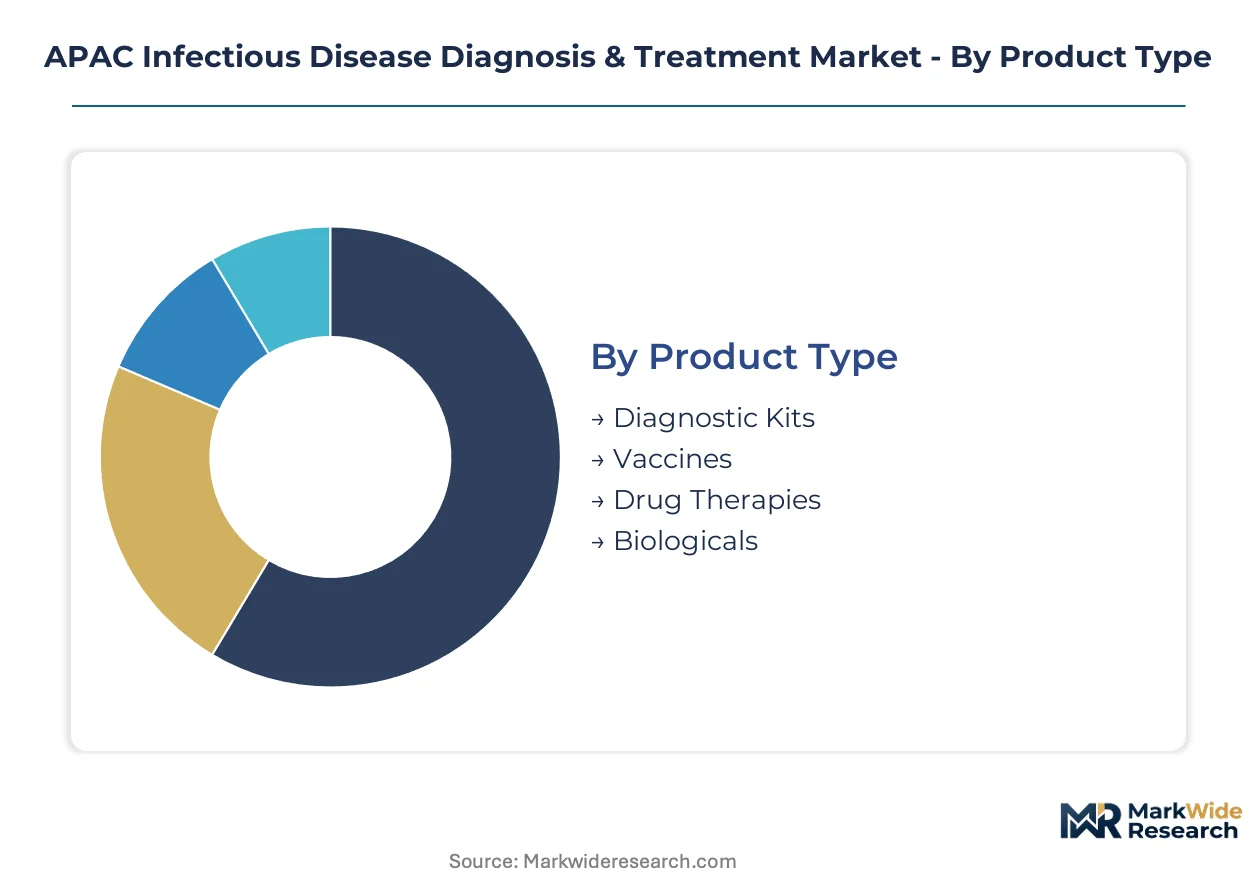
Infectious disease management across APAC demands precise segment alignment with regulatory pathways and care delivery models. Product type determines CDSCO versus NMPA submission routes. End-user concentration shapes procurement negotiation leverage.
Product Type:
CDSCO and NMPA validation requirements diverge sharply across pharmaceutical versus diagnostic product categories, creating distinct capital allocation thresholds for manufacturers.
- Diagnostic Kits:Nucleic acid amplification platforms and antigen detection assays operate at 10-100 copies per milliliter sensitivity thresholds. India's tier-2 and tier-3 cities are closing infrastructure gaps fastest, driving molecular kit demand through public-private laboratory partnerships.
- Vaccines:Prophylactic immunization products for tuberculosis, hepatitis, and endemic respiratory pathogens. India's PLI scheme is redirecting capital toward domestic API and vaccine production, reducing import dependency for critical infectious disease prophylaxis.
- Drug Therapies:Antimicrobial and antiviral pharmaceutical interventions for established disease management.
- Biologicals:Monoclonal antibodies and recombinant protein therapeutics targeting resistant pathogen strains.
Drug therapies handle the majority of throughput; diagnostic kits are climbing the fastest on share.
End User:
Procurement centralization is redrawing access patterns across institutional versus decentralized care settings.
- Hospitals:Acute care facilities with integrated laboratory infrastructure and specialist infectious disease capacity. Southeast Asian hospital networks are scaling automated molecular diagnostic platforms, compressing turnaround times for pathogen identification.
- Laboratories:Reference and hospital-affiliated diagnostic facilities processing high-throughput sample volumes. Persistent shortages of trained molecular biologists across Southeast Asia constrain throughput capacity for nucleic acid amplification platforms.
- Clinics:Primary care and specialty outpatient facilities with limited on-site diagnostic capability.
- Home Care:Patient-directed sampling and remote monitoring configurations.
Laboratories handle the majority of throughput; home care is gaining share fastest.
Technology:
Workflow automation density separates premium positioning from commodity competition.
- Molecular Diagnostics:PCR and nucleic acid amplification platforms with multiplex pathogen detection and laboratory information system integration. Abbott Laboratories leverages point-of-care manufacturing footprints to sustain supply continuity in fragmented distribution environments.
- Point-of-Care Testing:Portable diagnostic devices enabling same-day result delivery outside centralized laboratory infrastructure. Vietnam's central highlands and comparable rural catchments present first-mover advantages for portable testing networks targeting malaria and respiratory pathogen screening.
- Immunoassays:Antibody and antigen detection methods for serological screening.
- Imaging:Radiological and ultrasound-based pathogen complication assessment.
Molecular diagnostics handles the majority of throughput; point-of-care testing is expanding most quickly.
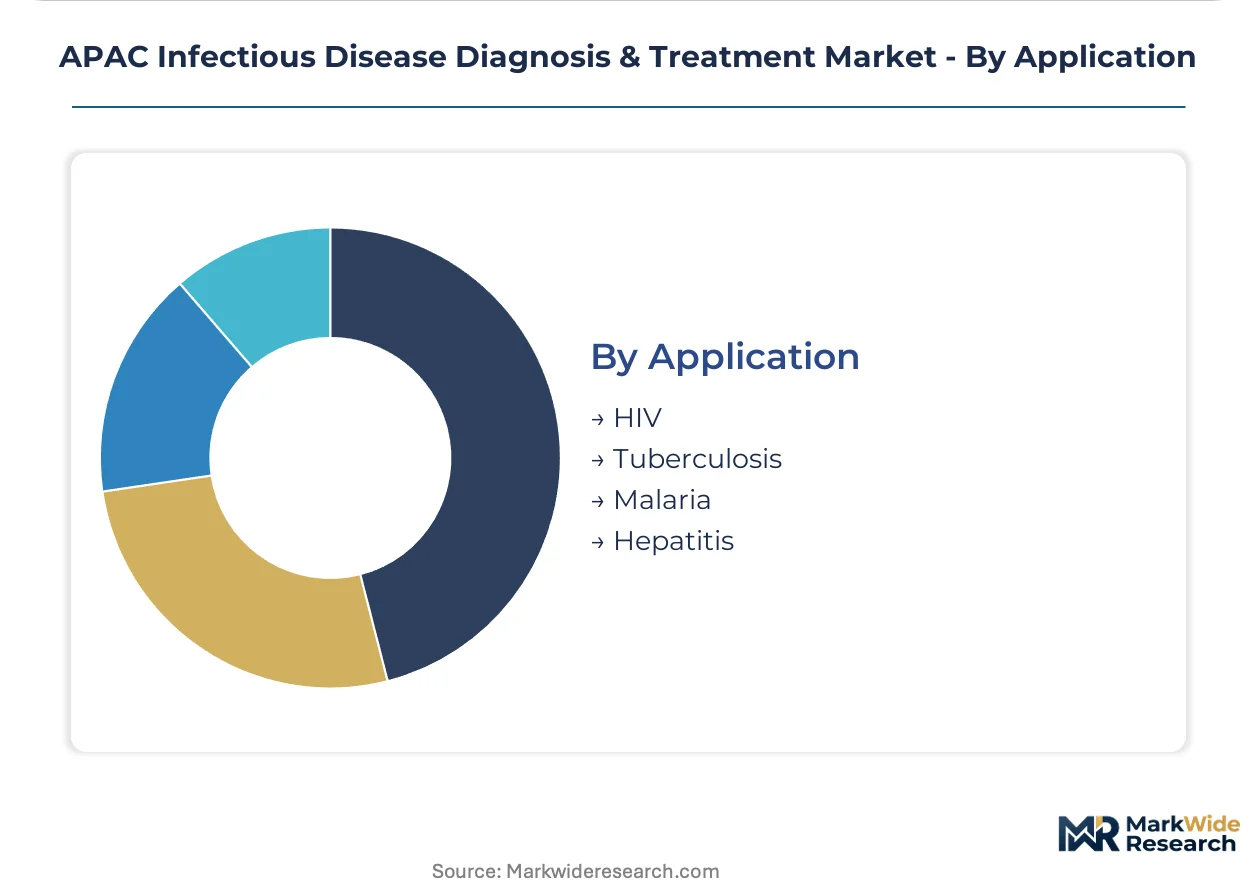
Application:
National essential medicine list revisions directly shape volume allocation across disease-specific procurement tenders.
- Tuberculosis:Long-course antimicrobial regimens and molecular resistance profiling. Community health centers in Thailand and Vietnam are piloting CRISPR-Cas12 systems for same-day confirmation, decomposing traditional hub-and-spoke sample transport delays.
- HIV:Antiretroviral therapy maintenance and viral load monitoring. Recurring pharmaceutical demand sustains volume dominance across long-course treatment segments.
- Malaria:Rapid diagnostic testing and artemisinin-based combination therapies.
- Hepatitis:Viral load quantification and antiviral intervention monitoring.
Tuberculosis handles the majority of throughput; hepatitis is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Singapore and Australia sits substantially above Vietnam and Indonesia, creating a two-tier procurement environment where premium molecular platforms dominate affluent city-states while cost-optimized point-of-care devices penetrate price-sensitive emerging markets.
India
Tier-2 and tier-3 cities in Karnataka and Tamil Nadu are closing diagnostic infrastructure gaps through public-private laboratory partnerships. CDSCO streamlined premarket validation pathways for endemic disease diagnostics are accelerating tuberculosis and dengue assay registrations. Maharashtra's state health mission is consolidating hospital procurement into centralized framework agreements, fragmenting vendor access for diagnostic platform suppliers.
China
Domestic manufacturers in the Yangtze River Delta are capturing molecular diagnostics share through NMPA accelerated review pathways for dengue fever and influenza priorities. The national regulator's compressed timelines are redirecting multinational R&D investment toward localized clinical trial infrastructure. Beijing-Tianjin-Hebei corridor hospitals are scaling automated platforms with laboratory information system integration requirements.
Vietnam
Community health centers in the central highlands are piloting CRISPR-Cas12 systems for same-day tuberculosis confirmation, decomposing traditional hub-and-spoke sample transport delays. The Ministry of Health is observing China's NMPA framework for potential regulatory adaptation. Ho Chi Minh City hospital networks are consolidating laboratory procurement under provincial health department oversight.
Australia
TGA alignment with EU-MDR standards is extending clinical validation timelines and elevating documentation burdens for novel assay developers. Sydney and Melbourne hospital networks maintain premium positioning for high-throughput diagnostic workflows. The regulatory transition is compressing margins for developers targeting the public hospital procurement channel.
Thailand
Bangkok metropolitan hospitals anchor demand for integrated molecular diagnostic platforms with multiplex pathogen detection capabilities. The Food and Drug Administration is tightening premarket requirements for imported diagnostic devices. Chiang Mai and Khon Kaen provincial health clusters are expanding point-of-care testing networks for malaria and respiratory pathogen screening.
APAC Infectious Disease Diagnosis & Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the APAC infectious disease landscape. The market structure fragments across multinational platform suppliers, domestic pharmaceutical manufacturers, and emerging diagnostic specialists. Three archetypes dominate: integrated diagnostics conglomerates with laboratory ecosystem control, generic pharmaceutical producers with API backward integration, and point-of-care technology specialists with field-deployable platforms. Competitive moves concentrate on regulatory pathway optimization and state-level procurement consolidation navigation.
Among the integrated diagnostics tier, Abbott Laboratories and F. Hoffmann-La Roche Ltd occupy positions representing workflow automation density and premium hospital network anchoring respectively. Danaher Corp exemplifies the platform ecosystem archetype competing on laboratory consolidation trends. These three entities represent the dominant competitive anchors shaping procurement dynamics across Southeast Asian hospital networks and Indian state health missions.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Danaher Corp |
| Bio-Rad Laboratories Inc |
| Merck & Co. |
| Pfizer Inc. |
| Thermo Fisher Scientific Inc |
| Aurobindo Pharma |
| Dr. Reddy's Laboratories |
| Others |
Pricing and Supply Chain Analysis
CDSCO and NMPA certification tiers gate both supplier qualification and price positioning simultaneously, with validated molecular platforms commanding 40-60% premiums over unregistered alternatives while reagent manufacturers face margin compression from polymerase supply concentration.
Pricing Analysis
Configured-to-order pricing for multiplex assay panels with custom pathogen menus spreads 25-35% above standard off-the-shelf configurations. Three-tier pricing structure across premium, standard, and economy levels separates CE-IVD certified platforms from research-use-only systems and unvalidated imports. Cost compression in the economy tier is intensifying because Indian state health missions are consolidating procurement into framework agreements with volume-based price ceilings. Public hospital laboratories exhibit highest price sensitivity; premium private hospital networks in Singapore and Australia demonstrate lowest sensitivity due to integrated platform ecosystem requirements.
Supply Chain Analysis
Port congestion on the Shanghai-Singapore trade lane and container availability constraints at Nhava Sheva are elevating inbound logistics costs for European-manufactured diagnostic instruments. Manufacturing concentration centers on China for PCR thermal cyclers and reagent plastics, India for API and vaccine bulk production, and Germany for high-precision optical detection modules. Raw material dependencies include fluorophore-labeled probes, recombinant polymerase enzymes, and medical-grade polypropylene consumables. Single-source vulnerability in CRISPR guide RNA synthesis creates supply chain risk. Distribution runs through authorized distributor networks with state-level tender navigation capabilities rather than direct hospital contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory information system interoperability standards are triggering a platform-economics inflection, with vendors controlling middleware integration capturing disproportionate margin pools across Southeast Asian hospital networks.
For Market Incumbents: Consolidate workflow automation density through captive LIS middleware development, defending against point-of-care specialists eroding molecular platform attach rates. Deepen backward integration into polymerase enzyme production to offset North American supplier concentration risk. Prioritize CDSCO streamlined pathway pre-validation investments ahead of Maharashtra and Gujarat state health mission consolidations.
For New Entrants and Emerging Players: Anchor in Vietnam's central highlands and comparable ASEAN rural catchments where portable CRISPR-based platforms bypass legacy hub-and-spoke infrastructure constraints. Target malaria and respiratory pathogen screening applications where same-day result delivery commands premium positioning against centralized laboratory alternatives. Pursue telemedicine-integrated sampling kit distribution partnerships to bypass traditional hospital laboratory gatekeepers.
For Investors and Strategic Acquirers: Australia's TGA EU-MDR alignment reshapes the acquisition landscape by extending clinical validation timelines and elevating capital barriers for novel assay developers. Position for 5-10 year viability windows favoring platform ecosystem controllers with installed base conversion leverage over point-product specialists. Target acquisition archetypes: domestic Indian manufacturers with CDSCO registration infrastructure and ASEAN distribution footprint. Monitor NMPA accelerated review pathway expansion into Indonesian and Vietnamese regulatory frameworks as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Streamlined Pathway Pre-Validation | Accelerates tuberculosis and dengue assay registrations ahead of state procurement consolidations in Karnataka and Tamil Nadu. |
| Laboratory Information System Middleware Development | Captures platform ecosystem control across Indonesian and Philippine hospital network heterogeneity. |
| CRISPR-Cas12 Field Deployment Pilot Programs | Decomposes traditional sample transport delays in Thailand and Vietnam community health centers. |
| Domestic Polymerase Enzyme Backward Integration | Reduces import dependency exposure from concentrated North American and European supplier bases. |
| Telemedicine-Integrated Sampling Kit Distribution | Creates direct-to-patient channels bypassing centralized hospital laboratory procurement gatekeepers. |
Research Methodology
The analysis maps molecular diagnostics platforms, vaccine manufacturing, and antimicrobial therapeutics segments, each validated through hospital laboratory directors, state health mission procurement officers, CDSCO regulatory consultants, and infectious disease specialists. Primary interviews with biomedical engineers and GPO contracts managers combined with secondary validation from CDSCO registration databases, NMPA accelerated review pathway disclosures, and Indian state health mission tender documents. Bottom-up platform shipment data and top-down pharmaceutical expenditure estimates undergo triangulation consistency checks.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user concentration, technology workflow automation density, and disease application priority aligned with national essential medicine list revisions. CAGRs derive from instrument placement trajectories, reagent pull-through coefficients, and therapy course completion rates. Forecast inputs incorporate PLI scheme capital allocation patterns and NMPA review timeline compression effects.
Decision-makers should treat outputs as directional under assumptions of sustained CDSCO-NMPA regulatory convergence and stable polymerase supply availability; material deviation would warrant model refresh. Pandemic-related procurement distortions, abrupt essential medicine list revisions, or trade lane disruptions represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Retropharyngeal Abscess Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Infectious Enteritis Treatment Market
Infectious Disease
Direct-Acting Antiviral Medicines Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Meningococcal Disease Treatment Market