
 Chronic Hepatitis B (CHB) Market | 2026-2036
Chronic Hepatitis B (CHB) Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Hepatitis B (CHB) Market Analysis
Hepatology specialist availability is bifurcating market access between major metropolitan corridors and underserved rural zones. Gilead Sciences dominates nucleos(t)ide analogue supply through backward integration into active pharmaceutical ingredient production. Bristol-Myers Squibb differentiates via immunomodulator R&D intensity, while GlaxoSmithKline leverages its infectious disease franchise to anchor hospital formulary presence.
Chronic Hepatitis B constitutes a persistent liver infection caused by the hepatitis B virus, characterized by detectable hepatitis B surface antigen for longer than six months and measurable viral load above diagnostic thresholds; its primary clinical purpose centers on preventing cirrhosis, hepatocellular carcinoma, and end-stage liver failure through sustained viral suppression. Nucleos(t)ide analogues occupy the mature revenue core due to entrenched tenofovir and entecavir prescribing habits, while immunomodulators represent the fastest-growing category as investigators pursue functional cure endpoints. Oral delivery mode commands the volume lead, though subcutaneous interferon formulations retain niche positioning in select genotype populations.
FDA breakthrough therapy designation and EMA PRIME eligibility are reshaping trial design expectations and payer pre-approval access frameworks across major markets. WHO prequalification standards govern procurement eligibility for developing-country national hepatitis programs, compressing manufacturing quality thresholds. Stakeholders must monitor functional cure readouts from siRNA and capsid inhibitor combinations to recalibrate portfolio priorities before patent cliffs erode incumbent analogue franchises.
Market Dynamics
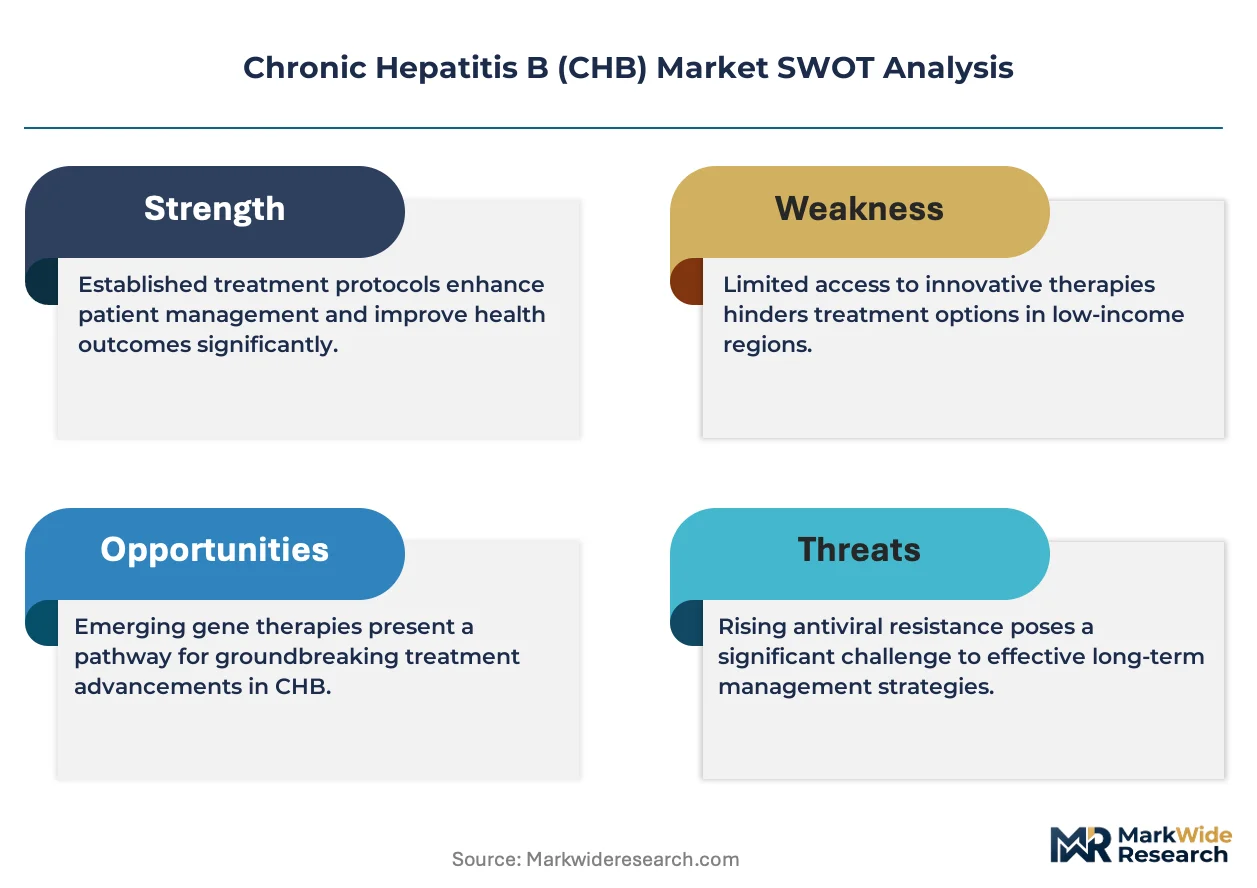
Functional cure endpoints are compressing nucleos(t)ide analogue prescribing windows as siRNA and capsid inhibitor combinations advance through Phase IIb trials, forcing incumbent manufacturers to accelerate pipeline diversification before patent expirations erode entrenched revenue streams.
Growth Catalysts
- US screening mandates:CDC and USPSTF universal adult hepatitis B screening recommendations expand addressable patient pools through earlier diagnosis capture.
- WHO prequalification standards:Procurement eligibility for developing-country national hepatitis programs compresses manufacturing quality thresholds and opens volume channels.
- Immunomodulator R&D intensity:Bristol-Myers Squibb and peer investment in checkpoint inhibitors and therapeutic vaccines accelerates functional cure timelines.
Market Restraints
- API supply concentration:Backward integration into tenofovir and entecavir active pharmaceutical ingredient production limits supplier diversity to Indian and Chinese manufacturers.
- Interferon tolerability ceiling:Subcutaneous pegylated interferon alpha retains niche positioning only in select genotype populations due to neuropsychiatric side effect profiles.
- Reimbursement compression:Medicare Part D and Medicaid formulary placement negotiations constrain pricing power for oral antiviral maintenance therapy.
Strategic Opportunities
- Rural hepatology deserts:Telemedicine-enabled specialist consultation models unlock diagnosis and treatment initiation in underserved US counties lacking board-certified hepatologists.
- Combination regimen white space:siRNA plus capsid inhibitor plus nucleos(t)ide analogue triplets represent unclaimed functional cure territory ahead of registrational trials.
- Hospital formulary anchoring:Infectious disease franchise breadth enables GlaxoSmithKline-style portfolio bundling to secure preferred antiviral positioning.
Industry Challenges
- Hepatology workforce scarcity:Fellowship program graduation rates lag patient prevalence growth, creating diagnosis-to-treatment interval bottlenecks.
- Biomarker validation timelines:HBsAg quantification and HBV RNA assays require harmonization across FDA, EMA, and PMDA diagnostic approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Hepatitis B (CHB) Market |
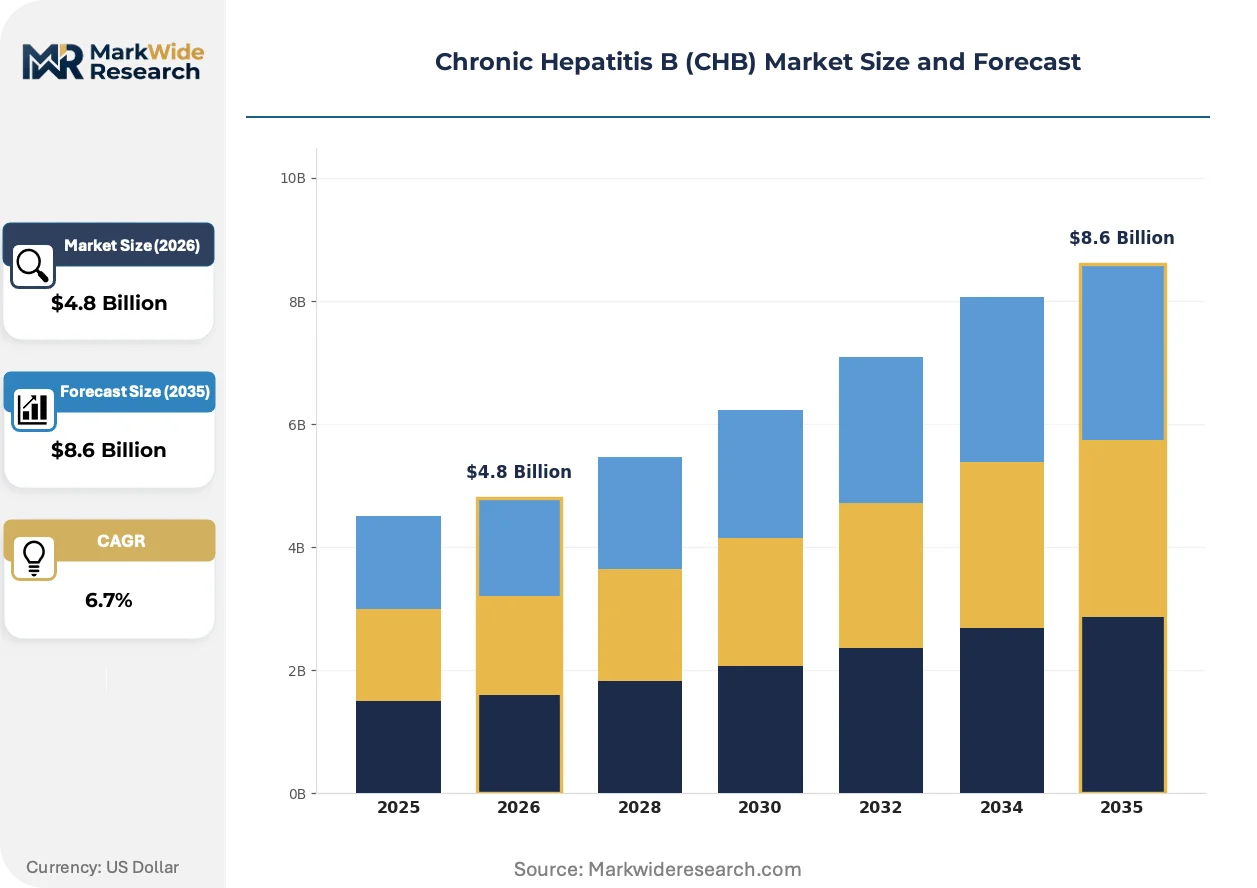
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Drugs, Interferons, Nucleos(t)ide Analogues, Immunomodulators End User: Hospitals, Clinics, Diagnostic Labs, Specialty Treatment Centers Therapy Area: Hepatology, Infectious Diseases, Gastroenterology, Pharmacology Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous |
| Companies Covered | Gilead Sciences, GlaxoSmithKline, Bristol-Myers Squibb, Novartis AG, Merck & Co., F. Hoffmann-La Roche, Johnson & Johnson, Arbutus Biopharma, Cipla Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Hepatitis B (CHB) Market Emerging Trajectories
RNA interference platforms and capsid assembly modulators are converging to redefine therapeutic endpoints, shifting market value from lifelong viral suppression toward finite-duration functional cure regimens.
Small interfering RNA constructs targeting conserved HBV transcripts are displacing maintenance nucleos(t)ide analogue monotherapy in investigator-sponsored trials. Academic medical centers in the United States and Western Europe are enrolling patients into combination cohorts at accelerating velocity. This displacement compresses the addressable lifetime value per patient while expanding eligible treatment initiations.
EMA PRIME eligibility and FDA breakthrough therapy designation are reshaping trial design expectations across major markets. Accelerated approval pathways compress Phase III duration and enable payer pre-approval access frameworks. Immunomodulator developers are restructuring protocols to capture functional cure endpoints earlier.
Specialty pharmacy distribution is consolidating patient access channels as oral antiviral volume concentrates through limited networks. Payers are directing tenofovir and entecavir dispensing toward PBM-affiliated mail-order platforms. This channel compression is most visible in US commercial insurance and Medicare Advantage formularies.
Chronic Hepatitis B (CHB) Market Segmentation
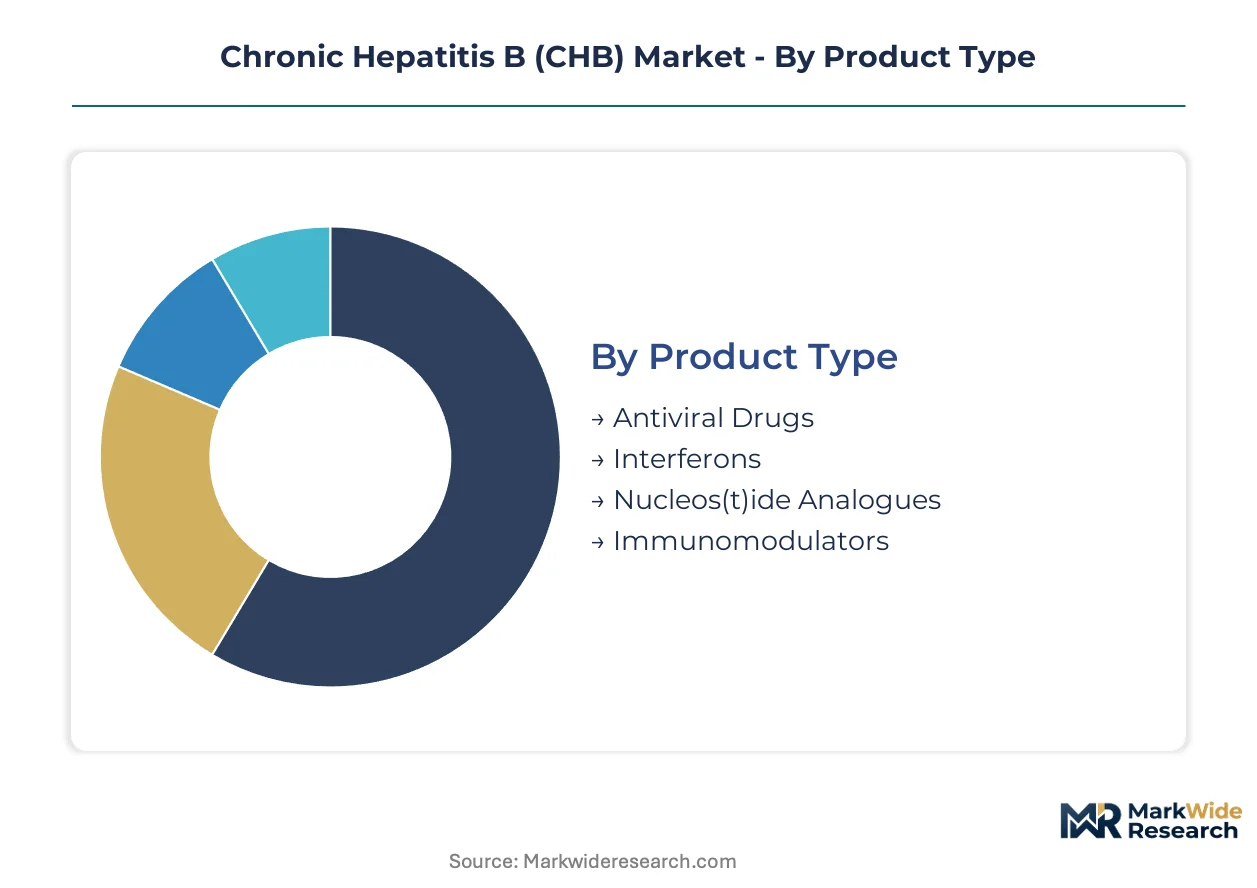
CHB market segmentation reveals how treatment protocols fragment across clinical settings and therapeutic mechanisms. Regulators in the United States, Europe, and Asia-Pacific impose distinct approval standards that reshape competitive positioning within each category.
Product Type:
FDA breakthrough therapy designation and EMA PRIME eligibility create divergent commercialization timelines across therapeutic classes.
- Nucleos(t)ide Analogues:Entecavir and tenofovir formulations constitute the established maintenance backbone, with prescribing habits entrenched through decades of safety data. Demand concentrates in United States Medicare Part D formularies where reimbursement stability sustains high-volume dispensing despite patent erosion pressures.
- Immunomodulators:Checkpoint inhibitors and therapeutic vaccines target functional cure endpoints through immune system restoration. Clinical trial enrollment is accelerating fastest in Western European academic medical centers pursuing finite-duration regimens.
- Antiviral Drugs:Direct-acting agents outside the nucleos(t)ide class occupy pipeline positions ahead of registrational trials.
- Interferons:Pegylated alpha formulations retain restricted utility in select genotype populations.
Nucleos(t)ide analogues handle the majority of throughput; immunomodulators are expanding most quickly on share.
End User:
Patient acuity and reimbursement complexity determine site-of-care economics across the treatment continuum.
- Hospitals:Tertiary centers manage decompensated cirrhosis and hepatocellular carcinoma complications requiring multidisciplinary coordination. United States academic medical centers anchor clinical trial recruitment for novel combination regimens.
- Specialty Treatment Centers:Dedicated hepatology clinics optimize viral load monitoring and HBsAg quantification workflows. Capacity is climbing the fastest in United States metropolitan corridors where screening mandates expand eligible patient pools.
- Clinics:Community-based settings initiate maintenance therapy for stable patients.
- Diagnostic Labs:Reference laboratories process confirmatory serology and molecular testing.
Hospitals absorb the highest-complexity cases; specialty treatment centers are gaining share fastest through focused service line development.
Therapy Area:
Specialist training pathways and fellowship program outputs constrain workforce availability within each discipline.
- Hepatology:Board-certified specialists direct treatment decisions for advanced fibrosis and cirrhosis patients. Workforce scarcity in United States rural counties creates diagnosis-to-treatment interval bottlenecks that telemedicine models attempt to address.
- Infectious Diseases:Broad antimicrobial expertise positions these specialists for HBV-HIV coinfection management. Hospital formulary influence is steepest in this segment through portfolio bundling strategies.
- Gastroenterology:Generalists handle initial screening and referral coordination.
- Pharmacology:Clinical pharmacists optimize nucleos(t)ide analogue adherence and drug interaction surveillance.
Hepatology directs the most complex therapeutic decisions; infectious diseases is climbing fastest through hospital anchoring.
Delivery Mode:
Route of administration shapes patient adherence profiles and pharmacy distribution economics.
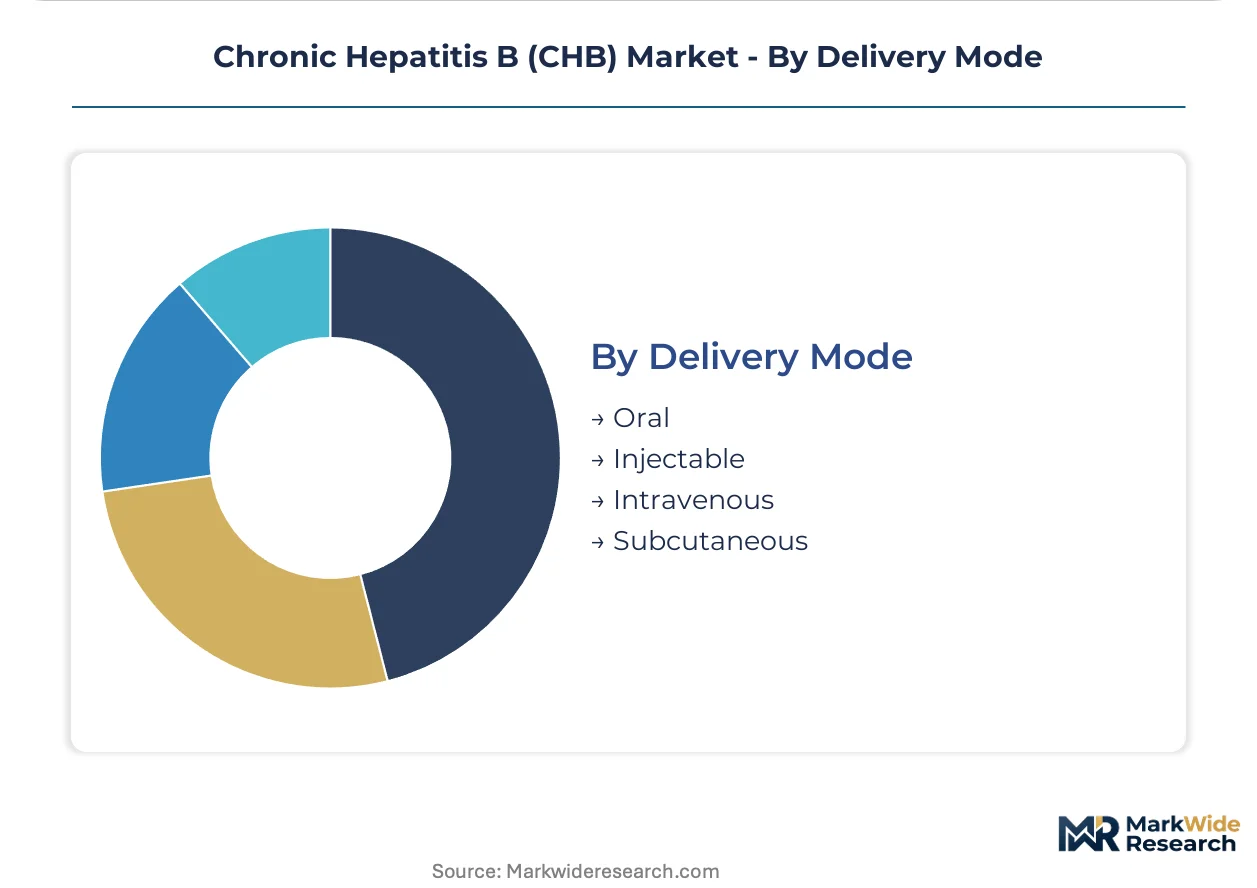
- Oral:Once-daily tenofovir and entecavir tablets dominate maintenance therapy through convenience and tolerability advantages. United States specialty pharmacy channels concentrate volume through PBM-affiliated mail-order platforms.
- Subcutaneous:Pegylated interferon alpha requires weekly self-injection with neuropsychiatric monitoring obligations. Niche positioning persists in select genotype populations where finite treatment duration offsets tolerability burdens.
- Injectable:Intramuscular formulations occupy limited clinical roles.
- Intravenous:Hospital-administered routes apply to investigational agents and acute complications.
Oral delivery handles the majority of patient-years; subcutaneous routes are contracting on share as alternatives advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designation anchors United States market acceleration, while EMA PRIME eligibility and WHO prequalification standards reshape access frameworks across European and developing-country markets respectively.
United States
CDC universal adult screening mandates and Medicare Part D reimbursement stability sustain high diagnosis-to-treatment conversion rates. FDA accelerated approval pathways compress Phase III timelines for siRNA and capsid inhibitor combinations. Boston and San Francisco academic medical centers anchor clinical trial recruitment for functional cure regimens.
Germany
EMA PRIME eligibility streamlines market access for immunomodulator developers pursuing finite-duration endpoints. REACH compliance requirements govern active pharmaceutical ingredient import standards for tenofovir and entecavir formulations. Frankfurt and Munich hepatology centers concentrate specialist workforce capacity for advanced fibrosis management.
China
NMPA priority review pathways expedite domestic biosimilar approvals for nucleos(t)ide analogues. National hepatitis elimination program procurement compresses pricing for entecavir through volume-based tendering. Shanghai and Beijing hospital systems pilot combination therapy protocols ahead of registrational trials.
Japan
PMDA sakigake designation accelerates regulatory review for novel antiviral mechanisms targeting functional cure endpoints. METI industrial policy supports domestic pharmaceutical manufacturing quality upgrades for WHO prequalification eligibility. Osaka and Nagoya specialty treatment centers optimize HBsAg quantification workflows for treatment monitoring.
India
CDSCO streamlined approval pathways expand access to generic tenofovir formulations for national hepatitis control programs. PLI scheme incentives strengthen domestic active pharmaceutical ingredient production for export markets. Hyderabad and Mumbai manufacturing clusters supply prequalified antivirals to developing-country procurement systems.
Chronic Hepatitis B (CHB) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Chronic Hepatitis B therapeutic space. Gilead Sciences dominates nucleos(t)ide analogue supply through backward integration into active pharmaceutical ingredient production, while Bristol-Myers Squibb and GlaxoSmithKline anchor immunomodulator and infectious disease portfolio positions respectively. Three archetypes define competitive positioning: integrated incumbents with manufacturing control, immunomodulator specialists pursuing functional cure endpoints, and emerging biotechs advancing siRNA and capsid inhibitor platforms. Dominant competitive moves include pipeline diversification ahead of patent cliffs and hospital formulary bundling to secure preferred antiviral positioning.
Among United States-based integrated pharmaceutical developers, Gilead Sciences, Bristol-Myers Squibb, and Johnson & Johnson occupy positions spanning nucleos(t)ide analogue maintenance therapy through immunomodulator innovation. Gilead Sciences exemplifies the manufacturing-integrated archetype through supply chain control over tenofovir active pharmaceutical ingredients. Bristol-Myers Squibb represents immunomodulator R&D intensity through checkpoint inhibitor and therapeutic vaccine investment. Johnson & Johnson sits within the diversified healthcare conglomerate tier, leveraging infectious disease franchise breadth for hospital formulary anchoring. These three entities collectively illustrate how incumbent manufacturers defend positioning against pipeline displacement from siRNA and capsid inhibitor combinations.
| Leading Market Players |
|---|
| Gilead Sciences |
| GlaxoSmithKline |
| Bristol-Myers Squibb |
| Novartis AG |
| Merck & Co. |
| F. Hoffmann-La Roche |
| Johnson & Johnson |
| Arbutus Biopharma |
| Cipla Limited |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient batch scale economics in tenofovir and entecavir production entrench cost advantages for manufacturers with captive fermentation capacity, compressing price floors for generic entrants while sustaining margin buffers for integrated incumbents across United States Medicare Part D and developing-country procurement channels.
Pricing Analysis
United States list prices for branded nucleos(t)ide analogues command 15-40x multiples over Indian generic tenders, with price differentiation anchored in FDA bioequivalence certification tiers and originator brand legacy positioning. Three-tier pricing structure across premium originator, authorized generic, and economy prequalified tiers stratifies patient access by payer archetype. Pricing pressure stems from national hepatitis program volume-based tendering in China and India, where procurement aggregation compresses per-unit yields. Medicaid formulary directors exhibit highest price sensitivity due to budget cap constraints, while United States commercial insurers retain modest tolerance for originator premiums when prior authorization burdens shift to specialty pharmacies.
Supply Chain Analysis
India and China anchor tenofovir disoproxil fumarate active pharmaceutical ingredient production, with Hyderabad and Shanghai manufacturing clusters feeding formulation facilities across Southeast Asia and Africa. Raw material dependencies center on acetonitrile solvents, specialized fermentation media, and high-purity nucleoside intermediates sourced from dedicated chemical suppliers. Single-source vulnerability concentrates in backward-integrated incumbents controlling entecavir synthetic route patents, exposing procurement officers to supply interruption during regulatory inspection cycles. Distribution runs through PBM-affiliated specialty pharmacy networks in the United States and WHO-prequalified pooled procurement mechanisms in low-income country markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional cure endpoint convergence across siRNA, capsid inhibitor, and immunomodulator platforms is reshaping Chronic Hepatitis B from chronic maintenance toward finite-duration therapy economics, with interoperability demands across biomarker assay workflows and combination protocol standardization creating ecosystem orchestration opportunities.
For Market Incumbents: Consolidate manufacturing control over nucleos(t)ide analogue active pharmaceutical ingredients through capacity expansion in Indian chemical clusters, while accelerating pipeline diversification into siRNA and capsid inhibitor combinations ahead of patent cliff erosion. Lock in hospital formulary anchoring through infectious disease portfolio bundling that secures preferred antiviral positioning against emerging biotech displacement. For New Entrants and Emerging Players: Rural hepatology deserts in United States underserved counties present service-layer white space where telemedicine-enabled specialist consultation models unlock diagnosis and treatment initiation ahead of incumbent field force deployment. Target combination regimen development partnerships with academic medical centers in Boston and San Francisco, leveraging investigator-sponsored trial infrastructure to generate functional cure data ahead of registrational investment. For Investors and Strategic Acquirers: siRNA platform specialists with conserved transcript targeting intellectual property and Phase IIb combination data packages represent priority acquisition archetypes for portfolio supplementation ahead of incumbent R&D catch-up. Long-term viability over the next decade hinges on functional cure biomarker validation harmonization across FDA, EMA, and PMDA pathways, with HBsAg quantification assay standardization serving as the critical inflection signal for combination therapy reimbursement traction.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase IIb combination cohorts for siRNA plus capsid inhibitor regimens accelerate functional cure endpoint validation ahead of registrational design. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines and enables payer pre-approval access frameworks for novel mechanisms. |
| Backward Integration | Captive active pharmaceutical ingredient production for tenofovir and entecavir insulates margin structures against generic pricing erosion. |
| Pipeline Diversification | Immunomodulator investment in checkpoint inhibitors and therapeutic vaccines hedges nucleos(t)ide analogue revenue concentration risk. |
| Hospital System Partnership | Infectious disease franchise bundling secures preferred antiviral formulary positioning through GlaxoSmithKline-style portfolio anchoring strategies. |
Methodological Framework
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists and refined through secondary validation across FDA filings, ClinicalTrials.gov, EMA submissions, and hospital procurement databases. Bottom-up patient flow modeling and top-down epidemiological prevalence estimates were triangulated to constrain addressable market boundaries across the analysis window.
Variance decomposition across therapeutic class, delivery mode, end-user site of care, and regional regulatory cluster segmentation dimensions informed value and volume allocation. CAGRs were derived from treatment initiation rate projections, patent expiration erosion curves, and functional cure adoption scenario weighting, with inputs calibrated to WHO prequalification pipeline status and national hepatitis program procurement timelines.
Underlying assumptions cover sustained nucleos(t)ide analogue prescribing persistence, immunomodulator tolerability profiles, and biomarker assay harmonization progress, with deviation risk concentrated in functional cure clinical readout timing and hepatology workforce expansion trajectories. Recalibration cycles align with material shifts in FDA accelerated approval precedent, WHO prequalification standards, and combination therapy registrational outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Valley Fever Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Japanese Encephalitis Market