
 Acute Vulvovaginal Candidiasis Treatment Market | 2026-2036
Acute Vulvovaginal Candidiasis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Vulvovaginal Candidiasis Treatment Market Analysis
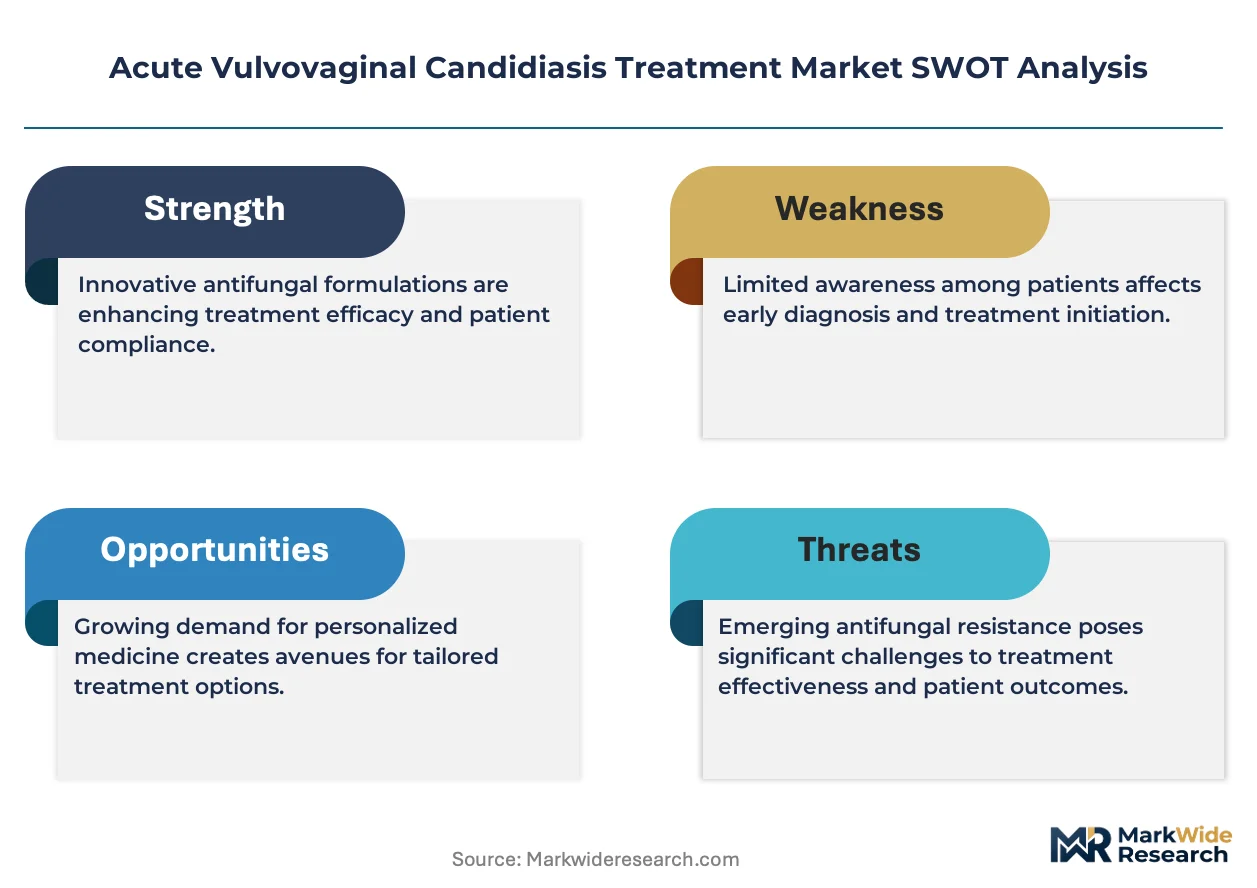
EMA antifungal resistance monitoring frameworks is rebalancing the cost-of-entry calculus for developers seeking European market access. Pfizer leverages its manufacturing scale to sustain broad distribution across retail pharmacy networks. Mycovia Pharmaceuticals differentiates through specialized R&D intensity in novel azole formulations. Bayer AG anchors its position via brand strength in over-the-counter topical segments.
Acute vulvovaginal candidiasis treatment encompasses pharmaceutical and non-pharmaceutical interventions targeting Candida albicans and non-albicans species, with topical azoles typically containing clotrimazole or miconazole at concentrations ranging from one to ten percent, and oral fluconazole administered as single-dose 150 mg regimens, designed to restore vaginal microbiome balance and eliminate fungal colonization. Prescription medication segments dominate value capture due to payer reimbursement structures, while oral antifungals represent the fastest-expanding product category driven by patient convenience preferences and extended-release formulation advances. Combination therapies concentrate margin pools where recurrent infection protocols justify premium pricing against standard monotherapy benchmarks.
FDA antifungal susceptibility testing requirements and EMA pharmacovigilance guidelines for reproductive-age women jointly reshape clinical endpoint standards and post-market surveillance obligations for new entrants. The WHO Essential Medicines List inclusion criteria for antifungal agents further influence national procurement decisions and access programs across multiple jurisdictions. Stakeholders must monitor resistance surveillance data and regulatory divergence between major health authorities to align portfolio investments with evolving evidentiary thresholds.
Market Dynamics
FDA antifungal susceptibility testing mandates and EMA pharmacovigilance frameworks are restructuring clinical trial designs and post-market surveillance obligations for acute vulvovaginal candidiasis treatment developers, elevating evidentiary thresholds and compliance costs simultaneously.
Growth Catalysts
- Self-administered home care protocols:Patient preference for convenient, privacy-preserving treatment options is expanding addressable demand beyond traditional clinic-dependent models.
- FDA evolving resistance surveillance guidance:Regulatory clarity on antifungal resistance monitoring is accelerating product development prioritization and streamlining approval pathways for novel formulations.
- Extended-release oral antifungal advances:Pharmaceutical formulation innovations are improving dosing convenience and adherence profiles, particularly benefiting recurrent infection management.
Market Restraints
- Azole resistance accumulation:Candida glabrata and non-albicans species exhibiting reduced fluconazole susceptibility are narrowing effective therapeutic options and complicating empirical treatment decisions.
- Reimbursement fragmentation:Payer variability across United States, Germany, and Japan is creating access inequities and limiting market penetration for premium-priced combination therapies.
- Generic oral fluconazole commoditization:Patent expiration and manufacturing scale concentration in India and China are compressing margins for standard-of-care monotherapy segments.
Strategic Opportunities
- Recurrent infection protocol specialization:Maintenance regimens and prophylactic positioning for high-burden patients justify premium pricing against episodic treatment benchmarks.
- Direct-to-consumer pharmacy channels:United States retail network expansion and telehealth integration are enabling bypass of traditional prescription gatekeeping for appropriate candidates.
- WHO Essential Medicines List alignment:Inclusion criteria navigation for antifungal agents is opening national procurement pathways and donor-funded access programs in low-resource settings.
Industry Challenges
- Microbiome characterization expertise scarcity:Vaginal fungal-bacterial interaction modeling and host-pathogen dynamics specialization remains concentrated in academic centers, constraining rational drug design pipelines.
- Resistance surveillance infrastructure gaps:Real-time antifungal susceptibility data collection and reporting systems are underdeveloped across outpatient settings, delaying resistance pattern detection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Vulvovaginal Candidiasis Treatment Market |
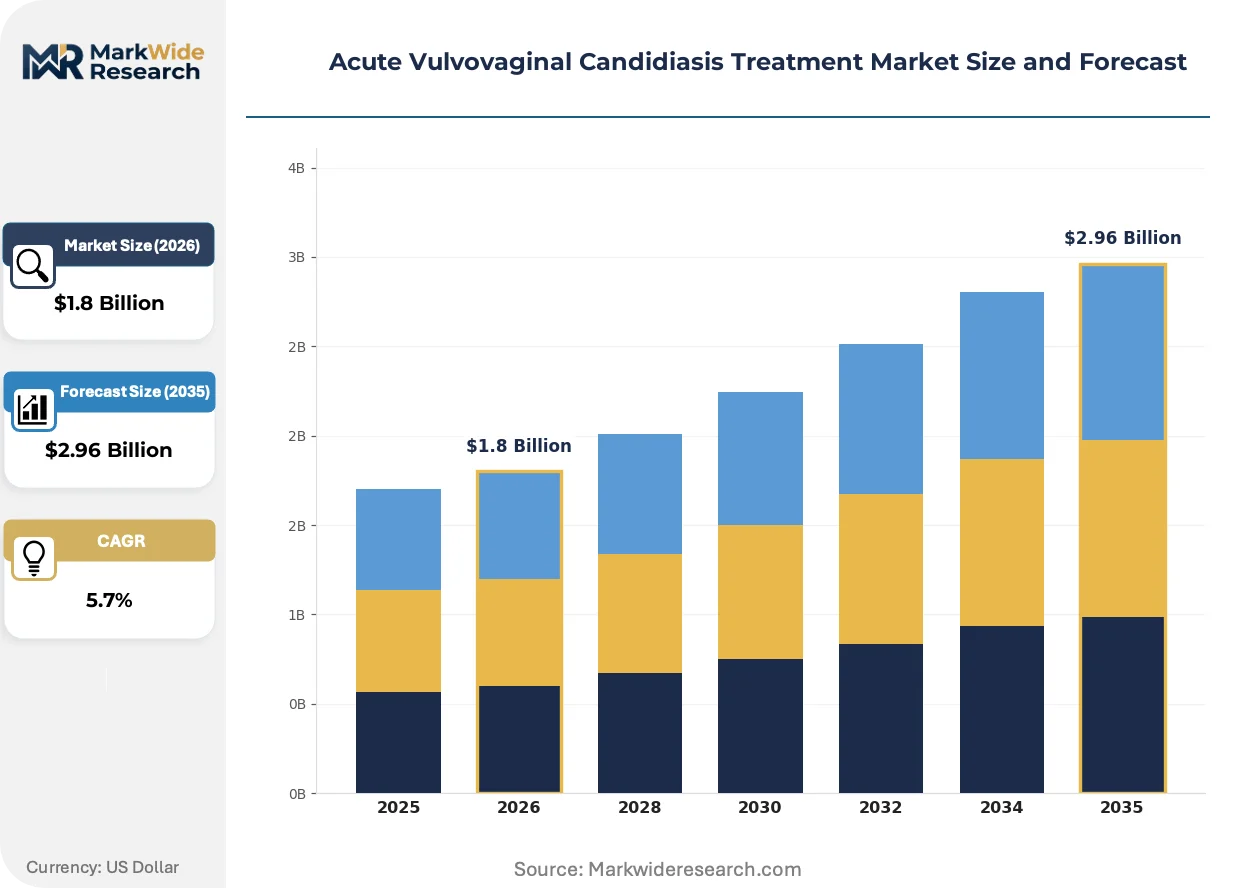
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Antifungals, Oral Antifungals, Combination Therapies, Probiotics Treatment Method: Prescription Medication, Over-the-Counter, Home Remedies, Alternative Therapies End User: Hospitals, Clinics, Home Care, Pharmacies Patient Demographics: Women of Reproductive Age, Pregnant Women, Postmenopausal Women, Immunocompromised Patients |
| Companies Covered | Astellas Pharma Inc., Mycovia Pharmaceuticals, Inc., Basilea Pharmaceutica Ltd., Scynexis, Inc., Pfizer, Inc., Bayer AG, Grupo Ferrer Internacional S.A., Bristol-Myers Squibb Company, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Vulvovaginal Candidiasis Treatment Market Emerging Trajectories
Extended-release formulation technologies and resistance-aware prescribing protocols are actively restructuring product development priorities and clinical practice patterns across acute vulvovaginal candidiasis treatment markets.
Novel azole derivatives with modified pharmacokinetic profiles are expanding into recurrent infection maintenance protocols, where infectious disease specialists in United States academic medical centers are adopting these agents for fluconazole-refractory cases, and this expansion is compressing the addressable market for repeated single-dose oral therapy by enabling longer inter-episode intervals.
REACH authorization requirements for reproductive-toxicity data and EMA pharmacovigilance guidelines for antifungal exposure in pregnancy are extending preclinical evaluation timelines and post-market commitment obligations, and these regulatory burdens are disproportionately affecting smaller developers targeting novel mechanisms, prompting portfolio prioritization toward topical formulations with more favorable safety profiles.
Telehealth-integrated prescription fulfillment is displacing traditional clinic-visit dependencies for initial diagnosis and treatment initiation, with United States direct-to-consumer platforms capturing growing share of uncomplicated case management, and this channel rotation is most visible in metropolitan markets where pharmacy network density supports same-day medication access without facility-based encounters.
Acute Vulvovaginal Candidiasis Treatment Market Segmentation
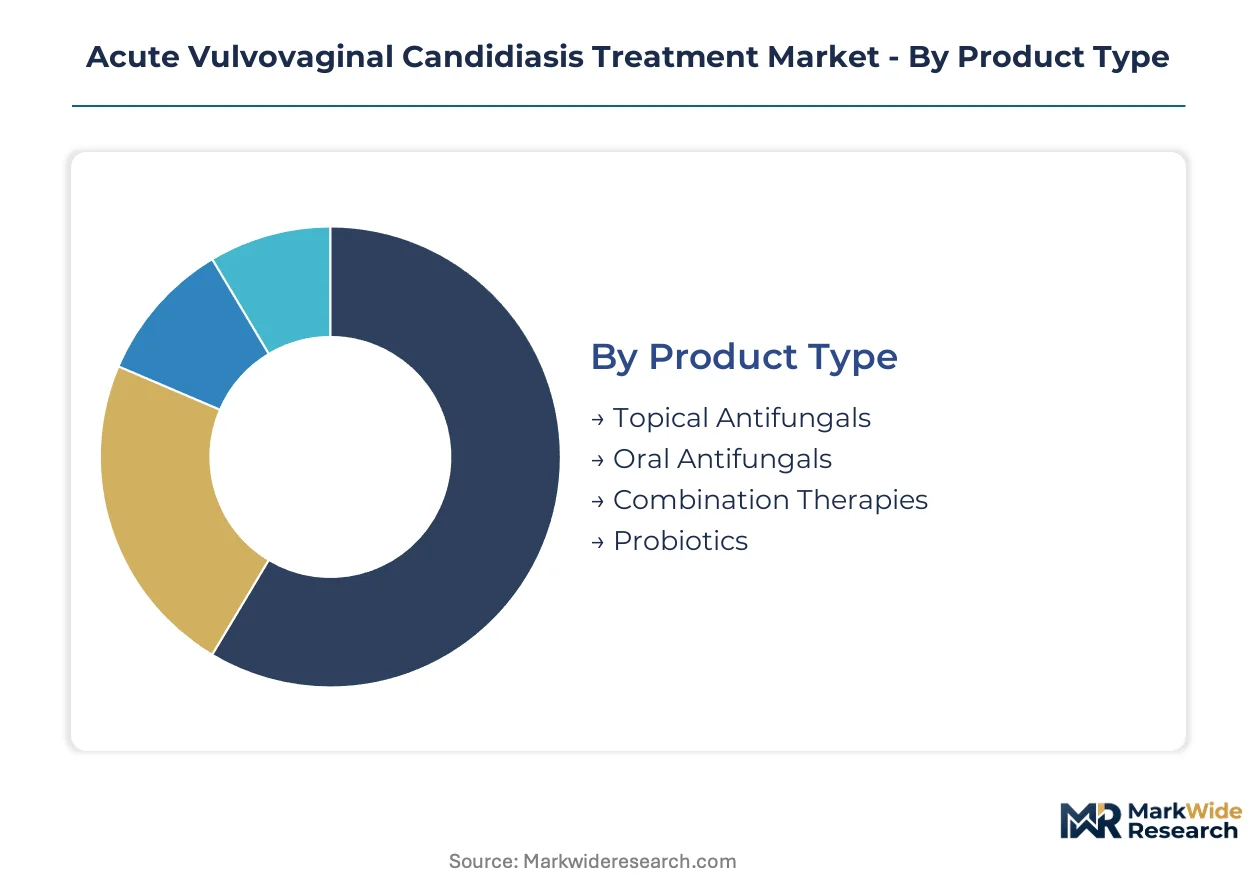
Product positioning in acute vulvovaginal candidiasis treatment hinges on balancing clinical efficacy against convenience economics. Prescription pathways capture premium value through reimbursement leverage, while self-directed channels expand volume through reduced friction.
Product Type:
Volume concentrates in established azole formulations, while premium pools concentrate where resistance profiles demand novel mechanisms.
- Topical Antifungals:Clotrimazole and miconazole formulations at one to ten percent concentrations deliver localized fungal elimination with minimal systemic exposure. Demand clusters in United States retail pharmacy networks where privacy-preserving self-selection drives repeat purchase frequency.
- Oral Antifungals:Single-dose fluconazole 150 mg regimens and extended-release innovations address adherence gaps in recurrent infection protocols. United States infectious disease specialists in academic medical centers are expanding maintenance prescribing for refractory cases, compressing inter-episode intervals.
- Combination Therapies:Dual-mechanism protocols targeting azole-resistant Candida glabrata justify premium positioning against monotherapy benchmarks through reduced treatment failure rates.
- Probiotics:Lactobacillus-based microbiome restoration products occupy adjunctive positioning with limited standalone reimbursement coverage.
Today's leader: Topical Antifungals. Tomorrow's challenger: Oral Antifungals.
Treatment Method:
Access modality determines margin structure through gatekeeper density and regulatory surveillance intensity.
- Prescription Medication:FDA antifungal susceptibility testing mandates and EMA pharmacovigilance frameworks elevate evidentiary thresholds for novel entrants, concentrating value capture among established manufacturers with surveillance infrastructure.
- Over-the-Counter:United States direct-to-consumer pharmacy channels bypass traditional clinic dependencies, with telehealth-integrated fulfillment capturing metropolitan markets where same-day access displaces facility-based encounters.
- Home Remedies:Boric acid and yogurt-based interventions persist in uninsured and underinsured populations despite limited clinical validation.
- Alternative Therapies:Essential oil and herbal protocols occupy wellness-adjacent positioning with minimal regulatory oversight.
Prescription Medication anchors value pools. Over-the-Counter is gaining share fastest through channel rotation.
End User:
Site-of-care migration from institutional to ambulatory settings reconfigures distribution economics and patient acquisition costs.
- Hospitals:Severe or complicated cases requiring intravenous antifungal administration concentrate in academic medical centers with infectious disease consultation capacity.
- Clinics:Outpatient gynecology and primary care settings manage uncomplicated episodes with empirical azole prescribing.
- Home Care:Self-administered protocols are expanding addressable demand beyond clinic-dependent models through privacy preservation and convenience optimization.
- Pharmacies:United States retail network density supports same-day medication access without prescription gatekeeping for appropriate candidates.
Home Care represents the steepest expansion trajectory. Pharmacies defend margin through channel integration.
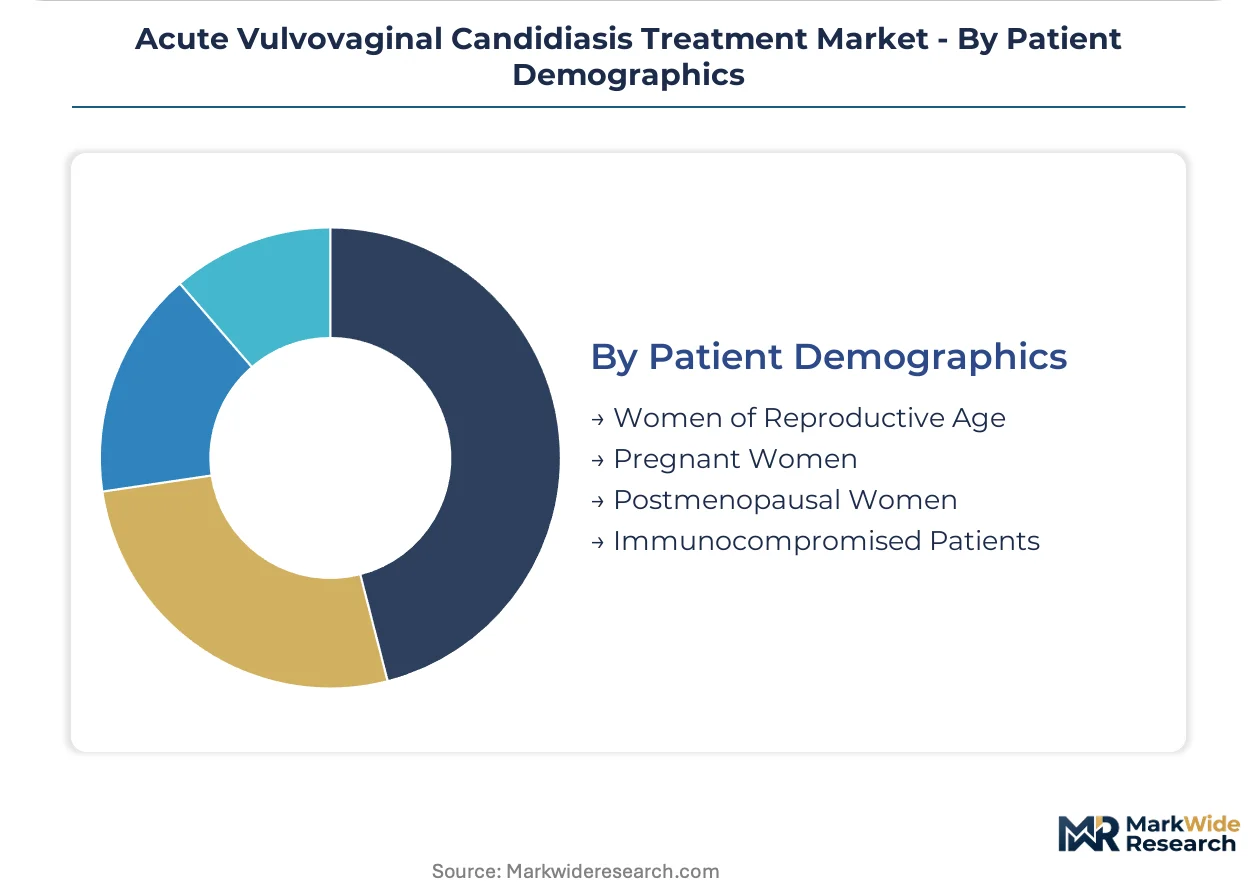
Patient Demographics:
Disease burden intensity and treatment complexity vary sharply across hormonal and immunological status.
- Women of Reproductive Age:Peak incidence concentrates in this cohort, with recurrent infection protocols justifying premium maintenance regimens against episodic benchmarks.
- Pregnant Women:REACH authorization requirements for reproductive-toxicity data and EMA pharmacovigilance guidelines extend preclinical timelines, favoring topical formulations with favorable safety profiles.
- Postmenopausal Women:Atrophic vaginitis comorbidity and estrogen deficiency alter microbiome dynamics, requiring differentiated therapeutic approaches.
- Immunocompromised Patients:HIV and chemotherapy-associated immunosuppression elevate non-albicans species prevalence, narrowing effective empirical options.
Women of Reproductive Age dominates volume. Immunocompromised Patients commands premium through protocol complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized infectious disease specialists and gynecological researchers concentrate in academic medical centers across key jurisdictions, anchoring clinical trial infrastructure and resistance surveillance networks that shape regional market access patterns.
United States
Direct-to-consumer pharmacy channels and telehealth-integrated prescription fulfillment drive volume expansion in metropolitan markets with same-day medication access. FDA antifungal susceptibility testing mandates elevate evidentiary thresholds for novel entrants. Boston and San Francisco academic medical centers lead maintenance regimen adoption for fluconazole-refractory cases.
Germany
EMA pharmacovigilance frameworks and REACH authorization requirements for reproductive-toxicity data extend preclinical evaluation timelines for developers. Statutory health insurance reimbursement structures favor established azole formulations over premium-priced combination therapies. Frankfurt and Munich host concentration of infectious disease specialists influencing empirical prescribing protocols.
Japan
PMDA guidelines for antifungal exposure in pregnancy favor topical formulations with favorable safety profiles in this regulatory environment. Aging demographics elevate postmenopausal patient segments requiring differentiated therapeutic approaches. Tokyo and Osaka medical centers concentrate expertise in non-albicans species management.
United Kingdom
NHS procurement frameworks and NICE technology appraisals shape access decisions for novel antifungal agents. Self-administered home care protocols expand addressable demand beyond traditional clinic-dependent models. London teaching hospitals anchor resistance surveillance data collection and reporting systems.
India
CDSCO regulatory pathways and domestic manufacturing scale concentration in generic oral fluconazole compress margins for standard-of-care segments. Rising patient awareness and pharmacy network expansion in tier-1 cities support volume growth. Mumbai and Bangalore clusters concentrate formulation expertise and clinical research infrastructure.
Acute Vulvovaginal Candidiasis Treatment Market Vendor Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with surveillance infrastructure and manufacturing scale. Established players with regulatory compliance capabilities capture value pools concentrated in prescription pathways. Three archetypes dominate: multinational conglomerates with broad distribution networks, specialized antifungal developers with novel mechanism focus, and generic manufacturers with cost-optimized scale. Portfolio diversification toward recurrent infection protocols and geographic expansion into direct-to-consumer channels represent the dominant competitive moves.
Among multinational pharmaceutical conglomerates, Pfizer and Bayer AG exemplify archetypes leveraging manufacturing scale and brand strength respectively. Mycovia Pharmaceuticals occupies a position within the specialized developer tier focused on novel azole formulations. Astellas Pharma and Basilea Pharmaceutica represent additional anchors in the innovation-focused segment, with Scynexis exemplifying resistance-aware therapeutic development. Bristol-Myers Squibb and Johnson & Johnson sit within diversified healthcare conglomerates with portfolio breadth spanning multiple therapeutic areas.
| Leading Market Players |
|---|
| Astellas Pharma Inc. |
| Mycovia Pharmaceuticals, Inc. |
| Basilea Pharmaceutica Ltd. |
| Scynexis, Inc. |
| Pfizer, Inc. |
| Bayer AG |
| Grupo Ferrer Internacional S.A. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
EMA pharmacovigilance frameworks for reproductive-toxicity data and REACH authorization requirements gate qualified supply for premium-tier oral antifungal formulations, concentrating pricing power among manufacturers with established surveillance infrastructure while compressing margins for standard topical azoles facing generic commoditization pressures.
Pricing Analysis
The bundled-versus-unbundled service split separates prescription pathways with reimbursement leverage from direct-to-consumer channels competing on convenience economics. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation novelty and resistance profile, with novel azole derivatives commanding brand premiums against commodity fluconazole. Pricing pressure stems from Indian and Chinese manufacturing scale in generic oral segments, intensifying cost compression for standard monotherapy. Retail pharmacy chains exhibit highest price sensitivity, while academic medical centers prioritize clinical efficacy over acquisition cost for refractory cases.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and CDSCO localization incentives are reshaping active pharmaceutical ingredient sourcing patterns for azole manufacturing. API production concentrates in India, China, and the United States, with formulation finishing distributed across regional hubs. Key inputs include imidazole intermediates, propylene glycol carriers, and specialized polymer matrices for extended-release designs. Single-source vulnerability in Indian API manufacturing creates exposure to export restriction risks. Distribution runs through wholesale pharmacy networks with telehealth-integrated direct fulfillment gaining metropolitan share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in acute vulvovaginal candidiasis treatment rests on formulation premiumization toward recurrent infection protocols and supply chain rationalization that captures cost efficiencies from Indian API sourcing without quality compromise.
For Market Incumbents: Anticipate azole resistance accumulation narrowing empirical therapeutic options by deepening R&D investment in novel mechanism antifungals and securing backward integration into specialized API manufacturing to defend against Indian generic scale. Channel control through telehealth platform partnerships offers defensive positioning as direct-to-consumer fulfillment displaces traditional clinic dependencies. For New Entrants and Emerging Players: Capture white-space opportunity in fluconazole-refractory maintenance regimens where infectious disease specialists seek extended-interval dosing solutions, and in microbiome-adjunctive positioning where probiotic co-formulations lack clinical validation. The United States direct-to-consumer pharmacy channel represents the most penetrable access point for appropriate candidates bypassing prescription gatekeeping. For Investors and Strategic Acquirers: Roll-up economics work for specialized antifungal developers because EMA pharmacovigilance burdens disproportionately constrain smaller innovators, creating distressed acquisition targets with novel pipeline assets. Platform consolidation around resistance-aware therapeutic portfolios offers five-to-ten year viability as surveillance infrastructure becomes table stakes. The signal to watch is FDA antifungal susceptibility testing mandate expansion, which would accelerate evidentiary threshold elevation and favor scaled surveillance capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Improves adherence profiles for recurrent infection maintenance protocols in academic medical centers. |
| Telehealth Platform Integration | Enables same-day prescription fulfillment bypassing traditional clinic visit dependencies in metropolitan markets. |
| Resistance Surveillance Infrastructure Investment | Positions manufacturers for FDA antifungal susceptibility testing mandate compliance and post-market obligations. |
| API Manufacturing Scale-Up | Captures cost efficiencies from Indian and Chinese supply concentration while securing quality certification tiers. |
| Recurrent Infection Protocol Specialization | Justifies premium pricing against episodic treatment benchmarks through reduced treatment failure rates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and infectious disease specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-volume modeling and top-down pharmaceutical expenditure triangulation anchored market size estimates.
Comparable historical periods anchored the projection horizon across treatment line, dosage form, administration route, and patient population segments. CAGRs derived from fitted growth curves incorporating azole resistance surveillance trends, telehealth adoption trajectories, and reimbursement framework evolution. Forecast inputs included patent expiration schedules for fluconazole formulations and WHO Essential Medicines List inclusion criteria navigation.
Antifungal resistance surveillance data gaps, regulatory divergence between FDA and EMA evidentiary thresholds, and generic manufacturing scale concentration in India are the dominant revision risks for forecast trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Norovirus Infection Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Direct-Acting Antiviral Medicines Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Hepatitis C Market