
 Mycobacterium Infections Treatment Market | 2026-2036
Mycobacterium Infections Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Mycobacterium Infections Treatment Market Foresight
Hospital procurement consolidation is realigning purchasing power toward centralized infectious disease units and academic medical centers. Johnson & Johnson dominates the rifamycin-class portfolio through manufacturing scale and WHO prequalification breadth. Insmed Incorporated specializes in inhaled liposomal amikacin formulations for refractory nontuberculous mycobacterial lung disease. Novartis AG navigates competitive tenders through geographic dominance in high-burden tuberculosis markets.
Mycobacterium infections treatment encompasses pharmaceutical and supportive interventions targeting pathogenic species including Mycobacterium tuberculosis complex and nontuberculous mycobacteria, with standard regimens requiring six to twenty-four months of multi-drug combination therapy to prevent resistance emergence. The primary commercial purpose centers on reducing mortality from tuberculosis and chronic pulmonary disease caused by environmental mycobacteria in immunocompromised populations. Antibiotics and antimycobacterial agents command the largest revenue share due to mandatory prolonged dosing, while inhalation administration routes represent the fastest-expanding segment driven by lung-targeted delivery for refractory cases. Combination therapy anchors margin pools where proprietary fixed-dose formulations command premium positioning against generic single-agent alternatives.
The FDA oversees clinical trial endpoints and New Drug Application pathways for novel tuberculosis regimens, while WHO prequalification standards determine eligibility for Global Fund and national program procurement across endemic countries. EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations that unlock European hospital formulary access. India's CDSCO mandates local bioequivalence studies for imported fixed-dose combinations, shaping market entry timelines for multinational manufacturers. Stakeholders must monitor regulatory divergence between stringent authority requirements and pragmatic national program needs.
Market Dynamics
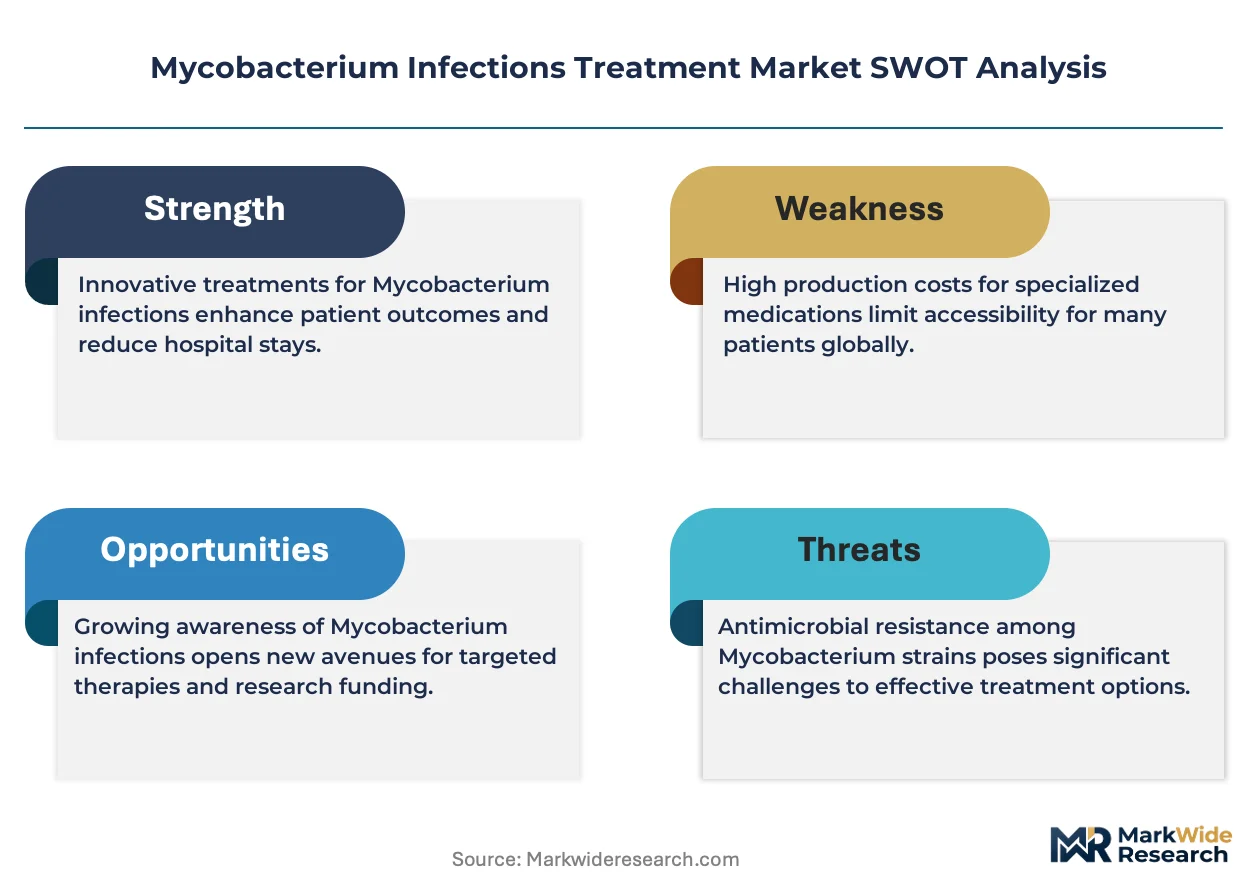
Hospital procurement consolidation is compressing vendor margins while concentrating purchasing authority within centralized infectious disease units and academic medical centers that now negotiate multi-year supply agreements.
Growth Catalysts
- WHO Prequalification Mandate:Global Fund eligibility requirements for multidrug-resistant tuberculosis therapies are accelerating manufacturer investment in bioequivalence studies and quality certification.
- Inhaled Delivery Platforms:Liposomal amikacin formulations for refractory nontuberculous mycobacterial lung disease are expanding addressable patient populations beyond oral therapy failures.
- India's RNTCP Infrastructure:Government-run Revised National Tuberculosis Control Program clinics provide established distribution channels reaching high-burden rural populations.
Market Restraints
- API Supply Concentration:Rifamycin-class active pharmaceutical ingredient production clusters in specific manufacturing regions, creating single-source vulnerability for critical first-line agents.
- CDSCO Bioequivalence Requirements:India's mandate for local clinical studies on imported fixed-dose combinations extends registration timelines and elevates entry costs for multinational firms.
- Prolonged Therapy Duration:Six-to-twenty-four-month treatment regimens strain patient adherence and reimbursement sustainability, elevating default risk in public procurement contracts.
Strategic Opportunities
- Refractory NTM Lung Disease:Immunocompromised populations with chronic pulmonary disease represent underserved segments where lung-targeted delivery commands premium positioning.
- Fixed-Dose Combination Proprietary Formulations:Multi-agent single-pill regimens differentiate against generic single-agent alternatives in hospital formulary competitions.
- Academic Medical Center Partnerships:Centralized infectious disease units seek integrated supply relationships spanning diagnostics, therapeutics, and adherence monitoring technologies.
Industry Challenges
- Specialized Formulation Expertise:Liposomal encapsulation and inhalation device engineering require capabilities scarce among contract development and manufacturing organizations.
- EMA-FDA Endpoint Divergence:Discrepant clinical trial requirements between centralized European marketing authorizations and US New Drug Application pathways force duplicate study designs.
- Legacy Distribution Fragmentation:National tuberculosis program procurement in endemic countries operates through fragmented tender processes with inconsistent quality specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycobacterium Infections Treatment Market |
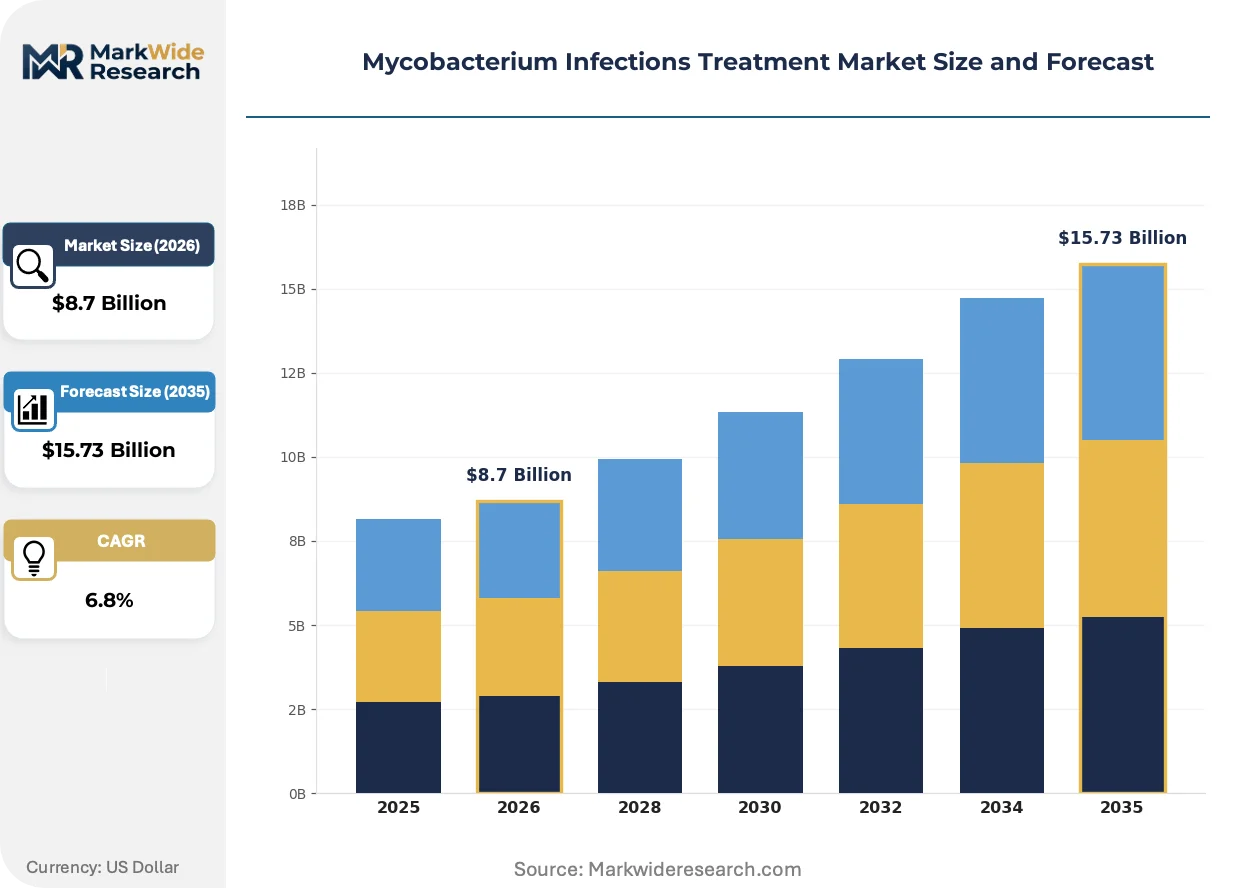
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antimycobacterial Agents, Combination Therapy, Supportive Care Administration Route: Oral, Intravenous, Inhalation, Topical End User: Hospitals, Outpatient Clinics, Homecare Settings, Research Laboratories Treatment Stage: Initial Phase, Stabilization Phase, Maintenance Phase, Recurrence Management |
| Companies Covered | Insmed Incorporated, Sanofi, Novartis AG, Pfizer Inc., Johnson & Johnson, Teva Pharmaceutical Industries Ltd, AstraZeneca, Merck & Co., Inc, Paratek Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycobacterium Infections Treatment Market Shifts & Advancements
Inhalation administration routes are gaining share as developers engineer lung-targeted delivery systems that bypass systemic toxicity while improving drug concentration at infection sites.
Liposomal amikacin suspension technology is modularizing treatment protocols for refractory nontuberculous mycobacterial infections. Academic medical centers with specialized pulmonary units are adopting these platforms ahead of community hospitals. The technology is modularizing combination therapy design by enabling localized high-dose delivery that reduces systemic adverse event profiles.
WHO prequalification standards for multidrug-resistant tuberculosis therapies are tightening manufacturing quality requirements across endemic markets. Manufacturers must now demonstrate continuous process verification and supply chain traceability to maintain eligibility for Global Fund procurement. Indian and South African national programs are prioritizing prequalified suppliers in tender evaluations, reshaping competitive access.
Centralized hospital procurement models are displacing decentralized pharmacy purchasing in infectious disease treatment. Large health systems now aggregate demand across multiple facilities to negotiate volume-based contracts with single-source suppliers. This consolidation is most advanced in US academic medical centers and European hospital networks with integrated formulary management.
Mycobacterium Infections Treatment Market Segmentation
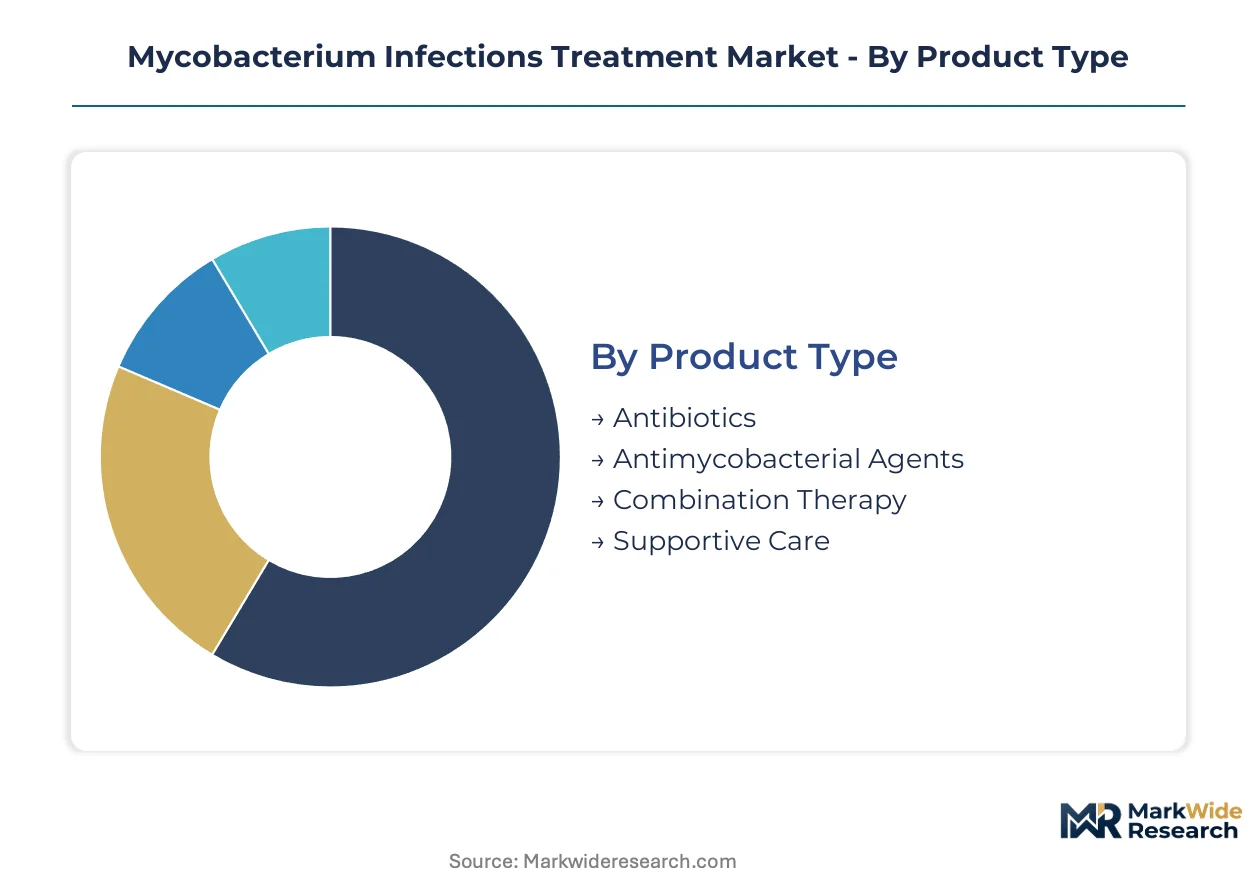
Treatment modality segmentation reveals where capital deployment concentrates in mycobacterial therapeutics. Product formulation complexity and administration technology requirements create divergent margin structures across the value chain.
Product Type:
Antibiotics and antimycobacterial agents demand the heaviest upfront manufacturing investment due to fermentation capacity requirements and WHO prequalification infrastructure.
- Antibiotics:Rifamycin-class agents anchor first-line tuberculosis protocols. Demand clusters in India's RNTCP clinics and South African national program tenders where volume procurement dominates.
- Antimycobacterial Agents:Second-line injectables and fluoroquinolones target multidrug-resistant strains. Hospital infectious disease units in academic medical centers drive uptake for salvage therapy protocols.
- Combination Therapy:Fixed-dose single-pill formulations streamline adherence monitoring.
- Supportive Care:Adjunctive nutritional and pulmonary rehabilitation products.
Most installed capacity flows through Antibiotics. Expansion is steepest in Combination Therapy.
Administration Route:
Delivery mechanism selection hinges on infection site accessibility and systemic toxicity thresholds, with lung-targeted platforms commanding development priority.
- Inhalation:Liposomal amikacin suspensions enable localized high-dose delivery for refractory nontuberculous mycobacterial lung disease. Academic medical centers with specialized pulmonary units adopt these platforms ahead of community hospitals to bypass systemic adverse events.
- Oral:First-line fixed-dose combinations dominate ambulatory care. India's government-run clinics and high-burden African national programs prioritize oral regimens for adherence sustainability in resource-limited settings.
- Intravenous:Hospital-based administration for severe or disseminated infections.
- Topical:Cutaneous mycobacterial infection management in dermatology practices.
Oral formulations capture the highest patient volume. Inhalation platforms are climbing the fastest as developers expand addressable populations beyond oral therapy failures.
End User:
Procurement authority concentration determines contract structure complexity across the care continuum.
- Hospitals:Centralized infectious disease units negotiate multi-year supply agreements aggregating demand across facilities. Academic medical centers in the US and European hospital networks lead formulary consolidation.
- Outpatient Clinics:Government-run tuberculosis control programs serve as dominant distribution channels in endemic countries.
- Homecare Settings:Directly observed therapy programs and patient support services.
- Research Laboratories:Clinical trial sites and reference laboratories for resistance testing.
Hospital procurement absorbs the majority of high-value combination therapies. Outpatient Clinics are gaining share fastest as national programs decentralize treatment access.
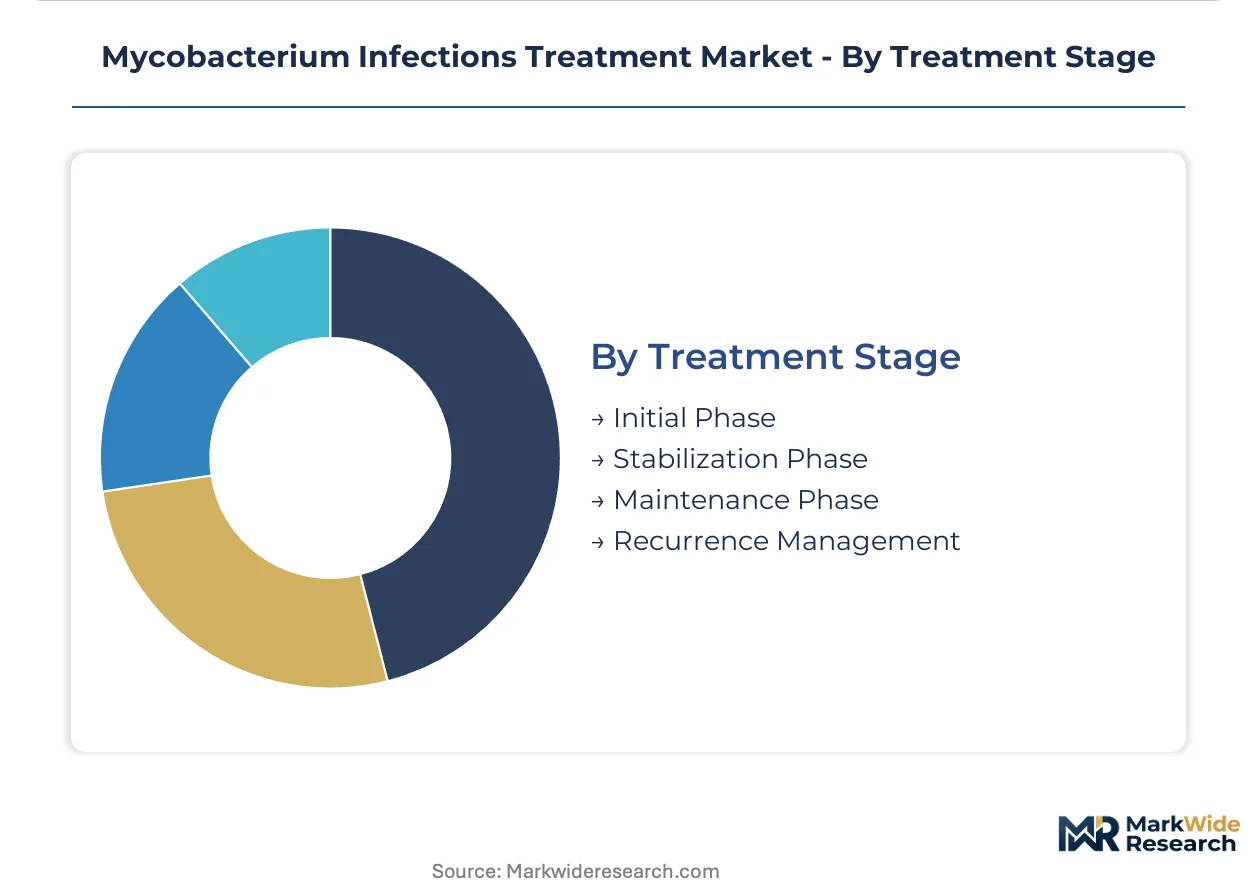
Treatment Stage:
Therapy duration and monitoring intensity vary sharply across the clinical trajectory, with upfront phases requiring the most intensive resource allocation.
- Initial Phase:Intensive multi-drug induction regimens spanning two months. Hospital admission rates peak here for severe pulmonary or disseminated disease, concentrating demand in academic medical center infectious disease units.
- Maintenance Phase:Prolonged continuation therapy four to twenty-two months. Patient adherence monitoring technologies and fixed-dose combination procurement dominate spend in this extended window.
- Stabilization Phase:Transition from intensive to continuation therapy with resistance testing.
- Recurrence Management:Salvage protocols for relapse or reinfection cases.
Maintenance Phase consumes the longest duration of drug supply. Recurrence Management shows the steepest expansion trajectory as resistant strain prevalence elevates retreatment needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates government procurement for tuberculosis therapies through its RNTCP infrastructure, while the United States channels demand toward academic medical centers with specialized infectious disease units.
United States
FDA oversight of New Drug Application pathways shapes clinical trial investments for novel tuberculosis regimens. Hospital procurement consolidation concentrates purchasing authority within centralized infectious disease units at academic medical centers. Boston and New York Metro clusters anchor research partnerships spanning diagnostics, therapeutics, and adherence monitoring technologies.
India
Government-run Revised National Tuberculosis Control Program clinics serve as the dominant distribution channel for antimycobacterial agents across high-burden rural populations. CDSCO mandates local bioequivalence studies for imported fixed-dose combinations, extending registration timelines for multinational manufacturers. Maharashtra and Gujarat house manufacturing clusters for rifamycin-class active pharmaceutical ingredients.
Germany
EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations that unlock European hospital formulary access. REACH compliance requirements shape raw material sourcing for liposomal formulation development. Baden-Württemberg and Bavaria concentrate pharmaceutical manufacturing infrastructure for specialized antimycobacterial agents.
South Africa
National tuberculosis program procurement prioritizes WHO-prequalified suppliers in tender evaluations for multidrug-resistant therapies. The country's pharmaceutical regulator enforces quality certification standards aligned with Global Fund eligibility requirements. Gauteng and Western Cape provinces anchor hospital networks with integrated infectious disease management capabilities.
Japan
PMDA marketing authorization pathways determine access for novel inhaled delivery platforms targeting refractory nontuberculous mycobacterial lung disease. METI industrial policy supports domestic fermentation capacity for antibiotic active pharmaceutical ingredients. Kanto and Kansai regions concentrate pulmonary specialty centers adopting lung-targeted therapeutic technologies.
Mycobacterium Infections Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the mycobacterial therapeutics value chain. Johnson & Johnson and Novartis AG leverage manufacturing scale and geographic breadth against Insmed Incorporated's concentrated expertise in inhaled liposomal formulations. Three archetypes dominate: integrated pharmaceutical conglomerates with WHO prequalification infrastructure, specialty inhalation device developers, and generic fixed-dose combination manufacturers. Competitive moves center on strategic partnerships with academic medical centers and portfolio diversification into adherence monitoring technologies.
Among diversified pharmaceutical conglomerates, Johnson & Johnson and Sanofi exemplify scale-driven positioning through manufacturing breadth and regulatory certification depth. Insmed Incorporated occupies a specialist tier focused on refractory nontuberculous mycobacterial lung disease, representing the pure-play archetype against broader portfolio competitors. Novartis AG and Pfizer Inc. anchor the multinational tier navigating competitive tenders through established hospital formulary relationships.
| Leading Market Players |
|---|
| Insmed Incorporated |
| Sanofi |
| Novartis AG |
| Pfizer Inc. |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd |
| AstraZeneca |
| Merck & Co., Inc |
| Paratek Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Hospital procurement consolidation toward centralized infectious disease units and academic medical centers anchors contract-based long-term offtake agreements that compress vendor margins while securing volume commitments. India's government-run Revised National Tuberculosis Control Program clinics operate through tender-based procurement that prioritizes WHO-prequalified suppliers, creating price floors determined by certification investment rather than manufacturing cost alone.
Pricing Analysis
Capacity additions in Maharashtra and Gujarat are reshaping price floors for rifamycin-class active pharmaceutical ingredients as domestic fermentation scale expands. Three-tier pricing structure across WHO-prequalified premium, nationally certified standard, and non-prequalified economy levels separates suppliers by regulatory certification depth. Pricing pressure stems from CDSCO-mandated local bioequivalence studies that extend registration timelines and elevate entry costs for multinational manufacturers. Government procurement programs exhibit highest price sensitivity due to budget-constrained tender processes, while academic medical centers with specialized pulmonary units demonstrate lowest sensitivity for lung-targeted delivery platforms.
Supply Chain Analysis
Specialized fermentation technologists in Maharashtra, Gujarat, and selected European manufacturing clusters constrain workforce availability for liposomal encapsulation and inhalation device engineering. Rifamycin-class active pharmaceutical ingredient production draws from concentrated fermentation capacity, while liposomal amikacin suspensions rest on scarce phospholipid supply and precision nebulizer component sourcing. Single-source vulnerability pervades critical first-line agent manufacturing where API production clusters in specific regions. Distribution runs through hospital procurement consolidation in academic medical centers and government-run tuberculosis control program clinics in endemic countries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where demand shifts toward WHO-prequalified premium formulations and lung-targeted delivery platforms that command positioning above generic single-agent alternatives.
For Market Incumbents: Deepen backward integration into rifamycin-class active pharmaceutical ingredient fermentation capacity to defend against API supply concentration risks. Secure multi-year supply agreements with centralized infectious disease units before procurement consolidation completes, while investing in continuous process verification infrastructure to maintain WHO prequalification eligibility for Global Fund access. For New Entrants and Emerging Players: Academic medical center partnerships offer the most penetrable entry channel for refractory nontuberculous mycobacterial lung disease platforms. Target immunocompromised populations with chronic pulmonary disease through lung-targeted delivery technologies that bypass systemic toxicity, leveraging specialized pulmonary unit adoption as reference sites for broader hospital formulary expansion. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with WHO prequalification infrastructure are the most active acquirer in this space, seeking specialty inhalation device developers to complement broad-spectrum antibiotic portfolios. Focus acquisition screening on pure-play liposomal formulation specialists with proprietary nebulizer engineering capabilities. Watch for inflection signals in CDSCO registration timeline compression or EMA-FDA endpoint harmonization initiatives that would reduce duplicate study burdens.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Investment | Unlocks Global Fund procurement eligibility across endemic country national programs. |
| Liposomal Formulation Development | Enables lung-targeted delivery for refractory nontuberculous mycobacterial infections. |
| Academic Medical Center Partnership | Secures reference site status for specialized pulmonary unit adoption. |
| Fixed-Dose Combination Proprietary Formulation | Differentiates against generic single-agent alternatives in hospital formulary competitions. |
| CDSCO Local Bioequivalence Study Completion | Accelerates market entry timelines for imported combinations in India. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases; plus customs and trade data — were reconciled through bottom-up and top-down triangulation. Conversations with formulary directors at academic medical centers and payer access specialists in endemic countries informed demand-side assumptions. Secondary sources included WHO prequalification listings, Global Fund procurement records, and national tuberculosis program tender documentation.
Data-stream reconciliation across treatment modality, administration route, end-user procurement authority, and regional regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value buildups validated against macro healthcare expenditure trends. Forecast inputs incorporated WHO prequalification pipeline status, CDSCO registration progression, and hospital procurement consolidation velocity.
Revisions become necessary when regulatory divergence between EMA and FDA intensifies, API supply concentration triggers shortage conditions, or government procurement budget constraints materialize beyond modeled scenarios. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Efavirenz Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Varicella Zoster Infection Treatment Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Virology Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Actinomycosis Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Typhoid Fever Vaccine Market