
 Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market | 2026-2036
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market Foresight
Hospital formulary revenue is fragmenting across novel antibiotic classes as payer pressure intensifies on legacy glycopeptide pricing. Pfizer Inc. leverages its hospital distribution infrastructure to sustain broad access for established intravenous therapies across major health systems. Melinta Therapeutics, Inc. specializes in late-stage resistant infection protocols, while Nabriva Therapeutics anchors its position through oral-stepdown formulations that reduce length-of-stay costs.
Acute Bacterial Skin and Skin Structure Infection (ABSSSI) encompasses deep soft-tissue infections, surgical site infections, and major cutaneous abscesses requiring systemic antibacterial therapy with documented tissue penetration exceeding plasma protein binding thresholds of 90 percent. The primary commercial purpose centers on reducing progression to sepsis, limb-threatening necrosis, and unplanned readmissions in diabetic, immunocompromised, and post-surgical patient cohorts. Oxazolidinones capture concentrated margin pools in outpatient parenteral antimicrobial therapy transitions, while lipopeptides lead inpatient settings where methicillin-resistant Staphylococcus aureus predominates. Oral delivery modes are expanding fastest as payers mandate early hospital discharge with bioequivalent ambivalent coverage.
The FDA's QIDP pathway and EMA's priority medicines scheme shape clinical trial design and commercial sequencing for new ABSSSI entrants, with both regulators mandating non-inferiority margins against vancomycin benchmarks. Japan's PMDA and China's NMPA have tightened tissue distribution study requirements, forcing sponsors to demonstrate adequate drug concentration at infection sites beyond simple plasma pharmacokinetics. Stakeholders must monitor how CMS's new technology add-on payment revisions and parallel European DRG reforms alter reimbursement for novel agents against generic vancomycin and linezolid.
Market Dynamics
Hospital antibiotic stewardship programs are fragmenting formulary revenue across novel lipopeptide and oxazolidinone classes while CMS reimbursement reforms compress length-of-stay incentives.
Growth Catalysts
- FDA QIDP Pathway:The Qualified Infectious Disease Product designation accelerates clinical trial timelines and commercial sequencing for novel Gram-positive agents entering ABSSSI protocols.
- Japan PMDA Tissue Distribution Mandates:Stricter pharmacokinetic requirements at infection sites drive sponsors to invest in advanced penetration studies beyond plasma protein binding thresholds.
- Post-Surgical Cohort Expansion:Rising diabetic and immunocompromised patient volumes in tertiary care centers sustain demand for MRSA-targeted inpatient therapies.
Market Restraints
- Generic Vancomycin Pricing:Legacy glycopeptide commoditization caps reimbursement ceilings for novel intravenous entrants in Medicare DRG frameworks.
- Plasma Protein Binding Thresholds:Technical requirements exceeding 90 percent tissue penetration create formulation barriers for oral-stepdown candidates.
- European DRG Parallel Reforms:Bundled payment structures in Germany and France reduce incremental margin capture for premium antibiotics against standard-of-care benchmarks.
Strategic Opportunities
- China NMPA Fast-Track:Priority review pathways for anti-infectives with documented resistant-pathogen coverage open accelerated market entry for qualifying sponsors.
- Outpatient Parenteral Antimicrobial Therapy:Home infusion networks in the United States create channel expansion for bioequivalent oral formulations reducing hospital readmission risk.
- EMA Priority Medicines Scheme:PRIME designation incentives for unmet medical need categories lower regulatory friction for novel mechanism agents targeting biofilm-associated infections.
Industry Challenges
- Clinical Microbiology Talent Scarcity:Specialized infectious disease pharmacokinetic expertise gaps delay protocol design for tissue distribution studies required by Japan and China regulators.
- Legacy EHR Integration:Antibiotic stewardship software deployment in community hospital systems faces interoperability friction with existing pharmacy information management platforms.
- Patent Thicket Navigation:Oxazolidinone and lipopeptide IP estates create licensing complexity for formulation innovators seeking freedom-to-operate in oral delivery modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market |
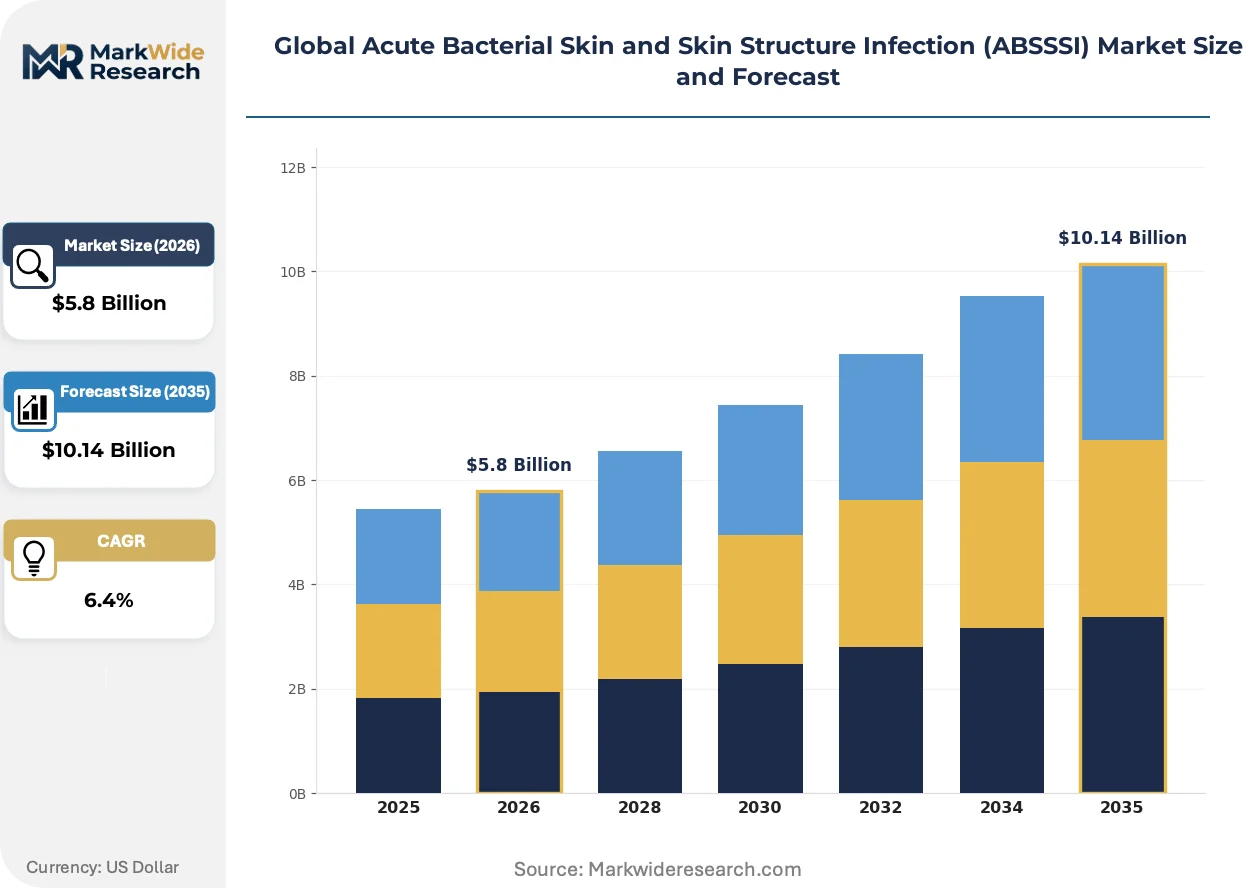
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cephalosporins, Glycopeptides, Oxazolidinones, Lipopeptides, Fluoroquinolones Therapy Area: Cellulitis, Impetigo, Erysipelas, Wound Infections, Abscesses End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Home Healthcare, Long-Term Care Facilities Delivery Mode: Oral, Intravenous, Topical, Intramuscular |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., Melinta Therapeutics, Inc., Paratek Pharmaceuticals, Inc., AbbVie Inc., Basilea Pharmaceutica, Nabriva Therapeutics, Endo Pharmaceuticals, Glenmark Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market Shifts & Advancements
Computational modeling and regulatory pathway convergence are compressing development timelines while payer pressure forces differentiation beyond efficacy non-inferiority.
Artificial intelligence-driven molecular dynamics simulation is virtualizing preclinical tissue penetration prediction for novel lipopeptide candidates. Mid-cap sponsors in the United States and Switzerland now deploy physics-based modeling to prioritize lead compounds before initiating costly animal distribution studies. This capability is virtualizing traditional empirical screening cycles that previously consumed 18-24 months in early-phase development.
EMA's revised clinical trial guidance on non-inferiority margins for skin and soft tissue infections tightens statistical thresholds against vancomycin comparators. Sponsors must now demonstrate sustained clinical response at test-of-cure visits rather than simple cessation of lesion spread. European trial sites in Germany, France, and Italy are responding by extending patient follow-up protocols and investing in centralized digital lesion measurement systems.
Integrated delivery networks in the United States are consolidating antibiotic procurement through sole-source contracts with mandatory generic step-down clauses. Hospital systems now require bioequivalent oral alternatives within 72 hours of clinical stabilization, displacing extended intravenous courses. This restructuring is most visible in Medicare Advantage–dominated markets where capitated reimbursement rewards early discharge with ambivalent coverage continuity.
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market Segmentation
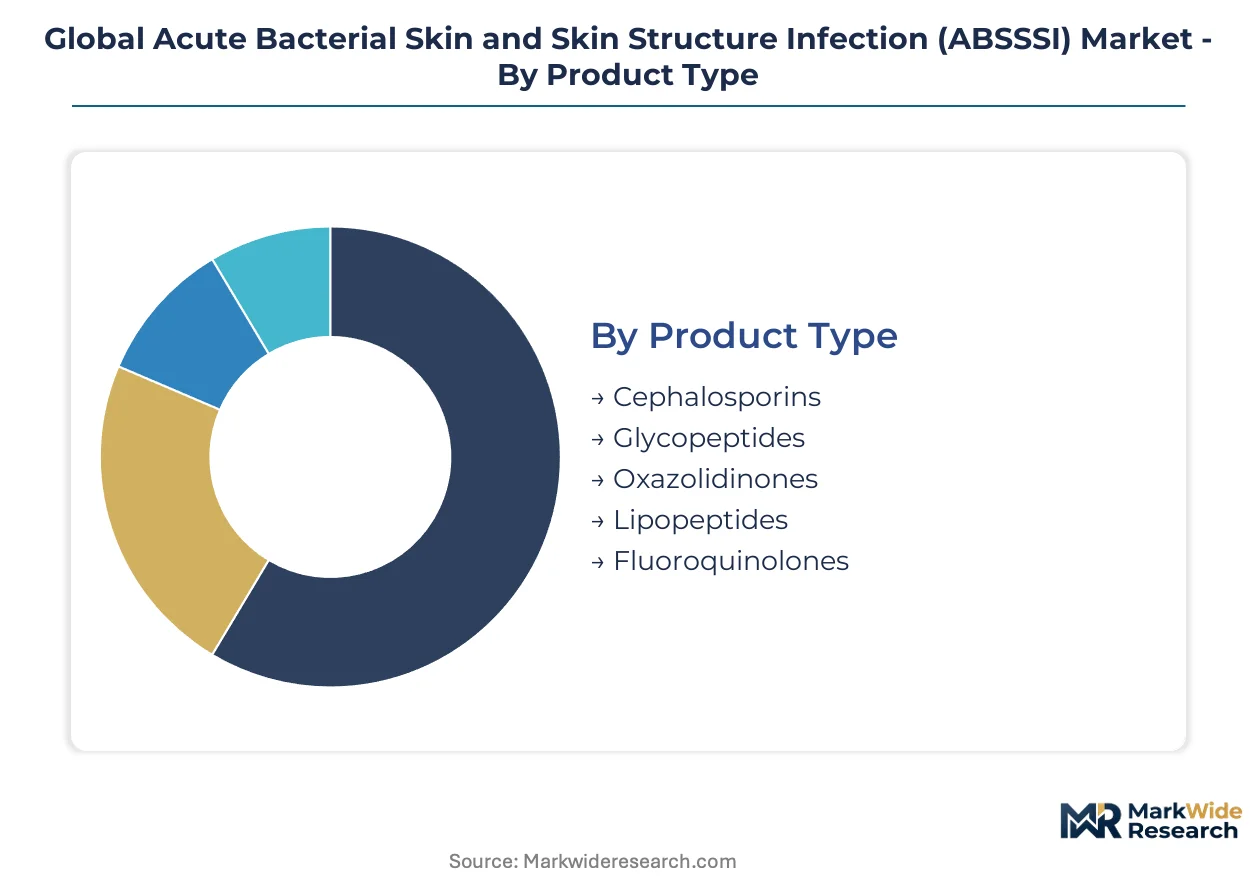
ABSSSI market segmentation reflects divergent clinical workflows across inpatient stabilization, surgical intervention, and ambulatory step-down phases. Antibiotic class selection and delivery mode choices directly correlate with infection severity, comorbidity burden, and payer-mandated length-of-stay targets.
Product Type:
Lipopeptides and oxazolidinones command premium positioning with extended patent protection, while glycopeptides face rapid generic commoditization compressing procurement cycles.
- Lipopeptides:Cyclic lipopeptide structures demonstrate concentration-dependent bactericidal activity against MRSA biofilm formations. United States tertiary care centers deploy these agents in diabetic foot infection protocols where limb salvage rates drive formulary preference.
- Oxazolidinones:Synthetic protein synthesis inhibitors achieve 100% oral bioavailability enabling seamless intravenous-to-oral transitions. Medicare Advantage networks in Florida and Texas prioritize these agents for outpatient parenteral antimicrobial therapy programs reducing readmission penalties.
- Glycopeptides:Vancomycin and teicoplanin dominate empirical therapy in cost-constrained hospital systems.
- Cephalosporins:Beta-lactam options retain utility in methicillin-susceptible Staphylococcus aureus populations.
- Fluoroquinolones:Respiratory fluoroquinolones face restricted ABSSSI labeling due to tendon toxicity warnings.
Glycopeptides anchors the volume base while lipopeptides gains share at the steepest rate.
Therapy Area:
Clinical presentation determines reimbursement tiering, with deep soft-tissue infections qualifying for higher DRG weights than superficial dermatologic conditions.
- Wound Infections:Post-surgical and traumatic wound infections require systemic therapy with documented tissue penetration. German and French hospital networks mandate negative-pressure wound therapy adjuncts for grade III-IV infections.
- Abscesses:Major cutaneous abscesses with diameter exceeding 75 millimeters qualify for ABSSSI trial enrollment. United States emergency departments favor ultrasound-guided drainage with concurrent lipopeptide therapy.
- Cellulitis:Diffuse superficial spreading infections drive high-volume oral antibiotic dispensing.
- Erysipelas:Well-demarcated superficial infections respond to narrow-spectrum penicillin derivatives.
- Impetigo:Limited non-bullous presentations often resolve with topical mupirocin monotherapy.
Cellulitis generates the highest prescription volume while wound infections command the steepest per-patient revenue.
End User:
Site-of-care migration from inpatient wards to ambulatory settings reshapes antibiotic procurement patterns and formulary contracting structures.
- Hospitals:Inpatient wards and emergency departments manage severe ABSSSI with sepsis risk. Japanese tertiary centers under PMDA stewardship mandates restrict broad-spectrum empirical therapy pending culture results.
- Ambulatory Surgical Centers:Same-day surgical facilities require prophylactic and post-operative infection protocols. United States Medicare-certified ASCs in California and New York face bundled payment pressure to minimize post-discharge antibiotic costs.
- Home Healthcare:Infusion nursing services deliver prolonged intravenous courses.
- Specialty Clinics:Infectious disease and wound care centers manage refractory cases.
- Long-Term Care Facilities:Skilled nursing environments confront elevated MRSA colonization rates.
Hospitals retain the dominant revenue share while home healthcare climbs the fastest as payers mandate early discharge.
Delivery Mode:
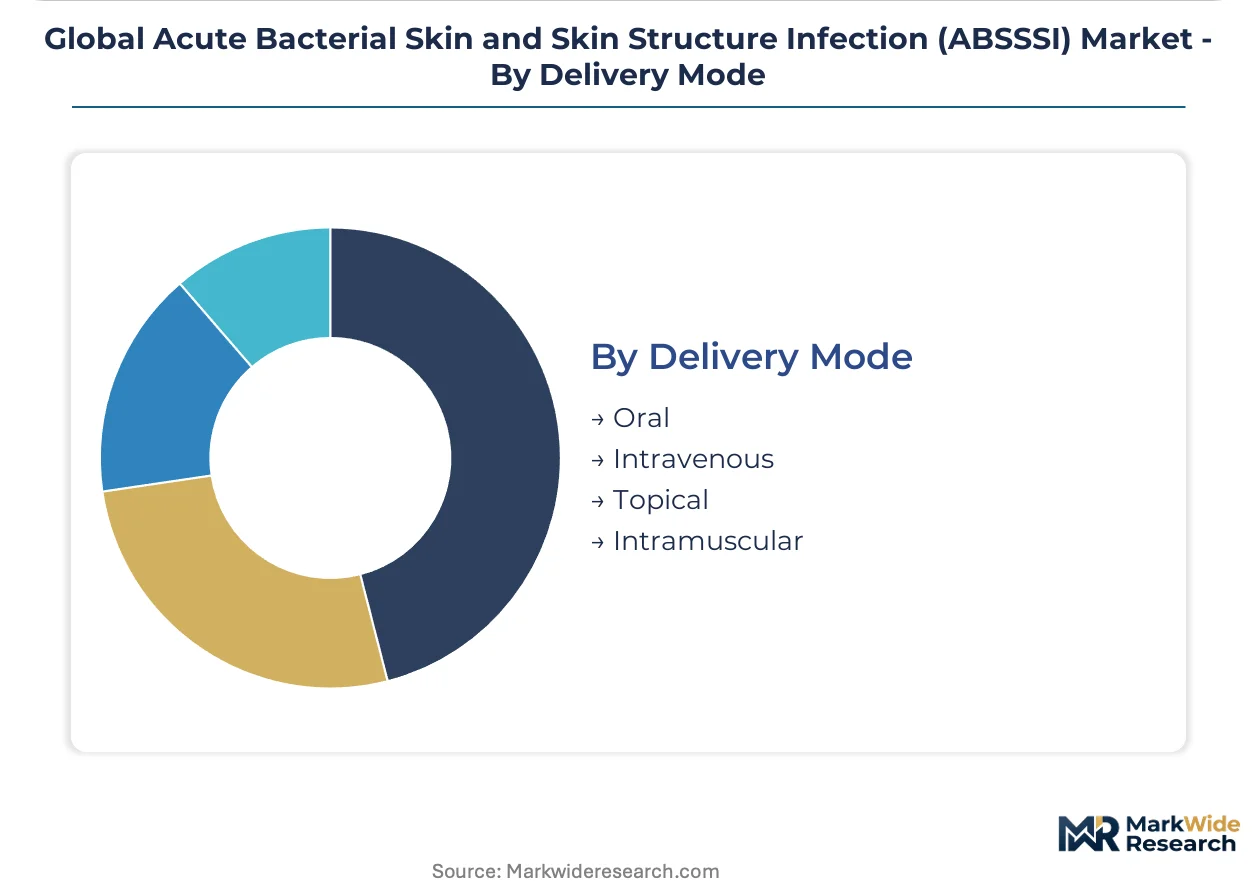
Pharmacokinetic requirements and patient compliance profiles segment administration routes across acute and chronic treatment phases.
- Intravenous:Continuous or intermittent infusion ensures therapeutic levels in critically ill patients. China's NMPA requires bioequivalence documentation for generic intravenous formulations entering centralized hospital procurement.
- Oral:Tablet and suspension formulations enable ambulatory completion of therapy courses. Swissmedic-approved oral oxazolidinones support early discharge protocols in Basel and Zurich hospital networks.
- Topical:Limited to localized impetigo and minor wound infections.
- Intramuscular:Depot formulations offer alternatives for vascular access limitations.
Intravenous administration anchors the volume base while oral delivery expands at the steepest trajectory as step-down protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies, with European DRG frameworks squeezing novel antibiotic premiums while United States Medicare Advantage networks tolerate higher reimbursement for oral-stepdown therapies that compress length-of-stay.
United States
Integrated delivery networks in Florida and Texas consolidate procurement through sole-source contracts with mandatory generic step-down clauses. FDA QIDP designation accelerates commercial sequencing for novel Gram-positive agents entering hospital formularies. The Mayo Clinic and Cleveland Clinic anchor stewardship-driven adoption of lipopeptide protocols in diabetic foot infection cohorts.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia face bundled DRG payment structures that cap incremental margins for premium antibiotics against vancomycin benchmarks. EMA revised clinical trial guidance tightens non-inferiority statistical thresholds for skin and soft tissue infection protocols. Berlin and Frankfurt trial sites extend patient follow-up with centralized digital lesion measurement systems.
Japan
Tertiary care centers in Tokyo and Osaka restrict broad-spectrum empirical therapy under PMDA stewardship mandates pending culture confirmation. Stricter pharmacokinetic requirements at infection sites drive sponsors to invest in advanced tissue penetration studies beyond plasma protein binding thresholds. The Kanto region concentrates formulary decision-making for novel oxazolidinone transitions.
China
NMPA fast-track pathways for anti-infectives with documented resistant-pathogen coverage accelerate market entry for qualifying sponsors. Centralized hospital procurement in Beijing and Shanghai requires bioequivalence documentation for generic intravenous formulations. The Yangtze River Delta anchors demand for MRSA-targeted inpatient therapies in post-surgical diabetic cohorts.
Switzerland
Swissmedic-approved oral oxazolidinones support early discharge protocols in Basel and Zurich hospital networks reducing length-of-stay costs. Mid-cap sponsors deploy physics-based molecular dynamics simulation to virtualize preclinical tissue penetration prediction. The Basel pharmaceutical cluster concentrates computational modeling capabilities for lipopeptide lead compound prioritization.
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market Competitive Landscape
Multinational pharmaceutical conglomerates and specialized infectious disease biotechs split the market between volume-driven glycopeptide commoditization and premium lipopeptide-oxazolidinone innovation. Hospital formulary contracting power concentrates with three to five global players leveraging distribution infrastructure, while mid-cap specialists carve positions through resistant-pathogen protocols and oral-stepdown formulations. Competitive maneuvering centers on M&A consolidation of late-stage development assets and strategic partnerships with integrated delivery networks for sole-source procurement contracts.
Among the established pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. occupy positions anchored by hospital distribution scale and legacy intravenous therapy portfolios. Melinta Therapeutics, Inc. exemplifies the specialized biotech archetype targeting late-stage resistant infection protocols with differentiated mechanism agents. These three entities collectively represent the strategic spectrum from broad formulary access to narrow therapeutic specialization that defines competitive positioning in ABSSSI markets.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| Melinta Therapeutics, Inc. |
| Paratek Pharmaceuticals, Inc. |
| AbbVie Inc. |
| Basilea Pharmaceutica |
| Nabriva Therapeutics |
| Endo Pharmaceuticals |
| Glenmark Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Undercapacity in sterile lipopeptide active pharmaceutical ingredient manufacturing across Switzerland and the United States is forcing sponsors to commit to multi-year offtake agreements, compressing procurement flexibility while elevating price premiums for guaranteed supply slots.
Pricing Analysis
After-sales revenue from hospital stewardship consulting and formulary integration services now drives lifetime value for novel antibiotic developers. Three-tier pricing structure across premium lipopeptide, standard oxazolidinone, and economy glycopeptide levels stratifies procurement tiers. Cost compression in the glycopeptide tier is intensifying because Medicare DRG bundling caps reimbursement ceilings. Generic vancomycin buyers in cost-constrained community hospital systems exhibit the highest price sensitivity, while integrated delivery networks negotiating sole-source contracts for oral-stepdown therapies show the lowest.
Supply Chain Analysis
Contract manufacturing concentration rests with Lonza in Switzerland, Catalent in the United States, and Samsung Biologics in South Korea for sterile injectable lipopeptide production. Active pharmaceutical ingredient synthesis draws from China and India, while finished dose formulation centers on the United States and Germany. Single-source vulnerability in cyclic lipopeptide precursor supply creates exposure to export licensing delays. Distribution runs through hospital GPO contracts and specialty pharmacy networks for outpatient parenteral antimicrobial therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized infectious disease pharmacokinetic expertise gaps in clinical microbiology talent pools are constraining protocol design velocity, making tissue distribution study capabilities the scarce asset that separates viable entrants from stalled development programs.
For Market Incumbents: Insulate formulary positioning by deepening backward integration into sterile manufacturing capacity in Basel and Zurich clusters, while investing in FDA QIDP pathway navigation expertise to accelerate competitor lag time. Generic vancomycin commoditization threatens margin pools in Medicare DRG frameworks. For New Entrants and Emerging Players: China's Yangtze River Delta hospital procurement networks represent underpenetrated white space for MRSA-targeted inpatient therapies. Oral-stepdown formulation partnerships with Medicare Advantage home infusion networks in Florida and Texas offer the most penetrable ambulatory channel. Pursue NMPA fast-track qualification to compress regulatory timeline against established players. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across lipopeptide manufacturing scale-up, favoring asset-light platform licensing over captive production investment. Long-term viability in this market hinges on acquiring mid-cap specialists with documented resistant-pathogen coverage and existing EMA priority medicines scheme designations. Monitor CMS new technology add-on payment revisions as the critical reimbursement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA QIDP Designation Pathway | Accelerates clinical trial timelines and commercial sequencing for novel Gram-positive agents. |
| Hospital System Partnership | Secures sole-source procurement contracts with integrated delivery networks in Texas and Florida. |
| Manufacturing Scale-Up | Expands sterile lipopeptide capacity in Swiss and U.S. contract manufacturing clusters. |
| Regulatory Approval Pathway | Navigates Japan PMDA tissue distribution mandates and China NMPA bioequivalence requirements. |
| Pipeline Diversification | Targets biofilm-associated infection mechanisms eligible for EMA priority medicines scheme incentives. |
Research Methodology
The analysis maps lipopeptide, oxazolidinone, glycopeptide, cephalosporin, and fluoroquinolone antibiotic classes, each validated through infectious disease pharmacokinetic specialists, hospital formulary directors, regulatory affairs leads, and payer access specialists. Primary interviews combined with secondary validation against FDA QIDP filings, EMA submission databases, ClinicalTrials.gov protocols, and CMS Medicare reimbursement data. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to constrain estimate variance.
Assumptions held fixed include FDA non-inferiority margin requirements against vancomycin benchmarks, while variables included CMS new technology add-on payment revisions and European DRG reform trajectories. The analytical framework modeled antibiotic class, therapy area severity tier, end-user site-of-care, and delivery mode across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporated hospital antibiotic stewardship program adoption curves and generic vancomycin pricing elasticity.
Practitioners should monitor FDA QIDP designation grant rates, Japan PMDA tissue distribution study requirement changes, and CMS reimbursement tier revisions for early signals of forecast deviation. Quarterly review of hospital formulary placement velocity and generic glycopeptide procurement price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Human Immunodeficiency Virus Type 1 (HIV 1) Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Mycobacterium Infections Treatment Market