
 Anti Obesity Prescription Drugs Market | 2026-2036
Anti Obesity Prescription Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Obesity Prescription Drugs Market Intelligence
Biopharmaceutical manufacturing capacity in Denmark is broadening as peptide synthesis investments accelerate across North Atlantic production corridors. Novo Nordisk A/S anchors European supply through large-scale fill-finish infrastructure. Eli Lilly and Company competes via differentiated incretin-based pipelines. Pfizer Inc. sustains late-stage development across oral small-molecule candidates.
Anti obesity prescription drugs comprise pharmacological agents indicated for chronic weight management through appetite suppression, nutrient absorption inhibition, or metabolic pathway modulation, with GLP-1 receptor agonists representing the dominant mechanism class requiring cold-chain distribution for peptide-based injectables. Their primary commercial purpose centers on reducing obesity-related comorbidity burden within integrated healthcare systems. GLP-1 agonists capture the deepest margin pools as physician preference concentrates on agents with demonstrated cardiovascular outcomes data. Injectable solutions command premium positioning against oral tablets due to bioavailability advantages and dosing adherence profiles. Extended-release formulations are gaining fastest traction within homecare settings where patient self-administration reduces clinic dependency.
FDA oversight through the Division of Metabolism and Endocrinology Products shapes trial design requirements and label expansion pathways, while EMA's CHMP evaluations determine centralized market access across EU member states. Japan's PMDA imposes distinct ethnic bridging study mandates that delay entry for non-domestic developers. Stakeholders must monitor evolving prior authorization criteria from CMS and national health technology assessment bodies as reimbursement gatekeeping tightens amid budget impact scrutiny.
Market Dynamics
GLP-1 receptor agonist pipelines are compressing development timelines as cardiovascular outcome trials become the gatekeeper for formulary placement and physician prescribing hierarchies.
Growth Catalysts
- Medicare Part D expansion:CMS reimbursement pathways for obesity pharmacotherapy are broadening beneficiary access across United States integrated delivery networks.
- Peptide synthesis automation:Continuous manufacturing platforms are reducing batch-to-batch variability and accelerating scale-up for injectable incretin analogues.
- Cardiometabolic bundling:United States health systems are consolidating obesity management within value-based care contracts that tie provider payments to comorbidity reduction metrics.
Market Restraints
- Cold-chain infrastructure gaps:Last-mile temperature control failures in emerging markets degrade peptide stability and limit distribution reach.
- API supply concentration:Fermentation-derived starting materials for GLP-1 agonists originate from a narrow base of European contract manufacturers.
- PMDA ethnic bridging mandates:Japan's requirement for domestic pharmacokinetic studies adds 18-24 months to regulatory timelines for non-Japanese developers.
Strategic Opportunities
- Oral small-molecule penetration:Non-peptide GLP-1 receptor agonists are advancing through Phase III trials with room-temperature stability profiles.
- Homecare self-administration:Auto-injector training programs are reducing clinic dependency and expanding addressable patient populations.
- Germany's DiGA pathway:Digital health applications for weight management companion tools are securing statutory health insurance reimbursement.
Industry Challenges
- Peptide chemist scarcity:Specialized talent for solid-phase synthesis and purification operations commands premium compensation in Denmark and Switzerland.
- Fill-finish capacity bottlenecks:Aseptic manufacturing lines for high-viscosity injectables require capital commitments exceeding standard biologics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Obesity Prescription Drugs Market |
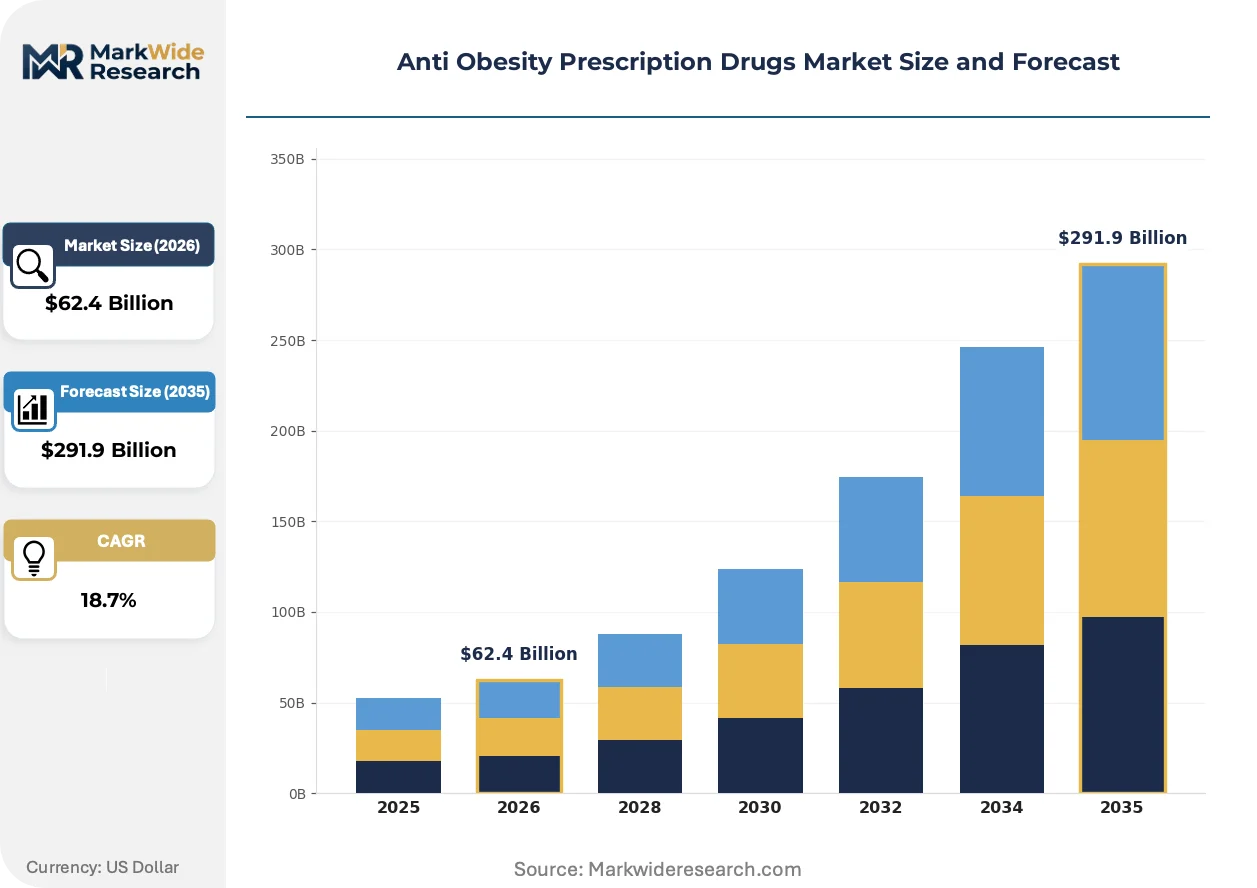
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $291.9 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GLP-1 Agonists, Sibutramine, Phentermine, Orlistat Delivery Mode: Oral Tablets, Injectable Solutions, Extended-Release Formulations, Sublingual Sprays End User: Clinics, Hospitals, Homecare, Pharmacies Patient Demographic: Adults, Adolescents, Pediatric Patients, Geriatric Patients |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, F. Hoffmann-La Roche Ltd, GlaxoSmithKline plc, Pfizer Inc., Currax Pharmaceuticals LLC, VIVUS LLC, Rhythm Pharmaceuticals Inc., Boehringer Ingelheim International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Obesity Prescription Drugs Market Strategic Shifts & Innovations
Dual and triple incretin agonist architectures are displacing single-mechanism therapies as the competitive frontier for next-generation obesity pharmacotherapy.
Oral GLP-1 receptor agonist formulations are expanding into patient segments that refuse or discontinue injectable therapy. Primary care physicians in United States managed care organizations are prescribing these agents at accelerating rates for BMI 27-30 populations. The technology is expanding into employer-sponsored wellness programs where needle aversion previously capped penetration.
EMA's centralized procedure for obesity drug approvals is harmonizing label requirements across Germany, France, and Italy. Manufacturers must now submit cardiovascular outcomes data as part of initial marketing authorization rather than post-approval commitments. This regulatory shift compresses development timelines for sponsors with existing heart failure or MACE trial infrastructure.
Specialty pharmacy distribution is consolidating patient onboarding and adherence monitoring under single-provider contracts. United States payers are directing covered lives toward limited distribution networks that capture injection training and refill compliance data. This channel concentration is most visible in Medicare Advantage plans where star ratings depend on medication persistence metrics.
Anti Obesity Prescription Drugs Market Segmentation
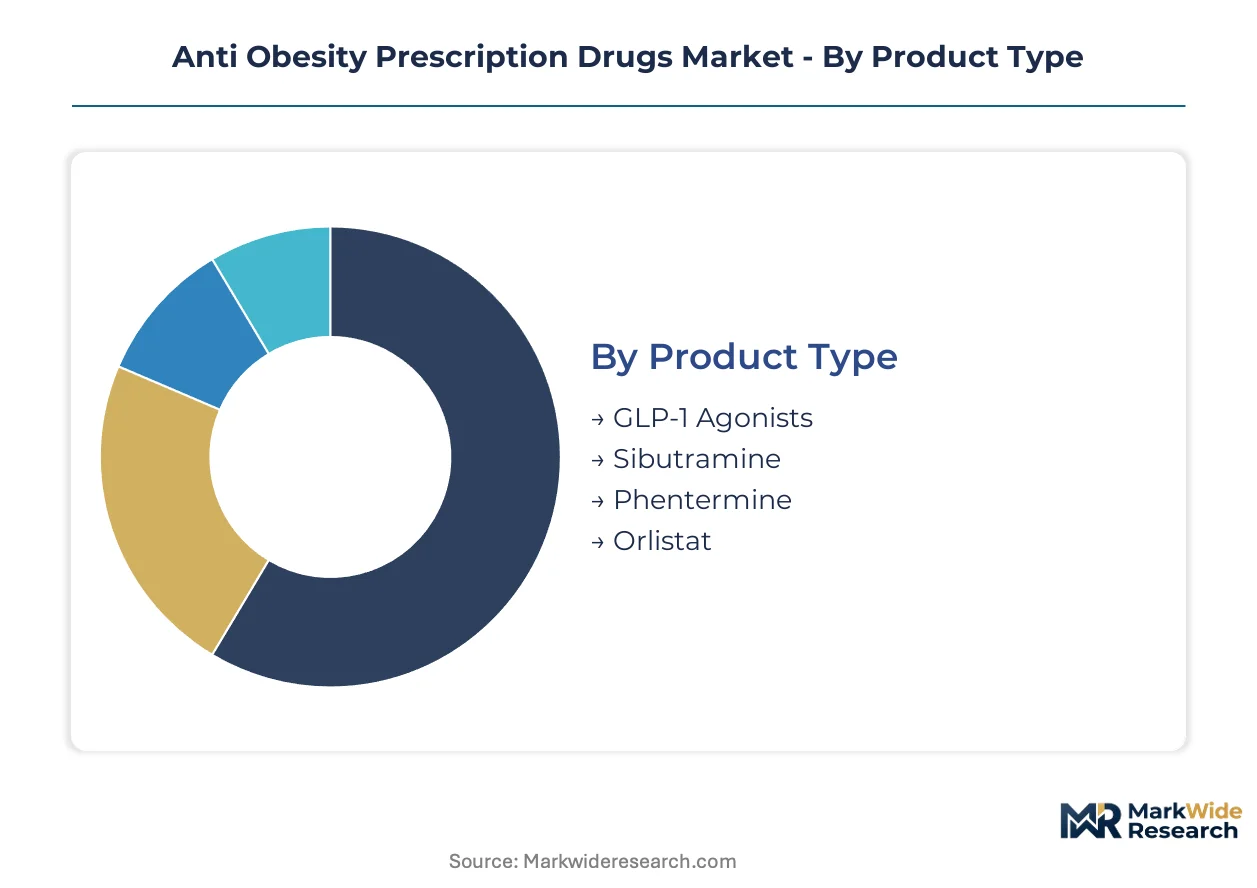
Segmentation in the anti-obesity prescription drugs market determines reimbursement tiers, distribution infrastructure requirements, and physician prescribing hierarchies. Each dimension carries distinct regulatory, pricing, and supply chain implications that shape commercial strategy.
Product Type:
Replacement cycles accelerate as cardiovascular outcomes data become the gatekeeper for formulary placement, forcing older mechanisms into declining share positions.
- GLP-1 Agonists:Peptide-based incretin analogues modulate appetite through central and peripheral GLP-1 receptor activation. Demand concentrates in United States integrated delivery networks where Medicare Advantage plans tie provider payments to comorbidity reduction metrics. Cold-chain requirements limit distribution reach in emerging markets with infrastructure gaps.
- Sibutramine:Serotonin-norepinephrine reuptake inhibitor that elevates satiety signaling through hypothalamic pathways. Prescription volume has collapsed across European markets following EMA safety withdrawals, though residual demand persists in select Middle Eastern jurisdictions with distinct risk-benefit frameworks.
- Phentermine:Sympathomimetic amine approved for short-term weight management through central nervous system stimulation. United States retail pharmacies dispense the majority of prescriptions under controlled substance scheduling requirements.
- Orlistat:Lipase inhibitor reducing dietary fat absorption through gastrointestinal enzyme blockade. Over-the-counter availability in several jurisdictions has eroded prescription volumes for the branded formulation.
Volume placements concentrate in GLP-1 Agonists; the faster expansion belongs to this same segment as cardiovascular outcomes data broaden labeled indications.
Delivery Mode:
Cost tiering separates premium-positioned injectables from commoditized oral tablets, with reimbursement bandwidth determining accessible segments for each patient population.
- Injectable Solutions:Subcutaneous delivery of peptide therapeutics requiring cold-chain distribution and patient training programs. United States specialty pharmacy networks capture the deepest margin pools through limited distribution contracts.
- Extended-Release Formulations:Depot injections and implantable devices reducing dosing frequency to monthly or quarterly intervals. Germany's statutory health insurance system reimburses these formulations at premium rates for patients with documented adherence failures on standard regimens.
- Oral Tablets:Small-molecule formulations with room-temperature stability profiles enabling broad retail pharmacy distribution. Japan's PMDA imposes distinct bioequivalence requirements that delay generic substitution.
- Sublingual Sprays:Rapid-absorption delivery bypassing first-pass hepatic metabolism for acute appetite suppression. Regulatory pathways remain unsettled across major markets.
Patient access concentrates in Injectable Solutions; the steepest expansion trajectory belongs to Extended-Release Formulations as homecare self-administration reduces clinic dependency.
End User:
Application setting determines reimbursement coding, with facility-based administration commanding distinct payment rates from ambulatory or self-directed therapy.
- Clinics:Specialty metabolic disease programs within integrated healthcare systems managing complex comorbidity profiles. United States value-based care contracts increasingly bundle obesity pharmacotherapy with diabetes and cardiovascular management.
- Hospitals:Inpatient initiation of therapy for patients with acute obesity-related complications. Discharge planning must coordinate with outpatient coverage to ensure medication persistence.
- Homecare:Self-administration models supported by telehealth monitoring and auto-injector training programs. Germany's DiGA pathway reimburses companion digital health applications for weight management.
- Pharmacies:Retail dispensing of oral formulations with pharmacist-led adherence counseling. Prior authorization requirements from United States payers increasingly direct patients toward limited distribution networks.
Prescription initiation concentrates in Clinics; the volume shift is moving fastest toward Homecare as reimbursement frameworks accommodate remote patient monitoring.
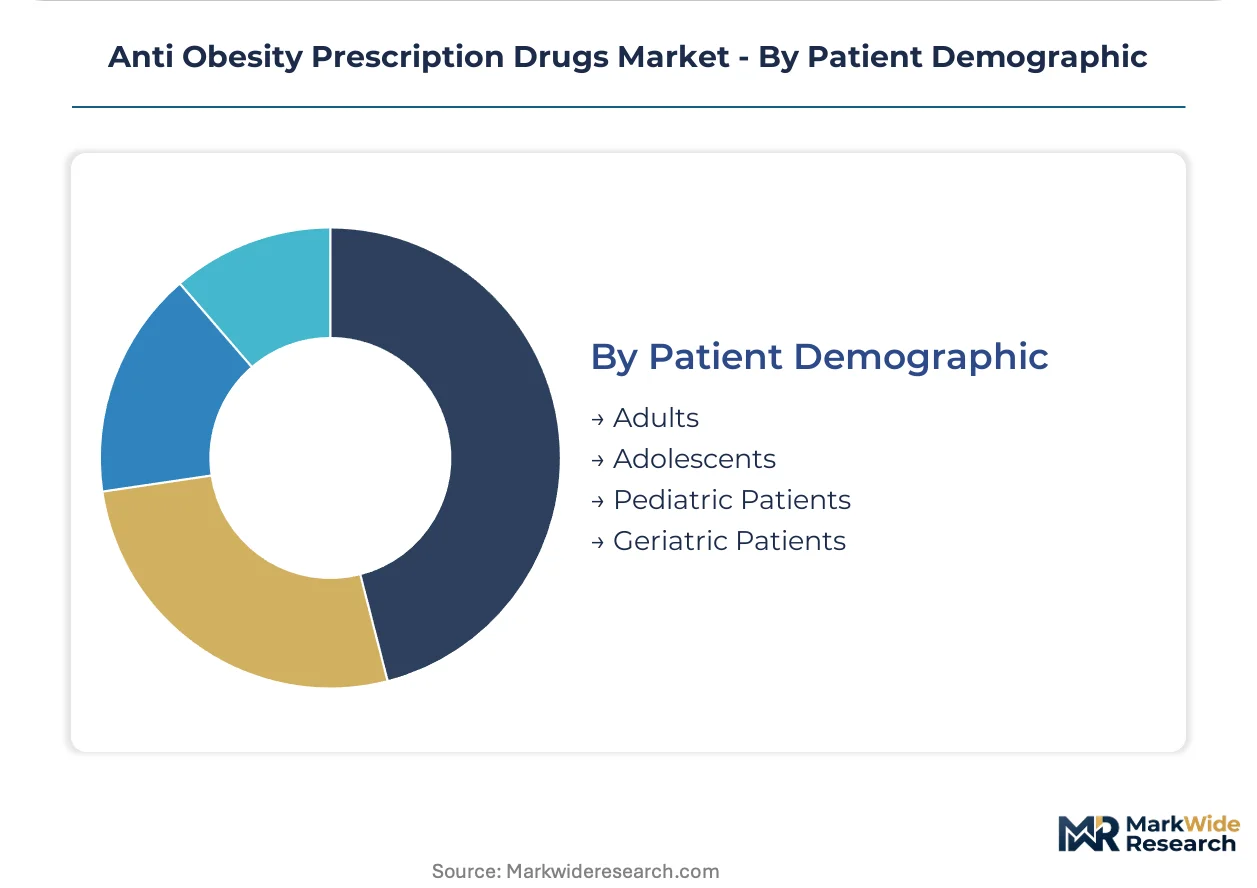
Patient Demographic:
Maturity differentiation separates established adult indications from emerging pediatric and geriatric segments with distinct trial requirements and safety monitoring protocols.
- Adults:Primary approved population with BMI thresholds of 30 or 27 with comorbidities across major regulatory jurisdictions. United States employer-sponsored wellness programs are expanding coverage to BMI 27-30 populations previously excluded.
- Adolescents:Patients aged 12-17 with obesity-related metabolic complications. FDA requires dedicated juvenile toxicity studies that extend development timelines.
- Pediatric Patients:Children below age 12 where pharmacotherapy remains investigational outside rare genetic obesity syndromes. EMA's pediatric investigation plan mandates drive sponsor investment in this segment.
- Geriatric Patients:Adults over 65 with age-adjusted BMI thresholds and heightened cardiovascular risk profiles. Medicare Part D expansion is broadening beneficiary access across United States markets.
Commercial investment concentrates in Adults; the regulatory attention is shifting most quickly toward Adolescents as pediatric obesity prevalence drives trial enrollment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide synthesis feedstock from Danish fermentation corridors anchors European supply, while North American demand concentrates around Medicare reimbursement expansion and employer wellness program adoption.
United States
CMS reimbursement pathways for obesity pharmacotherapy are broadening beneficiary access across integrated delivery networks. FDA's Division of Metabolism and Endocrinology Products mandates cardiovascular outcomes data for label expansion, compressing development timelines for sponsors with existing heart failure trial infrastructure. Specialty pharmacy networks in New Jersey and North Carolina capture the deepest margin pools through limited distribution contracts for injectable incretin analogues.
Germany
Statutory health insurance reimbursement for extended-release formulations commands premium rates for patients with documented adherence failures on standard regimens. EMA's CHMP evaluations determine centralized market access across EU member states, with cardiovascular outcomes data now required as part of initial marketing authorization. Bavaria's metabolic disease programs within integrated healthcare systems are consolidating obesity management with value-based care contracts tying provider payments to comorbidity reduction metrics.
Japan
PMDA ethnic bridging study mandates add 18-24 months to regulatory timelines for non-domestic developers seeking market entry. METI oversight shapes domestic pharmacokinetic requirements that delay generic substitution for oral small-molecule formulations. Tokyo's specialty clinics are expanding metabolic disease programs as reimbursement frameworks evolve under national health technology assessment pathways.
Denmark
Biopharmaceutical manufacturing capacity is broadening as peptide synthesis investments accelerate across North Atlantic production corridors. Novo Nordisk anchors European supply through large-scale fill-finish infrastructure in the Copenhagen region. Zealand's fermentation-derived starting material suppliers face concentration risk as global demand for GLP-1 agonist APIs outpaces batch-to-batch variability improvements from continuous manufacturing platforms.
Switzerland
Specialized talent for solid-phase synthesis and purification operations commands premium compensation in Basel and Zurich chemical corridors. Swissmedic evaluations determine market access timelines for cardiovascular outcome trials submitted through centralized EU procedures. Geneva's contract manufacturing organizations are expanding aseptic manufacturing lines for high-viscosity injectables requiring capital commitments exceeding standard biologics infrastructure.
Anti Obesity Prescription Drugs Market Key Industry Players
Global majors compete with regional champions across cardiovascular outcome trial infrastructure and cold-chain distribution reach. The market structure concentrates around peptide-based innovators with demonstrated MACE data, while oral small-molecule specialists occupy distinct positioning for needle-averse patient segments. Three archetypes dominate: large-cap incretin platform owners, mid-cap cardiovascular outcome trial specialists, and emerging oral formulation developers. Capacity expansion and strategic partnerships represent the dominant competitive moves as fill-finish bottlenecks constrain injectable supply.
Among North American and European innovators, Novo Nordisk A/S, Eli Lilly and Company, and Pfizer Inc. occupy positions across the GLP-1 agonist development spectrum. Novo Nordisk exemplifies the vertically integrated peptide manufacturer with captive European production infrastructure. Eli Lilly represents the cardiovascular outcome trial specialist with differentiated incretin-based pipelines advancing through Phase III. Pfizer anchors the oral small-molecule tier with room-temperature stability profiles targeting patient segments that refuse injectable therapy. Each occupies distinct archetype positioning without direct overlap in mechanism or delivery mode.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| F. Hoffmann-La Roche Ltd |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Currax Pharmaceuticals LLC |
| VIVUS LLC |
| Rhythm Pharmaceuticals Inc. |
| Boehringer Ingelheim International GmbH |
| Others |
Cost & Logistics Intelligence
Captive European production infrastructure anchors supply positioning and pricing power for peptide-based incretin analogues, with Novo Nordisk's Danish fill-finish corridors enabling premium capture against outsourced competitors facing API concentration risk. This integration choice insulates margin pools from fermentation feedstock volatility while locking in formulary placement through cardiovascular outcomes data.
Pricing Analysis
Service-bundling separates injection-training programs from unbundled oral tablet dispensing, with United States specialty pharmacy networks commanding premium capture for adherent patient management. Three-tier pricing structure across cardiovascular-outcome-proven, emerging-mechanism, and generic oral formulations reflects FDA label differentiation and CMS reimbursement bandwidth. Pricing pressure stems from Medicare Part D negotiation mandates compressing net prices for GLP-1 agonists with MACE data. Employer-sponsored wellness programs exhibit highest price sensitivity; integrated delivery networks with value-based contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Danish fermentation corridors supplying GLP-1 agonist starting materials, where Zealand's batch-to-batch variability constraints tether global injectable output to North Atlantic weather and energy disruptions. Solid-phase synthesis draws from Switzerland and Denmark; fill-finish capacity concentrates in Denmark and United States. Tariff exposure on Chinese-sourced peptide reagents compounds API supply concentration. Distribution runs through limited specialty pharmacy networks capturing patient adherence data for payer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
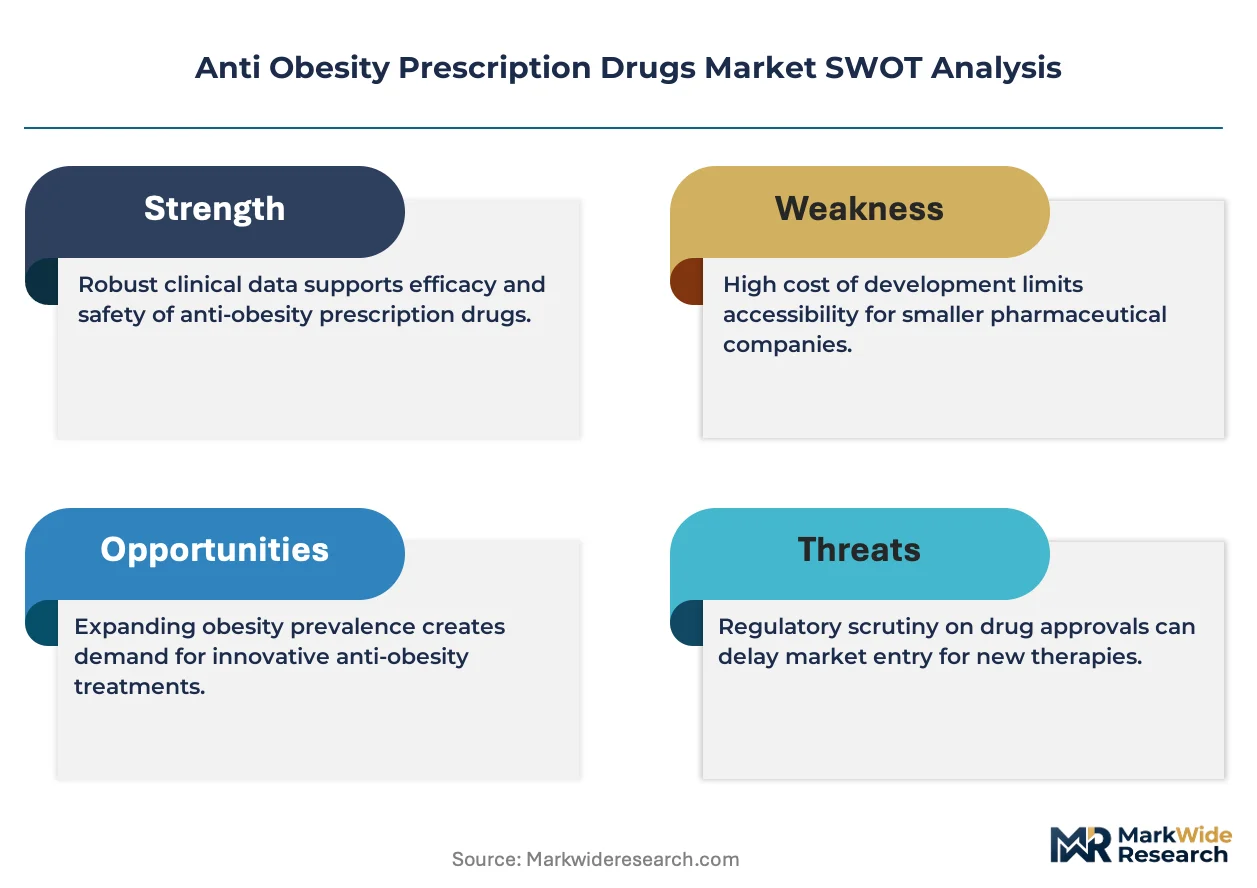
FDA cardiovascular outcomes requirements erect a cost-of-compliance moat that rewards sponsors with existing heart failure trial infrastructure while excluding capital-constrained entrants from formulary placement.
For Market Incumbents: To counter oral small-molecule entrants targeting needle-averse patient segments, Novo Nordisk and Eli Lilly should deepen backward integration into Danish and Swiss peptide synthesis corridors while expanding auto-injector training programs that reduce clinic dependency and lock in homecare reimbursement codes. For New Entrants and Emerging Players: Oral formulation technology offers the most penetrable wedge against injectable incumbents, with Japan's PMDA ethnic bridging delays creating white-space for domestic pharmacokinetic specialists and Germany's DiGA pathway enabling digital health companion tools for statutory insurance reimbursement. For Investors and Strategic Acquirers: Exit pathways concentrate in cardiovascular outcome trial specialists with Phase III MACE data, where long-term viability across the 5-10 year window hinges on CMS negotiation carve-outs for agents with demonstrated comorbidity reduction. The signal to watch is EMA's centralized procedure timeline compression for sponsors submitting heart failure endpoints as initial authorization rather than post-approval commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Advancement | FDA's Division of Metabolism and Endocrinology Products mandates MACE data for label expansion, compressing development timelines for prepared sponsors. |
| Manufacturing Scale-Up | Danish fill-finish capacity expansion addresses high-viscosity injectable bottlenecks that constrain GLP-1 agonist supply to Medicare Advantage plans. |
| Regulatory Approval Pathway | EMA's CHMP now requires cardiovascular outcomes data as part of initial marketing authorization rather than post-approval commitments. |
| Pipeline Diversification | Dual and triple incretin agonist architectures displace single-mechanism therapies as the competitive frontier for next-generation obesity pharmacotherapy. |
| Licensing Agreement | Japanese developers with domestic pharmacokinetic capabilities secure 18-24 month regulatory advantages over non-domestic entrants facing PMDA bridging mandates. |
Research Approach
Multi-period observation of formulary placement trends, CMS reimbursement code expansions, and EMA centralized procedure timelines anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Secondary validation drew from FDA filings, EMA CHMP assessments, ClinicalTrials.gov cardiovascular outcome trial registrations, and CMS Medicare Part D utilization data. Bottom-up patient-flow modeling and top-down manufacturer capacity estimates were triangulated against disclosed prescription volume trends.
Segment-weighting applied treatment line, dosage form, administration route, patient population, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns for chronic disease pharmacotherapies with comparable comorbidity reduction profiles. Forecast inputs included Medicare Advantage star rating dependencies, employer wellness program coverage expansion trajectories, and cold-chain infrastructure buildout rates in target markets.
Several conditions sit outside the modeled scope, including unannounced regulatory pathway changes, abrupt CMS reimbursement reversals, and breakthrough manufacturing technologies that could disrupt peptide synthesis economics. Forecasts reflect documented assumptions about cardiovascular outcome trial readout timelines and formulary negotiation dynamics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Estrogen Replacement Therapy (ERT) Market
Pharmaceuticals
Global Divalproex Sodium Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Global Treatment-Resistant Depression Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
P2X7 Receptor Antagonists Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Short-Acting Insulin Market