
 Depression and Seasonal Affective Disorder Therapeutics Market | 2026-2036
Depression and Seasonal Affective Disorder Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Depression and Seasonal Affective Disorder Therapeutics Market Outlook
Outcome-based reimbursement contracts and value-based care financing is reconfiguring which developers can sustain late-stage CNS programs. Eli Lilly and Company leverages its metabolic-psychiatry crossover pipeline to anchor diversified neuroscience revenue. Pfizer Inc. competes through manufacturing scale across oral and injectable antidepressant formats. Takeda Pharmaceutical Company Limited specializes in Japanese-origin monoamine modulators with established Asian regulatory dossiers.
Depression and Seasonal Affective Disorder therapeutics comprise pharmacological agents, neuromodulation devices, psychotherapeutic protocols, and photoperiodic interventions designed to restore monoaminergic tone, circadian entrainment, and prefrontal-limbic connectivity, typically formulated as oral tablets, depot injections, or calibrated light-emitting panels for clinical or home deployment. Antidepressants remain the largest product type category, though margin pools are shifting toward digital therapeutics as FDA breakthrough device designations accumulate. Injectable delivery modes are outpacing oral formulations in growth velocity, driven by long-acting injectable antipsychotic-antidepressant combinations and ketamine-derived clinic protocols.
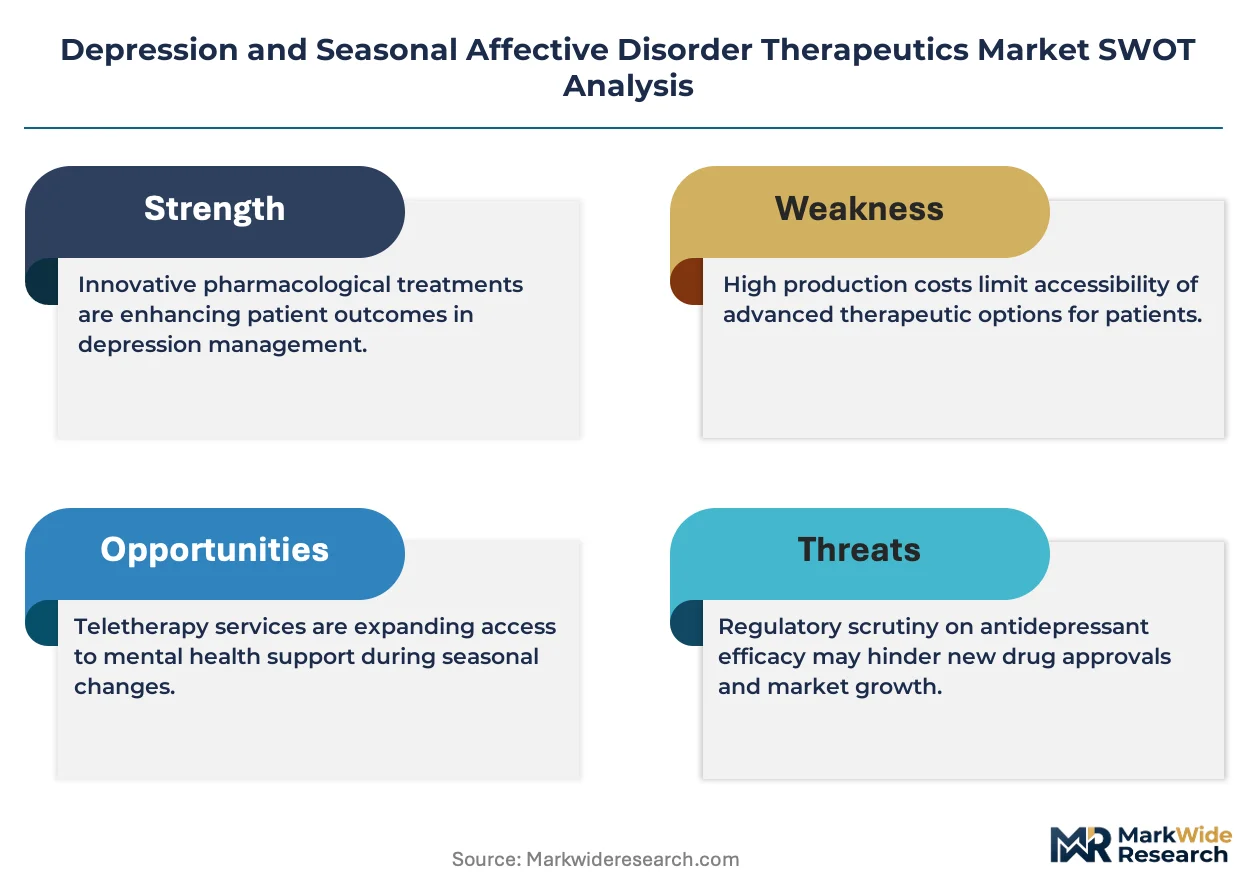
FDA breakthrough therapy designation and EMA PRIME eligibility are compressing regulatory timelines for novel mechanisms in treatment-resistant depression, while the DEA's scheduling review of psychedelic compounds is reshaping investigational access frameworks. The FDA's draft guidance on digital therapeutics for psychiatric conditions is creating parallel approval pathways that bifurcate traditional drug-device regulatory boundaries. Stakeholders must monitor how CMS national coverage determinations for esketamine and transcranial magnetic stimulation will recalibrate site-of-care economics across hospital outpatient and freestanding clinic settings.
Market Dynamics
Long-acting injectable formulations and digital therapeutics are fragmenting the traditional oral antidepressant monopoly, forcing incumbents to rebuild commercial infrastructure around clinic-based administration and prescription digital health reimbursement codes.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:The FDA's accelerated review mechanism compresses development timelines for treatment-resistant depression candidates, enabling earlier revenue recognition for novel mechanisms targeting serotonin receptor subtypes.
- Photoperiodic Intervention Protocols:Calibrated light-emitting panels for home deployment are expanding addressable patient populations beyond clinic-dependent modalities, particularly in northern latitudes with pronounced seasonal variation.
- Neuromodulation Device Integration:Transcranial magnetic stimulation systems are achieving outpatient clinic penetration through portable platform designs that reduce capital requirements for psychiatric practice expansion.
Market Restraints
- Ketamine Supply Concentration:DEA-controlled substance scheduling creates procurement bottlenecks for esketamine-derived clinic protocols, limiting site-of-care expansion to hospital outpatient departments with specialized licensing.
- Reimbursement Fragmentation:CMS national coverage determinations for interventional psychiatry vary across Medicare administrative contractors, producing geographic inequities in patient access to neuromodulation services.
- Serotonin Syndrome Liability:Polypharmacy risks with monoamine oxidase inhibitors constrain combination therapy approaches, narrowing the therapeutic window for treatment-resistant patient subpopulations.
Strategic Opportunities
- Digital Therapeutic Formularies:Employer-sponsored health plans in the United States are piloting standalone reimbursement for FDA-cleared prescription digital therapeutics, creating direct-to-payer contracting channels outside pharmacy benefit managers.
- Metabolic-Psychiatry Convergence:Glucagon-like peptide-1 receptor agonists with demonstrated neuropsychiatric effects are opening crossover indications that leverage existing endocrinology infrastructure for depression screening.
- EMA PRIME Eligibility:European priority medicines designation offers accelerated assessment pathways for novel antidepressants addressing unmet need, compressing time-to-market for mechanisms with differentiated receptor binding profiles.
Industry Challenges
- Psychiatrist Workforce Density:Rural and semi-urban regions face specialist scarcity that limits interventional psychiatry service deployment, requiring telemedicine-integrated care models with asynchronous supervision protocols.
- Legacy Electronic Health Record Integration:Digital therapeutics platforms encounter interoperability friction with dominant EHR vendors, complicating prescribing workflows and outcome data capture for value-based contracting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Depression and Seasonal Affective Disorder Therapeutics Market |
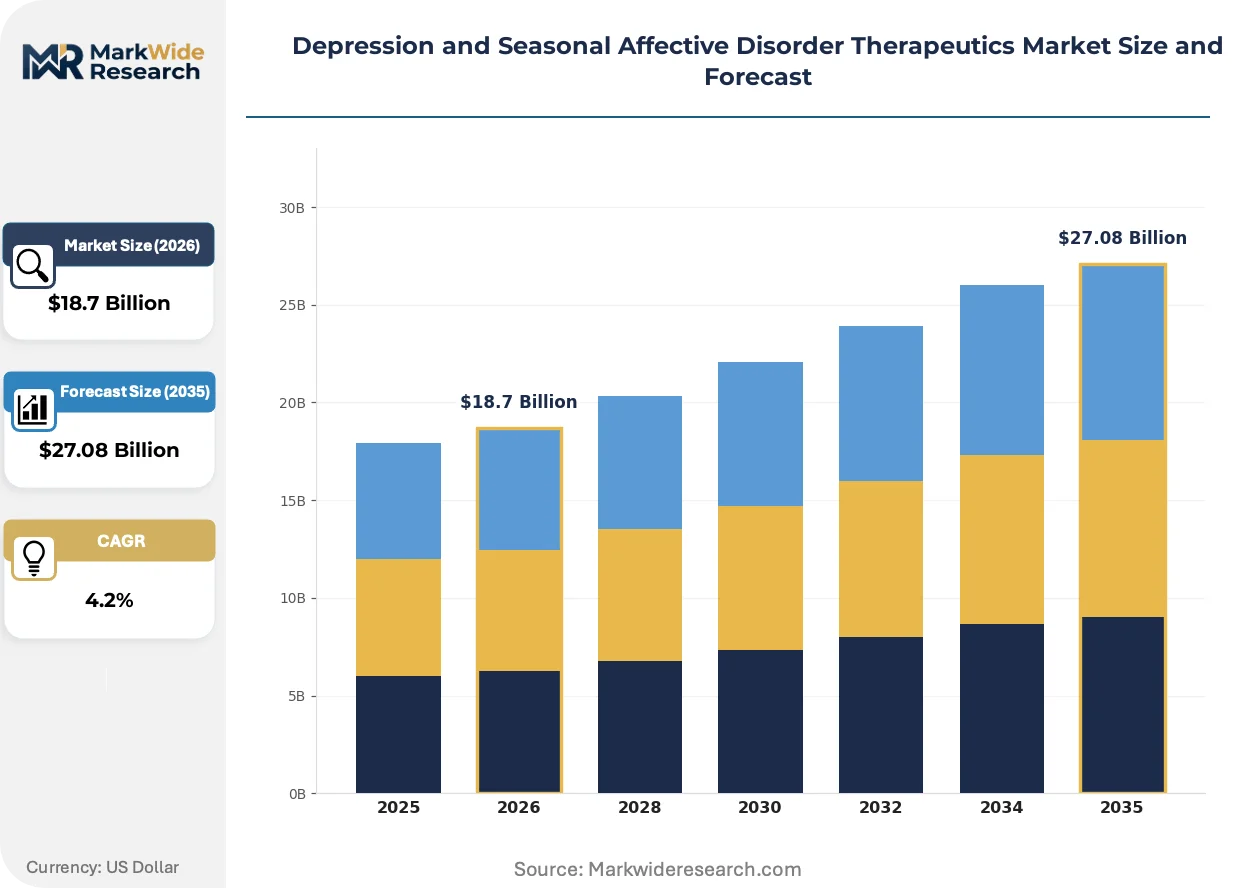
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Psychotherapy, Light Therapy, Lifestyle Modifications Delivery Mode: Oral, Injectable, Transdermal, Digital Therapies End User: Hospitals, Clinics, Homecare, Telehealth Services Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, Johnson & Johnson, GlaxoSmithKline, AbbVie Inc., Novartis AG, Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd., Otsuka Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Depression and Seasonal Affective Disorder Therapeutics Market Strategic Shifts
Biomarker-guided patient stratification and psychedelic-derived investigational programs are restructuring clinical trial design and site-of-care economics across the depression therapeutics landscape.
Machine learning algorithms analyzing electroencephalographic signatures and inflammatory biomarkers are rendering obsolete the trial-and-error antidepressant selection paradigm that dominated psychiatric practice for decades. Academic medical centers and large multi-site psychiatric clinics are deploying these platforms to compress time-to-remission metrics. The technology is rendering obsolete the six-to-eight-week response assessment windows that previously determined formulary positioning.
EMA's PRIME eligibility criteria for psychiatric medicines now explicitly incorporate patient-reported outcome measures and digital endpoint validation, shifting regulatory precedent toward real-world evidence acceptance. This policy evolution enables adaptive licensing pathways that permit post-approval dose optimization studies. Small-to-mid-cap developers with novel mechanisms are restructuring European filing strategies to prioritize these accelerated assessment frameworks.
Employer health plans and behavioral health carve-out vendors are unbundling traditional episode-based reimbursement into per-member-per-month capitation models for depression management. This purchasing shift concentrates volume with integrated care organizations capable of demonstrating remission-rate performance guarantees. The transformation is most visible in United States commercial markets where large self-insured employers direct specialty pharmacy and digital therapeutic procurement through consolidated vendor relationships.
Depression and Seasonal Affective Disorder Therapeutics Market Segmentation
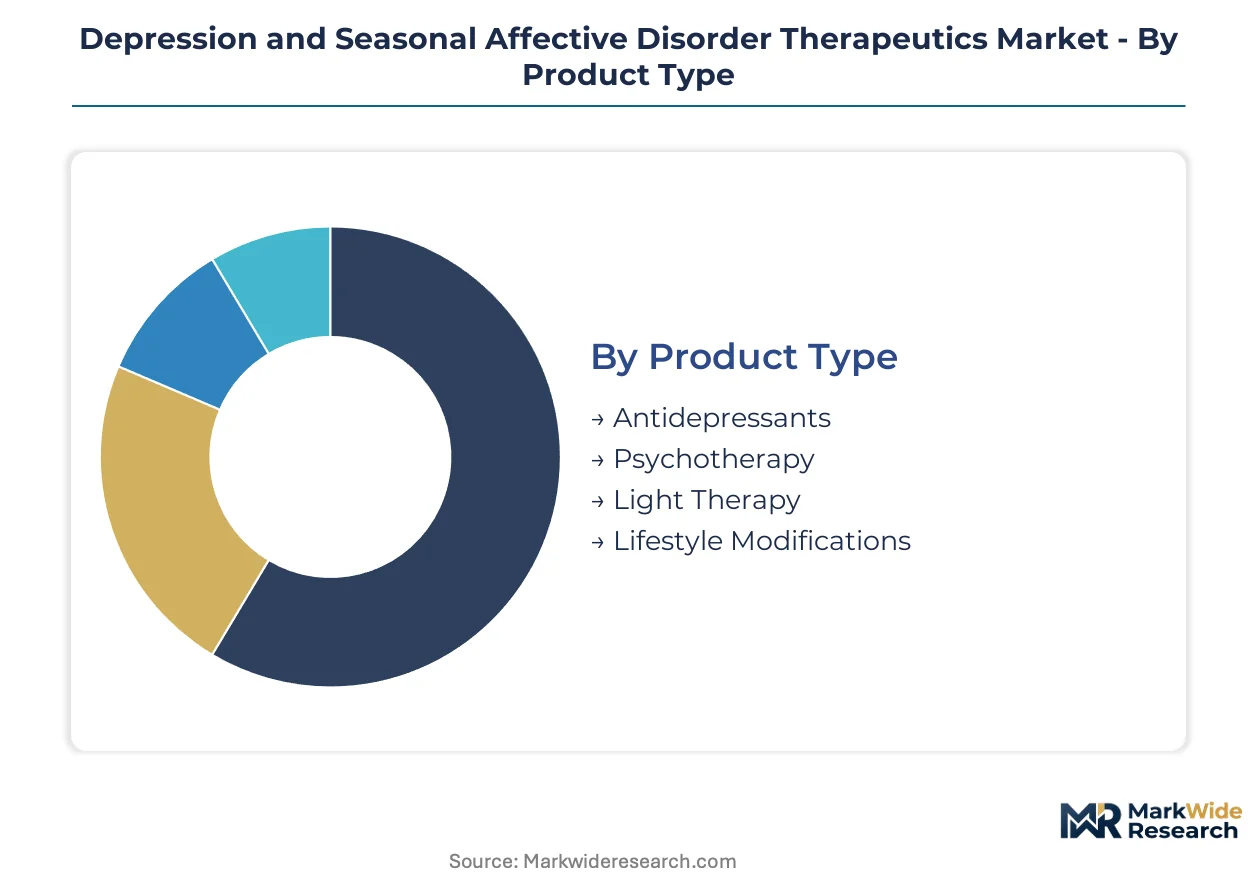
Depression and Seasonal Affective Disorder therapeutics fragment across pharmacological, device-based, and behavioral intervention modalities. Each segment carries distinct reimbursement codes, site-of-care economics, and regulatory pathways that shape commercial strategy.
Product Type:
Antidepressants span SSRIs, SNRIs, atypical agents, and emerging rapid-acting formulations for acute suicidal ideation. Psychotherapy protocols include cognitive behavioral therapy, interpersonal therapy, and dialectical behavior therapy delivered through licensed practitioners. Light therapy employs calibrated 10,000-lux panels for circadian phase shifting in seasonal depression. Lifestyle modifications encompass sleep hygiene coaching, exercise prescription, and nutritional psychiatry interventions.
- Antidepressants:Oral tablets and long-acting injectables modulate monoaminergic neurotransmission through serotonin, norepinephrine, and dopamine receptor targets. Demand concentrates in United States specialty psychiatric clinics where FDA breakthrough therapy designations for treatment-resistant depression accelerate formulary access.
- Psychotherapy:Structured talk therapy protocols delivered by licensed psychologists and clinical social workers address cognitive distortions and behavioral activation deficits. United States employer-sponsored health plans are expanding per-session reimbursement caps as digital delivery platforms achieve parity credentialing.
- Light Therapy:Calibrated full-spectrum emission panels for home deployment entrain circadian rhythms in latitudes with pronounced winter photoperiod reduction.
- Lifestyle Modifications:Sleep-wake scheduling, physical activity protocols, and omega-3 supplementation adjuncts prescribed as augmentation strategies.
The dominant share belongs to Antidepressants, while Psychotherapy is closing the gap fastest as value-based care contracts emphasize remission-rate performance guarantees.
Delivery Mode:
Route of administration determines pharmacokinetic profiles, patient adherence patterns, and site-of-care requirements across the therapeutic continuum.
- Oral:Immediate-release and extended-release tablets dominate first-line prescribing through primary care channels. United States retail pharmacy networks maintain 90-day supply programs for maintenance-phase selective serotonin reuptake inhibitors.
- Injectable:Intramuscular depot formulations and intravenous ketamine-derived protocols target treatment-resistant populations requiring supervised administration. Hospital outpatient departments with DEA Schedule III licensing control site-of-care expansion for esketamine protocols.
- Transdermal:Patch-based monoamine oxidase inhibitors and hormone-modulating delivery systems bypass first-pass hepatic metabolism.
- Digital Therapies:FDA-cleared prescription software applications deliver cognitive behavioral therapy modules through smartphone interfaces with clinician dashboard oversight.
Injectable formats command premium reimbursement in hospital-based settings, though Digital Therapies are expanding most quickly through direct-to-employer contracting channels.
End User:
Care setting selection depends on illness severity, intervention invasiveness, and reimbursement infrastructure maturity.
- Hospitals:Inpatient psychiatric units and emergency departments manage acute suicidal ideation, catatonia, and medication-resistant depressive episodes requiring electroconvulsive therapy or intravenous ketamine protocols.
- Clinics:Freestanding psychiatric practices and community mental health centers deliver outpatient medication management and psychotherapy with transcranial magnetic stimulation capability.
- Homecare:Visiting nurse services administer long-acting injectable antipsychotic-antidepressant combinations and monitor phototherapy compliance in homebound seniors.
- Telehealth Services:Asynchronous and synchronous virtual platforms extend psychiatrist workforce reach into rural and semi-urban regions with specialist scarcity.
Clinics capture the highest procedure volume for interventional psychiatry, yet Telehealth Services are gaining share fastest through CMS expanded reimbursement waivers.
Age Group:
Developmental stage dictates diagnostic criteria, pharmacokinetic considerations, and regulatory safeguards for investigational therapies.
- Adults:Ages 18-64 represent the core prescribing population with established diagnostic frameworks and broad formulary coverage across employer and Medicaid plans.
- Seniors:Patients over 65 require geriatric psychiatry expertise for polypharmacy management, cognitive safety monitoring, and vascular depression phenotyping.
- Adolescents:Ages 12-17 face FDA boxed warning considerations for antidepressant-associated suicidality and mandatory risk mitigation strategies.
- Children:Pediatric depression protocols emphasize family-based interventions with restricted pharmacologic options pending pediatric-specific trial data.
Adults retain the largest treated population, though Seniors are climbing the fastest as aging demographics expand the 65-plus cohort with late-onset depression and comorbid vascular pathology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of esketamine and neuromodulation devices concentrate in markets with mature psychiatric infrastructure, while export capacity for generic antidepressant APIs clusters in contract manufacturing hubs. Reimbursement heterogeneity creates divergent site-of-care economics across national health systems.
United States
Employer-sponsored health plans and Medicare Advantage contracts drive demand for digital therapeutics and interventional psychiatry. FDA breakthrough therapy designations for treatment-resistant depression accelerate formulary access timelines. The Boston-Cambridge corridor anchors psychedelic-derived investigational programs with academic medical center partnerships.
Germany
Statutory health insurance funds integrate neuromodulation services through ambulatory care reimbursement reform. EMA PRIME eligibility criteria compress assessment timelines for novel antidepressant mechanisms. The Rhine-Main cluster concentrates psychiatric digital health startups with BfArM fast-track approvals.
Japan
Aging demographics expand the late-onset depression patient pool with comorbid vascular pathology. PMDA Sakigake designation offers priority review for CNS candidates addressing unmet need. The Kanto region hosts translational psychiatry consortia linking university hospitals to pharmaceutical development.
United Kingdom
NHS England's mental health investment standard mandates community-based talking therapy access targets. NICE technology appraisals determine commissioning thresholds for digital therapeutics and device-based interventions. The Oxford-London corridor concentrates neuroimaging-guided biomarker research platforms.
India
Domestic formulation manufacturing supplies generic SSRI and SNRI exports to emerging markets. CDSCO accelerated approval pathways for orphan psychiatric indications attract multinational trial investment. The Hyderabad-Bengaluru corridor anchors contract research organizations with CNS therapeutic expertise.
Depression and Seasonal Affective Disorder Therapeutics Market Competitive Environment
On the supply side, the industry is consolidating around metabolic-psychiatry convergence and long-acting injectable platforms. Large-cap pharmaceutical developers anchor diversified neuroscience revenue through crossover pipelines spanning endocrinology and psychiatry. Mid-cap specialists occupy niche positions in neuromodulation hardware and prescription digital therapeutics. Competitive moves concentrate on portfolio diversification into device-drug combinations and strategic partnerships with telehealth infrastructure providers.
Within the metabolic-psychiatry archetype, Eli Lilly and Company represents the convergence strategy through glucagon-like peptide-1 receptor agonist crossovers. Pfizer Inc. exemplifies manufacturing-scale competition across oral and injectable antidepressant formats. Takeda Pharmaceutical Company Limited occupies a position specializing in Japanese-origin monoamine modulators with established Asian regulatory dossiers.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| Johnson & Johnson |
| GlaxoSmithKline |
| AbbVie Inc. |
| Novartis AG |
| Takeda Pharmaceutical Company Limited |
| Teva Pharmaceutical Industries Ltd. |
| Otsuka Pharmaceutical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in DEA-licensed esketamine compounding facilities concentrates pricing power among hospital outpatient departments with Schedule III controlled substance licensing, forcing developers to absorb site-of-care premiums or abandon clinic expansion strategies entirely. This utilization squeeze simultaneously elevates input costs for generic antidepressant APIs and compresses margins on digital therapeutic subscriptions competing for employer formulary slots.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture FDA breakthrough therapy designations and long-acting injectable formats with hospital outpatient administration requirements, while standard tiers cover oral SSRI maintenance prescriptions through retail pharmacy networks. Price differentiation rests on DEA licensing status and reimbursement code density rather than manufacturing cost alone. Cost compression in the economy tier intensifies because Indian and Chinese API manufacturers expand generic SSRI export capacity. Medicaid programs and self-insured employers exhibit highest price sensitivity, whereas specialty psychiatric clinics with value-based contracts demonstrate lowest sensitivity due to outcome-based reimbursement guarantees.
Supply Chain Analysis
Upstream ketamine precursor chemicals flow from India, China, and select European contract manufacturers under international narcotics control conventions. Active pharmaceutical ingredients for oral antidepressants draw from Hyderabad-Bengaluru API clusters and Zhejiang province manufacturing hubs, with finished dose formulation concentrated in United States and European Union GMP-certified facilities. Single-source vulnerability pervades the esketamine supply chain where DEA quota allocations restrict domestic manufacturing expansion. Distribution runs through specialty pharmacy channels for controlled substances and direct-to-clinic logistics for neuromodulation hardware, with digital therapeutics bypassing physical supply chains entirely through prescription software platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as FDA breakthrough device designations for digital therapeutics accumulate and employer-sponsored health plans pilot standalone reimbursement outside traditional pharmacy benefit managers. Penetration tailwinds from metabolic-psychiatry convergence and long-acting injectable adoption create multiple entry vectors for differentiated competitors.
For Market Incumbents: Pre-empt biosimilar encroachment on oral antidepressant franchises by accelerating metabolic-psychiatry crossover pipeline investments and securing DEA-licensed site-of-care partnerships for esketamine-derived protocols. Vertical integration into digital therapeutic platforms defends against formulary displacement as employer contracts unbundle traditional episode-based reimbursement into per-member-per-month capitation models. For New Entrants and Emerging Players: Establish a beachhead in prescription digital therapeutics for seasonal affective disorder, where photoperiodic intervention protocols face lighter regulatory scrutiny than pharmacologic candidates and direct-to-payer contracting channels bypass entrenched pharmacy benefit manager relationships. Target northern latitude markets with pronounced winter photoperiod reduction and employer populations with established behavioral health carve-out vendors. For Investors and Strategic Acquirers: Capital is best deployed toward neuromodulation hardware specialists with portable transcranial magnetic stimulation platforms and FDA breakthrough device designations, positioned for outpatient clinic penetration with reduced capital requirements. Long-term viability over the five-to-ten year horizon hinges on reimbursement infrastructure maturation for interventional psychiatry services. Monitor CMS national coverage determination patterns for esketamine and transcranial magnetic stimulation as the critical inflection signal for site-of-care economics expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Breakthrough Therapy Designation Pursuit | FDA accelerated review compresses development timelines for treatment-resistant depression candidates targeting serotonin receptor subtypes. |
| Digital Therapeutic FDA Submission | Prescription software applications with clinician dashboard oversight unlock direct-to-employer contracting outside pharmacy benefit managers. |
| DEA Schedule III Licensing Expansion | Controlled substance procurement authorization enables hospital outpatient department site-of-care economics for esketamine protocols. |
| Metabolic-Psychiatry Pipeline Diversification | Glucagon-like peptide-1 receptor agonist crossovers leverage existing endocrinology infrastructure for depression screening expansion. |
| Neuromodulation Device CE Marking | EMA MDR compliance opens ambulatory care reimbursement pathways through German statutory health insurance fund integration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at major payers, and hospital procurement managers specializing in psychiatric services. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov protocol registries, and CMS national coverage determination records. Bottom-up prescription volume modeling and top-down therapeutic class revenue estimates were triangulated against hospital procurement database benchmarks.
Calibration against historical antidepressant launch trajectories and digital therapeutic adoption curves informed the analytical framework across the projection horizon. Segmentation dimensions encompassed treatment line, dosage form, administration route, patient population severity, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year estimates, with specific inputs including DEA controlled substance scheduling decisions, employer-sponsored health plan behavioral health carve-out penetration rates, and specialty psychiatric clinic expansion metrics.
Sensitivities concentrate around DEA quota allocation revisions, CMS national coverage determination delays for interventional psychiatry, and psychedelic compound rescheduling timelines that could accelerate or compress investigational access frameworks. Cross-checking against IQVIA prescription audit data and Definitive Healthcare facility infrastructure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
Mycoses Treatment Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Analgesics Market
Pharmaceuticals
Drug Designing Tools Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market