
 Burkholderia Infections Market | 2026-2036
Burkholderia Infections Market Size, Share, and Industry Trends Forecast 2026-2036
Burkholderia Infections Market Analysis
Polymyxin B is decoupling from first-line treatment protocols as nephrotoxicity concerns reshape product economics across the Burkholderia cepacia complex space. Pfizer Inc. leverages its established anti-infective manufacturing scale to sustain supply chain reliability for hospital formularies. Merck & Co., Inc. anchors its position through deep R&D investment in novel mechanism antimicrobials against multidrug-resistant gram-negative pathogens. Novabiotics Ltd. specializes in liposome-encapsulated formulations that differentiate its pipeline from conventional antibiotic delivery.
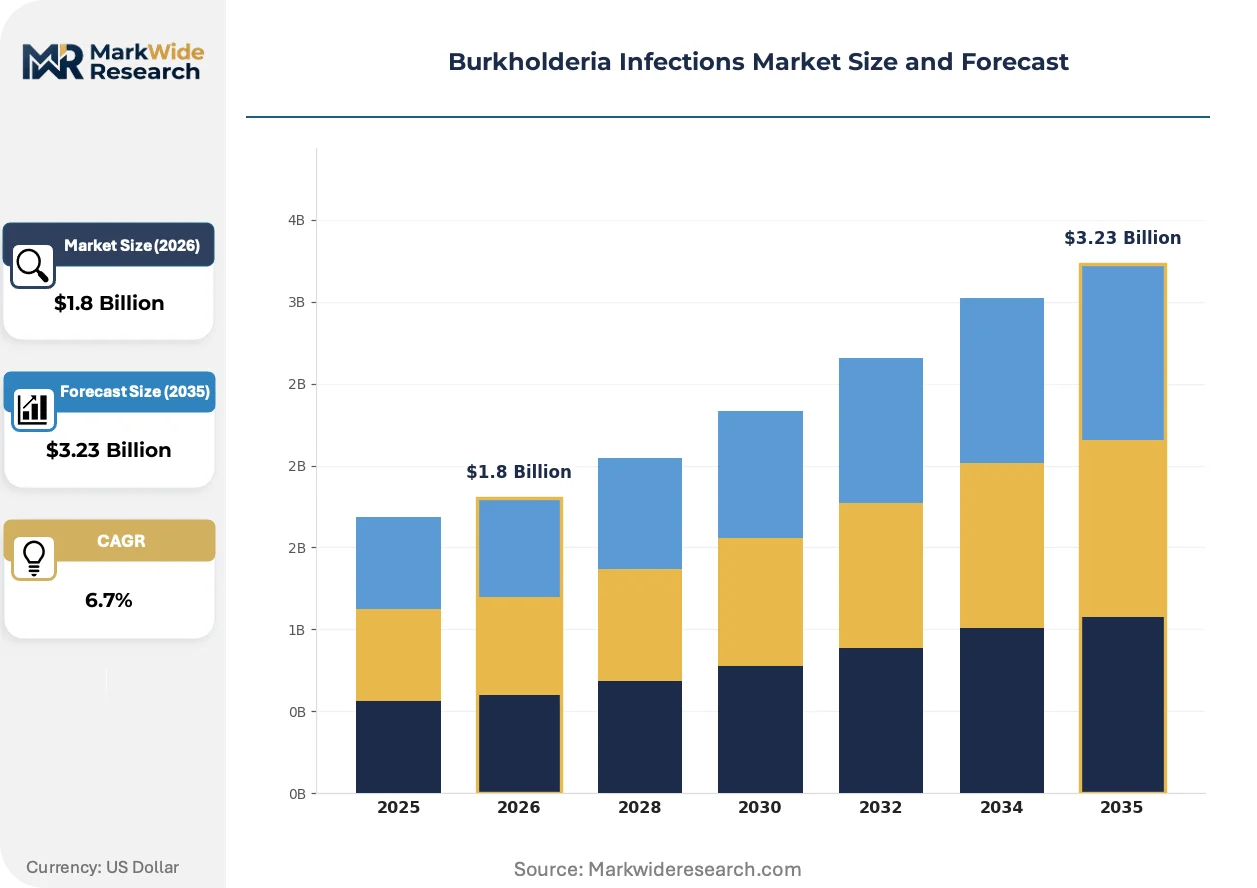
Burkholderia infections encompass a spectrum of clinical syndromes caused by Burkholderia cepacia complex and Burkholderia pseudomallei, requiring precise species identification via biochemical profiling or molecular methods due to intrinsic resistance to multiple antibiotic classes. These pathogens primarily threaten immunocompromised hosts, cystic fibrosis patients, and individuals in endemic tropical regions, driving demand for rapid diagnostics and targeted therapeutics. The antibiotics segment dominates current revenue as clinicians confront rising carbapenem resistance, while the diagnostics category captures accelerating growth from PCR-based and MALDI-TOF platform expansion in hospital laboratories. Intravenous delivery maintains the largest share due to severity of bloodstream and pneumonia presentations, though inhaled formulations are gaining traction for chronic respiratory colonization management.
The FDA's Qualified Infectious Disease Product program and EMA's PRIME designation framework shape development incentives, accelerating market access for novel therapies targeting priority pathogens. BIS standards in India and CDSCO manufacturing compliance requirements further define quality benchmarks for regional suppliers seeking hospital procurement contracts. Stakeholders must monitor antimicrobial stewardship mandates and resistance surveillance networks to align portfolio investments with evolving treatment guidelines and reimbursement criteria.
Market Dynamics
Carbapenem resistance rates in Burkholderia cepacia complex isolates are forcing hospital antimicrobial stewardship committees to restrict empiric polymyxin use and demand rapid species identification, compressing diagnostic turnaround windows from 48 hours toward 4-hour molecular targets.
Growth Catalysts
- FDA Qualified Infectious Disease Product designation:This framework accelerates review timelines and extends market exclusivity for novel antibiotics targeting priority gram-negative pathogens, drawing venture capital into early-stage development programs.
- Cystic fibrosis patient registries:Coordinated surveillance networks in the United States and United Kingdom generate real-world epidemiology data that shapes payer coverage decisions and hospital formulary placement for chronic suppressive therapies.
- PCR-based bloodstream pathogen detection:FilmArray and similar multiplex platforms reduce time-to-identification from days to hours, enabling targeted therapy initiation and supporting diagnostic test menu expansion in tertiary care centers.
Market Restraints
- Polymyxin manufacturing concentration:Active pharmaceutical ingredient production for polymyxin B and colistin concentrates in Chinese and Indian chemical synthesis facilities, exposing supply chains to environmental compliance shutdowns and export restriction volatility.
- Nephrotoxicity liability thresholds:FDA boxed warnings and EMA renal monitoring requirements elevate clinical trial costs and post-market surveillance burdens for developers pursuing polymyxin-based combination regimens.
- Intrinsic efflux pump expression:Burkholderia species harbor multiple resistance-nodulation-division efflux systems that limit intracellular accumulation of tetracyclines and fluoroquinolones, constraining oral step-down options and prolonging intravenous therapy duration.
Strategic Opportunities
- Melioidosis endemic expansion:Climate-driven range extension of Burkholderia pseudomallei into northern Australia and southern China creates demand for point-of-care diagnostics and vaccine development partnerships with tropical medicine institutes.
- Inhaled liposomal formulation delivery:Nebulized antibiotic deposition directly to infected airspaces offers pharmacokinetic advantages over systemic dosing for chronic respiratory colonization in cystic fibrosis populations.
- Biodefense procurement mechanisms:BARDA and equivalent agencies in the United Kingdom and Australia maintain stockpiling contracts for melioidosis countermeasures, providing non-commercial revenue streams independent of hospital antibiotic purchasing cycles.
Industry Challenges
- Reference laboratory capacity constraints:Accurate speciation within the Burkholderia cepacia complex requires specialized biochemical profiling and 16S rRNA sequencing expertise that concentrates in regional public health laboratories, creating diagnostic backlogs during outbreak investigations.
- Antimicrobial stewardship audit complexity:Hospital pharmacy and infectious disease departments must reconcile pre-emptive broad-spectrum coverage with de-escalation protocols, requiring integrated electronic health record decision support that few institutions have fully deployed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burkholderia Infections Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Diagnostics, Therapeutics Application: Hospital Acquired Infections, Pneumonia, Bloodstream Infections, Wound Infections Delivery Mode: Intravenous, Oral, Intramuscular, Inhalation End User: Hospitals, Clinics, Research Laboratories, Homecare |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline plc, Johnson & Johnson, Novartis AG, Sanofi S.A., Novabiotics Ltd., Aridis Pharmaceuticals LLC, iQur Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burkholderia Infections Market Emerging Trajectories
Whole-genome sequencing is compressing the timeline from pathogen isolation to resistance profiling, while regulatory incentives and diagnostic platform miniaturization reshape how developers prioritize indications and commercialization pathways.
MALDI-TOF mass spectrometry is unifying bacterial identification and antimicrobial resistance marker detection into single-workflow platforms. Hospital microbiology laboratories in the United States and Germany are replacing biochemical panel systems with Bruker and bioMérieux instruments that reduce technologist hands-on time. This convergence is compressing capital equipment procurement cycles and favoring vendors with integrated antibiotic susceptibility testing modules.
The FDA's Limited Population Pathway for Antibacterial and Antifungal Drugs creates streamlined approval routes for pathogens with documented resistance patterns. Developers targeting Burkholderia pseudomallei leverage smaller trial datasets and alternative endpoints to reach market faster than under traditional superiority trial designs. Southeast Asian regulatory authorities are aligning with FDA precedent to accelerate national registration of melioidosis therapeutics.
Hospital procurement committees now require pharmacoeconomic modeling for formulary inclusion of novel antibiotics against resistant gram-negatives. Payers in France and the United Kingdom demand standardized quality-of-life outcome measures that extend beyond 30-day mortality to capture long-term pulmonary function in cystic fibrosis patients. This behavioral shift elevates real-world evidence generation requirements and reshapes contract structures toward outcomes-linked rebates rather than volume-based purchasing.
Burkholderia Infections Market Segmentation
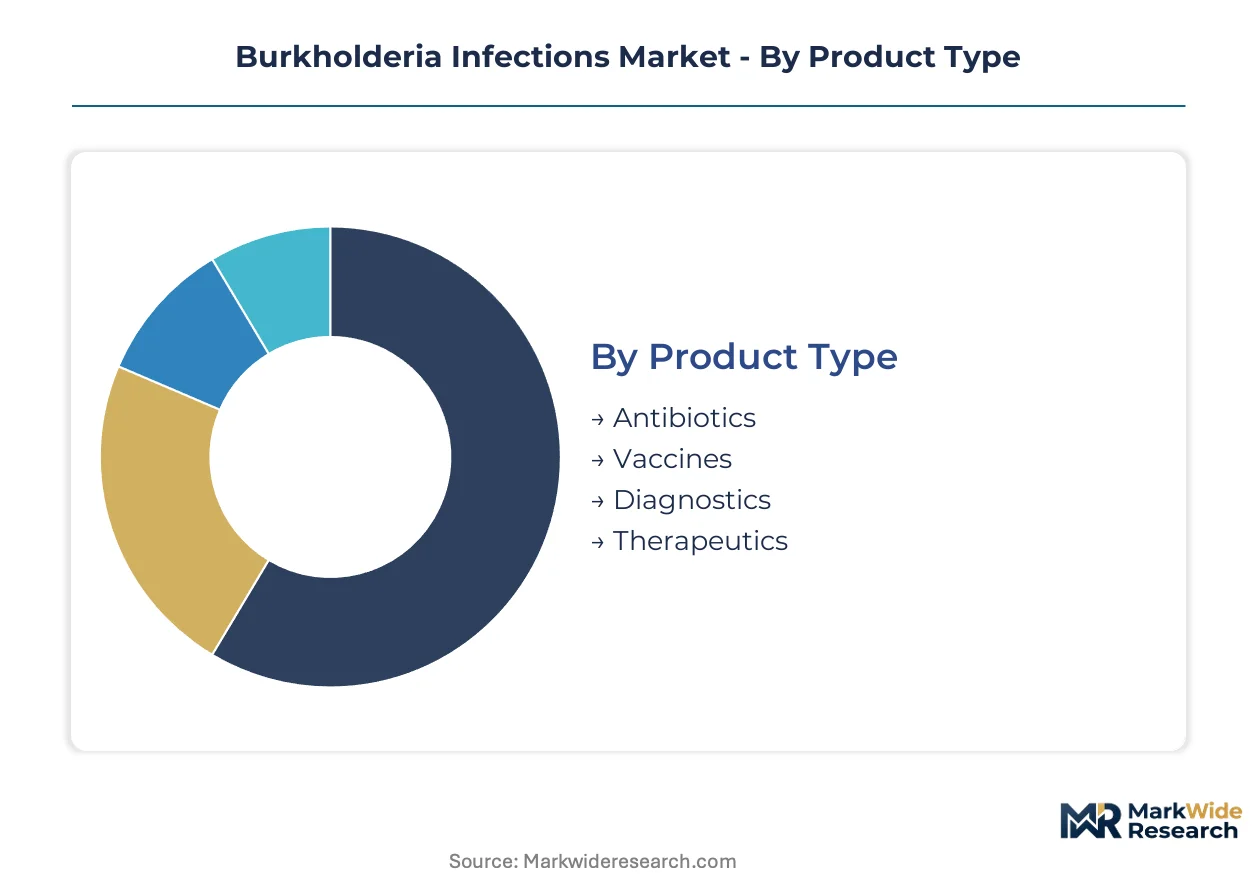
Segmentation in the Burkholderia infections space reflects divergent clinical workflows across acute care and chronic management settings. Hospital procurement committees evaluate products through distinct lenses—diagnostic turnaround time, antibiotic stewardship compliance, and route-of-administration flexibility for cystic fibrosis populations.
Product Type:
Upgrade cycles in this category accelerate as resistance profiles shift and regulatory pathways reward novel mechanisms over incremental improvements.
- Antibiotics:Carbapenems, polymyxins, and newer beta-lactam/beta-lactamase inhibitor combinations dominate hospital formularies. Demand concentrates in tertiary care centers managing multidrug-resistant Burkholderia cepacia complex outbreaks, driven by FDA Qualified Infectious Disease Product incentives that compress development timelines.
- Diagnostics:PCR-based platforms and MALDI-TOF mass spectrometry systems reduce identification time from days to hours. Adoption accelerates in United States and German hospital laboratories seeking to meet antimicrobial stewardship mandates for rapid species confirmation.
- Vaccines:Development programs target Burkholderia pseudomallei for melioidosis prevention in endemic regions. BARDA and equivalent biodefense agencies provide non-commercial funding streams.
- Therapeutics:Adjunctive therapies including immunomodulators and phage-based approaches occupy early-stage pipelines. Clinical validation remains limited relative to established antibiotic classes.
Antibiotics sit at the top of the volume ranking, with diagnostics climbing the fastest.
Application:
Cost tier differentiation separates emergency empiric therapy from targeted chronic suppression regimens.
- Hospital Acquired Infections:Burkholderia cepacia complex outbreaks in intensive care units and oncology wards drive demand for rapid diagnostics and combination antibiotic protocols. United States cystic fibrosis centers report colonization rates that shape formulary priorities.
- Pneumonia:Lower respiratory tract infections in immunocompromised hosts require prolonged intravenous courses. Inhaled antibiotic deposition is gaining pharmacokinetic validation for chronic respiratory management.
- Bloodstream Infections:Bacteremia presentations in melioidosis-endemic regions necessitate aggressive parenteral therapy. Diagnostic blood culture sensitivity limits remain a constraint.
- Wound Infections:Trauma-associated infections in tropical agriculture workers present diagnostic delays due to nonspecific clinical presentation. Point-of-care molecular testing penetration remains limited.
Pneumonia captures the largest addressable patient population, with hospital acquired infections expanding most quickly due to surveillance network expansion.
Delivery Mode:
Customer workflow integration determines adoption—hospital infusion centers prioritize reliability, while homecare settings demand portability.
- Intravenous:Continuous infusion pumps and elastomeric devices support prolonged beta-lactam administration in cystic fibrosis patients. United States home infusion providers are expanding service lines for chronic suppressive therapy.
- Inhalation:Nebulized liposomal formulations achieve direct airway deposition with reduced systemic exposure. Novabiotics and similar developers pursue cystic fibrosis-specific indications.
- Oral:Trimethoprim-sulfamethoxazole remains the primary oral option for melioidosis maintenance therapy. Intrinsic efflux pump expression in Burkholderia species limits fluoroquinolone utility.
- Intramuscular:Depot formulations for prophylactic or post-exposure indications occupy biodefense stockpiling discussions. Clinical validation for melioidosis remains incomplete.
Intravenous administration retains volume leadership, with inhalation gaining share fastest on cystic fibrosis chronic management validation.
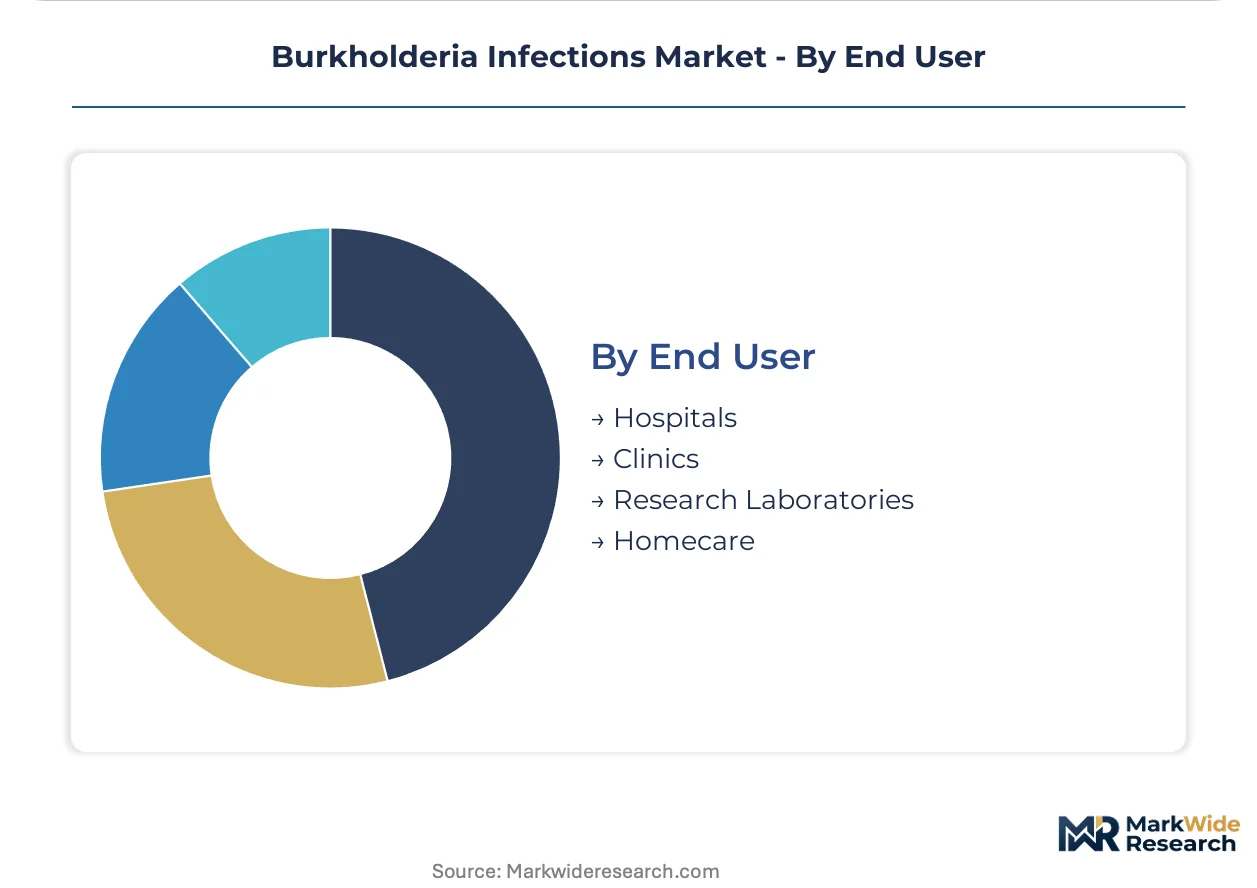
End User:
Supply concentration in reference laboratory services creates access tiering between academic medical centers and community hospitals.
- Hospitals:Antimicrobial stewardship committees in United States tertiary centers restrict polymyxin empiric use and mandate rapid diagnostic confirmation. EMA renal monitoring requirements elevate post-market surveillance burdens.
- Research Laboratories:Whole-genome sequencing capacity concentrates in regional public health laboratories and academic centers. Backlogs during outbreak investigations create diagnostic delays.
- Clinics:Outpatient cystic fibrosis programs in the United Kingdom and Australia coordinate chronic suppressive therapy delivery. Telemedicine integration supports adherence monitoring.
- Homecare:Home infusion nursing services enable prolonged intravenous antibiotic courses without hospitalization. Reimbursement variability across United States payers constrains uniform access.
Hospitals dominate procurement volume, with homecare demonstrating the steepest expansion trajectory on cost-containment and patient preference alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor anchors clinical development activity for Burkholderia therapeutics, with cystic fibrosis patient registries and biodefense procurement mechanisms creating concentrated demand pockets across distinct national healthcare systems.
United States
Cystic fibrosis centers in Boston and Chapel Hill drive diagnostic test validation and chronic suppressive therapy protocols. BARDA maintains stockpiling contracts for melioidosis countermeasures through the Strategic National Stockpile. The FDA's Qualified Infectious Disease Product designation accelerates review timelines for developers targeting priority gram-negative pathogens.
United Kingdom
National Health Service antimicrobial stewardship mandates compress diagnostic turnaround windows in London and Manchester tertiary centers. The UK Health Security Agency coordinates melioidosis surveillance through imported case monitoring. MHRA alignment with FDA Limited Population Pathway precedent streamlines national registration for novel antibiotics.
Australia
Melioidosis endemic expansion into northern Queensland and the Northern Territory creates demand for point-of-care diagnostics and vaccine partnerships with tropical medicine institutes in Darwin and Cairns. The Therapeutic Goods Administration fast-tracks registration for pathogens with documented resistance patterns. Commonwealth biodefense funding supports regional stockpiling independent of commercial purchasing cycles.
Germany
Hospital microbiology laboratories in Berlin and Munich adopt MALDI-TOF mass spectrometry platforms to reduce technologist hands-on time for species identification. EMA renal monitoring requirements for polymyxin-based regimens elevate post-market surveillance burdens. The German Center for Infection Research coordinates whole-genome sequencing capacity for outbreak investigations.
India
Polymyxin active pharmaceutical ingredient production concentrates in Hyderabad and Mumbai chemical synthesis facilities, exposing supply chains to environmental compliance shutdowns. CDSCO manufacturing compliance requirements define quality benchmarks for regional suppliers seeking hospital procurement contracts. BIS standards further shape diagnostic platform certification for import substitution.
Burkholderia Infections Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and R&D investment intensity. The vendor base separates into three tiers: diversified pharmaceutical conglomerates with established anti-infective divisions, mid-cap specialists pursuing novel mechanism antimicrobials, and platform-technology developers advancing liposome-encapsulated delivery systems. Consolidation pressures favor entities with integrated antibiotic susceptibility testing modules and hospital formulary relationships. Dominant competitive moves include strategic partnerships with biodefense agencies and geographic expansion into melioidosis-endemic regions.
Within the diversified pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. occupy positions defined by manufacturing scale and hospital supply chain reliability. Novabiotics Ltd. exemplifies the platform-technology archetype, with its UK-based structure signaling specialization in formulation differentiation. These three entities represent distinct strategic postures: scale-driven supply security, deep R&D investment in novel mechanisms, and delivery-system innovation for chronic respiratory indications.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Novartis AG |
| Sanofi S.A. |
| Novabiotics Ltd. |
| Aridis Pharmaceuticals LLC |
| iQur Ltd. |
| Others |
Supply Flow & Price Mechanics
Polymyxin API grade divergence separates hospital-grade formulations from research-use material, with FDA Qualified Infectious Disease Product certification creating a premium tier that commands supply chain prioritization from Hyderabad and Mumbai manufacturers. This bifurcation concentrates pricing power among CDSCO-compliant facilities while exposing non-certified producers to margin compression from environmental compliance costs and export restriction volatility.
Pricing Analysis
Active pharmaceutical ingredient cost pass-through from Indian and Chinese chemical synthesis facilities shapes contract structures for polymyxin B and colistin procurement. Three-tier pricing structure across QIDP-certified, standard pharmaceutical-grade, and research-use tiers reflects FDA renal monitoring compliance burdens and EMA post-market surveillance requirements. Pricing pressure stems from nephrotoxicity liability thresholds elevating clinical trial costs for combination regimens. Hospital antimicrobial stewardship committees exhibit highest price sensitivity for empiric therapy protocols, while biodefense procurement mechanisms demonstrate lowest sensitivity due to stockpiling mandates.
Supply Chain Analysis
Specialized fermentation technologist availability constraints in Hyderabad and Mumbai chemical corridors limit capacity expansion for lipopeptide antibiotic production. Active pharmaceutical ingredient manufacturing concentrates in India and China, with finished formulation processing distributed across United States and European packaging facilities. Raw material dependencies include soybean meal for fermentation media, specialized resins for chromatographic purification, and pyrogen-free water systems. Single-source vulnerability characterizes polymyxin B sulfate API supply due to manufacturing concentration in environmental compliance-sensitive zones. Distribution runs through hospital GPO contracts and national stockpiling agreements rather than wholesale pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where cystic fibrosis patient registry data and antimicrobial stewardship mandates are shifting procurement toward rapid diagnostic-therapeutic bundles with demonstrated pharmacoeconomic outcomes.
For Market Incumbents: Deepen backward integration into liposome-encapsulated formulation manufacturing to differentiate from commodity polymyxin suppliers facing nephrotoxicity liability thresholds. Expand captive supply of fermentation-derived APIs in CDSCO-compliant Indian facilities to buffer against environmental compliance shutdowns. Prioritize integrated antibiotic susceptibility testing modules that compress diagnostic turnaround windows for hospital formulary retention. For New Entrants and Emerging Players: Enter via point-of-care molecular diagnostics for melioidosis-endemic expansion zones in northern Australia and southern China where reference laboratory capacity constraints create diagnostic backlogs. Target cystic fibrosis homecare infusion services as the most penetrable segment, leveraging telemedicine integration for adherence monitoring. Pursue BARDA biodefense procurement mechanisms as a non-commercial revenue anchor independent of hospital purchasing cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing scale advantages intersect with FDA QIDP regulatory exclusivity periods. Five-to-ten year viability favors platform-technology developers with liposomal delivery differentiation over commodity antibiotic repricers. Acquisition target archetype: mid-cap specialists with novel mechanism antimicrobials against multidrug-resistant gram-negative pathogens and existing hospital formulary relationships. Watch FDA Limited Population Pathway approval velocity as inflection indicator for development-stage asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | QIDP designation accelerates review timelines for novel antibiotics against priority pathogens. |
| Regulatory Approval Pathway | Limited Population Pathway enables smaller trial datasets for Burkholderia pseudomallei indications. |
| Manufacturing Scale-Up | CDSCO-compliant API production secures hospital procurement contracts in Indian domestic market. |
| Pipeline Diversification | Inhaled liposomal formulations address chronic respiratory colonization in cystic fibrosis populations. |
| Strategic Partnership | BARDA stockpiling contracts provide non-commercial revenue independent of antibiotic purchasing cycles. |
Methodological Framework
Multiple input streams — infectious disease specialists at cystic fibrosis centers, hospital pharmacy and therapeutics committee members, regulatory affairs leads at anti-infective developers, and biodefense procurement officers — were reconciled against secondary validation from FDA QIDP designation records, EMA PRIME pathway submissions, ClinicalTrials.gov entries, and cystic fibrosis patient registry publications. Bottom-up triangulation across product-type segmentation and top-down cross-checks against national health expenditure patterns anchored volume and value estimates.
Data-stream reconciliation applied treatment line, administration route, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from segment-level growth rate synthesis and macro healthcare expenditure elasticity modeling. Forecast inputs incorporated antimicrobial stewardship mandate adoption curves and PCR-based diagnostic platform replacement cycles in tertiary care centers.
Inputs from FDA advisory committee transcripts and BARDA contract award announcements were available through the study window; gaps in real-world resistance surveillance network coverage introduce uncertainty bands around melioidosis-endemic region projections. Forecasts reflect documented assumptions regarding climate-driven range extension velocity and diagnostic platform miniaturization timelines. Material deviation in FDA approval velocity or polymyxin API manufacturing compliance enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Norovirus Infection Treatment Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Valley Fever Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Global Pelvic Inflammatory Disease Therapeutics Market
Infectious Disease
Varicella Zoster Infection Treatment Market
Infectious Disease
Efavirenz Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Arthropod Borne Viral Infections Market