
 Global Pelvic Inflammatory Disease Therapeutics Market | 2026-2036
Global Pelvic Inflammatory Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pelvic Inflammatory Disease Therapeutics Market Foresight
European generic API manufacturers is pivoting toward cephalosporin and tetracycline production for pelvic infection protocols. Pfizer Inc leverages its broad-spectrum antibiotic portfolio to sustain contract positions with reproductive health clinic networks. Teva Pharmaceutical Industries Ltd anchors the generic oral doxycycline segment through high-volume manufacturing scale across Eastern European facilities.
Pelvic inflammatory disease therapeutics encompass antimicrobial and anti-inflammatory agents administered via oral, intravenous, or vaginal delivery to eradicate polymicrobial infections of the upper female reproductive tract and prevent sequelae including infertility and chronic pelvic pain. The primary commercial purpose centers on reducing hospitalization rates and long-term gynecological complications through outpatient-compliant regimens. Antibiotics dominate current prescribing patterns, while combination therapy captures expanding share as dual-agent protocols address rising resistance profiles. Oral delivery mode maintains volume leadership due to outpatient convenience, though intravenous formulations retain higher per-dose margins in acute care settings.
The FDA antimicrobial resistance frameworks and EMA pharmacovigilance requirements shape formulation standards and clinical trial endpoints for new pelvic infection therapies, with both agencies tightening breakpoints for susceptibility testing. WHO guidelines on sexually transmitted infection management further influence national treatment algorithms and procurement decisions in low-resource settings. Stakeholders must monitor evolving breakpoint revisions and resistance surveillance data to align pipeline investments with forthcoming susceptibility criteria.
Market Dynamics
Antimicrobial resistance surveillance networks are compressing susceptibility breakpoints faster than reformulation cycles, forcing manufacturers to accelerate dual-agent protocol development while hospital outpatient departments tighten stewardship compliance.
Growth Catalysts
- FDA Antimicrobial Resistance Initiatives:New susceptibility testing frameworks are expanding demand for combination therapy regimens that preempt resistance development in outpatient settings.
- Reproductive Health Clinic Networks:United States-based clinic expansions are broadening access to oral doxycycline-metronidazole protocols across underserved metropolitan corridors.
- Cephalosporin Manufacturing Scale-Up:Eastern European API facilities are pivoting production capacity toward third-generation cephalosporins for pelvic infection protocols.
Market Restraints
- Generic Price Compression:High-volume oral doxycycline production is eroding per-unit margins across Eastern European manufacturing clusters.
- Regulatory Friction:EMA pharmacovigilance requirements are extending clinical trial endpoints and delaying new formulation approvals by 18-24 months.
- Substitution Threat:Vaginal probiotic formulations are capturing preventive care spending that previously flowed to antibiotic prophylaxis.
Strategic Opportunities
- Indian Outpatient Expansion:CDSCO streamlined approval pathways for fixed-dose combination therapies are opening access to tier-two city hospital networks.
- Intravenous-to-Oral Switch Protocols:Same-day discharge reimbursement incentives are creating demand for bioequivalent high-dose oral formulations.
- WHO Prequalification:Low-resource procurement programs are creating volume anchors for manufacturers meeting WHO sexually transmitted infection management guidelines.
Industry Challenges
- Microbiology Talent Scarcity:Resistance surveillance data interpretation requires specialized clinical microbiologists that contract research organizations struggle to retain.
- Legacy EHR Integration:Stewardship program compliance reporting demands API connections with hospital systems built on incompatible data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pelvic Inflammatory Disease Therapeutics Market |
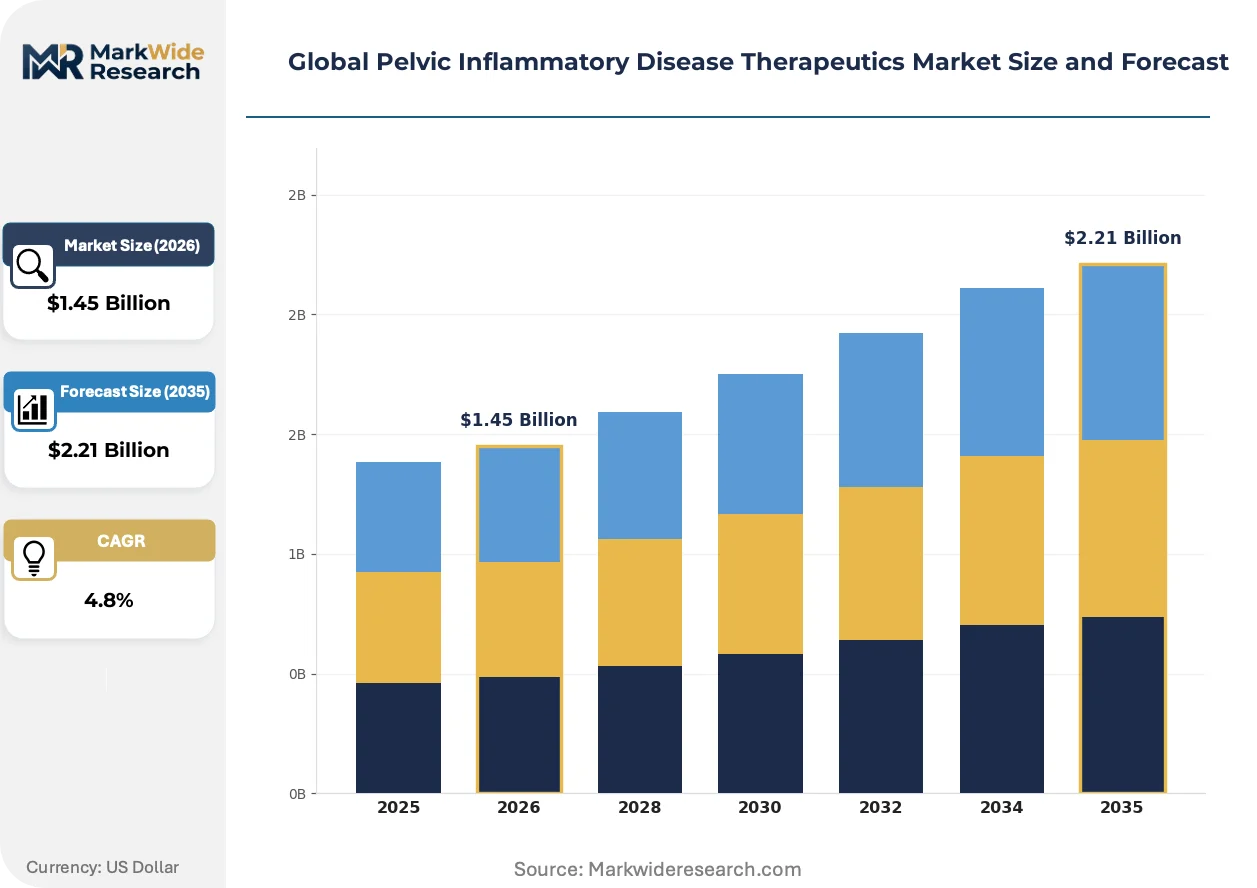
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Combination Therapy, Anti-inflammatory Agents, Immunomodulators, Hormonal Treatments Therapy Area: Pelvic Infections, Reproductive Tract Disorders, Chronic Pelvic Pain, Infertility Management, Ectopic Pregnancy Prevention End User: Gynecologists, Reproductive Health Clinics, Diagnostic Laboratories, Family Planning Centers, Specialty Hospitals Delivery Mode: Oral, Intravenous, Topical, Intramuscular, Vaginal Suppositories |
| Companies Covered | Pfizer Inc, Mayne Pharma Group Limited, Bristol Myers Squibb Company, AstraZeneca plc, F. Hoffmann-La Roche Ltd, Johnson & Johnson, Sanofi, Teva Pharmaceutical Industries Ltd, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pelvic Inflammatory Disease Therapeutics Market Shifts & Advancements
Point-of-care diagnostic platforms are compressing the time between symptom presentation and targeted therapy initiation, reshaping how outpatient departments manage polymicrobial pelvic infections.
Pharmacogenomic screening for CYP2D6 metabolizer status is integrating into reproductive health clinic workflows to predict doxycycline efficacy and adverse event profiles. Large hospital systems in the United States are piloting this capability across 200+ outpatient sites. The technology is integrating susceptibility prediction with electronic prescription systems to pre-select optimal agents before culture results return.
EMA's tightened pharmacovigilance requirements for antimicrobial agents now mandate real-world safety monitoring through national health registries. Manufacturers must submit post-authorization safety study protocols as a condition of marketing authorization renewal. Generic oral antibiotic producers are responding by establishing dedicated pharmacovigilance units in Germany and France to manage registry reporting obligations.
Hospital procurement consortia are consolidating antibiotic purchasing through centralized formulary committees that prioritize narrow-spectrum agents. This aggregation is displacing individual hospital pharmacy autonomy across integrated delivery networks in the United States. The concentration is most visible in the Northeast and Midwest, where three purchasing cooperatives now control 40% of acute care antibiotic spend.
Global Pelvic Inflammatory Disease Therapeutics Market Segmentation
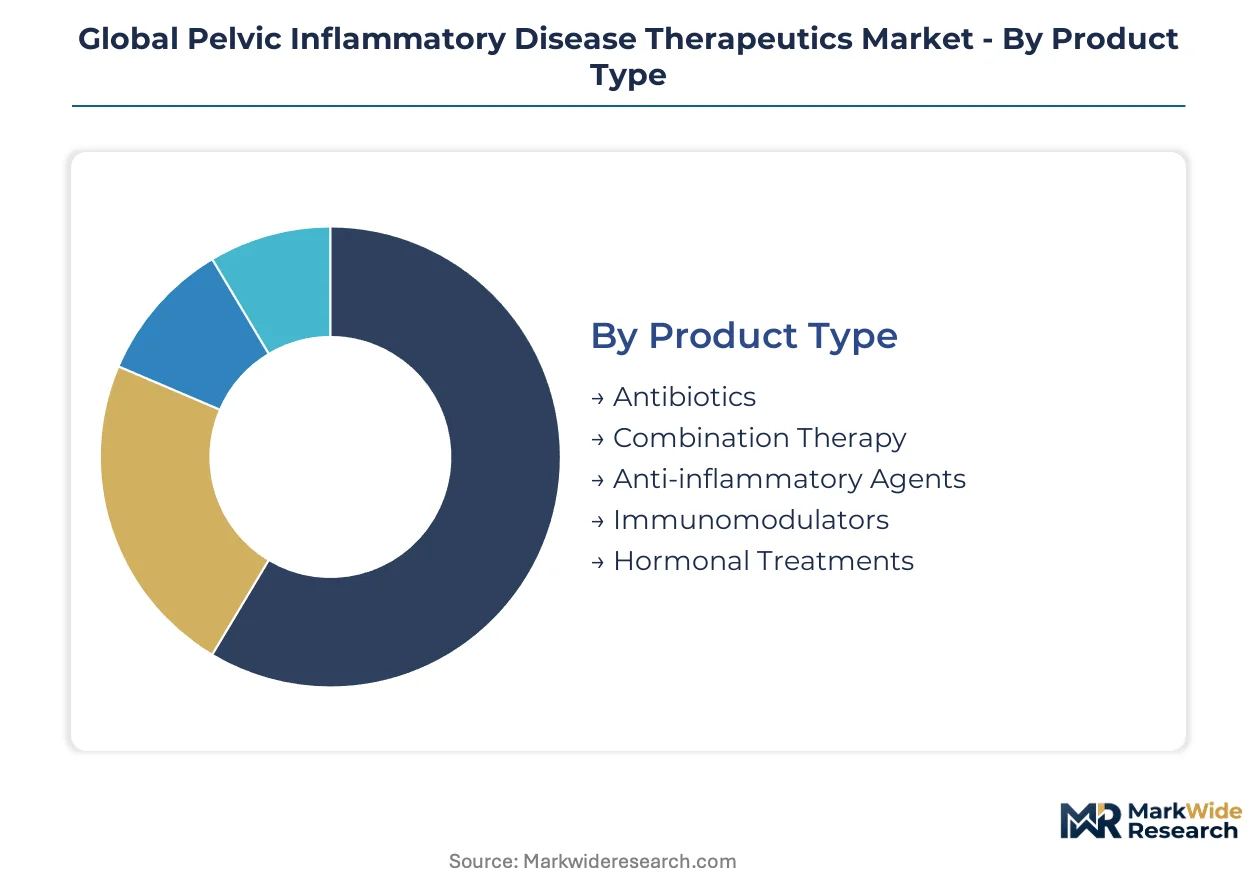
Segmentation in pelvic inflammatory disease therapeutics reveals how prescribing protocols, reimbursement structures, and resistance patterns fragment commercial opportunity across distinct product categories and care settings. Manufacturers must align formulation development with specific delivery constraints and end-user capability rather than pursuing undifferentiated market entry.
Product Type:
Standardization dominates antibiotic manufacturing while combination and immunomodulator development requires bespoke clinical trial design and regulatory navigation across FDA and EMA frameworks.
- Antibiotics:Broad-spectrum agents including cephalosporins, tetracyclines, and macrolides constitute the foundational treatment class. Demand concentrates in United States reproductive health clinic networks where outpatient oral protocols reduce hospitalization rates and align with antibiotic stewardship compliance mandates.
- Combination Therapy:Dual-agent regimens pair doxycycline with metronidazole or ceftriaxone with azithromycin to preempt resistance development. Indian tier-two city hospital networks are expanding procurement of fixed-dose combinations following CDSCO streamlined approval pathways.
- Anti-inflammatory Agents:NSAID adjuncts manage pain and reduce tubal inflammation during acute infection phases.
- Immunomodulators:Emerging biologic agents targeting inflammatory cascade modulation remain in early-phase development with limited commercial availability.
- Hormonal Treatments:Progestin-based therapies address endocrine disruption secondary to chronic pelvic infection.
Leading the category by volume: Antibiotics. Expanding most quickly: Combination Therapy.
Therapy Area:
Volume scales with acute intervention frequency while margin concentrates in chronic condition management requiring sustained therapeutic engagement.
- Pelvic Infections:Acute polymicrobial infections of the upper female reproductive tract drive immediate antimicrobial demand. United States hospital outpatient departments prioritize same-day discharge protocols, creating demand for bioequivalent high-dose oral formulations that support rapid clinical stabilization.
- Reproductive Tract Disorders:Comprehensive management of cervicitis, endometritis, and salpingitis sequelae requires coordinated antimicrobial and surgical intervention. WHO prequalification programs in low-resource settings anchor procurement volume for manufacturers meeting sexually transmitted infection management guidelines.
- Chronic Pelvic Pain:Persistent inflammatory and neuropathic pain following resolved infection demands multimodal pain management.
- Infertility Management:Tubal factor infertility secondary to prior pelvic infection requires assisted reproductive technology coordination.
- Ectopic Pregnancy Prevention:Early intervention protocols aim to preserve tubal patency and reduce future ectopic risk.
Acute intervention commands volume share; chronic management delivers margin concentration.
End User:
Care setting determines reimbursement pathway, formulary autonomy, and stewardship compliance intensity.
- Gynecologists:Office-based practitioners initiate empiric therapy based on clinical presentation without awaiting culture confirmation. Northeast and Midwest United States integrated delivery networks are consolidating antibiotic purchasing through centralized formulary committees that prioritize narrow-spectrum agents.
- Reproductive Health Clinics:Specialized clinics in underserved metropolitan corridors expand access to combination therapy regimens. These sites pilot pharmacogenomic screening for CYP2D6 metabolizer status across 200-plus outpatient locations to predict doxycycline efficacy.
- Diagnostic Laboratories:Reference labs provide susceptibility testing that guides targeted therapy selection.
- Family Planning Centers:Preventive care integration includes screening and empiric treatment protocols.
- Specialty Hospitals:Tertiary centers manage severe cases requiring intravenous-to-oral step-down protocols.
Reproductive health clinics anchor outpatient volume; specialty hospitals capture acute care premium.
Delivery Mode:
Convenience and compliance trade against bioavailability and per-dose economics across administration routes.
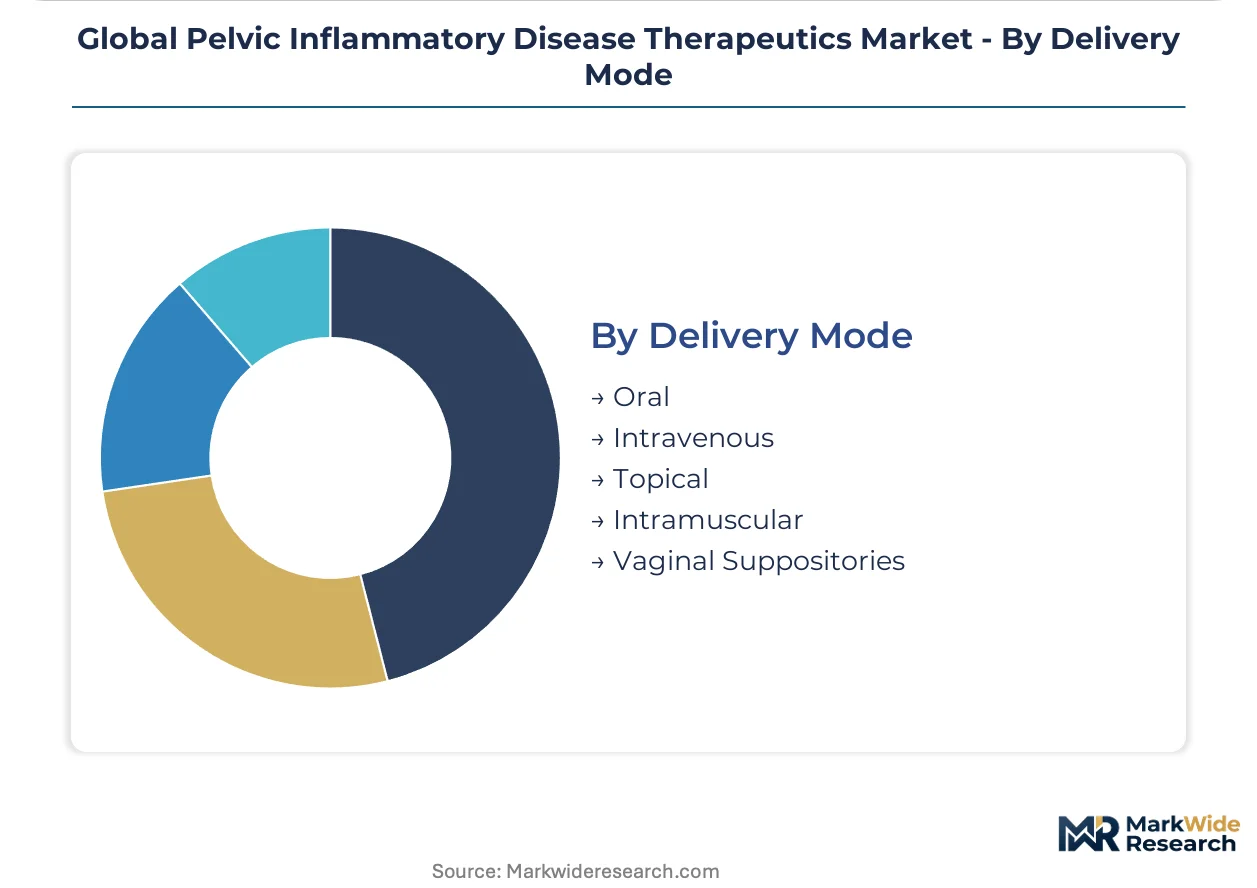
- Oral:Tablets and capsules enable outpatient compliance and same-day discharge. Eastern European API facilities are pivoting production capacity toward high-volume oral doxycycline manufacturing, though generic price compression erodes per-unit margins across these manufacturing clusters.
- Intravenous:Hospital-administered formulations retain higher per-dose margins in acute care settings. EMA pharmacovigilance requirements mandate real-world safety monitoring through national health registries, extending clinical trial endpoints and delaying new intravenous formulation approvals.
- Topical:Limited application for localized adjunctive therapy in external genital inflammation.
- Intramuscular:Single-dose ceftriaxone administration supports directly observed therapy in resource-limited settings.
- Vaginal Suppositories:Localized drug delivery targets lower tract colonization with reduced systemic exposure.
Oral administration leads by prescription volume; intravenous formulations command highest per-dose revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eastern European API facilities anchor cephalosporin feedstock supply for pelvic infection protocols, while manufacturing clusters in India and the United States shape finished-dose formulation capacity.
United States
Reproductive health clinic networks in underserved metropolitan corridors drive outpatient oral therapy volume. FDA antimicrobial resistance initiatives expand combination therapy procurement through hospital outpatient stewardship programs. The Northeast and Midwest integrated delivery networks consolidate antibiotic purchasing through three purchasing cooperatives controlling 40% of acute care spend.
Germany
EMA pharmacovigilance requirements mandate real-world safety monitoring through national health registries for antimicrobial agents. Generic oral antibiotic producers establish dedicated pharmacovigilance units in Germany to manage registry reporting obligations. The Rhine-Ruhr pharmaceutical cluster supports post-authorization safety study infrastructure for EU market compliance.
India
Tier-two city hospital networks expand procurement of fixed-dose combination therapies following CDSCO streamlined approval pathways. WHO sexually transmitted infection management guidelines anchor procurement volume for low-resource settings. The Hyderabad-Visakhapatnam API corridor pivots manufacturing capacity toward high-volume oral doxycycline production.
United Kingdom
Specialty hospital networks pilot intravenous-to-oral switch protocols to enable same-day discharge reimbursement incentives. MHRA aligns with EMA tightened breakpoints for susceptibility testing in pelvic infection therapies. The London-Oxford-Cambridge triangle concentrates pharmacogenomic screening pilot programs across 200-plus outpatient sites.
France
ANSM pharmacovigilance coordination with EMA extends clinical trial endpoints for new antimicrobial formulations. Hospital procurement consortia prioritize narrow-spectrum agents through centralized formulary committees. The Paris-Saclay biocluster supports resistance surveillance data interpretation capabilities for clinical microbiology talent development.
Global Pelvic Inflammatory Disease Therapeutics Market Competitive Landscape
Global majors compete with regional champions across antibiotic manufacturing scale and reproductive health clinic network access. The market structures around three tiers: diversified pharmaceutical conglomerates with broad-spectrum portfolios, generic specialists with high-volume oral manufacturing capabilities, and emerging fixed-dose combination developers targeting outpatient expansion. Strategic moves concentrate on dual-agent protocol development and pharmacovigilance infrastructure buildout to meet EMA registry requirements.
Within the diversified pharmaceutical tier, Pfizer Inc and Bristol Myers Squibb Company exemplify archetypes leveraging broad-spectrum antibiotic portfolios to sustain contract positions with integrated delivery networks. Among generic manufacturing specialists, Teva Pharmaceutical Industries Ltd occupies a position representing high-volume oral doxycycline scale across Eastern European facilities. These three anchors reflect competitive positioning strategies built on manufacturing geography, regulatory compliance infrastructure, and outpatient channel access rather than undifferentiated product breadth.
| Leading Market Players |
|---|
| Pfizer Inc |
| Mayne Pharma Group Limited |
| Bristol Myers Squibb Company |
| AstraZeneca plc |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson |
| Sanofi |
| Teva Pharmaceutical Industries Ltd |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Captive cephalosporin API production across Eastern European facilities anchors both supply security and pricing power for manufacturers serving pelvic infection protocols. This backward integration shields dual-agent regimen producers from raw material volatility while enabling margin defense against generic oral antibiotic price compression.
Pricing Analysis
Warranty-bundled pharmacovigilance services now separate premium antimicrobial suppliers from commodity generic producers in EU markets. Three-tier pricing structure across premium, standard, and economy levels reflects EMA compliance infrastructure investments, with German and French registry reporting units commanding 15-20% markups over unbundled competitors. Price erosion runs through high-volume oral doxycycline channels where Eastern European manufacturing clusters compete on volume scale. Hospital procurement consortia in the United States demonstrate highest price sensitivity, while specialty hospitals managing intravenous-to-oral step-down protocols accept premium positioning for bioequivalent high-dose formulations.
Supply Chain Analysis
Direct-to-hospital outpatient department channels handle stewardship-program compliance demand across integrated delivery networks in the United States. API production concentrates in India, China, and Eastern Europe, with the Hyderabad-Visakhapatnam corridor feeding high-volume oral doxycycline manufacturing. Active pharmaceutical ingredients for cephalosporins and tetracyclines draw from Chinese and Indian chemical intermediates, while finished-dose formulation capacity clusters in the United States, Germany, and India. Single-source vulnerability in third-generation cephalosporin feedstock creates exposure for manufacturers lacking dual-qualified suppliers. Distribution runs through hospital procurement consortia and reproductive health clinic networks with limited wholesale intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized clinical microbiology talent scarcity constrains resistance surveillance data interpretation capacity, propping pricing for manufacturers with captive pharmacovigilance infrastructure. This bottleneck limits rapid generic entry and sustains margin premiums for compliant dual-agent protocol developers.
For Market Incumbents: Hedge against vaginal probiotic substitution threats by securing reproductive health clinic network contracts with embedded pharmacogenomic screening services. Backward integration into Eastern European cephalosporin API production reduces exposure to single-source feedstock vulnerabilities. EMA registry compliance infrastructure investments create switching costs that lock hospital outpatient departments into long-term supply relationships. For New Entrants and Emerging Players: Capture CDSCO streamlined approval pathway advantages for fixed-dose combination therapies targeting Indian tier-two city hospital networks. White-space opportunity concentrates in bioequivalent high-dose oral formulations enabling same-day discharge protocols, where reimbursement incentives outweigh price sensitivity. Go-to-market positioning should emphasize intravenous-to-oral switch clinical data to differentiate from legacy generic suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified pharmaceutical conglomerates seeking reproductive health clinic network access and EMA pharmacovigilance infrastructure. Long-term viability hinges on dual-agent protocol pipeline depth and resistance surveillance data interpretation capabilities. The signal to watch is FDA breakpoint revision timing, which accelerates reformulation investment cycles and favors manufacturers with accelerated development infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacovigilance Infrastructure Buildout | EMA registry compliance mandates dedicated units in Germany and France for market access. |
| Dual-Agent Protocol Development | FDA susceptibility testing frameworks expand demand for combination therapy regimens. |
| Fixed-Dose Combination Approval | CDSCO streamlined pathways open Indian tier-two city hospital procurement channels. |
| API Manufacturing Scale-Up | Eastern European cephalosporin capacity pivots support pelvic infection protocol supply. |
| Pharmacogenomic Screening Integration | CYP2D6 metabolizer testing pilots across 200-plus United States outpatient sites. |
Research Methodology
Independent corroboration across regulatory filing databases, hospital procurement records, and API trade data underwrites the qualitative findings in this analysis. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and WHO prequalification records. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure triangulation cross-check segment-level estimates.
Comparable-period anchoring to historical antimicrobial resistance surveillance data and stewardship program adoption curves shaped the projection horizon. Segmentation modeling spanned product type, therapy area, end user, and delivery mode dimensions with regional regulatory cluster differentiation. CAGRs were derived from infection incidence trend analysis, resistance pattern evolution, and procurement policy shift assessment. Forecast inputs incorporated breakpoint revision timing, generic entry probability, and pharmacovigilance compliance cost trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA breakpoint revision timing and EMA pharmacovigilance requirement evolution. Forecasts reflect assumptions regarding resistance surveillance network expansion rates, clinic network consolidation pace, and generic manufacturing capacity addition timing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Herpes Infection Treatment Market
Infectious Disease
Direct-Acting Antiviral Medicines Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Periodic Fever Syndrome Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Measles Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Efavirenz Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market