
 Clostridium Difficile Infection Treatment Market | 2026-2036
Clostridium Difficile Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Clostridium Difficile Infection Treatment Market Analysis
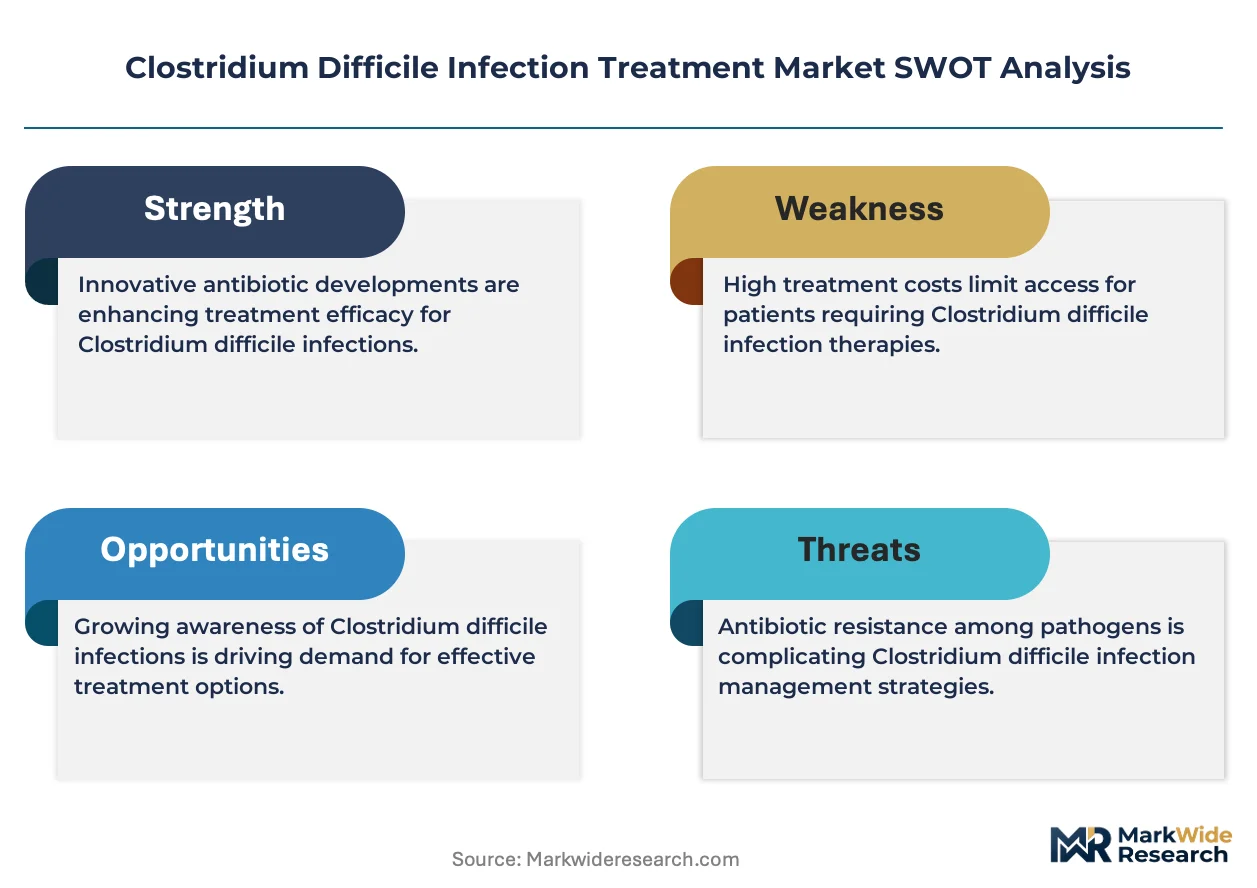
Aftermarket service revenue from post-treatment microbiome monitoring is reconfiguring how therapeutic developers capture lifetime patient value. Merck & Co., Inc. leverages its hospital formulary relationships to sustain recurrent infection protocol penetration. Pfizer Inc. anchors its position through R&D intensity in next-generation narrow-spectrum antibiotics. Seres Therapeutics, Inc. competes on live biotherapeutic product specialization, navigating FDA live biotherapeutic product guidance with early-mover advantage.
Clostridium difficile infection treatment encompasses pharmacological and biotherapeutic interventions targeting toxin-producing gram-positive anaerobic bacteria, with vancomycin and fidaxomicin representing standard-of-care antibiotics that disrupt cell wall synthesis at minimum inhibitory concentrations measured in micrograms per milliliter. The primary commercial purpose centers on reducing recurrence rates below 20% while preserving intestinal microbiome integrity. Antibiotics dominate current prescription volumes, yet fecal microbiota transplantation commands premium reimbursement as recurrence prevention shifts toward microbiome restoration. Monoclonal antibodies occupy an emerging margin pool through passive immunization strategies targeting C. difficile toxins A and B.
FDA live biotherapeutic product guidance, EMA advanced therapy medicinal product frameworks, and antimicrobial stewardship mandates from the Joint Commission collectively shape clinical trial design, manufacturing standards, and hospital procurement criteria for novel therapies. These regulatory layers elevate barriers for non-specialized entrants while rewarding developers with validated microbiome platforms. Stakeholders must monitor pipeline progression in live biotherapeutics against evolving FDA classification thresholds to anticipate reimbursement and competitive positioning shifts.
Market Dynamics
Antimicrobial stewardship programs are compressing antibiotic utilization rates while elevating microbiome restoration therapies into first-line protocols for recurrent cases. Hospital formularies now weight recurrence prevention above initial cure rates, restructuring prescriber incentives and procurement criteria across acute care networks.
Growth Catalysts
- Live Biotherapeutic Product Guidance:FDA classification pathways for fecal-derived and cultured microbiome products are accelerating clinical trial enrollment. Developers gain manufacturing clarity that reduces regulatory risk capital.
- Recurrent Infection Protocols:Hospital infection control committees now mandate microbiome restoration after second recurrence. This institutionalizes FMT and live biotherapeutic utilization into standard order sets.
- Japan:PMDA's regenerative medicine framework recognizes microbiome therapeutics as a priority review category. Domestic biotech firms are advancing rationally designed consortia through accelerated approval channels.
Market Restraints
- Donor Screening Costs:FMT supply chains require exhaustive pathogen testing and quarantine protocols. Per-procedure screening expenses consume margin at scale.
- Manufacturing Concentration:Live biotherapeutic production clusters in single-source contract manufacturing organizations with validated anaerobic fermentation capacity. Facility qualification timelines extend 18-24 months.
- Vancomycin Generic Substitution:Oral vancomycin capsules face commoditization as compounding pharmacies and generic manufacturers compress pricing. Narrow-spectrum alternatives struggle to justify premium positioning.
Strategic Opportunities
- Outpatient Infusion Centers:Microbiome restoration is migrating from inpatient endoscopy suites to ambulatory settings. Colonoscopy-sparing delivery formats unlock capacity expansion.
- EU Advanced Therapy Medicinal Product Incentives:EMA's priority medicines scheme offers fee reductions and accelerated assessment for microbiome therapeutics addressing unmet need in recurrent infection.
- Pharmacogenomic Stratification:Host microbiome profiling prior to antibiotic selection is converging with AI-driven recurrence risk scoring. Integrated diagnostics enable personalized therapy sequencing.
Industry Challenges
- Microbiome Analytics Talent Scarcity:Computational biologists with metagenomic pipeline expertise command premium compensation. Clinical-stage developers compete with agricultural and nutrition microbiome sectors for limited talent pools.
- Live Product Cold Chain Integrity:Anaerobic biotherapeutics require continuous temperature-controlled logistics with oxygen exclusion. Distribution network qualification delays commercial launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clostridium Difficile Infection Treatment Market |
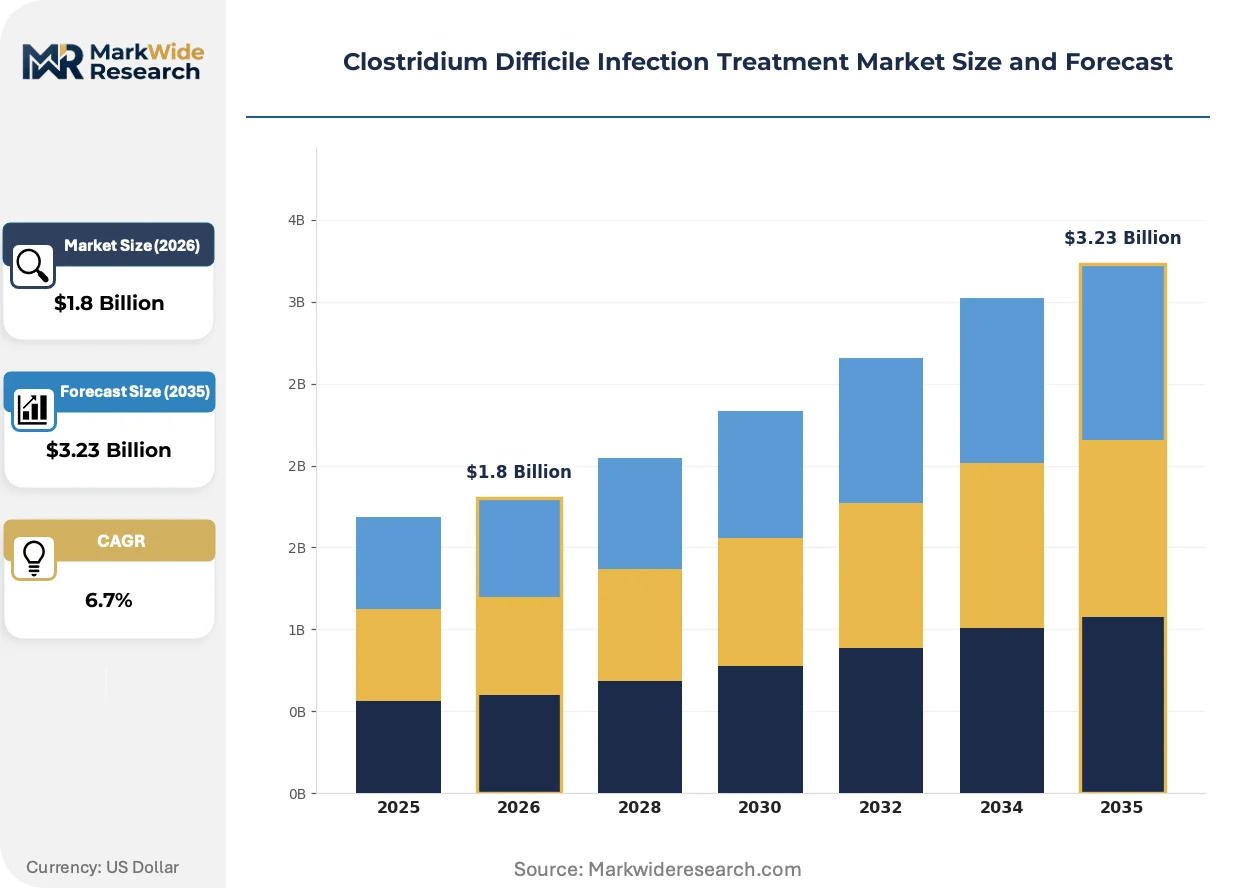
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Probiotics, Monoclonal Antibodies, Vaccines Treatment Approach: Oral Administration, Intravenous Infusion, Fecal Microbiota Transplantation, Combination Therapy End User: Hospitals, Clinics, Long-term Care Facilities, Home Care Diagnosis Method: Enzyme Immunoassay, Nucleic Acid Amplification Test, Stool Culture, PCR Testing |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., Astellas Pharma Inc., Seres Therapeutics, Inc., Ferring Pharmaceuticals, Nestlé Health Science, Acurx Pharmaceuticals, Inc., Vedanta Biosciences, Inc., MGB Biopharma Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clostridium Difficile Infection Treatment Market Emerging Trajectories
Microbiome restoration technologies are displacing antibiotic-centric treatment paradigms through rationally designed bacterial consortia and synthetic ecology approaches. Manufacturing and clinical validation advances are compressing development timelines for live biotherapeutic products.
Next-generation anaerobic fermentation platforms are digitizing quality control through real-time metabolite monitoring and predictive contamination detection. Contract manufacturers serving the live biotherapeutic sector deploy sensor arrays that flag process deviations before batch failure. This digitizing infrastructure reduces release testing burden and accelerates lot release for time-sensitive patient populations.
EMA's advanced therapy medicinal product framework is tightening manufacturing standards for microbiome-derived therapeutics while harmonizing quality specifications across member states. Developers must demonstrate clonal purity and functional stability across shelf-life conditions previously unrequired for donor-derived materials. German and French regulators are conducting coordinated inspections that elevate documentation requirements for anaerobic culture systems.
Hospital procurement committees now unbundle microbiome restoration services from endoscopy bundled payments. Standalone reimbursement codes for FMT and live biotherapeutic administration enable price transparency and vendor comparison. This contracting evolution is most advanced in United States integrated delivery networks where pharmacy benefit managers negotiate per-procedure rates independent of facility fees.
Clostridium Difficile Infection Treatment Market Segmentation
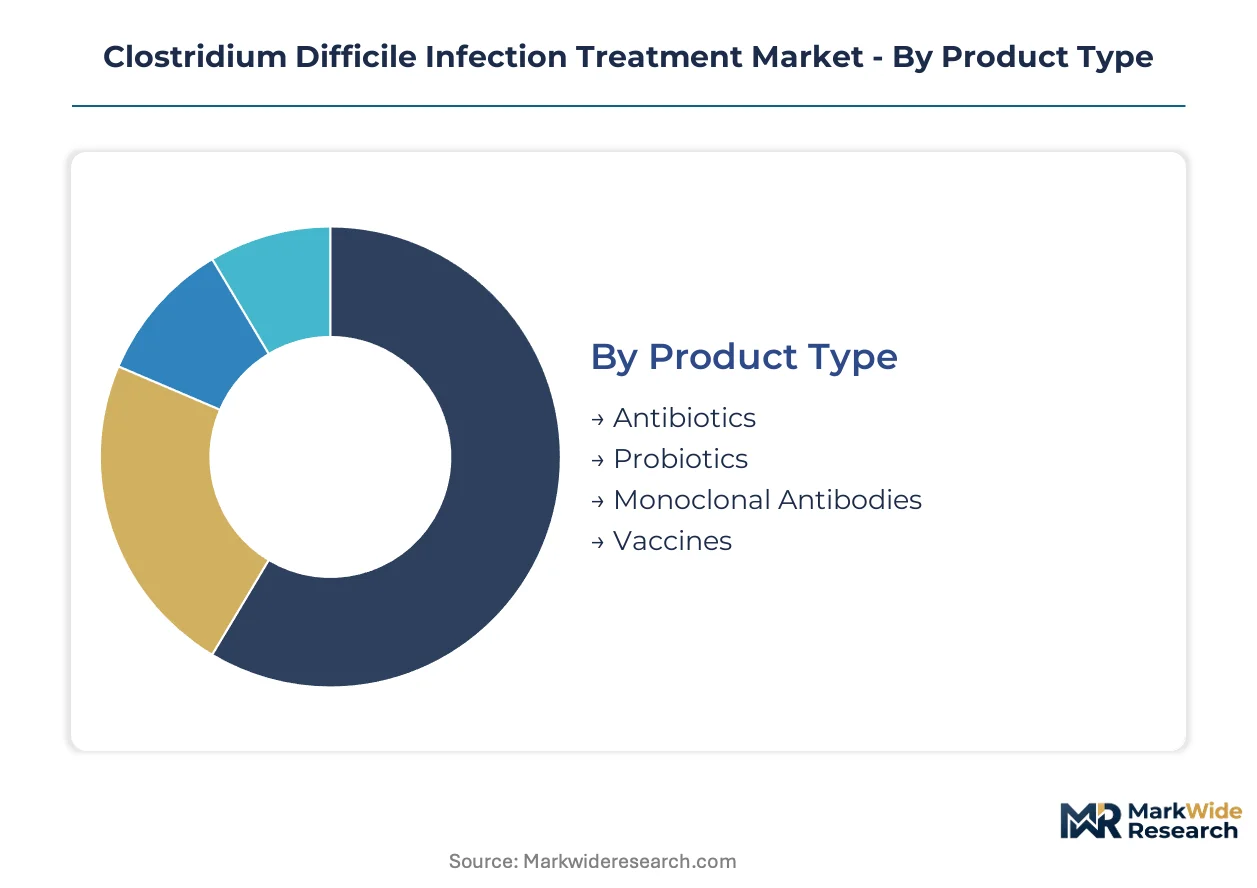
Treatment modality fragmentation in Clostridium difficile infection reflects divergent clinical priorities between initial cure and recurrence prevention. Segmentation reveals how hospital procurement committees balance antimicrobial stewardship mandates against microbiome restoration economics across acute and ambulatory settings.
Product Type:
Cost tier stratification separates commoditized antibiotics from premium biotherapeutics with distinct reimbursement pathways and manufacturing complexity.
- Antibiotics:Oral vancomycin and fidaxomicin disrupt cell wall synthesis at microgram-per-milliliter concentrations. Hospital formularies in the United States favor these agents for initial episodes despite generic substitution pressure on vancomycin pricing.
- Probiotics:Live biotherapeutic products deliver rationally designed bacterial consortia to restore colonization resistance. Japanese developers leverage PMDA's regenerative medicine priority review to accelerate cultured microbiome approvals ahead of Western competitors.
- Monoclonal Antibodies:Passive immunization targeting toxins A and B.
- Vaccines:Active immunization approaches in clinical development.
Antibiotics command the established base. The steepest expansion runs through probiotics.
Treatment Approach:
Application setting determines delivery infrastructure requirements, from oral dispensing to endoscopy suite scheduling and cold chain logistics.
- Oral Administration:Capsule and liquid formulations enable outpatient initiation without procedural overhead. United States integrated delivery networks prioritize oral agents for first-episode protocols to minimize length-of-stay metrics.
- Fecal Microbiota Transplantation:Colonoscopic, nasogastric, and capsule-based delivery of donor-derived microbiota. Recurrent infection protocols in US academic medical centers now mandate FMT after second recurrence, institutionalizing utilization into standard order sets.
- Intravenous Infusion:Hospital-based administration for severe or complicated cases.
- Combination Therapy:Sequential or concurrent antibiotic and microbiome restoration.
Oral administration retains volume dominance. Fecal microbiota transplantation captures margin expansion.
End User:
Customer type concentration shapes contracting structures, with acute care networks negotiating enterprise pricing distinct from long-term care reimbursement.
- Hospitals:Inpatient units and emergency departments manage severe, complicated, and recurrent cases. Infection control committees in the United States drive formulary decisions that weight recurrence prevention above initial cure rates.
- Long-term Care Facilities:Skilled nursing and rehabilitation centers manage high-recurrence-risk populations with extended antibiotic exposure histories. These settings concentrate elderly patients with disrupted microbiomes from prior healthcare encounters.
- Clinics:Outpatient gastrointestinal and infectious disease practices.
- Home Care:Post-discharge monitoring and oral therapy completion.
Hospitals anchor procurement volume. Long-term care facilities present the steepest utilization climb.
Diagnosis Method:
Technology maturity stratifies testing platforms by sensitivity, turnaround time, and capital equipment requirements.
- Nucleic Acid Amplification Test:Molecular detection of toxin gene sequences with high sensitivity. United States hospital laboratories deploy NAAT as frontline screening to reduce time-to-treatment initiation.
- PCR Testing:Polymerase chain reaction methods enable rapid pathogen identification. European reference laboratories standardize PCR protocols under EMA harmonized quality specifications for clinical trial enrollment.
- Enzyme Immunoassay:Antigen detection with faster turnaround but lower sensitivity.
- Stool Culture:Conventional microbiological confirmation with extended incubation.
Nucleic acid amplification tests command the installed base. PCR testing gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems exhibit the lowest price elasticity for microbiome restoration therapies, while European markets demonstrate acute sensitivity to vancomycin generic substitution. Japanese buyers occupy a middle position, prioritizing regulatory approval speed over cost minimization.
United States
Academic medical centers in Boston and the Research Triangle drive fecal microbiota transplantation protocol standardization. FDA live biotherapeutic product guidance accelerates clinical trial enrollment for cultured microbiome developers. Philadelphia's hospital network concentration anchors antimicrobial stewardship program implementation.
Germany
EMA advanced therapy medicinal product frameworks tighten manufacturing documentation for anaerobic culture systems. Reference laboratories in Heidelberg and Munich standardize PCR protocols under harmonized quality specifications. Baden-Württemberg's contract manufacturing cluster specializes in validated anaerobic fermentation capacity.
Japan
PMDA's regenerative medicine priority review category attracts domestic biotech investment in rationally designed bacterial consortia. Tokyo's academic hospitals pioneer colonoscopy-sparing delivery formats for outpatient microbiome restoration. Osaka's pharmaceutical corridor concentrates live biotherapeutic production expertise.
United Kingdom
NHS England's infection control mandates institutionalize microbiome restoration after second recurrence episodes. London's integrated care systems unbundle FMT services from endoscopy bundled payments. Cambridge's biotechnology cluster advances AI-driven recurrence risk scoring integration.
France
ANSM inspections elevate anaerobic culture system documentation requirements for microbiome-derived therapeutics. Parisian hospital networks negotiate standalone reimbursement codes for live biotherapeutic administration. Lyon-Grenoble's healthcare corridor concentrates pharmacogenomic stratification research.
Clostridium Difficile Infection Treatment Market Vendor Landscape
Pharmaceutical conglomerates and specialized microbiome developers split the market into distinct capability tiers. Large-cap drugmakers leverage hospital formulary relationships and manufacturing scale. Biotech specialists concentrate on live biotherapeutic product platforms and regulatory navigation. Dominant competitive moves include strategic partnerships for anaerobic fermentation capacity and portfolio diversification into microbiome monitoring services.
Within the large pharmaceutical tier, Merck & Co., Inc. and Pfizer Inc. exemplify established antibiotic market presence. Seres Therapeutics, Inc. occupies a specialized position representing live biotherapeutic product developers. These three entities anchor distinct strategic approaches: formulary-driven antibiotic distribution, R&D-intensive narrow-spectrum development, and microbiome platform specialization.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| Astellas Pharma Inc. |
| Seres Therapeutics, Inc. |
| Ferring Pharmaceuticals |
| Nestlé Health Science |
| Acurx Pharmaceuticals, Inc. |
| Vedanta Biosciences, Inc. |
| MGB Biopharma Ltd. |
| Others |
Supply Flow & Price Mechanics
Single-source contract manufacturing organizations with validated anaerobic fermentation capacity in Germany and the United States capture disproportionate margin from live biotherapeutic developers, concentrating pricing power upstream while hospital procurement committees squeeze antibiotic tiers downstream.
Pricing Analysis
Aftermarket microbiome monitoring services now drive lifetime patient value capture for therapeutic developers. Three-tier pricing structure across premium live biotherapeutics, standard narrow-spectrum antibiotics, and economy oral vancomycin segments reflects manufacturing complexity and reimbursement pathway differentiation. Cost compression in the vancomycin tier is intensifying because compounding pharmacies and generic manufacturers expand supply. Long-term care facilities exhibit acute price sensitivity, while academic medical centers in the United States demonstrate lowest elasticity for microbiome restoration therapies.
Supply Chain Analysis
Lonza, Thermo Fisher Scientific, and Catalent hold dominant contract manufacturing capacity for anaerobic biotherapeutic production across Switzerland, the United States, and Singapore. Live biotherapeutic supply draws from donor screening networks, cryopreservation infrastructure, and specialized cold chain logistics with oxygen exclusion protocols. Single-source vulnerability pervades the anaerobic fermentation tier where facility qualification timelines extend eighteen to twenty-four months. Distribution runs through hospital-specialty pharmacy channels for inpatient administration and direct-to-patient cold chain delivery for outpatient capsule formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from antibiotic-centric cyclical compression as antimicrobial stewardship mandates institutionalize microbiome restoration into recurrent infection protocols.
For Market Incumbents: Entrench formulary position through exclusive supply agreements with integrated delivery networks and backward integration into donor screening infrastructure. Merck & Co., Inc. and Pfizer Inc. face margin erosion from live biotherapeutic substitution; defensive R&D investment in narrow-spectrum antibiotics with microbiome-sparing profiles preserves hospital access. Certification investment in FDA live biotherapeutic product guidance compliance creates switching costs for competitor displacement. For New Entrants and Emerging Players: Japan's PMDA priority review pathway offers underpenetrated regulatory acceleration for rationally designed bacterial consortia ahead of Western approval timelines. Outpatient infusion centers in ambulatory settings present the most penetrable delivery infrastructure, bypassing colonoscopy suite capacity constraints. Go-to-market execution should target pharmacy benefit manager direct contracting for per-procedure reimbursement codes independent of facility fees. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across live biotherapeutic manufacturing as EMA advanced therapy medicinal product frameworks tighten documentation requirements. Five-to-ten year viability favors developers with validated anaerobic platforms and recurrent infection protocol institutionalization. Acquisition targets should demonstrate clonal purity validation and functional stability across shelf-life conditions. The signal to watch is FDA classification threshold evolution for fecal-derived versus cultured microbiome products.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Seres Therapeutics navigates FDA live biotherapeutic product guidance with early-mover enrollment acceleration. |
| Manufacturing Scale-Up | Baden-Württemberg's contract manufacturing cluster expands validated anaerobic fermentation capacity for European supply security. |
| Hospital System Partnership | Philadelphia's network concentration anchors antimicrobial stewardship program implementation and formulary access. |
| Regulatory Approval Pathway | PMDA's regenerative medicine priority review attracts Tokyo biotech investment in colonoscopy-sparing delivery formats. |
| Reimbursement Strategy | NHS England's unbundling of FMT services from endoscopy payments enables standalone live biotherapeutic contracting. |
Methodological Framework
A standing panel of formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists provided ongoing calibration throughout the study period. Primary interviews with drug development executives at live biotherapeutic developers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov enrollment data, and hospital procurement databases. Bottom-up prescription volume modeling and top-down antimicrobial stewardship program penetration estimates underwent iterative triangulation.
Scenario-bracketing framed analytical outputs across the analysis window, with segmentation dimensions spanning treatment modality, administration route, end-user facility type, and regional regulatory cluster. CAGRs derived from epidemiological recurrence rate projections, microbiome restoration adoption curves, and antibiotic stewardship compliance trajectories. Forecast inputs incorporated PMDA priority review timeline assumptions and EMA advanced therapy medicinal product manufacturing standard evolution.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by single-source contract manufacturers or breakthrough monoclonal antibody approvals would shift outcomes. Regulatory reclassification of fecal-derived products, donor screening protocol disruptions, or antimicrobial stewardship mandate relaxation present specific revision risks. Quarterly review of FDA live biotherapeutic product guidance updates, EMA inspection coordination patterns, and PMDA approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Hepatitis C Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Infectious Disease Diagnostics Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Ceftriaxone Injection Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Brucellosis Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Norovirus Infection Treatment Market