
 Vaginal Fungi Infections Treatment Market | 2026-2036
Vaginal Fungi Infections Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Vaginal Fungi Infections Treatment Market Insights
Prescription-grade azole formulations is bifurcating the competitive landscape into high-efficacy clinical channels and over-the-counter convenience segments. Pfizer Inc. leverages its established azole manufacturing infrastructure to sustain volume leadership across hospital formularies. Bayer AG anchors its position through consumer health distribution networks that reach pharmacy shelves directly. Mycovia Pharmaceuticals Inc. differentiates via novel polyene chemistry platforms targeting fluconazole-resistant Candida strains.
Vaginal fungi infections treatment encompasses pharmaceutical interventions designed to eliminate pathogenic Candida species from the vaginal mucosa, typically formulated with active concentrations of imidazoles, triazoles, or polyenes ranging from one to seven-day dosing regimens depending on severity and recurrence history. These therapies serve the primary purpose of restoring normal vaginal microbiota while relieving pruritus, discharge, and inflammation associated with vulvovaginal candidiasis. Oral antifungals capture the largest revenue pool due to patient preference for discrete single-dose therapy, though intravaginal delivery modes demonstrate faster symptom resolution and command premium positioning in recurrent infection protocols. Homecare settings represent the fastest-expanding end user channel as telehealth prescribing and direct-to-pharmacy fulfillment reduce clinical visit dependencies.
FDA review standards for topical vaginal products, EMA MDR requirements for device-drug combination applicators, and WHO essential medicines list inclusion criteria collectively determine which formulations achieve formulary access and reimbursement eligibility across developed markets. Regulatory pressure to reduce azole resistance development is accelerating investment in non-azole mechanisms and combination therapy protocols. Stakeholders must monitor evolving pharmacovigilance requirements for recurrent-use products and position development pipelines toward agents with demonstrated resistance-lowering profiles.
Market Dynamics
Azole resistance accumulation in recurrent vulvovaginal candidiasis cases is forcing pharmaceutical developers toward polyene and novel mechanism platforms, fundamentally restructuring R&D investment away from established imidazole chemistry.
Growth Catalysts
- Telehealth prescribing frameworks:Post-pandemic regulatory accommodations in the United States and Germany now permit asynchronous diagnosis and e-prescription fulfillment, expanding access for patients in rural or underserved postal codes.
- WHO essential medicines list inclusion:Listing of fluconazole and clotrimazole drives national procurement prioritization across low and middle-income health systems, anchoring volume commitments for generic manufacturers.
- Homecare diagnostic kits:Over-the-counter pH and fungal antigen detection devices enable patient-initiated therapy selection, reducing clinical visit burdens and accelerating treatment initiation timelines.
Market Restraints
- Active pharmaceutical ingredient concentration:Three Chinese manufacturers control bulk azole intermediate supply, creating vulnerability to environmental compliance shutdowns and export quota restrictions.
- EMA MDR device-drug classification:Vaginal applicators with integrated dosing mechanisms face reclassification as Class III medical devices, extending approval timelines and elevating clinical evidence requirements.
- Topical formulation substitution:Generic miconazole and clotrimazole creams commoditize at price points below novel oral agents, compressing reimbursement headroom for differentiated entrants.
Strategic Opportunities
- Japan's aging demographic:Elevated diabetes prevalence and immunosenescence expand the addressable population for recurrent infection protocols, with PMDA fast-track designations available for azole-sparing candidates.
- Subscription pharmacy models:Direct-to-consumer platforms in the United States bundle diagnostic testing, prescription fulfillment, and recurrence monitoring into annual contracts, capturing lifetime value from chronic sufferers.
- Combination therapy protocols:Pairing oral fluconazole with intravaginal boric acid or nystatin addresses biofilm-associated recalcitrance, opening premium pricing tiers for refractory case management.
Industry Challenges
- Clinical trial recruitment:Stringent FDA exclusion criteria for acute uncomplicated cases narrow eligible participant pools, prolonging Phase III enrollment and inflating per-patient costs.
- Resistance surveillance infrastructure:Patchy Candida speciation and antifungal susceptibility testing in community laboratories obscures true azole resistance prevalence, complicating formulary decision-making.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaginal Fungi Infections Treatment Market |
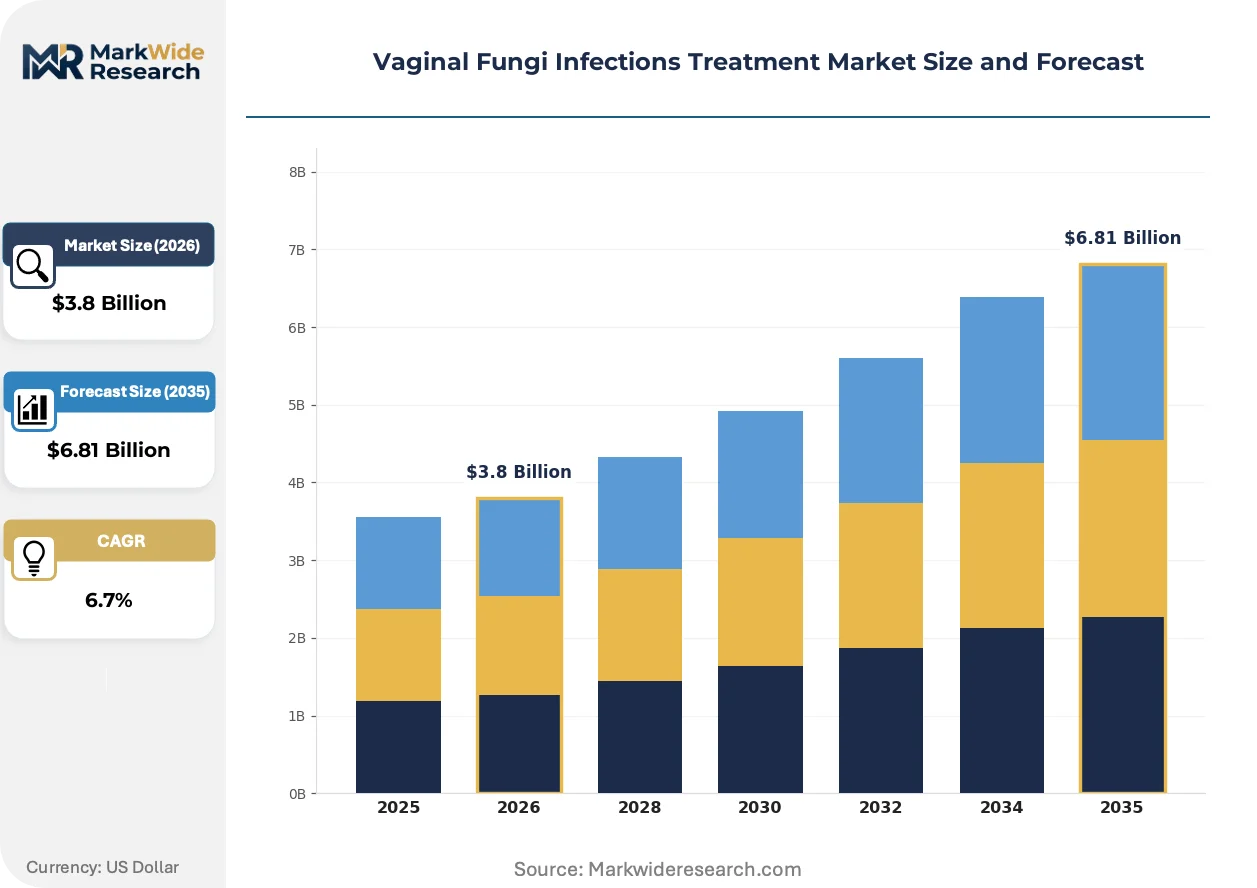
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifungal Creams, Oral Antifungals, Suppositories, Topical Solutions Delivery Mode: Topical, Oral, Intravaginal, Injection End User: Hospitals, Clinics, Homecare Settings, Pharmacies Treatment Duration: Short-term, Long-term, Acute Care, Maintenance Therapy |
| Companies Covered | Pfizer Inc., Bayer AG, Mycovia Pharmaceuticals Inc., Scynexis Inc., Astellas Pharma Inc., GlaxoSmithKline plc, Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Basilea Pharmaceutica Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaginal Fungi Infections Treatment Market Trends and Innovations
Formulation science and delivery mechanism advances are compressing dosing duration while improving mucosal retention, reshaping competitive differentiation around convenience and recurrence prevention rather than standalone efficacy.
Oteseconazole and other tetrazole derivatives are supplanting legacy triazoles in recurrent infection protocols due to reduced CYP450 interaction profiles. Gynecology practices in Germany and the United States are prioritizing these agents for patients on hormonal contraception or anticoagulation therapy. The shift is compressing market share for fluconazole in high-comorbidity patient segments.
FDA draft guidance on vaginal drug products now mandates in vitro release testing and mucosal irritation studies for all new molecular entities, elevating development costs but improving safety documentation standards. European manufacturers face parallel EMA quality guideline revisions for semisolid dosage forms. Smaller developers without established topical formulation expertise are retreating from the pipeline, concentrating innovation among well-capitalized incumbents.
Patients with recurrent infection histories now self-refer to specialty telehealth platforms rather than primary care gatekeepers, fragmenting prescription volume across direct-to-consumer channels. This behavior concentrates in the United States and United Kingdom where pharmacy benefit structures permit out-of-network reimbursement. Traditional gynecology practices are responding by unbundling diagnostic and therapeutic services to retain patient relationships.
Vaginal Fungi Infections Treatment Market Segmentation
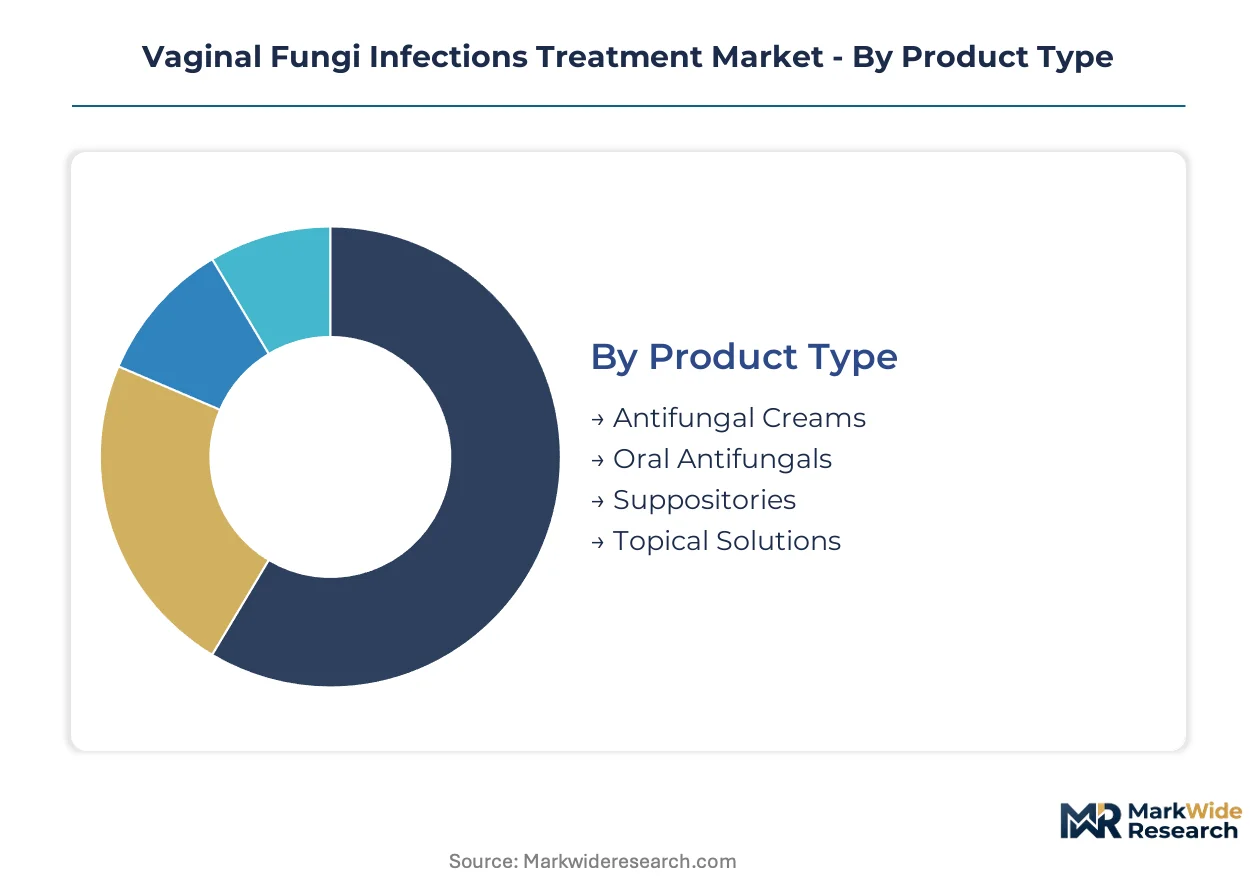
Treatment modality selection in this market hinges on infection severity, recurrence history, and patient preference for convenience versus speed of symptom resolution. Channel dynamics differ sharply across segments, with prescription pathways dominating oral antifungals while retail and direct-to-consumer routes capture growing shares of topical and homecare-administered therapies.
Product Type:
Channel mix varies substantially by formulation physics—creams and solutions flow through pharmacy retail, oral tablets concentrate in prescription fulfillment networks, while suppositories occupy a hybrid position across clinical and homecare channels.
- Oral Antifungals:Single-dose fluconazole tablets and multi-day itraconazole regimens deliver systemic Candida clearance through bloodstream distribution. Prescription volume concentrates in the United States and Germany where telehealth prescribing frameworks enable asynchronous diagnosis and e-prescription fulfillment, expanding access beyond traditional gynecology practices.
- Antifungal Creams:Imidazole-based semisolid formulations including clotrimazole and miconazole provide localized vulvar application with minimal systemic absorption. Demand clusters in over-the-counter pharmacy channels across Japan and the United Kingdom, driven by patient preference for self-initiated therapy without clinical visit requirements.
- Suppositories:Intravaginal solid dosage forms release active agents directly at the infection site.
- Topical Solutions:Liquid formulations enable precise application to affected mucosal surfaces.
Oral antifungals dominate prescription revenue. Antifungal creams represent where volume expansion concentrates through retail channel growth.
Delivery Mode:
Cost tier stratification separates premium-positioned oral agents from economy-tier topical alternatives, with intravaginal delivery commanding intermediate pricing based on formulation complexity and applicator integration.
- Oral:Systemic delivery via gastrointestinal absorption achieves therapeutic concentrations throughout vaginal mucosa without local application burden. Patient preference for discrete, single-dose therapy drives concentration in the United States and Germany, though CYP450 interaction concerns limit use in patients on hormonal contraception or anticoagulation.
- Topical:External vulvar application of creams and solutions addresses pruritus and inflammation without systemic exposure. Volume concentrates in Japan and the United Kingdom where pharmacy benefit structures permit out-of-network reimbursement for over-the-counter purchases.
- Intravaginal:Direct mucosal delivery via creams, gels, or ovules achieves higher local drug concentrations.
- Injection:Parenteral administration reserved for severe or disseminated candidiasis in immunocompromised patients.
Oral delivery anchors premium pricing tiers. Intravaginal modes are climbing the fastest as homecare diagnostic kits enable patient-initiated therapy selection.
End User:
Customer type fragmentation reflects divergent purchasing authority—institutional procurement governs hospital and clinic segments while individual decision-making drives homecare and pharmacy channels.
- Homecare Settings:Patient-administered therapy selection supported by telehealth prescribing and direct-to-pharmacy fulfillment models. Expansion concentrates in the United States and Germany where regulatory accommodations for asynchronous diagnosis reduce clinical visit dependencies.
- Hospitals:Inpatient formulary committees govern antifungal selection for complicated or recurrent cases requiring speciation and susceptibility testing. Volume concentrates in tertiary referral centers across Japan and the United States managing refractory infections in immunocompromised populations.
- Clinics:Outpatient gynecology practices provide diagnosis and prescription for uncomplicated cases.
- Pharmacies:Retail and mail-order fulfillment channels serve prescription and over-the-counter demand.
Hospital procurement governs premium agent access. Homecare settings represent the steepest expansion trajectory as patient self-referral to telehealth platforms fragments prescription volume.
Treatment Duration:
Maturity differentiation separates established short-term and acute protocols from emerging maintenance approaches addressing recurrent infection management.
- Short-term:One-to-three-day regimens of high-concentration azole formulations achieve mycological cure in uncomplicated infections. Standard of care in the United States and United Kingdom where patient preference for rapid resolution drives prescribing patterns.
- Maintenance Therapy:Extended weekly or monthly fluconazole suppression prevents recurrence in patients with three or more annual episodes. Concentrates in Germany and Japan where specialized referral centers manage refractory cases through prophylactic protocols.
- Acute Care:Intensive intervention for severe symptoms or first-episode diagnosis.
- Long-term:Extended duration protocols for immunocompromised or diabetic patients.
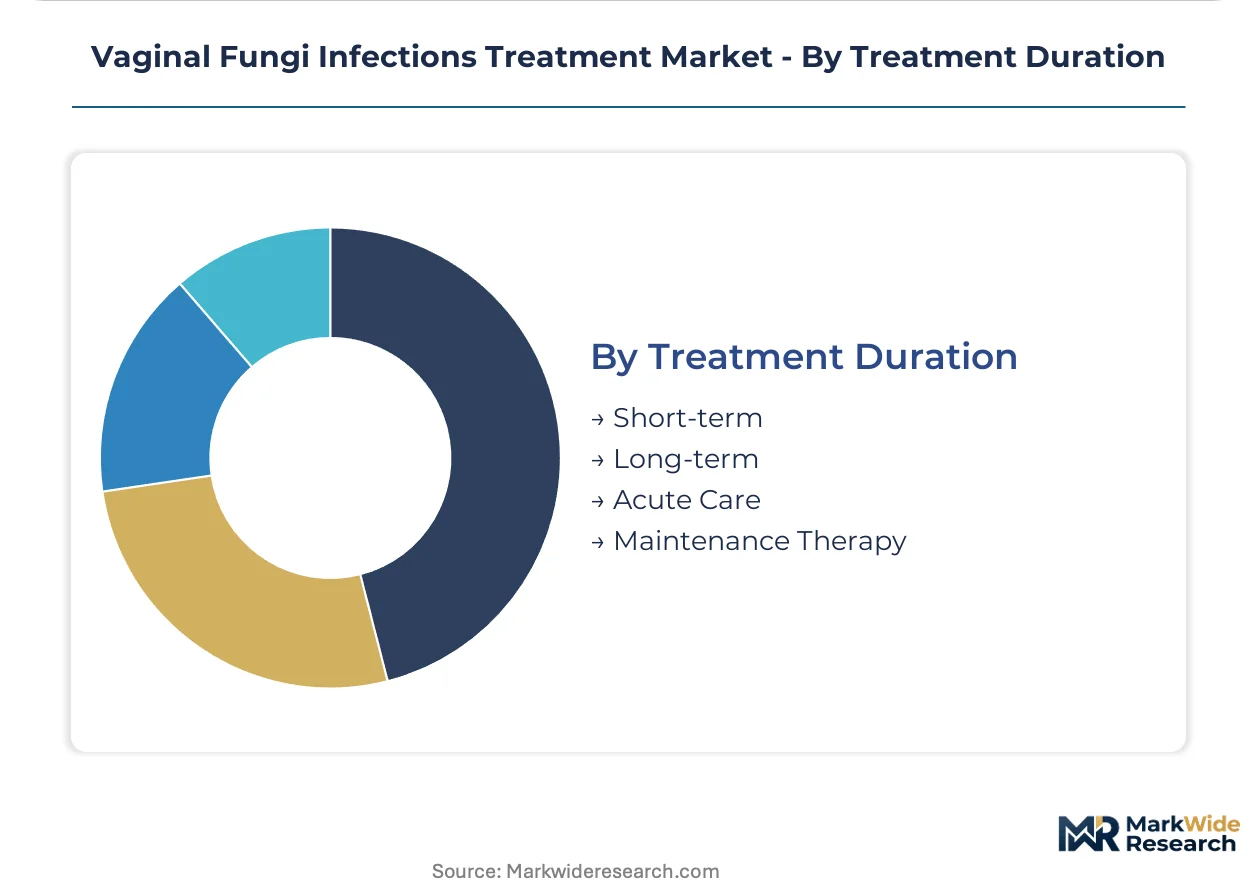
Short-term protocols dominate transaction volume. Maintenance therapy is where pricing power concentrates through chronic disease management models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Three Chinese manufacturers control bulk azole intermediate supply for vaginal antifungal formulations. FDA and EMA regulatory pathways now prioritize azole-sparing agents. Demand concentrates in health systems with established reimbursement for prescription-grade therapies.
United States
Telehealth prescribing frameworks enable asynchronous diagnosis and e-prescription fulfillment across rural postal codes. FDA draft guidance on vaginal drug products mandates in vitro release testing for new molecular entities. Massachusetts and California clusters host specialty telehealth platforms capturing patient self-referrals.
Germany
Specialized referral centers manage refractory cases through prophylactic maintenance protocols. EMA MDR requirements reclassify vaginal applicators with integrated dosing mechanisms as Class III medical devices. Bavaria and North Rhine-Westphalia concentrate gynecology practices unbundling diagnostic and therapeutic services.
Japan
Elevated diabetes prevalence and immunosenescence expand the addressable population for recurrent infection protocols. PMDA fast-track designations are available for azole-sparing candidates. Tokyo and Osaka metropolitan areas anchor hospital formulary committees governing premium agent access.
United Kingdom
Pharmacy benefit structures permit out-of-network reimbursement for over-the-counter purchases. MHRA aligns with EMA quality guideline revisions for semisolid dosage forms. London and Southeast England fragment prescription volume across direct-to-consumer channels.
India
WHO essential medicines list inclusion drives national procurement prioritization across public health systems. CDSCO regulates topical vaginal products under pharmaceutical and medical device classifications. Maharashtra and Gujarat host generic manufacturing clusters supplying bulk azole formulations.
Vaginal Fungi Infections Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in this market. Incumbents with established azole manufacturing infrastructure sustain volume leadership across hospital formularies. Consumer health specialists anchor retail pharmacy networks. Novel mechanism developers target fluconazole-resistant strains. Competitive moves concentrate on portfolio diversification toward azole-sparing platforms and strategic partnerships for homecare diagnostic integration.
Within the established pharmaceutical tier, Pfizer Inc. and Bayer AG occupy positions reflecting divergent channel strategies. Pfizer leverages prescription fulfillment networks and hospital formulary relationships. Bayer anchors consumer health distribution reaching pharmacy shelves directly. Mycovia Pharmaceuticals Inc. exemplifies the novel mechanism archetype, representing development priorities shifting toward polyene chemistry platforms.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| Mycovia Pharmaceuticals Inc. |
| Scynexis Inc. |
| Astellas Pharma Inc. |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Basilea Pharmaceutica Ltd. |
| Others |
Pricing and Supply Chain Analysis
Bulk azole intermediate manufacturing at three Chinese facilities generates scale economies that compress cost floors for generic formulations while elevating entry barriers for novel mechanism developers. This concentration anchors pricing power among incumbent API suppliers and propagates cost volatility through downstream formulation tiers when environmental compliance shutdowns interrupt export flows.
Pricing Analysis
FDA draft guidance on vaginal drug products dictates the pricing tier structure by mandating in vitro release testing and mucosal irritation studies that elevate development costs for new molecular entities. Three-tier pricing structure across premium, standard, and economy levels separates novel tetrazole derivatives from branded azole tablets and generic topical creams. Cost compression in the economy tier is intensifying because Indian generic manufacturers exploit WHO essential medicines list procurement commitments. Pharmacy benefit structures in the United States and Germany render institutional buyers least price-sensitive while uninsured cash-pay patients in retail channels exhibit highest elasticity.
Supply Chain Analysis
Shanghai Port customs clearance delays underwrite supply vulnerability for azole API shipments destined to European formulation facilities. Active pharmaceutical ingredient production concentrates in China, India, and Italy, with intermediate synthesis anchored in Shandong and Gujarat chemical parks. Finished formulation draws from ketoconazole base, miconazole nitrate, and specialized vaginal applicator polymers. Single-source vulnerability concentrates in environmental compliance enforcement patterns across Chinese manufacturing zones. Distribution runs through hospital procurement consortia, retail pharmacy networks, and direct-to-consumer telehealth platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA and EMA device-drug classification precedents create switching costs that protect incumbent formulary positions. Network effects concentrate in hospital procurement consortia and pharmacy benefit manager preferred drug lists.
For Market Incumbents: Fortify azole manufacturing infrastructure through backward integration into API supply and captive production of vaginal applicator components. Emerging polyene chemistry platforms from Mycovia Pharmaceuticals and Scynexis threaten fluconazole market share in recurrent infection segments. Prioritize certification investment for Class III medical device reclassification under EMA MDR requirements to extend approval timeline advantages over undercapitalized entrants. For New Entrants and Emerging Players: PMDA fast-track designation for azole-sparing candidates opens white-space access in Japan's aging demographic with elevated diabetes prevalence and immunosenescence. Telehealth prescribing frameworks in Germany and the United States fragment prescription volume toward direct-to-consumer channels with lower formulary committee barriers. Pursue go-to-market positioning through subscription pharmacy models bundling diagnostic testing and recurrence monitoring. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with demonstrated resistance-lowering profiles and established topical formulation expertise. Long-term viability hinges on portfolio diversification toward non-azole mechanisms as azole resistance accumulation accelerates. Target acquisition archetypes include specialty telehealth platforms with integrated pharmacy fulfillment and novel mechanism developers with Phase III-ready polyene candidates. Monitor Candida speciation surveillance infrastructure expansion as inflection indicator for formulary prioritization shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA MDR Class III reclassification for device-drug applicators elevates clinical evidence requirements and consolidates innovation among well-capitalized incumbents. |
| Pipeline Diversification | Novel tetrazole and polyene chemistry platforms address fluconazole-resistant Candida strains and capture premium positioning in recurrent infection protocols. |
| Strategic Partnership | Collaboration with homecare diagnostic kit manufacturers enables patient-initiated therapy selection and reduces clinical visit dependencies. |
| Reimbursement Strategy | Pharmacy benefit structures in the United States and Germany favor prescription-grade antifungal access and anchor volume commitments for oral formulations. |
| Manufacturing Scale-Up | Vertical integration into azole API production mitigates vulnerability to Chinese environmental compliance shutdowns and export quota restrictions. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO essential medicines procurement databases. Bottom-up prescription volume modeling and top-down epidemiological incidence estimates were triangulated to anchor market size calculations.
Variance decomposition across infection severity segments, recurrence history strata, and regional regulatory clusters structured the analytical framework. Compound annual growth rates were derived from log-linear trend fitting across the projection horizon, with patient population aging, diabetes prevalence trajectories, and telehealth adoption curves serving as key demand-side inputs. Supply-side constraints incorporated API manufacturing capacity utilization and environmental compliance enforcement patterns.
Underlying assumptions cover reimbursement stability in developed markets and azole resistance prevalence surveillance quality, with deviation risk concentrated in Chinese API export policy shifts and EMA MDR implementation timelines. Practitioners should keep alternative scenarios live as regulatory classification precedents and resistance surveillance infrastructure evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Brucellosis Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Tuberculous Meningitis Treatment Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Hepatitis C Market
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Gram Positive Bacterial Infections Market