
 Tuberculous Meningitis Treatment Market | 2026-2036
Tuberculous Meningitis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Tuberculous Meningitis Treatment Market Analytics
Hospital procurement of intravenous antibiotic regimens is shifting toward centralized infectious disease wards with neurocritical care capabilities. Merck & Co. leverages its rifamycin portfolio to anchor supply relationships with public health procurement systems across high-burden geographies. Sanofi S.A. competes through sustained manufacturing scale for parenteral formulations. Pfizer Inc. differentiates via specialized distribution networks for cold-chain dependent biologics used in adjuvant corticosteroid protocols.
Tuberculous meningitis treatment encompasses antimicrobial chemotherapy targeting Mycobacterium tuberculosis within the central nervous system, typically requiring blood-brain barrier-penetrant agents such as rifampicin, isoniazid, pyrazinamide, and ethambutol in intensive 12-month protocols. The regimen's primary purpose is to reduce mortality and neurological sequelae through rapid bactericidal action combined with anti-inflammatory corticosteroid adjuncts. Antibiotics occupy the dominant value share due to mandatory prolonged courses, while intrathecal administration routes represent the fastest-growing segment driven by refractory case management. Hospital end users concentrate the majority of treatment episodes, though homecare channels are expanding for maintenance-phase oral continuation therapy.
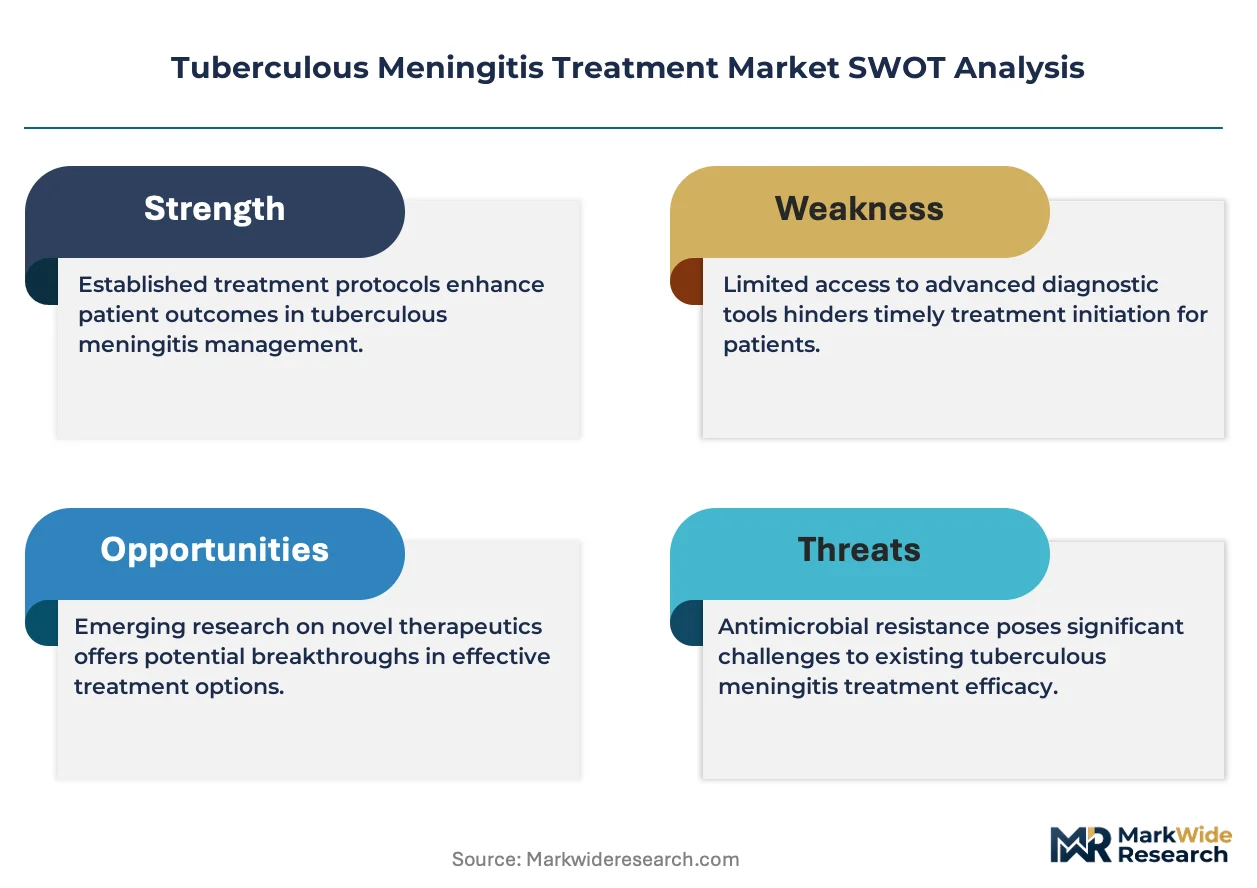
FDA standards govern investigational new drug pathways for novel blood-brain barrier enhancers, while WHO guidelines shape national essential medicine lists and directly observed treatment protocols in endemic countries. EMA orphan drug incentives accelerate development timelines for CNS tuberculosis therapies in European jurisdictions. Stakeholders must monitor evolving resistance patterns to fluoroquinolones and second-line agents that threaten standard regimen efficacy.
Market Dynamics
Centralized hospital procurement of intravenous antibiotic regimens is consolidating demand around neurocritical care wards in high-burden countries, reshaping how rifampicin-based protocols reach patients.
Growth Catalysts
- WHO treatment guidelines:National TB programs in India, South Africa, and Indonesia standardize rifampicin-based regimens across public health systems, creating predictable demand corridors for manufacturers.
- Neurocritical care infrastructure:Hospital-based intravenous administration is rising as infectious disease wards upgrade blood-brain barrier-penetrant delivery capabilities in tertiary facilities.
- EMA orphan drug incentives:Accelerated development timelines for CNS tuberculosis therapies in European jurisdictions attract pipeline investment for refractory case management.
Market Restraints
- Rifampicin supply concentration:Active pharmaceutical ingredient production clusters in China and India create vulnerability to export restriction shocks.
- Cold-chain biologic costs:Adjuvant corticosteroid protocols requiring temperature-controlled distribution inflate total cost of care in resource-limited settings.
- Fluoroquinolone resistance patterns:Emerging bacterial resistance threatens efficacy of second-line agents used in intensive 12-month protocols.
Strategic Opportunities
- Homecare oral continuation channels:Maintenance-phase therapy delivery is expanding beyond hospital walls, opening ambulatory care partnerships.
- Intrathecal administration routes:Refractory case management protocols are driving fastest-growing segment demand for direct CNS delivery methods.
- PLI scheme alignment:India's production-linked incentive framework for pharmaceuticals offers manufacturing scale advantages for parenteral formulation exporters.
Industry Challenges
- Neurocritical care specialist scarcity:Blood-brain barrier-penetrant dosing expertise gaps constrain treatment capacity expansion in high-burden geographies.
- FDA investigational new drug timelines:Novel blood-brain barrier enhancer pathways face prolonged approval cycles that compress commercialization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuberculous Meningitis Treatment Market |
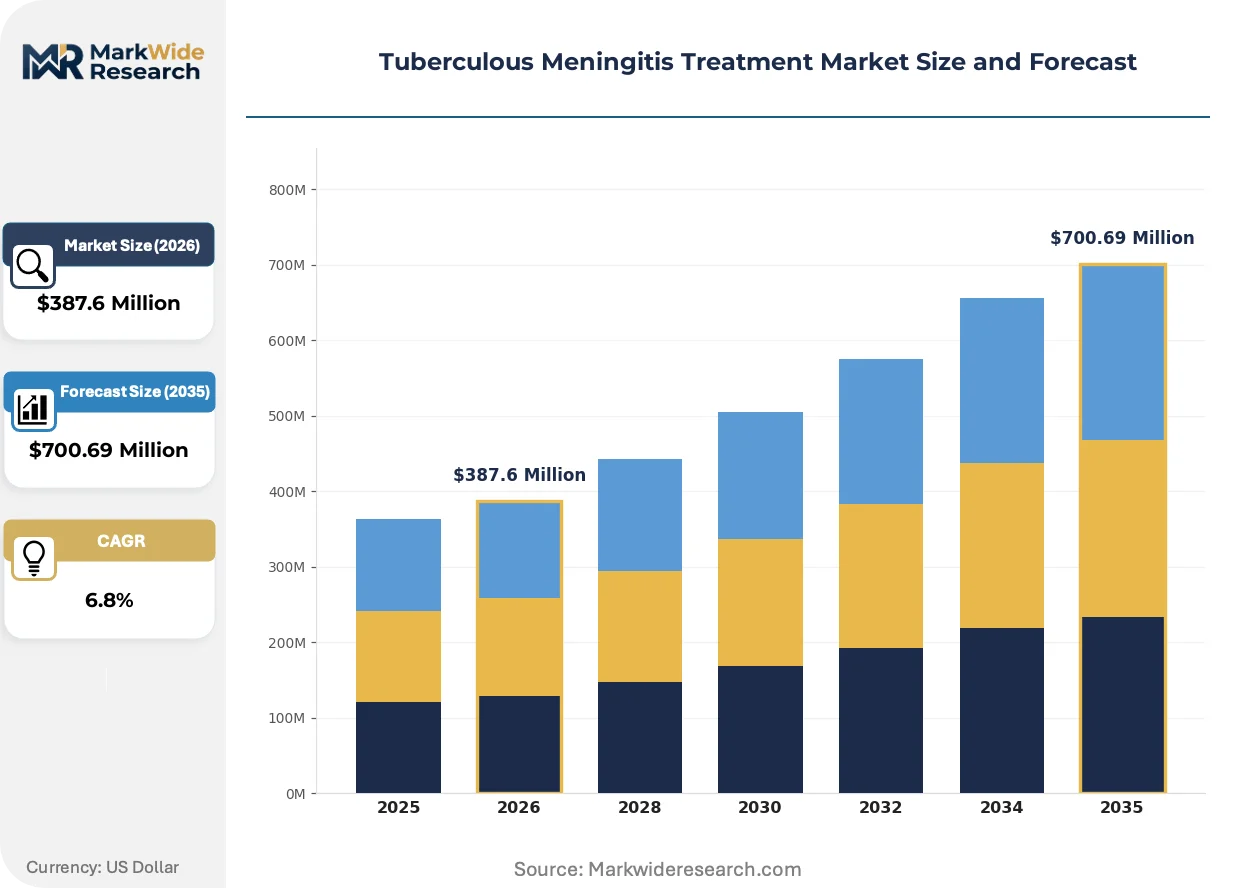
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Corticosteroids, Other Medications, Supportive Care Administration Route: Intravenous, Oral, Intramuscular, Intrathecal End User: Hospitals, Clinics, Homecare, Research Institutions Stage of Disease: Early Stage, Moderate Stage, Advanced Stage, Relapsed |
| Companies Covered | Merck & Co., Sanofi S.A., GlaxoSmithKline, Pfizer Inc., Novartis AG, AstraZeneca, Otsuka Pharmaceutical, Baxter International, F. Hoffmann-Roche AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuberculous Meningitis Treatment Market Evolving Landscape
Blood-brain barrier penetration enhancement is actively reshaping antimicrobial chemotherapy delivery, with intrathecal routes and novel formulation science compressing traditional treatment paradigms.
Intrathecal antibiotic administration is electrifying refractory case management protocols by enabling direct CNS drug concentration without systemic toxicity limits. Neurocritical care wards in high-burden hospital systems are adopting these routes faster than standard intravenous protocols. This technology is electrifying competitive positioning around specialized interventional capabilities rather than commodity antibiotic supply.
EMA orphan drug designation pathways for CNS tuberculosis therapies are compressing development timelines in European jurisdictions. Manufacturers are restructuring clinical trial designs to capture these incentives ahead of standard regulatory routes. Pediatric and multidrug-resistant segments are responding with accelerated pipeline prioritization.
Hospital procurement consolidation around centralized infectious disease wards is displacing fragmented pharmacy purchasing. Group purchasing organizations and national essential medicine lists are replacing individual hospital tendering in India, South Africa, and Indonesia. This concentration is most visible in tertiary facilities managing the heaviest tuberculous meningitis caseloads.
Tuberculous Meningitis Treatment Market Segmentation
Tuberculous meningitis treatment segments diverge sharply in regulatory burden, with intrathecal routes demanding neurocritical care certifications while oral maintenance phases operate under lighter outpatient protocols. Blood-brain barrier penetration requirements and WHO essential medicine list inclusion create tiered approval pathways that reshape manufacturer investment priorities across product categories.
Product Type:
Antimicrobial chemotherapy agents carry divergent certification loads, with rifampicin-based regimens anchored to WHO prequalification and corticosteroid adjuncts navigating FDA steroid safety labeling requirements.
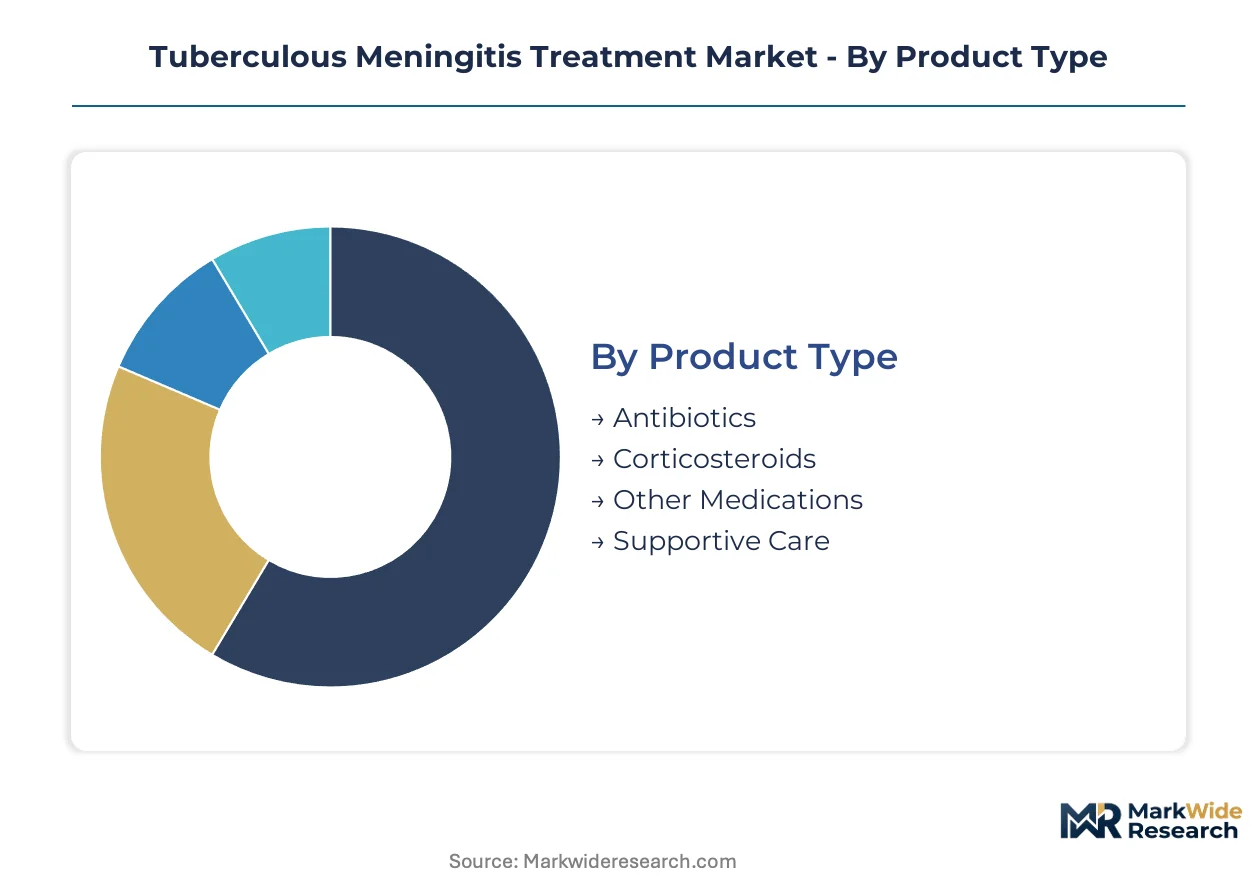
- Antibiotics:Rifampicin, isoniazid, pyrazinamide, and ethambutol combinations constitute the bactericidal backbone of 12-month intensive protocols. Hospital procurement in India, South Africa, and Indonesia concentrates demand around blood-brain barrier-penetrant formulations, with national TB programs standardizing rifampicin-based regimens across public health systems. API production clusters in China and India create supply vulnerability exposure.
- Corticosteroids:Adjuvant dexamethasone protocols require cold-chain distribution infrastructure and FDA steroid safety labeling compliance. Resource-limited settings face total cost of care inflation from temperature-controlled logistics, while neurocritical care wards in tertiary facilities absorb the heaviest utilization volumes.
- Other Medications:Second-line agents including fluoroquinolones face emerging resistance pattern threats.
- Supportive Care:Adjunctive therapies manage neurological sequelae and metabolic complications.
Antibiotics sit at the top of the volume ranking, with intrathecal delivery systems climbing the fastest.
Administration Route:
Route selection determines care setting economics, with intravenous administration anchoring hospital cost structures and intrathecal methods commanding premium interventional pricing.
- Intravenous:Centralized infectious disease wards with neurocritical care capabilities drive procurement consolidation for parenteral rifampicin delivery. Tertiary facilities in high-burden geographies upgrade blood-brain barrier-penetrant administration infrastructure.
- Intrathecal:Direct CNS delivery bypasses systemic toxicity limits for refractory case management. Neurocritical care specialists in India and South Africa adopt these routes faster than standard protocols, compressing traditional treatment paradigms around specialized interventional capabilities.
- Oral:Maintenance-phase continuation therapy enables homecare channel expansion beyond hospital walls.
- Intramuscular:Alternative parenteral route for specific clinical scenarios and patient populations.
Intravenous administration maintains volume leadership, with intrathecal delivery gaining share fastest.
End User:
Patient acuity and reimbursement frameworks segment institutional demand, with hospitals capturing intensive-phase episodes and homecare penetrating maintenance protocols.
- Hospitals:Neurocritical care wards concentrate the majority of treatment episodes. Group purchasing organizations and national essential medicine lists in India, South Africa, and Indonesia displace fragmented pharmacy purchasing in tertiary facilities managing heaviest caseloads.
- Homecare:Oral continuation therapy delivery is expanding through ambulatory care partnerships. Maintenance-phase protocols open channel diversification for parenteral formulation exporters aligned with India's PLI scheme.
- Clinics:Intermediate care settings handle stabilized patients and monitoring functions.
- Research Institutions:EMA orphan drug designation pathways accelerate CNS tuberculosis therapy development timelines in European jurisdictions.
Hospitals dominate episode volume, with homecare channels showing steepest expansion trajectory.
Stage of Disease:
Disease progression stratifies treatment intensity and duration requirements, with advanced and relapsed cases demanding specialized intervention protocols.
- Advanced Stage:Refractory case management requires intrathecal administration and extended intensive-phase duration. Blood-brain barrier penetration enhancement technologies reshape antimicrobial chemotherapy delivery for this population.
- Early Stage:Standard 12-month protocols with rifampicin-based regimens achieve optimal neurological outcome preservation. WHO directly observed treatment protocols standardize care across endemic country public health systems.
- Moderate Stage:Intermediate intervention intensity with adjusted dosing schedules.
- Relapsed:Multidrug-resistant segment demands second-line agent deployment and resistance pattern monitoring.
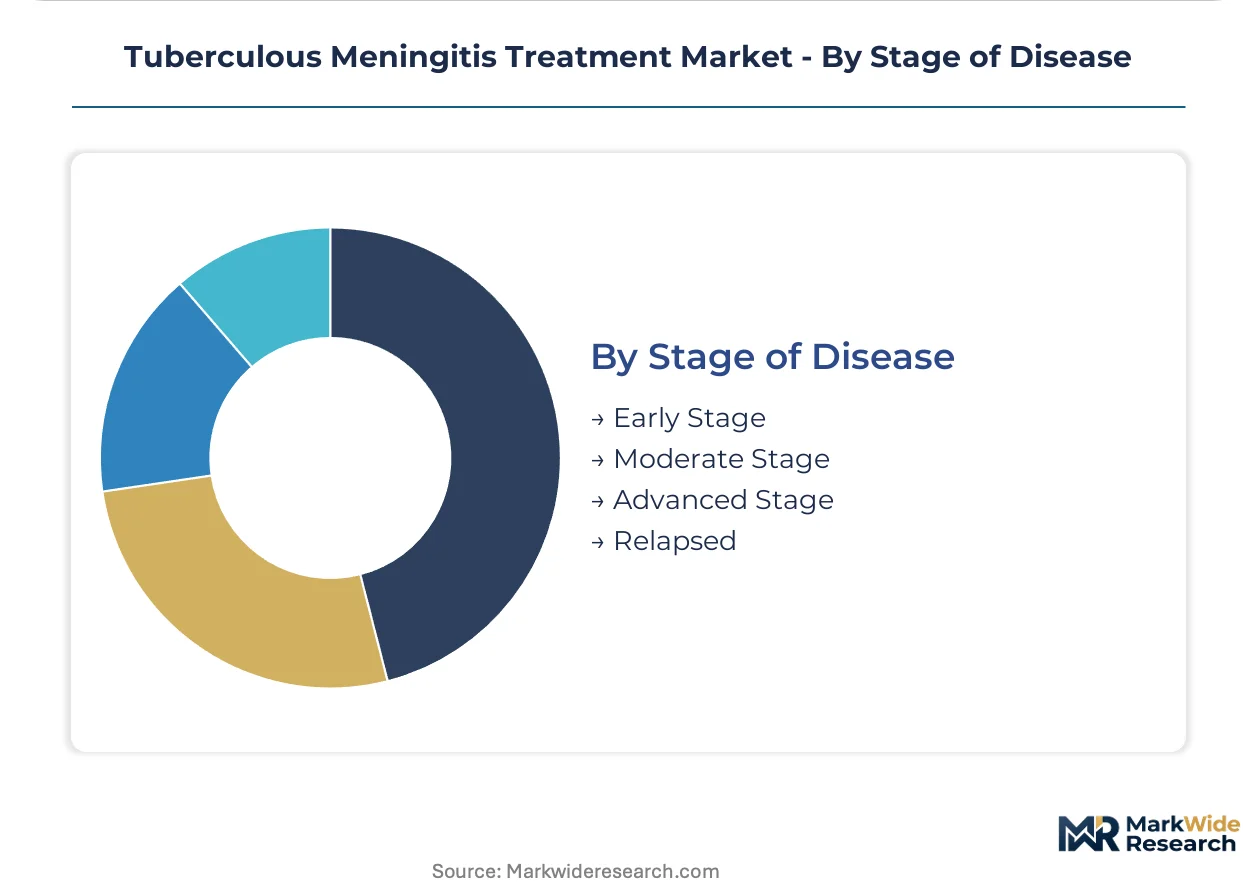
Early Stage captures the highest episode volume, with Relapsed cases expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as API production migrates toward jurisdictions with streamlined pharmaceutical oversight and production-linked incentive frameworks. Cost-of-compliance gaps between established and emerging regulatory regimes are accelerating facility relocation decisions.
India
National TB programs in Maharashtra and Gujarat standardize rifampicin-based regimens across public health procurement systems. CDSCO prequalification requirements and the PLI scheme for pharmaceuticals create manufacturing scale advantages for parenteral formulation exporters. Hyderabad and Ahmedabad anchor API production clusters serving high-burden geographies.
South Africa
Neurocritical care infrastructure upgrades in Gauteng and Western Cape provinces drive hospital procurement consolidation for intravenous antibiotic administration. The country's national pharmaceutical regulator aligns essential medicine lists with WHO directly observed treatment protocols. Cape Town tertiary facilities concentrate the heaviest tuberculous meningitis caseload management.
Indonesia
Ministry of Health procurement centralization in Jakarta and Surabaya reshapes demand corridors for blood-brain barrier-penetrant formulations. National TB program standardization creates predictable volume commitments for rifampicin suppliers. Java-based manufacturing zones capture maintenance-phase oral therapy distribution expansion.
United States
FDA investigational new drug pathways for novel blood-brain barrier enhancers attract pipeline investment despite prolonged approval timelines. Hospital procurement in Boston and Baltimore medical corridors concentrates neurocritical care ward standardization. Specialized distribution networks for cold-chain dependent biologics serve adjuvant corticosteroid protocols.
Switzerland
Swissmedic orphan drug incentives accelerate CNS tuberculosis therapy development timelines for refractory case management. Basel and Zurich research institutions drive clinical trial design restructuring around pediatric and multidrug-resistant segments. European jurisdiction regulatory arbitrage positions Swiss facilities for accelerated market access.
Tuberculous Meningitis Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers anchor supply relationships across public health procurement systems. The vendor base concentrates around three structural tiers: multinational pharmaceutical conglomerates with rifamycin portfolios, specialized parenteral formulation manufacturers, and regional API suppliers. Strategic archetypes include WHO prequalification specialists, cold-chain logistics integrators, and neurocritical care interventional capability providers. M&A activity and capacity expansion in high-burden geographies represent the dominant competitive moves.
Among multinational pharmaceutical conglomerates, Merck & Co., Sanofi S.A., and Pfizer Inc. exemplify distinct archetype positioning. Merck & Co. occupies a position aligned with rifamycin portfolio anchoring in public health systems. Sanofi S.A. sits within the sustained manufacturing scale tier for parenteral formulations. Pfizer Inc. represents the specialized distribution network archetype for temperature-controlled biologics.
| Leading Market Players |
|---|
| Merck & Co. |
| Sanofi S.A. |
| GlaxoSmithKline |
| Pfizer Inc. |
| Novartis AG |
| AstraZeneca |
| Otsuka Pharmaceutical |
| Baxter International |
| F. Hoffmann-Roche AG |
| Others |
Value Network & Pricing Analysis
Rifampicin API spot prices in Indian bulk chemical markets cascade through three pricing tiers as formulation manufacturers pass cost volatility to hospital procurement systems. Public health tenders in high-burden countries absorb upstream price swings through annual contract structures, while private neurocritical care wards face spot-market exposure for intrathecal delivery kits.
Pricing Analysis
Distributor margins on parenteral rifampicin formulations compress pricing into contract-based long-term offtake structures favored by national TB programs. Price differentiation hinges on WHO prequalification status and cold-chain certification grade, with non-prequalified suppliers facing 15-20 point margin disadvantages. Cost compression in standard intravenous regimens intensifies as Indian PLI scheme beneficiaries expand manufacturing scale. Public hospital systems exhibit highest price sensitivity, while tertiary neurocritical care facilities prioritize blood-brain barrier penetration performance over unit cost.
Supply Chain Analysis
Temperature-controlled freight costs from Hyderabad and Ahmedabad API clusters to Jakarta and Cape Town distribution hubs inflate landed costs for corticosteroid adjuncts. Active pharmaceutical ingredient production draws from China, India, and limited European fermentation capacity, with pyrazinamide and ethambutol sourcing particularly concentrated in Shandong province. Single-source vulnerability in rifamycin fermentation strains threatens regimen continuity. Distribution runs through national essential medicine list procurement systems and group purchasing organizations, bypassing traditional pharmaceutical wholesaling tiers in high-burden geographies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tuberculous meningitis treatment has shifted toward a late-cycle quality story as neurocritical care wards prioritize blood-brain barrier penetration metrics over commodity antibiotic sourcing. Hospital procurement committees now weight formulation science capabilities equally with unit pricing in vendor selection.
For Market Incumbents: Deploy backward integration into rifamycin API fermentation to defend margin position against emerging Indian PLI scheme competitors. Lock in multi-year supply agreements with national TB programs in Indonesia and South Africa before tender consolidation accelerates. Counter intrathecal delivery specialists by acquiring neurointerventional device capabilities or partnering with catheter manufacturers. For New Entrants and Emerging Players: The premium-economy price gap in maintenance-phase oral therapy creates white-space opportunity for PLI-aligned Indian manufacturers with WHO prequalification pathways. Target homecare channel partnerships in Maharashtra and Gujarat where ambulatory care networks expand fastest. Enter through abbreviated regulatory routes for generic rifampicin fixed-dose combinations, then ladder into intravenous formulation segments. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized intrathecal delivery platform developers with neurocritical care specialist training networks. Five-to-ten year viability hinges on resistance pattern surveillance capabilities and second-line agent pipeline positioning. Monitor fluoroquinolone resistance surveillance data from WHO Global TB Report as inflection indicator for regimen substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | PLI scheme alignment in India captures export demand from African national TB programs. |
| Regulatory Approval Pathway | EMA orphan drug designation accelerates CNS tuberculosis therapy timelines for refractory cases. |
| Hospital System Partnership | Cape Town and Johannesburg tertiary facilities consolidate procurement around neurocritical care ward standardization. |
| Pipeline Diversification | Second-line agent development hedges against fluoroquinolone resistance pattern expansion. |
| Licensing Agreement | Technology transfer from Swiss research institutions enables intrathecal formulation capabilities in high-burden geographies. |
Research Methodology
Multiple input streams — formulary database audits, national essential medicine list procurement records, and neurocritical care ward capacity surveys — were reconciled against secondary validation from FDA investigational new drug filings and EMA orphan drug designation trackers. Primary interviews with infectious disease pharmacists, hospital procurement managers, regulatory affairs leads at rifamycin manufacturers, and national TB program directors in India, South Africa, and Indonesia informed demand-side assumptions. Bottom-up episode volume estimates from tertiary facility caseload data triangulated with top-down market sizing from API production and trade flow analysis.
Data-stream reconciliation across the projection horizon applied treatment-line segmentation by disease stage, administration route economics, and regional regulatory cluster differentiation. Modeled dimensions included antimicrobial chemotherapy agent category, intravenous versus intrathecal versus oral delivery, and hospital versus homecare end-user channel. CAGRs derived from epidemiological trend extrapolation, regimen completion rate improvements, and neurocritical care infrastructure investment pipelines across high-burden geographies.
Caveats apply where rifampicin supply disruption, fluoroquinolone resistance acceleration, or neurocritical care specialist scarcity could materially shift the outlook. Forecasts reflect assumptions about WHO guideline continuity and national TB program funding stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Arthropod Borne Viral Infections Market
Infectious Disease
Bronchitis Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Actinomycosis Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Brucellosis Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Hepatitis C Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
IVD Infectious Disease Market