
 Coxsackievirus Infections Treatment Market | 2026-2036
Coxsackievirus Infections Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Coxsackievirus Infections Treatment Market Outlook
Antiviral drug development revenue is tilting toward platform-based small-molecule discovery rather than traditional high-throughput screening. Pfizer leverages its established infectious disease infrastructure to sustain pipeline momentum across enterovirus targets. Merck & Co. anchors its position through manufacturing scale that supports pandemic-readiness contracts. Sanofi competes by specializing in pediatric formulation expertise that addresses the primary patient demographic.
Coxsackievirus infections treatment encompasses pharmaceutical and biological interventions targeting enteroviruses within the Picornaviridae family, which replicate at 33–37°C in human intestinal and cardiac tissues and primarily serve to reduce viral load, prevent myocardial damage, and manage neurological complications in susceptible populations. Vaccines command the largest product-type allocation due to prevention-focused public health budgets, while immune modulators represent the fastest-expanding category as clinicians seek to interrupt cytokine-driven cardiac inflammation. Among therapy areas, hand, foot, and mouth disease generates the highest prescription volume through seasonal pediatric demand, whereas viral myocarditis concentrates margin pools in specialized hospital settings where intravenous delivery dominates.
The FDA governs antiviral efficacy benchmarks through its Division of Antiviral Products, while the EMA's Committee for Medicinal Products for Human Use sets parallel standards that manufacturers must satisfy for transatlantic market access. Both frameworks elevate the cost of clinical validation but simultaneously protect approved therapies from low-efficacy competitors. Stakeholders must monitor emerging resistance patterns in coxsackievirus serotype B3 to anticipate where therapeutic portfolios require mechanistic diversification.
Market Dynamics
Pediatric hospitals are consolidating their antiviral procurement around platform-based small-molecule discovery, compressing traditional high-throughput screening timelines and reshaping how manufacturers prioritize pipeline investments.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's Division of Antiviral Products has streamlined efficacy benchmarks for enterovirus therapies, reducing clinical trial design timelines for sponsors targeting coxsackievirus serotypes.
- Seasonal Surveillance Infrastructure:United States public health departments have expanded outbreak monitoring systems, driving predictable procurement cycles for prophylactic inventories in pediatric care networks.
- Myocarditis Protocol Expansion:Cardiac intensive care units are adopting standardized cytokine-driven inflammation management, pulling immune modulators into frontline treatment algorithms.
Market Restraints
- Clinical Validation Cost Structure:EMA Committee for Medicinal Products for Human Use parallel standards require duplicate efficacy demonstrations, elevating development costs for transatlantic market access.
- Resistance Pattern Uncertainty:Emerging coxsackievirus serotype B3 polymorphisms threaten mechanistic durability of approved antiviral classes, forcing portfolio diversification investments.
- Pediatric Formulation Complexity:Age-appropriate dosing and palatability requirements for oral antivirals extend development timelines compared to adult infectious disease programs.
Strategic Opportunities
- Neurological Complication Protocols:Hospital systems are formalizing enterovirus-associated encephalitis treatment pathways, creating demand for intravenous antiviral delivery systems.
- Hand, Foot, and Mouth Disease Seasonal Contracts:Regional health authorities in temperate climates are moving toward annual prophylactic procurement frameworks, stabilizing revenue predictability for vaccine suppliers.
- Platform Manufacturing Convergence:Combination of continuous bioprocessing with single-use systems is enabling rapid serotype-specific vaccine adaptation without facility revalidation.
Industry Challenges
- Virology Specialization Scarcity:Enterovirus taxonomy expertise is concentrated in academic medical centers, limiting qualified personnel for clinical trial design and regulatory submission preparation.
- Multi-Site Coordination Complexity:Pediatric infectious disease trials require activation across dispersed children's hospital networks, inflating site management overhead and enrollment variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coxsackievirus Infections Treatment Market |
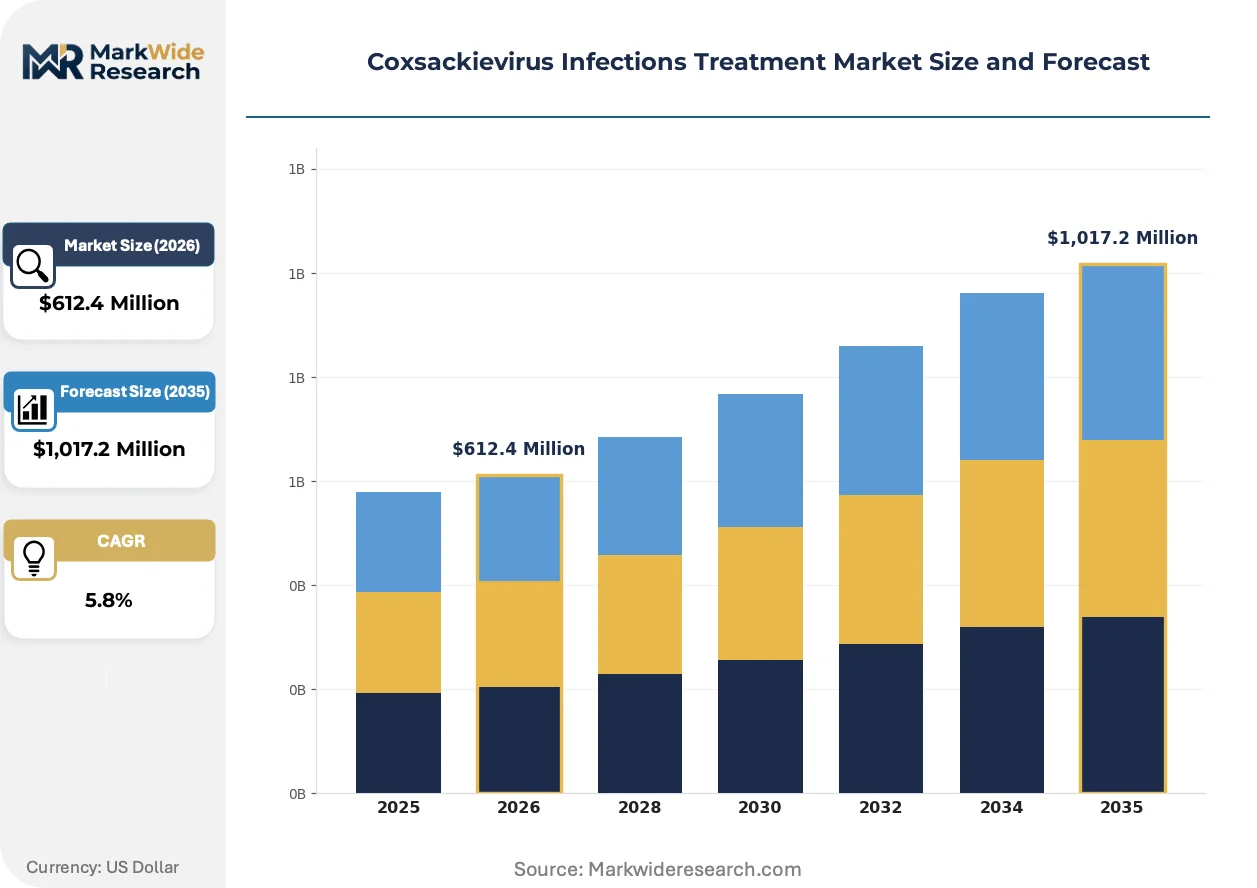
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Antiviral Drugs, Immune Modulators, Supportive Care Therapy Area: Hand, Foot, and Mouth Disease, Viral Myocarditis, Meningitis, Herpangina End User: Hospitals, Clinics, Research Laboratories, Home Care Settings Delivery Mode: Oral, Intravenous, Intranasal, Topical |
| Companies Covered | Pfizer, Johnson & Johnson, F. Hoffmann-La Roche, Merck & Co., AbbVie, Bayer, Sanofi, Bristol-Myers Squibb, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coxsackievirus Infections Treatment Market Strategic Shifts
Antiviral development workflows are compressing discovery-to-candidate timelines through computational biology integration, while regulatory frameworks and hospital procurement models adapt to platform-based manufacturing capabilities.
RNA-dependent RNA polymerase inhibitors are migrating from broad-spectrum enterovirus candidates toward serotype-specific formulations with improved cardiac tissue penetration. Pediatric infectious disease specialists are prioritizing these candidates in early-phase protocols. This migration from generalist to targeted mechanisms is compressing the addressable patient population while elevating reimbursement thresholds for demonstrated myocarditis prevention.
REACH registration requirements for novel antiviral intermediates are expanding safety documentation obligations for European manufacturing supply chains. Contract manufacturers serving the infectious disease sector are consolidating their chemical supplier networks to reduce compliance audit burden. Pediatric formulation specialists are most affected, as excipient selection now requires extended toxicological dossiers before process validation.
Hospital procurement departments are consolidating antiviral purchasing through centralized infectious disease formularies rather than therapeutic category-specific contracts. Group purchasing organizations are absorbing direct manufacturer relationships that previously ran through distributor networks. This consolidation is most visible in United States children's hospital systems, where seasonal coxsackievirus outbreak preparedness now drives annual joint procurement cycles across multi-state networks.
Coxsackievirus Infections Treatment Market Segmentation
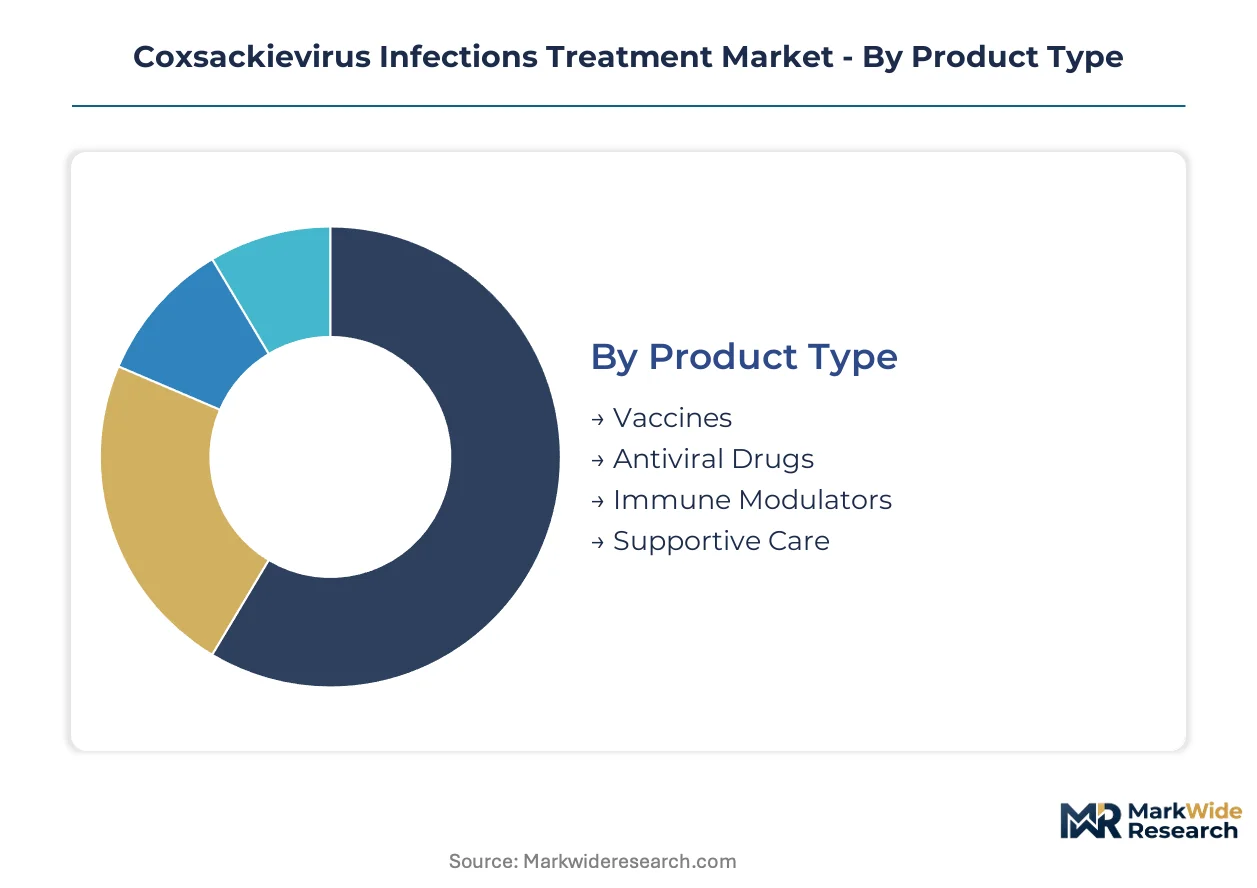
Segmentation in the coxsackievirus treatment market reveals divergent procurement rhythms across product categories. Vaccine suppliers operate on multi-year public health contracting cycles, while antiviral developers face compressed clinical validation timelines driven by FDA accelerated approval pathways. Understanding these velocity differences enables manufacturers to align pipeline investments with segment-specific revenue recognition patterns.
Product Type:
Vaccines turn over slowest due to multi-dose regimen development and cold-chain infrastructure requirements, while immune modulators cycle fastest as clinicians iterate through cytokine-targeting protocols in cardiac intensive care units.
- Vaccines:Inactivated or live-attenuated formulations targeting coxsackievirus serotypes A16 and B3, stabilized for tropical distribution. Demand concentrates in United States pediatric networks where CDC immunization schedules drive annual procurement volumes. Seasonal outbreak surveillance in temperate climates creates predictable manufacturing windows for suppliers with pandemic-readiness contracts.
- Immune Modulators:Biologics and small-molecule cytokine inhibitors interrupting IL-6 and TNF-alpha pathways in myocarditis progression. Cardiac intensive care units in Germany and France are adopting these agents as first-line inflammation management, pulling manufacturers toward intravenous formulation expertise. The steepest expansion trajectory sits here as clinicians seek alternatives to corticosteroid protocols.
- Antiviral Drugs:RNA-dependent RNA polymerase inhibitors and capsid-binding agents reducing viral replication in intestinal and cardiac tissues.
- Supportive Care:Hydration solutions, antipyretics, and topical analgesics managing symptomatic presentation in outpatient settings.
Vaccines dominate installed base through prevention-focused public health budgets. Immune modulators are where expansion concentrates as cardiac complication protocols formalize across hospital systems.
Therapy Area:
Cost tier stratification separates high-acuity hospital interventions from outpatient management, with neurological and cardiac indications commanding premium reimbursement against routine pediatric presentations.
- Hand, Foot, and Mouth Disease:Self-limiting mucocutaneous infection primarily affecting children under five, characterized by vesicular eruptions on palms, soles, and oral mucosa. Outpatient clinics in Japan and South Korea manage seasonal surges through standardized supportive care pathways. Volume concentration here reflects demographic susceptibility rather than intervention complexity.
- Viral Myocarditis:Inflammatory destruction of cardiac myocytes by coxsackievirus B serotypes, requiring intensive hemodynamic monitoring and immunomodulatory intervention. Specialized cardiac centers in the United States and Germany concentrate margin pools through prolonged hospitalization and mechanical circulatory support. Reimbursement thresholds elevate with demonstrated prevention of dilated cardiomyopathy progression.
- Meningitis:Aseptic inflammation of meninges presenting with fever and altered mental status, necessitating cerebrospinal fluid analysis.
- Herpangina:Vesicular pharyngitis in pediatric populations, managed through symptomatic relief in primary care settings.
Hand, foot, and mouth disease captures prescription volume through seasonal pediatric demand. Viral myocarditis is where margin expansion concentrates as specialized cardiac protocols proliferate.
End User:
Customer type fragmentation splits procurement authority between centralized hospital formularies and distributed primary care networks, with research laboratories operating on grant-funded acquisition cycles distinct from clinical reimbursement.
- Hospitals:Acute care institutions managing severe coxsackievirus complications through emergency departments and intensive care units. United States children's hospital networks are consolidating antiviral procurement through multi-state group purchasing organizations, compressing manufacturer negotiation leverage. Seasonal preparedness mandates drive joint contracting for outbreak surge capacity.
- Clinics:Outpatient facilities diagnosing and managing uncomplicated infections in community settings.
- Research Laboratories:Academic and commercial entities conducting serotype surveillance and antiviral efficacy studies.
- Home Care Settings:Residential environments where family caregivers administer supportive therapies for mild infections.
Hospitals dominate installed base through high-acuity intervention requirements. Research laboratories are where pipeline partnerships concentrate as developers seek early-phase collaboration for mechanistic validation.
Delivery Mode:
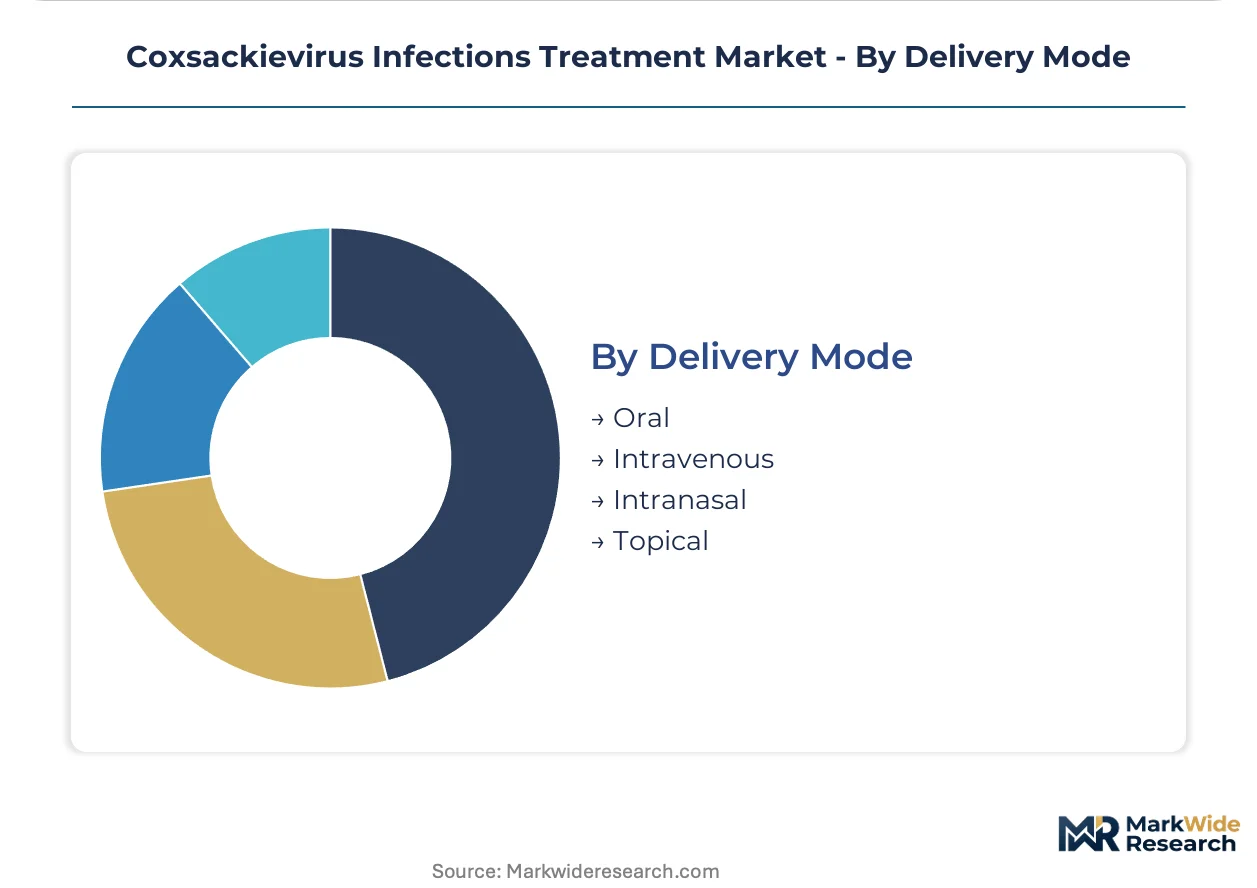
Supply concentration varies by administration complexity, with intravenous formulations requiring compounding pharmacy infrastructure against oral distribution through standard pharmaceutical wholesaling.
- Intravenous:Parenteral delivery systems for antivirals and immune modulators in hospitalized patients. Compounding pharmacies in France and Switzerland specialize in sterile preparation of biologic infusions for cardiac intensive care. Regulatory scrutiny from EMA and national health technology assessment bodies elevates documentation requirements for batch release.
- Oral:Tablet and liquid formulations enabling outpatient management of uncomplicated infections.
- Intranasal:Mucosal delivery platforms under investigation for rapid immune priming.
- Topical:Localized application for mucocutaneous lesion management in herpangina and hand, foot, and mouth disease.
Oral formulations dominate installed base through outpatient prescription volume. Intravenous delivery is where therapeutic innovation concentrates as manufacturers target high-acuity cardiac and neurological indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies, with outpatient pediatric networks in Japan and South Korea driving hard negotiations on vaccine procurement while United States cardiac centers absorb premium pricing for intravenous immune modulators without volume elasticity.
United States
CDC immunization schedules and seasonal outbreak surveillance in temperate climates drive predictable manufacturing windows for vaccine suppliers with pandemic-readiness contracts. The FDA's Division of Antiviral Products governs efficacy benchmarks that elevate clinical validation costs but protect approved therapies from low-efficacy competitors. Children's hospital networks in the Midwest and Southeast are consolidating antiviral procurement through multi-state group purchasing organizations.
Germany
Cardiac intensive care units in Berlin and Munich are adopting immune modulators as first-line inflammation management for viral myocarditis, pulling manufacturers toward intravenous formulation expertise. The EMA's Committee for Medicinal Products for Human Use requires parallel efficacy demonstrations that duplicate development costs for transatlantic market access. The Rhine-Ruhr and Bavarian medical technology clusters concentrate sterile compounding pharmacy infrastructure for biologic infusions.
Japan
Outpatient clinics manage seasonal surges of hand, foot, and mouth disease through standardized supportive care pathways with concentrated prescription volume. METI oversees pharmaceutical pricing negotiations that compress margin expansion for prophylactic vaccines. The Kanto region around Tokyo anchors pediatric infectious disease research partnerships between academic medical centers and commercial developers.
France
Compounding pharmacies in Lyon and Paris specialize in sterile preparation of biologic infusions for cardiac intensive care under elevated EMA batch release scrutiny. ANSM enforces national health technology assessment documentation requirements that extend regulatory timelines for novel antiviral intermediates. The Île-de-France region concentrates virology taxonomy expertise for clinical trial design and regulatory submission preparation.
Switzerland
Specialized cardiac centers in Zurich and Geneva command premium reimbursement thresholds for demonstrated myocarditis prevention through mechanistically targeted therapies. Swissmedic maintains parallel standards with EMA that protect therapeutic portfolios but force portfolio diversification investments against emerging resistance patterns. The Basel pharmaceutical corridor anchors platform-based small-molecule discovery infrastructure.
Coxsackievirus Infections Treatment Market Competitive Environment
Platform-based small-molecule discovery specialists and legacy infectious disease infrastructure operators split the market between compressed clinical timelines and established regulatory relationships. The vendor base concentrates around three strategic archetypes: pediatric formulation experts addressing palatability requirements, manufacturing scale players supporting pandemic-readiness contracts, and platform-technology developers leveraging computational biology integration. Dominant competitive moves include backward integration into chemical supply chains and strategic partnerships with academic medical centers for mechanistic validation.
Within the platform-technology tier, Pfizer and Merck & Co. exemplify divergent approaches to sustaining pipeline momentum across enterovirus targets. Pfizer occupies a position leveraging established infectious disease infrastructure, while Merck & Co. anchors manufacturing scale capabilities. Sanofi sits within the pediatric formulation specialization vector, addressing the primary patient demographic through age-appropriate dosing expertise.
| Leading Market Players |
|---|
| Pfizer |
| Johnson & Johnson |
| F. Hoffmann-La Roche |
| Merck & Co. |
| AbbVie |
| Bayer |
| Sanofi |
| Bristol-Myers Squibb |
| AstraZeneca |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in sterile compounding pharmacy infrastructure across France and Switzerland drives supplier prioritization toward high-margin intravenous immune modulator contracts, compressing negotiation leverage for oral antiviral purchasers in outpatient networks.
Pricing Analysis
After-sales service revenue from multi-year pandemic-readiness contracts drives lifetime value for vaccine suppliers serving United States children's hospital networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation complexity and cold-chain certification grade. Pricing pressure stems from METI-negotiated reimbursement compression in Japan's outpatient pediatric clinics. Volume-based procurement through group purchasing organizations exhibits lowest price sensitivity, while independent primary care networks demonstrate highest elasticity.
Supply Chain Analysis
Upstream active pharmaceutical ingredient feedstock draws from India, China, and the United States for RNA-dependent RNA polymerase inhibitor synthesis. Critical inputs span nucleoside analog precursors, specialized bioreactor media, and single-use sterile containment systems. Single-source vulnerability concentrates in tropical-stabilized vaccine adjuvant supply. Distribution runs through centralized hospital formularies and group purchasing organization networks rather than traditional pharmaceutical wholesaling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in neurological complication protocols as hospital systems formalize enterovirus-associated encephalitis treatment pathways, creating specialized niches for intravenous delivery system developers.
For Market Incumbents: Pre-empt emerging platform-technology developers by securing exclusive chemical supply agreements for nucleoside analog precursors and expanding sterile compounding capacity in the Rhine-Ruhr corridor. Backward integration into REACH-compliant intermediate manufacturing protects against EMA documentation burden escalation.
For New Entrants and Emerging Players: Geographic underpenetration in Swiss and German cardiac intensive care networks for cytokine-targeting biologics presents accessible entry points. Focus formulation development on intravenous IL-6 pathway inhibitors with demonstrated myocarditis prevention. Pursue hospital system partnerships through academic medical center collaborations rather than direct group purchasing organization contracting.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pediatric vaccine suppliers with multi-year CDC schedule alignment and pandemic-readiness contract structures. Five-to-ten year viability favors manufacturers with platform-based small-molecule discovery infrastructure. Monitor FDA Division of Antiviral Products accelerated approval pathway utilization rates as inflection indicator for clinical timeline compression benefits.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA accelerated approval pathway utilization compresses enterovirus therapy development timelines for sponsors. |
| Regulatory Approval Pathway | EMA parallel efficacy demonstrations protect transatlantic market access but elevate validation investment requirements. |
| Manufacturing Scale-Up | Continuous bioprocessing with single-use systems enables rapid coxsackievirus serotype-specific vaccine adaptation. |
| Pipeline Diversification | Mechanistic diversification against emerging coxsackievirus serotype B3 resistance patterns preserves portfolio durability. |
| Hospital System Partnership | Multi-state children's hospital network procurement consolidation demands direct manufacturer-formulary relationships. |
Study Parameters
Operator-level perspectives from infectious disease specialists, cardiac intensive care unit directors, pediatric hospital procurement managers, and regulatory affairs leads anchored the qualitative base. Secondary validation drew from FDA filings, EMA Committee for Medicinal Products for Human Use opinions, ClinicalTrials.gov protocol registrations, and hospital formulary databases. Bottom-up patient population modeling and top-down public health budget allocation analysis provided triangulation across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon through sensitivity testing of outbreak surveillance intensity and immunization schedule adherence assumptions. Segmentation dimensions spanned product type, therapy area, end user, and delivery mode, with regional regulatory cluster effects modeled separately. CAGRs derived from epidemiological trend extrapolation and procurement cycle pattern recognition, incorporating serotype surveillance data and cardiac complication protocol adoption curves as forecast inputs.
Practitioners should monitor emerging coxsackievirus serotype B3 polymorphism patterns and EMA REACH documentation expansion for early signals requiring forecast revision. Cross-checking against CDC immunization schedule update announcements and seasonal outbreak surveillance reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Human Immunodeficiency Virus Type 1 (HIV 1) Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Herpes Infection Treatment Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Infectious Disease Treatments Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Bronchitis Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Virology Market
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Brucellosis Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market