
 Rare Inflammatory Disease Treatment Market | 2026-2036
Rare Inflammatory Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Inflammatory Disease Treatment Market Outlook
Specialty hospital networks is rotating toward home-based infusion and self-administration models, reducing reliance on traditional inpatient biologic delivery. AbbVie Inc. anchors its position through deep R&D intensity in immunology modulators for refractory granulomatosis. Pfizer Inc. leverages global manufacturing scale to supply intravenous biologics across European centralized procurement frameworks. Novartis AG differentiates through gene therapy platforms targeting monogenic autoinflammatory pathways.
Rare inflammatory disease treatment encompasses pharmacological and biological interventions designed to modulate dysregulated immune responses in conditions with prevalence below specific population thresholds, typically requiring monoclonal antibodies, recombinant proteins, or nucleic acid therapies that achieve targeted cytokine inhibition or immune cell depletion. These therapies primarily serve to halt progressive organ damage, preserve functional capacity, and reduce mortality in patient populations where standard immunosuppression proves inadequate. Biologics occupies the dominant value share due to premium pricing and chronic administration requirements in systemic sclerosis maintenance protocols. Gene therapy represents the fastest-expanding segment as vector manufacturing costs decline and durable response profiles attract payer investment. Small molecules retains relevance in oral maintenance regimens where patient preference for non-injectable delivery sustains volume demand.
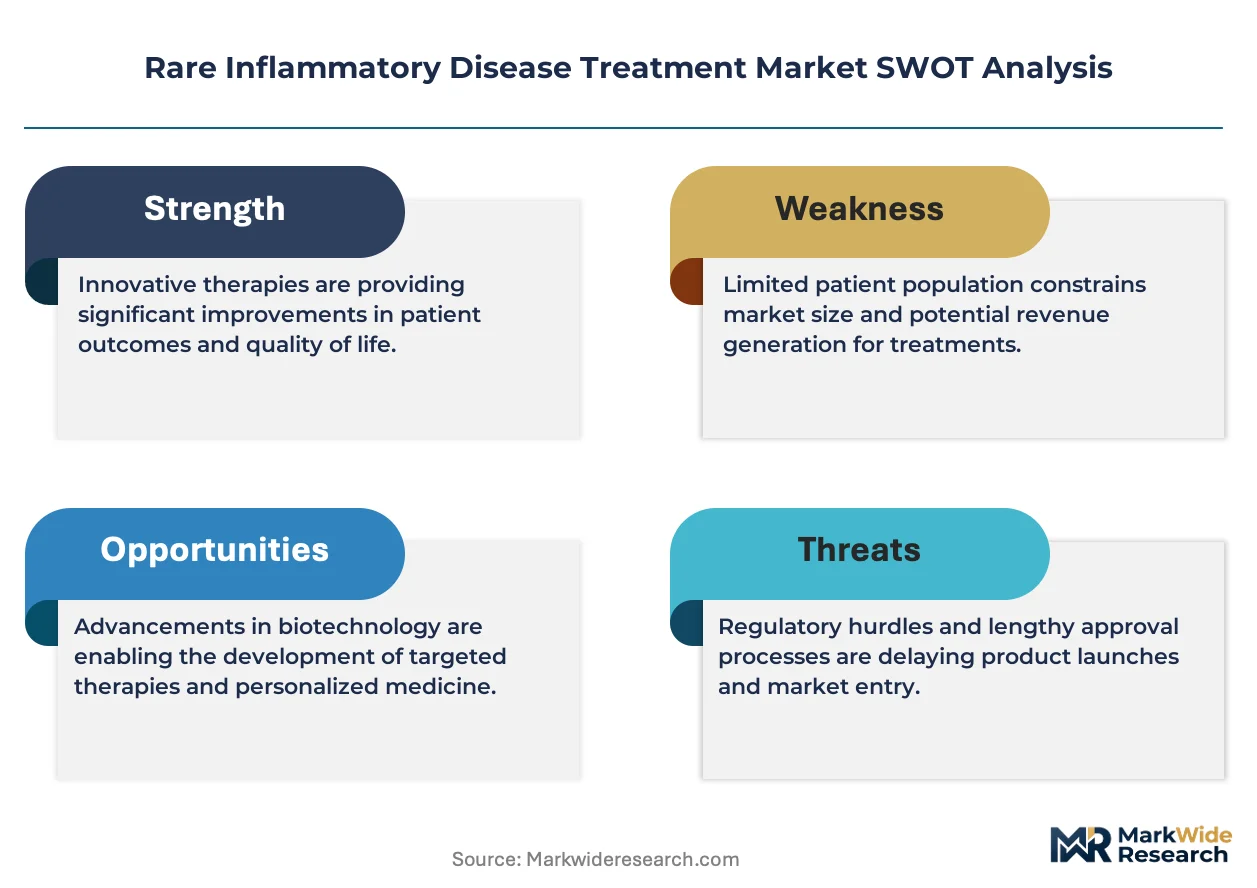
The FDA Orphan Drug Designation program accelerates development timelines and extends market exclusivity for sponsors addressing populations below 200,000 in the United States, while the EMA Committee for Orphan Medicinal Products enforces parallel incentives across European member states with centralized pediatric investigation plan requirements. Japan's PMDA Sakigake designation streamlines priority review for rare disease biologics, creating a tri-regional regulatory corridor that shapes global clinical development sequencing. Stakeholders must monitor evolving HTA body methodologies for gene therapy valuation as single-administration curative claims challenge traditional cost-effectiveness frameworks.
Market Dynamics
The FDA Orphan Drug Designation program, alongside EMA parallel pathways and Japan's PMDA Sakigake designation, is compressing clinical trial timelines while extending market exclusivity windows for sponsors addressing ultra-rare inflammatory populations.
Growth Catalysts
- EMA Committee for Orphan Medicinal Products:Centralized pediatric investigation plan requirements across European member states accelerate multi-country trial enrollment.
- Home-based infusion models:Specialty hospital networks in the United States are rotating toward self-administration protocols, reducing facility overhead and expanding patient access.
- Vector manufacturing cost decline:Gene therapy platforms targeting monogenic autoinflammatory pathways are achieving production economics that attract payer investment.
Market Restraints
- Companion diagnostic requirements:FDA mandates for biomarker-validated patient selection add 18-24 months to development timelines and fragment addressable populations.
- Plasma-derived raw material concentration:Biologic production depends on specialized fractionation capacity concentrated in Germany, Ireland, and the United States.
- HTA methodology lag:European health technology assessment bodies lack frameworks for single-administration curative claims, creating reimbursement uncertainty.
Strategic Opportunities
- Japan's centralized referral networks:Systemic sclerosis and dermatomyositis management infrastructure creates concentrated prescriber access for novel biologics.
- Subcutaneous formulation conversion:Intravenous-to-subcutaneous delivery innovation opens self-administration channels and reduces infusion center dependency.
- IRA price negotiation provisions:Orphan drug carve-outs for small-molecule therapies create pricing protection windows distinct from biologic categories.
Industry Challenges
- Gene therapy vector supply:Lentiviral and AAV manufacturing capacity constraints limit batch sizes and create queue-based patient access rationing.
- Cross-border licensing complexity:Patent thickets around cytokine inhibition mechanisms require multi-territory freedom-to-operate analyses before trial initiation.
- Biomarker standardization delays:Lack of harmonized interferon signature assays across academic medical centers complicates patient stratification for lupus nephritis trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Inflammatory Disease Treatment Market |
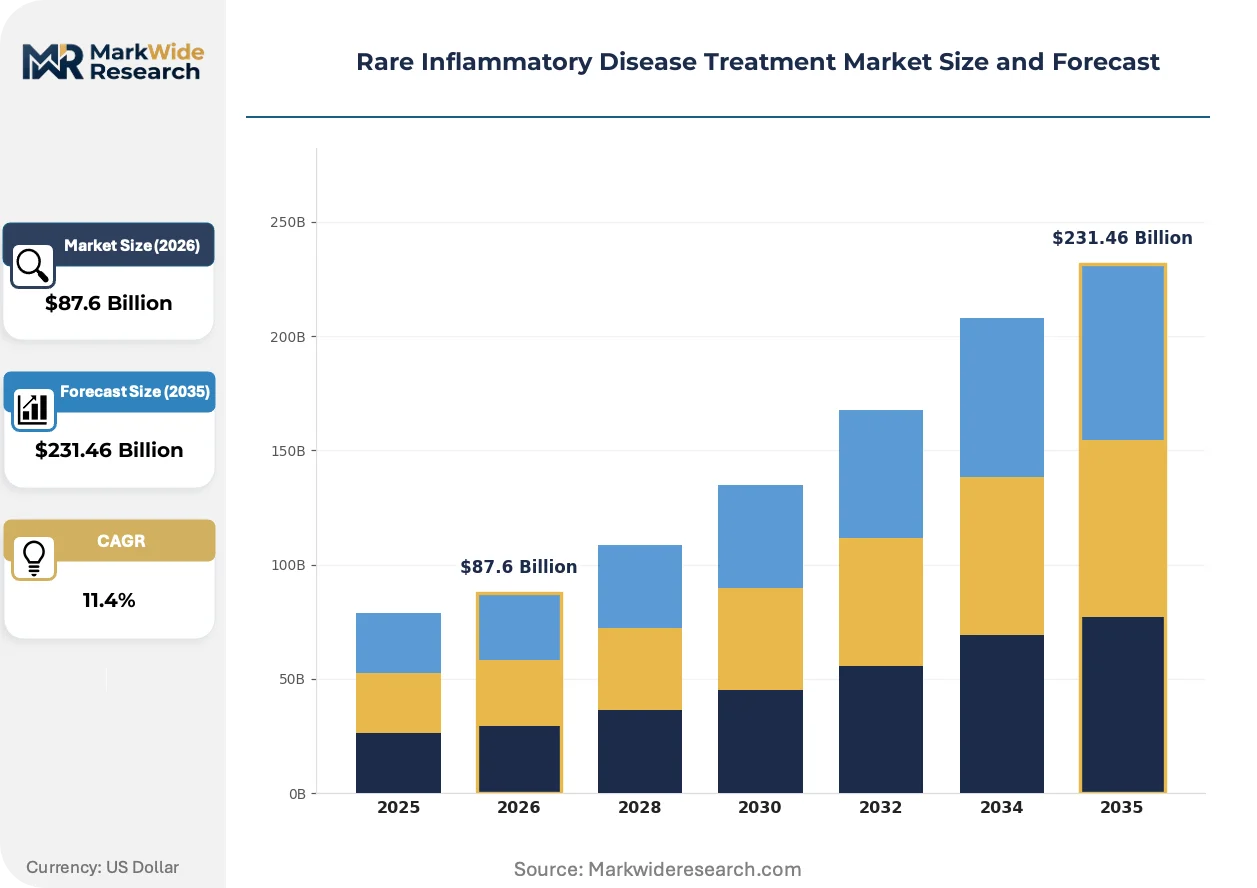
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Gene Therapy, Combination Therapy Therapy Area: Systemic Sclerosis, Sjögren's Syndrome, Dermatomyositis, Granulomatosis Delivery Mode: Injectable, Oral, Intravenous, Topical End User: Hospitals, Clinics, Home Care, Research Institutions |
| Companies Covered | Mallinckrodt Plc, Regeneron Pharmaceuticals Inc., AbbVie Inc., Swedish Orphan Biovitrum AB, Johnson & Johnson, Pfizer Inc., Bausch Health, Novartis AG, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Inflammatory Disease Treatment Market Strategic Shifts
Gene therapy platforms are compressing traditional chronic administration models while regulatory convergence across the FDA, EMA, and PMDA is reshaping clinical development sequencing. These forces are accelerating vector manufacturing scale-up and redefining payer value assessment frameworks.
RNA interference technology is fragmenting the small-molecule maintenance segment by enabling durable cytokine suppression without chronic immune suppression. Academic medical centers in Germany and Japan are adopting siRNA protocols for refractory autoinflammatory conditions. This modality is compressing the addressable market for oral immunosuppressants in systemic sclerosis maintenance.
REACH authorization requirements for novel biologic manufacturing inputs are forcing European sponsors to requalify supply chains for excipients and cell culture media. The EMA's tightened environmental risk assessments for genetically modified organisms used in production are extending facility approval timelines. Vector manufacturers are responding by consolidating production in Switzerland and Ireland where regulatory precedents exist.
Patient advocacy organizations are consolidating purchasing influence through centralized procurement negotiations with specialty pharmacies. United States-based rare disease foundations are establishing preferred distribution agreements that bypass traditional wholesale channels. This channel compression is most visible in dermatomyositis and vasculitis patient populations where prescriber concentration enables direct contracting.
Rare Inflammatory Disease Treatment Market Segmentation
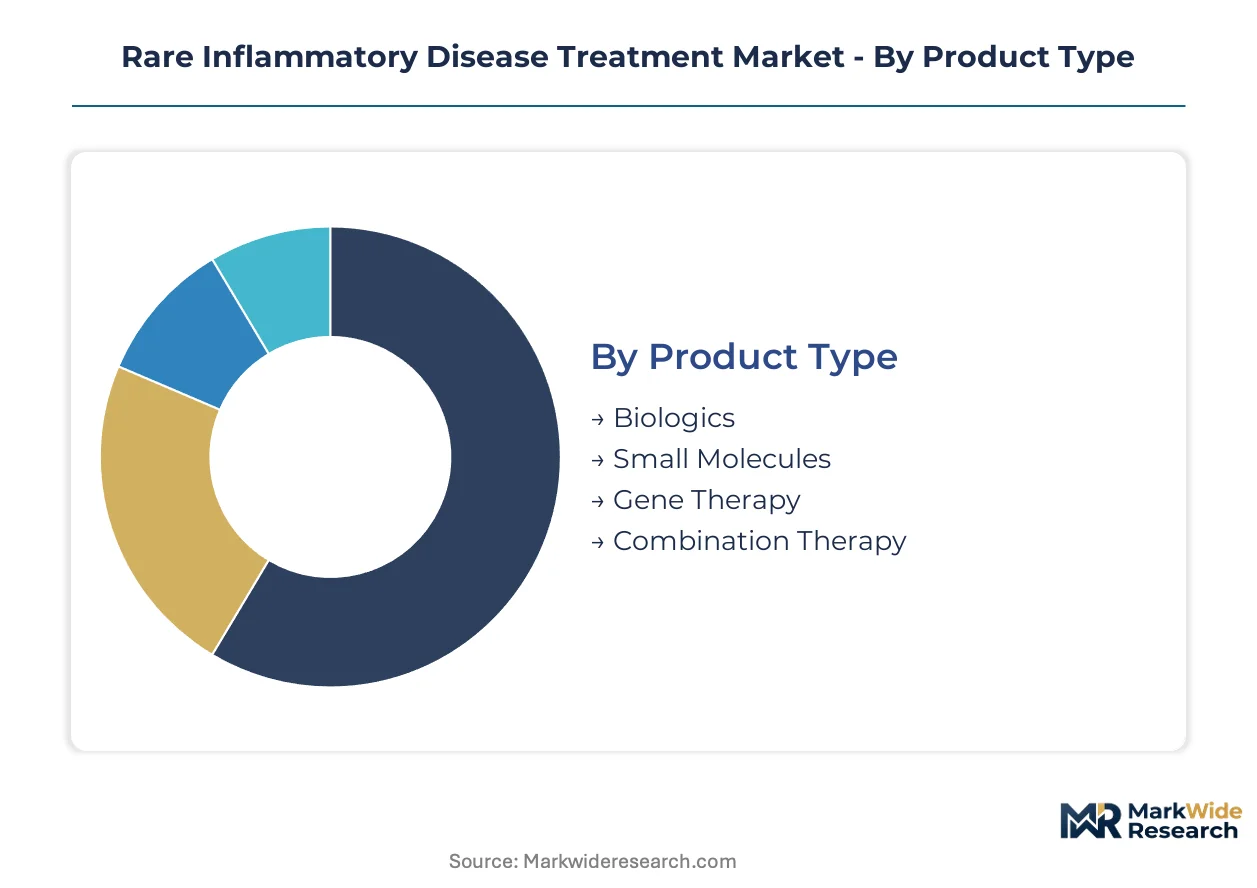
Segmentation in rare inflammatory disease treatment reveals how pricing power, reimbursement pathways, and patient access constraints vary across therapeutic modalities. Understanding these divisions exposes where sponsors capture value and where payers resist premium claims.
Product Type:
Margin pools concentrate in chronic administration regimens where manufacturing complexity creates natural exclusivity windows and pricing leverage.
- Biologics:Monoclonal antibodies and recombinant proteins targeting cytokine pathways require mammalian cell culture production and cold-chain distribution. United States specialty hospitals anchor demand for intravenous maintenance protocols in systemic sclerosis, with FDA Orphan Drug exclusivity sustaining premium positioning.
- Gene Therapy:Single-administration viral vector platforms deliver durable transgene expression for monogenic autoinflammatory disorders. Vector manufacturing cost declines and PMDA Sakigake priority review in Japan are accelerating clinical translation, though HTA valuation frameworks lag curative claims.
- Small Molecules:Oral immunosuppressants retain volume relevance in patient preference-driven maintenance settings.
- Combination Therapy:Sequential biologic-small molecule protocols address refractory cases through mechanism stacking.
Biologics holds installed capacity. Gene Therapy is rotating up the share rankings.
Therapy Area:
Volume concentration tracks where referral networks have matured and biomarker-validated endpoints enable regulatory approval.
- Systemic Sclerosis:Progressive fibrotic organ involvement drives chronic biologic consumption with established endpoints for interstitial lung disease progression. German centralized referral networks and United States academic medical centers concentrate prescriber access for novel antifibrotic-immunomodulator combinations.
- Dermatomyositis:Refractory cutaneous and muscle inflammation creates demand for B-cell depletion and JAK inhibition where standard corticosteroids fail.
- Sjögren's Syndrome:Exocrine gland dysfunction with systemic complications remains underserved by targeted therapies.
- Granulomatosis:ANCA-associated vasculitis subtypes require cyclophosphamide-sparing biologic induction protocols.
Systemic Sclerosis captures the deepest patient pools. Dermatomyositis is climbing the fastest as biomarker stratification improves trial success rates.
Delivery Mode:
Patient preference and reimbursement site-of-care policies are reconfiguring where value accumulates across the administration pathway.
- Injectable:Subcutaneous biologics enable self-administration and reduce infusion center dependency. United States home care networks and specialty pharmacies are expanding capacity for patient training and remote monitoring, with IRA reimbursement site-neutral policies compressing hospital outpatient margins.
- Intravenous:Hospital-based infusion retains concentration for acute induction and complex comorbidity management.
- Oral:Small molecule maintenance preserves patient autonomy in chronic settings.
- Topical:Limited to localized cutaneous manifestations with minimal systemic exposure.
Intravenous holds installed capacity. Injectable is rotating up the share rankings.
End User:
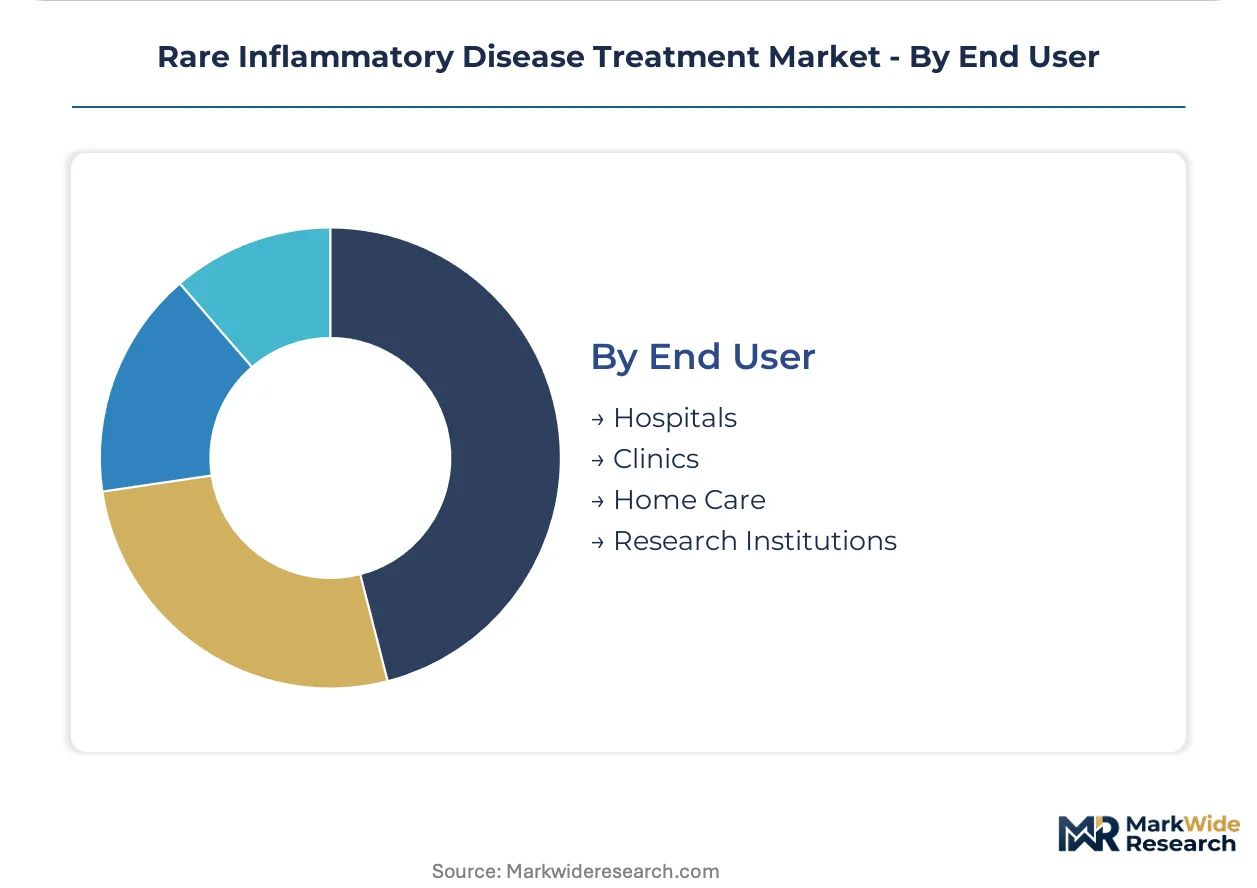
Channel structure determines pricing realization and patient access speed, with consolidation among specialty sites creating gatekeeper dynamics.
- Hospitals:Academic medical centers in Japan, Germany, and the United States concentrate rare disease expertise and clinical trial access. EMA centralized procurement frameworks and United States 340B pricing create divergent net revenue realizations for identical therapies.
- Home Care:Self-administration models expand through nursing-supported protocols and remote therapeutic monitoring.
- Clinics:Community rheumatology practices handle stable maintenance patients with established regimens.
- Research Institutions:Early-phase trial sites generate evidence but limited commercial volume.
Hospitals holds installed capacity. Home Care is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports plasma-derived raw materials to United States biologic manufacturers, anchoring transatlantic supply chains for rare inflammatory disease therapies. Japanese vector manufacturers supply lentiviral platforms to European gene therapy sponsors. Swissmedic-registered production facilities in Basel-Stadt consolidate fill-finish capacity for subcutaneous formulations.
United States
Academic medical centers in Boston and the Research Triangle anchor systemic sclerosis clinical trial enrollment. The FDA Orphan Drug Designation program compresses development timelines through priority review vouchers. Specialty hospital networks in Texas and California are rotating toward home-based infusion models.
Germany
Centralized referral networks in Bavaria and North Rhine-Westphalia concentrate dermatomyositis prescriber access. The EMA Committee for Orphan Medicinal Products enforces pediatric investigation plan requirements across member states. Plasma fractionation clusters in Hesse supply immunoglobulin raw materials to biologic manufacturers.
Japan
PMDA Sakigake designation streamlines priority review for autoinflammatory biologics in Kanto and Kansai regions. Systemic sclerosis management infrastructure in Tokyo and Osaka creates concentrated demand for novel antifibrotics. METI funding supports domestic vector manufacturing scale-up in Chubu.
Switzerland
Gene therapy production in Basel-Stadt and Zürich benefits from established Swissmedic environmental risk assessment precedents for genetically modified organisms. Vector manufacturers consolidate batch release capacity to serve EMA centralized procurement frameworks. Roche and Novartis legacy infrastructure anchors immunology R&D employment.
United Kingdom
London and Manchester academic centers participate in EMA parallel scientific advice for rare disease trials. The MHRA orphan medicine pathway mirrors EMA incentives post-Brexit. Northern England manufacturing sites handle fill-finish for subcutaneous biologics exported to European markets.
Rare Inflammatory Disease Treatment Market Competitive Environment
Listed leaders compete with private specialists across vector manufacturing and plasma fractionation, creating tiered access to scarce production inputs. Consolidation concentrates around mammalian cell culture capacity and viral vector platforms. Three archetypes dominate: integrated biopharma conglomerates with immunology depth, orphan-focused specialists with regulatory acceleration expertise, and contract development organizations with captive vector supply. Capacity expansion and strategic partnerships represent the dominant competitive moves as queue-based patient access rationing forces manufacturing prioritization decisions.
Among integrated biopharma conglomerates, AbbVie Inc. and Pfizer Inc. exemplify scale-driven archetypes with global manufacturing footprints, while Novartis AG occupies a position bridging gene therapy platform development with established biologic commercial infrastructure. Swedish Orphan Biovitrum AB represents the orphan-focused specialist archetype with concentrated rare disease regulatory expertise. Mallinckrodt Plc anchors the plasma-derived therapeutics segment where fractionation capacity constraints create natural exclusivity windows. These players collectively illustrate how manufacturing scarcity and regulatory acceleration capabilities determine competitive positioning in ultra-rare inflammatory populations.
| Leading Market Players |
|---|
| Mallinckrodt Plc |
| Regeneron Pharmaceuticals Inc. |
| AbbVie Inc. |
| Swedish Orphan Biovitrum AB |
| Johnson & Johnson |
| Pfizer Inc. |
| Bausch Health |
| Novartis AG |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
FDA Orphan Drug Designation and companion diagnostic mandates gate both supply qualification timelines and price differentiation across therapeutic tiers simultaneously. These regulatory requirements compress development economics for gene therapy platforms while extending exclusivity windows that sustain premium positioning for biologic maintenance protocols.
Pricing Analysis
Current-generation intravenous biologics command substantial premiums over prior-generation oral immunosuppressants, while next-generation gene therapy platforms are establishing curative-pricing paradigms. Three-tier pricing structure across premium gene therapies, standard biologics, and economy small molecules reflects manufacturing complexity and administration frequency. Price differentiation tracks FDA exclusivity status and biomarker-validated patient stratification. Pricing pressure stems from IRA negotiation provisions targeting small-molecule categories, though biologic carve-outs preserve margin structures. Hospital procurement committees demonstrate highest price sensitivity; academic medical centers with trial access show lowest sensitivity due to research funding offsets.
Supply Chain Analysis
Vector manufacturing lead times extending 12-18 months create inventory rationing queues that limit patient access to gene therapy platforms. Supply concentrates in Switzerland, Ireland, and the United States for lentiviral and AAV production, with Germany and the United States anchoring plasma-derived immunoglobulin fractionation. Raw material dependencies span specialized cell culture media, fetal bovine serum, and pharmaceutical-grade excipients subject to REACH authorization requirements. Single-source vulnerability pervades vector manufacturing where batch release capacity remains concentrated. Distribution runs through specialty pharmacy networks and hospital outpatient infusion centers, with home care channels expanding for subcutaneous formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing scarcity for viral vectors and plasma-derived inputs concentrates value capture among sponsors with secured production capacity. Vector batch release expertise and cold-chain logistics capabilities represent critical asset gaps that determine competitive viability.
For Market Incumbents: Compound manufacturing scarcity advantages by securing multi-year vector supply agreements and expanding mammalian cell culture footprint in Switzerland or Ireland. Gene therapy platform entrants threaten biologic maintenance revenue streams; defend through subcutaneous formulation conversions that reduce infusion center dependency and extend dosing intervals. For New Entrants and Emerging Players: Lead with RNA interference modalities for refractory autoinflammatory conditions where siRNA manufacturing complexity creates natural barriers to rapid competitive replication. Sjögren's Syndrome represents the most penetrable therapy area due to persistent unmet need and limited targeted competition. Pursue academic medical center partnerships in Germany or Japan to establish prescriber relationships before commercial infrastructure buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract development organizations possessing captive vector manufacturing capacity. Long-term viability hinges on sponsor ability to navigate HTA valuation evolution for single-administration curative claims. Watch for EMA centralized procurement framework adoption rates as the signal indicating pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Conversion | Reduces hospital outpatient dependency and aligns with IRA site-neutral reimbursement policies. |
| Companion Diagnostic Co-development | Secures FDA biomarker-validated patient selection and fragments addressable populations for pricing power. |
| Vector Manufacturing Scale-Up | Addresses lentiviral and AAV batch constraints that currently ration patient access queues. |
| Academic Medical Center Partnership | Concentrates prescriber access in systemic sclerosis and dermatomyositis referral networks. |
| HTA Evidence Generation Investment | Builds payer acceptance frameworks for gene therapy curative claims across European markets. |
Study Parameters
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying market size estimates. Primary interviews with payer access specialists and rare disease foundation leadership combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored value estimates.
Segmentation dimensions modeled span therapeutic modality, therapy area, delivery mode, and end-user channel across the projection horizon. Treatment line stratification, dosage form differentiation, and regional regulatory cluster dynamics informed volume and value disaggregation. CAGRs were derived from epidemiological trend analysis, pricing trajectory assessment, and adoption curve modeling for novel modalities. Forecast inputs incorporated biomarker validation timelines and HTA body methodology evolution for gene therapy valuation.
Forecasts assume regulatory continuity in FDA Orphan Drug Designation, EMA Committee for Orphan Medicinal Products frameworks, and PMDA Sakigake pathways; material policy shifts would require re-modeling. Vector manufacturing scale-up delays, companion diagnostic approval setbacks, or HTA curative-claim rejections represent specific risk factors. Revision becomes warranted when gene therapy batch release capacity or plasma fractionation throughput crosses utilization thresholds that trigger sustained patient access rationing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Byler Disease Market
Rare Diseases
Pure Red Cell Aplasia Market
Rare Diseases
Skeletal Dysplasia Market
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Lesch-Nyhan Syndrome Market
Rare Diseases
Hairy Cell Leukemia Market
Rare Diseases
Mucopolysaccharidosis (MPS) Treatment Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Acid Sphingomyelinase Deficiency Market
Rare Diseases
Erdheim-Chester Disease Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Yellow Nail Syndrome Treatment Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market