
 Brucellosis Market | 2026-2036
Brucellosis Market Size, Share, and Industry Trends Forecast 2026-2036
Brucellosis Market Outlook
mRNA platform migration is reshaping veterinary vaccine development timelines and cold-chain requirements. Zoetis leverages its mammalian cell culture infrastructure to anchor recombinant subunit production for livestock markets. Merck Animal Health competes through distributor-controlled channel networks across North American cattle operations. Boehringer Ingelheim differentiates its portfolio with temperature-stable formulations suited for rural veterinary deployment.
Brucellosis constitutes a zoonotic bacterial infection caused by Brucella species, primarily B. abortus, B. melitensis, and B. suis, with lipopolysaccharide-rich cell walls that complicate serological differentiation and vaccine design. Vaccines dominate product type revenue due to compulsory eradication programs in endemic zones, while diagnostic kits represent the fastest-expanding segment as point-of-need PCR platforms displace slow agglutination tests. Antibiotics retain stable demand for human therapeutic protocols despite prolonged dual-drug regimens and relapse risks.
The USDA's Center for Veterinary Biologics oversees potency and safety standards for brucellosis vaccines sold in United States markets, while the OIE Terrestrial Manual sets international harmonization benchmarks for diagnostic test validation. India's CDSCO and FSSAI jointly regulate veterinary pharmaceutical imports and residue limits in dairy products, shaping procurement criteria for agricultural institutions. Stakeholders must monitor regulatory divergence between live attenuated and recombinant vaccine approval pathways as countries revise national eradication blueprints.
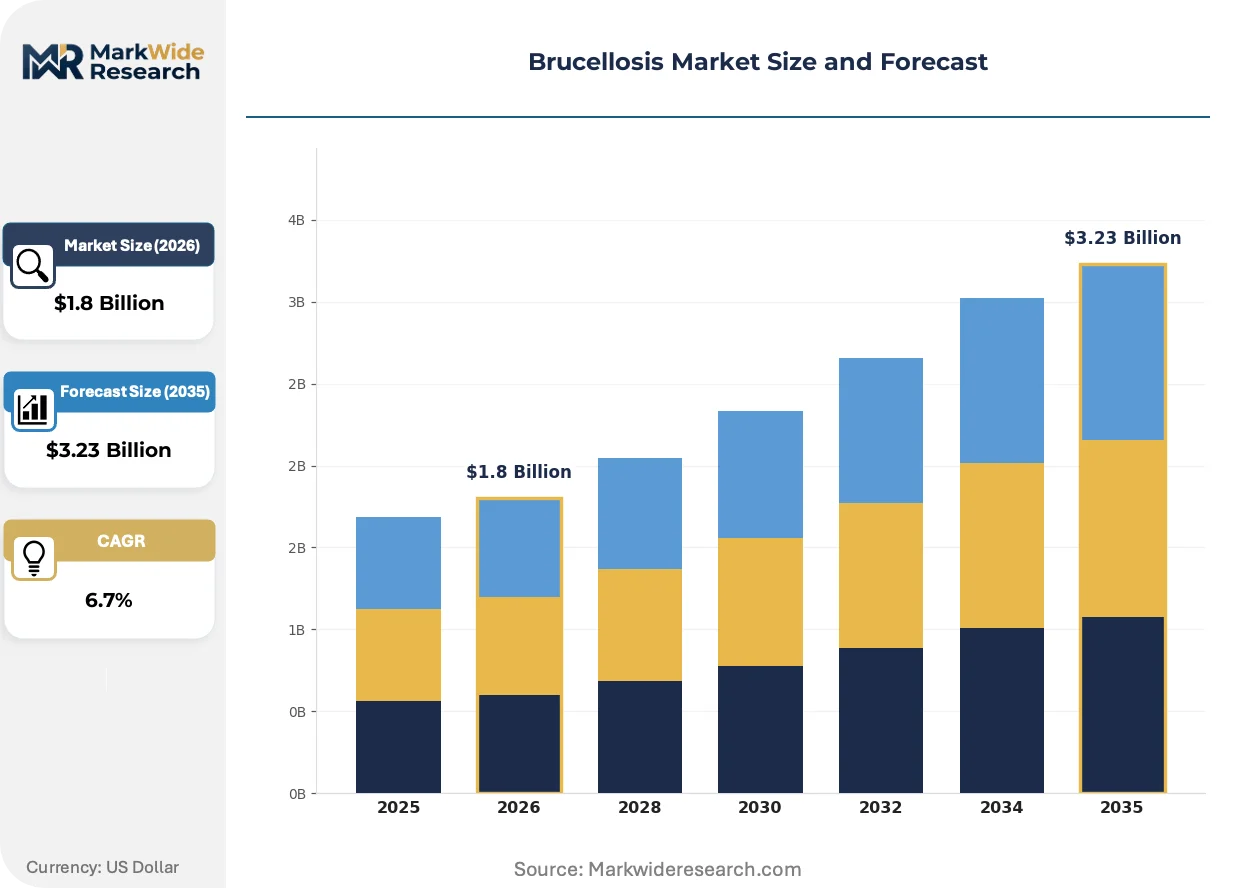
Market Dynamics
mRNA platform migration compresses veterinary vaccine development timelines from years to months while simultaneously elevating cold-chain infrastructure requirements across livestock-heavy economies. Livestock producers and veterinary clinics face pressure to upgrade storage and distribution capabilities as novel biologics displace traditional live attenuated formulations.
Growth Catalysts
- Compulsory Eradication Mandates:India's National Animal Disease Control Programme channels sustained public procurement toward brucellosis vaccination, anchoring demand for domestic and imported biologics alike.
- Point-of-Care PCR Platforms:Diagnostic kit manufacturers are capturing share from slow agglutination tests as veterinary clinics prioritize rapid pathogen identification in field conditions.
- Temperature-Stable Formulations:Advances in lyophilization and adjuvant chemistry enable vaccine deployment in rural veterinary settings lacking reliable refrigeration infrastructure.
Market Restraints
- Lipopolysaccharide Complexity:Brucella species share antigenic signatures with other gram-negative bacteria, complicating serological differentiation and elevating false-positive rates in surveillance programs.
- Prolonged Therapeutic Regimens:Human brucellosis treatment requires dual-antibiotic protocols spanning six weeks or longer, with relapse risks limiting patient compliance and therapeutic confidence.
- Regulatory Divergence:Approval pathways for live attenuated versus recombinant subunit vaccines differ substantially across national veterinary biologics frameworks, fragmenting market access.
Strategic Opportunities
- Sub-Saharan Livestock Belt:Underpenetrated veterinary service networks in Ethiopia, Nigeria, and Kenya present whitespace for diagnostic and vaccine distribution partnerships with agricultural ministries.
- Recombinant Marker Vaccines:Differentiation between infected and vaccinated animals (DIVA) capability unlocks export certification advantages for cattle operations in B. abortus-endemic zones.
- Public-Private Surveillance Integration:Blockchain-traceable livestock health records align with tightening residue monitoring requirements under India's FSSAI dairy safety protocols.
Industry Challenges
- Cold-Chain Infrastructure Deficits:Rural veterinary posts in tropical climates lack consistent electricity access, degrading mRNA and other temperature-sensitive biologics before administration.
- Serological Standardization Gaps:Harmonization between OIE Terrestrial Manual benchmarks and national laboratory proficiency testing remains incomplete, complicating cross-border livestock trade certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brucellosis Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Diagnostic Kits, Antibiotics, Biologics End User: Veterinary Clinics, Hospitals, Research Laboratories, Agricultural Institutions Distribution Channel: Direct Sales, Online Channels, Distributors, Retail Pharmacies Application: Animal Health, Human Health, Dairy Production, Research |
| Companies Covered | Zoetis, Merck Animal Health, Ceva Santé Animale, Boehringer Ingelheim, Colorado Serum Company, CZ Vaccines, Indian Immunologicals, Hester Biosciences Limited, Jordan Bio-Industries Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brucellosis Market Strategic Shifts
Livestock disease management is undergoing platform-level transformation as molecular diagnostics, novel vaccine architectures, and digital traceability systems converge. Veterinary service providers must adapt operational models to capture value from these simultaneous shifts.
Loop-mediated isothermal amplification (LAMP) kits are digitizing field-based brucellosis detection by eliminating thermal cycler dependency. Regional veterinary laboratories in India and Brazil are adopting these platforms to reduce turnaround times from days to hours. The technology is digitizing diagnostic workflows previously constrained by centralized laboratory capacity and skilled technician availability.
China's NMPA and SAMR have tightened veterinary biologics registration pathways, accelerating domestic vaccine output while raising barriers to imported products. Domestic manufacturers gain timeline advantages in dossier review, compressing market entry windows for foreign competitors. Livestock producers in Sichuan and Inner Mongolia are responding by consolidating procurement relationships with domestic suppliers.
Integrated livestock health platforms bundle vaccination records, diagnostic results, and movement permits into single digital interfaces. Cattle cooperatives in Denmark and the Netherlands are piloting these systems to streamline compliance with EU animal health law. The shift is most visible in export-oriented dairy operations where traceability documentation directly determines market access premiums.
Brucellosis Market Segmentation
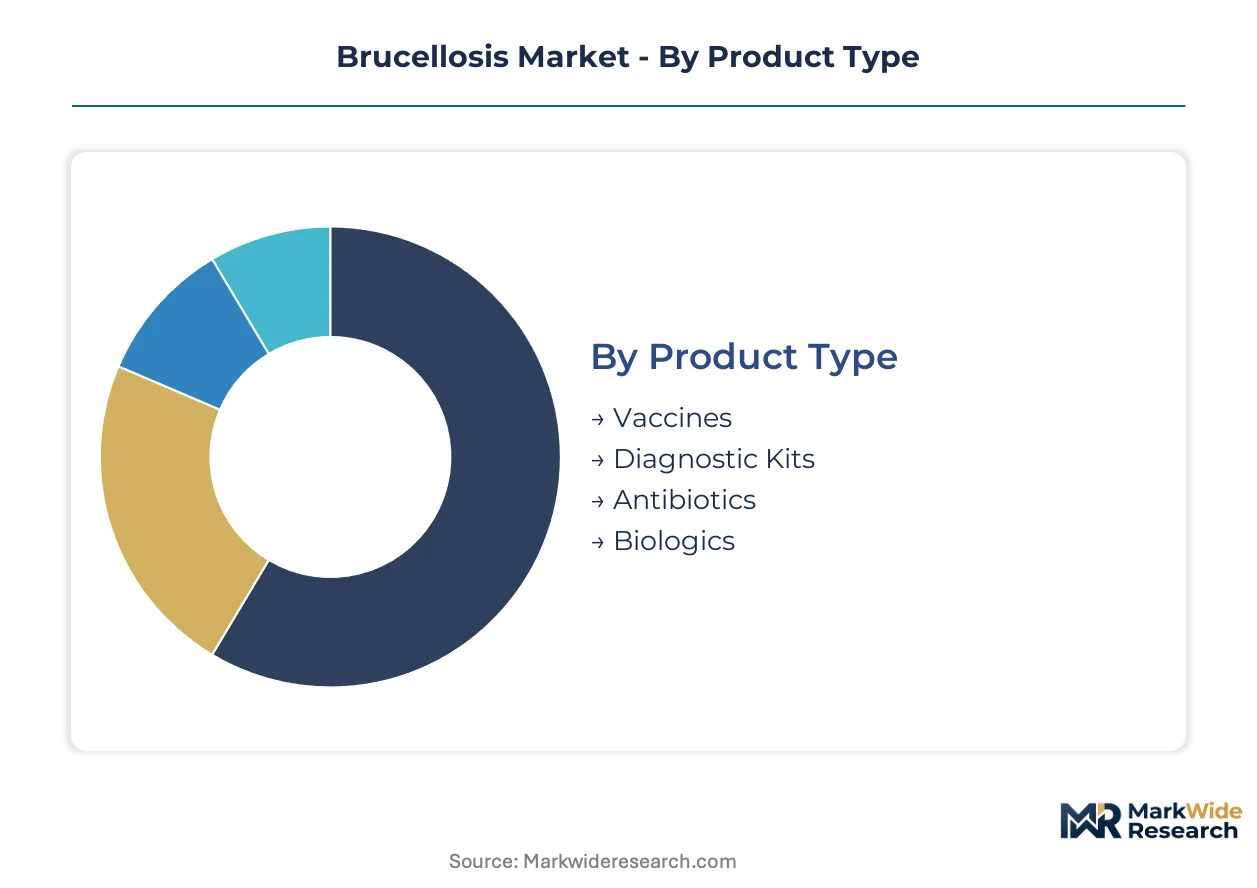
Brucellosis market segmentation reveals distinct procurement rhythms across product categories, with vaccines and diagnostic kits cycling through veterinary channels on fundamentally different timelines. Understanding these turnover patterns helps suppliers align inventory and technical support resources with actual field demand.
Product Type:
Vaccines turn over on multi-year eradication program cycles, while diagnostic kits refresh quarterly as veterinary clinics consume rapid-test inventories and upgrade platform generations.
- Vaccines:Live attenuated and recombinant subunit formulations dominate procurement under compulsory eradication mandates. India's National Animal Disease Control Programme channels sustained public tenders toward B. abortus and B. melitensis strains, with temperature-stable lyophilized products gaining preference in rural deployment zones lacking reliable cold-chain infrastructure.
- Diagnostic Kits:Point-of-care PCR and LAMP platforms are displacing slow agglutination tests in veterinary clinics across Brazil and India. Regional laboratories prioritize digitized workflows that eliminate thermal cycler dependency, compressing turnaround from days to hours in field conditions.
- Antibiotics:Dual-drug therapeutic protocols for human brucellosis—doxycycline-rifampin combinations—maintain stable hospital procurement despite six-week regimen durations and relapse risks that complicate patient compliance.
- Biologics:Recombinant marker vaccines with DIVA capability unlock export certification advantages for cattle operations in endemic zones, though regulatory divergence between live attenuated and subunit approval pathways fragments market access.
Vaccines anchor the volume base while diagnostic kits gain share at the steepest rate.
End User:
Customer concentration varies sharply by procurement authority, with agricultural institutions wielding bulk purchasing power against fragmented veterinary clinic demand.
- Veterinary Clinics:Frontline livestock health providers in India, Brazil, and Ethiopia drive diagnostic kit consumption and vaccine administration, with procurement constrained by cold-chain infrastructure deficits in tropical rural posts.
- Hospitals:Human therapeutic demand centers on infectious disease wards managing brucellosis relapse cases, with antibiotic stewardship programs scrutinizing prolonged dual-drug protocols.
- Research Laboratories:Brucella species characterization and vaccine efficacy studies depend on biosafety-3 containment facilities, with funding concentrated at USDA and OIE reference laboratories.
- Agricultural Institutions:India's state veterinary departments and China's provincial animal husbandry bureaus execute mass vaccination campaigns under national eradication blueprints, consolidating demand for temperature-stable formulations.
Agricultural institutions dominate procurement scale while veterinary clinics generate the highest transaction frequency.
Distribution Channel:
Channel selection tracks product temperature sensitivity and customer technical sophistication, with cold-chain biologics favoring controlled direct relationships.
- Direct Sales:Vaccine manufacturers maintain dedicated field forces for agricultural ministry tenders and large cattle cooperative accounts, ensuring cold-chain integrity through controlled logistics.
- Online Channels:Diagnostic consumables and smaller-format PCR platforms migrate to digital procurement for veterinary clinics seeking rapid replenishment of test kit inventories.
- Distributors:Merck Animal Health and comparable suppliers leverage distributor-controlled networks across North American cattle operations, extending reach into geographically dispersed ranching communities.
- Retail Pharmacies:Human antibiotic protocols flow through pharmacy channels in endemic regions, though prolonged regimens limit repeat purchase frequency relative to acute infection therapies.
Distributors capture the broadest geographic coverage while direct sales secure the highest-value eradication program contracts.
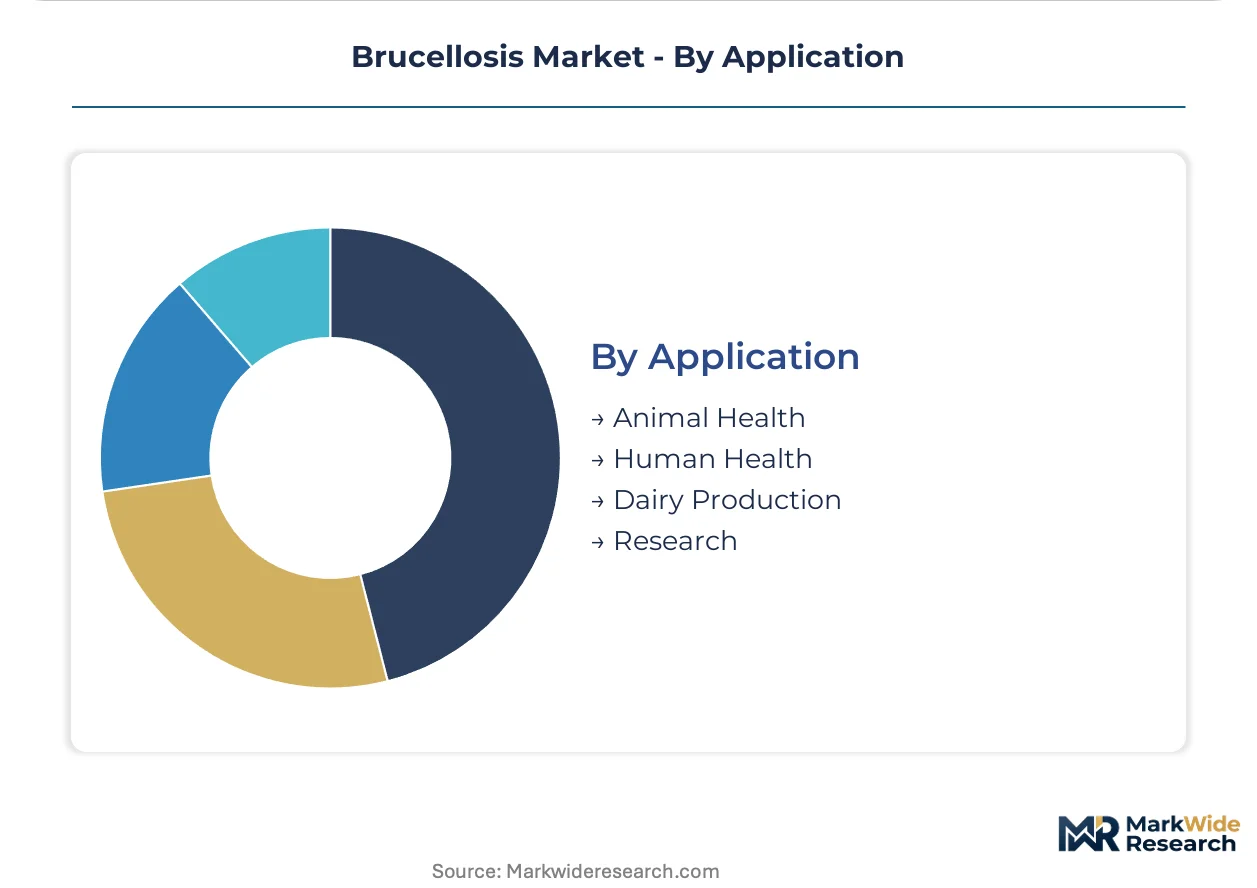
Application:
Application segmentation reflects divergent regulatory frameworks and reimbursement structures between veterinary and human health domains.
- Animal Health:Compulsory vaccination programs and serological surveillance dominate resource allocation, with China's NMPA and SAMR tightening domestic biologics registration to accelerate local vaccine output.
- Human Health:Therapeutic demand concentrates in Mediterranean, Middle Eastern, and Central Asian endemic zones, with WHO guidelines shaping national treatment protocols.
- Dairy Production:India's FSSAI residue monitoring requirements and EU animal health law drive traceability investments, with blockchain-integrated health records emerging in export-oriented operations.
- Research:Brucella pathogenesis studies and novel vaccine platform development occupy academic and government laboratories, with mRNA migration compressing development timelines from years to months.
Animal health commands the largest revenue pool while dairy production applications expand most quickly under tightening food safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports brucellosis vaccines and diagnostic platforms to Bangladesh, Nepal, and Sri Lankan livestock cooperatives under bilateral veterinary cooperation frameworks. Brazil ships temperature-stabilized biologics to Paraguay, Uruguay, and Argentine cattle operations through Mercosur-aligned sanitary protocols.
United States
USDA's Center for Veterinary Biologics mandates potency testing for all brucellosis vaccines entering interstate commerce, with B. abortus strain RB51 dominating procurement for cattle operations. Texas and Kansas feedlot clusters drive diagnostic kit consumption as large-scale producers implement serological surveillance for export certification to Mexico and Canada.
China
NMPA and SAMR tightened veterinary biologics registration timelines in 2023, compressing domestic vaccine approval windows while extending review periods for imported products. Sichuan and Inner Mongolia provincial animal husbandry bureaus now consolidate procurement with domestic manufacturers like CZ Vaccines, displacing foreign suppliers from mass vaccination tenders.
India
The National Animal Disease Control Programme channels sustained public procurement toward B. abortus and B. melitensis vaccination, with CDSCO regulating import pathways for veterinary pharmaceuticals. Gujarat and Rajasthan state veterinary departments deploy temperature-stable lyophilized vaccines through rural posts lacking reliable cold-chain infrastructure.
Brazil
ANVISA harmonizes veterinary biologics standards with OIE Terrestrial Manual benchmarks, enabling diagnostic kit exports to Mercosur partners. Mato Grosso and Goiás cattle cooperatives adopt point-of-care PCR platforms for rapid pathogen identification, displacing slow agglutination tests in field conditions.
Germany
EMA veterinary product standards shape EU-wide brucellosis eradication protocols, with Bavarian and Lower Saxon dairy operations leading blockchain-traceable health record adoption. These systems streamline compliance with FSSAI-equivalent residue monitoring requirements for Middle Eastern export markets.
Brucellosis Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement authority structures. Agricultural ministries consolidate vaccine demand through tender mechanisms while veterinary clinics generate dispersed diagnostic kit orders. Three archetypes dominate: multinational animal health conglomerates with mammalian cell culture infrastructure, regional biologics specialists with temperature-stable formulation expertise, and domestic manufacturers leveraging regulatory timeline advantages. Competitive moves center on distributor network expansion for geographic reach and lyophilization capacity additions for rural deployment.
Among scale-driven multinational players, Zoetis Inc. and Merck Animal Health occupy positions anchored by integrated research and manufacturing infrastructure. Boehringer Ingelheim exemplifies the formulation-specialist archetype through its emphasis on temperature-stable products suited for infrastructure-constrained veterinary posts. Indian Immunologicals represents the domestic-manufacturer archetype, securing timeline advantages in CDSCO-regulated procurement channels against foreign competitors facing extended dossier review periods.
| Leading Market Players |
|---|
| Zoetis |
| Merck Animal Health |
| Ceva Santé Animale |
| Boehringer Ingelheim |
| Colorado Serum Company |
| CZ Vaccines |
| Indian Immunologicals |
| Hester Biosciences Limited |
| Jordan Bio-Industries Center |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure on imported veterinary biologics widens pricing spreads between domestic and foreign-sourced vaccines while simultaneously reshaping procurement relationships toward local manufacturing partnerships. India's CDSCO import pathway delays and China's NMPA registration tightening compress margins for multinational suppliers while creating tiered cost structures across live attenuated, recombinant subunit, and mRNA platform categories.
Pricing Analysis
The technology-generation pricing gap separates legacy live attenuated vaccines from recombinant subunit formulations and emerging mRNA candidates, with each tier commanding distinct procurement budgets. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity, DIVA certification status, and cold-chain requirements. Pricing pressure stems from agricultural ministry tender consolidation in India and China, where volume aggregation squeezes per-dose margins. Veterinary clinics in tropical climates exhibit highest price sensitivity due to infrastructure constraints, while export-oriented dairy cooperatives prioritize certified premium tiers regardless of cost.
Supply Chain Analysis
Upstream feedstock for Brucella vaccine production draws from specialized cell culture media suppliers concentrated in the United States, Germany, and China, with fetal bovine serum and recombinant protein expression systems representing critical input dependencies. Adjuvant chemistry components and lyophilization stabilizers rest on chemical manufacturing networks spanning India and Switzerland. Single-source vulnerability in mammalian cell culture infrastructure creates chokepoint risk for recombinant subunit output. Distribution runs through controlled direct sales for cold-chain biologics and distributor networks for diagnostic consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brucellosis market functions as a defensive-moat arena where regulatory entrenchment protects incumbents through multi-year veterinary biologics registration timelines that deter rapid competitive entry.
For Market Incumbents: Harden cold-chain infrastructure partnerships in tropical veterinary posts to preempt temperature-stable formulation competitors. Secure backward integration into adjuvant manufacturing to buffer raw material cost volatility. Anchor lyophilization capacity additions in India and Brazil to defend against domestic manufacturers exploiting regulatory timeline advantages in CDSCO and ANVISA channels. For New Entrants and Emerging Players: Pursue point-of-care diagnostic kit distribution in Ethiopia, Nigeria, and Kenya where veterinary service networks remain underpenetrated and agglutination tests still dominate. Target LAMP platform partnerships with regional laboratories seeking thermal-cycler independence. Enter through agricultural ministry diagnostic tenders rather than vaccine registration pathways to bypass multi-year biologics approval barriers. For Investors and Strategic Acquirers: The market sits at a platform-transition phase that favors formulation-specialist targets with temperature-stable expertise over pure mRNA platform bets. Long-term viability hinges on DIVA-capable recombinant marker vaccine portfolios aligned with export certification requirements. Watch for OIE Terrestrial Manual harmonization initiatives as the signal indicating accelerated cross-border trade and consolidated procurement authority.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Temperature-stable formulations unlock rural veterinary deployment in India and sub-Saharan Africa. |
| Regulatory Approval Pathway Optimization | CDSCO and NMPA timeline advantages determine competitive positioning in public procurement tenders. |
| Point-of-Care Diagnostic Platform Launch | LAMP and PCR digitization displaces slow agglutination tests in Brazilian and Indian field conditions. |
| Backward Integration into Adjuvant Supply | Captive stabilizer production buffers cost volatility in lyophilized vaccine manufacturing. |
| Strategic Partnership with Agricultural Ministries | Blockchain-traceable health records align with India's FSSAI dairy safety protocol requirements. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, veterinary pharmaceutical trade data, and OIE reference laboratory publications. Veterinary biologics manufacturers, state animal husbandry department procurement officers, and diagnostic platform distributors provided operational perspectives. USDA Center for Veterinary Biologics guidance documents, CDSCO veterinary import regulations, and FSSAI residue monitoring protocols supplied institutional validation. Bottom-up segment sizing triangulated against top-down eradication program budget allocations.
Forecast inputs span vaccine platform generation transitions, diagnostic kit platform displacement rates, and agricultural ministry tender consolidation patterns across the analysis window. Segmentation modeling incorporates product type, end-user procurement authority, distribution channel temperature requirements, and application-specific regulatory frameworks. CAGRs derive from program budget trajectories, livestock population growth, and technology substitution curves in point-of-care diagnostics.
Macroeconomic conditions sit as an overlay; deviation in livestock commodity prices, veterinary service infrastructure investment cycles, or bilateral sanitary protocol negotiations would shift the trajectory. Forecasts reflect assumptions about regulatory pathway stability and eradication program continuity. Material shifts in mRNA platform cold-chain economics or OIE harmonization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Actinomycosis Market
Infectious Disease
Norovirus Infection Treatment Market
Infectious Disease
Hepatitis C Market
Infectious Disease
Infectious Enteritis Treatment Market
Infectious Disease
Valley Fever Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Q Fever Market
Infectious Disease
Virology Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Bronchitis Market
Infectious Disease
Efavirenz Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Clostridium Difficile Infection Treatment Market