
 Viral Hemorrhagic Fever Market | 2026-2036
Viral Hemorrhagic Fever Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Hemorrhagic Fever Market Analytics
The capability gap between large-scale biologics manufacturers and specialized antiviral developers is reorganizing competitive dynamics in viral hemorrhagic fever therapeutics. Gilead Sciences leverages its nucleotide analogue platform to sustain pipeline leadership across filovirus indications. BioCryst Pharmaceuticals Corp. anchors its position through polymerase inhibitor specialization, while Mapp Biopharmaceutical competes on monoclonal antibody development for Ebola virus disease.
Viral hemorrhagic fever comprises a group of zoonotic illnesses caused by RNA viruses from four families—Filoviridae, Arenaviridae, Bunyaviridae, and Flaviviridae—characterized by vascular permeability, coagulopathy, and multi-organ failure with case fatality rates ranging from 5% to 90% depending on virus species and clinical management. Vaccines command the largest product type segment through government stockpile commitments, while diagnostic kits represent the fastest-expanding category as point-of-care molecular platforms displace centralized laboratory confirmation in outbreak settings. The indication landscape tilts toward Ebola virus and Lassa Fever, where funded development programs concentrate, leaving Crimean-Congo Hemorrhagic Fever with thinner commercial pipelines despite its geographic breadth.
FDA emergency use authorization frameworks and WHO prequalification standards shape product registration pathways, with the former enabling accelerated deployment during declared outbreaks and the latter governing procurement eligibility for multilateral health agencies. The EU MDR and EMA orphan drug incentives influence European development priorities, particularly for indications with limited endemic presence in member states. Stakeholders must monitor how the FDA's Project BioShield and BARDA advanced development contracts reshape manufacturing scale requirements and geographic sourcing strategies for pandemic countermeasures.
Market Dynamics
Government stockpile procurement mandates are compressing development timelines and forcing manufacturers to prioritize platform scalability over indication-specific optimization in viral hemorrhagic fever countermeasures.
Growth Catalysts
- BARDA Advanced Development Contracts:US funding mechanisms de-risk manufacturing scale-up for nucleotide analogue platforms, accelerating transition from clinical to commercial readiness.
- Sub-Saharan Surveillance Infrastructure:Field laboratory networks in Nigeria, Sierra Leone, and Guinea drive point-of-care diagnostic kit deployment for Ebola and Lassa Fever detection.
- WHO R&D Blueprint:This priority-setting framework channels multilateral resources toward filovirus and arenavirus vaccine candidates, reducing sponsor uncertainty in indication selection.
Market Restraints
- Cold Chain Dependency:RNA-based vaccines require uninterrupted -80°C storage, limiting distribution to urban centers with reliable electricity infrastructure in endemic regions.
- Biologics Manufacturing Concentration:Contract development and manufacturing organizations cluster in North America and Western Europe, creating geographic mismatch with outbreak-prone zones.
- Animal Rule Limitations:FDA approval pathways for lethal pathogens rely on surrogate efficacy endpoints, complicating label expansion and reimbursement negotiations.
Strategic Opportunities
- Crimean-Congo Hemorrhagic Fever:Thinner commercial pipelines for this tick-borne indication across Central Asia, the Middle East, and Eastern Europe present first-mover advantages for polymerase inhibitor developers.
- EU MDR Orphan Drug Incentives:EMA fee waivers and protocol assistance provisions reduce regulatory costs for sponsors targeting rare hemorrhagic fever indications with limited European endemic presence.
- Multiplex Molecular Platforms:Convergence of CRISPR-based detection with smartphone-connected readout devices enables differential diagnosis of four virus families in single-test formats.
Industry Challenges
- Biosafety Level 4 Facility Scarcity:Live virus work requires specialized containment infrastructure, constraining preclinical and clinical manufacturing capacity to fewer than fifty sites worldwide.
- Outbreak-Driven Demand Volatility:Intermittent epidemic cycles complicate inventory planning and workforce retention for specialized antiviral developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Hemorrhagic Fever Market |
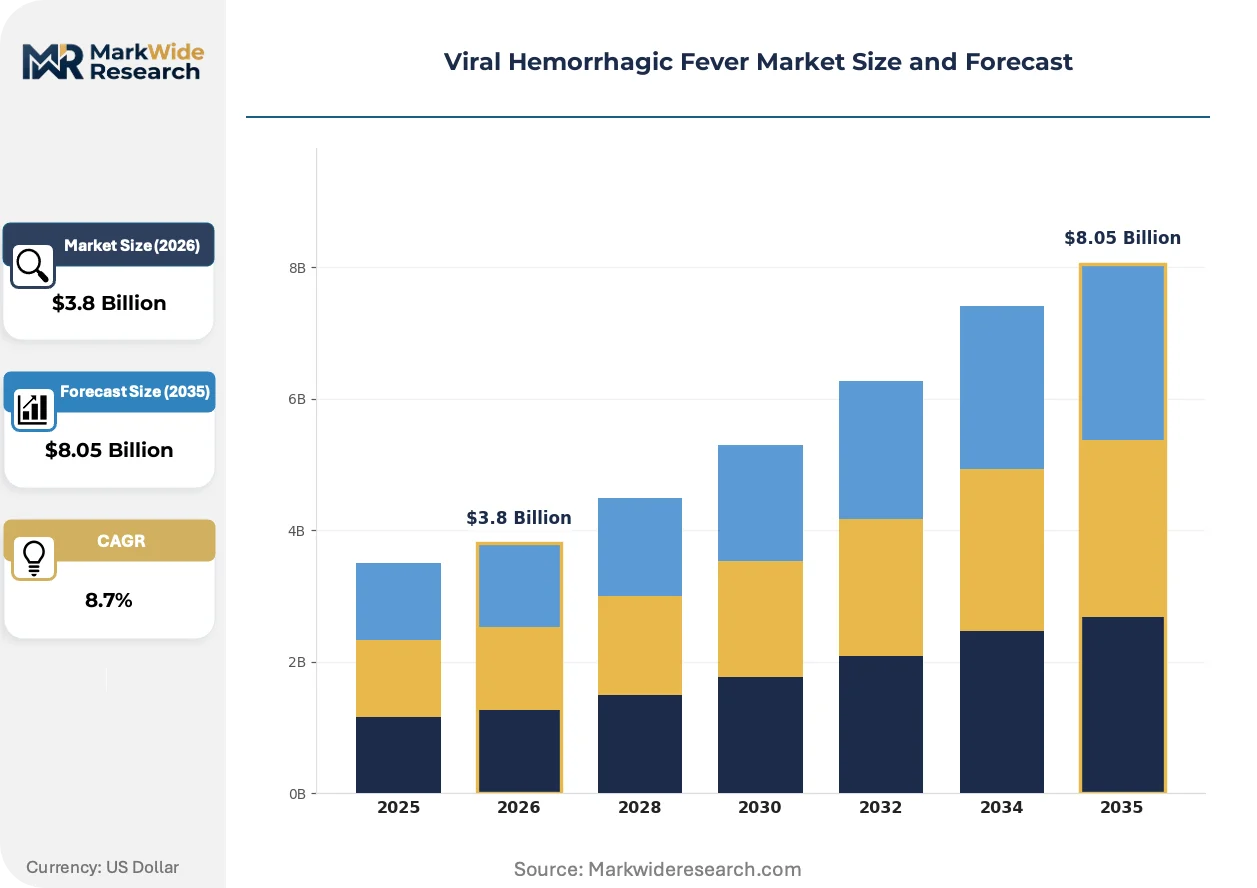
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Therapeutics, Diagnostic Kits, Laboratory Services Indication: Dengue Fever, Ebola Virus, Lassa Fever, Crimean-Congo Hemorrhagic Fever Care Setting: Hospitals, Clinics, Research Laboratories, Field Units End User: Healthcare Facilities, Government Agencies, NGOs, Pharmaceutical Companies |
| Companies Covered | Teva Pharmaceuticals, Roche Diagnostics Corp., Novartis AG, Pfizer Inc., Merck & Co., Inc., Abbott Laboratories, Gilead Sciences, BioCryst Pharmaceuticals Corp., Mapp Biopharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Hemorrhagic Fever Market Evolving Landscape
Platform standardization is colliding with indication-specific regulatory requirements, forcing developers to balance manufacturing flexibility against the validation burden of multi-pathogen production lines.
Recombinant vesicular stomatitis virus vector technology is fragmenting traditional vaccine development paradigms by enabling rapid strain adaptation without complete reformulation. National public health institutes in endemic countries are adopting this platform for local outbreak response manufacturing. The technology is fragmenting centralized supply chains into distributed, regional production networks with shorter distribution radii.
FDA Project BioShield procurement mechanisms are reshaping contract structures toward multi-year stockpile commitments with guaranteed minimum orders. This industrial consequence reduces revenue volatility for qualified suppliers while raising barriers for non-preferred vendors. Vaccine manufacturers with existing emergency use authorization track records capture disproportionate share of these indefinite-delivery contracts.
Integrated disease surveillance networks are compressing the interval between outbreak detection and therapeutic deployment. Ministries of health in West African nations now mandate real-time case reporting to centralized platforms, replacing paper-based notification systems. This behavioral shift is most visible in Nigeria's Lassa Fever response, where genomic sequencing integration enables variant-matched countermeasure selection within days of cluster identification.
Viral Hemorrhagic Fever Market Segmentation
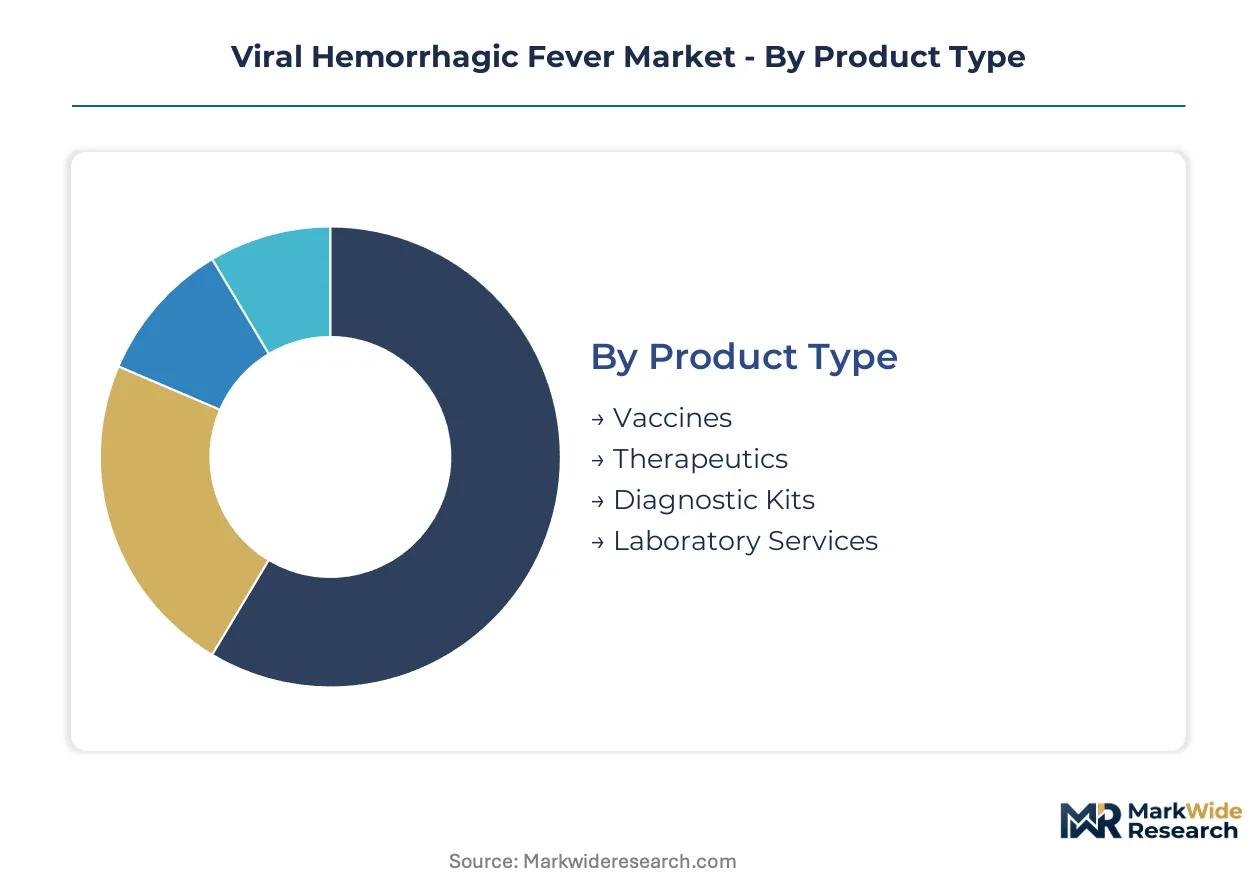
Product differentiation in viral hemorrhagic fever countermeasures tracks directly to procurement authority and deployment urgency. Government stockpile mandates favor platform scalability, while outbreak response demands portability and rapid turnaround.
Product Type:
Vaccines capture the deepest margin pools through multi-year stockpile commitments with guaranteed minimum orders.
- Vaccines:Recombinant vesicular stomatitis virus vectors and nucleotide analogue platforms dominate development pipelines. Procurement concentrates in US BARDA and WHO prequalification pathways, with cold chain infrastructure determining geographic reach. Government stockpile mandates compress development timelines and prioritize platform scalability.
- Diagnostic Kits:Point-of-care molecular platforms displace centralized laboratory confirmation in outbreak settings. Demand clusters in Nigeria, Sierra Leone, and Guinea field laboratory networks, driven by real-time case reporting mandates and genomic sequencing integration for variant-matched countermeasure selection.
- Therapeutics:Polymerase inhibitors and monoclonal antibodies target filovirus and arenavirus indications. Development concentrates in specialized antiviral developers with BSL-4 manufacturing partnerships.
- Laboratory Services:Genomic sequencing and biosafety containment operations support surveillance infrastructure. Revenue depends on outbreak-driven contract volatility and regional public health institute partnerships.
Vaccines hold installed capacity. Diagnostic kits are rotating up the share rankings.
Indication:
Development funding flows determine competitive intensity across this category, with filovirus and arenavirus programs commanding disproportionate resources.
- Ebola Virus:Filovirus vaccine candidates lead WHO R&D Blueprint prioritization. US FDA emergency use authorization frameworks and prior outbreak response manufacturing experience create vendor preference in indefinite-delivery contracts.
- Lassa Fever:Arenavirus surveillance infrastructure in West African ministries of health drives diagnostic deployment. Nigeria mandates real-time case reporting to centralized platforms, compressing detection-to-deployment intervals.
- Dengue Fever:Flaviviridae indication with broader geographic distribution but thinner hemorrhagic fever-specific countermeasure development relative to filovirus investment.
- Crimean-Congo Hemorrhagic Fever:Tick-borne Bunyaviridae indication across Central Asia, Middle East, and Eastern Europe. Commercial pipelines remain underdeveloped despite geographic breadth, presenting first-mover positioning for polymerase inhibitor developers.
Ebola virus commands development funding. Lassa Fever is climbing the fastest in diagnostic deployment volume.
Care Setting:
Facility biosafety tier and electricity reliability segment procurement specifications and distribution logistics.
- Field Units:Mobile diagnostic platforms and vaccine cold chain alternatives target remote outbreak zones. Deployment depends on solar-powered refrigeration and smartphone-connected readout devices for CRISPR-based detection.
- Hospitals:Urban referral centers with reliable -80°C storage infrastructure anchor vaccine administration. Case management protocols and intensive care capacity determine mortality outcomes.
- Clinics:Peripheral health facilities with limited containment infrastructure rely on rapid diagnostic referral and supportive care protocols.
- Research Laboratories:BSL-4 containment sites concentrate in fewer than fifty global locations, constraining preclinical and clinical manufacturing capacity for live virus work.
Hospitals hold installed capacity. Field units are gaining share fastest through surveillance network expansion.
End User:
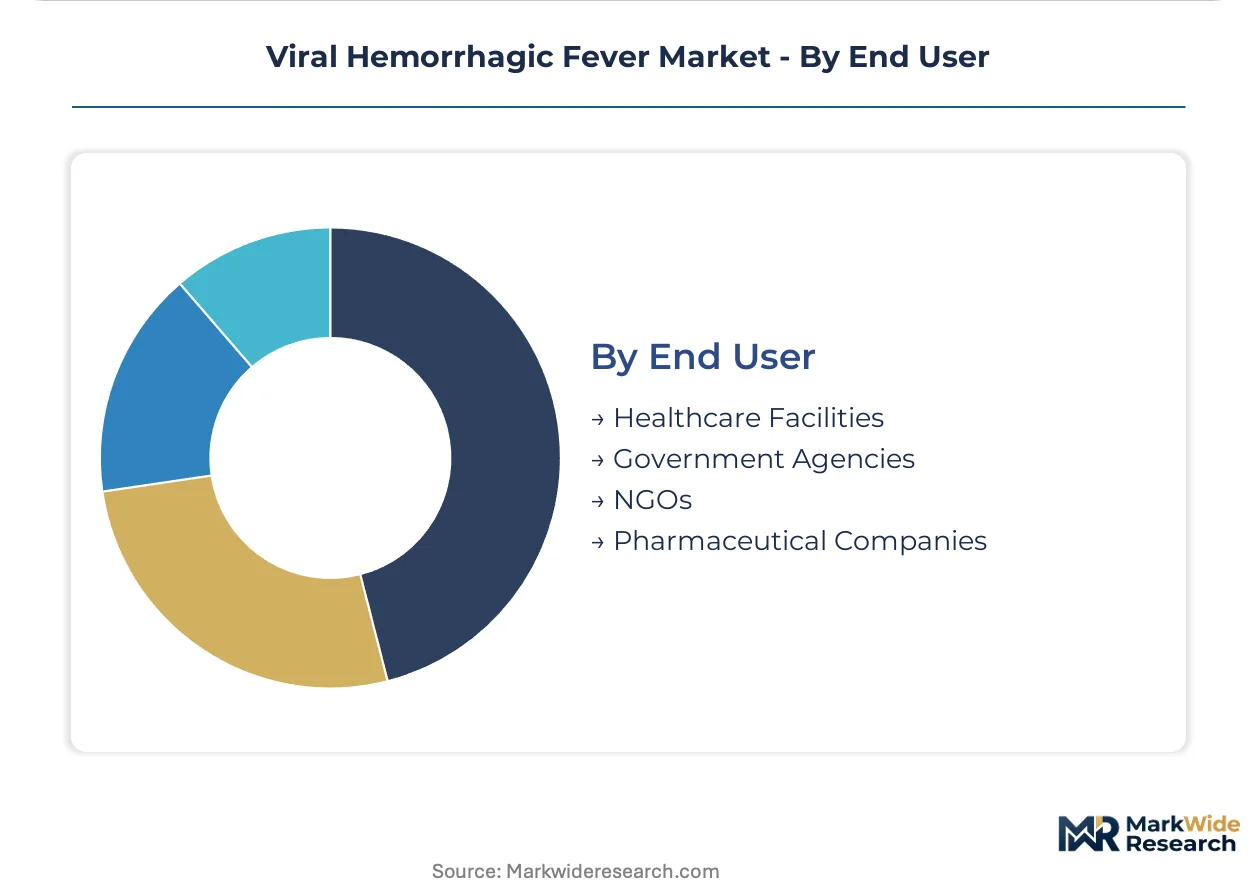
Budget authority and procurement mechanism type—stockpile versus emergency response—segment pricing power and contract structure.
- Government Agencies:National public health institutes and defense departments drive multi-year stockpile procurement. US Project BioShield and BARDA advanced development contracts reshape manufacturing scale requirements.
- Healthcare Facilities:Hospital networks and regional referral centers administer deployed countermeasures. Reimbursement negotiations face complexity from FDA Animal Rule surrogate endpoint limitations.
- NGOs:Médecins Sans Frontières and epidemic response consortia deploy field diagnostics and therapeutics during declared outbreaks. Demand spikes correlate with WHO emergency declarations.
- Pharmaceutical Companies:Sponsors and contract manufacturers access BSL-4 partnerships and platform technology licensing for pipeline expansion.
Government agencies hold installed capacity. Healthcare facilities are rotating up the share rankings through treatment center accreditation programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports nucleotide analogue platforms and monoclonal antibody manufacturing expertise while importing specialized BSL-4 containment services from European partners. This trade pattern concentrates value capture in North American biologics developers while leaving field deployment logistics to regional health systems in endemic zones.
United States
BARDA advanced development contracts and FDA emergency use authorization frameworks drive domestic manufacturing scale-up for filovirus vaccines. The country's national pharmaceutical regulator prioritizes platform standardization over indication-specific optimization in outbreak countermeasures. Boston and San Francisco anchor nucleotide analogue development clusters where Gilead Sciences maintains pipeline leadership.
Nigeria
Real-time case reporting mandates and Lassa Fever surveillance infrastructure compress detection-to-deployment intervals for diagnostic kits. The country's national pharmaceutical regulator aligns procurement specifications with WHO prequalification standards for field laboratory networks. Lagos and Abuja concentrate point-of-care molecular platform deployment for arenavirus detection.
Germany
EMA orphan drug incentives and EU MDR fee waivers reduce regulatory costs for sponsors targeting rare hemorrhagic fever indications. The country's national pharmaceutical regulator emphasizes protocol assistance provisions for polymerase inhibitor developers. Frankfurt and Munich host specialized antiviral manufacturing partnerships serving Central Asian outbreak zones.
China
NMPA accelerated review pathways for pandemic countermeasures attract multilateral procurement contracts for vaccine stockpiles. The country's national pharmaceutical regulator harmonizes emergency use frameworks with WHO R&D Blueprint priority-setting. Shanghai and Beijing concentrate CRISPR-based detection platform manufacturing for multiplex molecular diagnostics.
Sierra Leone
Ebola virus disease response infrastructure and genomic sequencing integration enable variant-matched countermeasure selection within days of cluster identification. The country's national health ministry mandates solar-powered refrigeration for vaccine cold chain alternatives in field units. Freetown anchors West African surveillance network coordination for filovirus outbreak response.
Viral Hemorrhagic Fever Market Competitive Landscape
Concentration sits with large-scale biologics manufacturers holding emergency use authorization track records and specialized antiviral developers with BSL-4 manufacturing partnerships. The market structure tilts toward platform scalability over indication-specific optimization due to government stockpile procurement mandates. Three archetypes dominate: nucleotide analogue platform specialists, polymerase inhibitor developers, and monoclonal antibody manufacturers. Competitive moves center on strategic partnerships for geographic sourcing and technology licensing for rapid strain adaptation.
Within the biologics manufacturing tier, Gilead Sciences, BioCryst Pharmaceuticals Corp., and Mapp Biopharmaceutical exemplify divergent specialization strategies. Gilead Sciences represents the nucleotide analogue platform archetype with sustained pipeline leadership across filovirus indications. BioCryst Pharmaceuticals Corp. occupies a position within polymerase inhibitor specialization, particularly for arenavirus and Bunyaviridae targets. Mapp Biopharmaceutical anchors the monoclonal antibody development segment for Ebola virus disease. These three entities collectively illustrate how capability gaps between manufacturing scales reorganize competitive dynamics in viral hemorrhagic fever therapeutics.
| Leading Market Players |
|---|
| Teva Pharmaceuticals |
| Roche Diagnostics Corp. |
| Novartis AG |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Abbott Laboratories |
| Gilead Sciences |
| BioCryst Pharmaceuticals Corp. |
| Mapp Biopharmaceutical |
| Others |
Value Network & Pricing Analysis
Platform manufacturing scale economies at nucleotide analogue facilities concentrate supply capacity in North American biologics clusters, compressing per-dose cost floors for stockpiled vaccines while elevating barriers for non-preferred vendors without BARDA qualification track records. This concentration feeds pricing power asymmetry between emergency use authorization holders and specialized antiviral developers competing on polymerase inhibitor differentiation.
Pricing Analysis
Government procurement agencies anchor contract pricing through multi-year stockpile commitments with guaranteed minimum orders under FDA Project BioShield mechanisms. Pricing stratifies across emergency use authorization tier, cold chain infrastructure grade, and manufacturing scale certification, with BARDA-qualified suppliers capturing premium terms against non-preferred vendors. Cost compression in point-of-care diagnostic tiers intensifies as CRISPR-based multiplex platforms displace centralized laboratory confirmation, squeezing margin pools for kit manufacturers without smartphone-connected readout integration. NGOs and epidemic response consortia exhibit highest price sensitivity due to outbreak-driven demand volatility, while national defense departments demonstrate lowest sensitivity given mandate urgency.
Supply Chain Analysis
Container availability constraints on transatlantic trade lanes elevate inbound logistics costs for European BSL-4 containment services contracted by North American sponsors. Manufacturing concentration clusters in the United States, Germany, and China, with nucleotide analogue platforms drawing from specialized fermentation capacity and monoclonal antibody production resting on Chinese hamster ovary cell line supply. Single-source vulnerability pervades BSL-4 facility access, with fewer than fifty global sites constraining live virus work capacity. Distribution runs through government stockpile depots and WHO prequalified cold chain networks, with regional field laboratory deployment managed by endemic country health ministries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outbreak-driven demand cycles position this market for cyclical recovery as surveillance infrastructure investment compresses detection-to-deployment intervals and stockpile refresh mandates accelerate procurement velocity.
For Market Incumbents: Compound platform standardization advantages by securing indefinite-delivery contract extensions with BARDA and WHO prequalification pathways before emerging entrants achieve emergency use authorization track records. Prioritize backward integration into BSL-4 manufacturing partnerships to defend against capacity scarcity threats from biosafety containment site concentration. Invest in nucleotide analogue strain adaptation capabilities to maintain pipeline leadership as recombinant vesicular stomatitis virus vector technology fragments centralized supply chains. For New Entrants and Emerging Players: Anchor in Crimean-Congo Hemorrhagic Fever indication development where commercial pipelines remain underdeveloped despite geographic breadth across Central Asia, the Middle East, and Eastern Europe. Target polymerase inhibitor specialization for tick-borne Bunyaviridae targets, leveraging EU MDR orphan drug incentives to reduce regulatory cost burdens. Pursue technology licensing agreements with national public health institutes in endemic countries for distributed regional manufacturing under the recombinant vesicular stomatitis virus vector platform. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vaccine manufacturers with multi-year government stockpile commitments and guaranteed minimum order structures. Long-term viability over the projection horizon hinges on platform scalability against indication-specific regulatory validation burdens. Target specialized antiviral developers with BSL-4 manufacturing partnerships and polymerase inhibitor pipelines for arenavirus and Bunyaviridae indications. Monitor WHO R&D Blueprint priority-setting shifts as inflection indicators for multilateral funding flow redirection.| Strategic Initiative | Industry Significance |
|---|---|
| BARDA Advanced Development Contracting | De-risks manufacturing scale-up for nucleotide analogue platforms transitioning to commercial readiness. |
| WHO Prequalification Pathway Navigation | Unlocks procurement eligibility for multilateral health agencies in sub-Saharan African endemic zones. |
| BSL-4 Manufacturing Partnership Formation | Secures containment infrastructure access for live virus work constrained to fewer than fifty global sites. |
| Multiplex Molecular Platform Integration | Enables CRISPR-based differential diagnosis of four virus families with smartphone-connected readout deployment. |
| EU MDR Orphan Drug Incentive Utilization | Reduces regulatory costs through EMA fee waivers for rare hemorrhagic fever indications with limited European endemic presence. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA emergency use authorization filings, WHO prequalification status databases, BARDA contract award records, and EMA orphan drug designation registers. Primary interviews engaged drug development executives at nucleotide analogue platform specialists, regulatory affairs leads navigating FDA Animal Rule pathways, hospital procurement managers in Nigerian referral centers, and formulary directors at multilateral health agencies. Bottom-up demand modeling triangulated against top-down epidemiological burden projections and government stockpile commitment disclosures.
Segmentation dimensions modeled span product type, indication, care setting biosafety tier, and end user procurement authority across the projection horizon. CAGR derivation incorporated epidemiological surveillance data, outbreak frequency distributions, and stockpile refresh cycle patterns. Industry-specific forecast inputs included WHO R&D Blueprint priority-setting revisions and FDA Project BioShield indefinite-delivery contract award trajectories.
Underlying assumptions cover sustained government funding for outbreak preparedness infrastructure, with deviation risk concentrated in epidemic cycle intermittency and cold chain deployment constraints in electricity-unreliable endemic regions. Practitioners should keep alternative scenarios live as WHO R&D Blueprint priority rankings and FDA emergency use authorization pathway criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Measles Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Pork Tapeworm Infection Treatment Market
Infectious Disease
Viral Gastroenteritis Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Point-Of-Care Infectious Disease Testing Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Global Veterinary Infectious Disease Diagnostics Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Virology Market
Infectious Disease
Norovirus Infection Treatment Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Gram Positive Bacterial Infections Market