
 Ceftriaxone Injection Market | 2026-2036
Ceftriaxone Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Ceftriaxone Injection Market Insights
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape for sterile injectable manufacturers seeking European market access. Hikma Pharmaceuticals leverages vertically integrated API and finished-dose capabilities to sustain supply security across regulated markets. Aurobindo Pharma anchors its position through high-volume production of cephalosporin APIs for internal formulation use and external supply. Qilu Pharmaceutical dominates domestic tender participation in China while navigating registration pathways for US FDA and EU EMA approvals.
Ceftriaxone injection is a sterile, third-generation cephalosporin antibiotic formulated as sodium salt for parenteral administration, typically reconstituted from lyophilized powder or supplied as ready-to-use intravenous solutions with specified potency per vial. It functions by inhibiting bacterial cell wall synthesis through affinity for penicillin-binding proteins, serving as a first-line or reserve therapy for severe gram-negative and selected gram-positive infections across inpatient and outpatient settings. Vials and pre-filled syringes occupy distinct margin pools, with pre-filled formats commanding premium positioning in emergency and surgical prophylaxis applications where dosing speed reduces clinical workflow friction. Hospitals remain the dominant end-user channel, though ambulatory surgical centers represent a faster-growing site of care as same-day procedures expand and post-discharge antimicrobial protocols shift to outpatient administration.
FDA Current Good Manufacturing Practice enforcement and EMA's Falsified Medicines Directive serialization requirements shape product standards, batch release documentation, and distribution traceability for ceftriaxone injectables entering regulated markets. India's CDSCO and China's NMPA maintain parallel bioequivalence and stability testing protocols that govern which manufacturers qualify for public procurement tenders versus private hospital contracts. Stakeholders must monitor how antimicrobial resistance surveillance data from WHO and national health agencies influence formularies, as resistance pattern shifts directly alter which cephalosporin generations retain preferred status in treatment guidelines.
Market Dynamics
Antimicrobial stewardship mandates across acute care networks are compressing formulary slots for broad-spectrum antibiotics while simultaneously elevating procurement scrutiny on supplier qualification and batch traceability.
Growth Catalysts
- Stewardship program expansion:Hospital networks in the United States are embedding FDA Current Good Manufacturing Practice standards into vendor scorecards, privileging manufacturers with documented API sourcing transparency.
- India's API-to-finished-dose integration:Domestic manufacturers under CDSCO oversight are capturing government tender volumes through captive backward integration into cephalosporin intermediate production.
- Pre-filled syringe format preference:Emergency departments and ambulatory surgical centers are specifying ready-to-use presentations to reduce reconstitution errors and accelerate dosing workflows.
Market Restraints
- API supply concentration:Cephalosporin intermediate manufacturing clusters in Zhejiang and Shandong provinces create single-source dependency risks for finished-dose producers elsewhere.
- EMA serialization compliance:Falsified Medicines Directive traceability requirements impose capital-intensive packaging line upgrades that disqualify smaller manufacturers from European tender participation.
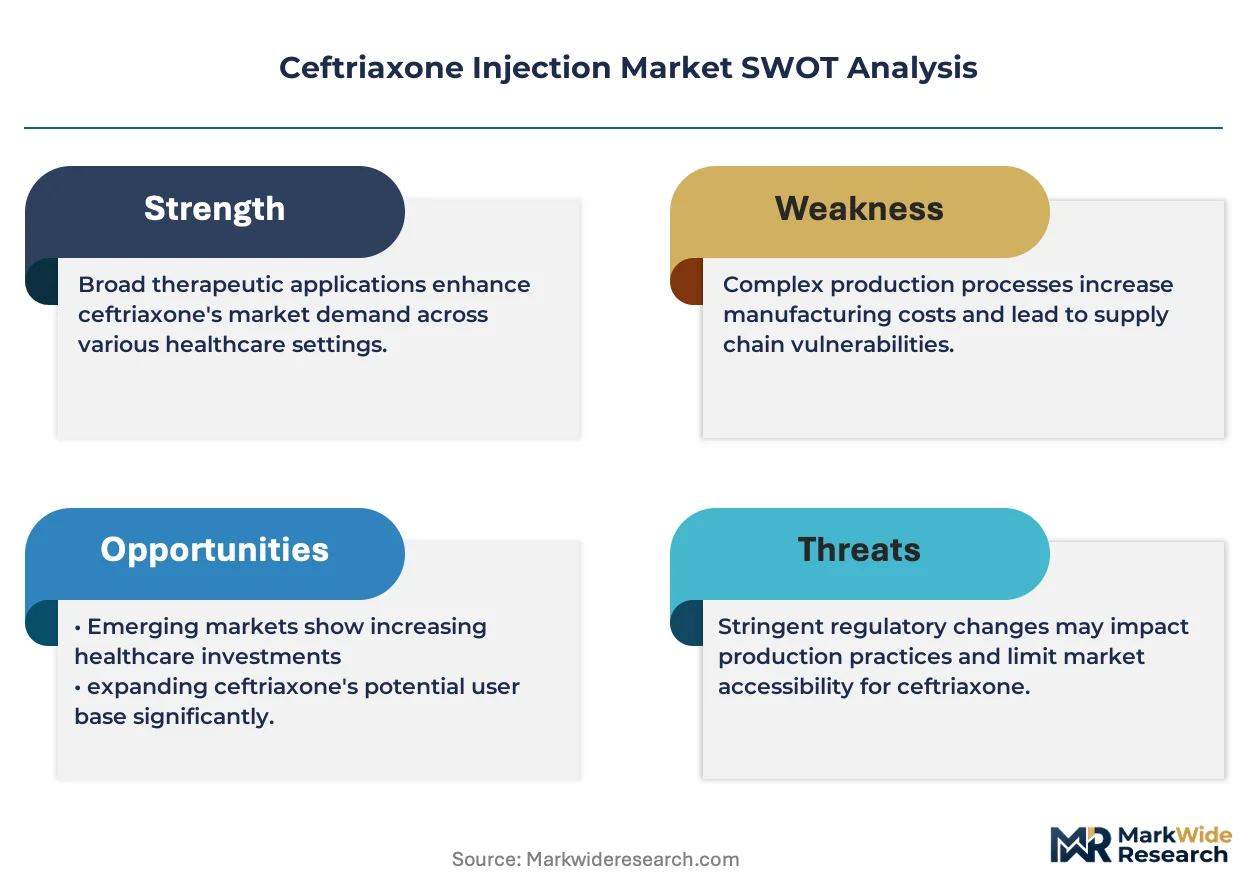
- Carbapenem substitution pressure:Rising gram-negative resistance in intensive care units is displacing ceftriaxone from empiric sepsis protocols in favor of broader-spectrum reserve antibiotics.
Strategic Opportunities
- Brazilian public hospital expansion:ANVISA registration pathways for sterile injectables remain underpenetrated by Asian manufacturers relative to domestic and European incumbents.
- Outpatient parenteral antimicrobial therapy:Home infusion services are creating demand for stability-enhanced formulations with extended room-temperature storage claims.
- EU Medical Device Regulation convergence:CE marking under MDR Article 117 is enabling combination product positioning for device-integrated delivery systems at premium price tiers.
Industry Challenges
- Sterile manufacturing workforce scarcity:Aseptic processing technicians with active pharmaceutical ingredient handling certification command wage premiums that compress margin structures for mid-scale facilities.
- Bioequivalence study backlog:FDA and EMA reference product sourcing delays are extending abbreviated new drug application timelines for generic injectable filers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceftriaxone Injection Market |
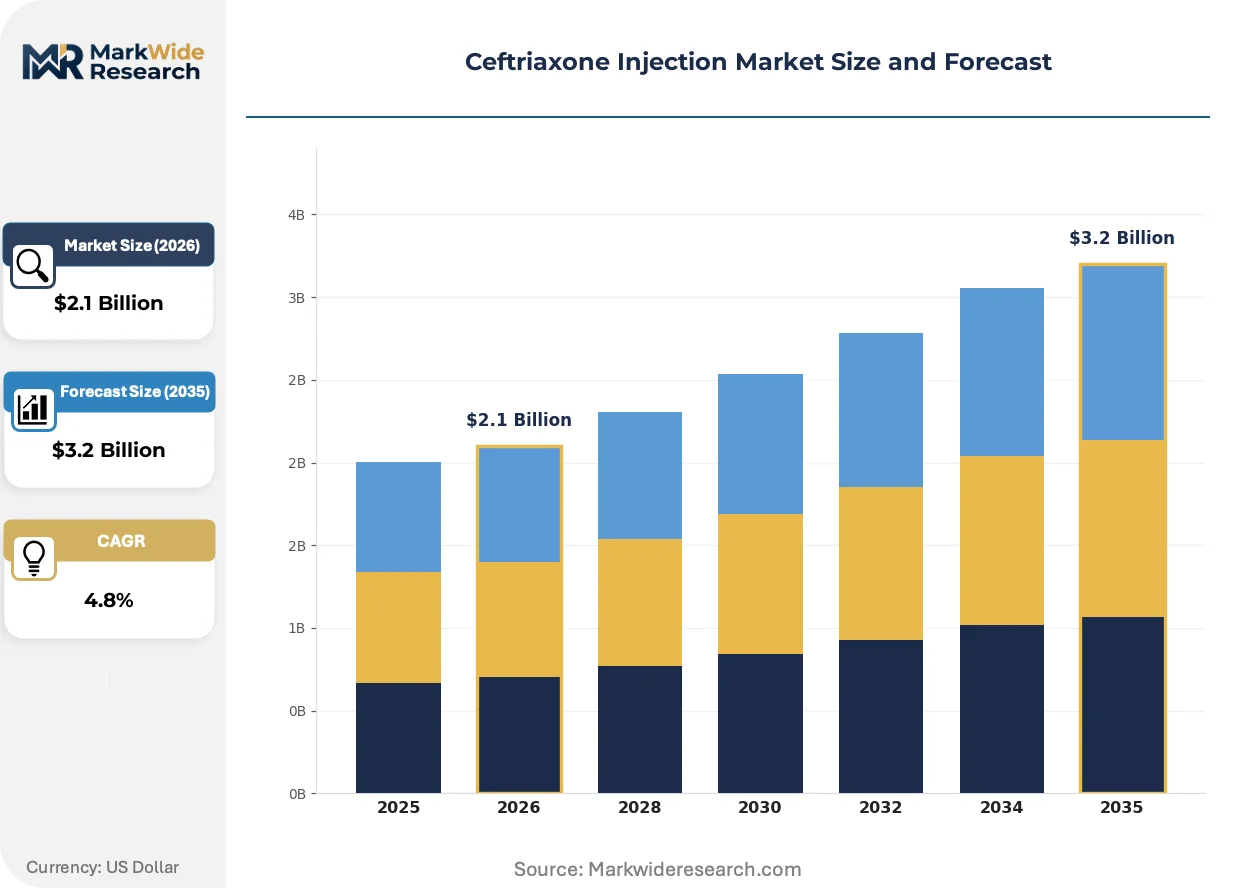
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Intravenous Solutions, Pre-filled Syringes, Ampoules Application: Bacterial Infections, Meningitis, Pneumonia, Surgical Prophylaxis End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Healthcare Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Oral |
| Companies Covered | Hikma Pharmaceuticals, Aurobindo Pharma, Qilu Pharmaceutical, Novartis, Lupin Pharmaceuticals, Orchid Pharma, Nectar Lifesciences, ACS DOBFAR, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceftriaxone Injection Market Trends and Innovations
Ready-to-use formulation technologies and packaging integration are compressing the gap between manufacturing output and point-of-care administration speed.
Lyophilized powder-in-vial formats with rapid-dissolution excipient matrices are miniaturizing reconstitution time requirements. Hospital pharmacies facing technician staffing constraints are adopting these presentations to maintain throughput without expanding compounding infrastructure. The technology is miniaturizing the clinical workflow friction that previously justified premium pricing for liquid-stable alternatives.
EMA's Falsified Medicines Directive serialization mandates are forcing wholesale distributors to deploy verification systems at secondary packaging levels. Manufacturers serving European markets must integrate aggregation events between primary vial labeling and case-level tracking. Sterile injectable specialists with existing serial number management infrastructure are capturing tender allocations from competitors facing compliance timeline compression.
Consolidated procurement consortia in the United States are displacing individual hospital formulary autonomy with standardized antimicrobial stewardship protocols. Multi-hospital systems are mandating therapeutic interchange policies that restrict ceftriaxone to specific indication categories. This behavioral shift is most visible in Medicare-dependent networks where readmission penalty exposure elevates resistance surveillance reporting requirements.
Ceftriaxone Injection Market Segmentation
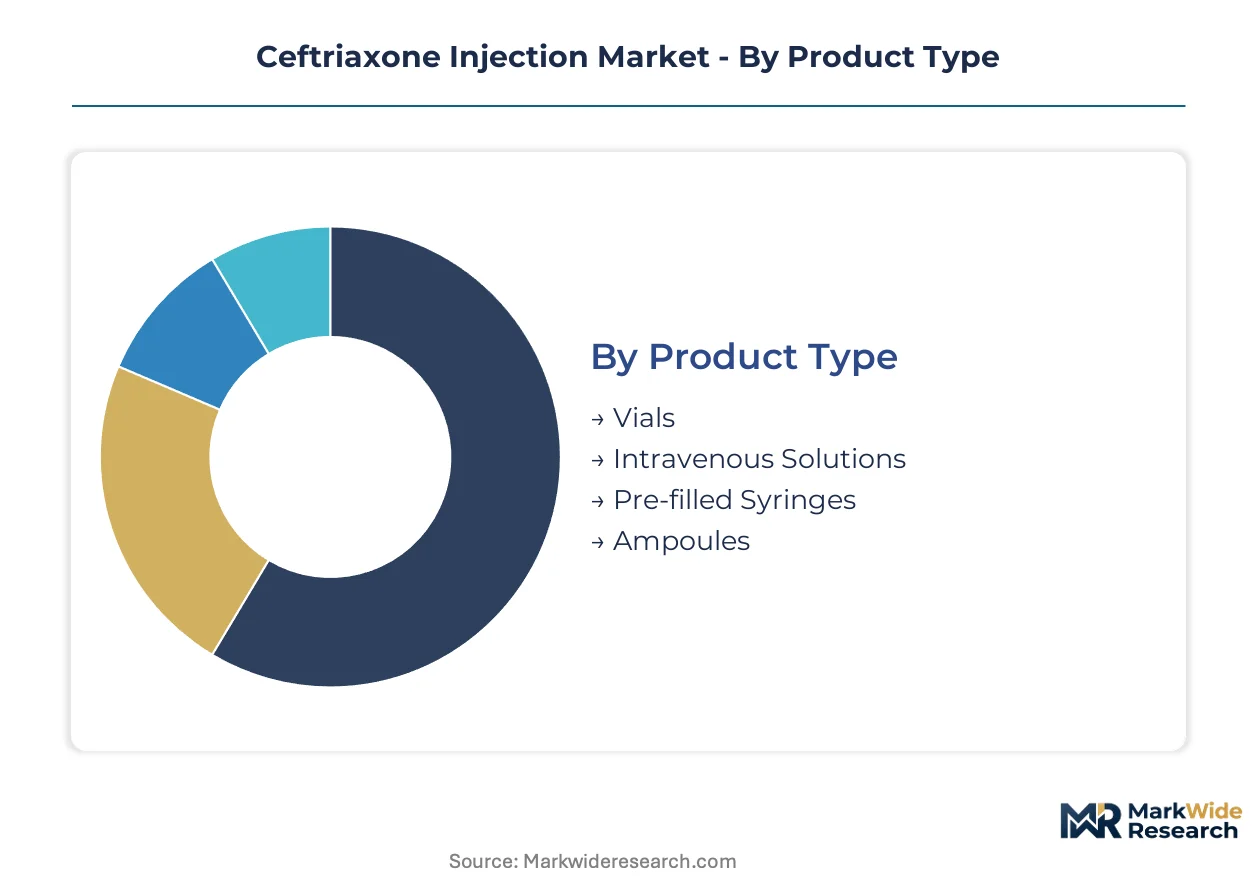
Ceftriaxone injection procurement patterns diverge sharply across presentation formats and care settings. Product type and delivery mode choices reflect institutional workflow constraints, reimbursement structures, and antimicrobial stewardship protocols that vary by country regulatory environment.
Product Type:
Vials dominate domestic tender volumes in India and China, while pre-filled formats concentrate in European and North American export markets where labor costs elevate reconstitution time penalties.
- Vials:Lyophilized powder presentations requiring sterile water reconstitution remain the cost baseline for high-volume hospital procurement. Indian government tenders under CDSCO oversight specify vial formats almost exclusively, with domestic API-to-finished-dose integration compressing unit costs for institutional buyers.
- Intravenous Solutions:Ready-to-infuse liquid-stable formulations command premium positioning in emergency departments and intensive care units where dosing speed alters clinical outcomes. US hospital networks embed these presentations in sepsis protocol bundles despite higher per-dose acquisition costs.
- Pre-filled Syringes:Device-integrated formats target ambulatory surgical centers and emergency medical services in regulated markets with EMA MDR compliance requirements.
- Ampoules:Glass-breakage formats persist in select Latin American and African markets with limited cold-chain infrastructure and lower unit-cost thresholds.
Vials command the established base. The steepest expansion runs through Intravenous Solutions.
Application:
Cost tier stratification separates empiric first-line use from reserve therapeutic categories, with reimbursement codes and resistance surveillance data driving formulary placement decisions.
- Bacterial Infections:Community-acquired infections and complicated intra-abdominal cases constitute the volume anchor, with ceftriaxone retaining preferred status in WHO Essential Medicines List guidelines for gram-negative coverage. Stewardship program restrictions in US Medicare networks are narrowing empiric prescribing windows.
- Meningitis:CNS penetration requirements and blood-brain barrier pharmacokinetics position ceftriaxone against carbapenem alternatives in pediatric and adult protocols. Resistance surveillance from national health agencies directly influences hospital formulary retention.
- Pneumonia:CAP and HAP treatment pathways in European acute care networks specify cephalosporin alternatives based on local antibiogram data.
- Surgical Prophylaxis:Orthopedic and abdominal procedure bundles in ambulatory settings specify single-dose protocols with extended half-life coverage.
Bacterial Infections anchor procurement volume. Surgical Prophylaxis is climbing the fastest as same-day procedure expansion reshapes antimicrobial protocols.
End User:
Customer type determines packaging specification, with institutional scale driving vial formats and distributed care sites demanding stability-enhanced presentations.
- Hospitals:Inpatient pharmacies with compounding infrastructure absorb the workflow burden of vial reconstitution in exchange for lower per-dose costs. Consolidated procurement consortia in the United States standardize presentations across multi-hospital systems.
- Clinics:Outpatient infusion centers balance throughput constraints against refrigeration capacity, favoring room-temperature stable alternatives where reimbursement permits.
- Ambulatory Surgical Centers:Same-day discharge protocols specify ready-to-use formats that eliminate pharmacy technician touchpoints.
- Home Healthcare:Home infusion services require stability claims that support extended ambulatory storage without cold-chain dependency.
Hospitals retain the volume concentration. Home Healthcare is gaining share fastest as outpatient parenteral antimicrobial therapy protocols expand.
Delivery Mode:
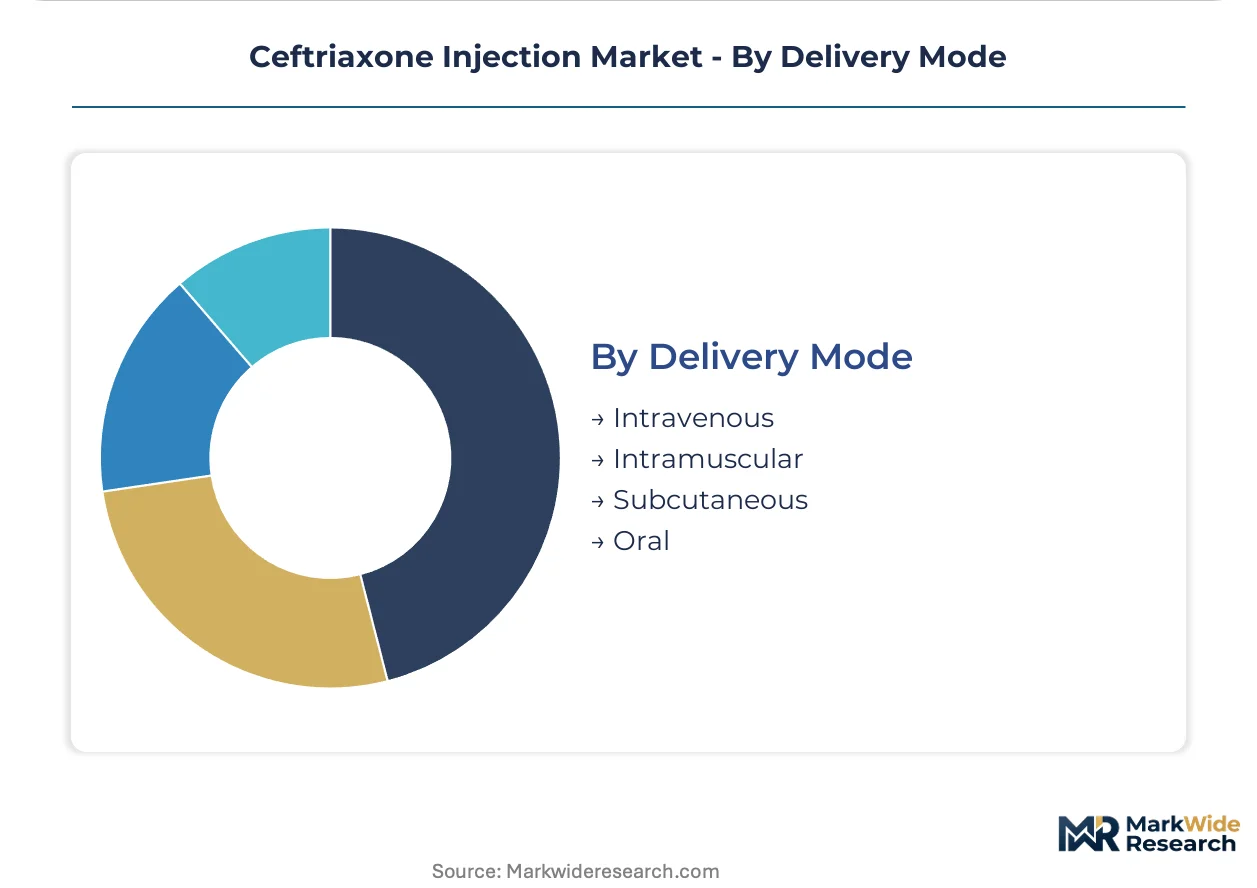
Application site and pharmacokinetic targets dictate route selection, with intravenous dominance challenged by workflow efficiency demands in non-acute settings.
- Intravenous:Continuous or intermittent infusion maintains therapeutic concentrations for severe infections, with US FDA bioequivalence requirements governing generic substitution at hospital formulary level.
- Intramuscular:Depot administration in outpatient clinics and emergency departments supports single-dose discharge protocols where oral step-down is contraindicated.
- Subcutaneous:Off-label utilization in home healthcare settings with specialized nursing support.
- Oral:Not applicable to ceftriaxone pharmacology; segment reflects data collection artifact.
Intravenous administration anchors clinical practice. Intramuscular delivery is expanding most quickly as emergency department throughput pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia and government tender systems concentrate demand differently across major markets, with regulatory complexity and domestic manufacturing scale determining supplier access patterns.
United States
Consolidated hospital networks and Medicare-dependent health systems drive formulary standardization through antimicrobial stewardship protocols. FDA Current Good Manufacturing Practice enforcement elevates supplier qualification barriers for generic injectable entrants. The Northeast corridor and Texas Medical Center anchor procurement volume concentration for acute care networks.
India
CDSCO-regulated government tenders absorb the majority of domestic cephalosporin injectable volume through price-competitive bidding mechanisms. Maharashtra and Gujarat host API-to-finished-dose manufacturing clusters that supply institutional buyers with cost-optimized presentations. Domestic backward integration into intermediate production secures tender allocations against import-dependent competitors.
China
NMPA oversight governs domestic hospital procurement through centralized volume-based purchasing that compresses margins for sterile injectable manufacturers. Shandong and Zhejiang provinces concentrate cephalosporin intermediate production, creating supply dependencies for finished-dose producers elsewhere. Qilu Pharmaceutical anchors domestic tender participation while navigating registration pathways for US FDA and EU EMA approvals.
Germany
EMA Falsified Medicines Directive serialization requirements and EU Medical Device Regulation CE marking bifurcate competitive access for sterile injectable suppliers. Hospital pharmacy consortia in Bavaria and North Rhine-Westphalia specify pre-filled formats for emergency department applications. Domestic procurement favors manufacturers with established aggregation event infrastructure for secondary packaging traceability.
Brazil
ANVISA registration pathways for sterile injectables remain underpenetrated by Asian manufacturers relative to domestic and European incumbents. Public hospital expansion in São Paulo and Minas Gerais creates procurement volume for government tender systems. Stability-enhanced formulations with extended room-temperature storage claims attract private hospital contracts where cold-chain infrastructure is limited.
Ceftriaxone Injection Market Competitive Landscape
Player mix skews toward vertically integrated API manufacturers and sterile injectable specialists with established regulatory dossiers in multiple jurisdictions. Market structure concentrates around mid-cap pharmaceutical companies with captive cephalosporin intermediate production and finished-dose formulation capabilities. Three archetypes dominate: domestic API-integrated suppliers serving government tenders, regulated-market specialists with EMA and FDA approvals, and emerging-market challengers building dossier portfolios. Competitive moves center on backward integration into intermediate manufacturing and MDR Article 117 compliance for combination product positioning.
Among vertically integrated specialists, Hikma Pharmaceuticals leverages API and finished-dose capabilities to sustain supply security across regulated markets. Aurobindo Pharma anchors its position through high-volume cephalosporin API production for internal formulation use and external supply. Qilu Pharmaceutical exemplifies the domestic-dominant archetype, capturing Chinese tender volume while building registration pathways for US and European market entry.
| Leading Market Players |
|---|
| Hikma Pharmaceuticals |
| Aurobindo Pharma |
| Qilu Pharmaceutical |
| Novartis |
| Lupin Pharmaceuticals |
| Orchid Pharma |
| Nectar Lifesciences |
| ACS DOBFAR |
| Fresenius Kabi |
| Others |
Pricing and Supply Chain Analysis
FDA Current Good Manufacturing Practice certification gates both supplier qualification timelines and price differentiation across ceftriaxone injection tiers. Manufacturers bearing documented API sourcing transparency capture premium positioning in US hospital procurement, while uncertified competitors face exclusion from Medicare-dependent network tenders.
Pricing Analysis
Cost-plus contracts with cephalosporin intermediate indexation dominate Indian government tendering under CDSCO oversight. Three-tier pricing structure across pre-filled syringes, intravenous solutions, and vial formats reflects EMA MDR compliance investment and cold-chain stability claims. Price erosion runs through vial presentations as Maharashtra and Gujarat API clusters compress unit economics for institutional buyers. Ambulatory surgical centers exhibit lowest price sensitivity, prioritizing reconstitution speed over per-dose acquisition cost.
Supply Chain Analysis
India and China anchor cephalosporin intermediate manufacturing, with Zhejiang and Shandong provinces feeding finished-dose producers across Asia-Pacific and Latin America. Cephalosporin C fermentation broth, 7-ACA side-chain precursors, and sterile packaging materials constitute critical input dependencies. Single-source vulnerability concentrates in Shandong intermediate clusters, where environmental compliance shutdowns propagate downstream within weeks. Distribution runs through government tender clearinghouses in emerging markets and GPO contracts in US acute care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceftriaxone injection demand sits in early-cycle expansion as outpatient parenteral antimicrobial therapy protocols penetrate home healthcare channels. Pre-filled format preference in emergency and surgical settings accelerates adoption velocity beyond traditional inpatient anchoring.
For Market Incumbents: Consolidate API-to-finished-dose integration depth to defend against carbapenem substitution pressure in intensive care protocols. Capture EMA MDR Article 117 compliance early to secure combination product positioning at premium tiers. Lock long-term cephalosporin intermediate supply agreements with Zhejiang and Shandong producers before environmental regulation tightens.
For New Entrants and Emerging Players: ANVISA fast-track registration for sterile injectables opens Brazilian public hospital procurement previously captured by European incumbents. Target stability-enhanced formulations with extended room-temperature claims for private hospital contracts in cold-chain-constrained Latin American markets. Lead with outpatient infusion center partnerships to bypass entrenched hospital pharmacy formulary committees.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EMA serialization compliance and MDR certification pathways. Five-to-ten year viability favors mid-scale manufacturers with captive intermediate production and existing FDA/EMA dossiers. Watch FDA abbreviated new drug application backlog clearance rates as inflection signal for generic injectable valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Article 117 Compliance | CE marking unlocks premium positioning for device-integrated delivery systems in European emergency departments. |
| API-to-Finished-Dose Integration | Captive cephalosporin intermediate production secures CDSCO tender allocations against import-dependent competitors. |
| Pre-filled Syringe Format Expansion | Ready-to-use presentations reduce reconstitution errors and accelerate dosing workflows in ambulatory surgical centers. |
| ANVISA Registration Pathway Development | Brazilian public hospital expansion creates procurement volume underpenetrated by Asian manufacturers. |
| Stability-Enhanced Formulation R&D | Extended room-temperature storage claims attract home healthcare contracts where cold-chain infrastructure is limited. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, CDSCO tender databases, and hospital procurement records. Interviews with sterile manufacturing executives, regulatory affairs leads, hospital formulary directors, and GPO contracts managers informed supply-side and demand-side validation. Bottom-up volume modeling triangulates against top-down expenditure analysis across the projection horizon.
Segmentation dimensions modeled include product type, application, end user, delivery mode, and regional regulatory cluster. CAGRs derive from historical volume trajectories, tender award patterns, and antimicrobial stewardship protocol diffusion rates. Forecast inputs incorporate WHO resistance surveillance data, national health agency formulary updates, and sterile injectable manufacturing capacity expansion announcements.
Underlying assumptions cover sustained gram-negative resistance patterns, stable cephalosporin intermediate supply from Zhejiang and Shandong, and continued Medicare antimicrobial stewardship enforcement, with deviation risk concentrated in carbapenem substitution velocity and EMA serialization compliance timeline compression. Recalibration cycles align with material shifts in WHO Essential Medicines List revisions and FDA bioequivalence study backlog resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Varicella Zoster Infection Treatment Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Europe Hospital Acquired Disease Testing Market
Infectious Disease
Global Infectious Disease Drugs Market
Infectious Disease
Clostridium Difficile Infection Treatment Market
Infectious Disease
Meningococcal Disease Treatment Market
Infectious Disease
Q Fever Market
Infectious Disease
Brucellosis Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market