
 Point-Of-Care Infectious Disease Testing Market | 2026-2036
Point-Of-Care Infectious Disease Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Point-Of-Care Infectious Disease Testing Market Outlook
CLIA-waived certification under the Clinical Laboratory Improvement Amendments is unwinding competitive access for point-of-care infectious disease testing platforms, favoring manufacturers with established regulatory infrastructure. Abbott leverages its Alinity portfolio to sustain channel dominance across urgent care networks. bioMérieux SA specializes in syndromic respiratory panels that differentiate its menu against commodity rapid tests. Siemens Healthineers anchors European hospital procurement through integrated instrument-reagent contracts.
Point-of-care infectious disease testing comprises diagnostic assays performed at or near the patient site, typically delivering results within 15–30 minutes through cartridge-based or strip-based formats without centralized laboratory processing. These systems employ immunochromatographic, nucleic acid amplification, or biosensor detection methods to identify pathogens from blood, saliva, nasal swabs, or urine specimens, enabling immediate clinical decision-making for antibiotic stewardship and isolation protocols. Lateral flow assays occupy the highest volume tier due to minimal training requirements and lowest per-test cost, while nucleic acid tests capture expanding margin pools as multiplex respiratory panels replace single-analyte rapid tests. Microfluidics is displacing conventional cartridge architectures among premium platforms, though automated systems face capital constraint barriers in resource-limited clinics.
FDA's Emergency Use Authorization framework and CLIA waiver pathways shape product development priorities, directing R&D investment toward simplicity and operator-independence rather than laboratory-grade sensitivity. The European Union's In Vitro Diagnostic Regulation (IVDR) and WHO prequalification standards are tightening performance documentation requirements, raising compliance costs for market entry. Stakeholders must monitor evolving reimbursement codes from CMS and national health technology assessment bodies, as coverage determination for novel multiplex panels will dictate which platform investments generate sustainable returns.
Market Dynamics
CLIA-waiver compression is collapsing traditional laboratory gatekeeping, forcing manufacturers to engineer for untrained operators rather than clinical laboratory scientists. This regulatory inflection redistributes competitive advantage toward firms with pre-cleared platforms and established FDA rapport.
Growth Catalysts
- CDC and HRSA program funding:Sustained federal investment through the CDC and HRSA programs is underwriting instrument placement in federally qualified health centers across the United States.
- Antimicrobial stewardship mandates:Hospital accreditation requirements for rapid pathogen identification are accelerating cartridge-based platform adoption in emergency departments.
- Microfluidic cartridge architectures:Automated sample processing without centrifugation is expanding test menus to molecular targets previously confined to central laboratories.
Market Restraints
- IVDR documentation burden:The European Union's In Vitro Diagnostic Regulation is raising compliance costs and extending timelines for CE marking of novel multiplex panels.
- Reagent supply concentration:Polymerase and fluorescent probe manufacturing clusters in Germany and the United States create single-source vulnerabilities for nucleic acid test producers.
- Lateral flow sensitivity ceiling:Immunochromatographic detection limits prevent reliable identification of low-titer infections in early-stage patients.
Strategic Opportunities
- WHO prequalification pathway:Alignment with WHO prequalification standards unlocks procurement eligibility for Global Fund and PEPFAR programs in sub-Saharan Africa.
- Pharmacy clinic channel expansion:Retail health clinics in the United States are installing CLIA-waived platforms for same-visit prescribing of antivirals.
- Multiplex respiratory syndromic panels:Simultaneous detection of SARS-CoV-2, influenza, and RSV from single swab specimens commands premium reimbursement over single-analyte alternatives.
Industry Challenges
- CLIA-waiver validation complexity:FDA requirements for operator-independence studies demand extensive untrained user trials that extend development timelines.
- Legacy LIS integration friction:Point-of-care instruments must interface with hospital information systems through HL7 or FHIR protocols that lack standardization across vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-Of-Care Infectious Disease Testing Market |
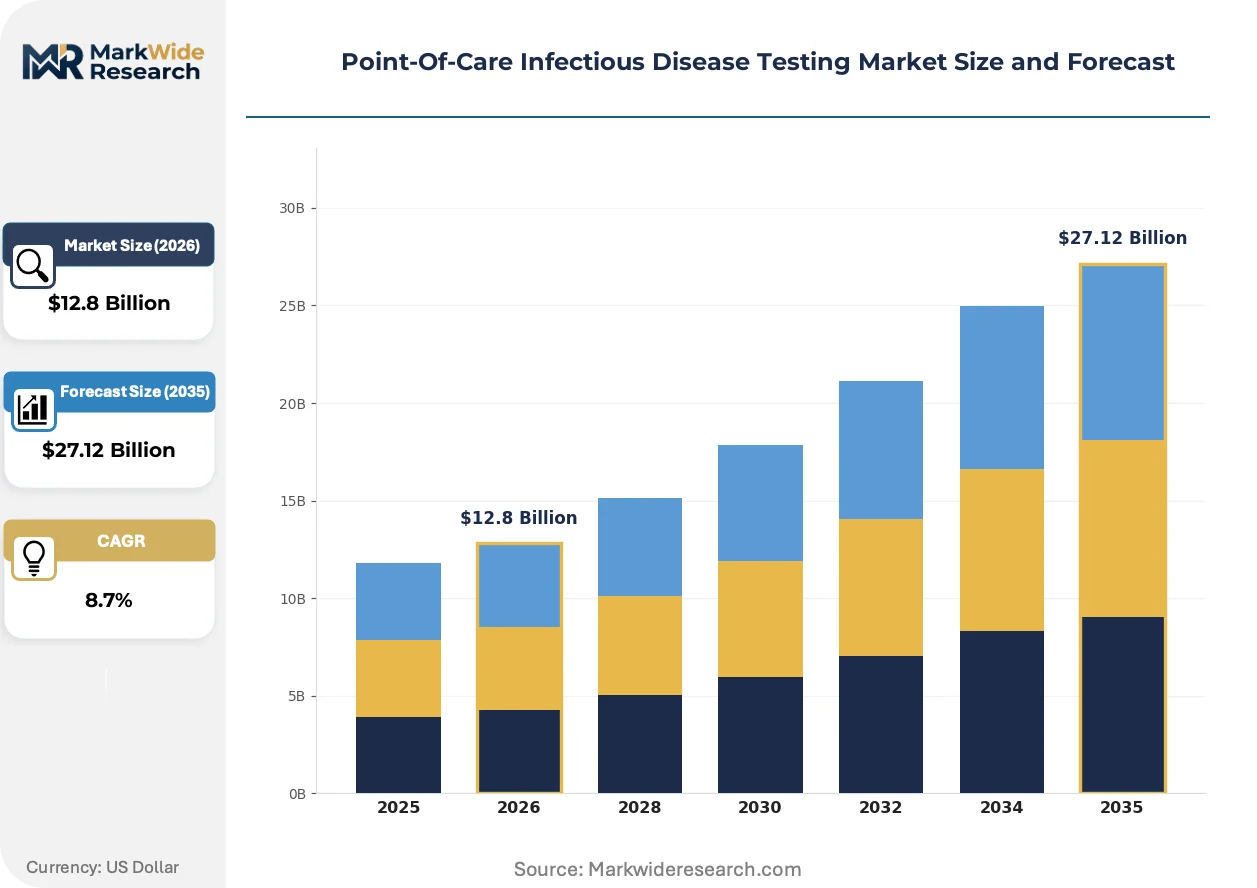
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Nucleic Acid Tests, Rapid Antigen Tests, Serological Tests, PCR Tests End User: Clinics, Hospitals, Home Care, Diagnostic Laboratories Technology: Microfluidics, Lateral Flow Assays, Automated Systems, Biosensors Sample Type: Blood, Saliva, Nasal Swabs, Urine |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Siemens Healthineers, Danaher Corporation, bioMérieux SA, Becton, Dickinson & Company, Thermo Fisher Scientific Inc, Quest Diagnostics Incorporated, Bio-Rad Laboratories Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-Of-Care Infectious Disease Testing Market Strategic Shifts
Detection chemistry miniaturization and regulatory pathway bifurcation are fragmenting the competitive landscape into simplicity-optimized and performance-optimized platform tiers. Manufacturers now face divergent R&D bets between CLIA-waived accessibility and laboratory-comparable sensitivity.
Isothermal nucleic acid amplification is decomposing the thermal cycler bottleneck that previously confined molecular diagnostics to laboratory settings. Urgent care networks in the United States are adopting loop-mediated amplification cartridges for influenza and streptococcal detection. This temperature-stable chemistry collapses capital requirements and enables battery-operated instruments in mobile clinics.
FDA's Emergency Use Authorization framework has created a parallel clearance track that compresses premarket review timelines for emerging pathogen targets. Manufacturers now maintain modular platform architectures that accommodate rapid assay insertion for pandemic response. Respiratory panel developers in the United States are prioritizing EUA-compatible regulatory packages over traditional 510(k) submissions.
Pharmacy-based testing is displacing physician office laboratories as the dominant decentralized channel for infectious disease diagnosis. CVS MinuteClinic and Walgreens Healthcare are negotiating direct instrument contracts that bypass traditional distribution. This channel consolidation in the United States is forcing manufacturers to reconfigure service models around high-volume, low-touch support structures.
Point-Of-Care Infectious Disease Testing Market Segmentation
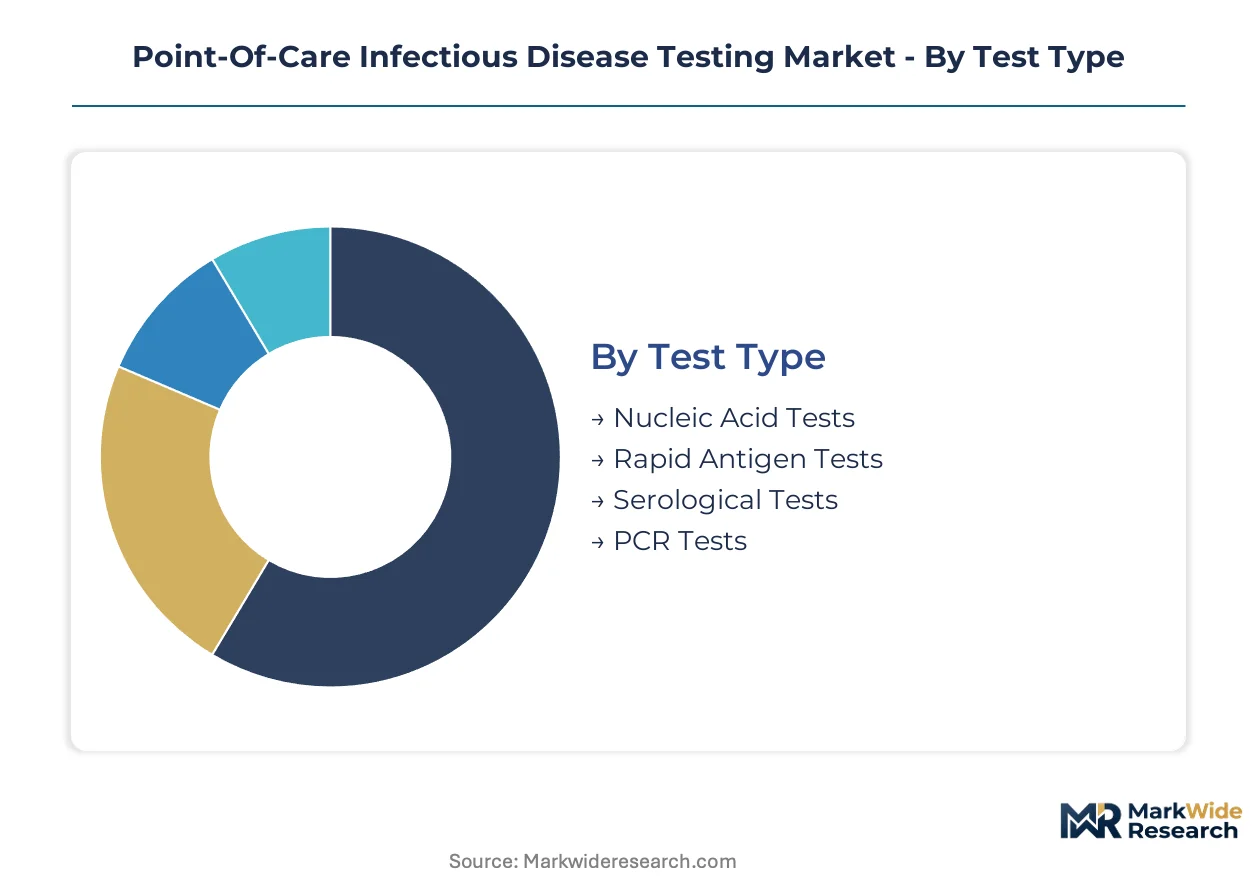
Segmentation in point-of-care infectious disease testing reveals how regulatory pathways and reimbursement structures fragment demand across platform tiers. Test complexity and operator certification requirements determine which segments capture volume versus margin.
Test Type:
FDA's CLIA waiver tiers segment the market by operator independence and analytical performance, with nucleic acid amplification platforms facing stricter validation than immunochromatographic alternatives.
- Nucleic Acid Tests:Isothermal amplification and PCR-based cartridges detect viral RNA with laboratory-comparable sensitivity. Hospital emergency departments in the United States prioritize these for syndromic respiratory panels despite higher per-test costs, driven by antimicrobial stewardship mandates requiring pathogen-specific identification within one hour.
- Rapid Antigen Tests:Lateral flow immunochromatographic strips deliver visual results in 15 minutes without instrumentation. Federally qualified health centers deploy these for influenza and streptococcal screening where CLIA-waived status enables operation by medical assistants rather than laboratory personnel.
- Serological Tests:Antibody detection assays identify past infection through fingerstick whole blood specimens.
- PCR Tests:Traditional thermal cycling platforms remain concentrated in urgent care networks with existing laboratory infrastructure.
Rapid antigen tests handle the majority of throughput; nucleic acid tests are expanding most quickly on share.
End User:
Procurement authority and reimbursement eligibility concentrate demand differently across care settings, with federal program funding shaping instrument placement priorities.
- Clinics:Community health centers and retail health clinics represent the fastest-expanding installation base. CVS MinuteClinic and Walgreens Healthcare negotiate direct purchasing agreements for CLIA-waived platforms, bypassing traditional distribution to enable same-visit antiviral prescribing for influenza and COVID-19.
- Hospitals:Emergency departments and isolation wards require instrument-reagent contracts with integrated LIS connectivity. Siemens Healthineers anchors European hospital procurement through bundled service agreements covering maintenance, calibration, and assay menu expansion.
- Home Care:Over-the-counter rapid tests for SARS-CoV-2 and influenza gained reimbursement traction through CMS temporary codes.
- Diagnostic Laboratories:Reference labs deploy high-throughput automated systems for outbreak screening and confirmatory testing.
Clinics absorb the steepest volume growth; hospitals retain the premium pricing tier.
Technology:
Capital intensity and operator training requirements stratify adoption by resource availability, with battery-operated platforms penetrating mobile and resource-limited settings.
- Microfluidics:Integrated cartridge architectures automate sample preparation, amplification, and detection in disposable consumables. Abbott leverages its Alinity m platform to consolidate molecular, serological, and antigen testing on unified hardware, reducing capital expenditure for mid-volume clinics.
- Lateral Flow Assays:Nitrocellulose membrane strips with colloidal gold or fluorescent nanoparticle labels dominate the lowest-cost tier. These occupy the highest absolute test volume globally due to minimal training requirements and ambient temperature stability.
- Automated Systems:Random-access analyzers with barcode tracking and LIS integration serve high-throughput urgent care networks.
- Biosensors:Electrochemical and optical transducer platforms enable multiplex detection from minimal sample volumes.
Lateral flow assays command the installed base; microfluidics platforms are gaining share fastest.
Sample Type:
Collection convenience and pathogen yield characteristics determine menu expansion priorities, with self-collected specimens reducing healthcare worker exposure and clinic throughput bottlenecks.
- Nasal Swabs:Anterior nares and mid-turbinate specimens concentrate respiratory viral load for SARS-CoV-2, influenza, and RSV detection. Pharmacy clinic channels in the United States standardize on nasal swab multiplex panels to support same-visit prescribing workflows.
- Blood:Fingerstick capillary and venipuncture specimens enable serological antibody detection and antigenemia identification. bioMérieux SA specializes in blood-based syndromic panels that differentiate sepsis pathogens against commodity rapid tests.
- Saliva:Self-collection without healthcare worker supervision expanded during pandemic response periods.
- Urine:Stream-collected specimens support sexually transmitted infection and urinary tract pathogen detection.
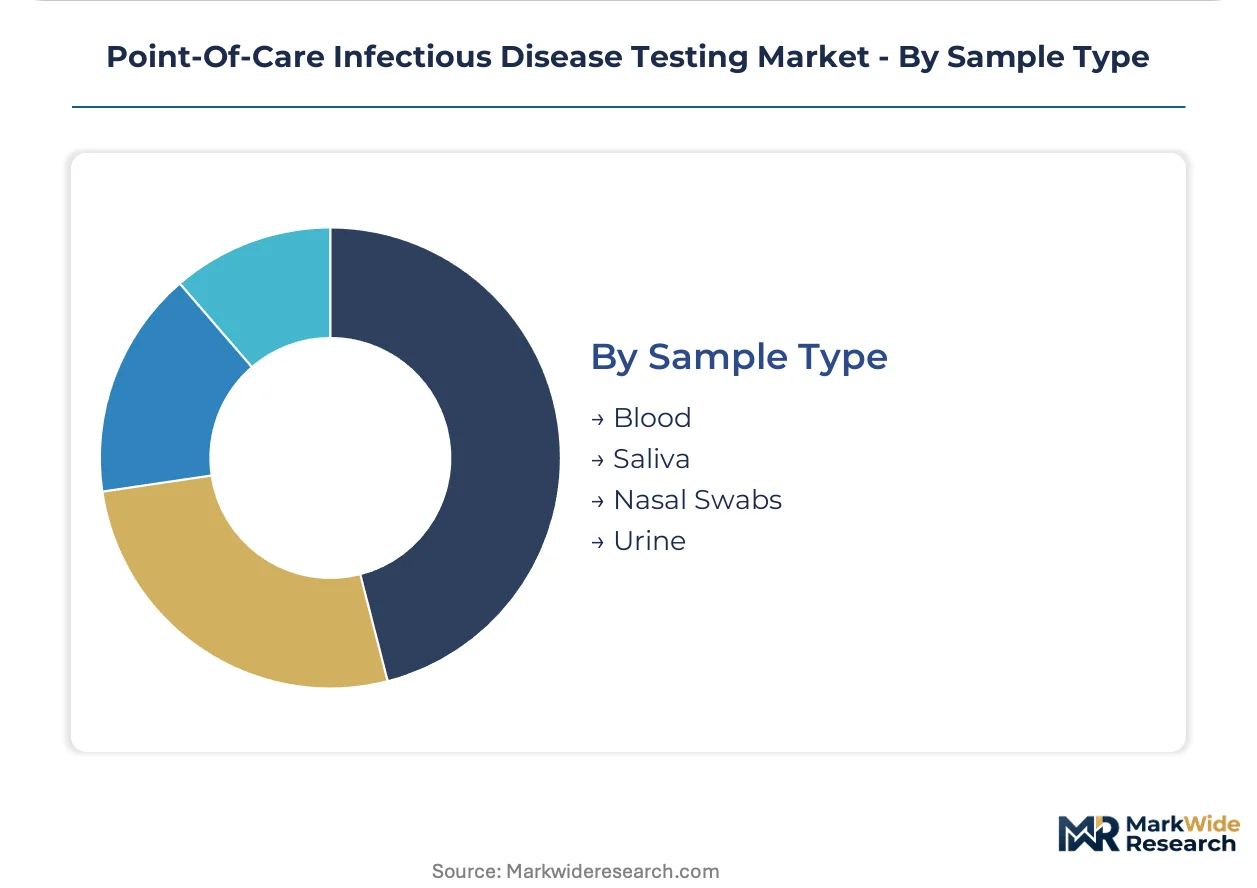
Nasal swabs generate the highest test volume; saliva collection is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federally qualified health centers and retail pharmacy clinics concentrate instrument procurement authority in the United States, while hospital procurement networks anchor demand in Germany and France. Government reimbursement codes and regulatory waiver pathways determine platform economics in each market.
United States
CVS MinuteClinic and Walgreens Healthcare negotiate direct purchasing agreements for CLIA-waived platforms, bypassing traditional distribution channels entirely. CDC and HRSA program funding underwrites instrument placement in community health centers across underserved counties. The Research Triangle Park cluster in North Carolina hosts polymerase and fluorescent probe manufacturing facilities serving nucleic acid test producers.
Germany
Hospital procurement through integrated instrument-reagent contracts dominates platform adoption in emergency departments and isolation wards. The EU In Vitro Diagnostic Regulation extends CE marking timelines and raises documentation burdens for multiplex panel developers. The Rhine-Main metropolitan region concentrates reagent manufacturing infrastructure for isothermal amplification chemistries.
France
ANSM oversight of clinical performance studies shapes validation requirements for syndromic respiratory panels seeking market entry. Hospital accreditation mandates for rapid pathogen identification accelerate cartridge-based platform installation in Parisian emergency departments. The Lyon biocluster hosts specialized manufacturing for microfluidic cartridge architectures.
United Kingdom
NHS England procurement frameworks concentrate demand through national tender processes for urgent care networks. MHRA recognition of FDA CLIA-waiver studies streamlines regulatory pathways for US-cleared platforms. The Cambridge-Oxford corridor anchors molecular diagnostics R&D facilities serving European market requirements.
India
CDSCO import licensing requirements and price controls on diagnostic reagents shape platform economics for mid-volume clinics. WHO prequalification alignment unlocks procurement eligibility for Global Fund programs targeting tuberculosis and HIV detection. The Hyderabad-Genome Valley cluster manufactures lateral flow strips for domestic and export markets.
Point-Of-Care Infectious Disease Testing Market Competitive Environment
Player mix skews toward diversified conglomerates with established regulatory infrastructure and specialized diagnostics pure-plays with syndromic panel expertise. Market structure concentrates around three to five integrated instrument-reagent platforms competing for hospital and urgent care contracts. Strategic archetypes include CLIA-waiver specialists optimizing for untrained operator workflows, multiplex respiratory panel developers commanding premium reimbursement, and microfluidics platform builders consolidating test menus on unified hardware. Dominant competitive moves encompass direct purchasing agreements with retail pharmacy chains and modular platform architectures accommodating rapid assay insertion for emerging pathogens.
Among US-based diversified health technology conglomerates, Abbott and Danaher Corporation occupy positions anchoring the CLIA-waiver and automated systems tiers respectively. European specialists exemplify differentiated positioning, with bioMérieux SA representing the syndromic respiratory panel archetype and Siemens Healthineers sitting within the integrated hospital procurement tier. These three entities collectively illustrate how regulatory rapport, manufacturing scale, and channel-specific contracting authority stratify competitive positioning across decentralized testing infrastructure.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Danaher Corporation |
| bioMérieux SA |
| Becton, Dickinson & Company |
| Thermo Fisher Scientific Inc |
| Quest Diagnostics Incorporated |
| Bio-Rad Laboratories Inc |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at polymerase and fluorescent probe manufacturing clusters in Germany and the United States shapes both supply concentration and price floors for nucleic acid test producers. CLIA-waiver validation complexity compresses margins for manufacturers engineering for untrained operators, while instrument-reagent bundling in hospital procurement sustains premium pricing tiers.
Pricing Analysis
Instrument-reagent contracts with annual price indexation anchor pricing in hospital and urgent care procurement. Pricing stratifies across CLIA-waived rapid antigen tests, multiplex respiratory panels, and laboratory-comparable molecular platforms based on analytical performance and operator certification requirements. Cost compression in lateral flow manufacturing intensifies as pharmacy clinic channels negotiate direct purchasing agreements bypassing traditional distribution. Federally qualified health centers exhibit highest price sensitivity due to federal program funding constraints, while hospital emergency departments prioritize stewardship compliance over per-test cost.
Supply Chain Analysis
Germany and the United States anchor reagent manufacturing for isothermal amplification chemistries and fluorescent probe production. Polymerase enzymes, nitrocellulose membranes, and colloidal gold nanoparticles constitute critical input dependencies. Single-source vulnerability concentrates in German fluorescent probe suppliers serving multiplex panel developers. Distribution runs through direct purchasing agreements with CVS MinuteClinic and Walgreens Healthcare in the United States, alongside traditional distribution to federally qualified health centers and hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CLIA-waiver compression constitutes a high-growth disruption as regulatory pathways collapse traditional laboratory gatekeeping, redirecting competitive advantage toward firms with pre-cleared platforms and established FDA rapport.
For Market Incumbents: Compound channel control through direct purchasing agreements with retail pharmacy chains to defend against emerging CLIA-waiver specialists. Deepen regulatory infrastructure investment to accelerate assay menu expansion on modular platforms, countering threat from syndromic panel pure-plays with narrower FDA rapport but faster turnaround times. For New Entrants and Emerging Players: FDA Emergency Use Authorization fast-track positioning unlocks procurement eligibility for pandemic response contracts without traditional 510(k) timelines. Pharmacy clinic channel expansion in underserved United States counties represents the most penetrable white-space, with same-visit antiviral prescribing workflows creating sticky demand. WHO prequalification alignment enables Global Fund and PEPFAR procurement eligibility in sub-Saharan Africa as a parallel go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors microfluidics platform builders consolidating test menus on unified hardware over single-assay lateral flow commoditizers. Long-term viability across the analysis window hinges on reimbursement code capture for novel multiplex panels. Acquisition target archetype: CLIA-waiver specialists with established untrained user validation studies and pharmacy clinic channel contracts. Signal to watch: CMS coverage determination timelines for respiratory syndromic panels as inflection indicator for sustainable returns.| Strategic Initiative | Industry Significance |
|---|---|
| FDA CLIA-Waiver Pathway Investment | Compresses time-to-market for untrained operator platforms in urgent care networks. |
| Pharmacy Clinic Direct Contracting | Bypasses traditional distribution to capture CVS MinuteClinic and Walgreens Healthcare procurement. |
| Multiplex Respiratory Panel Development | Commands premium reimbursement over single-analyte alternatives through stewardship compliance. |
| WHO Prequalification Alignment | Unlocks Global Fund and PEPFAR eligibility for tuberculosis and HIV detection in Africa. |
| Modular Platform Architecture | Enables rapid assay insertion for emerging pathogens under Emergency Use Authorization frameworks. |
Study Parameters
Desk research of FDA 510(k) and EUA filings, CMS reimbursement code databases, and WHO prequalification listings preceded structured interviews with regulatory affairs directors at diagnostics manufacturers, hospital procurement committee members, and pharmacy clinic operations managers. Secondary validation drew from CDC program documentation, HRSA funding disclosures, and European hospital procurement tender databases. Bottom-up instrument placement modeling triangulated against top-down market sizing from reagent production capacity estimates.
Variance decomposition across test type, end user, technology, and sample type segmentation dimensions informed analytical framework construction over the projection horizon. CAGRs derived from instrument installation base expansion rates and per-test pricing trajectories modeled separately before reconciliation. Industry-specific forecast inputs included CLIA-waiver approval timelines and CMS coverage determination schedules for novel multiplex panels.
Underlying assumptions cover sustained federal funding through CDC and HRSA programs, with deviation risk concentrated in reimbursement code delays and IVDR documentation timeline extensions. Forecasts reflect these conditions with recalibration cycles aligning with material shifts in regulatory pathway bifurcation and pharmacy clinic channel consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Actinomycosis Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
Viral Hemorrhagic Fever Market
Infectious Disease
Acute Viral Rhinosinusitis Treatment Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Gram Positive Bacterial Infections Market
Infectious Disease
Veterinary Infectious Disease Therapeutics Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Vaccine Management Solution Market
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Pork Tapeworm Infection Treatment Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Direct-Acting Antiviral Medicines Market