
 Japanese Encephalitis Market | 2026-2036
Japanese Encephalitis Market Size, Share, and Industry Trends Forecast 2026-2036
Japanese Encephalitis Market Foresight
Multi-source procurement for Japanese encephalitis vaccines is decoupling from historical single-source dependence in several endemic countries. Bharat Biotech leverages its WHO-prequalified manufacturing platform to anchor supply contracts across South and Southeast Asia. Chengdu Institute of Biological Products dominates domestic Chinese demand through state-backed distribution channels. Valneva SE specializes in traveler vaccination segments with differentiated cold-chain logistics.
Japanese encephalitis is a mosquito-borne flaviviral infection prevented through formalin-inactivated or live attenuated vaccines requiring two-dose primary series with aluminum hydroxide adjuvant. The virus, transmitted by Culex tritaeniorhynchus, causes severe neurological disease with case-fatality rates exceeding twenty percent in symptomatic patients. Inactivated vaccines retain the largest revenue share due to established safety profiles in pediatric national immunization programs. Live attenuated vaccines represent the fastest-growing category as single-dose convenience reduces programmatic costs in resource-limited settings. Subunit vaccines occupy emerging pipeline positions where recombinant platforms target improved reactogenicity profiles.
India's CDSCO and China's NMPA enforce divergent lot-release testing standards that fragment registration timelines for multinational suppliers. WHO prequalification operates as the de facto gatekeeper for Gavi-funded procurement, effectively shaping manufacturer R&D priorities and clinical trial site selection. Stakeholders must monitor evolving Japanese regulatory frameworks under PMDA guidance for imported biologicals as Tokyo revises traveler health mandates. Procurement officers face critical decisions between inactivated and live attenuated platforms as country-level cost-effectiveness thresholds tighten.
Market Dynamics
Procurement fragmentation across endemic zones is dismantling single-source vaccine supply structures that dominated Japanese encephalitis immunization programs for decades. National immunization schedules in Southeast Asia and China now solicit multiple qualified suppliers, compressing tender timelines and reshaping manufacturer investment priorities.
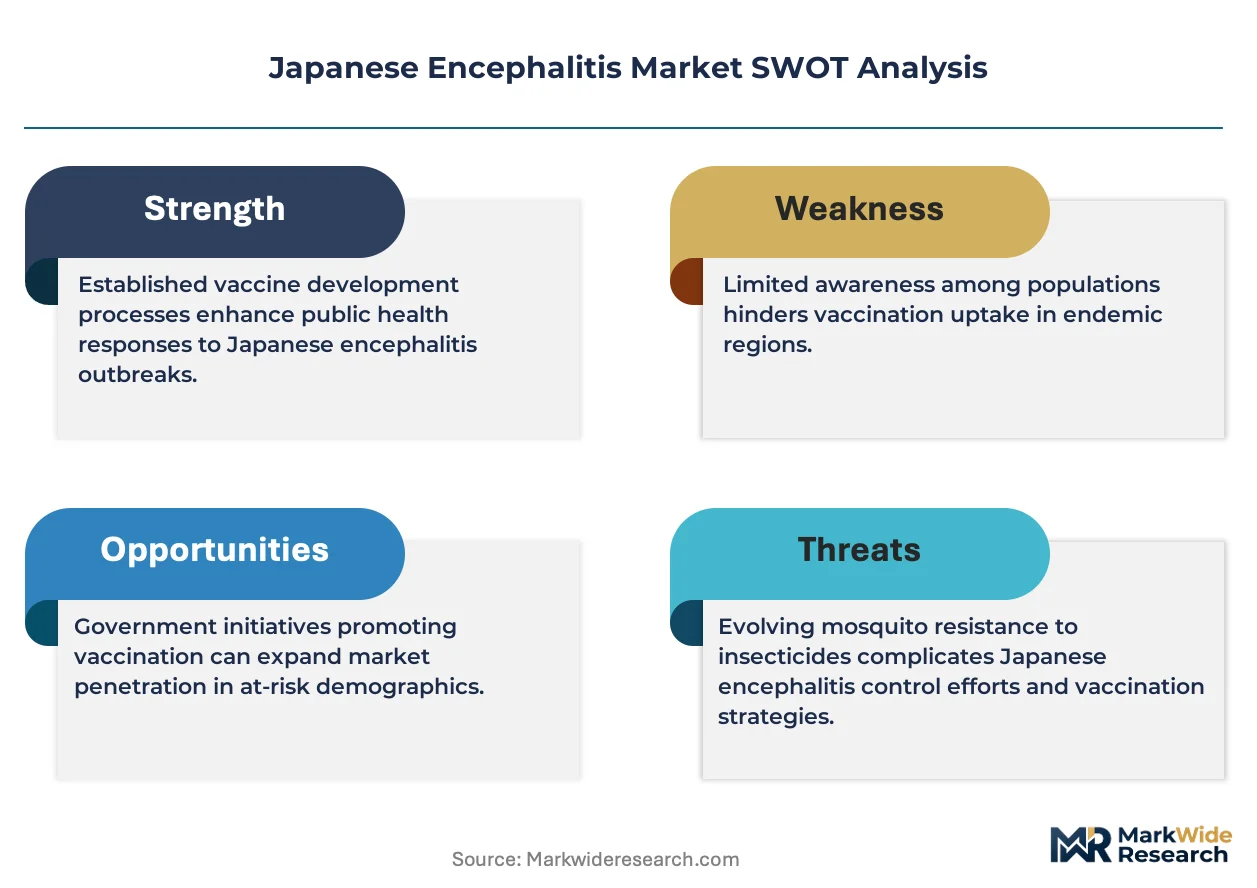
Growth Catalysts
- WHO Prequalification Pathways:The WHO prequalification program accelerates supplier access to Gavi-funded procurement pools, lowering entry barriers for biological manufacturers from India and Southeast Asia.
- Live Attenuated Platforms:Single-dose live attenuated vaccines reduce cold-chain logistics burdens and programmatic delivery costs in resource-limited rural districts.
- China:Provincial vaccination campaigns in high-incidence prefectures expand immunization coverage beyond historical urban-rural disparities, creating sustained procurement volumes.
Market Restraints
- Aluminum Hydroxide Supply Concentration:Adjuvant raw material sourcing concentrates among limited specialty chemical suppliers, exposing vaccine manufacturers to input price volatility and qualification delays.
- CDSCO-NMPA Divergence:India's CDSCO and China's NMPA enforce incompatible lot-release testing protocols, fragmenting registration timelines and duplicating clinical documentation requirements for multinational suppliers.
- Vector Control Substitution:Larviciding programs and Wolbachia-infected mosquito releases in select Indonesian provinces reduce perceived urgency for preventive immunization in donor-funded budgets.
Strategic Opportunities
- Myanmar and Cambodia:These underpenetrated Mekong basin markets lack domestic manufacturing capacity and rely on irregular donor supply, creating entry points for WHO-prequalified suppliers with established cold-chain partnerships.
- Recombinant Subunit Platforms:Emerging pipeline candidates target improved reactogenicity profiles in pediatric populations, potentially displacing formalin-inactivated vaccines in premium national immunization segments.
- Traveler Health Mandates:Revised PMDA guidance under Japan's incoming biological import frameworks may expand pre-departure vaccination requirements for Japanese nationals visiting endemic zones.
Industry Challenges
- Cold-Chain Qualification Talent:Vaccine manufacturers face acute shortages of validation engineers capable of documenting temperature excursion protocols to WHO prequalification standards.
- Legacy Inactivated Vaccine Integration:National immunization programs with established two-dose inactivated schedules confront technical and political friction when transitioning to single-dose live attenuated alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japanese Encephalitis Market |
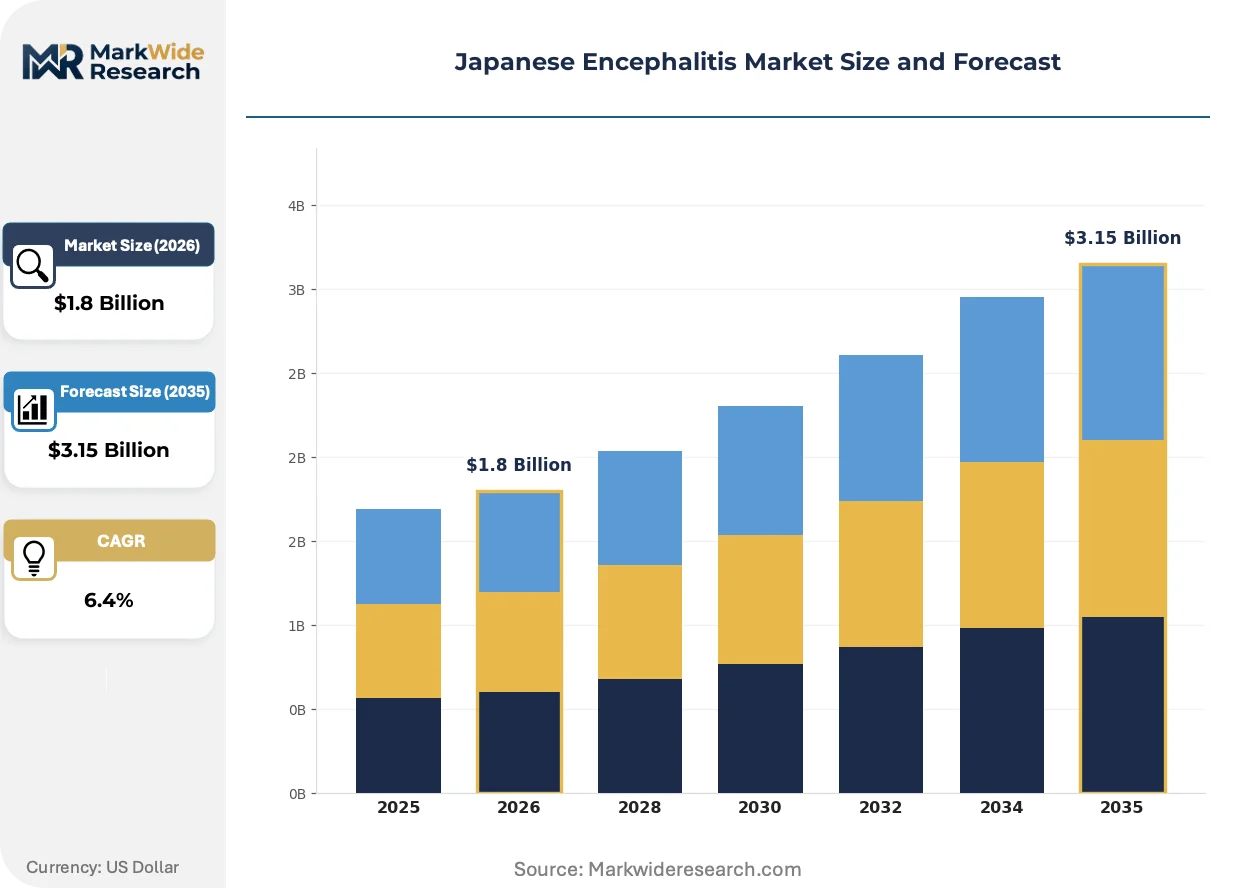
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccines, Live Attenuated Vaccines, Subunit Vaccines, Combination Vaccines End User: Hospitals, Clinics, Public Health Organizations, Research Institutions Delivery Mode: Intramuscular, Subcutaneous, Oral, Others Application: Preventive Immunization, Outbreak Response, Traveler Vaccination, Veterinary Use |
| Companies Covered | Sanofi Pasteur, Bharat Biotech, Chengdu Institute of Biological Products, Valneva SE, Biological E. Limited, Meiji Holdings Co. Ltd., Panacea Biotec Ltd., BIKEN, Adimmune Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japanese Encephalitis Market Shifts & Advancements
Japanese encephalitis vaccine development is pivoting toward platform technologies that compress development timelines and enable rapid strain adaptation. These shifts are reshaping R&D allocation, regulatory submission strategies, and procurement evaluation criteria across endemic markets.
mRNA vaccine platforms are rewriting the economics of flaviviral immunogen design. Bharat Biotech and select Chinese biologics developers are evaluating mRNA constructs for Japanese encephalitis that could reduce production cycles from months to weeks. National immunization program officers in Vietnam and the Philippines are monitoring these candidates for potential inclusion in outbreak response stockpiles. This technology is compressing the traditional decade-long vaccine development paradigm into multi-year horizons.
REACH-compliant adjuvant reformulation is forcing aluminum hydroxide substitution in European-bound traveler vaccine supply chains. Valneva SE and other traveler-focused manufacturers are requalifying alternative adjuvant systems to maintain CE-marked product registration. The live attenuated segment faces minimal disruption, as these formulations require no adjuvant and bypass the regulatory complexity entirely.
Consolidated national tendering is displacing fragmented district-level procurement across Indonesian provincial health systems. The Ministry of Health in Jakarta now centralizes Japanese encephalitis vaccine acquisition through single-source contracts with WHO-prequalified suppliers, eliminating the price arbitrage and quality variation that characterized previous multi-district purchasing. District cold-chain infrastructure investments are accelerating to accommodate centralized delivery schedules.
Japanese Encephalitis Market Segmentation
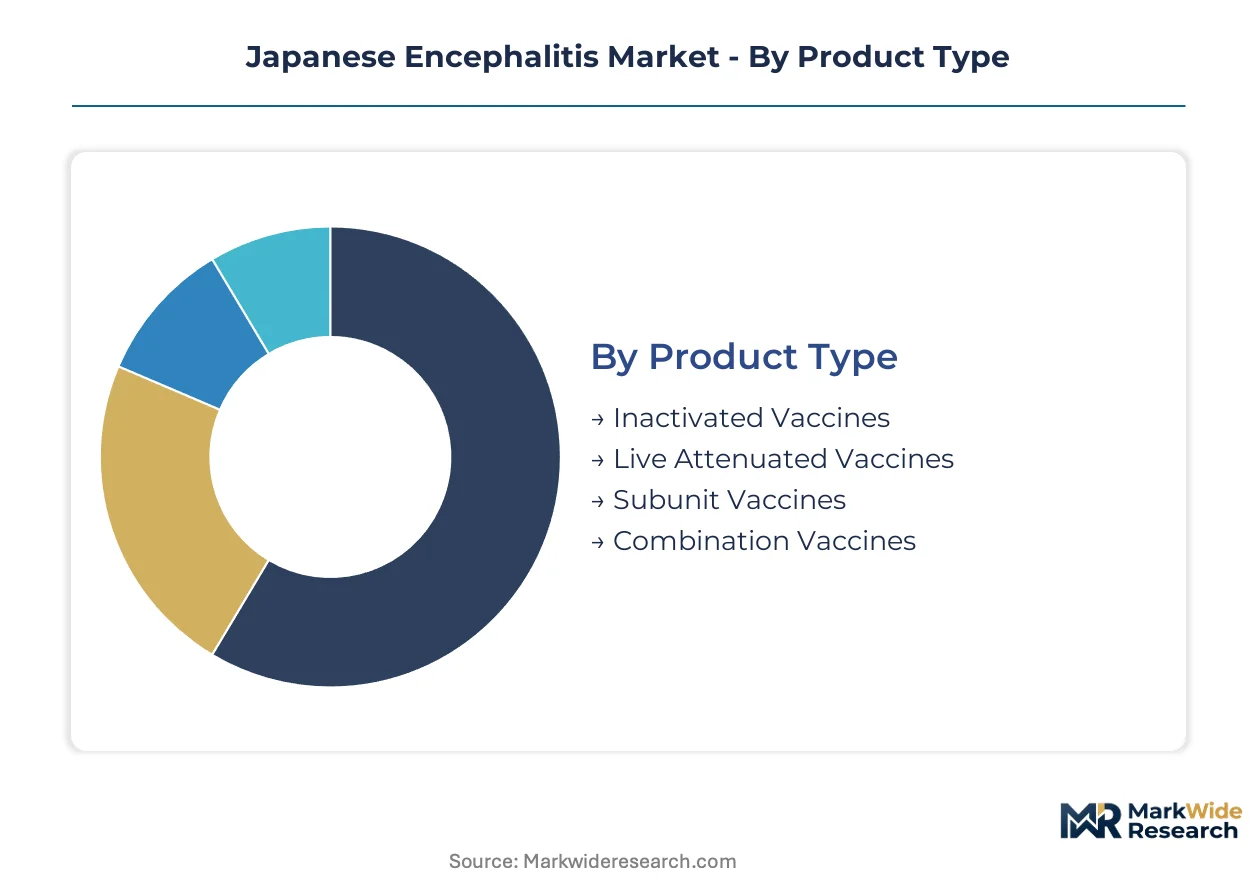
Japanese encephalitis vaccine procurement patterns diverge sharply across product platforms and delivery settings. Understanding these segment boundaries clarifies where manufacturing investments concentrate and which customer relationships anchor long-term revenue stability.
Product Type:
Capital intensity varies dramatically across vaccine platforms, with inactivated formulations demanding the highest upfront manufacturing infrastructure.
- Inactivated Vaccines:Formalin-inactivated formulations with aluminum hydroxide adjuvant require dedicated biosafety level facilities and extended production cycles. National immunization programs in India and Vietnam anchor procurement volumes for pediatric two-dose schedules, though cold-chain burdens limit rural penetration.
- Live Attenuated Vaccines:Single-dose convenience eliminates adjuvant dependencies and halves cold-chain logistics costs. Chinese provincial campaigns and Indonesian district health systems drive accelerating procurement as programs transition from inactivated platforms.
- Subunit Vaccines:Recombinant protein candidates in clinical development target improved reactogenicity profiles for sensitive pediatric populations.
- Combination Vaccines:Japanese encephalitis antigens co-formulated with measles or hepatitis components remain experimental with limited commercial traction.
Inactivated vaccines absorb the bulk of installed capacity; live attenuated vaccines are expanding most quickly.
End User:
Customer concentration patterns reveal where procurement decision-making centralizes versus fragments across institutional tiers.
- Public Health Organizations:Gavi-funded national immunization programs and WHO prequalification pathways dominate volume procurement across endemic Southeast Asian markets. Tender consolidation in Indonesia and Myanmar compresses supplier margins while securing multi-year supply commitments.
- Hospitals:Urban tertiary centers manage severe Japanese encephalitis cases and administer post-exposure prophylaxis during outbreak clusters. District hospital networks in Bangladesh and Nepal serve as distribution nodes for rural outreach campaigns.
- Clinics:Private practitioner networks in Thailand and Malaysia handle traveler vaccination demand with premium pricing flexibility.
- Research Institutions:Academic medical centers and field epidemiology units conduct phase III trials and post-marketing surveillance for novel vaccine platforms.
Public health organizations command the largest procurement volumes; clinics capture the highest per-dose margins.
Delivery Mode:
Route selection determines cold-chain complexity, personnel training requirements, and patient compliance trajectories across immunization programs.
- Intramuscular:Deltoid or anterolateral thigh administration dominates inactivated and subunit vaccine delivery, requiring trained healthcare workers and sterile injection equipment. WHO prequalification standards mandate specific needle gauge documentation for tender eligibility.
- Subcutaneous:Live attenuated vaccines utilize this route with reduced local reactogenicity, enabling broader lay vaccinator deployment in resource-limited Cambodian and Laotian districts.
- Oral:No commercially available Japanese encephalitis vaccines currently employ oral delivery, though experimental mucosal formulations remain in preclinical evaluation.
- Others:Intradermal micro-needle patches and jet injectors occupy niche research positions with limited regulatory approval pathways.
Intramuscular delivery anchors current immunization infrastructure; subcutaneous administration is gaining programmatic preference for live attenuated platforms.
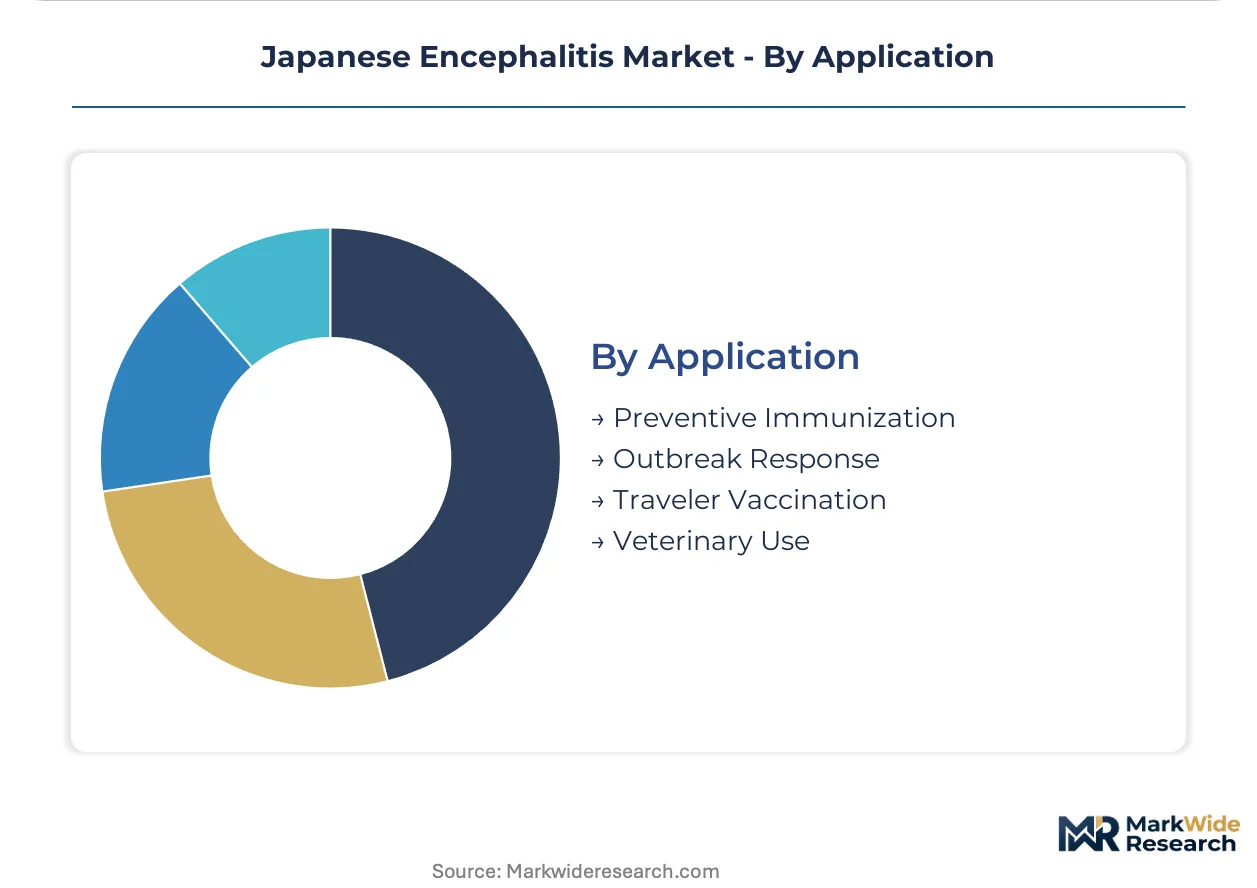
Application:
Demand segmentation by use case exposes divergent price sensitivity, urgency timelines, and regulatory documentation requirements.
- Preventive Immunization:Routine childhood schedules and catch-up campaigns in endemic zones generate predictable recurring procurement. India's Universal Immunization Programme and China's provincial health bureaus constitute the largest addressable demand pools.
- Traveler Vaccination:Pre-departure immunization for Japanese nationals, Australian tourists, and European expatriates commands premium pricing through private clinic channels. PMDA guidance revisions may expand mandatory coverage requirements.
- Outbreak Response:Emergency stockpile deployment during Culex vector surges requires rapid-release lot protocols and surge manufacturing agreements with CDSCO-registered suppliers.
- Veterinary Use:Equine and porcine vaccination programs in Japanese livestock sectors represent a marginal revenue segment with distinct regulatory oversight.
Preventive immunization absorbs the dominant procurement volume; traveler vaccination delivers the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum hydroxide adjuvant production concentrates in Gujarat and Jiangsu provinces, anchoring vaccine manufacturing clusters across South and East Asia. This feedstock geography shapes where formulation facilities locate and which regulators oversee lot-release protocols.
India
India's Universal Immunization Programme drives procurement volumes through Gavi-funded tenders, with CDSCO enforcing lot-release testing standards that fragment registration timelines for multinational entrants. Bharat Biotech anchors supply contracts from its Hyderabad manufacturing base, while Biological E. Limited operates formulation capacity in Telangana serving domestic and export markets.
China
Provincial vaccination campaigns in Sichuan and Yunnan prefectures expand coverage beyond historical urban-rural disparities, creating sustained demand pools. NMPA enforces divergent testing protocols from Indian regulators, duplicating clinical documentation requirements for foreign suppliers. Chengdu Institute of Biological Products dominates domestic distribution through state-backed channels in the Sichuan-Chongqing cluster.
Indonesia
Consolidated national tendering through Jakarta's Ministry of Health displaces fragmented district-level procurement, eliminating price arbitrage between provincial health systems. WHO prequalification operates as the de facto gatekeeper for Gavi-funded pools, compressing supplier margins while securing multi-year commitments. District cold-chain infrastructure investments accelerate to accommodate centralized delivery schedules.
Japan
Revised PMDA guidance under incoming biological import frameworks may expand pre-departure vaccination requirements for Japanese nationals visiting endemic zones. Traveler health mandates concentrate demand in Tokyo and Osaka clinic networks, where premium pricing flexibility exceeds public procurement rates. Meiji Holdings Co. Ltd. maintains domestic distribution relationships with metropolitan health authorities.
Vietnam
National immunization program officers monitor mRNA platform candidates for potential outbreak response stockpile inclusion, compressing traditional development timelines. WHO prequalification accelerates supplier access to Gavi-funded procurement pools, lowering entry barriers for biological manufacturers. Cold-chain partnerships with Ho Chi Minh City logistics providers enable rural district penetration for live attenuated platforms.
Japanese Encephalitis Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers respond to tender consolidation across Southeast Asian national immunization programs. The supplier base fragments across three tiers: state-backed Chinese institutes with captive domestic demand, Indian biological manufacturers leveraging WHO prequalification for export access, and European specialists targeting traveler vaccination premiums. Strategic archetypes include platform-agnostic contract manufacturers, vertically integrated adjuvant-to-vial producers, and regional distribution anchors. Competitive intensity centers on cold-chain qualification speed and regulatory submission parallelism across CDSCO-NMPA divergence.
Within the state-backed institute tier, Chengdu Institute of Biological Products exemplifies domestic market capture through provincial distribution control. Among WHO-prequalified Indian suppliers, Bharat Biotech and Biological E. Limited occupy positions shaped by Gavi tender access and CDSCO registration pathways. At the traveler-focused end, Valneva SE represents premium segment positioning through differentiated logistics capabilities.
| Leading Market Players |
|---|
| Sanofi Pasteur |
| Bharat Biotech |
| Chengdu Institute of Biological Products |
| Valneva SE |
| Biological E. Limited |
| Meiji Holdings Co. Ltd. |
| Panacea Biotec Ltd. |
| BIKEN |
| Adimmune Corp. |
| Others |
Supply & Pricing Matrix
Gavi-funded national immunization programs anchor procurement volumes through multi-year tender structures that compress supplier margins while securing volume commitments. WHO prequalification operates as the de facto pricing gatekeeper, with certified manufacturers commanding premium positioning over non-qualified competitors in Southeast Asian public tenders.
Pricing Analysis
Service bundling separates cold-chain logistics from base vaccine pricing in traveler vaccination segments, where Valneva SE and private clinic networks capture margin through differentiated delivery capabilities. Three-tier pricing structure across premium, standard, and economy levels reflects WHO prequalification status, aluminum hydroxide adjuvant sourcing, and single-dose versus two-dose regimen convenience. Cost compression in live attenuated platforms is intensifying because Indonesian and Vietnamese national programs prioritize programmatic cost reductions over per-dose procurement savings. Public health organizations exhibit highest price sensitivity, while Japanese traveler clinics demonstrate lowest elasticity due to pre-departure mandate compliance requirements.
Supply Chain Analysis
WHO prequalification certification gates supplier access to Gavi-funded procurement pools, creating structural barriers for manufacturers lacking validated cold-chain documentation. Aluminum hydroxide adjuvant production concentrates in Gujarat and Jiangsu provinces, with vaccine formulation facilities clustering proximate to these feedstock sources in India and China. Single-source vulnerability permeates adjuvant raw material sourcing, where limited specialty chemical suppliers expose manufacturers to input price volatility and qualification delays. Distribution runs through state-backed channels in China, WHO-coordinated national tenders in Indonesia and Vietnam, and private clinic networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO prequalification pathways erect a cost-of-compliance moat that rewards manufacturers with validated manufacturing platforms and cold-chain documentation, while excluding capital-constrained entrants from Gavi-funded procurement pools.
For Market Incumbents: Anticipate mRNA platform disruption by accelerating cold-chain qualification investments and securing multi-year tender commitments before novel candidates reach phase III endpoints. Bharat Biotech and Chengdu Institute of Biological Products should deepen backward integration into aluminum hydroxide adjuvant production to defend margin position against input price volatility. Regulatory submission parallelism across CDSCO-NMPA divergence remains essential for multinational supplier positioning. For New Entrants and Emerging Players: WHO prequalification in Southeast Asia opens a window for supply contracts in Myanmar and Cambodia, where underpenetrated Mekong basin markets lack domestic manufacturing capacity and rely on irregular donor supply. Target live attenuated platform segments in Indonesian provincial health systems transitioning from inactivated schedules, leveraging single-dose convenience to displace established suppliers. Cold-chain partnership alliances with Ho Chi Minh City logistics providers enable rural district penetration without proprietary infrastructure investment. For Investors and Strategic Acquirers: The window for entry favors platform-agnostic contract manufacturers with existing biological production infrastructure and WHO prequalification track records. Long-term viability hinges on regulatory submission capabilities across divergent CDSCO-NMPA protocols rather than product differentiation alone. Watch for PMDA guidance revisions on Japanese traveler health mandates as the inflection signal for premium segment demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Accelerates Gavi-funded tender access for Indian and Southeast Asian biological manufacturers. |
| Live Attenuated Platform Transition | Reduces programmatic delivery costs in Indonesian and Vietnamese rural districts. |
| Cold-Chain Infrastructure Investment | Enables centralized national tender compliance in Jakarta's Ministry of Health procurement. |
| Adjuvant Backward Integration | Secures aluminum hydroxide supply against Gujarat and Jiangsu production concentration risks. |
| mRNA Platform Development | Compresses development timelines for outbreak response stockpile inclusion in Vietnam and Philippines. |
Research Methodology
Regulatory filings from CDSCO, NMPA, and WHO prequalification databases formed the secondary backbone, supplemented by customs trade data on aluminum hydroxide adjuvant flows and national immunization program procurement disclosures. Primary interviews with vaccine development executives, regulatory affairs leads at biological manufacturers, Gavi procurement officers, and district cold-chain logistics managers in Vietnam and Indonesia validated demand assumptions. Bottom-up triangulation across product platform volumes and top-down reconciliation against Gavi disbursement records anchored market size estimation.
Historical tender award patterns and procurement volume trajectories informed the projection framework across the analysis window. Segmentation modeling incorporated vaccine platform type, delivery route, end-user institution tier, and regional regulatory cluster dimensions. CAGRs derived from weighted average of epidemiological burden projections, national immunization schedule expansion timelines, and manufacturer capacity expansion announcements. Live attenuated platform transition rates and mRNA candidate development milestones served as vaccine-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for mRNA platform commercialization would alter the outlook for inactivated vaccine revenue retention. Forecasts reflect assumptions on Gavi funding continuity, WHO prequalification queue progression, and aluminum hydroxide supply stability. A model refresh is warranted upon material change in Japanese PMDA traveler health mandate revisions or Chinese provincial vaccination campaign expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Communicable Diseases Treatment Market
Infectious Disease
Pelvic Inflammatory Disease (PID) Treatment Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Vaginal Fungi Infections Treatment Market
Infectious Disease
Pyomyositis Market
Infectious Disease
Retropharyngeal Abscess Treatment Market
Infectious Disease
Bronchitis Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
IVD Infectious Disease Market
Infectious Disease
Pork Tapeworm Infection Treatment Market
Infectious Disease
Infectious Disease Molecular Diagnostics Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Viral Hemorrhagic Fever Market