
 Pediatric Healthcare Market | 2026-2036
Pediatric Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Healthcare Market Intelligence
The consolidation of purchasing power within large, integrated children's hospital networks is realigning the competitive landscape for pediatric healthcare providers. Pfizer leverages its extensive vaccine development pipeline to secure large public health contracts with national governments. Novartis specializes in advanced cell and gene therapies for pediatric oncology and rare genetic conditions. Johnson & Johnson sustains a broad market presence through its diverse portfolio, which includes consumer health products, medical devices, and pharmaceuticals tailored for pediatric use.
Pediatric healthcare comprises medical services, pharmaceuticals, and devices tailored to the unique physiological and developmental needs of patients from birth through adolescence. This requires age-specific drug formulations, specialized diagnostic equipment calibrated for smaller body sizes, and treatment protocols that account for distinct developmental stages. Within therapy areas, pediatric oncology and developmental disorders command significant R&D investment and higher reimbursement rates. Pediatric vaccines remain a foundational product type, characterized by large-volume government tenders and public health initiatives.
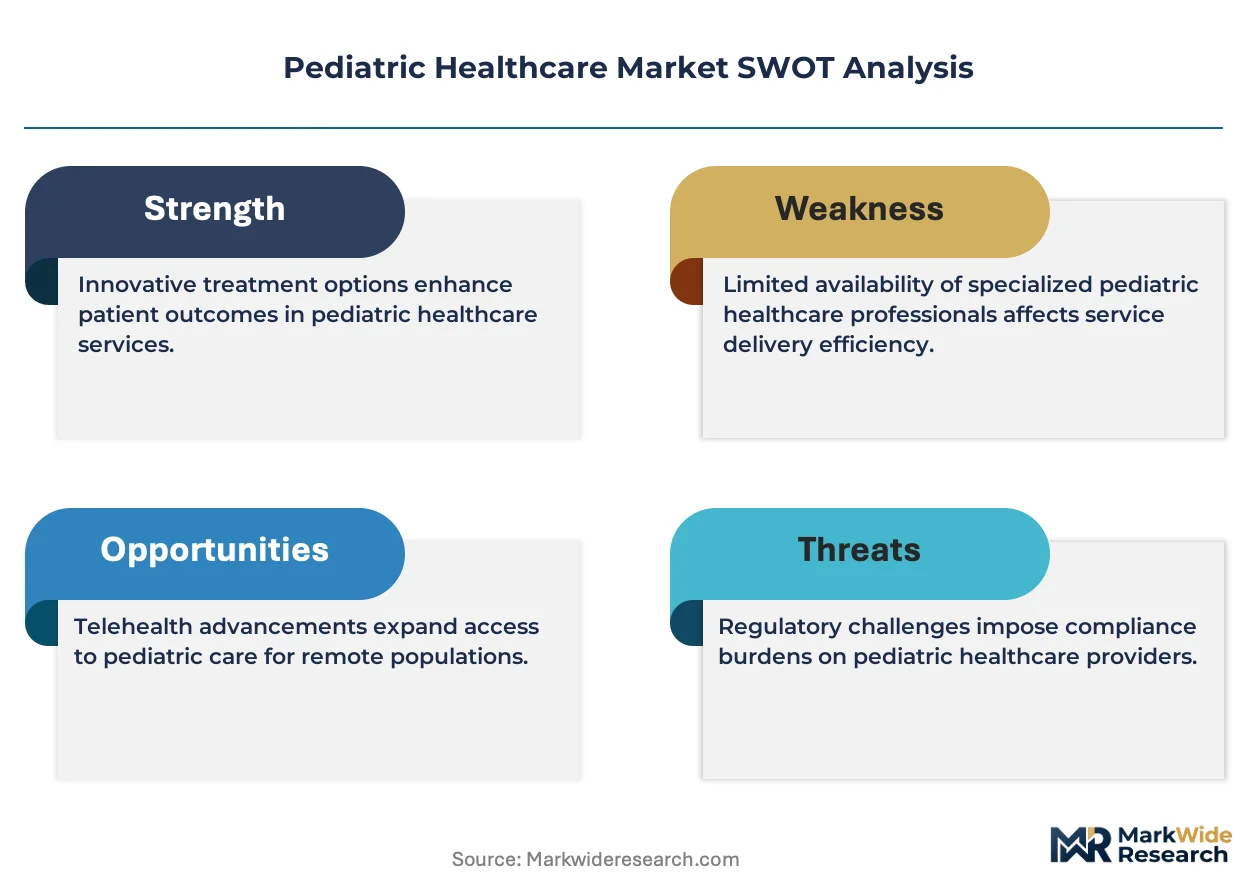
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) impose stringent requirements for pediatric clinical trials. These mandates, alongside standards from bodies like China's NMPA, govern market access by ensuring products are proven safe and effective for specific age groups. Providers must now decide how to integrate emerging telemedicine and home healthcare models while navigating complex reimbursement policies for these newer delivery modes.
Market Dynamics
The pediatric healthcare market's structure is defined by the dual forces of regulatory mandates compelling age-specific clinical trials and technological breakthroughs in gene therapy. This creates a high-stakes environment where market access depends on navigating complex research and development pathways.
Growth Catalysts
- Novel Gene Therapies:The development of advanced gene and cell therapies for rare monogenic diseases, such as spinal muscular atrophy and certain leukemias, provides a significant technological impetus for market expansion and investment in specialized treatment centers.
- Favorable Regulatory Pathways:Incentives like the Orphan Drug Act in the United States and similar frameworks from the EMA encourage investment in pediatric clinical trials for rare diseases by offering market exclusivity and streamlined review processes.
- Specialty Care Expansion:Demand from integrated children's hospital networks and specialty care centers for advanced diagnostic and treatment technologies is expanding, particularly in developed economies like the United States, Germany, and Japan.
Market Restraints
- High Development Costs:The substantial financial investment required for developing age-specific drug formulations and conducting rigorous, multi-stage pediatric clinical trials acts as a significant barrier to entry for smaller pharmaceutical and biotech firms.
- Clinical Trial Complexity:Ethical considerations and logistical challenges associated with enrolling pediatric patients, especially infants and neonates, in clinical studies create bottlenecks that can delay product development and regulatory approval timelines.
- Divergent Regulatory Standards:Navigating disparate and stringent data requirements from global regulatory bodies, including the FDA, EMA, and China's NMPA, complicates global product launches and increases compliance costs for manufacturers.
Strategic Opportunities
- Telemedicine Integration:The convergence of telemedicine platforms with remote patient monitoring devices offers a significant opportunity to manage chronic pediatric conditions like asthma and diabetes, improving care continuity and access in rural areas.
- Emerging Market Penetration:There is a substantial opportunity to expand access to essential pediatric vaccines and specialty care services in large, underserved populations across Southeast Asia and Latin America through public-private partnerships.
- Public Health Initiatives:Large-volume government tenders and public health programs focused on vaccination and preventative care in countries such as India and Brazil provide a stable and predictable demand channel for foundational pediatric products.
Industry Challenges
- Reimbursement Policy Navigation:Providers face significant operational hurdles in securing adequate and consistent reimbursement for novel treatments like gene therapies and new delivery models like home healthcare, which often lack established payment codes.
- Specialized Talent Shortages:A persistent lack of trained pediatric sub-specialists, particularly in high-demand fields such as developmental-behavioral pediatrics and pediatric endocrinology, constrains the capacity of healthcare systems to deliver specialized care.
- Legacy System Integration:The complexity of integrating modern electronic health records and digital diagnostic tools with outdated hospital IT infrastructure creates data silos, operational inefficiencies, and cybersecurity vulnerabilities for healthcare providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Healthcare Market |
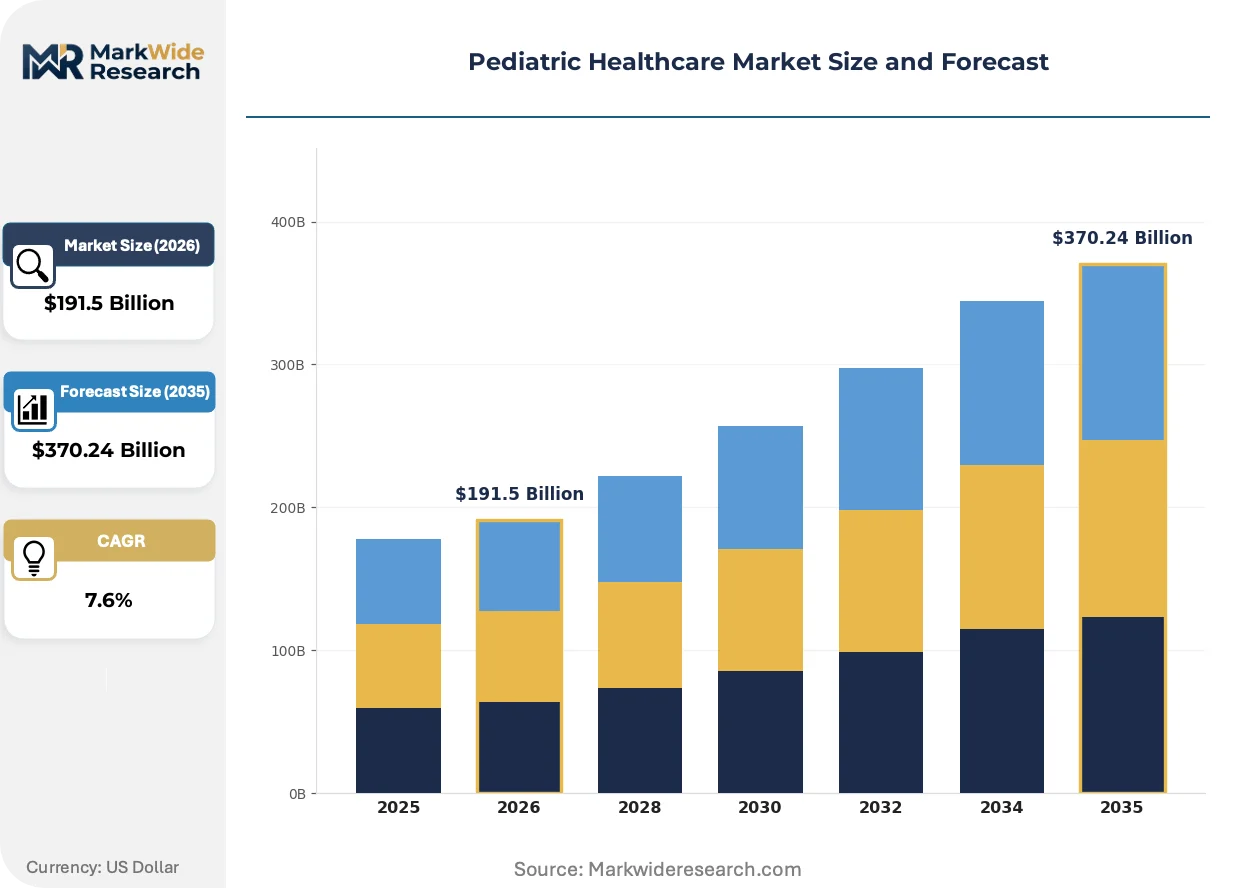
| Market Size in 2026 | $191.5 Billion |
| Market Size in 2035 | $370.24 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pediatric Vaccines, Nutritional Supplements, Growth Hormones, Diagnostic Devices, Therapeutic Equipment Therapy Area: Neonatology, Pediatric Oncology, Infectious Diseases, Pediatric Cardiology, Developmental Disorders End User: Children's Hospitals, Pediatric Clinics, Diagnostic Laboratories, Specialty Care Centers, Community Health Facilities Delivery Mode: Inpatient Care, Outpatient Services, Telemedicine, Home Healthcare, Mobile Clinics |
| Companies Covered | Johnson & Johnson, Novartis, Pfizer, AstraZeneca, Roche Holding, GlaxoSmithKline, Merck & Co., Abbott Laboratories, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Healthcare Market Strategic Shifts & Innovations
Precision medicine is fundamentally altering treatment protocols, shifting the focus from broad-spectrum interventions to highly targeted therapies for genetic and oncological conditions. This movement is paralleled by the digital transformation of care delivery, which is decentralizing services beyond traditional hospital settings.
Cell and gene therapies represent a paradigm shift in treating pediatric diseases. These treatments are designed to correct underlying genetic defects or engineer a patient's own cells to fight cancer. Specialized pediatric oncology centers and rare disease institutes are the primary adopters. This technology is electrifying the therapeutic landscape for previously untreatable conditions, creating entirely new, high-value segments focused on curative outcomes.
Regulatory mandates for pediatric-specific data are becoming more stringent worldwide. Policies from the U.S. FDA and the European Medicines Agency now require Pediatric Investigation Plans (PIPs) for most new drugs, compelling sponsors to conduct studies in children. This forces earlier investment in pediatric research during the drug development lifecycle. The oncology and rare disease therapy areas are most affected, requiring complex trial designs to prove safety and efficacy across specific age cohorts.
Consolidation of purchasing power within large, integrated children's hospital networks is a defining demand-side shift. This trend is displacing fragmented, single-institution procurement with centralized, volume-based contracting for pharmaceuticals, vaccines, and medical devices. This pattern is most advanced in the United States and parts of the United Kingdom, where health systems are leveraging their scale to negotiate more favorable pricing and standardize care protocols.
Pediatric Healthcare Market Segmentation
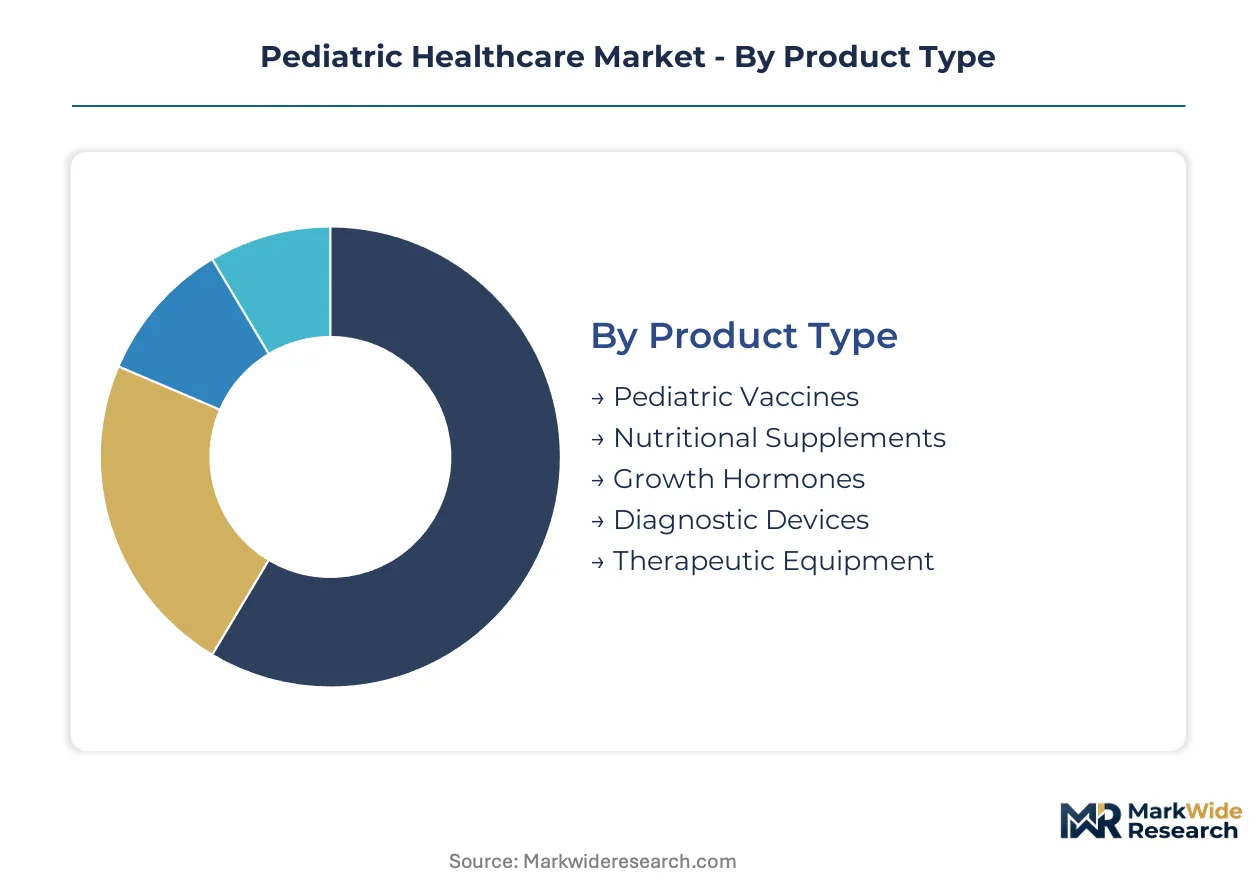
Understanding the Pediatric Healthcare Market requires a granular examination of its constituent segments, revealing distinct demand drivers and competitive dynamics. This segmentation illuminates where value creation concentrates and identifies areas ripe for specialized innovation. Strategic planning for market participants relies on precise insights into these varied sub-markets.
Product Type:
High-volume foundational products contrast sharply with premium, technology-intensive solutions within the product type segmentation.
- Pediatric Vaccines:These biological preparations stimulate immunity against infectious diseases, formulated specifically for pediatric immune systems and developmental stages. Demand concentrates in national public health programs across India and Brazil, driven by large-scale immunization initiatives.
- Nutritional Supplements:These products provide essential vitamins, minerals, and other nutrients, supporting infant and adolescent development across all regions.
- Growth Hormones:Pharmaceutical agents treat growth hormone deficiency, often requiring specialized medical oversight and specific reimbursement criteria.
- Diagnostic Devices:Specialized medical equipment and consumables calibrated for smaller body sizes and unique physiological parameters of pediatric patients. Demand is concentrating in integrated children's hospital networks in the United States and Germany, driven by advanced diagnostic needs.
- Therapeutic Equipment:Devices like ventilators and infusion pumps are adapted for pediatric use, supporting critical care and chronic condition management.
Mature deployment sits with Pediatric Vaccines. Newer deployment is concentrated in Diagnostic Devices.
Therapy Area:
Specialized applications define the therapy area segments, reflecting varying levels of R&D intensity and reimbursement structures.
- Neonatology:Medical services and products for critically ill or premature newborn infants, requiring highly specialized equipment and personnel.
- Pediatric Oncology:Comprehensive medical treatment for cancers affecting children, encompassing chemotherapy, radiation, and advanced cell and gene therapies. Demand is high in specialized pediatric cancer centers in the United States and Europe, driven by complex treatment protocols and research.
- Infectious Diseases:Diagnostics and treatments for common pediatric infections, with public health initiatives driving large-scale procurement.
- Pediatric Cardiology:Diagnosis and treatment of congenital and acquired heart conditions in children, requiring specialized surgical procedures in centers like Japan.
- Developmental Disorders:Interventions and therapies for conditions affecting a child's physical, cognitive, communication, social, and emotional development. Significant R&D investment targets novel therapies for conditions like autism spectrum disorder.
Pediatric Oncology represents the fastest-growing trajectory, driven by breakthroughs in targeted therapies.
End User:
Customer type differentiation shapes the end-user landscape, ranging from large institutional buyers to local community providers.
- Children's Hospitals:Dedicated facilities offering comprehensive, multidisciplinary care for pediatric patients, often serving as referral centers for complex cases. These institutions drive demand for advanced medical devices and specialized pharmaceuticals in urban centers.
- Pediatric Clinics:Outpatient facilities provide primary and secondary care for children, serving as the first point of contact for routine check-ups.
- Diagnostic Laboratories:Facilities conduct specialized tests for pediatric conditions, including genetic screenings and infectious disease panels.
- Specialty Care Centers:Focused facilities providing highly specialized treatment for specific pediatric conditions, such as diabetes, cystic fibrosis, or neurological disorders. Demand is strong in developed economies like the United States and Germany for advanced therapeutic options.
- Community Health Facilities:Local clinics offer basic pediatric health services, often serving underserved populations with a focus on preventative care.
Children's Hospitals are consistently expanding their service offerings, while Specialty Care Centers are gaining share fastest through focused expertise.
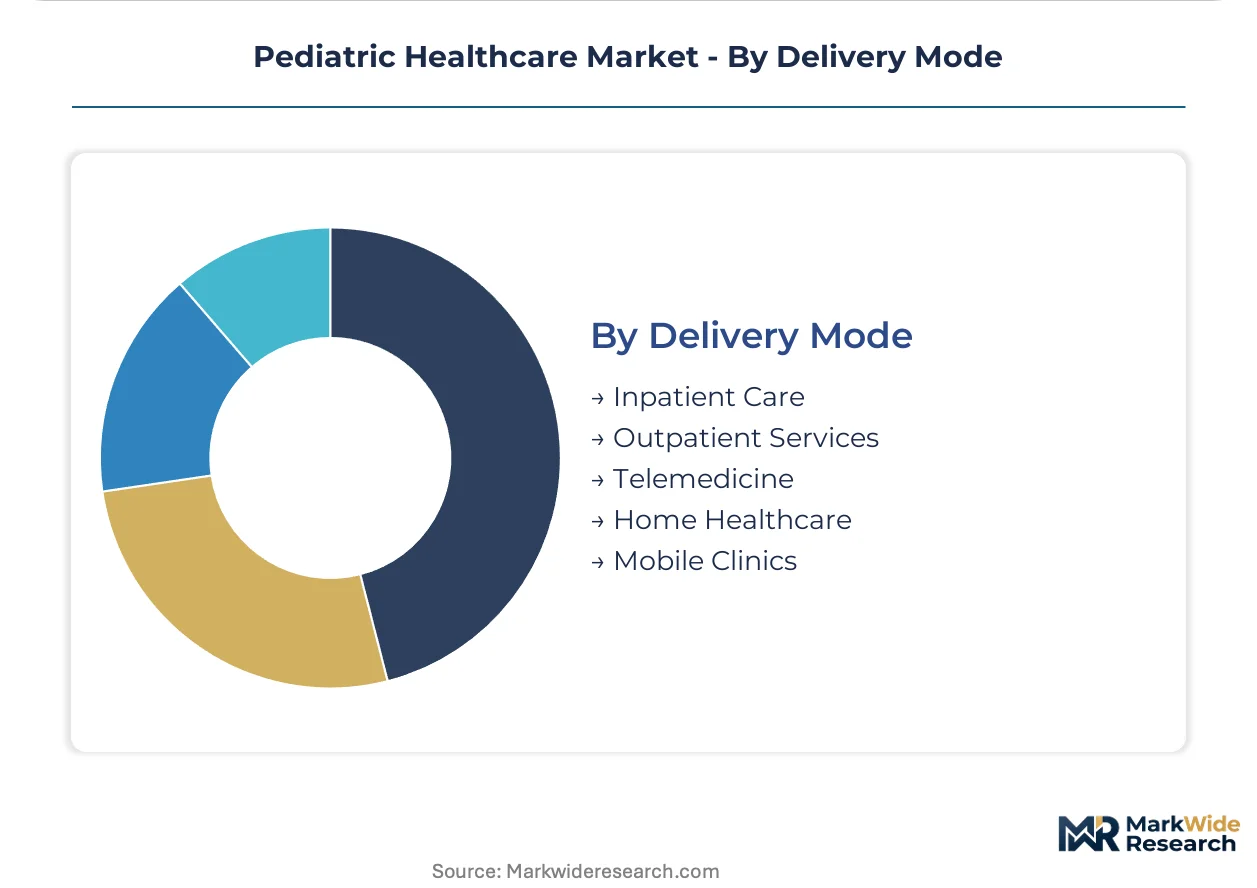
Delivery Mode:
Cost efficiency and patient access drive the delivery mode segmentation, influencing how pediatric healthcare services are rendered.
- Inpatient Care:Services requiring overnight hospital stays for intensive monitoring or complex treatments, essential for critical pediatric conditions.
- Outpatient Services:Medical consultations and treatments without overnight stays, forming the backbone of accessible pediatric care.
- Telemedicine:Delivery of healthcare services remotely using telecommunications technology, enabling virtual consultations, monitoring, and specialist advice. Adoption is expanding most quickly in rural areas and for chronic disease management in the United States.
- Home Healthcare:Medical and supportive care provided in patients' homes for chronic conditions, improving comfort and reducing readmissions.
- Mobile Clinics:Portable units deliver healthcare to underserved communities, providing basic screenings and vaccinations in remote regions.
Telemedicine and Home Healthcare demonstrate the steepest expansion trajectory, driven by convenience and technological integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors significant innovation and investment within the global pediatric healthcare landscape. This prominence stems from robust research infrastructure and a regulatory environment that incentivizes the development of specialized treatments for children. Other developed economies and large emerging markets also contribute substantially to the market's expansion through tailored initiatives.
United States
Demand for advanced diagnostic and treatment technologies, particularly novel gene therapies for rare diseases, drives market activity. The Orphan Drug Act and FDA's Pediatric Investigation Plans (PIPs) encourage pharmaceutical investment in pediatric clinical trials. The Boston/Cambridge biotech hub remains a critical center for pediatric rare disease research and specialized therapeutic development.
Germany
Specialty care expansion and a strong focus on advanced diagnostic devices characterize the German pediatric healthcare market. European Medicines Agency (EMA) mandates for pediatric clinical trials shape product development and market entry. Munich and Berlin host robust pediatric oncology research centers, advancing complex treatment protocols.
Japan
Specialized surgical procedures for pediatric cardiology and sophisticated diagnostic equipment generate significant demand in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) issues specific guidelines for pediatric drug development and medical device approvals. Demand is concentrating in Tokyo and Osaka, home to leading children's hospitals and medical device manufacturers.
India
Large-scale immunization initiatives and the procurement of essential pediatric vaccines are primary market drivers. The Central Drugs Standard Control Organization (CDSCO) regulates drug approvals, supporting various public health programs. Hyderabad and Pune are emerging as key centers for vaccine manufacturing and pediatric clinical trials.
Brazil
Public health programs focused on vaccination and preventative care sustain a stable demand channel for foundational pediatric products. ANVISA provides regulatory oversight for pharmaceutical products, aligning with national immunization strategies. São Paulo and Rio de Janeiro feature expanding pediatric clinics and community health facilities.
Pediatric Healthcare Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue novel gene therapies and digital health solutions. The market exhibits a tiered structure, with large diversified pharmaceutical corporations and specialized biotech firms competing across distinct segments. Key strategic archetypes include broad-portfolio pharmaceutical giants, focused cell and gene therapy developers, and specialized medical device manufacturers. Competitive moves often involve portfolio diversification to cover various pediatric needs and strategic partnerships to accelerate research and development.
Within the diversified pharmaceutical archetype, Johnson & Johnson maintains a broad market presence through its consumer health products, medical devices, and pharmaceuticals. Novartis occupies a position as a leader in advanced cell and gene therapies for pediatric oncology and rare genetic conditions. Pfizer leverages its extensive vaccine development pipeline to secure large public health contracts with national governments.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Novartis |
| Pfizer |
| AstraZeneca |
| Roche Holding |
| GlaxoSmithKline |
| Merck & Co. |
| Abbott Laboratories |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Vertical integration, particularly by large pharmaceutical companies, anchors both the supply position of specialized pediatric formulations and their pricing power for novel therapies. This structure influences market access and cost recovery for advanced treatments.
Pricing Analysis
Value-based pricing models for gene therapies often bundle long-term monitoring and patient support, reflecting the high upfront cost and curative potential. Price differentiation stems from clinical efficacy data and regulatory designations like orphan drug status in the United States. Pricing pressure stems from payer negotiations for high-cost treatments. Public health programs are most price-sensitive for foundational products like vaccines, while specialty care centers show less sensitivity for advanced oncology therapies.
Supply Chain Analysis
Stringent regulatory certifications from the FDA and EMA gate market access for pediatric medical devices and pharmaceuticals. Supply concentration for specialized inputs like viral vectors for gene therapy centers in the United States and Germany. Raw material dependencies include highly purified biologics and specialized diagnostic reagents. Single-source vulnerability for rare disease therapies presents a structural supply chain risk. Distribution runs through integrated children's hospital networks and national public health procurement agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pediatric healthcare market is a vertical-integration race, driven by firms seeking to control specialized manufacturing for cell and gene therapies. This allows tighter quality control and accelerated market entry for novel treatments.
For Market Incumbents: Acquire specialized pediatric clinical research organizations to accelerate trial timelines and navigate complex ethical considerations. This defends against emerging biotech firms with novel gene therapy platforms. Invest in advanced manufacturing capabilities for age-specific drug formulations to mitigate regulatory shifts requiring pediatric data. Expand digital health platforms to counter telemedicine entrants.
For New Entrants and Emerging Players: Launch via telemedicine platforms to access underserved rural populations for chronic disease management. Focus on developing diagnostic tools calibrated for smaller body sizes, targeting the underpenetrated home healthcare segment. Leverage public-private partnerships in Southeast Asia for essential vaccine distribution. Emphasize cost-effective solutions for common pediatric infections.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized biotech firms developing curative gene therapies for rare pediatric diseases. These companies offer long-term viability over a 5-10 year window, driven by high reimbursement rates and unmet medical needs. Target firms with robust clinical trial pipelines and established regulatory relationships. A key signal to watch is successful Phase 3 trial completion for novel therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates novel gene therapy approvals, addressing rare pediatric disease burdens. |
| Manufacturing Scale-Up | Ensures consistent supply of specialized pediatric drug formulations for global demand. |
| Hospital System Partnership | Integrates advanced diagnostic devices and treatment protocols within children's hospitals. |
| Telemedicine Platform Development | Expands access to specialized pediatric care for chronic conditions in rural areas. |
| Public-Private Partnership | Secures large-volume government tenders for essential pediatric vaccines in emerging markets. |
Research Approach
Independent corroboration across FDA filings, EMA submissions, and ClinicalTrials.gov underwrites the qualitative findings and market sizing. This methodology combines extensive primary interviews with regulatory affairs leads, hospital procurement managers, and pediatric sub-specialists. Secondary validation draws from formulary databases and industry association reports. Bottom-up and top-down triangulation ensures data consistency.
Rate-of-change decomposition analyzes historical trends and future projections across the analysis window. This framework models segmentation dimensions including product type, therapy area, end user, and delivery mode. Pediatric patient demographics and regional regulatory clusters also inform the model. Compound annual growth rates derive from a robust statistical analysis of these variables.
Unforeseen clinical trial outcomes, evolving reimbursement policies, and new regulatory mandates are the dominant revision risks. Forecasts reflect assumptions documented at the time of publication. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Mattress Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Pediatric MRI Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Global Pediatric Radiology Market