
 Global Pediatric Home Healthcare Services Market | 2026-2036
Global Pediatric Home Healthcare Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pediatric Home Healthcare Services Market Foresight
Modular service bundling is broadening buyer choice across the Global Pediatric Home Healthcare Services Market. Aveanna Healthcare leverages its multi-state network to sustain geographic coverage density for complex pediatric cases. BAYADA Home Health Care anchors its competitive stance through specialized clinical training protocols for pediatric nurses. Interim HealthCare Inc. differentiates by integrating family education modules into standard care plans.
Pediatric home healthcare services encompass skilled medical and therapeutic interventions delivered in a child's residence, typically requiring licensed nursing staff, durable medical equipment coordination, and family-centered care protocols that maintain clinical outcomes outside institutional settings. The primary purpose is reducing hospital readmission rates while supporting developmental continuity for children with chronic conditions. Skilled nursing commands the largest service-type revenue pool due to reimbursement advantages under Medicaid and private payer plans. Telehealth represents the fastest-expanding technology dimension as remote patient monitoring platforms gain payer acceptance for routine pediatric assessments. Home care settings retain dominant patient volume, though transitional care segments show rising utilization as hospitals accelerate discharge planning for medically complex pediatric populations.
The US FDA oversees medical device safety for home-use pediatric monitoring equipment, while state Medicaid agencies determine nursing hour authorization thresholds that directly shape service demand curves. HIPAA compliance requirements constrain data-sharing architectures across telehealth and electronic health record platforms, elevating operational costs for multi-state providers. Stakeholders must monitor evolving CMS guidance on home health value-based purchasing models and assess whether technology investments align with emerging quality metric frameworks.
Market Dynamics
Medicaid waiver program expansions across multiple US states are restructuring reimbursement authorization workflows, directly altering how pediatric home healthcare providers scale nursing capacity and geographic coverage density.
Growth Catalysts
- Medicaid HCBS Waivers:State-level Home and Community-Based Services waivers in Texas, Florida, and Ohio are extending nursing hour caps for medically complex pediatric patients, expanding addressable service volumes.
- Remote Patient Monitoring:FDA-cleared pediatric wearable devices for vital sign tracking are gaining CMS reimbursement codes, enabling continuous clinical oversight without in-person visits.
- Nursing Licensure Compacts:The Enhanced Nurse Licensure Compact now covers forty-one US states, allowing providers to deploy staff across state lines without redundant credentialing delays.
Market Restraints
- Registered Nurse Supply Concentration:Pediatric specialty nurses cluster disproportionately in urban hospital systems, leaving rural and exurban markets chronically understaffed for home-based deployment.
- Medicaid Rate Compression:State budget cycles in California, New York, and Illinois periodically freeze or reduce per-hour nursing reimbursement, squeezing provider operating margins.
- HIPAA Technical Safeguards:Encryption and access control requirements for telehealth platforms elevate IT infrastructure costs, particularly for multi-state operators managing fragmented state privacy overlays.
Strategic Opportunities
- India Pediatric Home Care:CDSCO regulatory pathways for imported medical devices are streamlining, opening avenues for US and European providers to export monitoring equipment and training protocols.
- Hospital-at-Home Pilots:CMS acute hospital care at home waivers are expanding eligibility to pediatric populations, creating new reimbursement streams for post-surgical and oncology patients.
- AI-Assisted Triage:Machine learning algorithms integrated with remote monitoring platforms are reducing false-positive alert rates, lowering nursing labor intensity per enrolled patient.
Industry Challenges
- Pediatric Specialty Certification Bottlenecks:Pediatric Home Health Nurse certification programs maintain limited annual cohort sizes, constraining workforce pipeline velocity.
- EHR Interoperability Friction:Home health agencies struggle to integrate proprietary telehealth data streams with hospital Epic and Cerner systems, delaying care coordination.
- Durable Medical Equipment Logistics:Ventilator and feeding pump maintenance networks lack density outside metropolitan corridors, extending equipment downtime in dispersed markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pediatric Home Healthcare Services Market |
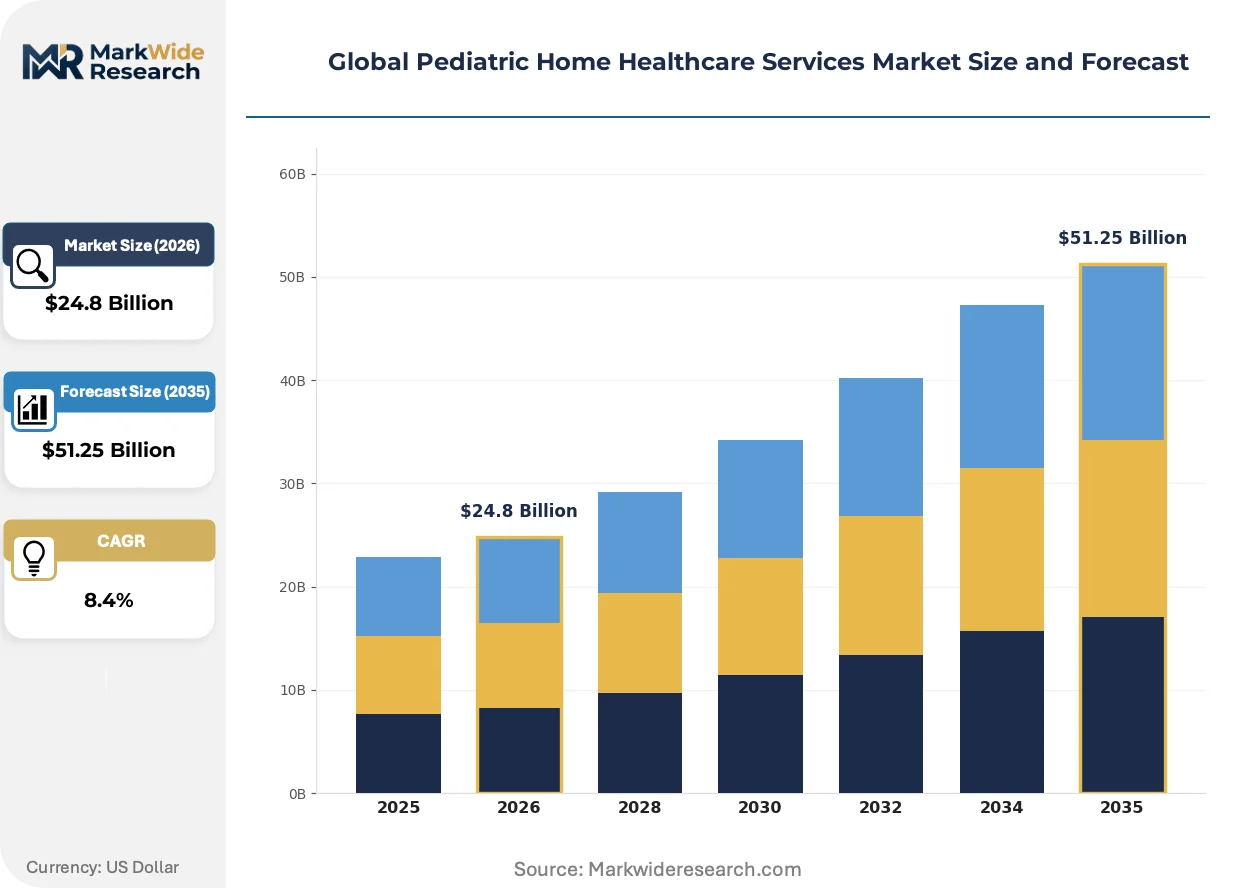
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Skilled Nursing, Physical Therapy, Occupational Therapy, Speech Therapy End User: Pediatric Patients, Families, Healthcare Providers, Caregivers Technology: Telehealth, Monitoring Devices, Mobile Apps, Electronic Health Records Care Setting: Home Care, Outpatient Care, Long-Term Care, Transitional Care |
| Companies Covered | Pediatric Home Service, Interim HealthCare Inc., Aveanna Healthcare, Care Options for Kids, BrightStar Care, BAYADA Home Health Care, Angels of Care Pediatric Home Health, Continuum Pediatric Nursing, Maxim Healthcare Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pediatric Home Healthcare Services Market Shifts & Advancements
Technology convergence between remote physiological monitoring and predictive analytics is compressing the latency between clinical deterioration signals and nursing intervention, redefining standard-of-care expectations for high-acuity pediatric cases.
Remote patient monitoring platforms are unifying continuous glucose tracking, pulse oximetry, and respiratory rate analytics into single-dashboard interfaces for pediatric patients with complex cardiac or metabolic conditions. Children's hospitals in Boston, Cincinnati, and Philadelphia are deploying these integrated systems for post-discharge surveillance of single-ventricle heart defect patients. This unifying architecture is collapsing the distinction between episodic home nursing visits and continuous virtual ward coverage, pressuring traditional staffing models built on hourly billing increments.
REACH authorization requirements for medical device substances of very high concern are extending compliance obligations to home-use pediatric monitoring equipment sold into European markets. Manufacturers must now document full material disclosure for sensors, adhesives, and battery components in FDA-cleared devices seeking CE marking. German and French notified bodies are enforcing these requirements most stringently, delaying market entry for US and Asian device makers by six to eighteen months.
Family caregivers are assuming expanded clinical responsibilities through structured training modules embedded in standard care plans, displacing reliance on scheduled nursing visits for routine tracheostomy suctioning and gastrostomy tube management. Pediatric home health agencies in Arizona, Colorado, and North Carolina are certifying parents as delegated care providers under state nurse practice act exemptions. This behavioral shift concentrates in markets where Medicaid nursing hour authorizations remain capped below clinical need thresholds.
Global Pediatric Home Healthcare Services Market Segmentation
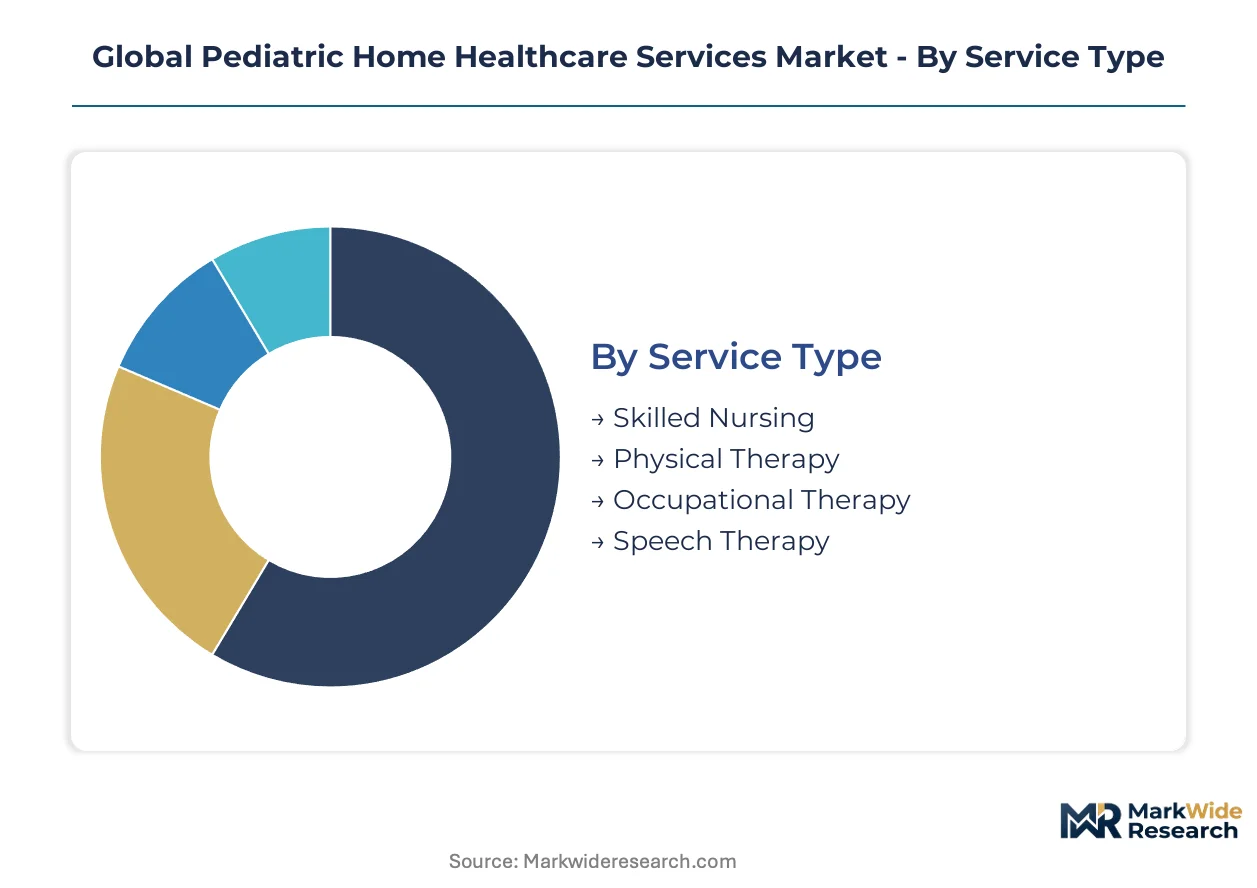
Pediatric home healthcare services fragment across four distinct category axes, each shaping how providers configure staffing models, technology stacks, and reimbursement strategies. Understanding these segment boundaries clarifies where Medicaid waivers concentrate funding and which technology investments yield measurable clinical returns.
Service Type:
Customization intensity varies sharply across this category, from standardized therapy protocols to highly individualized nursing care plans shaped by patient acuity and family capacity.
- Skilled Nursing:Licensed registered nurses deliver medication administration, ventilator management, and tracheostomy care under physician-directed protocols. Demand concentrates in Texas, Florida, and Ohio where Medicaid HCBS waivers have lifted nursing hour caps for medically complex pediatric patients, though rural markets face chronic staffing shortages.
- Physical Therapy:Mobility rehabilitation and gross motor development interventions target children with cerebral palsy, muscular dystrophy, and post-surgical recovery trajectories. Pediatric hospitals in Boston and Philadelphia anchor referral networks, with home-based deployment expanding fastest in markets where transportation barriers limit clinic access.
- Occupational Therapy:Fine motor skill development and adaptive equipment training support daily living independence.
- Speech Therapy:Augmentative communication and feeding/swallowing interventions address developmental delays and neurological conditions.
Leading the category by volume: Skilled Nursing. Expanding most quickly: Physical Therapy.
End User:
Cost tier stratification dominates this category, from institutional purchasers with negotiated rate schedules to individual families paying out-of-pocket for supplemental services.
- Pediatric Patients:Children with congenital heart defects, neuromuscular disorders, and technology-dependent conditions constitute the direct clinical focus. Complex cardiac patients discharged from Cincinnati Children's Hospital and Children's Hospital of Philadelphia drive highest acuity demand, with remote monitoring reducing readmission frequency.
- Families:Parents and guardians function as delegated care providers under state nurse practice act exemptions in Arizona, Colorado, and North Carolina. Structured training modules displace scheduled nursing visits for routine tracheostomy suctioning and gastrostomy tube management where Medicaid hour caps fall below clinical thresholds.
- Healthcare Providers:Hospitals, specialty clinics, and accountable care organizations coordinate referral workflows and outcomes accountability.
- Caregivers:Extended family members and paid non-clinical assistants supplement formal nursing coverage.
Dominating reimbursement volume: Pediatric Patients. Gaining share fastest: Families.
Technology:
Application maturity separates this category, from established EHR infrastructure to emerging AI-assisted triage platforms still seeking CMS coding acceptance.
- Telehealth:Video consultation and asynchronous messaging platforms enable remote physician oversight and nursing triage. CMS reimbursement codes for routine pediatric assessments are expanding, with integrated platforms unifying continuous glucose tracking, pulse oximetry, and respiratory rate analytics for single-ventricle heart defect surveillance.
- Monitoring Devices:FDA-cleared pediatric wearables for vital sign tracking include continuous glucose monitors and pulse oximetry sensors. REACH authorization requirements for substances of very high concern extend compliance obligations to sensors, adhesives, and battery components in devices seeking CE marking for German and French markets.
- Mobile Apps:Care coordination and medication adherence tools connect families with nursing teams.
- Electronic Health Records:Documentation platforms face interoperability friction integrating proprietary telehealth data streams with hospital Epic and Cerner systems.
Highest deployment maturity: Electronic Health Records. Steepest expansion trajectory: Telehealth.
Care Setting:
Patient volume concentration against margin profile distinguishes this category, with high-touch home care commanding premium rates against lower-acuity transitional alternatives.
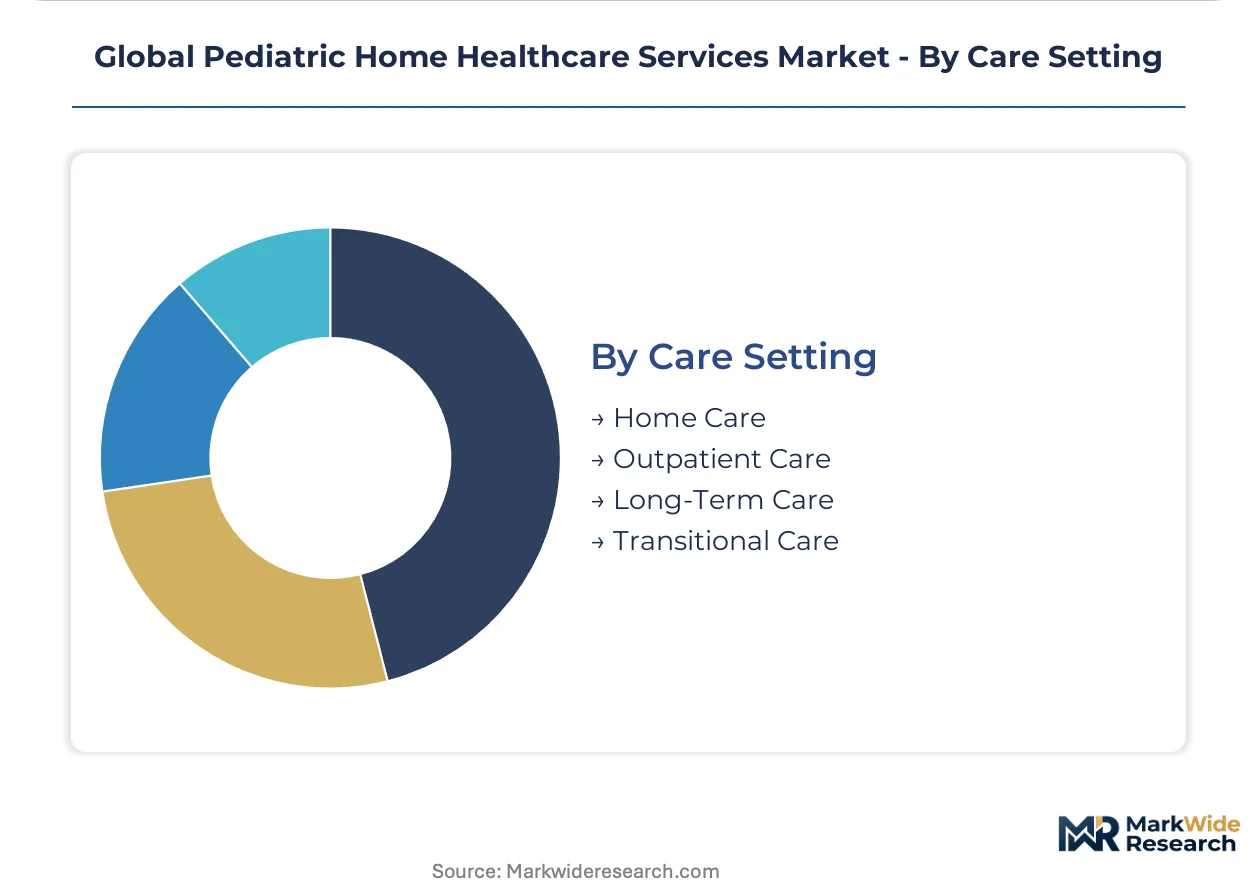
- Home Care:Residence-based skilled nursing and therapy services retain dominant patient volume across the market. Ventilator and feeding pump maintenance networks lack density outside metropolitan corridors, extending equipment downtime in dispersed US markets and constraining service reliability.
- Transitional Care:Post-discharge surveillance and hospital-at-home pilots are gaining utilization as CMS acute hospital care at home waivers expand eligibility to pediatric populations. Post-surgical and oncology patients in Boston, Cincinnati, and Philadelphia anchor early adoption.
- Outpatient Care:Clinic-based therapy and nursing visits serve patients with reliable transportation access.
- Long-Term Care:Residential facilities accommodate children requiring 24-hour supervision beyond family capacity.
Commanding greatest patient volume: Home Care. Climbing the fastest: Transitional Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service delivery concentrates in high-income markets with established Medicaid infrastructure, while emerging economies build regulatory frameworks for imported medical devices and training protocols.
United States
Medicaid HCBS waivers in Texas, Florida, and Ohio extend nursing hour caps for medically complex pediatric patients. CMS guidance on home health value-based purchasing models shapes provider technology investments. Children's hospitals in Boston, Cincinnati, and Philadelphia deploy integrated remote monitoring systems for post-discharge surveillance of single-ventricle heart defect patients.
Germany
German notified bodies enforce REACH authorization requirements for substances of very high concern in home-use pediatric monitoring equipment most stringently. CE marking delays for US and Asian device makers extend six to eighteen months. Medical device clusters in Munich and Berlin concentrate regulatory consulting expertise for pediatric wearable compliance.
India
CDSCO regulatory pathways for imported medical devices are streamlining, opening avenues for US and European providers. Central Drugs Standard Control Organization oversight governs continuous glucose monitors and pulse oximetry sensors seeking market authorization. Pediatric home care networks in Maharashtra and Karnataka pilot remote monitoring platforms for technology-dependent children.
United Kingdom
NHS England hospital-at-home initiatives expand eligibility to pediatric post-surgical and oncology populations. National Institute for Health and Care Excellence guidelines influence remote patient monitoring reimbursement thresholds. London and Manchester anchor integrated care systems testing AI-assisted triage for high-acuity pediatric cases.
Japan
PMDA pediatric medical device review pathways prioritize home-use monitoring equipment with established FDA clearance. Ministry of Economy, Trade and Industry funding supports telehealth platform development for rural pediatric access. Tokyo and Osaka metropolitan corridors concentrate pediatric specialty nursing workforce for home-based deployment.
Global Pediatric Home Healthcare Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Global Pediatric Home Healthcare Services Market. The vendor base stratifies into three tiers: multi-state networks with geographic coverage density, regional specialists with deep clinical training protocols, and technology-enabled platforms integrating family education modules. Dominant competitive moves include multi-state nursing licensure compact utilization for staff deployment flexibility and strategic partnerships with children's hospitals for referral workflow integration.
Within the multi-state network tier, Aveanna Healthcare and BAYADA Home Health Care exemplify geographic coverage archetypes, while Interim HealthCare Inc. represents the technology-integrated family education model. These three entities anchor distinct competitive positioning vectors: nursing hour authorization optimization, specialized pediatric clinical protocols, and care plan customization through family caregiver training modules.
| Leading Market Players |
|---|
| Pediatric Home Service |
| Interim HealthCare Inc. |
| Aveanna Healthcare |
| Care Options for Kids |
| BrightStar Care |
| BAYADA Home Health Care |
| Angels of Care Pediatric Home Health |
| Continuum Pediatric Nursing |
| Maxim Healthcare Services |
| Others |
Supply & Pricing Matrix
REACH authorization requirements for substances of very high concern gate qualified supply of pediatric monitoring equipment into European markets, with CE marking delays of six to eighteen months restricting premium-tier pricing access for non-compliant manufacturers. German and French notified bodies enforce these mandates most stringently, compressing margins for US and Asian device makers unable to document full material disclosure.
Pricing Analysis
Margin tightening in skilled nursing services reflects Medicaid rate compression cycles in California, New York, and Illinois that periodically freeze per-hour reimbursement. Three-tier pricing structure across premium, standard, and economy levels differentiates providers by geographic coverage density and specialized pediatric certification status. Cost-down pressure on telehealth platforms accelerates because HIPAA technical safeguard requirements elevate IT infrastructure spending for multi-state operators. Hospital systems demonstrate lowest price sensitivity due to outcomes-based contracting priorities, while individual families paying out-of-pocket exhibit highest sensitivity to per-visit rate variations.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO regulatory pathways are reshaping sourcing strategies for imported pediatric monitoring equipment, requiring localized technical documentation and training protocol adaptation. Manufacturing concentrates in the United States for FDA-cleared devices, Germany for REACH-compliant European market entry, and China for component-level sensor production. Component dependencies include pediatric-specific pulse oximetry sensors, continuous glucose monitor adhesives, and lithium-ion battery cells. Single-source vulnerability concentrates in proprietary telehealth software architectures that struggle with EHR interoperability. Distribution runs through children's hospital referral networks, Medicaid waiver program authorization workflows, and direct-to-family equipment leasing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
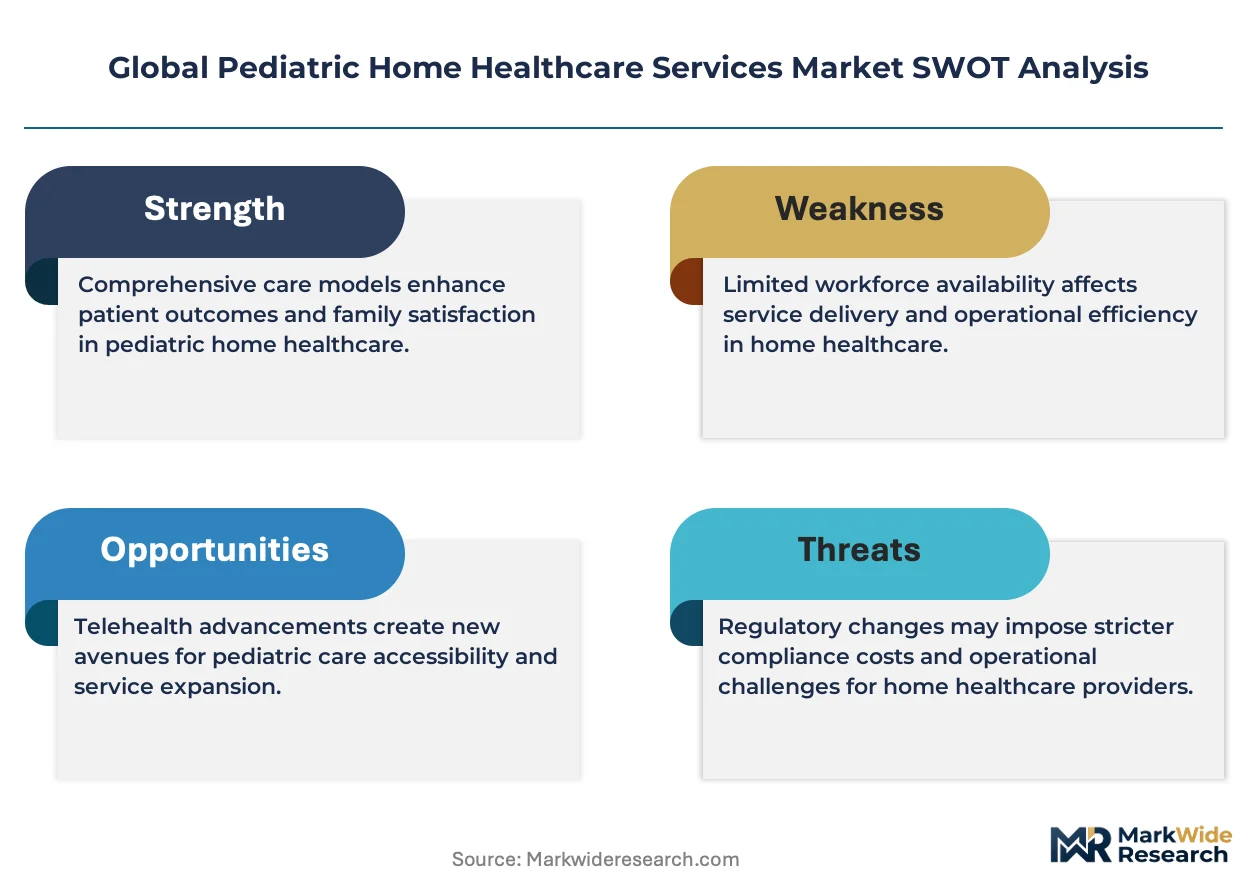
Pediatric specialty nurse certification bottlenecks constrain workforce pipeline velocity, propping pricing power for qualified providers capable of deploying licensed staff across state lines through the Enhanced Nurse Licensure Compact.
For Market Incumbents: Hedge against Medicaid rate compression by diversifying reimbursement streams through CMS hospital-at-home waiver participation and private payer value-based contracts. Backward integration into remote patient monitoring platform development reduces dependency on third-party telehealth vendors facing HIPAA compliance cost escalation. Geographic coverage density in Texas, Florida, and Ohio anchors defensive positioning where HCBS nursing hour caps have expanded most aggressively.
For New Entrants and Emerging Players: CMS acute hospital care at home waivers in the United States open a window for post-surgical and oncology pediatric segments previously captured by institutional providers. Target transitional care settings in Boston, Cincinnati, and Philadelphia where children's hospitals accelerate discharge planning for medically complex populations. Pursue strategic partnerships with integrated care systems testing AI-assisted triage platforms to bypass capital-intensive nursing workforce buildout.
For Investors and Strategic Acquirers: FDA clearance timelines for pediatric wearable devices are the leading indicator that technology-enabled platforms will consolidate ahead of pure-play nursing staffing models. Five-to-ten-year viability favors acquirers of remote monitoring infrastructure with established CMS reimbursement codes and hospital system integration capabilities. Watch for Enhanced Nurse Licensure Compact expansion announcements as workforce mobility inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Children's Hospital of Philadelphia and Cincinnati Children's anchor referral networks for complex cardiac discharge planning. |
| Reimbursement Strategy | CMS hospital-at-home waivers create new authorization pathways for post-surgical pediatric populations. |
| Software Companion Development | AI-assisted triage integration with remote monitoring reduces false-positive alert rates and nursing labor intensity. |
| CE Marking Pathway | German notified body enforcement of REACH requirements delays market entry for non-compliant device manufacturers. |
| Geographic Expansion | Enhanced Nurse Licensure Compact coverage across forty-one states enables staff deployment without redundant credentialing. |
Research Methodology
Independent corroboration across pediatric home health agency executives, state Medicaid waiver program administrators, children's hospital discharge planners, and biomedical equipment procurement managers underwrites the qualitative findings. Secondary validation draws from FDA 510(k) clearance databases, CMS Medicare cost report filings, state nursing licensure compact administrative records, and hospital procurement database extracts. Bottom-up nursing hour authorization analysis triangulates against top-down Medicaid expenditure trend modeling.
Rate-of-change decomposition across service type, technology adoption maturity, care setting acuity, and geographic regulatory cluster shapes the analytical framework throughout the forecast period. Segmentation dimensions modeled include skilled nursing versus therapy service mix, telehealth platform deployment status, transitional care eligibility expansion, and state-level HCBS waiver generosity indices. CAGRs derive from nursing workforce supply projections cross-referenced with pediatric chronic disease prevalence trajectories and remote monitoring reimbursement code expansion schedules.
Caveats apply where state budget cycles triggering Medicaid rate freezes, FDA pediatric device review pathway revisions, or HIPAA technical safeguard updates could materially shift the outlook. Forecasts embed assumptions regarding nursing licensure compact expansion continuity and CMS value-based purchasing model evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Pediatric MRI Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Growth Hormone Deficiency Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Global Pediatric Clinical Trials Market