
 OTC Pediatric Healthcare Market | 2026-2036
OTC Pediatric Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
OTC Pediatric Healthcare Market Analytics
North American contract manufacturing of pediatric syrups is shifting toward specialized facilities with dedicated allergen-free lines. Johnson & Johnson leverages its heritage brand equity to sustain shelf presence across mass retail and pharmacy channels. GlaxoSmithKline competes through pharmacist-directed recommendation programs that anchor professional trust in cold and cough formulations.
OTC pediatric healthcare encompasses non-prescription therapeutic and preventive products formulated specifically for infants and children, typically involving weight-calibrated dosing mechanisms, palatability-enhancing excipients, and child-resistant packaging that meets poison prevention standards. These products serve to treat common acute conditions and support nutritional supplementation without requiring physician prescription. Pain relief and cold & cough categories occupy established volume positions, while gummy formulations represent the fastest-growing delivery format as palatability-driven compliance improves dosing adherence. Nutritional therapy areas command premium positioning as parental willingness to invest in preventive micronutrient supplementation expands.
The FDA monograph system governs active ingredient selection and labeling claims for U.S. pediatric OTC products, while the EMA's pediatric investigation plans influence formulation development timelines for European market entry. China's NMPA maintains distinct registration pathways for imported versus domestically manufactured pediatric health products, creating tiered market access conditions. Stakeholders must monitor evolving monograph updates and regional pharmacovigilance requirements to anticipate reformulation obligations and competitive repositioning needs.
Market Dynamics
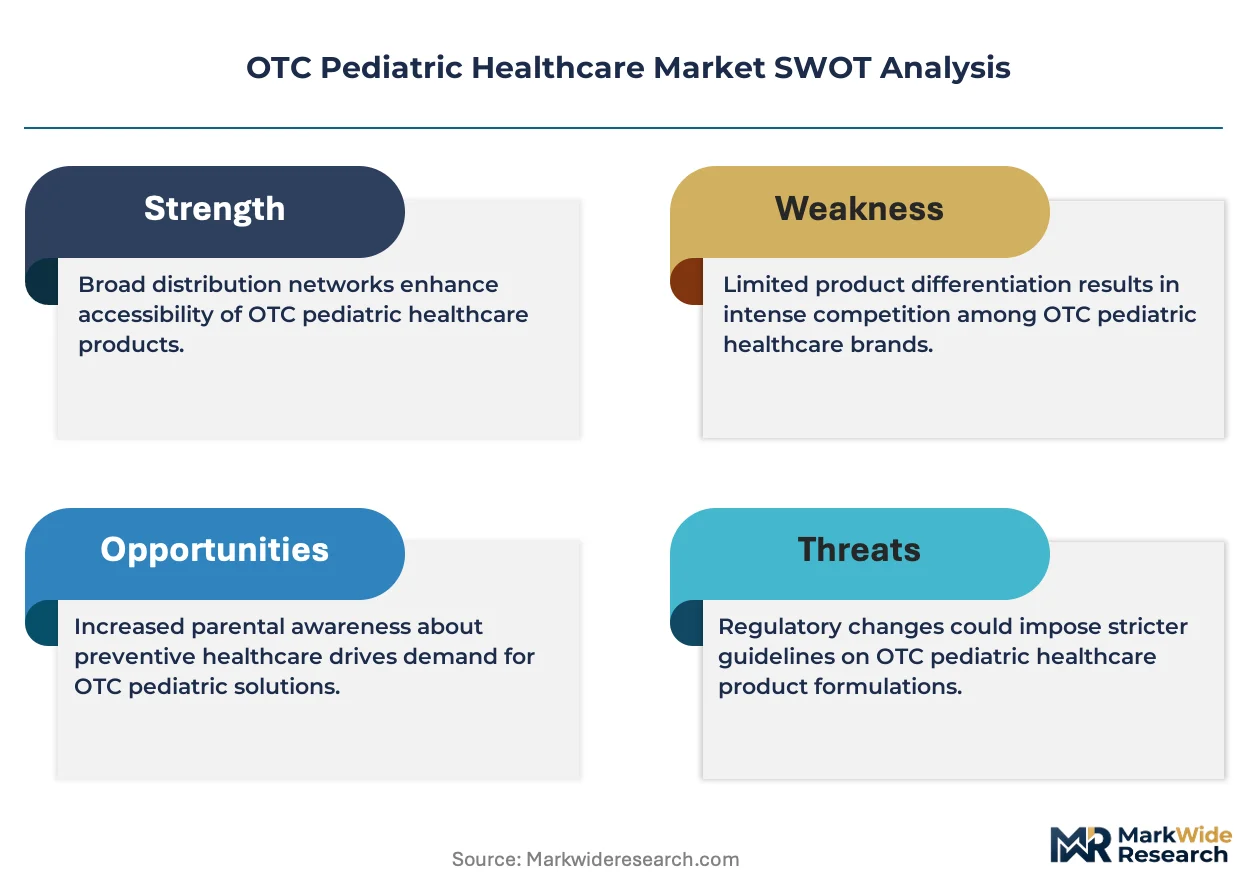
Parental preference for pharmacy-grade pediatric formulations is compressing demand toward clinically validated SKUs, forcing manufacturers to abandon legacy generalist positioning and invest in specialized production infrastructure.
Growth Catalysts
- FDA Monograph Alignment:The FDA's active ingredient monograph system provides clear formulation pathways, reducing regulatory uncertainty for U.S. market entrants and accelerating product development cycles.
- Retail Pharmacy Channel Dominance:Parents purchasing through pharmacy channels demonstrate higher compliance with weight-calibrated dosing protocols, creating pull-through for precision-formulated products.
- Gummy Format Technology:Palatability-enhancing excipient systems in chewable formats improve dosing adherence among toddlers, expanding addressable age brackets.
Market Restraints
- API Supply Concentration:Dependence on Chinese acetaminophen and ibuprofen active pharmaceutical ingredient suppliers creates input cost volatility and geopolitical exposure.
- EMA Pediatric Investigation Timelines:The European Medicines Agency's pediatric investigation plan requirements extend European market entry timelines by 18-24 months versus U.S. pathways.
- Substitution by Preventive Nutrition:Micronutrient supplementation regimens reduce incidence of deficiency-related conditions, compressing demand for acute therapeutic SKUs.
Strategic Opportunities
- Underpenetrated Chinese Tier-2 Cities:The NMPA's distinct registration pathway for domestically manufactured products enables faster market access in provincial urban centers outside Beijing and Shanghai.
- Pharmacist-Directed Recommendation Programs:Professional trust anchoring in German Apotheken channels creates white space for evidence-backed cold and cough formulations.
- Dual Carbon Alignment in China:NMPA and MEE coordination on green manufacturing standards offers regulatory tailwind for facilities adopting renewable energy in production.
Industry Challenges
- Allergen-Free Line Segregation:Dedicated production infrastructure for allergen-excluded pediatric syrups requires capital-intensive facility reconfiguration and extended validation timelines.
- Child-Resistant Packaging Certification:Poison Prevention Packaging Act compliance testing creates bottlenecks, with third-party certification backlogs extending launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OTC Pediatric Healthcare Market |
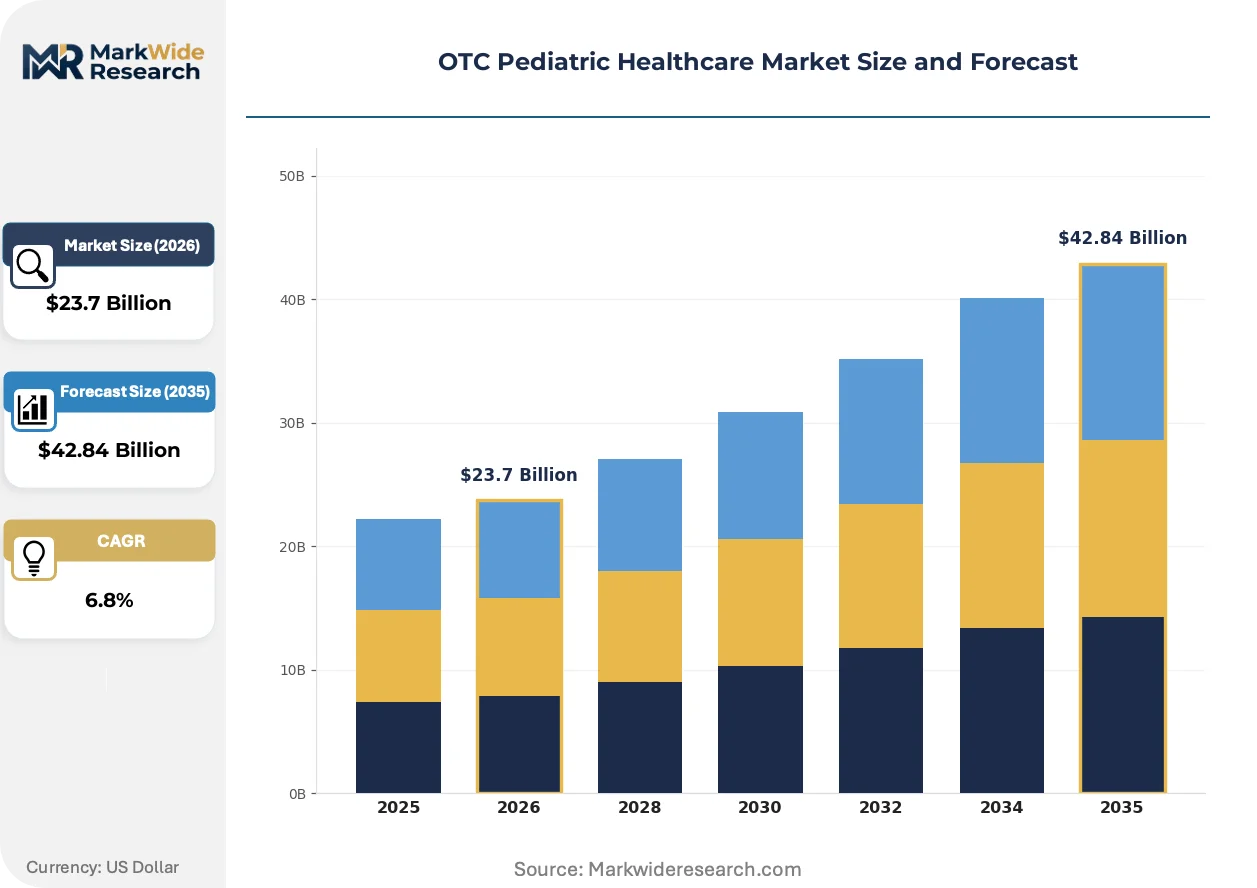
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relief, Cold & Cough, Digestive Health, Allergy Relief Form: Syrup, Gummies, Tablets, Lozenges End User: Parents, Pediatricians, Pharmacies, Hospitals Therapy Area: Respiratory, Gastrointestinal, Dermatological, Nutritional |
| Companies Covered | Johnson & Johnson, Procter & Gamble, GlaxoSmithKline, Bayer, Pfizer, Sanofi, Abbott Laboratories, Reckitt Benckiser Group, Amway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OTC Pediatric Healthcare Market Evolving Landscape
Precision dosing technologies and regulatory harmonization pressures are compressing competitive differentiation toward manufacturing quality and professional channel access rather than marketing expenditure.
Micro-dosing pump systems for liquid pediatric formulations is unifying weight-calibrated delivery with parent usability requirements. Pharmacy chains in Germany and the United States are adopting these devices at accelerating rates. The technology is unifying previously separate accuracy and convenience value propositions into single-SKU solutions.
REACH compliance alignment across EU member states is forcing reformulation of excipient portfolios, particularly for artificial coloring agents. Manufacturers serving European markets are removing azo dyes from pediatric liquid formulations ahead of regulatory deadlines. Cold and cough categories face the most immediate portfolio restructuring requirements.
Subscription-based replenishment models for chronic pediatric nutritional therapy are displacing episodic retail purchasing. Direct-to-parent digital platforms in the United States are capturing micronutrient category volume previously routed through mass retail. This channel shift is most visible in premium-positioned DHA and vitamin D segments.
OTC Pediatric Healthcare Market Segmentation
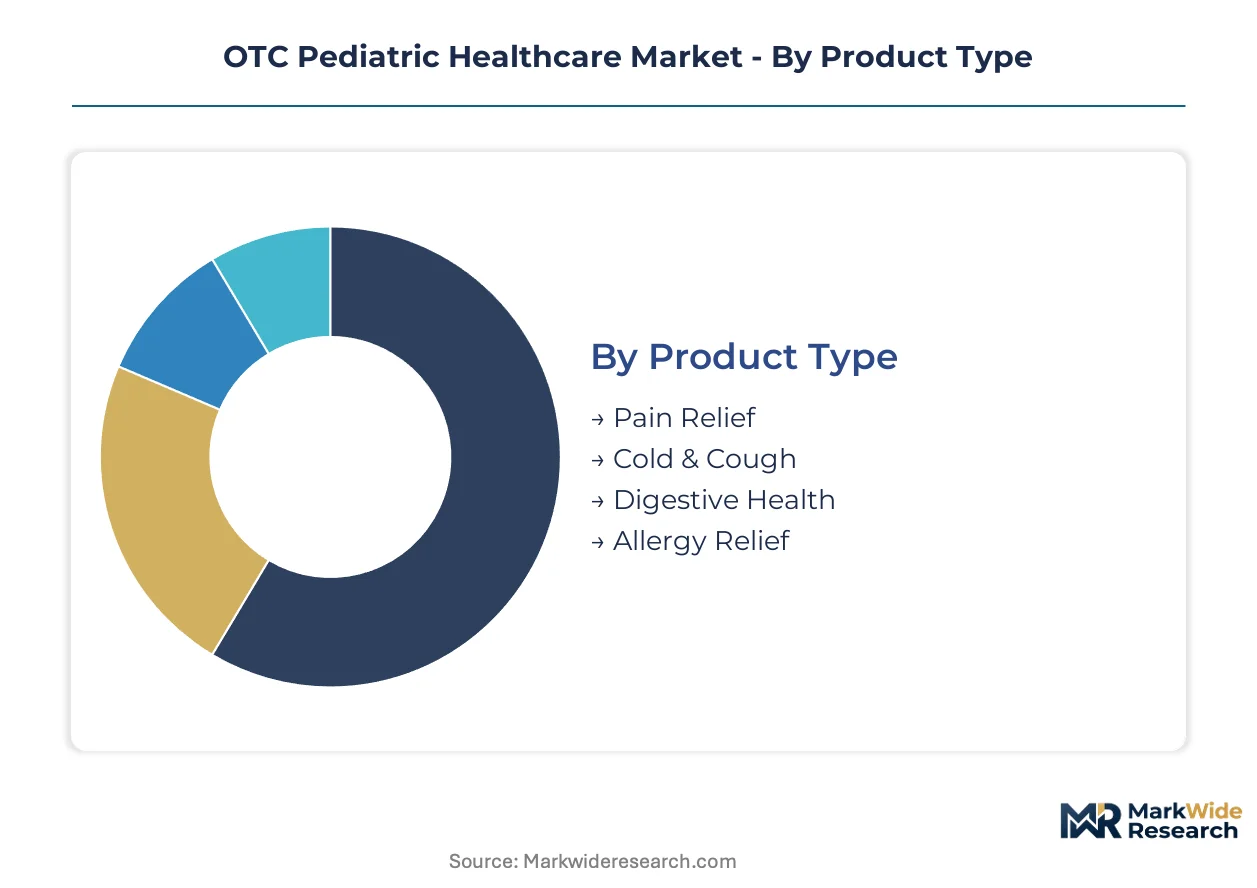
Pediatric OTC formulations demand precise technical alignment between delivery mechanism, age-appropriate dosing, and regulatory pathway. Segmentation reveals where manufacturing complexity concentrates and which specification tiers command channel access.
Product Type:
Active ingredient selection and monograph compliance requirements differentiate therapeutic categories by regulatory burden and production infrastructure needs.
- Pain Relief:Acetaminophen and ibuprofen suspensions dominate volume through pharmacy channels, with weight-calibrated dosing systems now standard. Parents purchasing through retail pharmacy demonstrate higher adherence to precision dosing protocols than mass retail buyers.
- Cold & Cough:Multi-symptom formulations face EMA pediatric investigation plan delays extending European entry timelines. German Apotheken channels anchor professional recommendation programs for this category.
- Digestive Health:Probiotic and anti-gas formulations serve acute discomfort episodes with shorter purchase cycles than preventive nutrition.
- Allergy Relief:Second-generation antihistamine liquids compete on palatability and non-drowsy claims for seasonal pediatric use.
Pain Relief leads on scale; Cold & Cough leads on momentum.
Form:
Delivery format selection determines excipient complexity, stability testing requirements, and age-bracket addressability.
- Syrup:Liquid suspensions remain the default for infants under 24 months, requiring child-resistant packaging certification under Poison Prevention Packaging Act standards. Third-party certification backlogs currently extend launch schedules for new syrup introductions.
- Gummies:Palatability-enhancing gelatin and pectin matrices expand dosing adherence among toddlers and school-age children. This format is climbing the fastest as parental preference shifts toward compliance-driven delivery systems.
- Tablets:Chewable and dispersible formats serve children aged 6-12 with established swallowing capability.
- Lozenges:Throat-soothing formulations occupy niche positioning for older children with choking-risk mitigation requirements.
Syrup leads on scale; Gummies leads on momentum.
End User:
Purchasing authority and professional influence create distinct channel requirements and recommendation dynamics.
- Parents:Direct purchasers drive 70%+ of volume through retail pharmacy and mass retail channels, with digital subscription platforms capturing chronic nutritional therapy replenishment.
- Pediatricians:Professional guidance influences initial product selection for first-time parents, creating brand loyalty anchors.
- Pharmacies:German Apotheken and US retail pharmacy chains operate pharmacist-directed recommendation programs that professionalize cold and cough purchases.
- Hospitals:Discharge prescription-to-OTC conversion protocols create initial exposure for specific brands in acute care settings.
Parents leads on scale; Pharmacies leads on momentum.
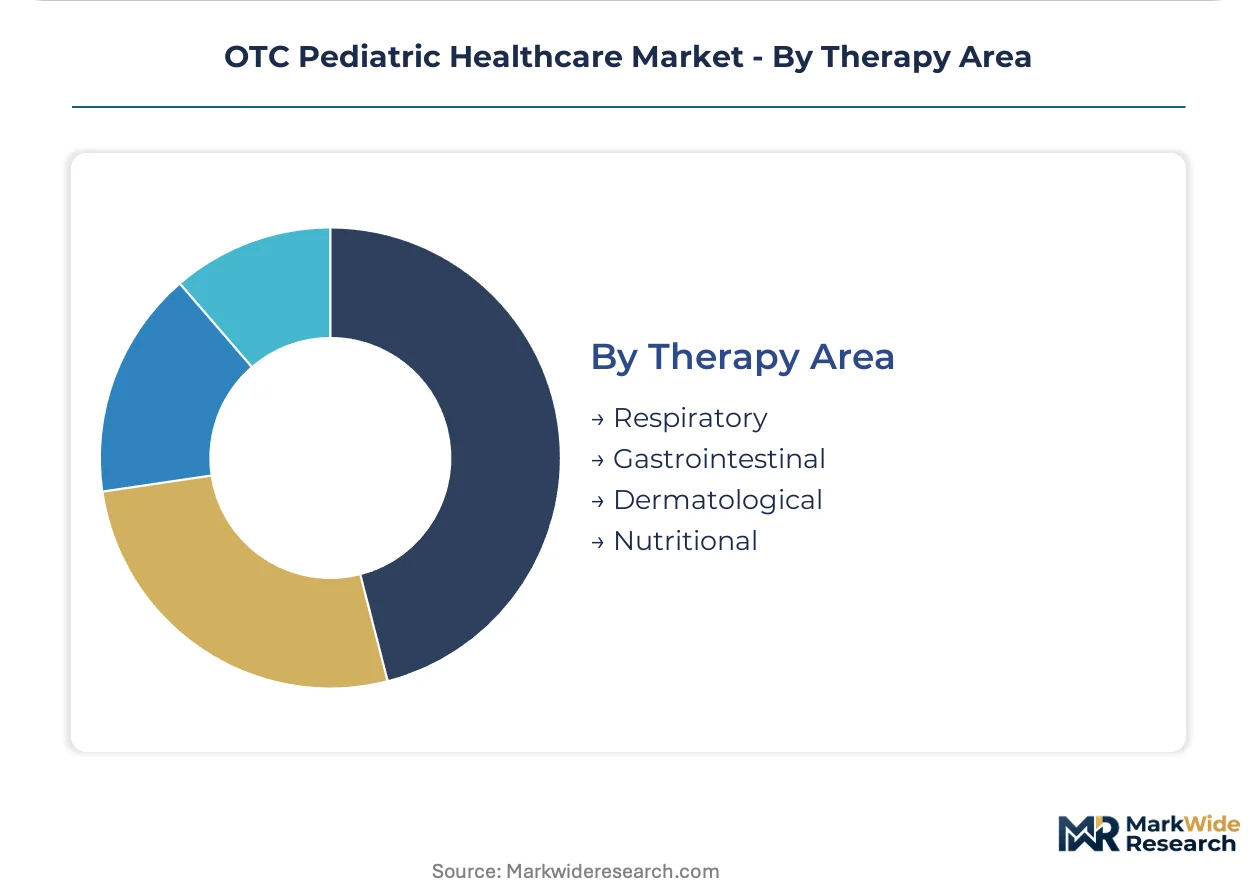
Therapy Area:
Condition prevalence and preventive versus acute treatment orientation shape SKU lifecycle and margin structure.
- Respiratory:Cold, cough, and allergy formulations face seasonal demand fluctuation and EMA reformulation pressures on excipient portfolios.
- Gastrointestinal:Anti-nausea and anti-diarrheal suspensions serve acute episodes with limited preventive substitution threat.
- Dermatological:Topical anti-itch and anti-fungal products compete with prescription alternatives for eczema and diaper rash management.
- Nutritional:DHA, vitamin D, and multivitamin gummies command premium positioning as parental investment in preventive micronutrient supplementation expands.
Respiratory leads on scale; Nutritional leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge sharply in channel dynamics, with German Apotheken anchoring professional recommendation programs while US retail pharmacy chains drive volume through mass accessibility. China concentrates manufacturing capacity for active pharmaceutical ingredients. Regulatory fragmentation across these three markets shapes divergent entry timelines and compliance burdens.
United States
Parents purchasing through CVS, Walgreens, and independent pharmacy channels demonstrate higher adherence to weight-calibrated dosing protocols than mass retail buyers. The FDA monograph system provides clear formulation pathways for acetaminophen and ibuprofen suspensions, reducing regulatory uncertainty for domestic entrants. Johnson & Johnson leverages heritage brand equity to sustain shelf presence across these channels, particularly in pain relief categories.
Germany
Professional trust anchoring in Apotheken channels creates distinct competitive dynamics for cold and cough formulations, with pharmacist-directed recommendation programs filtering product selection. EMA pediatric investigation plan requirements extend market entry timelines by 18-24 months versus US pathways, compressing first-mover advantages. Bavaria and North Rhine-Westphalia host concentrated distribution infrastructure serving these pharmacy networks.
China
Tier-2 cities outside Beijing and Shanghai present underpenetrated expansion opportunities as provincial urban centers build retail pharmacy capacity. The NMPA maintains distinct registration pathways for domestically manufactured versus imported pediatric health products, creating tiered access conditions. Yangtze River Delta manufacturing clusters supply acetaminophen and ibuprofen APIs to global formulators, concentrating input cost exposure.
United Kingdom
Boots and Superdrug pharmacy chains anchor OTC pediatric distribution, with digital subscription platforms capturing micronutrient replenishment volume previously routed through mass retail. MHRA alignment with EMA pediatric investigation frameworks extends formulation development timelines for European market entry. London and Southeast England concentrate headquarters operations for multinational players serving this regulatory zone.
India
Domestic manufacturers exploit cost advantages in syrup and suspension production for export to African and Southeast Asian markets. CDSCO registration requirements for imported pediatric formulations create protected conditions for local players in the domestic market. Maharashtra and Gujarat host concentrated pharmaceutical manufacturing clusters with dedicated liquid formulation capabilities.
OTC Pediatric Healthcare Market Competitive Landscape
United States producers anchor one tier through heritage brand equity and pharmacy channel dominance; European specialists hold another through EMA-aligned formulation capabilities and professional recommendation programs. The vendor base stratifies across three tiers: multinational conglomerates with diversified healthcare portfolios, mid-cap pharmaceutical specialists with concentrated pediatric focus, and regional generic manufacturers serving price-sensitive markets. Two dominant competitive moves are reshaping positioning: pharmacist-directed professional trust programs in European markets, and subscription-based direct-to-parent digital platforms displacing episodic retail purchasing in nutritional therapy categories.
Within the heritage-brand tier, Johnson & Johnson and Procter & Gamble occupy positions sustained by decades of parental recognition and pharmacy channel penetration. GlaxoSmithKline exemplifies the European specialist archetype, with positioning anchored in professional recommendation programs rather than consumer marketing expenditure. These three entities represent contrasting geographic and strategic orientations: US-based conglomerate diversification, US-based consumer health scale, and UK-based pharmaceutical professionalization.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Procter & Gamble |
| GlaxoSmithKline |
| Bayer |
| Pfizer |
| Sanofi |
| Abbott Laboratories |
| Reckitt Benckiser Group |
| Amway |
| Others |
Value Network & Pricing Analysis
Acetaminophen API spot price volatility in the Yangtze River Delta cascades through formulation tiers, compressing margins on standard pediatric suspensions while premium gummy formats absorb input fluctuations through palatability-driven price inelasticity among parent purchasers.
Pricing Analysis
Pharmacy chain markup layers stratify pediatric OTC pricing across three tiers: mass retail economy positioning, pharmacy-grade standard formulations, and direct-to-parent subscription premiums. Price differentiation hinges on FDA monograph compliance certification and weight-calibrated dosing technology integration. Cost compression in standard suspensions intensifies as API supply concentration erodes bargaining leverage. Mass retail parents exhibit highest price sensitivity; subscription-platform purchasers in nutritional therapy segments demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese acetaminophen and ibuprofen API manufacturers concentrated in Jiangsu and Zhejiang provinces. Raw material dependencies encompass gelatin matrices for gummy formats, pectin alternatives for allergen-free lines, and child-resistant packaging resins subject to petroleum price swings. Tariff exposure on imported excipients into the United States and European Union compounds logistics chokepoint risks at Shanghai and Ningbo ports. Distribution runs through pharmacy wholesale networks in Germany and the United States, with direct-to-parent platforms capturing replenishment volume in nutritional categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The OTC pediatric healthcare market functions as a geographic-arbitrage play: EMA pediatric investigation timelines extend European entry by 18-24 months versus FDA pathways, creating cost-of-capital differentials that reward U.S.-first formulation strategies.
For Market Incumbents: Anticipate substitution pressure from preventive micronutrient regimens compressing acute therapeutic SKU demand. Johnson & Johnson and GlaxoSmithKline should deepen backward integration into allergen-free syrup production infrastructure to defend pharmacy channel positioning against mid-cap specialists. Certification investment in REACH-aligned excipient portfolios anchors European market access against reformulation deadlines. For New Entrants and Emerging Players: NMPA's distinct registration pathway for domestically manufactured products in China opens a window for provincial tier-2 city penetration ahead of multinational import timelines. White-space targets include pharmacist-directed recommendation programs in German Apotheken and subscription-based DHA replenishment platforms in the United States. A go-to-market angle anchored in dual-carbon-aligned green manufacturing credentials secures regulatory tailwind with China's MEE coordination. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap pharmaceutical specialists possessing concentrated pediatric focus and EMA-aligned formulation capabilities. Long-term viability over the 5-10 year window favors acquisition targets with dedicated allergen-free production lines and established pharmacy channel relationships. The signal to watch is NMPA registration backlog clearance rates as inflection indicator for Chinese market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Allergen-Free Line Segregation | Dedicated production infrastructure meets poison prevention standards and captures pharmacy-grade premium positioning. |
| Pharmacist-Directed Recommendation Programs | Professional trust anchoring in German Apotheken channels filters product selection and sustains margin premiums. |
| Subscription-Based Replenishment Models | Direct-to-parent digital platforms capture micronutrient volume previously routed through mass retail pharmacy chains. |
| REACH Compliance Alignment | Reformulation of excipient portfolios ahead of ECHA deadlines secures European market continuity for liquid formulations. |
| Micro-Dosing Pump Technology Integration | Weight-calibrated delivery systems unify accuracy and convenience value propositions into single-SKU solutions for pharmacy chains. |
Research Methodology
Direct dialogue with regulatory affairs leads at pediatric formulation manufacturers, pharmacy procurement managers at CVS and Walgreens, and formulary directors at German Apotheken associations grounded qualitative insights. Secondary validation drew from FDA monograph filings, EMA pediatric investigation plan submissions, NMPA registration databases, and pharmacy retail audit data. Bottom-up SKU-level volume modeling and top-down macroeconomic triangulation converged on segment-level estimates.
Bottom-up demand modeling tracked product type, delivery form, and therapy area dimensions across the analysis window, while top-down macroeconomic calibration anchored aggregate market boundaries. CAGRs derived from regression against pediatric population cohorts, pharmacy channel penetration rates, and parent purchasing pattern shifts. Forecast inputs incorporated API price index trajectories and regulatory timeline differentials between FDA, EMA, and NMPA pathways.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained API supply disruption or accelerated preventive nutrition substitution. Forecasts reflect documented assumptions regarding monograph update schedules and channel migration velocities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Pediatric Dental Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Pediatric MRI Market
Pediatrics
Pediatric Catheter Market