
 Global Cerebral Palsy Treatment Market | 2026-2036
Global Cerebral Palsy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cerebral Palsy Treatment Market Foresight
North American neurotoxin manufacturing capacity is realigning toward higher-purity botulinum toxin formulations for movement disorders. Ipsen Biopharmaceuticals Inc. leverages its established toxinology platform to sustain leadership in spasticity indications. AbbVie Inc. anchors its position through integrated neurology portfolios spanning oral and injectable therapies. Merz GmbH & Co. KGaA differentiates via specialized dosing protocols refined for pediatric cerebral palsy populations.
Cerebral Palsy Treatment encompasses multidisciplinary interventions targeting motor dysfunction, spasticity, and associated comorbidities arising from non-progressive brain lesions acquired in early development, with botulinum toxin injections constituting the primary pharmacologic intervention requiring precise unit-based dosing calibrated to muscle volume and functional goals. The therapeutic objective centers on improving gait mechanics, reducing contracture risk, and enabling participation in structured rehabilitation programs across ambulatory and non-ambulatory patient strata. Medication segments for spasticity management command concentrated margin pools due to chronic administration requirements and limited generic substitution for complex biologics. Telehealth Services within delivery mode represent the fastest-expanding channel as remote monitoring platforms integrate with wearable motion sensors for therapy compliance tracking.
FDA orphan drug designations and EMA pediatric investigation plans shape clinical trial investment patterns by extending exclusivity protections and mandating age-appropriate formulation development. WHO rehabilitation 2030 initiative standards influence national procurement criteria for assistive devices and therapy equipment in low-resource settings. Stakeholders must monitor evolving CMS coverage determinations for intrathecal baclofen pumps and selective dorsal rhizotomy procedures as these shape referral patterns between surgical and pharmaceutical interventions.
Market Dynamics
Botulinum toxin manufacturing is consolidating around higher-purity formulations as FDA orphan drug incentives compress development timelines for pediatric spasticity indications. Pediatric clinics are expanding dedicated service lines for movement disorder management, creating concentrated demand pull for specialized dosing protocols.
Growth Catalysts
- Orphan Drug Incentives:FDA exclusivity extensions for neurotoxin development accelerate clinical trial investment in pediatric cerebral palsy populations. This regulatory framework reduces commercialization risk for complex biologics targeting small patient cohorts.
- Bundled Payment Reforms:United States Medicare reimbursement restructuring for chronic neurological conditions creates financial alignment between hospitals and long-term spasticity management programs.
- Telehealth Integration:Remote monitoring platforms incorporating wearable motion sensors are expanding therapy compliance tracking capabilities across ambulatory and non-ambulatory patient strata.
Market Restraints
- Biologic Manufacturing Concentration:Limited contract manufacturing organizations possess validated capacity for botulinum toxin production, creating supply vulnerability concentrated in North American and European facilities.
- Intrathecal Pump Substitution:Surgical interventions including baclofen pumps and selective dorsal rhizotomy compete for referral volume in severe spasticity cases, particularly where CMS coverage determinations favor procedural reimbursement.
- EMA Pediatric Investigation Requirements:Mandatory age-appropriate formulation development adds regulatory friction and extends timelines for market entry in European jurisdictions.
Strategic Opportunities
- Low-Resource Settings:WHO Rehabilitation 2030 initiative standards are opening procurement pathways for assistive devices and therapy equipment in African and Southeast Asian markets previously underserved by specialized spasticity care.
- Motion Sensor Convergence:Integration of wearable kinematic sensors with injection planning software is creating precision dosing capabilities calibrated to real-time gait mechanics data.
- Unit-Based Dosing Specialization:Development of muscle-volume-calibrated injection protocols for pediatric populations represents unmet need in markets where adult-derived dosing guidelines dominate clinical practice.
Industry Challenges
- Pediatric Toxinology Expertise Gap:Shortage of clinicians trained in child-specific neurotoxin dosing and functional goal-setting limits service line expansion in community hospital settings.
- Reimbursement Documentation Burden:CMS prior authorization requirements for repeat injection cycles create administrative friction that compresses clinic throughput and extends patient wait times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cerebral Palsy Treatment Market |
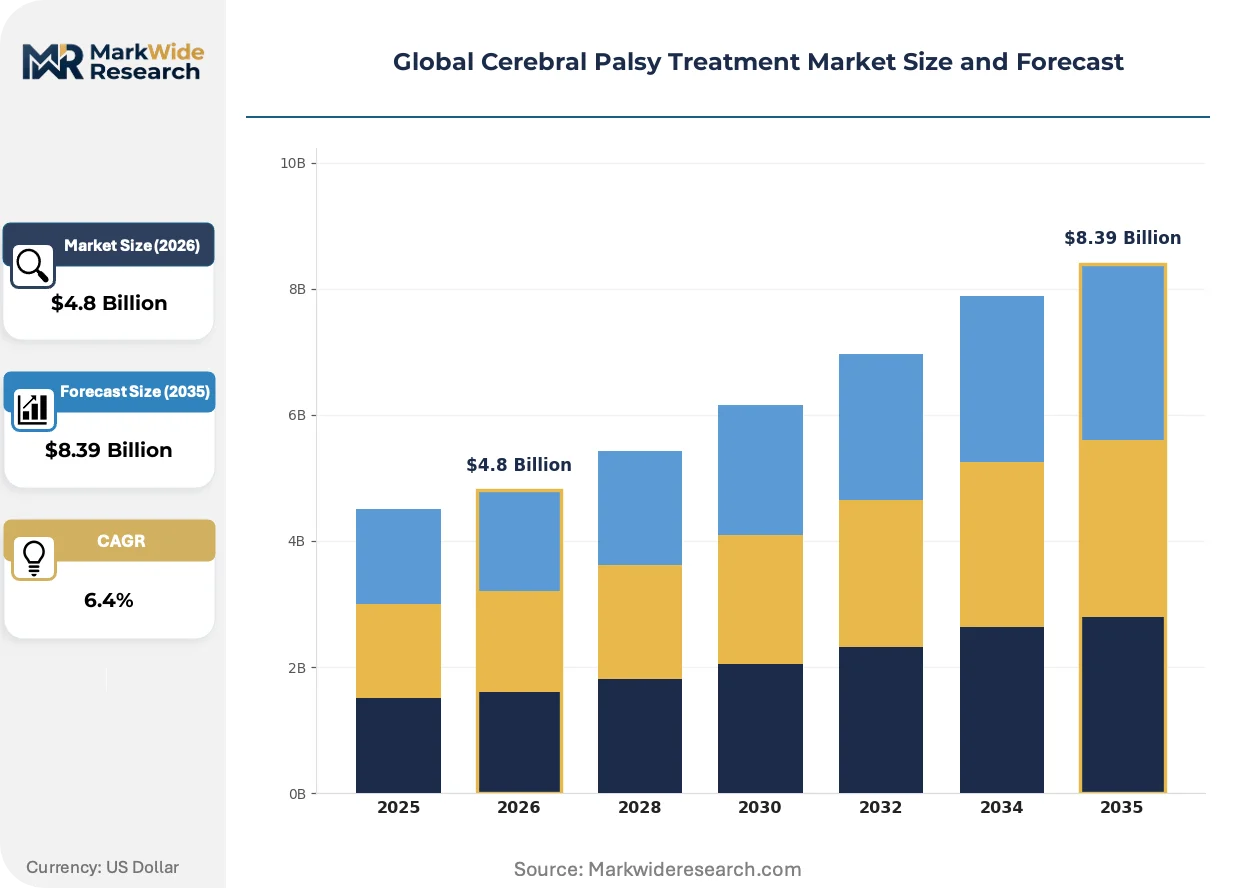
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Physical Therapy, Occupational Therapy, Speech Therapy, Medication, Surgical Intervention Application Area: Motor Function Improvement, Spasticity Management, Seizure Control, Pain Relief, Postural Correction End User: Rehabilitation Centers, Pediatric Clinics, Neurology Institutes, Special Education Schools, Home Care Providers Delivery Mode: Inpatient Therapy, Outpatient Therapy, Home-based Care, Telehealth Services, Community Programs |
| Companies Covered | Ipsen Biopharmaceuticals Inc., AbbVie Inc., Merz GmbH & Co. KGaA, Teva Pharmaceutical Industries Ltd., Supernus Pharmaceuticals, Inc., Neurocrine Biosciences, Inc., Pfizer Inc., Revance, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cerebral Palsy Treatment Market Shifts & Advancements
Motion capture technology is penetrating clinical workflows at accelerating velocity, reshaping how spasticity interventions are planned, delivered, and measured across rehabilitation settings.
Computer-assisted injection guidance systems incorporating ultrasound visualization and electromyographic feedback are automating needle placement accuracy in complex muscle groups. Pediatric movement disorder centers in the United States and Germany are deploying these platforms to reduce variability in toxin delivery. This automation is compressing the learning curve for new clinicians while standardizing functional outcomes across high-volume and low-volume treatment sites.
EMA pediatric investigation plans now mandate development of age-appropriate formulations as a condition of market authorization, forcing reformulation investment for existing neurotoxin products. Manufacturers must generate pharmacokinetic data in juvenile populations that differs substantially from adult reference ranges. European markets are responding with delayed generic entry timelines and extended data exclusivity provisions that protect innovator investment in pediatric-specific clinical programs.
Caregivers are demanding unbundled therapy services that separate injection procedures from mandatory bundled rehabilitation packages. United States pediatric clinics are disaggregating botulinum toxin administration from physical therapy blocks, allowing families to select preferred rehabilitation providers. This behavioral shift is fragmenting referral networks and forcing hospital systems to compete on injection pricing transparency rather than captive therapy bundling.
Global Cerebral Palsy Treatment Market Segmentation
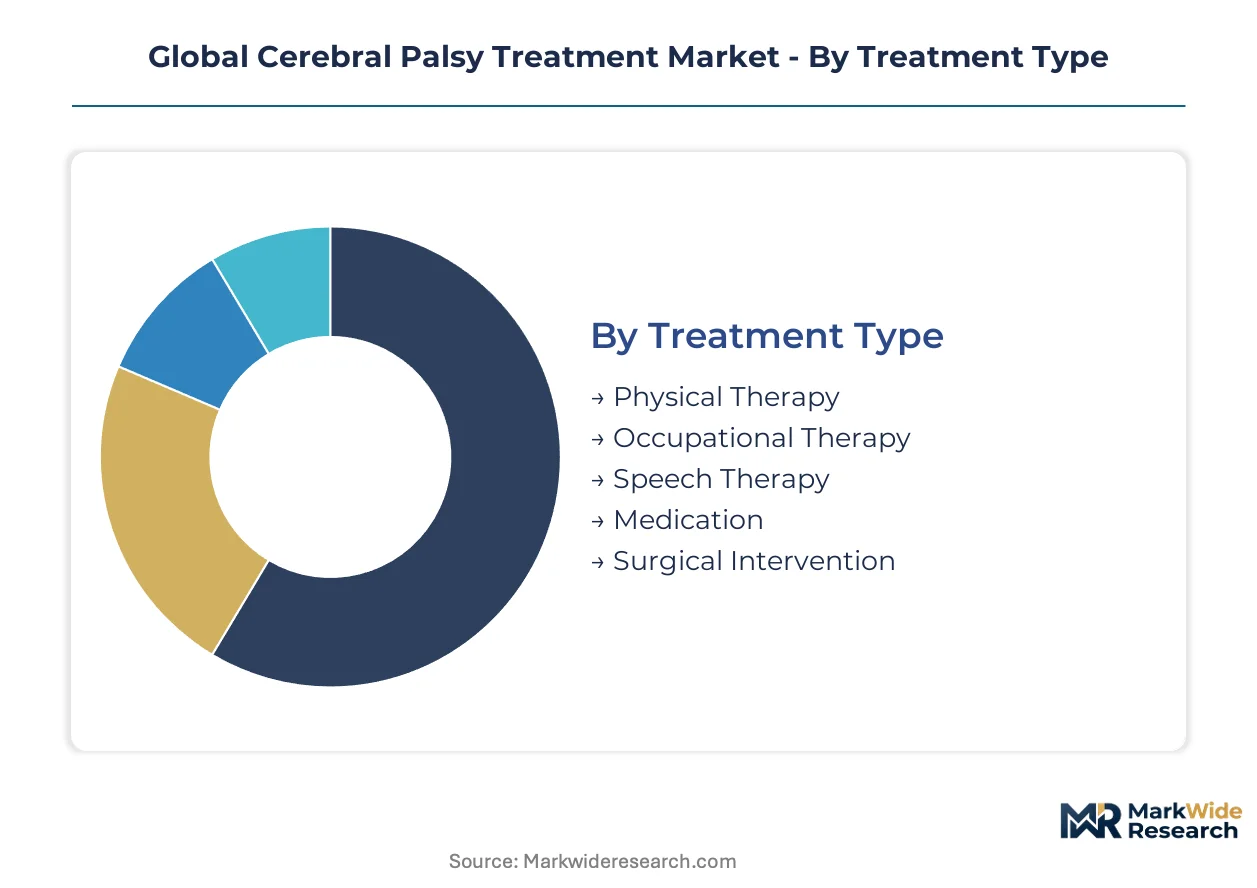
Treatment modality selection in cerebral palsy care hinges on functional goal specificity rather than diagnosis alone. Segmentation reveals how reimbursement structures and care setting capabilities reshape patient flows across intervention types.
Treatment Type:
Clinicians prioritize interventions based on spasticity severity, functional impairment level, and prior response to conservative measures.
- Medication:Pharmacologic management centers on botulinum toxin injections and oral spasticity agents requiring precise unit-based dosing calibrated to muscle volume. Demand concentrates in pediatric clinics managing ambulatory patients with focal spasticity patterns, driven by CMS reimbursement alignment for chronic neurological conditions.
- Physical Therapy:Structured rehabilitation programs targeting gait mechanics and contracture prevention constitute the foundational intervention across all severity strata. Rehabilitation centers in the United States and Germany are expanding dedicated service lines for movement disorder management, creating concentrated demand pull for specialized protocols.
- Occupational Therapy:Fine motor skill development and adaptive equipment training for daily living activities.
- Speech Therapy:Communication enhancement and dysphagia management for oromotor dysfunction.
- Surgical Intervention:Selective dorsal rhizotomy and orthopedic procedures for severe, non-responsive spasticity.
Volume sits with Physical Therapy; growth tilts toward Medication.
Application Area:
Functional outcome targets determine resource allocation across multidisciplinary care teams.
- Spasticity Management:Pharmacologic and interventional approaches targeting hypertonia reduction to enable participation in rehabilitation programs. Pediatric movement disorder centers in the United States are deploying computer-assisted injection guidance systems to standardize outcomes across high-volume and low-volume treatment sites.
- Motor Function Improvement:Gait training, balance intervention, and strength conditioning for mobility optimization. Demand concentrates in rehabilitation centers integrating wearable motion sensors for therapy compliance tracking, driven by telehealth platform expansion.
- Seizure Control:Antiepileptic medication management for comorbid seizure disorders.
- Pain Relief:Musculoskeletal and neuropathic pain interventions secondary to spasticity and contracture.
- Postural Correction:Seating systems, bracing, and surgical alignment for scoliosis and hip displacement prevention.
Spasticity Management captures the dominant share; Motor Function Improvement is climbing the fastest.
End User:
Care setting selection reflects patient acuity, equipment requirements, and reimbursement pathway optimization.
- Pediatric Clinics:Dedicated service lines for child-specific neurotoxin dosing and functional goal-setting. Clinics in the United States are disaggregating botulinum toxin administration from mandatory therapy bundles, allowing families to select preferred rehabilitation providers.
- Rehabilitation Centers:Comprehensive spasticity management with integrated therapy and equipment services. WHO Rehabilitation 2030 initiative standards are opening procurement pathways for assistive devices in African and Southeast Asian markets previously underserved by specialized care.
- Neurology Institutes:Academic medical centers with intrathecal pump and surgical intervention capabilities.
- Special Education Schools:Therapy integration within educational settings for school-age populations.
- Home Care Providers:Community-based therapy and caregiver training for non-ambulatory patients.
Rehabilitation Centers anchor volume; Pediatric Clinics are gaining share fastest.
Delivery Mode:
Access convenience and reimbursement documentation burden shape patient and caregiver channel preferences.
- Telehealth Services:Remote monitoring platforms incorporating wearable kinematic sensors for therapy compliance tracking and injection follow-up. United States pediatric clinics are deploying these platforms to reduce administrative friction from CMS prior authorization requirements.
- Outpatient Therapy:Scheduled clinic visits for injection cycles and structured rehabilitation sessions. Demand concentrates in community hospital settings where CMS bundled payment reforms for chronic neurological conditions create financial alignment.
- Inpatient Therapy:Acute rehabilitation and post-surgical recovery in hospital-based settings.
- Home-based Care:Direct therapy services and caregiver training in residential environments.
- Community Programs:Group-based interventions and peer support integration.
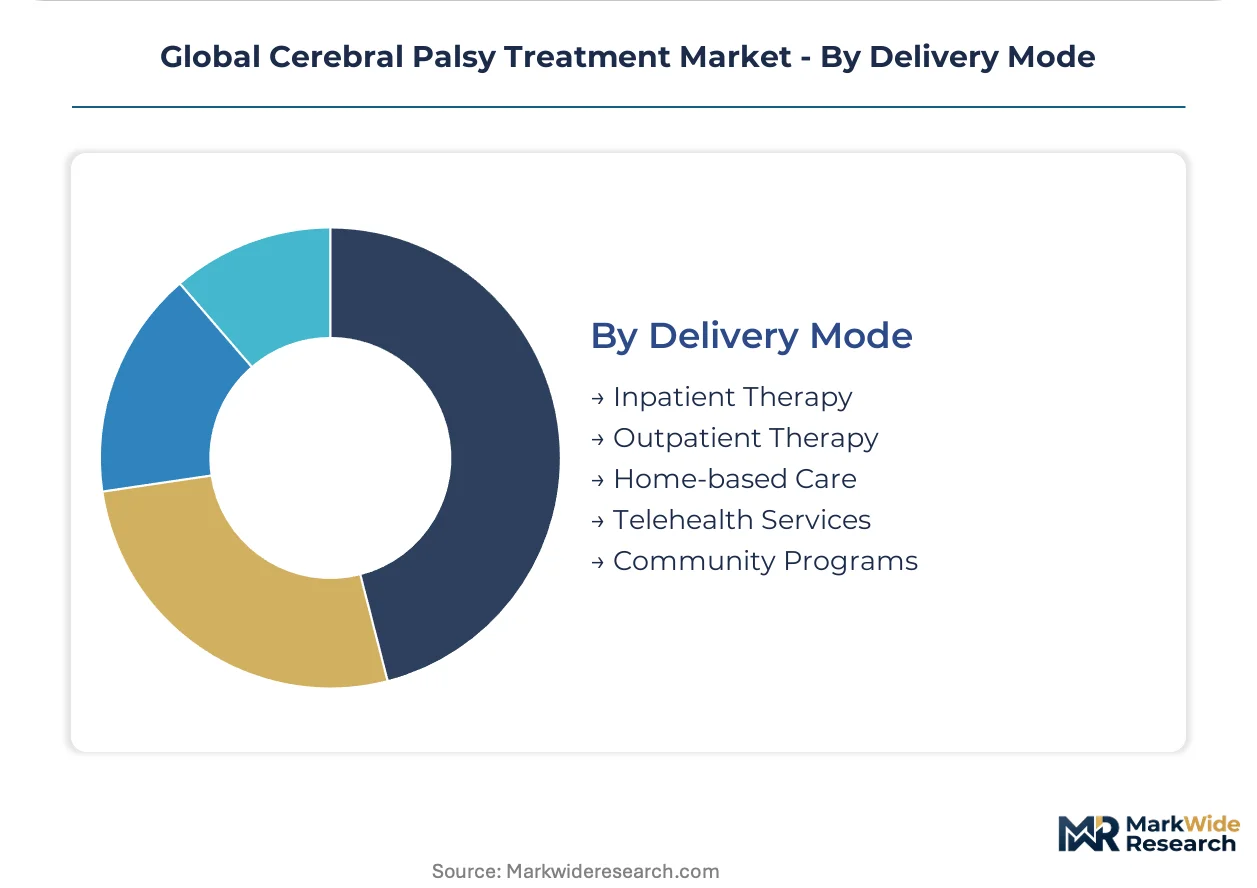
Outpatient Therapy maintains volume leadership; Telehealth Services show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Botulinum toxin manufacturing feedstock concentrates in North American and European fermentation facilities, with clinical demand patterns diverging sharply by reimbursement infrastructure and pediatric neurology specialist density.
United States
Pediatric movement disorder centers in Philadelphia and Boston drive concentrated neurotoxin utilization for spasticity management, with CMS bundled payment reforms creating financial alignment between hospitals and chronic care programs. FDA orphan drug incentives compress development timelines for pediatric-specific formulations. The Southeast corridor from Atlanta to Florida anchors expanding service lines as community hospitals recruit toxinology-trained clinicians.
Germany
EMA pediatric investigation plans mandate age-appropriate formulation development as a condition of market authorization, extending data exclusivity for innovators investing in juvenile pharmacokinetic studies. Heidelberg and Munich host academic medical centers deploying computer-assisted injection guidance systems. Baden-Württemberg manufacturing clusters supply higher-purity toxin formulations to European and export markets.
Japan
PMDA accelerated approval pathways for pediatric rare diseases align with global orphan drug frameworks, though domestic clinical trial requirements add regulatory friction. Tokyo and Osaka metropolitan areas concentrate pediatric rehabilitation infrastructure with integrated motion sensor platforms. METI industrial policy supports domestic fermentation capacity for biologic active pharmaceutical ingredients.
United Kingdom
NICE technology appraisals for intrathecal baclofen pumps and selective dorsal rhizotomy shape referral patterns between surgical and pharmaceutical interventions across NHS trusts. London and Manchester academic centers lead European adoption of telehealth-integrated spasticity monitoring. MHRA post-Brexit regulatory autonomy enables faster adaptation of FDA-approved pediatric indications.
Australia
TGA priority review pathways for pediatric medicines accelerate market entry for neurotoxin products with established FDA or EMA approvals. Sydney and Melbourne rehabilitation centers integrate wearable kinematic sensors with remote monitoring platforms. Federal disability insurance scheme funding expands access to assistive devices and community-based therapy in previously underserved regional areas.
Global Cerebral Palsy Treatment Market Competitive Landscape
Global majors compete with regional champions across toxinology platform maturity and pediatric dosing specialization. Market structure tilts toward consolidated biologic manufacturing with fragmented service delivery, as hospital systems and specialty clinics compete for referral volume rather than manufacturing scale. Three archetypes dominate: integrated neurology portfolio holders, pure-play neurotoxin specialists, and surgical-intervention device manufacturers. Capacity expansion in higher-purity fermentation and strategic partnerships for motion-sensor integration represent the dominant competitive vectors.
Among established biopharmaceutical incumbents, Ipsen Biopharmaceuticals Inc., AbbVie Inc., and Merz GmbH & Co. KGaA occupy positions exemplifying differentiated platform strategies. Ipsen anchors the pure-play toxinology specialist archetype with concentrated spasticity indication focus. AbbVie represents the integrated neurology portfolio model spanning oral and injectable therapy categories. Merz occupies a specialized dosing protocol position refined for pediatric cerebral palsy populations, distinguishing its clinical positioning from adult-derived guideline competitors.
| Leading Market Players |
|---|
| Ipsen Biopharmaceuticals Inc. |
| AbbVie Inc. |
| Merz GmbH & Co. KGaA |
| Teva Pharmaceutical Industries Ltd. |
| Supernus Pharmaceuticals, Inc. |
| Neurocrine Biosciences, Inc. |
| Pfizer Inc. |
| Revance |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
WHO Rehabilitation 2030 initiative standards gate qualified supply access and premium-tier pricing for assistive devices and therapy equipment, forcing manufacturers to certify compliance before penetrating low-resource procurement channels. Pediatric clinics in the United States and Germany absorb cost premiums for higher-purity botulinum toxin formulations, while African and Southeast Asian markets face supply exclusion where certification infrastructure remains underdeveloped.
Pricing Analysis
Service bundling versus unbundling now defines competitive positioning as United States pediatric clinics separate botulinum toxin administration from mandatory physical therapy packages. Three-tier pricing structure across premium, standard, and economy levels stratifies by formulation purity and injection guidance technology integration. Cost compression in standard-tier products intensifies because caregiver demand for pricing transparency fragments referral networks. Hospital systems purchasing at volume scale exhibit lowest price sensitivity; community clinics with limited toxinology expertise face highest budget constraint pressure.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume neurotoxin demand from pediatric movement disorder centers, while specialty distributors serve low-volume community clinic networks. Manufacturing feedstock concentrates in United States, German, and Japanese fermentation facilities with validated capacity for complex biologic production. Active pharmaceutical ingredient production draws from bacterial culture media, specialized fermentation vessels, and chromatographic purification systems. Single-source vulnerability runs through North American contract manufacturing organizations with pediatric-specific formulation capabilities. Distribution runs through cold-chain logistics partners maintaining toxin stability across injection site delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into motion sensor technology and injection planning software represents the decisive upstream lever as precision dosing capabilities separate market leaders from formulation-only competitors.
For Market Incumbents: Lock in exclusive partnerships with wearable kinematic sensor manufacturers to automate muscle-volume calibration protocols before generic toxin competitors replicate dosing guidance systems. Secure captive supply of higher-purity fermentation capacity in Baden-Württemberg and North American clusters to preempt capacity constraints from FDA orphan drug incentive-driven demand surges. Defend against intrathecal pump manufacturers expanding into spasticity management through bundled surgical-pharmaceutical offerings. For New Entrants and Emerging Players: Begin with telehealth-integrated remote monitoring platforms targeting Southeast Asian rehabilitation centers where WHO standards are opening procurement pathways previously blocked by equipment certification barriers. Penetrate lowest-cost economy tier through unbundled injection services that compete on price transparency against hospital-captive therapy packages. Deploy direct-to-caregiver marketing emphasizing therapy provider choice flexibility. For Investors and Strategic Acquirers: FDA pediatric investigation plan submissions exceeding historical filing rates is the leading indicator that data exclusivity extensions will concentrate returns among innovators with juvenile pharmacokinetic datasets. Position acquisition screening toward specialized dosing protocol developers with established pediatric cerebral palsy clinician training networks. Monitor EMA pediatric investigation plan compliance timelines as signal for European market entry friction and extended innovator protection windows.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric-Specific Formulation Development | EMA pediatric investigation plans mandate age-appropriate dosing data for market authorization. |
| Motion Sensor Platform Integration | Wearable kinematic sensors enable real-time gait mechanics calibration for precision toxin dosing. |
| Telehealth Service Line Expansion | Remote monitoring platforms reduce CMS prior authorization administrative friction for repeat injections. |
| Manufacturing Capacity Scale-Up | Higher-purity fermentation investments address supply vulnerability from limited contract manufacturing organizations. |
| Reimbursement Strategy Alignment | CMS bundled payment reforms create financial alignment between hospitals and chronic spasticity programs. |
Research Methodology
Document review covered FDA orphan drug designation filings, EMA pediatric investigation plans, CMS coverage determinations, and WHO Rehabilitation 2030 technical guidance documents, complemented by interviews with pediatric movement disorder specialists, hospital formulary directors, neurotoxin manufacturing executives, and rehabilitation center procurement managers. Secondary validation drew from ClinicalTrials.gov pediatric spasticity trial registries, SEC 10-K biologics segment disclosures, and national health insurance reimbursement databases. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored market sizing.
Historical volume trajectories cross-referenced against expert panel input on regulatory timeline acceleration and telehealth adoption curves shaped the projection framework. Segmentation dimensions modeled spasticity severity tier, treatment modality, patient ambulatory status, and regional reimbursement infrastructure cluster. CAGRs derived from unit-based dosing frequency projections calibrated to pediatric population prevalence studies and injection cycle reimbursement patterns.
Regulatory approval delays, intrathecal pump coverage determination shifts, and biosimilar neurotoxin entry are the dominant revision risks that could compress pharmaceutical intervention shares. Practitioners should monitor FDA pediatric exclusivity grant rates and CMS prior authorization requirement modifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Global Pediatric Radiology Market
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Pediatric Growth Hormone Deficiency Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Autism Service Platform Market
Pediatrics
Global Pediatric Home Healthcare Services Market