
 Pediatric Palliative Care Drugs Market | 2026-2036
Pediatric Palliative Care Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Palliative Care Drugs Market Insights
Oral morphine formulations are realigning cost structures across the Pediatric Palliative Care Drugs landscape as hospitals shift from intravenous to sublingual and liquid preparations for home-based care. Jazz Pharmaceuticals anchors its position through deep expertise in sedative and analgesic portfolios for rare pediatric conditions. Pfizer leverages broad manufacturing scale to supply hospital systems with standardized pediatric dosing formats. Merck KGaA competes via specialized anticonvulsant compounds tailored to neurological symptom management in infants and toddlers.
Pediatric palliative care drugs comprise pharmacological agents formulated specifically for symptom relief in children with life-limiting conditions, requiring weight-calibrated dosing, palatable delivery mechanisms, and compatibility with immature hepatic and renal function. The primary purpose centers on managing pain, seizures, anxiety, and respiratory distress while preserving cognitive function and quality of life. Analgesics occupy the largest volume share due to persistent pain as the dominant symptom across cancer, neuromuscular, and cardiac conditions. Transdermal administration routes represent the fastest-expanding segment as caregivers seek non-invasive alternatives for home care settings.
The FDA's pediatric study requirements and the EMA's Paediatric Investigation Plans shape development timelines and labeling standards, compelling sponsors to generate age-specific efficacy data before market authorization. The EU's F-Gas Regulation constrains propellant choices in metered-dose delivery systems, redirecting formulation investments toward dry-powder and nebulized alternatives. Stakeholders must monitor evolving pharmacovigilance mandates for extended pediatric safety follow-up, as regulators tighten post-market surveillance obligations for drugs used in fragile neonatal and infant populations.
Market Dynamics
The migration from hospital-based to home-based pediatric palliative care is compressing formulation requirements toward patient-administered delivery systems. Oral solutions, transdermal patches, and sublingual tablets now dominate pipeline investments as clinical protocols prioritize caregiver-managed symptom control outside institutional settings.
Growth Catalysts
- Pediatric Exclusivity Incentives:The FDA's Best Pharmaceuticals for Children Act grants additional market exclusivity to sponsors conducting pediatric studies. This mechanism accelerates age-appropriate formulation development for drugs originally approved in adult populations.
- Home Care Infrastructure:Dedicated pediatric hospice networks in the United States have expanded nursing support for complex medication regimens. These organizations drive volume toward formulations compatible with non-clinical administration environments.
- Neurological Symptom Burden:Rising incidence of progressive neuromuscular conditions in infants creates sustained demand for anticonvulsant and sedative compounds. Weight-calibrated dosing systems address pharmacokinetic variability in this fragile population.
Market Restraints
- API Supply Concentration:Morphine sulfate and other opioid active pharmaceutical ingredients concentrate among a limited set of European and Indian manufacturers. Geographic concentration creates vulnerability to export restriction cascades.
- Formulation Cost Barriers:Palatability engineering, stability testing, and pediatric-specific toxicology studies multiply development expenditures relative to adult equivalents. These cost structures deter generic entry for niche indications.
- Propellant Regulatory Constraints:The EU's F-Gas Regulation restricts hydrofluorocarbon use in metered-dose inhalers. This limitation forces reformulation investment toward dry-powder alternatives with different lung deposition profiles.
Strategic Opportunities
- Transdermal Delivery Expansion:Fentanyl and buprenorphine patch technologies adapted for pediatric metabolism enable multi-day dosing without repeated venous access. This modality addresses caregiver burden in home-based care models.
- Academic Medical Center Partnerships:Collaboration with pediatric oncology units provides real-world efficacy data and protocol integration pathways. These relationships accelerate formulary adoption and reimbursement establishment.
- Neonatal Pharmacovigilance Systems:Extended safety follow-up mandates for drugs used in neonates create demand for specialized post-market surveillance infrastructure. Service providers can capture recurring revenue through regulatory compliance support.
Industry Challenges
- Pediatric Formulation Expertise Scarcity:Clinical pharmacologists with neonatal and infant development experience remain concentrated in academic centers. Commercial recruitment for this specialized competency commands premium compensation.
- Multinational Labeling Harmonization:Divergent age-band definitions between FDA pediatric categories and EMA Paediatric Investigation Plans complicate global development strategies. Sponsors face redundant study requirements or geographic market exclusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Palliative Care Drugs Market |
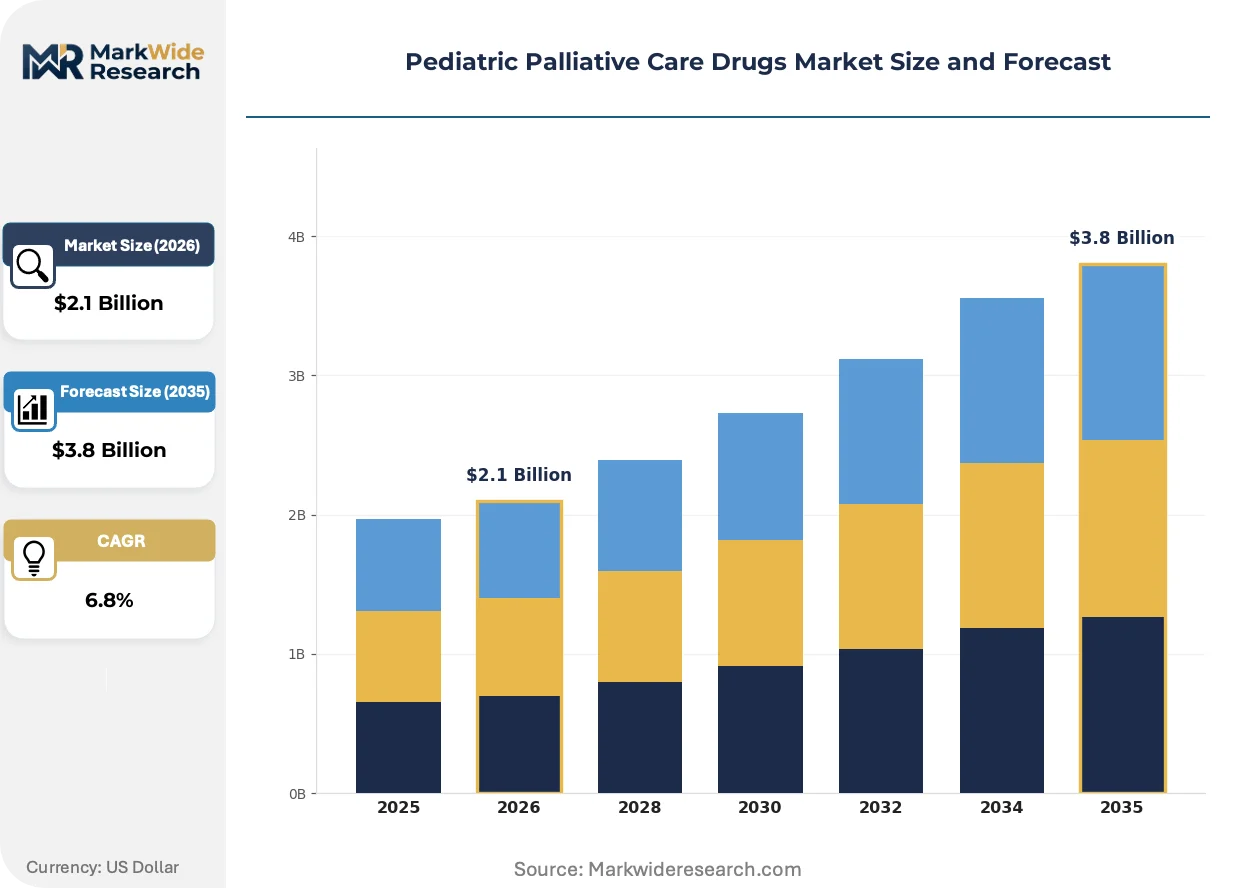
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antidepressants, Anticonvulsants, Sedatives Administration Route: Oral, Intravenous, Subcutaneous, Transdermal Care Setting: Home Care, Hospital, Hospice, Pediatric Ward Patient Age Group: Infants, Toddlers, Preschoolers, School-Aged Children |
| Companies Covered | BioMarin Pharmaceutical Inc, Jazz Pharmaceuticals Inc, Gilead Sciences Inc, Horizon Therapeutics plc, Sumitomo Dainippon Pharma Co Ltd, Pfizer, Sanofi, GSK, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Palliative Care Drugs Market Trends and Innovations
Formulation science is converging with digital health infrastructure to enable remote monitoring of medication adherence and symptom response. This integration creates new data streams that reshape both clinical protocols and regulatory evidence requirements.
Oral dispersible tablet technology is consolidating market position across pain and seizure management categories. Hospital systems in the United States and Germany are standardizing these formats for discharge protocols. The technology is consolidating procurement decisions around suppliers with integrated taste-masking and rapid-disintegration capabilities.
The EMA's Paediatric Investigation Plans now mandate inclusion of neonatal study cohorts for drugs with anticipated use in infants. This policy extension lengthens development timelines but generates label claims that competitors cannot replicate without equivalent investment. Oncology and neurology therapeutic areas face the most stringent cohort expansion requirements.
Caregiver-administered medication models are displacing institutional infusion dependence for stable chronic conditions. Home health agencies now coordinate directly with specialty pharmacies for compounded liquid preparations. This pattern is most visible in the United States, where reimbursement structures favor hospice enrollment over repeated hospitalization.
Pediatric Palliative Care Drugs Market Segmentation
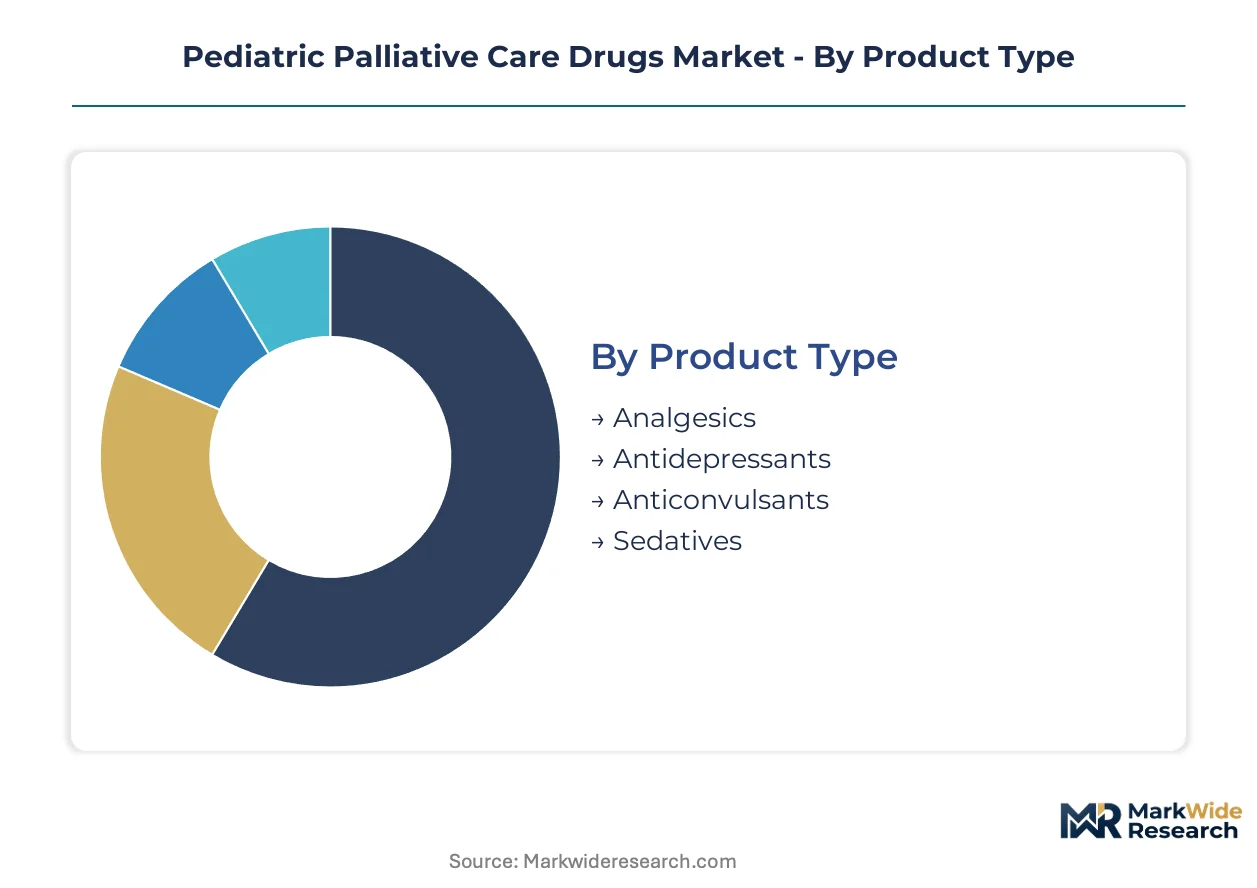
Pediatric palliative care drugs require precise segmentation to match formulation capabilities with developmental pharmacology. Age-specific metabolism, caregiver administration constraints, and care setting infrastructure each create distinct demand profiles that manufacturers must address through targeted product development.
Product Type:
Supply concentration for active pharmaceutical ingredients varies sharply across therapeutic categories, with opioid analgesics depending on concentrated European and Indian manufacturing bases while anticonvulsant APIs distribute more broadly.
- Analgesics:Morphine sulfate, fentanyl, and oxycodone formulations calibrated for weight-based pediatric dosing dominate procurement volumes. United States hospital systems and hospice networks drive demand for liquid and transdermal preparations that enable home-based pain management without intravenous access.
- Anticonvulsants:Levetiracetam, gabapentin, and phenobarbital compounds address seizure burden in progressive neuromuscular conditions. Germany's pediatric neurology centers and academic medical centers in Boston and Houston concentrate prescribing for these agents in infants and toddlers with epileptic encephalopathies.
- Sedatives:Midazolam and chloral hydrate preparations manage terminal agitation and procedural anxiety. Compounding pharmacies supply customized concentrations for individual patients.
- Antidepressants:Selective serotonin reuptake inhibitors and tricyclic compounds address mood disorders in school-aged children facing end-stage cardiac or oncologic conditions. Psychiatric consultation services in major children's hospitals guide prescribing patterns.
Analgesics absorb the bulk of installed capacity; anticonvulsants are expanding most quickly.
Administration Route:
Cost tier differentiation separates hospital-formulated intravenous preparations from patient-administered alternatives, with reimbursement structures favoring routes that reduce institutional dependency.
- Oral:Liquid solutions, dispersible tablets, and sublingual formulations enable caregiver-managed dosing outside clinical settings. Palatability engineering with taste-masking technologies determines formulary acceptance in United States pediatric hospice discharge protocols.
- Transdermal:Fentanyl and buprenorphine patches adapted for pediatric skin permeability provide sustained release over 72-hour intervals. Home health agencies in California, Texas, and Florida coordinate patch rotation schedules with specialty pharmacy networks.
- Intravenous:Continuous infusion protocols remain concentrated in pediatric intensive care units and inpatient oncology wards. Hospital-based compounding services prepare patient-specific concentrations.
- Subcutaneous:Butterfly needle infusion systems deliver analgesics and sedatives for patients with compromised venous access. Hospice nursing services train caregivers on site-of-care administration.
Oral routes command the largest share of new product development investment; transdermal delivery is gaining share fastest.
Care Setting:
Application requirements diverge between institutional protocols with pharmacy oversight and home environments where non-clinical caregivers assume primary administration responsibility.
- Home Care:Family-managed medication regimens require formulations with extended stability, clear visual dosing indicators, and minimal preparation steps. United States reimbursement through the Medicare hospice benefit and Medicaid waivers supports this care model expansion.
- Hospital:Pediatric wards and intensive care units maintain immediate access to intravenous opioids, rapid-acting sedatives, and reversal agents. Pharmacy and therapeutics committees standardize formularies across academic medical center networks.
- Hospice:Dedicated pediatric hospice organizations employ specialized nursing staff trained in complex symptom management. These entities in the United States maintain direct purchasing relationships with specialty distributors.
- Pediatric Ward:General pediatric units without dedicated palliative services rely on consultation-based prescribing from specialized teams. Formulary restrictions limit agent selection compared to dedicated palliative units.
Home care absorbs the bulk of patient volume; hospice enrollment is climbing the fastest.
Patient Age Group:
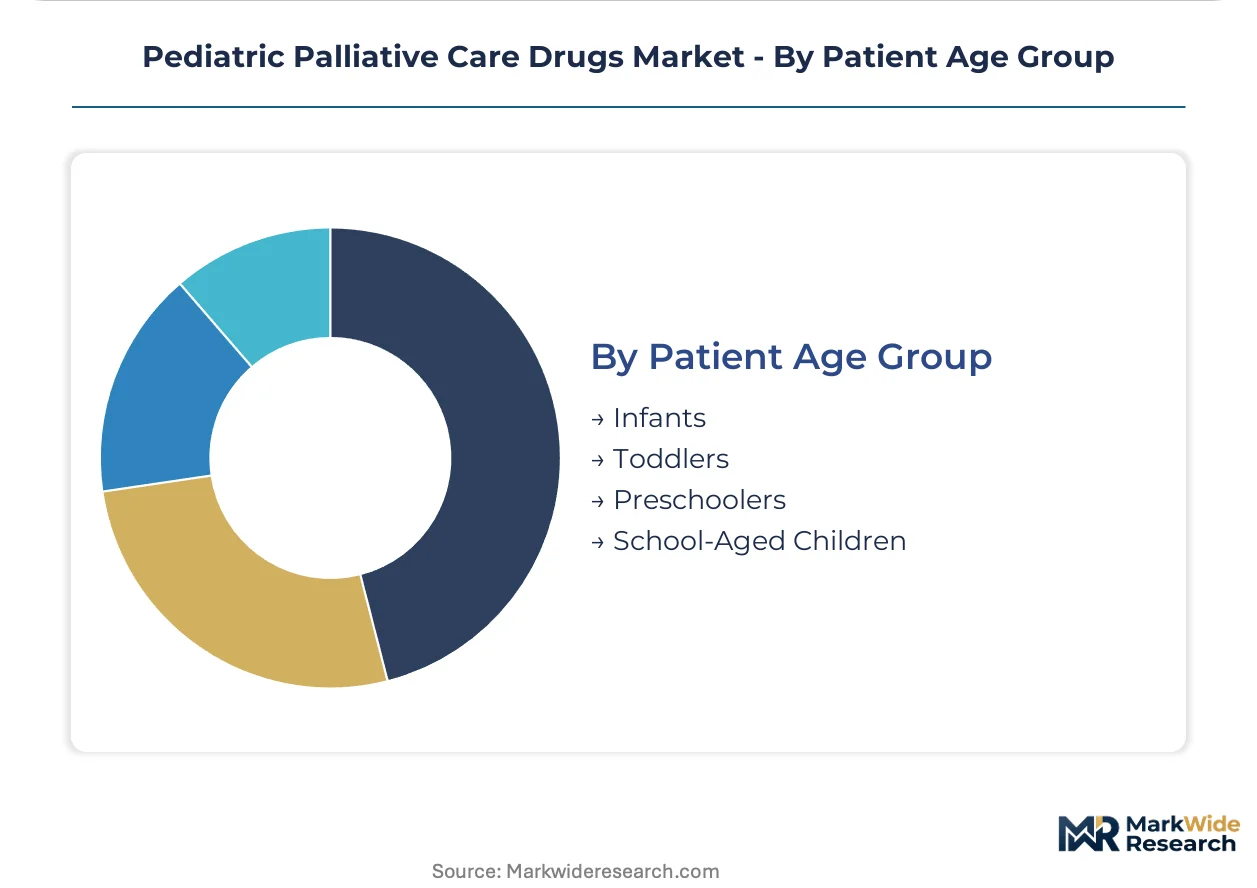
Volume concentration sits with school-aged children receiving oncologic palliation, while developmental pharmacology constraints create the steepest technical barriers in neonatal and infant populations.
- Infants:Hepatic enzyme immaturity and renal clearance limitations necessitate weight-calibrated dosing with narrow therapeutic indices. FDA pediatric study requirements mandate dedicated neonatal pharmacokinetic data for label claims.
- Toddlers:Rapid developmental changes in drug metabolism require frequent dose adjustments. Neuromuscular conditions including spinal muscular atrophy concentrate demand in this cohort.
- Preschoolers:Emerging ability to communicate pain and symptom experience enables more precise titration. Behavioral techniques supplement pharmacologic interventions.
- School-Aged Children:Cancer diagnoses and progressive cardiac conditions generate the largest absolute patient numbers. Cognitive capacity supports patient-controlled analgesia devices in select cases.
School-aged children absorb the bulk of therapeutic interventions; infants represent the steepest expansion trajectory for specialized formulation development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States hosts the dominant concentration of pediatric palliative care infrastructure, with specialized hospice networks and academic medical centers clustered in tax-advantaged healthcare zones across multiple states.
United States
Pediatric oncology units at Boston Children's Hospital and Texas Children's Hospital drive clinical adoption of liquid morphine and transdermal fentanyl formulations. The FDA's Best Pharmaceuticals for Children Act grants market exclusivity extensions for pediatric studies, accelerating age-appropriate development. California, Texas, and Florida host the densest networks of home health agencies coordinating specialty pharmacy distribution for hospice-enrolled families.
Germany
University hospitals in Heidelberg and Berlin maintain dedicated pediatric palliative wards with standardized protocols for neuromuscular symptom management. The EMA's Paediatric Investigation Plans mandate neonatal cohort inclusion, lengthening development timelines but securing non-replicable label claims. Bavaria and Baden-Württemberg concentrate prescribing for anticonvulsant compounds in infant epileptic encephalopathies.
United Kingdom
NHS England's specialized commissioning frameworks reimburse complex medication regimens for life-limiting conditions in children. The MHRA aligns with EMA pediatric data requirements while maintaining national formularies for liquid and dispersible preparations. London and Manchester academic centers generate real-world efficacy data that accelerates protocol integration across hospital networks.
Japan
PMDA pediatric review pathways prioritize oncology and neurology therapeutic areas with extended safety follow-up mandates. The country's national health insurance system reimburses weight-calibrated dosing systems for home-based care. Tokyo and Osaka metropolitan areas concentrate specialized nursing services for caregiver-managed medication administration.
India
CDSCO pediatric study waivers for essential medicines accelerate access to morphine sulfate and phenobarbital formulations. The country's pharmaceutical manufacturing base supplies APIs to European and North American formulation specialists. Maharashtra and Gujarat host contract manufacturers producing palatable liquid preparations for export markets.
Pediatric Palliative Care Drugs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical companies controlling hospital formulary access while niche developers capture orphan indication premiums. The market structures around three tiers: large-cap diversified manufacturers with pediatric dosing platforms, mid-cap rare disease specialists with sedative and analgesic expertise, and regional compounders serving hospice discharge protocols. Consolidation pressure concentrates among API suppliers for opioid and anticonvulsant actives, while formulation capabilities remain fragmented across geographies. Dominant competitive moves include strategic partnerships with academic medical centers for real-world data generation and backward integration into captive API supply for controlled substances.
Within the rare disease specialist tier, Jazz Pharmaceuticals and BioMarin Pharmaceutical exemplify archetypes leveraging deep expertise in age-appropriate formulations for neurological and metabolic conditions. Pfizer represents the scale-driven diversified manufacturer segment with standardized pediatric dosing formats supplied across hospital systems. Merck KGaA occupies a position bridging specialty anticonvulsant development with broad manufacturing infrastructure, anchoring the mid-cap integrated player category.
| Leading Market Players |
|---|
| BioMarin Pharmaceutical Inc |
| Jazz Pharmaceuticals Inc |
| Gilead Sciences Inc |
| Horizon Therapeutics plc |
| Sumitomo Dainippon Pharma Co Ltd |
| Pfizer |
| Sanofi |
| GSK |
| Merck KGaA |
| Others |
Pricing and Supply Chain Analysis
The EU's F-Gas Regulation gates qualified supply for metered-dose inhaler propellants while simultaneously segmenting pricing access, forcing manufacturers toward dry-powder alternatives that command premium positioning against stranded HFC-dependent inventory.
Pricing Analysis
Short lead-time premiums attach to compounding pharmacy networks capable of 24-48 hour turnaround on patient-specific liquid morphine concentrations, while spot inventory of standardized oral dispersible tablets trades at modest discounts. Three-tier pricing structure across premium, standard, and economy levels reflects FDA pediatric exclusivity status, GMP certification tier, and after-sales clinical support bundling. Cost compression in generic analgesic tiers is intensifying because Indian API manufacturers are expanding capacity for morphine sulfate. Hospice networks exhibit the highest price sensitivity due to fixed reimbursement rates, while academic medical centers prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
India's domestic-content mandates for essential medicines are reshaping sourcing patterns for contract manufacturers serving European and North American markets. Active pharmaceutical ingredient supply concentrates in India, China, and select European facilities for opioid analgesics, while anticonvulsant APIs distribute more broadly. Formulation inputs depend on specialized excipient grades for taste-masking and rapid-disintegration, pediatric-specific packaging materials, and controlled-substance security features. Single-source vulnerability concentrates in morphine sulfate API production, where geographic clustering creates export restriction exposure. Distribution runs through specialty pharmacy networks coordinated with home health agencies for direct-to-patient delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API manufacturing capacity for controlled substances operates under strict quota systems, propping pricing power for qualified suppliers capable of navigating DEA and international narcotics control frameworks.
For Market Incumbents: Deepen backward integration into captive morphine sulfate supply to insulate margin structures from Indian export volatility. Secure pediatric exclusivity extensions through expanded neonatal study commitments that competitors cannot replicate without equivalent timeline investment. Jazz Pharmaceuticals and Pfizer anchor positions through formulary control at Boston Children's Hospital and Texas Children's Hospital networks. For New Entrants and Emerging Players: The FDA's Best Pharmaceuticals for Children Act in the United States opens a window for sponsors of adult-approved drugs to capture exclusivity premiums through pediatric formulation development. Target transdermal delivery technologies for home-based hospice care, where caregiver-administered models are displacing institutional dependence. Partner with California and Florida home health agencies for direct distribution pathway establishment. For Investors and Strategic Acquirers: EMA mandating neonatal cohort inclusion in Paediatric Investigation Plans is the leading indicator that specialized pharmacovigilance infrastructure will command recurring revenue streams. Over the medium-term horizon, acquisition targets should feature integrated API-formulation capabilities with controlled-substance licensing. Watch for CDSCO pediatric study waivers in India accelerating access to essential medicines as the signal for API supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Neonatal Pharmacokinetic Study Expansion | EMA's cohort mandates secure non-replicable label claims for infant populations. |
| Transdermal Patch Technology Adaptation | Fentanyl and buprenorphine patches address caregiver burden in California hospice networks. |
| Academic Medical Center Partnership | Collaboration with Boston Children's Hospital accelerates formulary adoption pathways. |
| Controlled Substance API Backward Integration | Captive morphine sulfate supply insulates against Indian export restriction cascades. |
| Specialty Pharmacy Distribution Integration | Direct coordination with home health agencies enables patient-specific compounding scale. |
Research Methodology
Multi-period observation of FDA pediatric exclusivity grants, EMA Paediatric Investigation Plan approvals, and hospice enrollment patterns anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and specialty pharmacy procurement managers. Secondary validation drew from FDA filings, EMA submission databases, ClinicalTrials.gov pediatric study records, and CMS Medicare hospice reimbursement data. Bottom-up patient volume modeling and top-down pharmaceutical market sizing were triangulated to constrain estimate variance.
Input-output matrix framing connected API manufacturing capacity, formulation development timelines, and care setting infrastructure to patient access projections across the analysis window. Segmentation dimensions included therapeutic category, administration route, patient age band, and regional regulatory cluster. CAGRs were derived from compounding growth rates across these segments. Forecast inputs incorporated FDA pediatric study completion rates and EMA neonatal cohort expansion mandates as industry-specific demand drivers.
Caveats apply where DEA quota adjustments for controlled substances, export restriction cascades from Indian API manufacturers, or reimbursement rate changes for hospice services could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory pathway timelines and care model migration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Perfusion Products Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Pediatric Mattress Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Chronic Rhinosinusitis Market
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric Brain Tumor Market