
 Pediatric Mattress Market | 2026-2036
Pediatric Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Mattress Market Insights
Buyer concentration among pediatric hospital networks and specialty maternity chains is shifting procurement toward contract-based volume agreements with certified manufacturers. Naturepedic Organic Mattress leverages its organic supply chain to anchor premium positioning in institutional channels. Serta Simmons Bedding competes through manufacturing scale across foam and innerspring lines. Tempur Sealy International dominates temperature-responsive technology for neonatal applications.
A pediatric mattress is a purpose-engineered sleep surface designed for infants through school-aged children, typically incorporating firmness gradients between 20-40 ILD, breathable core materials, and dimension standards matching regulated crib and bed frame specifications to reduce suffocation risk and support musculoskeletal development. Foam and hybrid product types lead unit volume due to lighter weight and easier sanitation protocols in clinical settings, while organic cotton material segments command margin premiums through third-party certifications. The infant age group sustains the highest replacement frequency as growth milestones trigger size transitions.
The US Consumer Product Safety Commission and the Juvenile Products Manufacturers Association govern dimensional and flammability requirements, while the EU's REACH chemicals framework restricts certain flame retardants in imported pediatric sleep products. China's GB standards and the National Medical Products Administration set parallel technical benchmarks for clinical-grade mattresses used in pediatric wards. Stakeholders must monitor divergence between domestic certification requirements and import testing protocols when scaling cross-border distribution.
Market Dynamics
The US Consumer Product Safety Commission's updated flammability standards for crib mattresses have triggered material substitutions across domestic supply chains, compressing margins for foam-dependent manufacturers while opening pathways for certified organic alternatives.
Growth Catalysts
- Neonatal intensive care procurement:Hospital systems now consolidate purchasing through contract-based volume agreements with certified manufacturers, creating predictable demand channels for pressure-reducing pediatric surfaces.
- REACH chemicals framework:The EU's restrictions on certain flame retardants in imported pediatric sleep products have accelerated certification investments among exporters targeting European maternity chains.
- Temperature-responsive foam:Advances in phase-change materials are enabling precise thermoregulation for premature infants, differentiating clinical-grade mattresses in neonatal wards.
Market Restraints
- Petrochemical input volatility:Polyurethane foam producers face margin compression from propylene oxide and TDI price swings, forcing quarterly contract renegotiations with hospital purchasing groups.
- Chinese supply concentration:Overreliance on Zhejiang and Guangdong province manufacturers for organic cotton ticking creates vulnerability to regional logistics disruptions and quality variance.
- Dimensional standard fragmentation:Divergence between US crib dimensions, EU cot specifications, and China's GB standards forces SKU proliferation and inventory inefficiency for multinational brands.
Strategic Opportunities
- Subscription-based replacement models:Direct-to-parent rental services for infant-to-toddler size transitions are emerging in tier-one Chinese cities, capturing recurring revenue from growth-milestone-driven purchases.
- Biodegradable core materials:Convergence of natural latex processing and mycelium-based foams offers pathways to landfill-diversion claims aligned with China's dual carbon goals.
- Telehealth-integrated sleep monitoring:Pediatric mattresses embedded with pressure sensors and respiratory tracking are penetrating telemedicine channels serving rural US markets with specialist access gaps.
Industry Challenges
- Certification timeline compression:Third-party organic certifications from GOTS and OEKO-TEX require 8-14 month validation cycles, delaying product launches behind competitor window.
- Specialized polymer engineering talent:Formulation chemists with pediatric flammability compliance expertise command premium compensation, constraining R&D expansion at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Mattress Market |
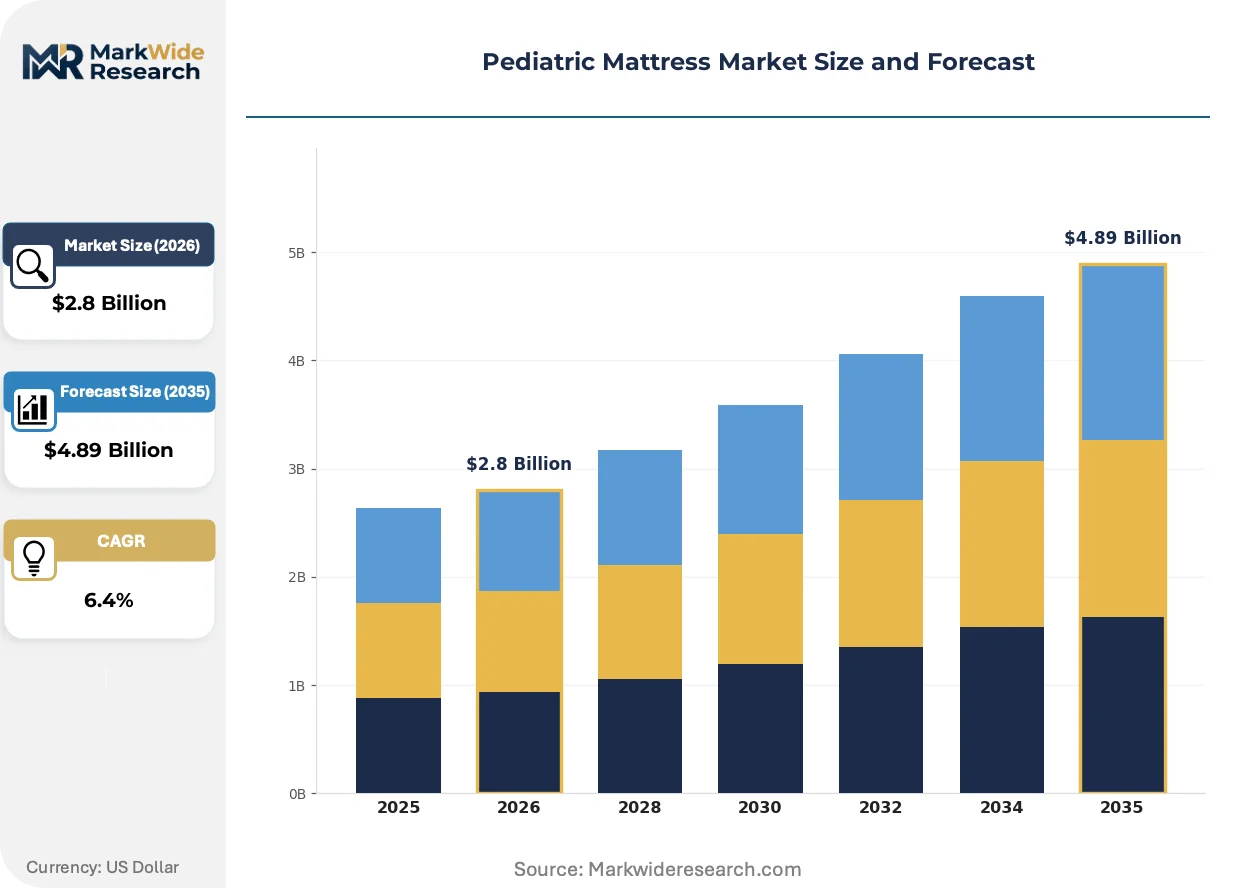
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Innerspring, Hybrid, Gel Age Group: Infants, Toddlers, Preschool, School-Aged Material: Organic Cotton, Memory Foam, Latex, Air Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Manufacturers |
| Companies Covered | Naturepedic Organic Mattress, Inc., Serta Simmons Bedding, LLC, Tempur Sealy International Inc., Colgate Mattress, Moonlight Slumber, Inter IKEA Holding B.V., Avocado Green Mattress, Inc., Purple Innovation, LLC, Saatva, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Mattress Market Trends and Innovations
Material science breakthroughs and procurement centralization are restructuring how pediatric sleep surfaces are specified, manufactured, and distributed across institutional and retail channels.
Pressure-mapping sensor arrays integrated into mattress cores are expanding into remote patient monitoring protocols for premature infants discharged to home care settings. Neonatal intensive care units in US hospital systems are piloting these surfaces to reduce readmission rates for apnea-related events. The technology is expanding into pediatric home health agencies seeking reimbursement advantages from outcome documentation.
China's GB standards for clinical-grade mattresses used in pediatric wards are tightening dimensional tolerances and breathability testing protocols under National Medical Products Administration oversight. Domestic manufacturers must retool cutting and quilting equipment to meet revised specifications effective across tertiary hospital procurement tenders. Exporters targeting China's maternity hospital chains face parallel compliance investments to maintain volume contract eligibility.
Consolidated buying by pediatric hospital networks and specialty maternity chains is displacing fragmented distributor relationships with direct manufacturer partnerships. Group purchasing organizations now mandate certified organic supply chain documentation and audit rights, filtering supplier bases to vertically integrated producers. This concentration is most visible in China's tier-one cities where replacement cycles for pediatric ward mattresses have compressed from five to three years amid healthcare infrastructure expansion.
Pediatric Mattress Market Segmentation
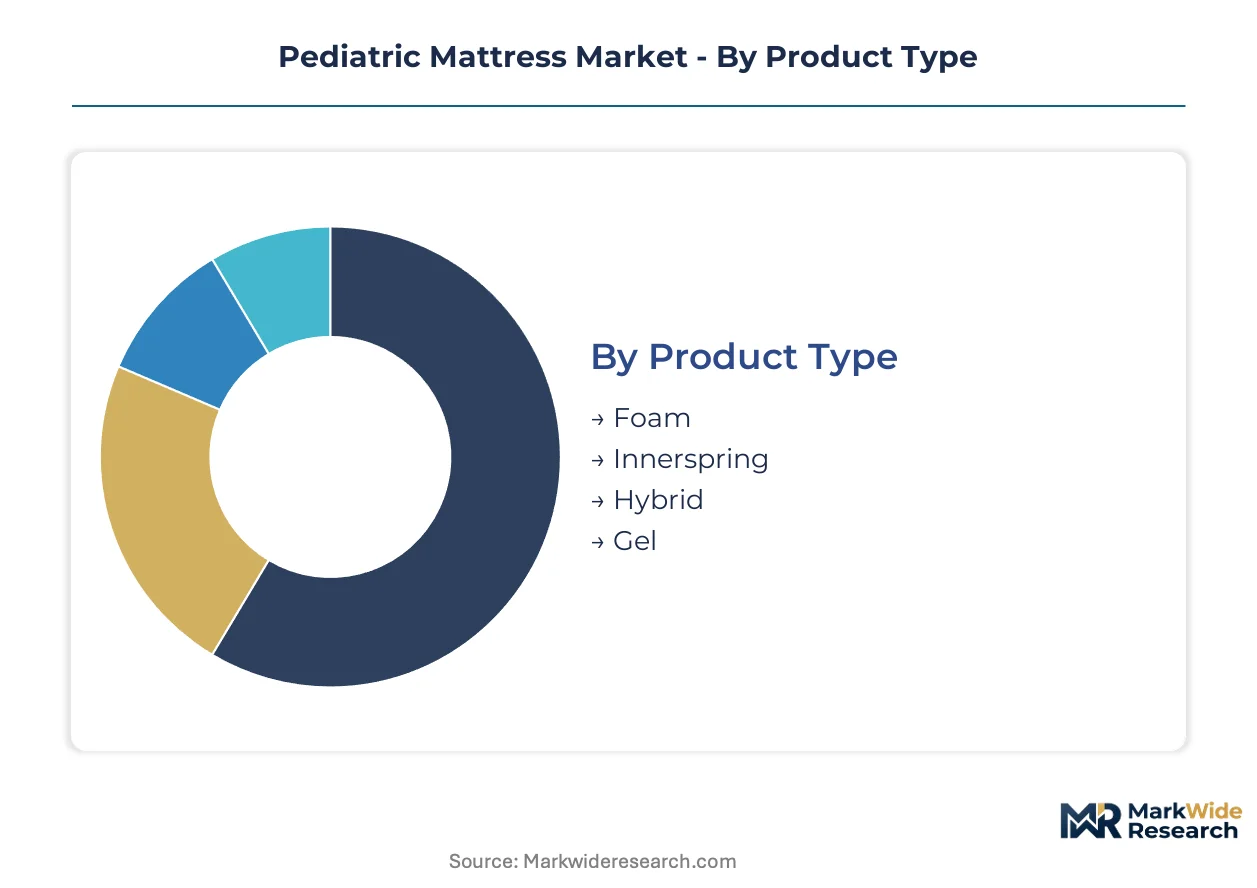
Pediatric mattress procurement patterns diverge sharply between institutional buyers prioritizing sanitation protocols and parents seeking developmental safety certifications. Segmentation reveals how material choices and channel strategies align with distinct replacement triggers across age milestones.
Product Type:
Replacement cycles accelerate where cleaning protocols demand lighter, non-porous surfaces that withstand hospital-grade disinfectants.
- Foam:Polyurethane and high-resilience formulations dominate clinical procurement for neonatal intensive care units due to seamless surfaces that resist fluid penetration. US hospital systems specify 20-40 ILD firmness gradients to meet Consumer Product Safety Commission suffocation-risk thresholds.
- Hybrid:Coil-and-foam combinations capture premium residential demand in China's tier-one cities where parents prioritize longevity across toddler-to-preschool transitions. Phase-change material integration differentiates clinical-grade hybrids for thermoregulation in premature infant care.
- Innerspring:Traditional coil construction persists in budget retail channels with perimeter edge support addressing toddler bed conversion needs.
- Gel:Viscoelastic gel infusions target temperature-sensitive sleepers in Mediterranean climates with cooling claims backed by limited pediatric-specific validation.
Foam sits at the top of the volume ranking, with Hybrid climbing the fastest.
Age Group:
Cost tier stratification follows developmental safety requirements, with stringent regulations compressing margins at the infant level while unlocking premium pricing for school-aged ergonomic features.
- Infants:Crib mattress specifications face the most intensive regulatory scrutiny, with firmness testing and breathability certification mandatory under US and EU frameworks. Replacement frequency peaks at 12-18 months as growth milestones trigger size transitions.
- Toddlers:Convertible crib-to-bed dimensions extend product lifecycles, with waterproof barriers and reinforced edges addressing potty-training accidents. China's maternity chains report strongest volume growth in this bracket.
- Preschool:Transition to standard twin dimensions opens private-label competition from furniture retailers bundling mattresses with themed bed frames.
- School-Aged:Orthopedic positioning and hypoallergenic claims support margin premiums, though replacement cycles extend to 5-7 years.
Infant mattresses command the highest unit velocity, while Toddler segments are gaining share fastest through conversion-compatible designs.
Material:
Supply concentration in certified organic cotton creates procurement bottlenecks that favor vertically integrated manufacturers with captive ticking production.
- Organic Cotton:GOTS-certified supply chains anchor premium positioning in institutional channels, with Naturepedic leveraging exclusive organic sourcing for maternity hospital contracts. REACH compliance costs filter out smaller competitors in European export markets.
- Memory Foam:Viscoelastic formulations with phase-change materials dominate temperature-responsive neonatal applications, with Tempur Sealy's clinical division holding formulation patents.
- Latex:Natural rubber cores from Sri Lankan and Malaysian plantations serve biodegradable positioning aligned with China's dual carbon goals.
- Air:Adjustable firmness chambers remain niche, targeting medical-grade pressure relief for homecare settings post-NICU discharge.
Organic Cotton leads value concentration, with Latex showing the steepest expansion trajectory on sustainability credentials.
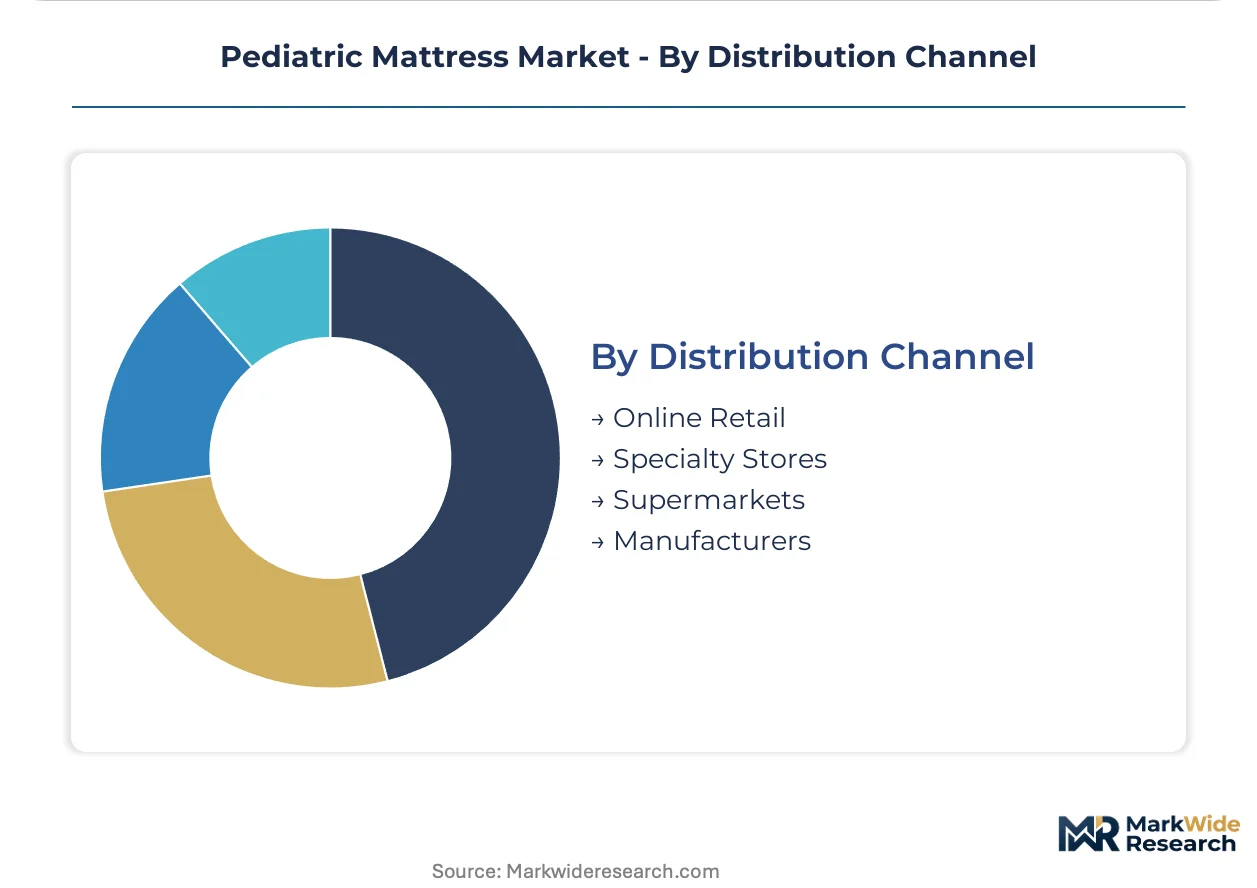
Distribution Channel:
Customer type fragmentation—hospital procurement officers versus individual parents—drives channel specialization with divergent margin structures.
- Online Retail:Direct-to-parent subscription models for size-transition replacements are emerging in Shenzhen and Shanghai, capturing recurring revenue through growth-milestone tracking.
- Specialty Stores:Maternity chains and juvenile product boutiques provide tactile evaluation for firmness preferences, with staff certification on safety standards supporting conversion rates.
- Supermarkets:Mass-market private labels compete on price with limited certification transparency, serving secondary-city demand in China's interior provinces.
- Manufacturers:Direct institutional sales to pediatric hospital networks displace distributor relationships, with group purchasing organizations mandating audit rights and supply chain documentation.
Manufacturers capture the largest contract values, while Online Retail is expanding most quickly through telehealth-integrated sleep monitoring bundles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's maternity hospital procurement volume outpaces US replacement cycles, while Germany's REACH enforcement filters supplier eligibility more aggressively than North American flammability standards.
United States
The Consumer Product Safety Commission's updated crib mattress flammability rules compress foam-dependent margins while accelerating organic certification investments. Hospital systems in Texas and California consolidate purchasing through group buying organizations mandating audit rights. Boston's pediatric research corridor drives pilot programs for sensor-embedded neonatal surfaces.
Germany
ECHA's REACH restrictions on halogenated flame retardants force material substitutions for exporters serving maternity chains across Bavaria and North Rhine-Westphalia. Berlin's procurement offices prioritize OEKO-TEX certification for pediatric ward tenders. Stuttgart's medical device cluster concentrates formulation expertise for clinical-grade thermoregulation.
China
NMPA oversight of GB standards for clinical-grade mattresses tightens dimensional tolerances under tertiary hospital procurement rules. Shenzhen and Shanghai maternity chains compress replacement cycles from five to three years amid infrastructure expansion. Guangdong province manufacturers retool quilting equipment to meet breathability testing protocols.
Japan
METI guidelines on chemical emissions in juvenile products align with JIS standards for mattress firmness and breathability. Tokyo's neonatal intensive care units specify pressure-reducing surfaces for premature infant protocols. Osaka's textile engineering base supplies phase-change material integration for temperature-responsive cores.
India
BIS certification requirements for crib mattress safety create compliance bottlenecks for imported foam products serving Delhi-NCR maternity hospitals. Maharashtra's pediatric healthcare infrastructure expansion drives replacement demand in Mumbai and Pune. Tamil Nadu's cotton processing clusters supply organic ticking for premium positioning.
Pediatric Mattress Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels, with contract-based hospital agreements favoring scaled manufacturers while direct-to-parent subscription models elevate niche certified producers. The vendor base separates into three strategic archetypes: vertically integrated organic specialists, foam-scaled industrial producers, and temperature-responsive technology licensors. Consolidation pressures manifest through group purchasing organization mandates and cross-border certification investments.
Within the organic-certified tier, Naturepedic Organic Mattress exemplifies supply chain control through captive sourcing, while Serta Simmons Bedding represents manufacturing scale across foam and innerspring construction. Tempur Sealy International anchors the temperature-responsive segment with formulation patents for neonatal thermoregulation applications.
| Leading Market Players |
|---|
| Naturepedic Organic Mattress, Inc. |
| Serta Simmons Bedding, LLC |
| Tempur Sealy International Inc. |
| Colgate Mattress |
| Moonlight Slumber |
| Inter IKEA Holding B.V. |
| Avocado Green Mattress, Inc. |
| Purple Innovation, LLC |
| Saatva, Inc. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between GOTS-certified organic mattresses and conventional polyurethane foam products manifests in divergent margin structures and sourcing strategies across the pediatric mattress industry. Premium organic tiers command three-to-five-year supply contracts with captive cotton ticking operations, while commodity foam producers absorb petrochemical volatility through quarterly price renegotiations with hospital purchasing groups.
Pricing Analysis
Capacity additions in Zhejiang province are reshaping price floors for organic cotton ticking as Guangdong manufacturers expand GOTS-certified quilting lines. Three-tier pricing structure across premium certified-organic, standard clinical-grade, and economy retail tiers separates hospital procurement officers from individual parent buyers. Pricing pressure stems from propylene oxide and TDI feedstock volatility compressing foam-dependent margins. Hospital systems exhibit lowest price sensitivity due to outcome-based reimbursement protocols, while mass-market parents in China's interior provinces drive aggressive private-label competition.
Supply Chain Analysis
Dual-sourcing requirements from group purchasing organizations now mandate qualified backup suppliers for both organic cotton ticking and high-resilience foam cores. Manufacturing concentrates in China, Sri Lanka, and Malaysia, with Sri Lankan latex plantations and Malaysian rubber processing feeding biodegradable core demand. Raw material dependencies rest on Zhejiang organic cotton cultivation, Guangdong foam formulation capacity, and German chemical inputs for phase-change materials. Single-source vulnerability runs through concentrated GOTS-certified ticking suppliers. Distribution feeds from manufacturer-direct hospital contracts and specialty maternity chains, with online subscription models penetrating tier-one Chinese cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
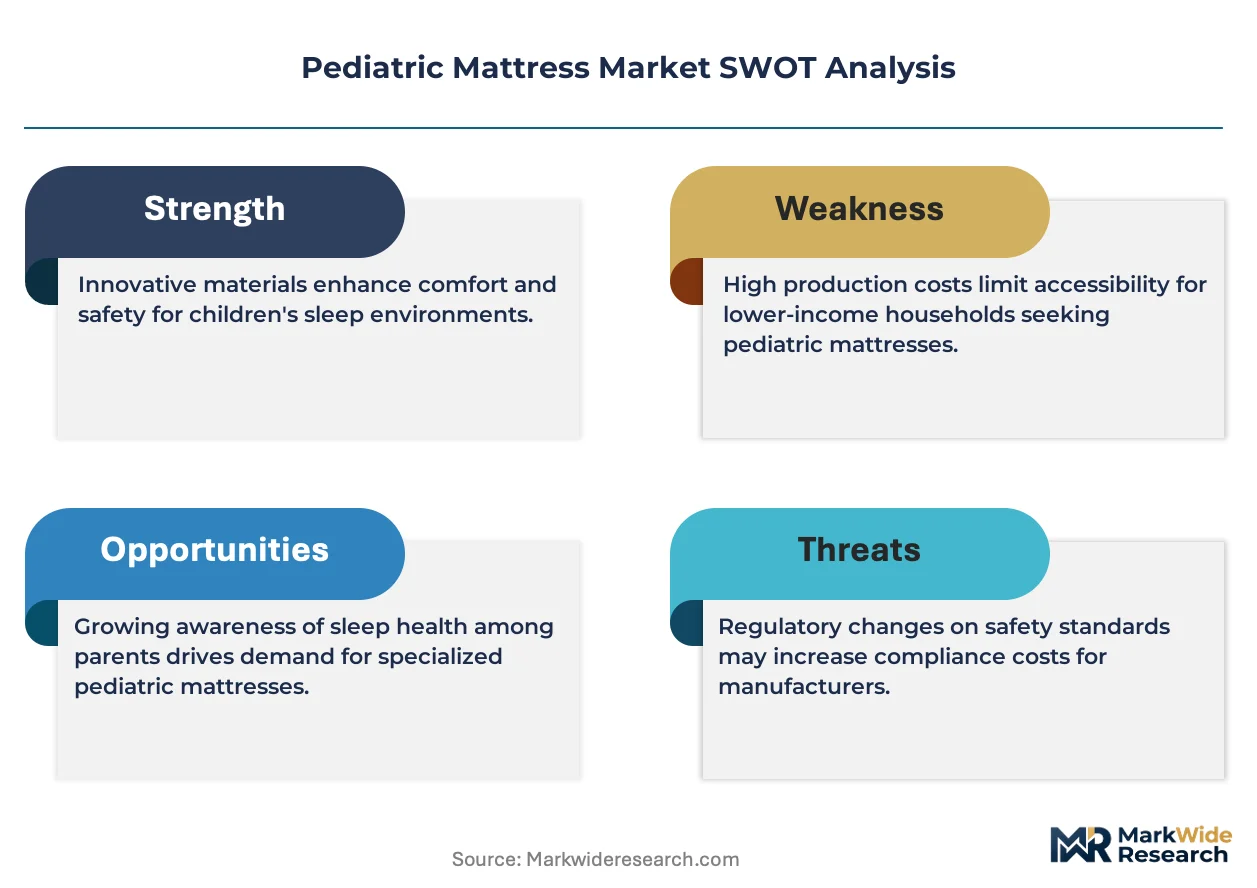
This market functions as a geographic-arbitrage play between REACH-compliant European export premiums and cost-optimized Chinese domestic production, with certification differential capturing margin spread.
For Market Incumbents: Hedge against petrochemical input volatility through backward integration into Sri Lankan latex plantations or exclusive organic cotton sourcing partnerships. Defend hospital contract renewals by embedding pressure-sensor telemetry for remote patient monitoring, creating switching costs against foam-only competitors. Prioritize GOTS certification maintenance as EU flame retardant restrictions filter supplier eligibility. For New Entrants and Emerging Players: Enter via telehealth-integrated sleep monitoring bundles targeting rural US markets with specialist access gaps, where reimbursement documentation creates sticky revenue. Capture white-space in biodegradable mycelium-foam cores aligned with China's dual carbon goals. Target Shenzhen and Shanghai subscription-based rental services for infant-to-toddler size transitions, where growth-milestone tracking enables recurring revenue capture. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated organic specialists holding captive GOTS-certified supply chains and established maternity hospital contracts. Five-to-ten-year viability hinges on regulatory divergence between US flammability standards and EU REACH restrictions favoring dual-certified producers. Watch for NMPA breathability testing protocol tightening as inflection signal for equipment retooling demand across Guangdong manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | GOTS and OEKO-TEX dual certification unlocks EU maternity chain eligibility under REACH restrictions. |
| Sensor Integration Partnership | Pressure-array telemetry embedded in neonatal surfaces reduces US hospital readmission rates for apnea events. |
| Biodegradable Core Development | Mycelium-based foam formulations align procurement specifications with China's dual carbon policy framework. |
| Subscription Model Launch | Direct-to-parent rental services in tier-one Chinese cities capture recurring revenue from growth-milestone transitions. |
| Backward Integration | Captive organic cotton ticking production insulates margin from Zhejiang supply concentration risks. |
Research Methodology
Multiple input streams — primary interviews with neonatal intensive care procurement officers, GOTS certification auditors, and polyurethane formulation chemists; secondary validation through FDA flammability filings, NMPA GB standard updates, and hospital GPO contract databases; customs trade records for organic cotton ticking — were reconciled through bottom-up unit volume modeling and top-down market value triangulation.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, age group milestone, material certification tier, and distribution channel concentration. CAGRs derived from historical replacement cycle compression in China's tier-one cities and penetration rates for sensor-embedded clinical surfaces. Forecast inputs incorporated REACH chemical restriction timelines and NMPA equipment retooling mandates.
Inputs from hospital purchasing committees and specialty maternity chain buyers were available through the study window; gaps in real-time polyurethane feedstock pricing introduce uncertainty bands around foam-dependent manufacturer margin projections. Deviation in US Consumer Product Safety Commission flammability rule enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric Tube Feeding Market
Pediatrics
Pediatric Dental Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Pediatric Catheter Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Paediatric Influenza Treatment Market
Pediatrics
Pediatric HIV Infection Treatment Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Middle East and Africa Pediatric Healthcare Market