
 Paediatric Influenza Treatment Market | 2026-2036
Paediatric Influenza Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Paediatric Influenza Treatment Market Analytics
Preventive vaccination scheduling as a subscription-like service layer is pivoting how pharmaceutical firms engage paediatric care networks. Roche Holding AG leverages its diagnostic-to-treatment integration to sustain loyalty across hospital systems. GlaxoSmithKline plc anchors its position through manufacturing scale in live-attenuated vaccine production. Sanofi S.A. differentiates via recombinant technology leadership in infant-specific formulations.
Paediatric influenza treatment encompasses antiviral chemoprophylaxis, active immunization, and supportive care modalities formulated for patients under eighteen years, with dosing calibrated by weight bands and developmental pharmacokinetics. Its primary purpose is reducing severe outcomes—hospitalization, secondary bacterial infection, and mortality—in immunologically immature populations. Antivirals capture the largest margin pool due to stockpiling obligations and pandemic preparedness contracts, while combination therapies represent the fastest-growing category as resistance surveillance expands. Orally dispersible tablets gain share against syrups where palatability engineering and cold-chain elimination reduce distribution costs.
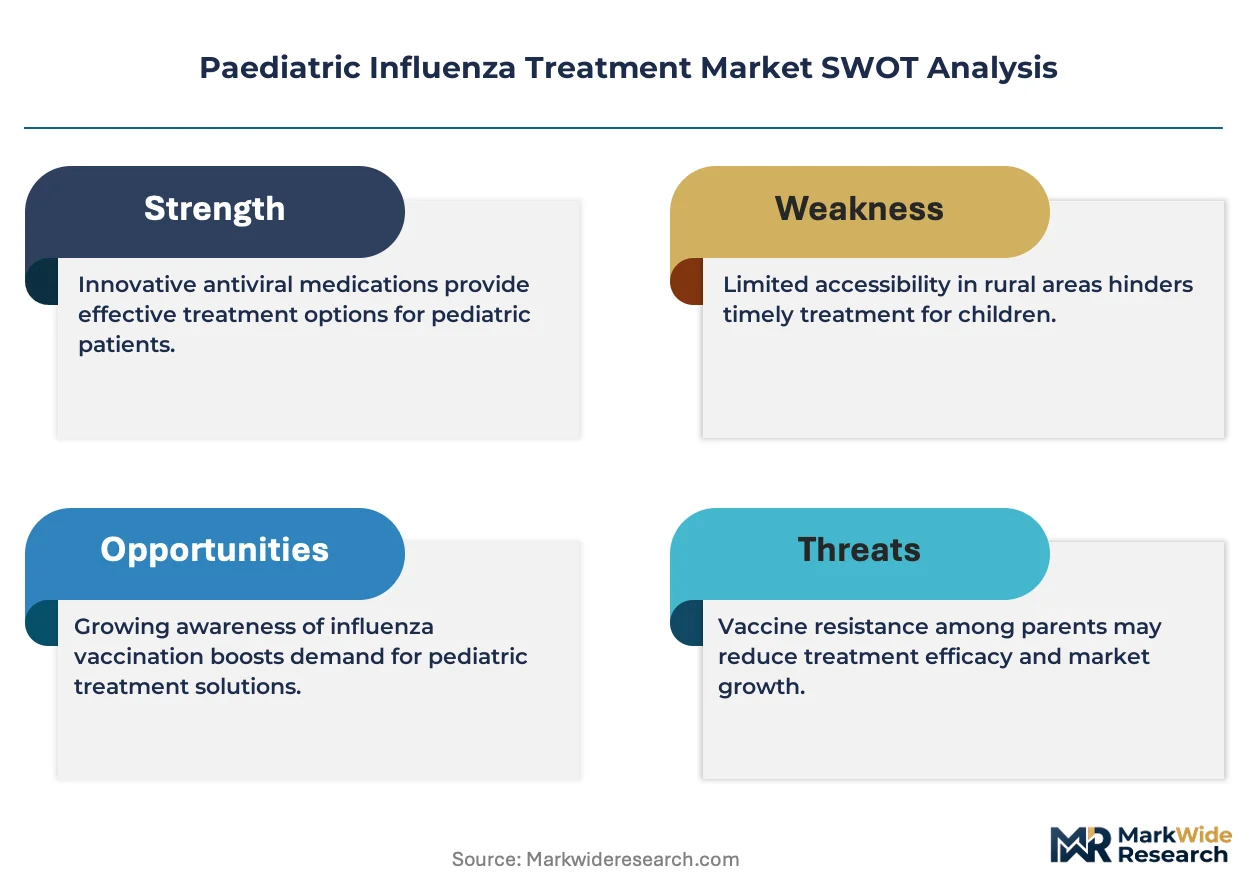
The FDA's paediatric study requirements under the Pediatric Research Equity Act and EMA's Paediatric Investigation Plans shape trial design and label expansion timelines, directly determining which molecules reach paediatric indications. WHO prequalification standards govern procurement eligibility for low-income country immunization programs, filtering market access for vaccine suppliers. Stakeholders must monitor antiviral resistance surveillance networks and regulatory harmonization between FDA and EMA paediatric development frameworks to anticipate portfolio prioritization shifts.
Market Dynamics
FDA's accelerated approval pathways for paediatric antivirals are compressing development timelines and forcing portfolio reallocation across pharmaceutical pipelines. This regulatory velocity is restructuring competitive positioning by rewarding firms with integrated diagnostic-to-treatment capabilities.
Growth Catalysts
- Paediatric Investigation Plans:EMA's structured development frameworks reduce regulatory uncertainty for sponsors targeting European market access. These plans streamline paediatric trial design and accelerate label expansions.
- Live-attenuated vaccine manufacturing:Cold-chain elimination technologies are expanding distribution reach into rural and resource-limited settings. This process innovation unlocks previously inaccessible patient populations.
- Seasonal immunization protocols:Paediatric clinics are broadening preventive service offerings as subscription-like vaccination scheduling gains traction among healthcare networks.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for neuraminidase inhibitors clusters in specific Asian manufacturing hubs, creating vulnerability to geopolitical disruption and quality enforcement actions.
- Paediatric formulation complexity:Weight-banded dosing requirements and palatability engineering demands extend development timelines and inflate per-unit production costs versus adult equivalents.
- Antiviral resistance surveillance gaps:Inconsistent national reporting standards for influenza strain mutations undermine stockpiling rationale and procurement planning for public health agencies.
Strategic Opportunities
- WHO prequalification pathways:Low-income country immunization programs represent underserved procurement volumes for suppliers meeting international quality standards. Prequalification unlocks multilateral purchasing contracts.
- Orally dispersible tablet formats:Syrup-replacing solid dosage forms are capturing share where caregiver convenience and cold-chain independence drive formulary decisions. This technology convergence addresses distribution cost pressures.
- Combination therapy development:Resistance surveillance expansion is creating white space for fixed-dose antiviral combinations targeting multiple viral mechanisms simultaneously.
Industry Challenges
- Paediatric pharmacokinetic expertise scarcity:Developmental pharmacology specialists capable of designing weight-appropriate dosing studies remain concentrated within a limited number of academic medical centers and contract research organizations.
- Regulatory harmonization friction:Divergent FDA and EMA paediatric study requirements force duplicate trial investments, stretching R&D budgets and delaying market entry timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paediatric Influenza Treatment Market |
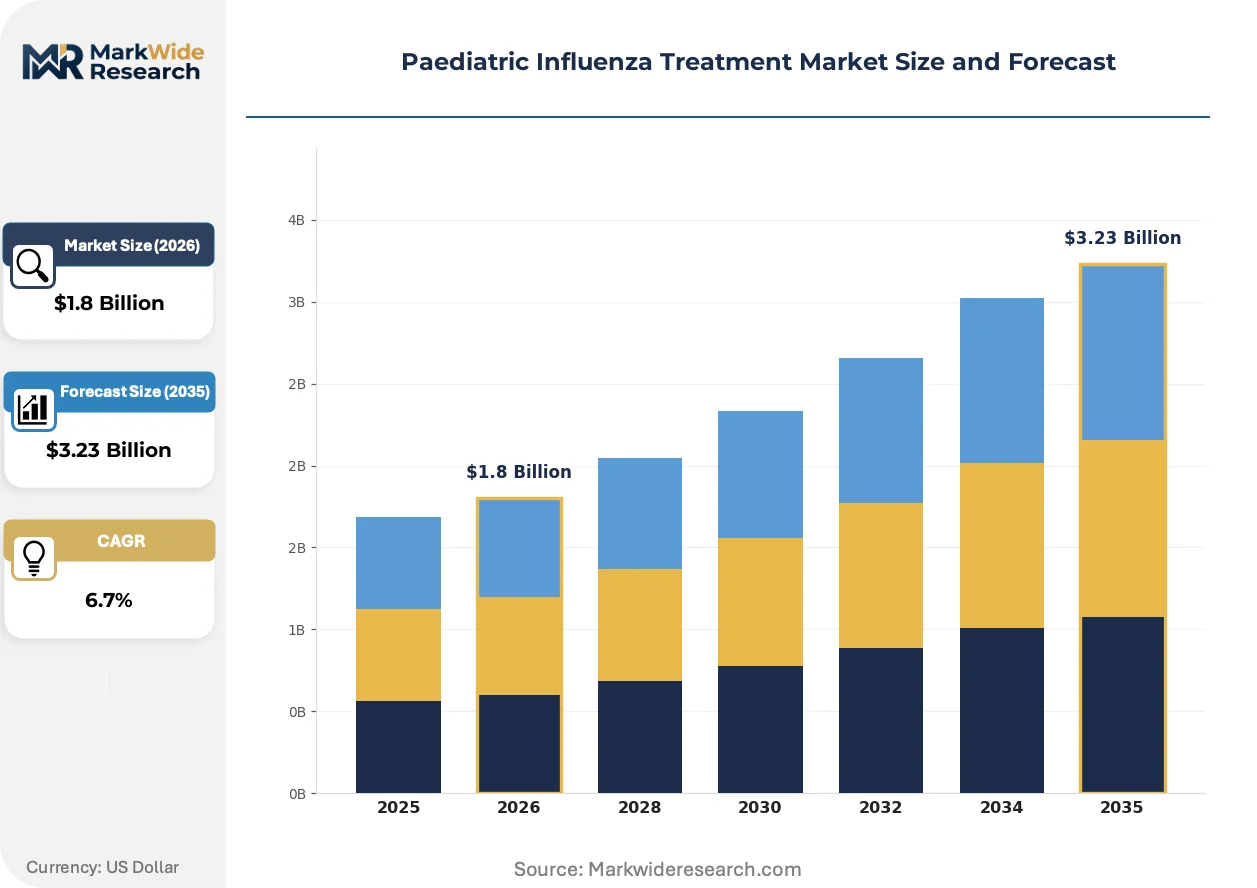
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirals, Vaccines, Combination Therapies, Herbal Remedies Delivery Mode: Injectables, Orally Dispersible Tablets, Inhalation, Syrups End User: Clinics, Hospitals, Home Care, Pharmacies Age Group: Infants, Toddlers, Preschoolers, Adolescents |
| Companies Covered | Roche Holding AG, GlaxoSmithKline plc, AstraZeneca plc, Sanofi S.A., Teva Pharmaceutical Industries Ltd., Abbott Laboratories, Daiichi Sankyo Company, Limited, Seqirus, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paediatric Influenza Treatment Market Evolving Landscape
Recombinant manufacturing platforms are displacing egg-based production methods across influenza vaccine supply chains. This technological transition is reshaping cost structures, yield predictability, and strain-matching responsiveness throughout paediatric immunization programs.
Orally dispersible tablet technology is rewriting paediatric antiviral administration paradigms. Hospital systems and retail pharmacies are adopting these formulations at accelerating rates to eliminate cold-chain dependencies and reduce spoilage losses. The shift is compressing distribution infrastructure requirements and enabling direct-to-clinic supply models previously impractical with liquid formulations.
EMA's Paediatric Investigation Plans are tightening development timelines for sponsors seeking European market authorization. The framework mandates early integration of paediatric study design into adult development programs, forcing resource reallocation toward juvenile toxicology and formulation science. Vaccine manufacturers with established paediatric track records are capturing disproportionate regulatory priority review slots.
Subscription-based preventive service contracting is displacing transactional vaccine procurement in integrated paediatric care networks. Large multi-site clinic operators are consolidating purchasing power through annual immunization agreements that bundle influenza with routine childhood vaccines. This purchasing pattern concentration is most visible in United States metropolitan markets where reimbursement frameworks support preventive care bundling.
Paediatric Influenza Treatment Market Segmentation
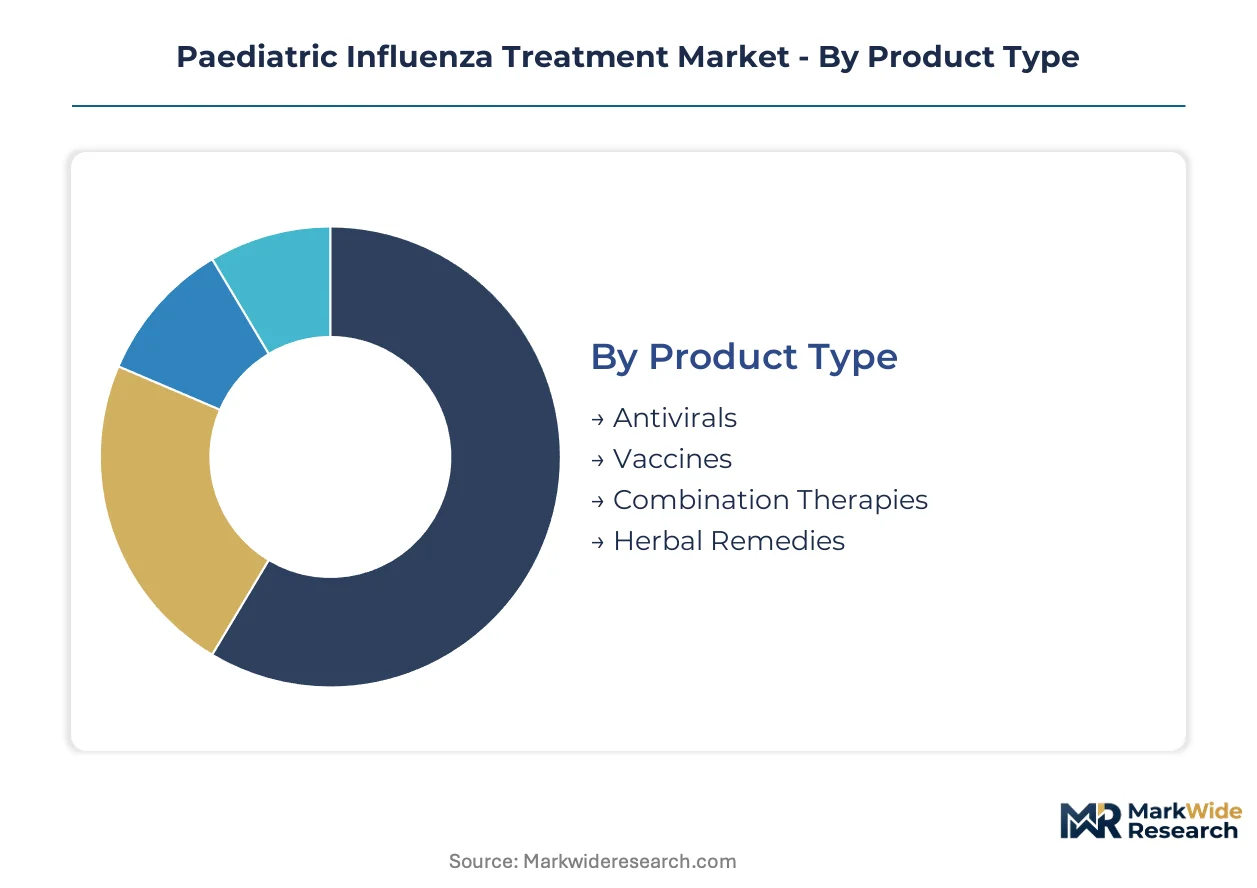
Segmentation in paediatric influenza treatment reveals distinct capital requirements and margin profiles across formulation technologies. Understanding these structural differences enables targeted portfolio allocation and channel strategy optimization for manufacturers.
Product Type:
Antiviral manufacturing demands the heaviest upfront investment due to active pharmaceutical ingredient synthesis complexity and regulatory validation requirements.
- Antivirals:Neuraminidase inhibitors and polymerase inhibitors require multi-step chemical synthesis with stringent purity controls. Demand concentrates in hospital formularies where stockpiling obligations and pandemic preparedness contracts create predictable procurement volumes.
- Vaccines:Egg-based and recombinant protein production platforms involve dedicated bioreactor infrastructure and cold-chain distribution networks. Paediatric clinics in the United States represent the primary demand concentration as seasonal immunization protocols expand.
- Combination Therapies:Fixed-dose formulations targeting multiple viral mechanisms simultaneously.
- Herbal Remedies:Botanical extracts with limited clinical validation in formal treatment guidelines.
Antivirals absorb the bulk of installed capacity; combination therapies are expanding most quickly.
Delivery Mode:
Distribution economics vary sharply between liquid formulations requiring refrigeration and solid dosage forms enabling ambient storage.
- Orally Dispersible Tablets:Rapidly disintegrating solid formulations eliminate cold-chain dependencies and reduce spoilage losses. Retail pharmacies in metropolitan United States markets are adopting these formats fastest where caregiver convenience drives formulary decisions.
- Syrups:Liquid suspensions with palatability engineering requirements and weight-banded dosing calibration.
- Injectables:Intramuscular and intravenous administration routes for severe cases.
- Inhalation:Dry powder and nebulized delivery for respiratory-targeted antiviral action.
Syrups retain the largest installed manufacturing base; orally dispersible tablets are climbing the fastest.
End User:
Channel concentration determines pricing power and reimbursement access across the care continuum.
- Clinics:Outpatient paediatric settings with preventive service bundling and subscription-like immunization scheduling.
- Hospitals:Inpatient acute care with formulary committees and stockpiling mandates.
- Home Care:Post-discharge and prophylactic administration with caregiver-managed dosing.
- Pharmacies:Retail and specialty dispensing with direct-to-consumer access.
Hospitals command the largest procurement volumes; clinics are gaining share fastest.
Age Group:
Developmental pharmacokinetics create distinct formulation and dosing challenges across maturation stages.
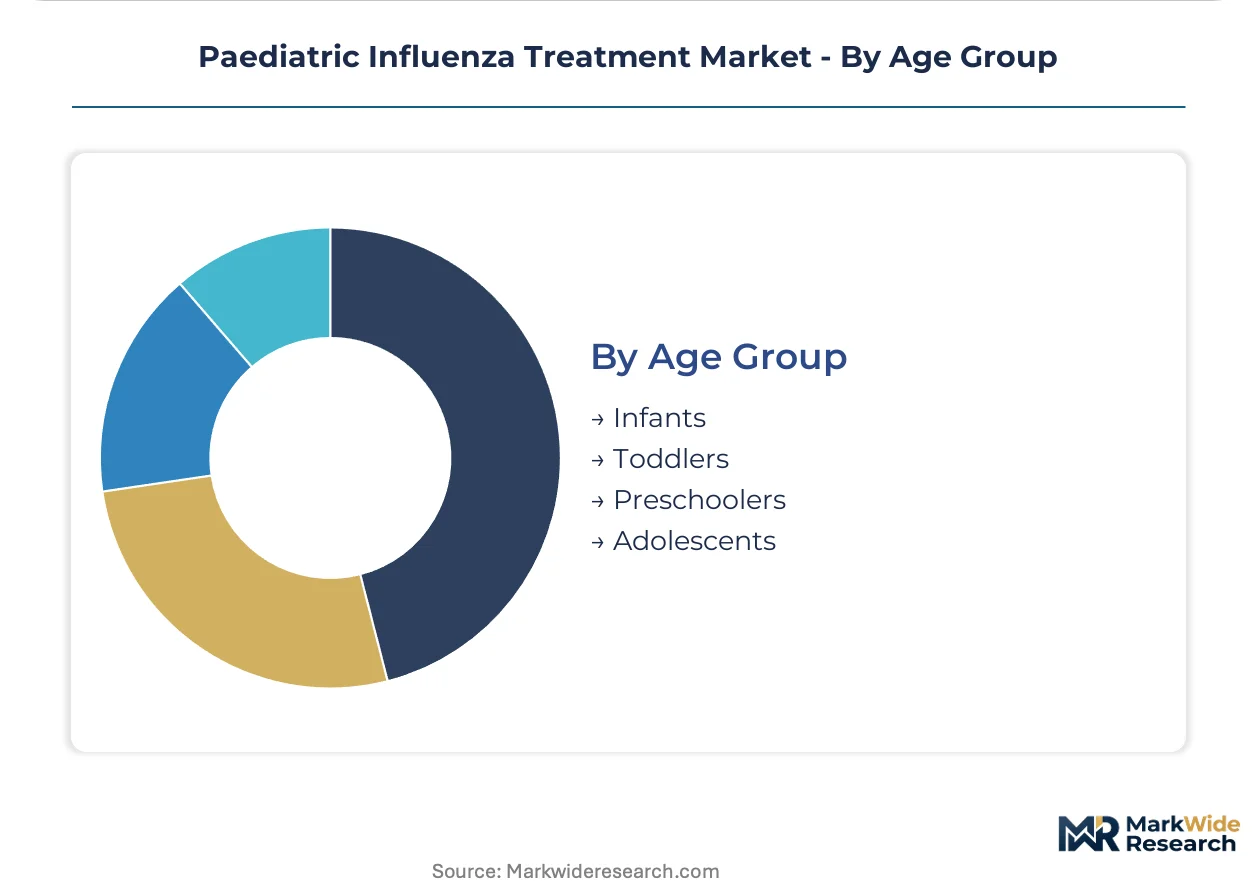
- Infants:Patients under 12 months with immature hepatic metabolism and renal clearance requiring specialized pharmacokinetic studies.
- Toddlers:Ages 1-3 years with weight-banded dosing and palatability-critical administration.
- Preschoolers:Ages 3-5 years with emerging compliance capabilities and school-based exposure risks.
- Adolescents:Ages 12-18 years approaching adult pharmacokinetic profiles with distinct social mixing patterns.
Toddlers represent the most formulation-intensive segment; adolescents are expanding fastest as school-based immunization programs broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biopharmaceutical corridor anchors paediatric antiviral development through dense concentrations of contract research organizations and FDA-aligned clinical trial infrastructure. The metropolitan cluster hosts specialized paediatric pharmacokinetic units that accelerate weight-banded dosing studies for juvenile indications.
United States
Childhood vaccination coverage rates and bundled reimbursement frameworks drive procurement volumes across integrated paediatric networks. FDA accelerated approval pathways compress development timelines for sponsors targeting juvenile indications. The Research Triangle Park corridor in North Carolina concentrates contract manufacturing for live-attenuated vaccine strains serving domestic immunization programs.
Germany
EMA Paediatric Investigation Plans streamline regulatory submissions for sponsors seeking European market authorization. The country's national pharmaceutical regulator enforces stringent post-marketing surveillance for paediatric antiviral safety signals. Baden-Württemberg's pharmaceutical manufacturing belt houses recombinant protein production facilities supplying continental immunization campaigns.
United Kingdom
National Health Service procurement frameworks prioritize cost-effective paediatric formulation access across primary care trusts. The Medicines and Healthcare products Regulatory Agency coordinates paediatric study requirements with EMA harmonization initiatives. London's translational research corridor bridges academic paediatric units with commercial vaccine development pipelines.
Japan
PMDA paediatric review guidelines mandate early integration of juvenile pharmacokinetic data into new drug applications. School-based immunization programs expand seasonal vaccination coverage among adolescent populations. The Kansai region's pharmaceutical cluster specializes in orally dispersible tablet manufacturing for paediatric antiviral export markets.
India
CDSCO paediatric trial regulations align with WHO prequalification standards for low-income country vaccine supply. Domestic manufacturing scale supports cost-competitive antiviral API production for global procurement contracts. Hyderabad's vaccine technology corridor concentrates bulk antigen production capabilities serving multilateral immunization programs.
Paediatric Influenza Treatment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the paediatric influenza treatment landscape. Integrated pharmaceutical conglomerates with captive manufacturing infrastructure face pressure from specialized biotech developers outsourcing production to contract manufacturing organizations. Three strategic archetypes dominate: vertically integrated vaccine manufacturers with egg-based and recombinant platforms, antiviral specialists with neuraminidase inhibitor portfolios, and diagnostic-to-treatment integrators leveraging companion testing ecosystems. Capacity expansion and regulatory priority review positioning constitute the dominant competitive moves reshaping market share trajectories.
Among Swiss-headquartered healthcare conglomerates, Roche Holding AG and Novartis AG occupy positions exemplifying diagnostic-to-treatment integration strategies. GlaxoSmithKline plc represents the vertically integrated vaccine manufacturing archetype with established paediatric formulation capabilities. Sanofi S.A. anchors the recombinant technology specialization vector through its protein engineering platforms. These three entities collectively illustrate how regulatory harmonization capabilities and manufacturing scale determine competitive positioning across paediatric antiviral and vaccine segments.
| Leading Market Players |
|---|
| Roche Holding AG |
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Sanofi S.A. |
| Teva Pharmaceutical Industries Ltd. |
| Abbott Laboratories |
| Daiichi Sankyo Company, Limited |
| Seqirus |
| Cipla |
| Others |
Value Network & Pricing Analysis
API precursor indices for neuraminidase inhibitors cascade through contract manufacturing tiers into three-tier pricing structures across premium, standard, and economy levels, with cold-chain elimination technologies compressing distribution cost differentials between formulations.
Pricing Analysis
Margin tightening in economy-tier antiviral syrups reflects API supply concentration in Asian manufacturing hubs and caregiver price sensitivity in retail pharmacy channels. Premium-mid-economy pricing differentiation hinges on FDA accelerated approval status and palatability engineering investment. Cost-down pressure on standard-tier vaccines accelerates because subscription-based procurement contracts consolidate purchasing power across integrated paediatric networks. Hospital formulary committees demonstrate lowest price sensitivity due to stockpiling mandates, while home care segments exhibit highest elasticity.
Supply Chain Analysis
WHO prequalification standards gate procurement eligibility for low-income country immunization programs, filtering supplier access to multilateral purchasing contracts. Active pharmaceutical ingredient synthesis draws from India, China, and South Korea, with recombinant protein production anchored in Germany and the United States. Supply chain risk centers on single-source vulnerability for live-attenuated vaccine strains and geopolitical exposure to quality enforcement actions. Distribution runs through hospital central pharmacies and direct-to-clinic models for orally dispersible tablet formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant manufacturing platforms are displacing egg-based production across paediatric influenza vaccine supply chains, creating portfolio reallocation imperatives for stakeholders across development and commercialization functions.
For Market Incumbents: Lock in regulatory priority review positioning through accelerated FDA paediatric study submissions and EMA Paediatric Investigation Plan harmonization. Deepen backward integration into recombinant protein production to capture yield predictability advantages against egg-based competitors. Defend formulary placement through diagnostic-to-treatment integration that bundles companion testing with antiviral dispensing.
For New Entrants and Emerging Players: Rural paediatric clinics in resource-limited settings represent the most penetrable buyer archetype for cold-chain-independent orally dispersible tablet formats. WHO prequalification pathway investment unlocks multilateral procurement contracts underserved by incumbent suppliers. Target school-based immunization programs in metropolitan United States markets through direct-to-clinic supply models that bypass traditional distribution tiers.
For Investors and Strategic Acquirers: The window for entry favors diagnostic-to-treatment integrators with companion testing ecosystems and regulatory harmonization capabilities across FDA and EMA frameworks. Long-term viability rests on capturing disproportionate priority review slots through established paediatric track records. Watch antiviral resistance surveillance network expansion as the signal indicating inflection toward combination therapy development investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Paediatric Investigation Plan Harmonization | EMA-aligned trial design reduces duplicate investment and accelerates European label expansion timelines. |
| Recombinant Manufacturing Scale-Up | Protein engineering platforms displace egg-based methods and improve strain-matching responsiveness. |
| Orally Dispersible Tablet Launch | Solid dosage formats eliminate cold-chain dependencies and enable rural distribution reach. |
| Diagnostic-to-Treatment Integration | Companion testing ecosystems sustain hospital formulary loyalty across influenza surveillance networks. |
| WHO Prequalification Pathway | International quality standards unlock multilateral procurement contracts in low-income country programs. |
Research Methodology
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up demand modeling triangulates against top-down market sizing across treatment modality, dosage form, administration route, and patient age band.
Comparable-period anchoring to historical immunization coverage rates and antiviral dispensing volumes establishes the forecast baseline across the projection horizon. Segmentation dimensions include product type, delivery mode, end-user setting, and age-specific developmental pharmacokinetics. CAGRs derive from regression analysis of procurement volume trends, reimbursement framework evolution, and regulatory approval velocity. Resistance surveillance network expansion and seasonal strain-matching accuracy constitute primary forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to antiviral resistance mutation patterns, regulatory harmonization friction between FDA and EMA frameworks, and geopolitical disruption to API supply chains. Forecasts reflect documented assumptions about immunization protocol expansion and pandemic preparedness contract renewal rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Middle East and Africa Pediatric Healthcare Market
Pediatrics
Paediatric Neuropsychiatric Disorders Treatment Market
Pediatrics
Global Pediatric Neuroblastoma Treatment Market
Pediatrics
Pediatric MRI Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Autism Service Platform Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Global Pediatric Clinical Trials Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Pediatrics Medicine Market
Pediatrics
Pediatric Dental Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
OTC Pediatric Healthcare Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric Nasal Cannula Market
Pediatrics
Pediatric Tube Feeding Market